
 Packaging Reel Market | 2026-2036
Packaging Reel Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Reel Market Analytics
ISO 9001 quality management certification is reorganizing supplier qualification protocols across the packaging reel value chain, forcing mid-tier manufacturers to upgrade process documentation or exit approved vendor lists. Sonoco Products Company leverages its captive paperboard mills and regional converting footprint to sustain cost-advantaged supply to North American industrial customers. Schill GMBH & CO. KG anchors its position through specialized steel and plywood reel engineering for heavy-gauge cable and wire applications. Pentre Group competes on rapid-turn custom dimensions, serving fragmented European packaging equipment OEMs with short-lead fulfillment.
Packaging reels are cylindrical cores or spools, typically manufactured from steel, plywood, or molded plastic, engineered to precise tolerances for flange diameter, bore size, and traverse length to ensure stable winding and unwinding of flexible films, tapes, and cables. Their primary industrial purpose centers on protecting product integrity during shipping, enabling automated dispensing, and minimizing material waste from edge damage or telescoping. Polyethylene reels dominate volume production for stretch and shrink film applications, while aluminum variants command premium positioning in medical supplies where moisture barrier properties and cleanroom compatibility justify higher unit economics. Paper-based reels retain cost-sensitive share in consumer goods palletizing, though moisture vulnerability constrains their growth trajectory in humid-climate logistics corridors.
FDA medical device packaging requirements and EU REACH chemical compliance standards are tightening material traceability obligations, compelling reel converters to document resin sourcing and surface treatment chemistry across their supply base. The EPA's evolving framework for industrial emissions is pressuring U.S.-based manufacturers to evaluate solvent-free coating alternatives for printed flange identification. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embedded carbon accounting rules reshape material qualification criteria for export-bound reel shipments.
Market Dynamics
ISO 9001 certification reorganization is forcing mid-tier reel manufacturers to upgrade process documentation or exit approved vendor lists, consolidating supply relationships around documented quality systems.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon emissions is pushing converters toward low-emission film formulations that require specialized reel surface treatments and bore tolerances.
- Healthcare logistics expansion:Sterile packaging requirements from medical supplies distributors are accelerating demand for aluminum reels with moisture barrier properties and cleanroom compatibility.
- Automotive precision specifications:German automotive OEMs are driving tighter flange diameter and traverse length tolerances for cable and wire applications.
Market Restraints
- Resin cost volatility:Polyethylene and polypropylene input fluctuations compress converter margins on high-volume molded plastic reel production.
- Supply concentration in steel reels:Heavy-gauge steel flange and drum manufacturing clusters in Central Europe create single-source vulnerability for heavy cable applications.
- Paper-based moisture limitation:Structural vulnerability to humidity damage constrains paper reel deployment in Southeast Asian and Latin American logistics corridors.
Strategic Opportunities
- Medical device traceability mandates:FDA device packaging requirements and EU REACH compliance standards create premium positioning for converters with documented resin sourcing and surface treatment chemistry.
- Solvent-free coating transition:EPA industrial emissions frameworks are opening market share for reel suppliers with water-based flange identification systems.
- Embedded carbon accounting:EU Green Deal carbon border adjustment mechanisms favor reel manufacturers with lifecycle-assessed aluminum and recycled steel supply chains.
Industry Challenges
- Quality management documentation:ISO 9001 certification timelines stretch 12-18 months for mid-tier manufacturers, delaying approved vendor list requalification.
- Multi-standard compliance:Simultaneous FDA medical device, EU REACH, and EPA emissions documentation requirements strain converter quality assurance staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Reel Market |
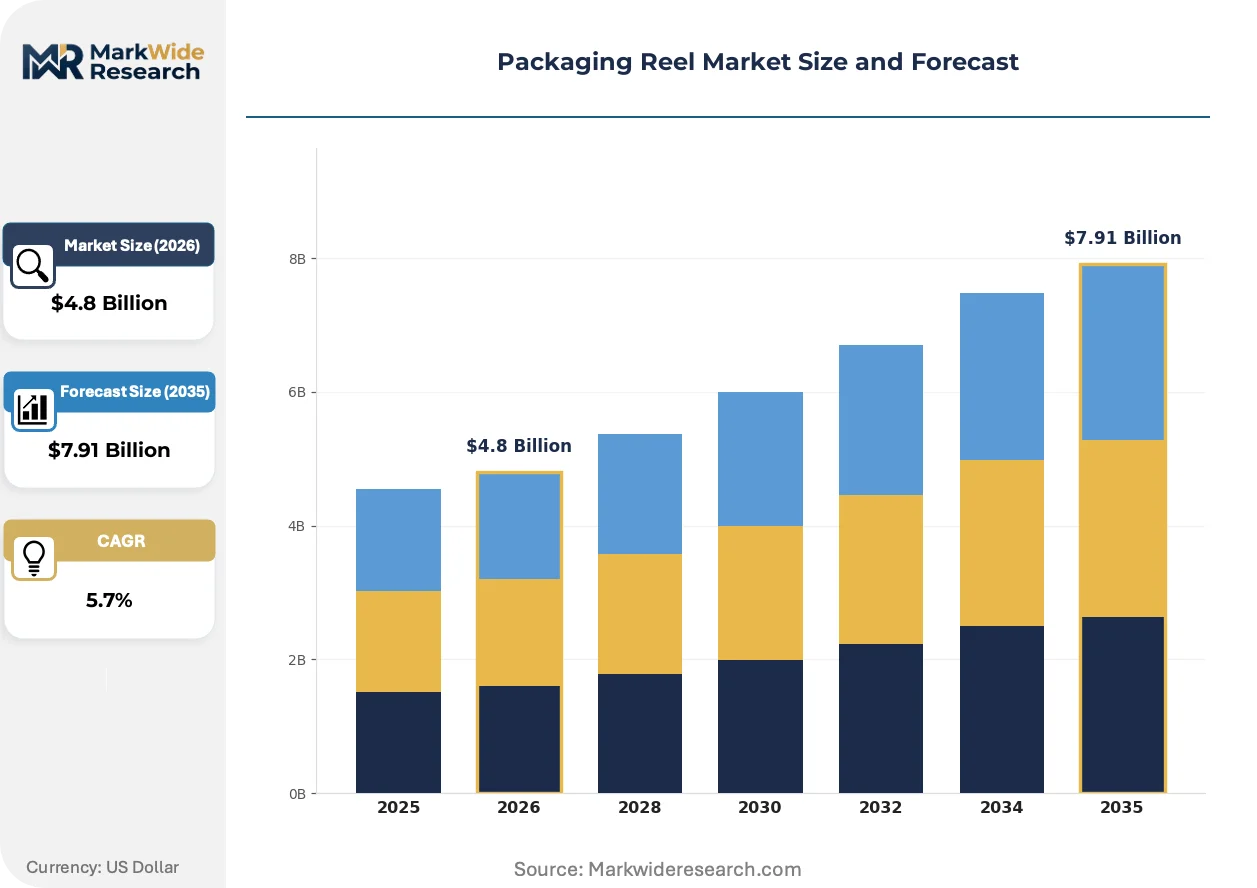
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Film, Shrink Film, Pallet Wrapping Film, Bubble Wrap Material: Polyethylene, Polypropylene, Paper, Aluminum Application: Food Packaging, Medical Supplies, Consumer Goods, Industrial Packaging Distribution Channel: Online Retail, Wholesalers, Direct Sales, Supermarkets |
| Companies Covered | Sonoco Products Company, Hubbell, Pentre Group, Schill GMBH & CO. KG, Vandor Corporation, Müller Plastik GmbH, Carris Reels, Hartmann & König Stromzuführungs AG, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Reel Market Evolving Landscape
Material science advances and regulatory chemistry documentation requirements are reshaping reel specification protocols across medical, automotive, and industrial film applications.
Recycled aluminum billet casting with certified post-consumer content is displacing primary aluminum reels in medical supplies packaging. Healthcare logistics networks in Germany and Switzerland are mandating documented carbon footprint reductions. This displacement is compressing first-use aluminum premiums and rewarding converters with closed-loop scrap partnerships.
REACH chemical compliance standards now require full material traceability for surface treatments and flange coatings used in EU-bound shipments. Reel converters must document resin sourcing back to polymerization batch level. Medical device and sterile film segments are responding by consolidating supply relationships around converters with existing documentation systems.
Automated dispensing system integration is shortening buyer switching cycles from annual contracts to quarterly performance reviews. Packaging equipment OEMs in Bavaria and Baden-Württemberg now specify reel bore tolerances to thousandth-of-millimeter precision. This pattern is most visible in automotive wire harness and industrial tape applications where line speed optimization drives specification tightening.
Packaging Reel Market Segmentation
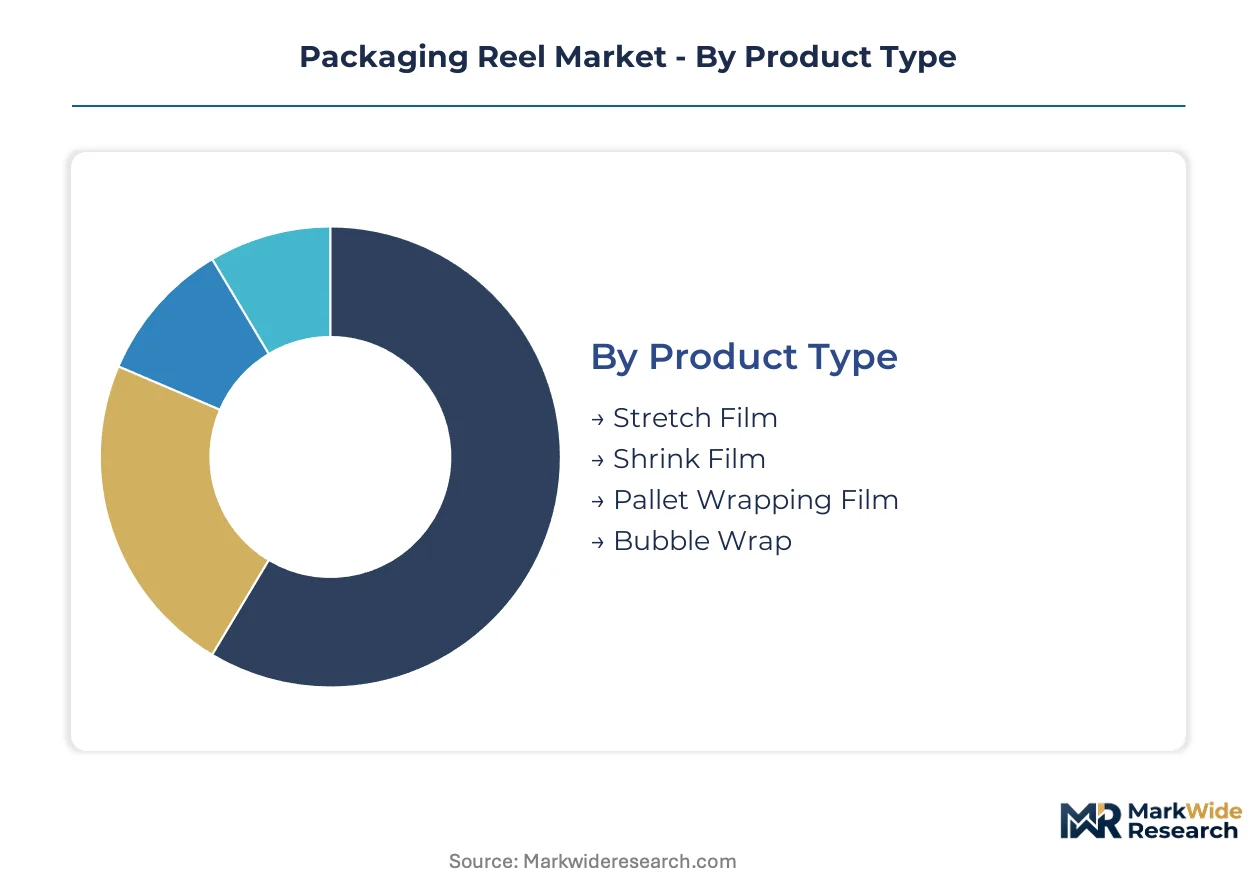
Packaging reel specification diverges sharply across end-use applications, with medical and automotive segments demanding precision tolerances while consumer goods tolerate wider variance. Material substitution pressures and regulatory compliance costs are fragmenting supplier portfolios along quality-tier lines.
Product Type:
Stretch film reels face the most acute substitution threat from pre-stretched film systems that reduce core consumption, while bubble wrap reels benefit from e-commerce cushioning demand that resists format displacement.
- Stretch Film:Linear low-density polyethylene formulations dominate reel specifications for pallet stabilization. German automotive logistics networks specify 76mm bore diameters with ±0.5mm tolerance for automated dispensing compatibility.
- Shrink Film:Cross-linked polyolefin reels require heat-resistant flange materials for high-tunnel applications. Medical device sterilization workflows in Switzerland drive demand for aluminum-cored variants with moisture barrier integrity.
- Pallet Wrapping Film:Heavy-gauge cast film reels serve industrial consolidation centers with extended traverse lengths.
- Bubble Wrap:Air retention film reels concentrate in e-commerce fulfillment corridors around Rotterdam and Hamburg port zones.
Stretch film retains volume leadership; bubble wrap holds the steepest expansion curve.
Material:
Cost tier stratification separates commodity polyethylene from certified aluminum, with paper occupying a narrowing mid-market position threatened by humidity performance gaps.
- Polyethylene:High-volume injection-molded reels serve stretch and shrink film converters with standardized 3-inch bore formats. Resin cost volatility compresses margins on commodity-grade production.
- Aluminum:Billet-cast reels with certified post-consumer content command medical supply premiums. FDA device packaging traceability mandates and EU REACH documentation requirements favor converters with closed-loop scrap partnerships in Germany.
- Polypropylene:Copolymer reels offer chemical resistance for industrial tape applications.
- Paper:Recycled fiber reels retain palletizing share in dry-climate European corridors.
Polyethylene dominates shipment volumes; aluminum delivers the strongest value-per-unit trajectory.
Application:
Customer type fragmentation splits procurement between specification-driven OEMs and price-sensitive distributors, with compliance burden concentrating in healthcare and food contact segments.
- Medical Supplies:Sterile packaging workflows demand aluminum reels with ISO 14644 cleanroom compatibility and documented surface treatment chemistry. Swiss and German healthcare logistics networks mandate carbon footprint reductions that displace primary aluminum.
- Food Packaging:FDA-compliant polyethylene reels with migration-tested resins serve modified atmosphere packaging. EU F-Gas Regulation phasedown pressures converters toward low-emission film formulations requiring specialized bore tolerances.
- Consumer Goods:Cost-optimized paper and polyethylene reels dominate retail palletizing.
- Industrial Packaging:Heavy-gauge steel and plywood reels from Schill anchor cable and wire applications.
Industrial packaging retains volume leadership; medical supplies commands the steepest specification escalation curve.
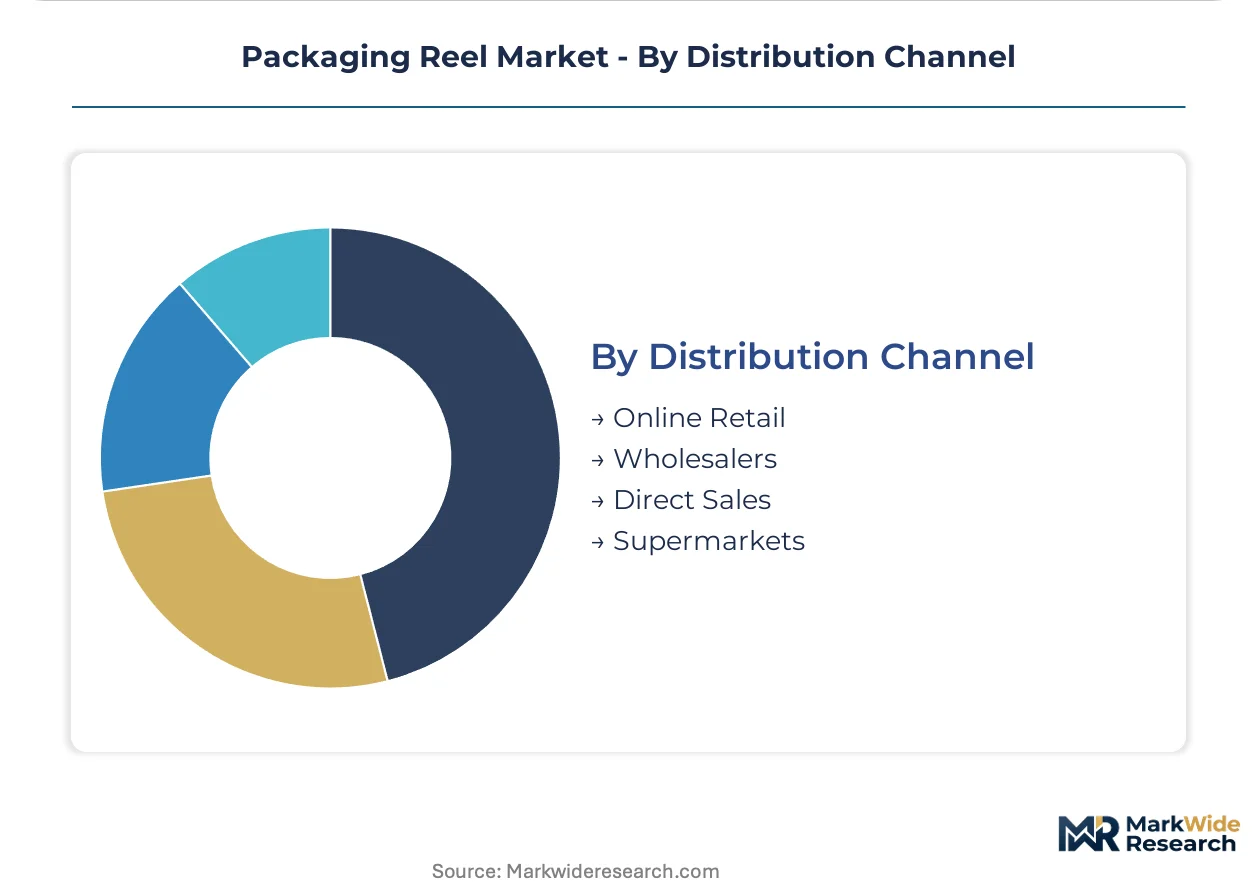
Distribution Channel:
Volume concentration favors direct sales for large-format industrial reels, while fragmentation characterizes custom-dimension procurement through equipment OEM channels.
- Direct Sales:Long-term supply agreements with automotive and cable manufacturers lock in annual volume commitments. Sonoco's captive paperboard mills sustain cost-advantaged supply through direct relationships with North American industrial customers.
- Wholesalers:Regional inventory positioning serves mid-tier converters with standardized dimension reels. Pentre Group competes on rapid-turn fulfillment for fragmented European packaging equipment OEMs.
- Online Retail:Catalog-based procurement gains share in small-volume MRO replenishment.
- Supermarkets:Limited penetration restricted to consumer-grade stretch film reels.
Direct sales retains volume leadership; online retail exhibits the fastest channel expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's embedded carbon accounting rules and FDA medical device traceability mandates are redrawing procurement geography for packaging reel suppliers. Germany, the United States, China, Switzerland, and Japan concentrate distinct demand profiles shaped by sector-specific regulatory frameworks.
Germany
Automotive wire harness and industrial tape applications from Bavarian OEMs specify flange diameter tolerances to thousandth-of-millimeter precision. The EU F-Gas Regulation phasedown pushes converters toward low-emission film formulations requiring specialized bore treatments. Stuttgart and Munich logistics corridors anchor heavy-gauge steel reel demand for cable manufacturers.
United States
North American industrial customers source cost-advantaged paperboard reels through mill-integrated supply chains. EPA industrial emissions frameworks pressure solvent-free coating adoption for flange identification systems. The Midwest manufacturing belt sustains polyethylene reel consumption for stretch film pallet stabilization.
China
Dual carbon goals reshape material qualification criteria for export-bound aluminum reel shipments to European healthcare networks. NMPA medical device packaging standards tighten parallel to FDA requirements for sterile film applications. Yangtze River Delta converters invest in closed-loop scrap partnerships to satisfy EU carbon border adjustments.
Switzerland
Swiss healthcare logistics networks mandate documented carbon footprint reductions that displace primary aluminum with certified post-consumer billet casting. Swissmedic medical device regulations align with EU REACH chemical compliance for surface treatment traceability. Zurich and Basel sterile packaging corridors concentrate premium reel specifications.
Japan
METI industrial standards drive precision tolerances for automated dispensing compatibility in electronics film applications. PMDA medical device packaging requirements mirror FDA traceability mandates for resin sourcing documentation. Kanto region packaging equipment OEMs specify rapid-turn custom dimensions with quarterly performance reviews.
Packaging Reel Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and material technology dimensions. The supplier base stratifies around ISO 9001 documentation capability, with documented quality systems consolidating approved vendor relationships. Three archetypes dominate: mill-integrated paperboard suppliers, precision metal engineering specialists, and rapid-turn custom dimension fabricators. Capacity expansion in recycled aluminum billet casting and backward integration into captive resin sourcing represent the dominant competitive vectors.
Among Germany-based engineering specialists, Schill GMBH & CO. KG and Müller Plastik GmbH exemplify the heavy-gauge metal and precision polymer segments respectively. Sonoco Products Company anchors the mill-integrated archetype with North American paperboard capabilities. These three occupy positions across distinct material tiers without overlapping specification ranges.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Hubbell |
| Pentre Group |
| Schill GMBH & CO. KG |
| Vandor Corporation |
| Müller Plastik GmbH |
| Carris Reels |
| Hartmann & König Stromzuführungs AG |
| Amcor plc |
| Others |
Value Network & Pricing Analysis
ISO 9001 certification reorganization gates both supply qualification and price differentiation simultaneously, forcing mid-tier reel manufacturers to absorb 12-18 month documentation timelines or forfeit approved vendor status to certified competitors commanding premium positioning.
Pricing Analysis
Certification level (ISO 9001/FDA-grade) creates the primary spread between premium aluminum reels for medical supplies and commodity polyethylene formats for consumer palletizing. Three-tier pricing structure across premium, standard, and economy levels reflects documented traceability depth, with REACH-compliant surface treatment chemistry commanding measurable premiums. Cost compression in molded plastic tiers is intensifying because resin input volatility erodes converter margins on high-volume standardized bores. Distributor buyers in consumer goods segments exhibit highest price sensitivity, while German automotive OEMs prioritize tolerance precision over unit cost.
Supply Chain Analysis
Rotterdam and Hamburg port congestion elevates inbound logistics costs for aluminum billet sourced from Yangtze River Delta casting facilities. Supply concentrates in Germany for precision steel flange engineering, China for recycled aluminum billet production, and the US Midwest for captive paperboard mill integration. Raw material dependencies rest on polyethylene resin from petrochemical corridors, certified post-consumer aluminum scrap, and engineered plywood laminates. Single-source vulnerability characterizes heavy-gauge steel drum manufacturing clusters in Central Europe. Distribution runs through direct sales agreements with automotive and cable manufacturers, supplemented by regional wholesaler inventory positioning for fragmented equipment OEM procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Packaging reel procurement is evolving into a service-attach opportunity as documented carbon footprint auditing and quarterly performance review contracts expand faster than hardware shipment volumes.
For Market Incumbents: Compound defensive positioning by deepening backward integration into captive resin sourcing and closed-loop aluminum scrap partnerships that satisfy EU carbon border adjustments. Pre-stretched film system substitution threatens core consumption volumes; counter with rapid-turn custom dimension capabilities that lock in quarterly contract reviews with Bavarian packaging equipment OEMs. ISO 14644 cleanroom compatibility certification represents the priority lever for medical supply retention. For New Entrants and Emerging Players: FDA medical device packaging fast-track certification opens white-space access in Swiss and German healthcare logistics networks where sterile packaging workflows mandate documented surface treatment chemistry. Target Southeast Asian e-commerce fulfillment corridors around port zones where bubble wrap reel demand resists format displacement. Pentre Group's rapid-turn fulfillment model offers a proven go-to-market template for fragmented European equipment OEM channels. For Investors and Strategic Acquirers: EU Green Deal embedded carbon accounting rules reshape the acquisition landscape toward converters with lifecycle-assessed aluminum and documented post-consumer content. Five-to-ten year viability favors mill-integrated paperboard suppliers with North American industrial customer density and precision metal engineering specialists with automotive OEM qualification. Monitor NMPA medical device packaging standard tightening in China as the signal indicating accelerated consolidation around traceability-capable suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Resin Sourcing | Insulates converters from polyethylene cost volatility while satisfying FDA batch-level traceability mandates. |
| Closed-Loop Aluminum Scrap Partnership | Enables certified post-consumer billet casting that commands medical supply premiums under EU carbon border adjustments. |
| ISO 14644 Cleanroom Compatibility Certification | Qualifies suppliers for Swiss and German healthcare logistics networks mandating sterile packaging workflows. |
| Water-Based Flange Identification System Transition | Positions converters for EPA solvent-free coating compliance while capturing share from emission-pressured competitors. |
| Quarterly Performance Review Contract Structure | Aligns with Bavarian OEM automated dispensing integration that has shortened buyer switching cycles from annual terms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, combining reel converter quality assurance directors, automotive OEM procurement teams, healthcare logistics network managers, and packaging equipment OEM specification engineers with secondary validation from EU F-Gas Regulation filings, EPA industrial emissions frameworks, FDA medical device packaging guidance documents, and customs trade data on aluminum billet flows. Bottom-up shipment analysis triangulated against top-down market sizing across material tiers and end-use applications.
Across the modeling period, volume and value outputs reflect segmentation by product type (stretch film, shrink film, bubble wrap), material (polyethylene, aluminum, steel, paper), application (medical supplies, automotive, food packaging, industrial), and distribution channel. CAGRs were derived from trend extrapolation of healthcare logistics expansion rates, automotive precision specification tightening patterns, and e-commerce cushioning demand trajectories, cross-referenced with resin cost elasticity assumptions and regulatory compliance timeline impacts.
Decision-makers should treat outputs as directional under sustained EU Green Deal implementation and stable healthcare logistics network expansion; material deviation in carbon border adjustment enforcement timelines or NMPA standard acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation phasedown pace and pre-stretched film substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
Printed Aluminium Foil Packaging Market
Packaging Materials
PVC Packing Straps Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
Packaging Primers Market
Packaging Materials
Packaging Straps and Buckles Market
Packaging Materials
Protein Packaging Market
Packaging Materials
Disposable Egg Trays Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Packaging Supplies Market
Packaging Materials
United States Single Use Packaging Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Cardboard Trays Market
Packaging Materials
New Packages and Materials for Power Devices Market