
 Hydrobike Market | 2026-2036
Hydrobike Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrobike Market Insights
Asset-light leasing partnerships between tourism operators and equipment financiers is rewriting competitive entry barriers in the hydrobike sector. Hydrobikes Inc. leverages direct-to-rental distribution to anchor North American waterfront contracts. Manta5 specializes in carbon-fiber hydrofoil architectures that dominate performance-oriented segments. Schiller Bikes controls premium marina placement through dockside service agreements.
A hydrobike is a human-powered watercraft combining bicycle drivetrain mechanics with pontoon or hydrofoil hull stabilization, typically operating at 3-8 knots via pedal-to-propeller transmission. The platform serves commercial rental fleets, fitness training programs, and recreational coastal tourism. Recreational Hydrobikes sustain the largest revenue pool due to scalable fleet economics at beach resorts and lake lodges. Electric Hydrobikes are capturing the fastest expansion as lithium-ion pedal-assist systems extend range for older users and expand accessible demographics. Fitness Hydrobikes occupy a mature niche anchored by boutique aquatic studio contracts with predictable replacement cycles.
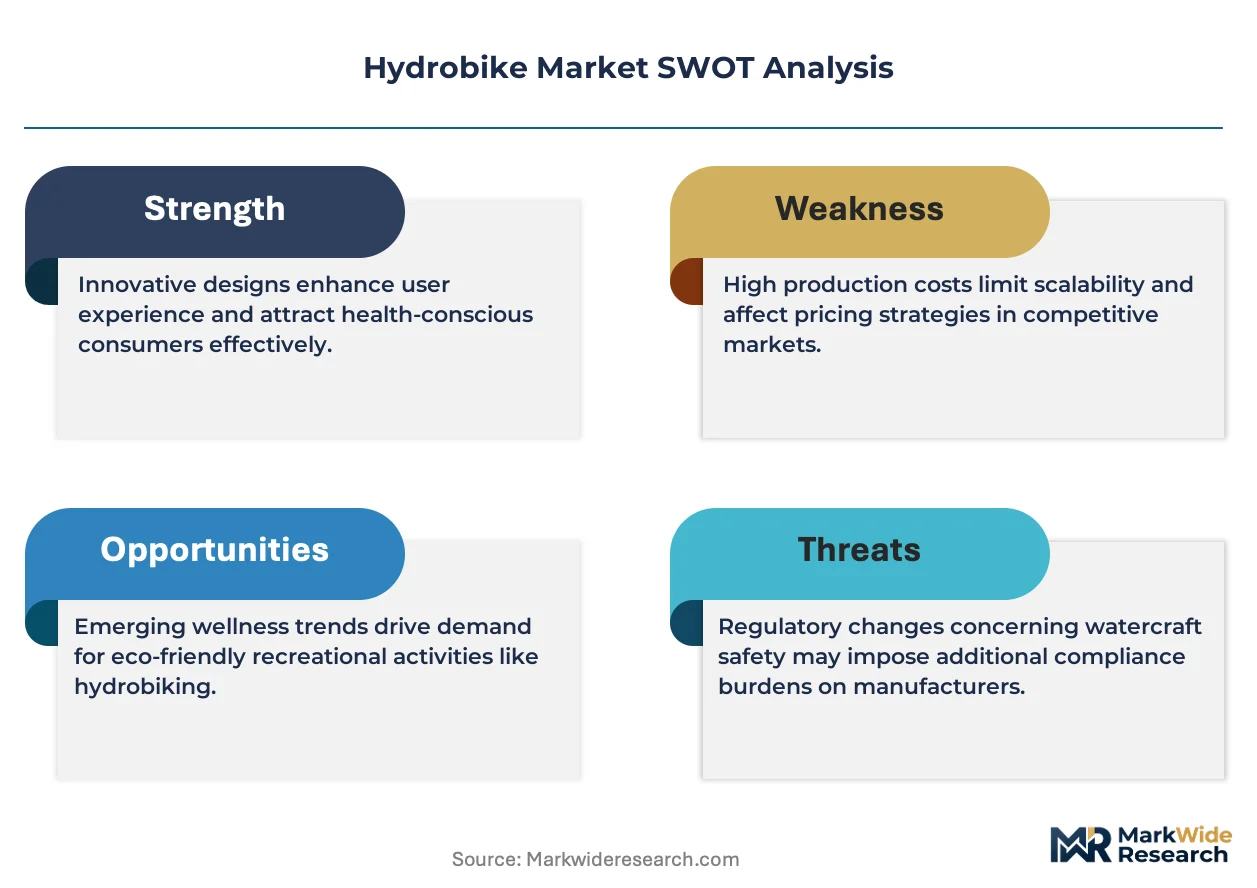
The US Coast Guard and EPA jointly govern hull material safety and anti-fouling coating standards for commercial watercraft operating in domestic waterways. The EU's REACH regulation and CE marking requirements restrict phthalate-based buoyancy compounds and mandate propeller guard specifications for rental deployment. Australia's TGA-aligned state maritime safety offices enforce operator certification for commercial hydrobike concessions on the Great Barrier Reef. Stakeholders must monitor evolving battery certification standards for electric variants and decide whether to internalize compliance teams or outsource to marine equipment certifiers.
Market Dynamics
Tourism operators in harbor cities from Sydney to Miami are consolidating procurement through asset-light leasing partnerships, compressing capital requirements for fleet expansion while concentrating purchasing power among equipment financiers.
Growth Catalysts
- EU Green Deal material standards:The F-Gas Regulation and REACH compliance requirements are accelerating replacement cycles for legacy buoyancy foams and hull coatings across Mediterranean rental fleets.
- Lithium-ion pedal-assist systems:Electric drivetrain architectures are extending accessible demographics to older users and mobility-limited tourists, expanding addressable market segments beyond traditional fitness enthusiasts.
- Great Barrier Reef concession scaling:Queensland maritime safety offices are certifying commercial operators at unprecedented rates, anchoring Australia as the fastest-expanding deployment geography.
Market Restraints
- Carbon-fiber supply concentration:Performance hydrofoil architectures depend on Japanese and South Korean prepreg suppliers, exposing manufacturers to input cost volatility and allocation constraints.
- REACH phthalate restrictions:The EU's ban on legacy buoyancy compounds forces reformulation of pontoon cores, adding certification delays and material qualification costs for European market entry.
- Dockside real estate scarcity:Premium marina placement agreements in coastal tourism corridors face escalating lease rates and exclusivity clauses, compressing margin structures for rental fleet operators.
Strategic Opportunities
- Boutique aquatic studio networks:Fitness Hydrobike replacement cycles are predictably mature, creating white space for subscription-based fleet refresh programs tied to boutique wellness chains.
- CE marking harmonization:The EU's consolidated propeller guard and hull stability standards enable pan-European distribution without country-by-country recertification, reducing market entry friction.
- Lake lodge eco-tourism:Underpenetrated freshwater concessions in the Alpine region and Nordic lake districts present untapped deployment potential for seasonal rental economics.
Industry Challenges
- Battery certification timelines:UN 38.3 and IEC 62133 testing protocols for lithium-ion pedal-assist systems add six-to-nine-month delays to electric variant commercialization.
- Marine technician scarcity:The intersection of bicycle drivetrain mechanics and corrosion-resistant hull maintenance requires hybrid skill sets that rental operators struggle to source at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrobike Market |
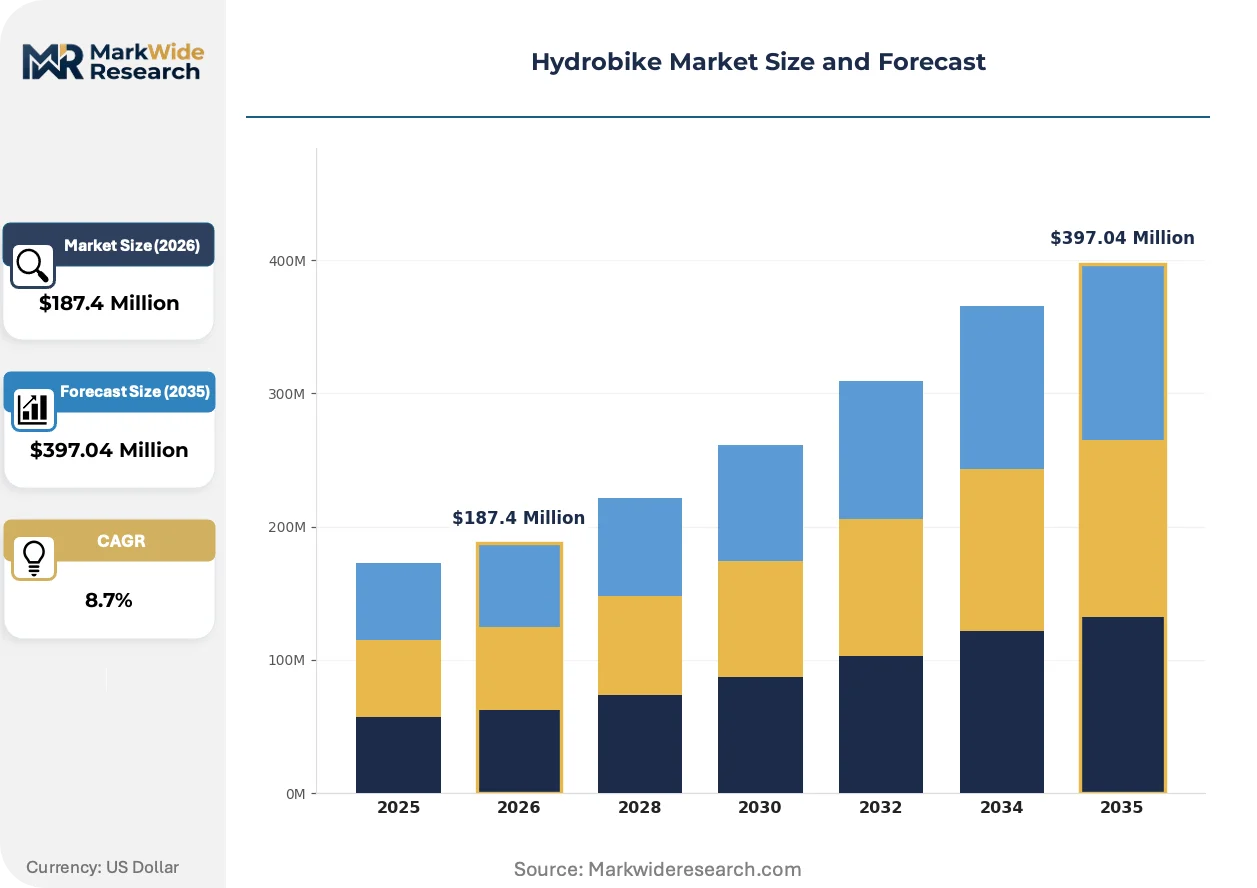
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recreational Hydrobikes, Racing Hydrobikes, Fitness Hydrobikes, Custom Hydrobikes End User: Sports Enthusiasts, Fitness Centers, Rental Companies, Individual Customers Technology: Manual Hydrobikes, Electric Hydrobikes, Hybrid Hydrobikes, Smart Hydrobikes Distribution Channel: Online Retail, Specialty Stores, Trade Shows, Direct Sales |
| Companies Covered | Austin Water Bikes, Hobie Cat Company, Hydrobikes Inc., Manta5, Seabike, Yamaha Motor Corporation, Dave Cornthwaite, Bike Boat, Schiller Bikes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrobike Market Trends and Innovations
Active materials and powertrain architectures are compressing the performance gap between recreational and electric-assisted platforms, while regulatory harmonization is reshaping certification economics across coastal tourism markets.
Modular carbon-fiber hydrofoil assemblies are collapsing the cost barrier between entry-level pontoon stability and performance-oriented foiling efficiency. Australian reef tourism operators are adopting these architectures at accelerated procurement cycles. The technology is collapsing the traditional segmentation between recreational accessibility and enthusiast-grade performance, forcing manufacturers to unify platform architectures.
The EPA's anti-fouling coating standards for commercial watercraft are tightening permissible biocide concentrations in hull treatments. This industrial consequence is accelerating migration toward silicone-based foul-release systems that eliminate toxic metal oxides. Electric Hydrobike variants operating in US domestic waterways face the most stringent compliance timelines, with manufacturers internalizing coating qualification teams rather than outsourcing to marine certifiers.
Outcome-based concession contracts are displacing traditional equipment purchase models in harbor city procurement. Tourism operators in Barcelona, Vancouver, and Auckland are piloting revenue-sharing arrangements where financiers retain fleet ownership and operators pay per-usage fees. This behavioral shift is most visible in Mediterranean and Asia-Pacific coastal markets where seasonal demand volatility makes fixed capital commitments structurally unattractive.
Hydrobike Market Segmentation
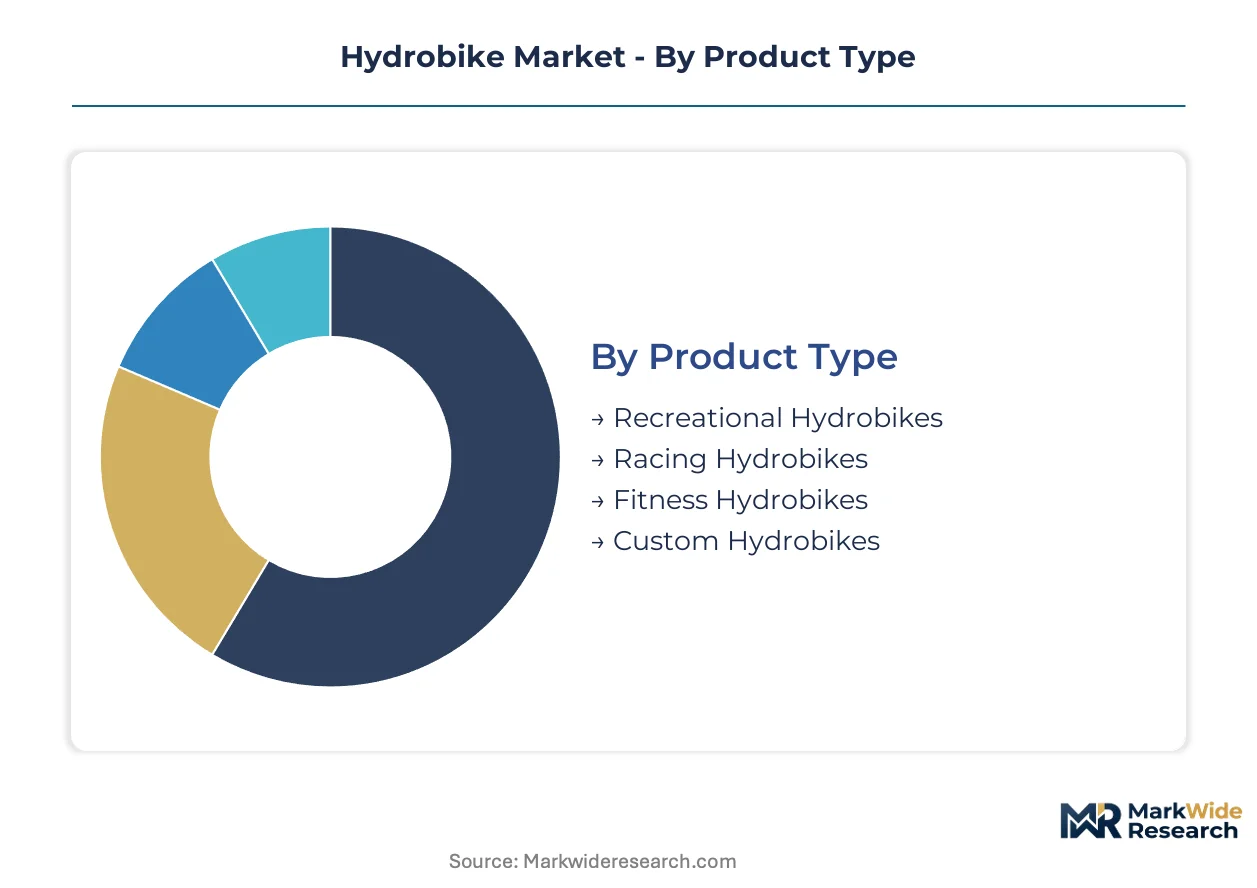
Hydrobike segmentation reveals divergent engineering requirements across use cases, from pontoon stability for harbor rentals to hydrofoil efficiency for performance enthusiasts. Manufacturers must balance modular platform architectures against specialized component stacks to capture value across deployment contexts.
Product Type:
The use-case spectrum spans casual waterfront recreation to competitive racing circuits, with each segment demanding distinct hull geometries and drivetrain calibrations.
- Recreational Hydrobikes:Pontoon-stabilized platforms with corrosion-resistant aluminum or polyethylene hulls dominate fleet procurement at coastal resorts and lake lodges. Australian reef tourism operators in Queensland are scaling concessions fastest, driven by streamlined maritime safety certifications for commercial operators.
- Fitness Hydrobikes:Stationary-compatible architectures with resistance-adjustable drivetrains anchor boutique aquatic studio contracts. Predictable replacement cycles across wellness chains in Miami and Sydney create recurring revenue pools for equipment financiers.
- Racing Hydrobikes:Carbon-fiber hydrofoil assemblies optimize hydrodynamic efficiency for competitive circuits. Japanese and South Korean prepreg suppliers control critical input streams.
- Custom Hydrobikes:Bespoke hull configurations serve specialized applications from adaptive accessibility programs to expedition touring. Low-volume production runs concentrate among artisan manufacturers.
Established volume favors Recreational Hydrobikes; emerging adoption favors Fitness Hydrobikes.
End User:
Customer archetypes range from capital-light rental operators to high-engagement individual enthusiasts, with procurement economics varying sharply across ownership models.
- Rental Companies:Fleet operators along Mediterranean and Asia-Pacific coastal corridors are consolidating procurement through asset-light leasing partnerships with equipment financiers. Revenue-sharing contracts displace traditional purchase models in Barcelona, Vancouver, and Auckland.
- Fitness Centers:Boutique aquatic studios in harbor cities from Sydney to Miami drive replacement-cycle demand for resistance-calibrated platforms. Subscription-based fleet refresh programs are gaining traction.
- Sports Enthusiasts:Performance-oriented buyers prioritize hydrofoil efficiency and carbon-fiber construction. Direct-to-consumer channels dominate this high-margin segment.
- Individual Customers:Recreational buyers seek accessible entry points through online retail and specialty marine dealers. Seasonal demand volatility concentrates purchases in Q2-Q3.
Rental Companies capture procurement volume; Fitness Centers are climbing the fastest in contract velocity.
Technology:
Powertrain architectures differentiate across human-only, pedal-assist, and connected variants, with regulatory compliance timelines varying by battery certification requirements.
- Electric Hydrobikes:Lithium-ion pedal-assist systems extend accessible demographics to older users and mobility-limited tourists. UN 38.3 and IEC 62133 testing protocols add six-to-nine-month commercialization delays for US and EU market entry.
- Manual Hydrobikes:Pure mechanical drivetrains eliminate battery compliance burdens and maintenance complexity. Dominant share in price-sensitive rental fleets across emerging concessions.
- Hybrid Hydrobikes:Dual-mode architectures switch between human and electric propulsion. Targeting transitional users in Alpine lake districts and Nordic freshwater tourism.
- Smart Hydrobikes:Connected platforms integrate GPS tracking, performance metrics, and fleet management telemetry. Marina operators in Miami and Sydney pilot IoT-enabled concession monitoring.
Manual Hydrobikes retain installed-base dominance; Electric Hydrobikes gain share fastest on demographic expansion.
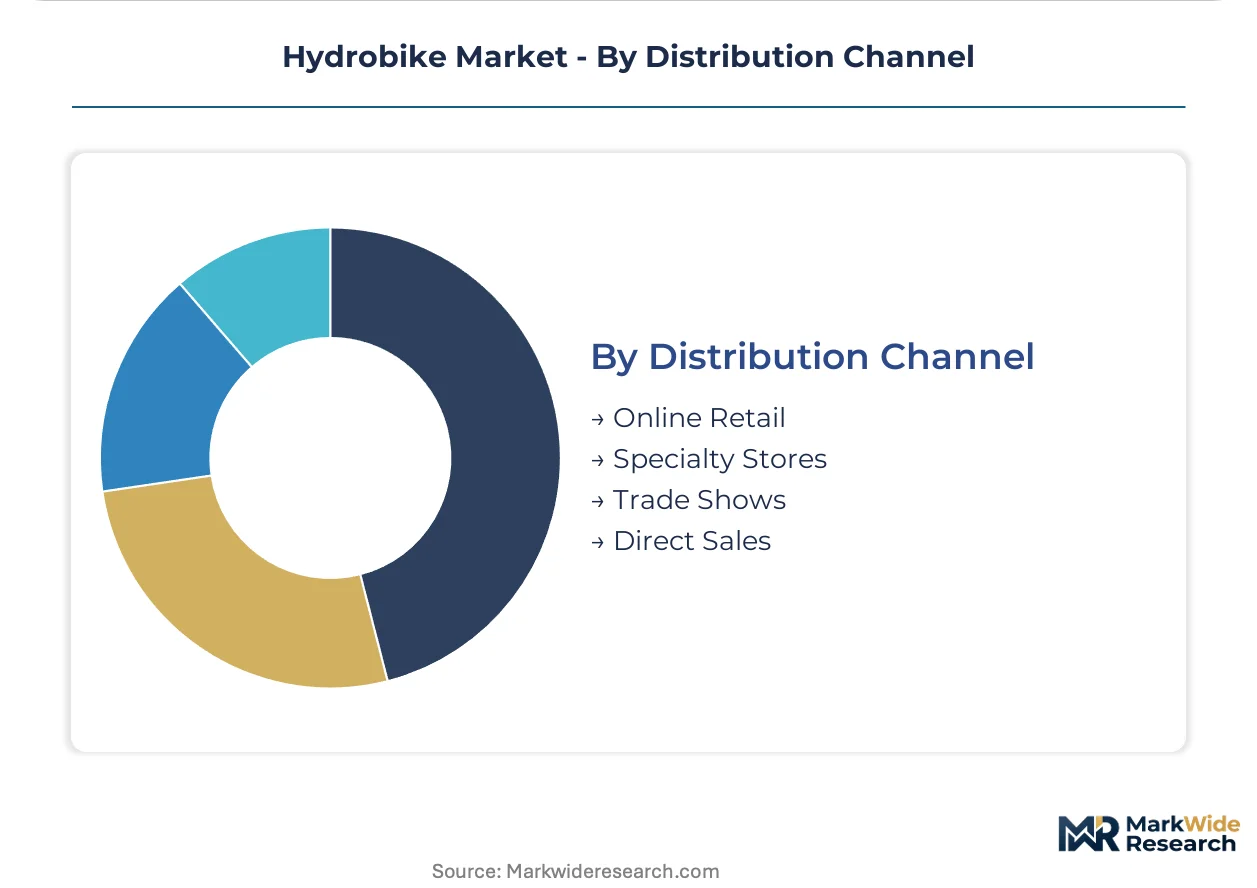
Distribution Channel:
Channel economics reflect capital intensity differences between direct fleet relationships and transactional retail throughput.
- Direct Sales:Manufacturer-to-rental-operator contracts anchor fleet procurement at scale. Dockside service agreements with premium marinas concentrate placement power among established suppliers.
- Specialty Stores:Marine and cycling retailers provide tactile evaluation for individual buyers. Coastal tourism corridors in Australia and Florida maintain highest door density.
- Online Retail:E-commerce platforms serve dispersed individual customers and small-scale fitness studios. Logistics complexity limits hydrofoil variant shipment feasibility.
- Trade Shows:Industry events in Barcelona, Miami, and Sydney concentrate B2B relationship formation. Seasonal alignment with northern hemisphere procurement cycles.
Direct Sales command fleet volume; Online Retail shows steepest expansion trajectory on demographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's F-Gas Regulation and Australia's streamlined maritime safety certifications are reshaping procurement patterns across coastal tourism corridors. Fleet operators in harbor cities from Barcelona to Sydney are consolidating equipment procurement through asset-light leasing partnerships. Regulatory harmonization in the EU and certification acceleration in Queensland are compressing market entry timelines for compliant manufacturers.
United States
Rental operators in Miami and San Diego are expanding hydrobike concessions along waterfront tourism districts. The EPA's anti-fouling coating standards for commercial watercraft are accelerating migration toward silicone-based foul-release hull treatments. California's coastal marina operators face dockside real estate scarcity that compresses margin structures for fleet deployment.
Australia
Queensland's TGA-aligned maritime safety offices are certifying commercial hydrobike operators at unprecedented rates for Great Barrier Reef concessions. The state's streamlined operator certification programs are anchoring Australia as the fastest-expanding deployment geography. Harbor cities from Cairns to Gold Coast are scaling hydrobike concessions through seasonal rental economics.
Germany
Alpine lake districts in Bavaria and Baden-Württemberg present underpenetrated freshwater concession potential for eco-tourism operators. The EU's REACH regulation restricts phthalate-based buoyancy compounds, forcing reformulation of pontoon cores for market entry. Lake Constance and Chiemsee operators are piloting hybrid hydrobike variants for transitional tourist demographics.
Spain
Barcelona's tourism operators are piloting revenue-sharing concession contracts that displace traditional equipment purchase models. The EU Green Deal's material standards are accelerating replacement cycles for legacy buoyancy foams across Mediterranean rental fleets. Costa Brava marina operators are consolidating procurement through equipment financier partnerships.
Canada
Vancouver harbor tourism operators are adopting asset-light leasing structures for fleet expansion in Pacific coastal markets. Health Canada and PMRA govern hull material safety standards for commercial watercraft operating in domestic waterways. British Columbia's lake lodge eco-tourism sector presents seasonal deployment potential for pedal-assist variants.
Hydrobike Market Competitive Landscape
Channel-controlling players compete with product-specialist players for placement in premium marina locations and rental fleet procurement. The vendor base organizes around dockside service agreements, direct-to-rental distribution networks, and carbon-fiber hydrofoil architectures. Three archetypes dominate: equipment financiers with fleet ownership models, performance specialists with hydrofoil engineering capabilities, and full-service providers with dockside maintenance infrastructure. Competitive moves concentrate on strategic partnerships with tourism operators and geographic expansion through concession licensing.
Among North American fabricators, Hydrobikes Inc. and Schiller Bikes occupy positions within the channel-control archetype, while New Zealand-based Manta5 exemplifies the performance-specialist tier. These three companies represent distinct strategic approaches to coastal tourism market penetration, with each anchoring a different competitive vector in fleet procurement and individual enthusiast segments.
| Leading Market Players |
|---|
| Austin Water Bikes |
| Hobie Cat Company |
| Hydrobikes Inc. |
| Manta5 |
| Seabike |
| Yamaha Motor Corporation |
| Dave Cornthwaite |
| Bike Boat |
| Schiller Bikes |
| Others |
Pricing and Supply Chain Analysis
Japanese and South Korean prepreg suppliers for carbon-fiber hydrofoil architectures concentrate upstream input pricing power, while downstream margin pools accrue to equipment financiers operating asset-light leasing partnerships with Mediterranean and Asia-Pacific rental operators.
Pricing Analysis
Certification level (CE marking/REACH compliance versus uncertified recreational grade) creates the primary spread between premium and entry-tier hydrobike procurement. Three-tier pricing structure across hydrofoil-performance, pontoon-stabilized, and basic recreational levels reflects hull material quality and drivetrain sophistication. Cost compression in electric variants is intensifying because UN 38.3 and IEC 62133 battery certification timelines extend commercialization cycles. Rental fleet operators exhibit highest price sensitivity due to seasonal demand volatility, while individual performance enthusiasts demonstrate lowest sensitivity anchored by carbon-fiber specification preferences.
Supply Chain Analysis
Tariff exposure between East Asian prepreg suppliers and EU/US assembly facilities dominates supply chain risk assessment for performance hydrofoil manufacturers. Manufacturing concentration centers on China for polyethylene hull molding, Japan and South Korea for carbon-fiber prepreg, and Australia for reef-tourism concession assembly. Raw material dependencies rest on epoxy resin systems, lithium-ion cell packs, and corrosion-resistant aluminum alloys. Single-source vulnerability from Japanese Toray and South Korean SK Chemicals prepreg allocation constrains hydrofoil variant scaling. Distribution runs through direct manufacturer-to-rental-operator contracts for fleet volume, supplemented by specialty marine retailers for individual enthusiast segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from subscription-based fleet refresh programs and dockside maintenance contracts is expanding faster than hardware sales, repositioning hydrobike market value capture toward recurring-revenue models.
For Market Incumbents: Harden dockside service agreement exclusivity in premium marina locations against emerging equipment financier partnerships threatening placement control. Deepen backward integration into corrosion-resistant coating qualification teams to accelerate EPA compliance timelines for electric variants. Prioritize certification investment in Queensland maritime safety frameworks to defend Australian reef concession share.
For New Entrants and Emerging Players: Pursue underpenetrated Alpine lake districts in Bavaria and Baden-Württemberg where hybrid hydrobike variants address transitional tourist demographics with limited incumbent presence. Target boutique aquatic studio networks in Miami and Sydney through subscription-based fleet refresh programs. Deploy direct-to-rental distribution bypassing specialty retail channel costs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed equipment financiers operating Mediterranean revenue-sharing concession portfolios. Long-term viability hinges on regulatory harmonization completion across EU member states and battery certification standardization. Monitor Queensland maritime safety office certification velocity as inflection indicator for Australia deployment scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Dockside Service Agreement Expansion | Schiller Bikes and Hydrobikes Inc. anchor placement power through marina exclusivity clauses in Miami and Barcelona. |
| CE Marking Harmonization Investment | Pan-European distribution without country-by-country recertification reduces market entry friction for compliant manufacturers. |
| Battery Certification Internalization | In-house UN 38.3 and IEC 62133 testing teams compress six-to-nine-month commercialization delays for electric variants. |
| Carbon-Fiber Supply Diversification | Reducing Toray and SK Chemicals prepreg concentration mitigates allocation risk for hydrofoil architecture scaling. |
| Subscription Fleet Refresh Programs | Revenue-sharing arrangements with boutique aquatic studios in Sydney and Miami displace traditional equipment purchase models. |
Research Methodology
A standing panel of fleet procurement managers at Mediterranean rental operators, dockside service technicians, Queensland maritime safety certification officers, and equipment financier portfolio directors provided ongoing calibration. Primary interviews with these stakeholders combined with secondary validation from EU REACH compliance databases, EPA anti-fouling coating filings, Australian TGA-aligned state maritime records, and SEC equipment manufacturer disclosures. Bottom-up segmentation modeling triangulated against top-down coastal tourism expenditure data.
Scenario-bracketing around regulatory harmonization velocity and battery certification timeline compression anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (recreational/fitness/racing/custom), technology architecture (manual/electric/hybrid/smart), and end-user procurement model (fleet lease versus individual purchase). CAGRs derived from equipment replacement cycle analysis, concession licensing velocity, and demographic accessibility expansion. Forecast inputs incorporated lithium-ion cell cost curves and marina real estate lease rate trajectories.
Macroeconomic conditions sit as an overlay; deviation in coastal tourism expenditure patterns, carbon-fiber input pricing, or EU Green Deal enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline standardization and reef tourism concession scaling. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorcycles, Scooters and Mopeds Market
Bikes and Motorcycles
Two-Wheeler Motorcycle Market
Bikes and Motorcycles
Fuel Cell Bikes Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
Two Wheeler Fenders Market
Bikes and Motorcycles
Bicycle Gear Shifter Market
Bikes and Motorcycles
Asia-Pacific Two-Wheeler Taxi Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Two-Wheeler Fuel Injection Systems Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
South Africa E-Bike Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Europe Motorcycle Airbag Market
Bikes and Motorcycles
Aluminum Alloy Bicycle Crankset Market
Bikes and Motorcycles
Shock Absorber Market