
 Denmark E-Bike Market | 2026-2036
Denmark E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark E-Bike Market Outlook
Electric bicycle technician shortages across Danish service networks is reorganizing how manufacturers build aftermarket loyalty. Royal Dutch Gazelle leverages its established dealer infrastructure to capture repeat maintenance revenue. Van Moof BV differentiates through integrated digital diagnostics that reduce physical service dependency. A. Winther A/S anchors its position in specialized cargo configurations for municipal procurement channels.
An electric bicycle combines a conventional pedal cycle with a rechargeable battery-powered motor delivering supplementary propulsion up to 25 km/h under EU type-approval, with frame-integrated lithium-ion packs and torque-sensor pedal-assist algorithms designed to reduce rider exertion during urban transit and commercial hauling. City E-Bikes dominate unit volume through Copenhagen's cycle superhighway integration, while Cargo E-Bikes command premium positioning as Danish logistics operators replace van fleets for urban parcel distribution. Lithium-Ion batteries sustain technology leadership due to energy density thresholds that dictate range-to-weight ratios across commuter and professional segments.
The Danish Road Traffic Act, CE marking requirements under EU harmonized standards, and F-Gas Regulation compliance for cooling components in battery thermal management systems collectively shape product homologation and market access protocols. Denmark's national building code mandates workplace cycling infrastructure, directly stimulating fleet procurement from employers. Stakeholders must monitor proposed EU Battery Regulation due diligence rules that will recalibrate supply chain accountability and end-of-life recycling obligations.
Market Dynamics
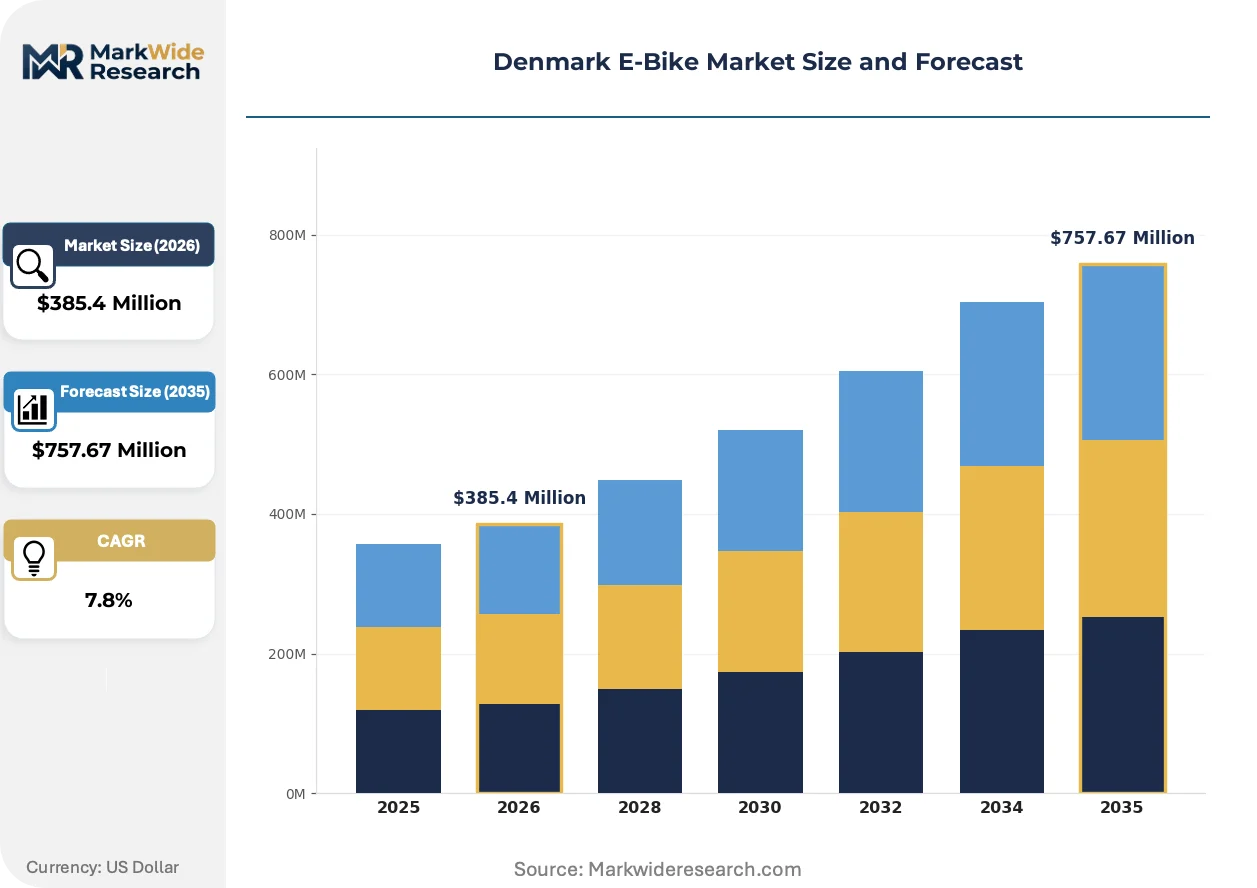
The Danish Road Traffic Act's 25 km/h pedal-assist threshold is concentrating product development around frame-integrated battery architectures and torque-sensor calibration, while Copenhagen's cycle superhighway network funnels commuter demand toward specific urban-optimized geometries.
Growth Catalysts
- The Danish Road Traffic Act:Mandates 25 km/h maximum assisted speed, creating design standardization that reduces homologation costs for domestic manufacturers and accelerates fleet procurement cycles.
- Workplace cycling infrastructure mandates:Denmark's national building code requires employer-provided bicycle parking and charging stations, directly stimulating B2B fleet adoption across Copenhagen and Aarhus corporate campuses.
- Last-mile logistics corridors:Urban freight operators in Copenhagen's central districts are replacing diesel van fleets with cargo e-bike configurations, driven by congestion charging zones and delivery time guarantees.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack manufacturers depend on Asian cell suppliers for energy-dense 18650 and 21700 formats, exposing Danish assemblers to shipping cost volatility and customs processing delays.
- F-Gas Regulation compliance costs:Thermal management systems using fluorinated greenhouse gases face phase-down schedules and leak-checking protocols that inflate R&D expenditure for battery cooling architectures.
- Service network fragmentation:Certified electric bicycle technicians remain scarce outside Copenhagen and Aarhus, extending repair lead times in Jutland and Zealand secondary cities and depressing resale values.
Strategic Opportunities
- Municipal procurement channels:Danish municipalities are tendering specialized cargo configurations for postal services, waste collection, and park maintenance, creating dedicated revenue streams insulated from consumer cyclicality.
- EU Battery Regulation due diligence:Upcoming supply chain accountability rules will reward early adopters of recycled content traceability systems and end-of-life take-back infrastructure with preferential market access positioning.
- Digital diagnostics integration:Over-the-air firmware updates and remote fault detection are reducing physical service dependency, enabling direct-to-consumer distribution models that bypass traditional dealer markups.
Industry Challenges
- Technician certification bottlenecks:Vocational training programs for electric bicycle diagnostics and battery replacement have not scaled with unit sales, creating service backlogs during peak riding seasons.
- CE marking timeline compression:EU type-approval procedures for new motor and battery combinations require 4-6 month validation cycles, delaying product launches behind competitor announcements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark E-Bike Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $757.67 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City E-Bikes, Mountain E-Bikes, Folding E-Bikes, Cargo E-Bikes Battery Type: Lithium-Ion, Lead-Acid, Nickel-Cadmium, Lithium-Polymer Usage Purpose: Commuting, Leisure, Delivery Services, Fitness Consumer Segment: Adults, Seniors, Students, Professionals |
| Companies Covered | Royal Dutch Gazelle, A. Winther A/S, CUBE Bikes, Sensa Bikes, Nørdic Bikes, Giant Manufacturing Co. Ltd, Van Moof BV, Strom Bikes, Principia bikes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark E-Bike Market Strategic Shifts
Frame-integrated battery architectures are displacing bolt-on pack designs as Danish manufacturers optimize for weather sealing and theft deterrence. Regulatory pressure on supply chain transparency is accelerating digital product passport adoption. Urban freight operators are reconfiguring procurement specifications around total cost of ownership rather than upfront unit price.
Mid-drive motor systems with torque-sensor pedal-assist algorithms are displacing hub-motor alternatives in the premium commuter segment. Copenhagen-based fleet operators specify these configurations for hill-climbing efficiency on the city's bridge-intensive cycle routes. The shift is compressing margins for entry-level hub-motor suppliers while rewarding drivetrain specialists with service-contract attach rates.
The EU Battery Regulation's due diligence obligations are reshaping supplier qualification protocols for Danish assemblers. Manufacturers must document cobalt, lithium, and nickel sourcing through audited supply chain maps to maintain CE marking eligibility. Cargo e-bike producers with municipal contracts face the most stringent documentation requirements, as public procurement rules layer additional sustainability verification atop harmonized standards.
Subscription-based fleet management is replacing outright purchase for Copenhagen's last-mile delivery operators. Logistics providers pay per-kilometer fees covering maintenance, battery replacement, and insurance, transferring residual value risk to manufacturers. This model concentrates demand among vertically integrated suppliers capable of underwriting long-term service obligations across Denmark's dispersed geography.
Denmark E-Bike Market Segmentation
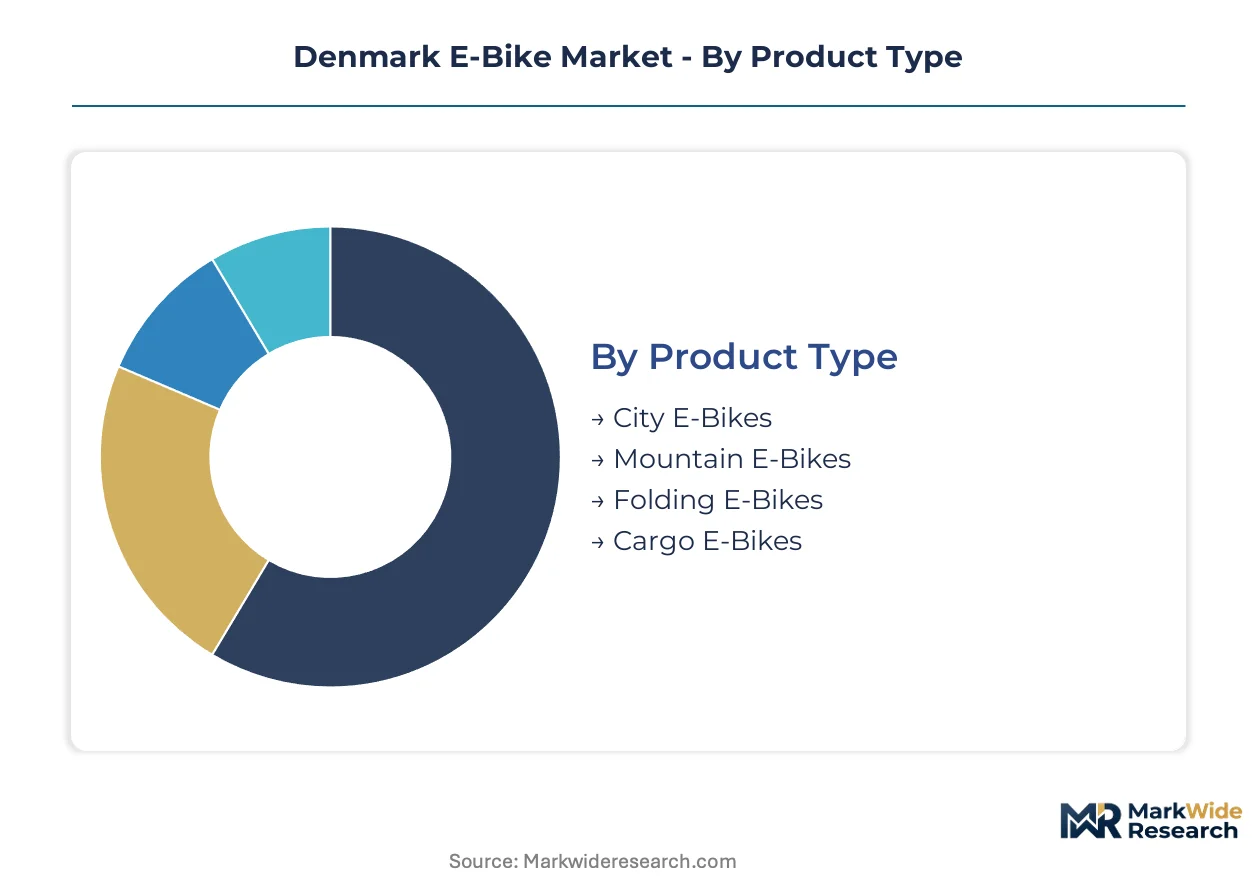
Segmentation in the Danish E-Bike Market reveals how regulatory thresholds and infrastructure investments concentrate demand into specific product configurations. Copenhagen's cycle superhighway network and the Road Traffic Act's 25 km/h limit create distinct competitive dynamics across product categories.
Product Type:
Substitution pressure from conventional bicycles and shared mobility services varies sharply across product configurations, with urban-optimized designs facing the strongest competitive tension from dockless e-scooters and public transit.
- City E-Bikes:Frame-integrated battery architectures with torque-sensor pedal-assist dominate this segment. Copenhagen's cycle superhighway network funnels commuter demand toward low-step geometries optimized for stop-and-start urban transit. Municipal fleet procurement from employers with workplace cycling infrastructure mandates sustains volume.
- Cargo E-Bikes:Specialized configurations with extended wheelbases and reinforced frames command premium positioning. Last-mile logistics operators in Copenhagen's central districts replace diesel van fleets to meet congestion charging compliance and delivery time guarantees. Municipal tenders for postal services and waste collection create dedicated B2B revenue streams.
- Mountain E-Bikes:Mid-drive motor systems with high-torque output for off-road terrain face limited domestic demand due to Denmark's flat topography.
- Folding E-Bikes:Compact designs with hinge-frame architectures target multimodal commuters integrating train and bicycle travel across Zealand's regional rail network.
City E-Bikes retain volume leadership; Cargo E-Bikes hold the steepest expansion curve.
Battery Type:
Cost tier stratification separates energy-dense premium configurations from heavier, price-sensitive alternatives, with supply chain concentration dictating margin pressure across Danish assemblers.
- Lithium-Ion:18650 and 21700 cylindrical cell formats deliver the energy density thresholds that dictate range-to-weight ratios. Danish manufacturers depend on Asian cell suppliers, exposing assemblers to shipping cost volatility and customs processing delays. CE marking requirements and upcoming EU Battery Regulation due diligence rules recalibrate supplier qualification protocols.
- Lithium-Polymer:Pouch-cell architectures enable custom form factors for frame integration in premium urban designs. Copenhagen-based fleet operators specify these configurations for theft-deterrent battery concealment. F-Gas Regulation compliance for thermal management systems inflates R&D expenditure.
- Lead-Acid:Sealed lead-acid packs persist in entry-level price tiers despite weight penalties that degrade handling.
- Nickel-Cadmium:Legacy chemistry with limited presence due to environmental disposal restrictions and inferior cycle life.
Lithium-Ion retains volume leadership; Lithium-Polymer holds the steepest expansion curve.
Usage Purpose:
Application-specific requirements drive divergent product specifications, with commercial use cases demanding durability certifications absent from consumer segments.
- Commuting:Daily urban transit applications specify integrated lighting, fender coverage, and rack compatibility. Copenhagen and Aarhus corporate campuses with workplace cycling infrastructure mandates stimulate fleet procurement. Weather sealing and torque-sensor calibration prioritize reliability over performance.
- Delivery Services:High-utilization operators require modular battery swapping and reinforced frames for cargo capacity. Subscription-based fleet management models transfer residual value risk to manufacturers capable of underwriting long-term service obligations.
- Leisure:Recreational riders prioritize comfort geometries and extended range for weekend excursions across Denmark's coastal routes.
- Fitness:Performance-oriented users seek minimal assist modes that preserve physical exertion metrics.
Commuting retains volume leadership; Delivery Services holds the steepest expansion curve.
Consumer Segment:
Customer type fragmentation reflects Denmark's demographic structure and cycling culture penetration across age and employment categories.
- Adults:Prime working-age consumers constitute the core market for daily transportation replacement. Copenhagen's bridge-intensive cycle routes favor mid-drive motor systems with hill-climbing efficiency.
- Professionals:Corporate fleet users benefit from employer-subsidized procurement through workplace cycling infrastructure mandates. Tax treatment of company bicycles accelerates B2B adoption.
- Seniors:Low-step frame designs with stability-optimized geometries address mobility maintenance needs in Denmark's aging population.
- Students:Price-sensitive demand concentrates on folding configurations for university campus storage constraints and theft risk mitigation.
Adults retain volume leadership; Professionals holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's e-bike consumption concentrates in urban corridors with cycle superhighway infrastructure, while secondary cities exhibit markedly different adoption patterns tied to commuter rail integration rather than standalone cycling networks.
Capital Region
Copenhagen's cycle superhighway network funnels commuter demand toward frame-integrated city e-bikes with torque-sensor calibration. The Danish Road Traffic Act's 25 km/h threshold shapes municipal fleet procurement specifications. Frederiksberg and Gentofte municipalities anchor cargo e-bike adoption for postal and waste collection services.
Central Denmark Region
Aarhus corporate campuses drive B2B fleet adoption through workplace cycling infrastructure mandates under Denmark's national building code. Mid-drive motor systems dominate bridge-intensive commuting routes. Randers and Silkeborg secondary cities face technician certification bottlenecks that extend repair lead times.
Southern Denmark Region
Odense multimodal commuters integrate folding e-bikes with regional rail services across Funen. The city's cargo e-bike logistics pilots for urban freight operators attract municipal tender participation. Svendborg and Kerteminde exhibit lower penetration due to dispersed settlement patterns.
North Jutland Region
Aalborg's university campus demand concentrates on price-sensitive folding configurations with theft-deterrent battery concealment. Student procurement cycles align with academic calendar peaks. Hjørring and Frederikshavn face service network fragmentation that depresses resale values.
Zealand Region
Roskilde and Køge logistics corridors replace diesel van fleets with cargo e-bikes to meet congestion charging compliance. The region's coastal leisure routes sustain recreational demand for extended-range configurations. Næstved and Slagelse lag in charging infrastructure deployment.
Denmark E-Bike Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding municipal procurement channels and subscription fleet management contracts while specialists anchor niche cargo configurations and digital diagnostics. The market structure rewards backward integration into battery thermal management and in-house production of frame-integrated architectures. Two strategic archetypes dominate: vertically integrated assemblers with service-contract underwriting capabilities, and component specialists with torque-sensor calibration expertise. Competitive moves concentrate on geographic expansion through dealer infrastructure acquisition and technology licensing for over-the-air firmware systems.
Within the integrated tier, Royal Dutch Gazelle and Van Moof BV exemplify divergent approaches to aftermarket loyalty—Gazelle through established dealer networks, Van Moof through remote diagnostics that reduce physical service dependency. A. Winther A/S occupies a specialized position in municipal cargo procurement. These three entities represent distinct competitive vectors: infrastructure-heavy distribution, digitally-enabled direct-to-consumer models, and public-sector contract specialization.
| Leading Market Players |
|---|
| Royal Dutch Gazelle |
| A. Winther A/S |
| CUBE Bikes |
| Sensa Bikes |
| Nørdic Bikes |
| Giant Manufacturing Co. Ltd |
| Van Moof BV |
| Strom Bikes |
| Principia bikes |
| Others |
Value Chain & Pricing Dynamics
Asian cell supplier scale economies in 18650 and 21700 cylindrical formats anchor cost floors for Danish assemblers, compressing margin flexibility while concentrating procurement leverage among vertically integrated pack manufacturers with direct cathode material sourcing.
Pricing Analysis
Long-term offtake contracts dominate procurement between Danish fleet operators and cargo e-bike manufacturers, insulating municipal buyers from lithium carbonate spot volatility while exposing smaller assemblers to price squeezes. Three-tier pricing structure across premium torque-sensor configurations, standard hub-motor designs, and economy lead-acid alternatives separates service-contract bundled offerings from transactional unit sales. Cost compression in entry-level tiers is intensifying because Asian cell suppliers prioritize 21700 format allocation to automotive contracts. Students and price-sensitive leisure riders exhibit highest price sensitivity; municipal procurement channels with total-cost-of-ownership mandates show lowest.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Copenhagen-based fleet operators with subscription-service obligations, while strategic stockpiling of 21700 cells concentrates among assemblers with municipal tender exposure. Cell production draws from China, South Korea, and Japan; frame manufacturing rests on Taiwanese aluminum extrusion; software calibration centers on Dutch and German motor controller specialists. Single-source vulnerability in cathode active material processing creates concentrated disruption risk. Distribution runs through dealer networks in Copenhagen and Aarhus, with direct-to-consumer digital channels gaining share among urban commuters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Denmark E-Bike Market is recovering from technician certification bottlenecks that depressed service capacity through peak riding seasons, with workplace cycling infrastructure mandates providing cyclical floor support for B2B fleet procurement.
For Market Incumbents: Compound dealer infrastructure density in Jutland and Zealand secondary cities to capture service revenue currently lost to independent repair backlogs. Extend backward integration into battery thermal management systems to reduce F-Gas Regulation compliance cost exposure. Prioritize municipal procurement channel lock-in through subscription fleet management underwriting capabilities that transfer residual value risk from public sector buyers. For New Entrants and Emerging Players: Differentiate on over-the-air firmware diagnostics that reduce physical service dependency, targeting Zealand Region logistics corridors with congestion charging compliance requirements. White-space availability concentrates in cargo e-bike configurations for Southern Denmark Region municipal tenders, where incumbent presence remains thin. Direct-to-consumer digital distribution with remote fault detection bypasses traditional dealer markups and accelerates customer acquisition cost recovery. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated assemblers with subscription fleet management contracts and in-house battery pack production. Long-term viability over a multi-year horizon favors targets with municipal procurement channel density and EU Battery Regulation due diligence infrastructure already deployed. Watch cargo e-bike tender win rates in secondary Danish municipalities as inflection indicator for subscription model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Expansion | Captures aftermarket service revenue in Jutland and Zealand secondary cities where technician scarcity depresses incumbent coverage. |
| Battery Thermal Management Integration | Reduces F-Gas Regulation compliance costs and accelerates CE marking timelines for frame-integrated architectures. |
| Subscription Fleet Management Launch | Transfers residual value risk to manufacturers while locking in municipal procurement channels with long-term service obligations. |
| Digital Diagnostics Platform Deployment | Enables direct-to-consumer distribution models that bypass traditional dealer markups in Copenhagen commuter segments. |
| EU Battery Regulation Compliance Infrastructure | Secures preferential market access positioning through audited cobalt and lithium supply chain traceability systems. |
Study Parameters
Initial hypotheses were tested against primary input from electric bicycle fleet procurement managers, municipal tender officers, dealer network operators, and battery pack assembly engineers and refined through secondary validation against Danish Road Traffic Act regulatory filings, EU type-approval documentation, customs import records for lithium-ion cells, and workplace cycling infrastructure mandate compliance reports. Bottom-up unit sales estimates from regional dealer networks were triangulated with top-down market sizing derived from municipal fleet procurement disclosures and employer bicycle benefit program participation data.
Variance decomposition across product type, battery chemistry tier, usage purpose, and consumer segment dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic cycling participation trends and infrastructure investment pipelines. Forecast inputs incorporated Copenhagen congestion charging zone expansion schedules and Aarhus corporate campus cycling facility deployment timelines.
Forecasts assume regulatory continuity in Danish Road Traffic Act speed thresholds and EU Battery Regulation due diligence implementation; material policy shifts would require re-modeling of supplier qualification costs and end-of-life recycling obligation impacts. Revision becomes warranted when lithium-ion cell shipping cost volatility or customs processing delays cross thresholds that alter assembler margin structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Automotive Chain Sprockets Market
Bikes and Motorcycles
E-Cargo Bike Market
Bikes and Motorcycles
Bike Kickstand Market
Bikes and Motorcycles
Two Wheeler Handlebars Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
Fixed Gear Bikes Market
Bikes and Motorcycles
Emission Control Catalyst for Motorcycle Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Carbon Fiber Bicycle Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Motorbike Riding Gear Market
Bikes and Motorcycles
Two-Wheeler Market
Bikes and Motorcycles
China Two Wheeler Market
Bikes and Motorcycles
Sweden E-Bike Market