
 Two-Wheeler Lighting Market | 2026-2036
Two-Wheeler Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Two-Wheeler Lighting Market Outlook
Aftermarket service revenue is narrowing as OEMs bundle lighting into platform warranty packages and captive service networks. FIEM Industries leverages its vertical integration into lens molding and electronics assembly to defend margin pools in integrated headlamp supply. Uno Minda anchors its position through deep channel control across Indian two-wheeler OEMs, while Varroc Lighting competes on manufacturing scale in tail lamp and indicator exports to European motorcycle brands.
Two-wheeler lighting encompasses the complete photometric system—headlamps, tail lamps, indicators, and auxiliary lamps—engineered to meet precise luminous intensity, beam pattern, and color-rendering specifications for motorized bicycles, scooters, and motorcycles. LED technology dominates new platform development due to superior efficacy, thermal management, and design flexibility in compact housing geometries. Halogen retains volume leadership in replacement cycles across price-sensitive segments, though LED retrofits are capturing margin pools in premium aftermarket channels. Headlights concentrate the highest engineering investment, while indicators and tail lights standardize faster across OEM platforms.
India's BIS mandates headlamp performance testing under AIS-010 standards, while European type approval requires ECE R112 compliance for LED and halogen headlamp units sold in member states. Japan's METI enforces JIS D 5500 safety specifications that Koito Manufacturing and Stanley Electric navigate for domestic OEM supply. Stakeholders must monitor how India's PLI scheme for automotive components reshapes supplier qualification thresholds and whether ECE regulatory updates accelerate laser headlamp adoption in premium motorcycle segments.
Market Dynamics
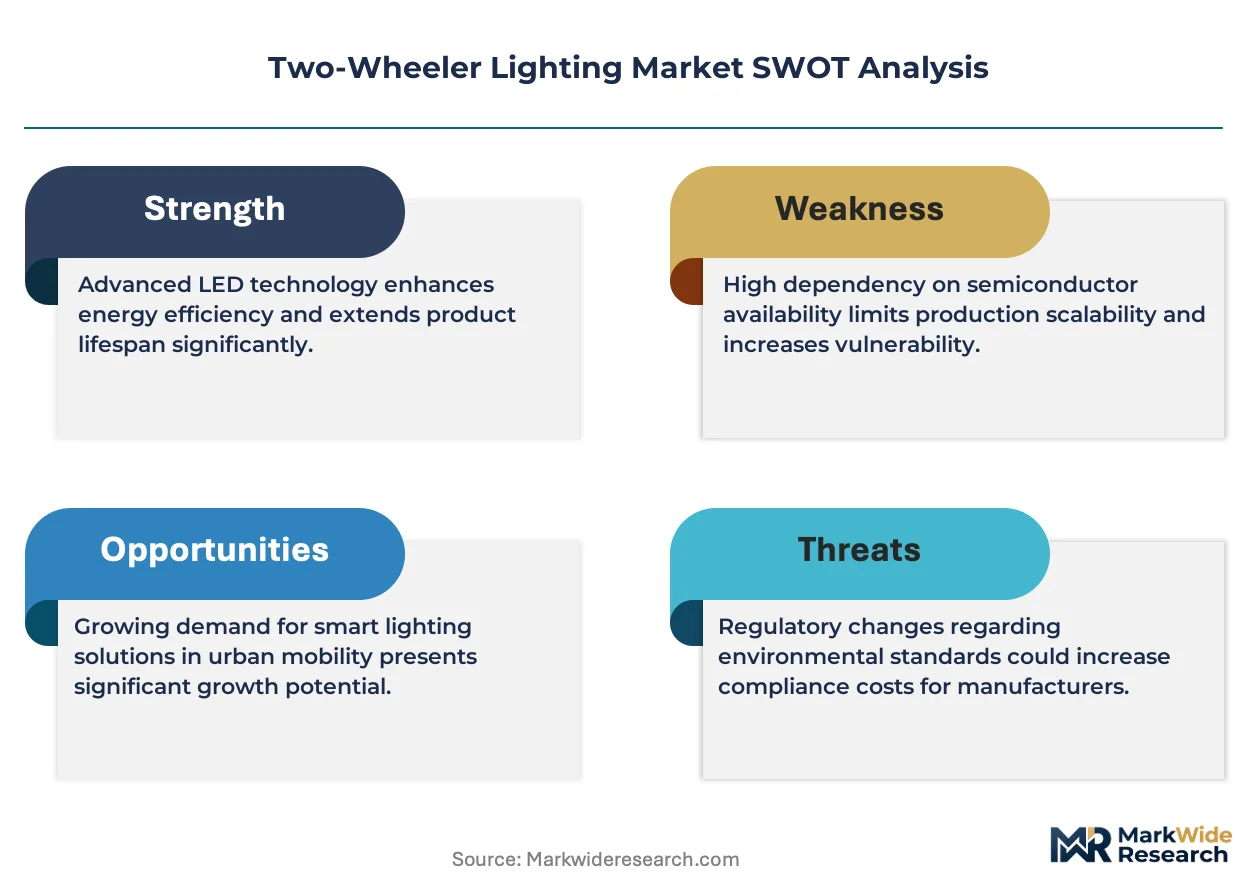
LED module integration is compressing supplier tiers as headlamp assemblies consolidate electronics, thermal management, and optics into single-source platforms, forcing halogen-dependent suppliers to retool or exit.
Growth Catalysts
- BIS AIS-010 Mandate:India's compulsory headlamp performance testing is accelerating OEM platform redesigns toward LED-compliant architectures, creating captive demand for certified module suppliers.
- Thermal Management Advances:Compact heat-sink designs and ceramic substrate materials are enabling LED deployment in 100cc-125cc commuter segments previously reserved for halogen.
- Southeast Asia Production Clusters:Thailand and Vietnam two-wheeler export hubs are localizing lighting supply to meet European type-approval requirements for LED tail lamp assemblies.
Market Restraints
- Aluminum Die-Cast Volatility:Housing material cost swings compress margin pools for mid-tier suppliers unable to pass through input price adjustments to OEMs.
- Optics Design Bottleneck:Precision lens molding capability concentrates among Japanese and German equipment holders, creating supply chokepoints for complex beam-pattern modules.
- Halogen Replacement Cycle Collapse:Extended LED lifespans are shrinking aftermarket parts turnover, eroding service revenue for independent distributors.
Strategic Opportunities
- India PLI Component Incentive:The production-linked incentive scheme for automotive electronics is lowering capital barriers for domestic LED driver circuit manufacturing.
- Laser Headlamp Convergence:Premium motorcycle segments are piloting laser-diode high-beam modules that extend throw distance beyond LED physical limits.
- Direct-to-Workshop Channels:Digital parts platforms are disintermediating traditional distributor networks for LED retrofit kits in urban Indian service clusters.
Industry Challenges
- Photometric Simulation Talent Scarcity:OEMs and suppliers compete for optical engineers capable of ray-tracing validation for complex free-form reflector designs.
- ECE R112 Certification Timelines:European type-approval testing for adaptive headlamp systems extends platform launch schedules by 8-14 months.
- Legacy Harness Integration:Retrofitting LED modules into existing wiring architectures without CAN-bus infrastructure creates voltage-mismatch failures in field deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two-Wheeler Lighting Market |
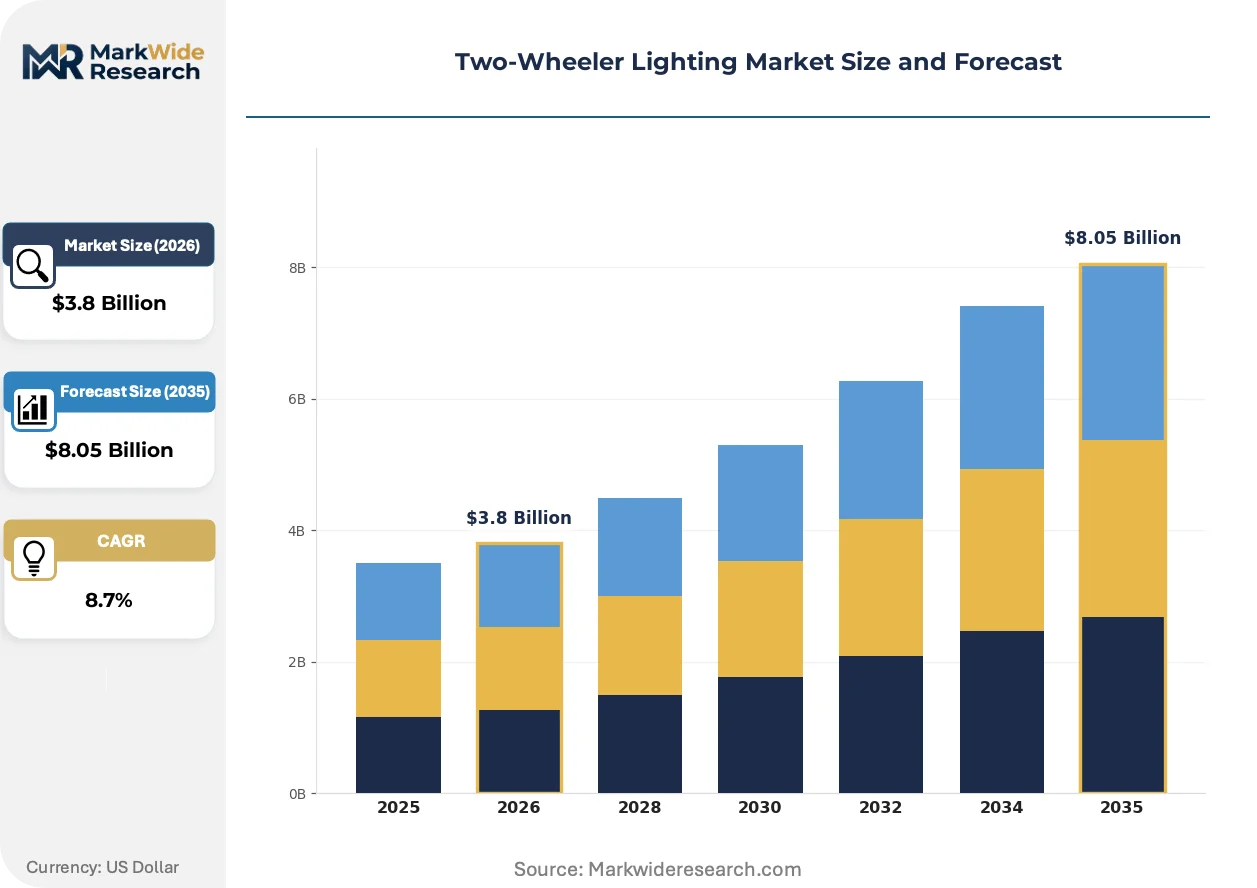
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Tail Lights, Indicators, Fog Lights Technology: Halogen, LED, Xenon, Laser End User: Manufacturers, Aftermarket Providers, Retailers, OEMs Installation Type: Integrated, Retrofit, Modular, Custom Fit |
| Companies Covered | FIEM Industries, Uno Minda, Varroc Lighting, Lumax Industries, OSRAM, HELLA, Koito Manufacturing, Hyundai Mobis, Stanley Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two-Wheeler Lighting Market Strategic Shifts
Module-level integration is eliminating discrete component boundaries as lighting systems absorb sensor inputs and communication protocols previously housed in separate vehicle domains.
Matrix LED arrays with pixel-level beam control are rendering obsolete traditional high-low beam mechanical shutters in premium motorcycle headlamp designs. European OEMs are adopting these systems fastest to meet ECE R123 glare-free requirements. The technology is compressing supplier differentiation toward software-defined beam patterns rather than hardware optics.
India's PLI scheme for automotive components is redirecting supplier capital toward in-house LED chip-on-board assembly. The incentive structure rewards domestic value-add above import thresholds, tightening qualification windows for foreign component sources. Tier-1 lighting suppliers are responding with joint ventures in Tamil Nadu and Gujarat electronics corridors.
Workshop procurement patterns are fragmenting as aggregator platforms aggregate demand across independent service points. These channels bypass traditional state-level distributor hierarchies for LED indicator and tail lamp replacements. The shift concentrates order flow in Mumbai, Delhi, and Bangalore urban service clusters where digital penetration deepest.
Two-Wheeler Lighting Market Segmentation
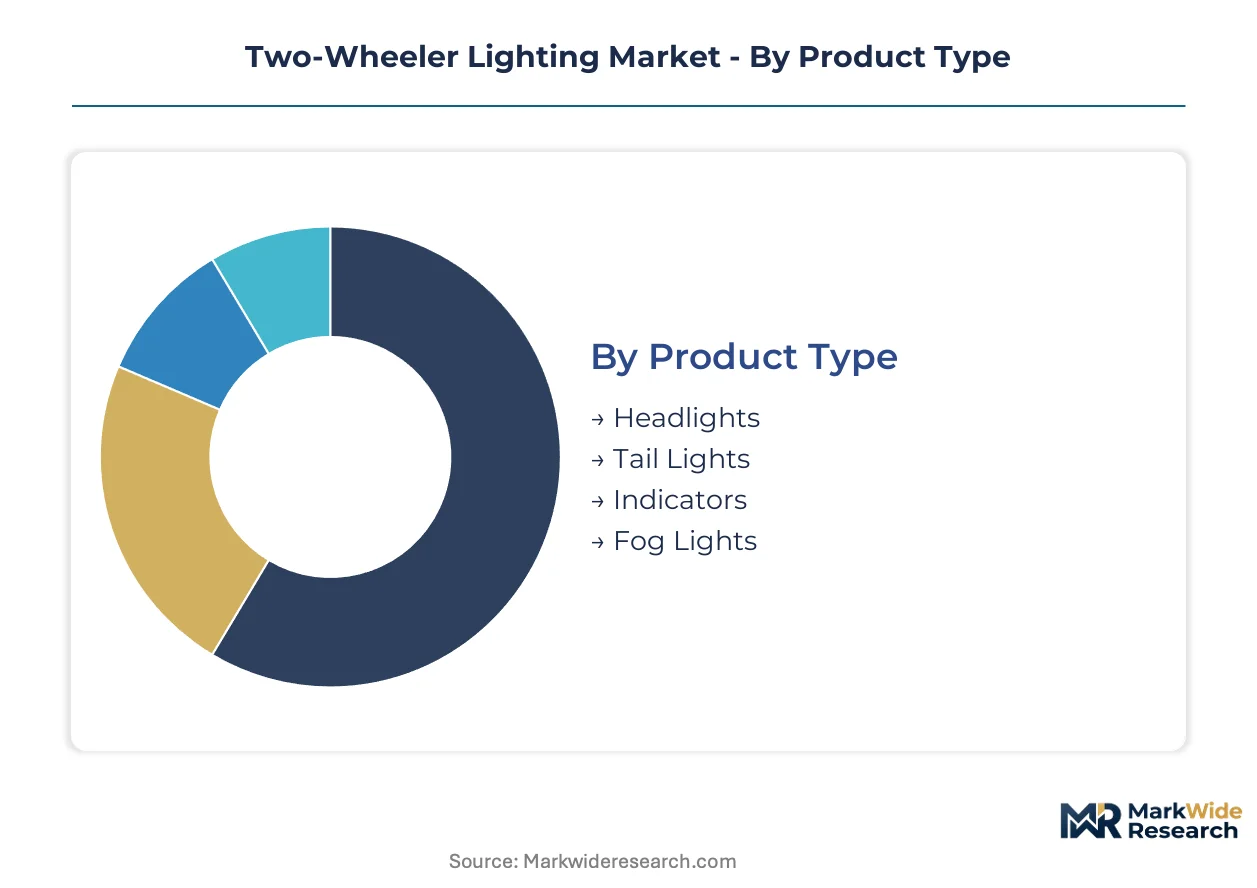
Segmentation in two-wheeler lighting reveals divergent margin structures across product categories. Aftermarket service intensity varies dramatically by technology vintage and installation complexity, reshaping supplier portfolio priorities.
Product Type:
Aftermarket service intensity peaks with headlight assemblies requiring precise beam alignment, while tail lamps and indicators standardize faster with lower technical intervention.
- Headlights:These assemblies integrate reflector optics, housing, and electronics into sealed units demanding specialized calibration equipment. Demand concentrates in Indian OEM procurement as BIS AIS-010 certification tightens compliance requirements for beam pattern precision.
- Tail Lights:LED tail lamp modules incorporate sequential indicators and brake-light intensity modulation. European motorcycle brands source these from Thai and Vietnamese export clusters to satisfy ECE R6 visibility standards.
- Indicators:Turn signal units prioritize durability against vibration and moisture ingress.
- Fog Lights:Auxiliary forward lighting for low-visibility conditions remains concentrated in premium motorcycle segments.
By volume, Indicators lead. By growth pace, Headlights are ahead.
Technology:
Cost tier stratification separates premium diode architectures from commodity filament replacements, with thermal management requirements determining supplier qualification thresholds.
- Halogen:Tungsten-halogen filaments dominate replacement cycles in price-sensitive commuter segments across India and Southeast Asia. Extended LED lifespans are compressing halogen aftermarket turnover, eroding distributor revenue pools.
- LED:Chip-on-board assemblies with ceramic substrates enable deployment in 100cc-125cc segments previously reserved for halogen. India's PLI scheme for automotive electronics is accelerating domestic LED driver circuit manufacturing.
- Xenon:High-intensity discharge systems require ballast electronics and precise arc positioning.
- Laser:Diode-pumped high-beam modules extend throw distance beyond LED physical limits in premium motorcycle segments.
Halogen retains volume dominance. Laser displays the steepest expansion trajectory.
End User:
Customer type determines procurement channel structure, with captive OEM networks diverging sharply from fragmented independent service points.
- Manufacturers:Two-wheeler OEMs specify lighting modules at platform design stage, locking in multi-year supply agreements.
- Aftermarket Providers:Independent distributors and service chains source replacement units for out-of-warranty vehicles.
- Retailers:Parts shops and online platforms sell direct to consumers for DIY installation.
- OEMs:Original equipment manufacturers bundle lighting into platform warranty packages and captive service networks.
Manufacturers command the largest revenue share. Aftermarket Providers are expanding most quickly through digital platform aggregation.
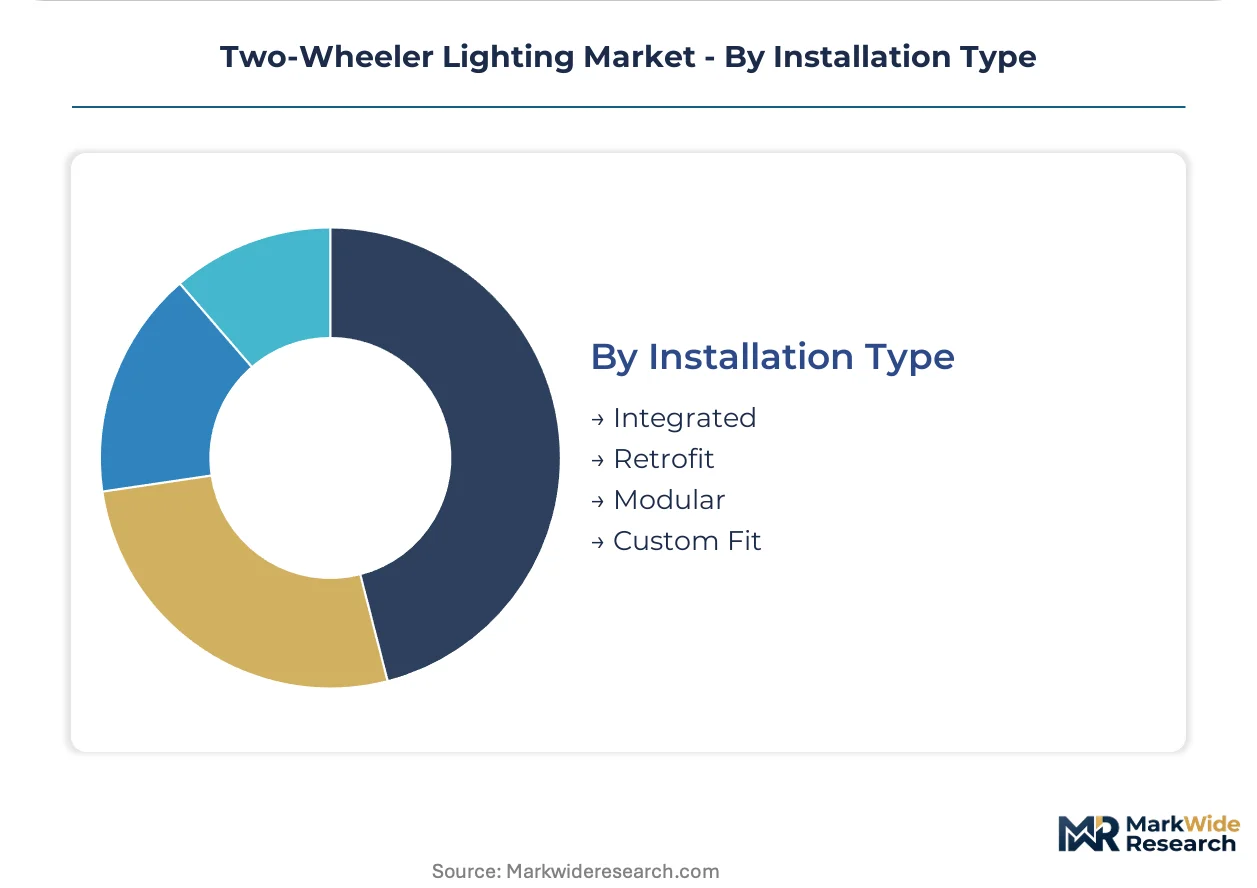
Installation Type:
Volume scale concentrates in factory-integrated units, while retrofit channels capture margin in premium customization segments.
- Integrated:Lighting modules installed during vehicle assembly require zero subsequent calibration.
- Retrofit:LED conversion kits for halogen housings demand beam pattern validation to avoid glare violations.
- Modular:Swappable component designs enable field replacement of individual optical elements.
- Custom Fit:Bespoke housing geometries for cruiser and adventure motorcycle segments.
Integrated leads by production volume. Custom Fit gains share fastest in premium personalization markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across major two-wheeler lighting markets, with India and Southeast Asia exhibiting acute cost sensitivity while European and Japanese buyers absorb premium diode architectures. This demand gradient reshapes supplier qualification thresholds and platform engineering priorities.
India
BIS AIS-010 headlamp certification mandates are accelerating OEM platform redesigns toward LED-compliant architectures across 100cc-125cc commuter segments. The PLI scheme for automotive electronics is redirecting supplier capital toward in-house LED chip-on-board assembly in Tamil Nadu and Gujarat electronics corridors.
Thailand
Two-wheeler export hub status drives localization of LED tail lamp supply to satisfy ECE R6 visibility standards for European motorcycle brands. The country's national automotive regulator enforces type-approval alignment with EU directives, compressing certification timelines for module suppliers.
Vietnam
Production clusters serving Japanese and European OEMs concentrate lighting module sourcing in Ho Chi Minh City industrial zones. Domestic assembly plants are upgrading photometric testing capacity to reduce reliance on third-party certification for indicator and tail lamp exports.
Germany
Premium motorcycle manufacturers specify ECE R112-compliant LED and laser headlamp systems with adaptive beam control. KBA type-approval requirements for glare-free matrix arrays extend platform development cycles, favoring suppliers with integrated electronics-optics capabilities.
Japan
METI-enforced JIS D 5500 specifications govern domestic OEM supply relationships for headlamp and auxiliary lighting. Kanto and Kansai industrial belts host concentrated optical engineering talent for precision reflector design and ray-tracing validation.
Two-Wheeler Lighting Market Competitive Environment
Capability concentration sits with integrated electronics-optics specialists; scale advantage sits with high-volume housing and module fabricators. The supplier base stratifies into three tiers: full-system integrators controlling thermal management and beam-pattern software; component specialists dominating precision lens molding; and commodity assemblers competing on die-cast housing throughput. Consolidation pressure is intensifying as headlamp modules absorb sensor inputs and communication protocols, forcing tier-2 electronics suppliers into acquisition targets or joint venture structures.
Among Indian-origin suppliers, FIEM Industries, Uno Minda, and Varroc Lighting occupy distinct competitive positions. FIEM Industries exemplifies the vertically integrated archetype with captive lens molding and electronics assembly capacity. Uno Minda represents channel-anchored scale players with deep OEM relationships across domestic two-wheeler manufacturers. Varroc Lighting sits within the export-oriented fabrication tier, serving European motorcycle brands from Southeast Asian production bases. These three anchors illustrate how geographic footprint and integration depth determine margin pool access in a market compressing supplier tiers.
| Leading Market Players |
|---|
| FIEM Industries |
| Uno Minda |
| Varroc Lighting |
| Lumax Industries |
| OSRAM |
| HELLA |
| Koito Manufacturing |
| Hyundai Mobis |
| Stanley Electric |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Indian die-cast housing facilities is compressing supplier margins and forcing tier-2 fabricators toward consolidation or exit, while OEM procurement teams exploit utilization gaps to extract price concessions on LED module assemblies.
Pricing Analysis
Long-term offtake contracts dominate OEM procurement of integrated headlamp modules, with multi-year agreements locking in volume commitments from Indian and Southeast Asian manufacturers. Pricing stratifies across premium matrix-LED systems, standard LED architectures, and economy halogen replacements, with BIS AIS-010 certification tier acting as the primary price differentiation driver. Cost compression in commodity halogen housings is intensifying because aluminum input volatility transfers directly to supplier P&Ls. Aftermarket distributors serving price-sensitive commuter segments exhibit acute price sensitivity, while European premium motorcycle OEMs absorb diode premiums for ECE R112-compliant adaptive systems.
Supply Chain Analysis
Aluminum ingot and polycarbonate resin feed from China, India, and Thailand anchor upstream material flows for housing and lens fabrication. LED chip-on-board assemblies draw from Taiwanese and South Korean substrate suppliers, while precision optics equipment concentrates among German and Japanese equipment holders. Single-source vulnerability in ceramic substrate supply creates chokepoints for thermal management modules. Distribution runs through captive OEM service networks for integrated assemblies and digital aggregator platforms for retrofit kit fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Module-level platform economics are displacing discrete component boundaries as lighting systems absorb sensor and communication functions, creating winner-take-most dynamics for suppliers controlling software-defined beam architectures.
For Market Incumbents: Pre-empt tier collapse by acquiring tier-2 electronics suppliers before joint venture structures lock out independent access to LED driver circuit capacity. FIEM Industries and Uno Minda demonstrate how backward integration into lens molding defends margin pools against halogen-dependent competitors facing retooling costs. Channel control across Indian OEM procurement desks remains the priority lever against emerging digital platform disintermediation. For New Entrants and Emerging Players: Pursue direct-to-workshop LED retrofit aggregation in Mumbai, Delhi, and Bangalore service clusters where digital penetration bypasses traditional state-level distributor hierarchies. The penetrable white-space sits in 100cc-125cc commuter LED conversion kits where thermal management advances enable diode deployment previously reserved for halogen. A workshop-facing digital procurement platform with same-day fulfillment anchors viable go-to-market positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across LED chip-on-board assembly as India's PLI scheme rewards domestic value-add above import thresholds. Long-term viability over the next decade hinges on qualification for OEM platform design-stage specification rather than aftermarket replacement cycles. Acquisition targets should display integrated electronics-optics capabilities with existing BIS or ECE certification pipelines. The signal to watch is PLI scheme disbursement velocity as indicator of domestic manufacturing commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Driver Circuit Manufacturing | PLI scheme incentives in Tamil Nadu and Gujarat lower capital barriers for domestic chip-on-board assembly. |
| Matrix LED Array Platform Development | ECE R123 glare-free requirements in Europe compress supplier differentiation toward software-defined beam control. |
| Digital Workshop Channel Aggregation | Urban Indian service clusters in Mumbai and Delhi bypass traditional distributor hierarchies for retrofit kit procurement. |
| Precision Lens Molding Capability Acquisition | Japanese and German equipment concentration creates supply chokepoints for complex beam-pattern modules. |
| Joint Venture in Southeast Asian Export Hubs | Thailand and Vietnam production clusters localize supply to meet European type-approval for tail lamp assemblies. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of BIS certification registries, ECE type-approval databases, and vehicle production records. Interviews with OEM platform engineers, tier-1 lighting supplier procurement teams, aftermarket distributor network heads, and photometric testing laboratory directors informed demand-side validation. Secondary sources include AIS-010 compliance filings, PLI scheme disbursement records, and trade data on aluminum die-cast and LED component imports. Bottom-up module shipment estimates triangulate against top-down two-wheeler production forecasts across Indian and Southeast Asian manufacturing clusters.
Forecast inputs span technology vintage, vehicle displacement class, OEM tier positioning, and regional regulatory compliance tier. Segmentation dimensions cover product type, diode architecture, installation configuration, and end-user procurement channel. Growth trajectory derivation rests on production volume elasticity to safety mandate timing and supplier qualification threshold shifts. Industry-specific inputs incorporate BIS AIS-010 enforcement phasing and ECE R112 adaptive system adoption curves across premium motorcycle platforms.
Sensitivities concentrate around PLI scheme continuation, aluminum price volatility, and ECE regulatory updates accelerating laser headlamp adoption. Forecasts embed assumptions on OEM platform redesign cycles and aftermarket digital channel penetration that material deviations could revise. Cross-checking against IHS Markit vehicle registration data and component import trajectories is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Global Two Wheeler Accessories Market
Bikes and Motorcycles
Two Wheeler Suspension System Market
Bikes and Motorcycles
India Two Wheeler Market
Bikes and Motorcycles
Germany E-Bike Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
Bike Kickstand Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Europe Motorcycle ADAS Market
Bikes and Motorcycles
Europe E Bike Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Europe Bicycle Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
Shock Absorber Market
Bikes and Motorcycles
Hydrobike Market
Bikes and Motorcycles
Switzerland E-Bike Market