
 Bike Kickstand Market | 2026-2036
Bike Kickstand Market Size, Share, and Industry Trends Forecast 2026-2036
Bike Kickstand Market Analytics
Taiwan is rewriting the competitive map for bicycle component manufacturing with dedicated kickstand foundries in Taichung and Kaohsiung. Pletscher anchors European premium positioning through Swiss-engineered side stand designs. Greenfield Industries dominates North American aftermarket channels with steel-based permanent mount lines. Decathlon leverages vertical retail integration to control pricing across adjustable stand SKUs.
A bike kickstand is a mechanical support arm, typically fabricated from aluminum alloy or steel tubing with a hardened rubber or thermoplastic foot, that maintains a bicycle in an upright stationary position when parked. The device employs a spring-loaded pivot mechanism or friction hinge to deploy and retract, with load ratings commonly engineered to support frames from lightweight road bikes to cargo e-bikes exceeding 25 kilograms. Side stand configurations lead volume due to universal compatibility with diamond-frame geometries, while center stand variants command margin premiums in the European utility cycling segment where stability during loading is critical. Carbon fiber kickstands remain a nascent category constrained by cost, though racing enthusiasts represent a concentrated addressable niche for weight-optimized integrated designs.
REACH compliance in Europe restricts certain chromate surface treatments, redirecting supply chains toward anodized aluminum finishes. The EU Green Deal's embodied carbon reporting requirements are forcing material transparency from Taiwanese OEMs through German distributors. Japan's JIS standards for bicycle accessories create a separate compliance threshold for kickstand fatigue testing that limits market access for uncertified producers. Stakeholders must monitor whether stricter e-bike weight classifications in major cycling markets will redefine load-bearing specifications across product tiers.
Market Dynamics
The EU Green Deal's circular economy mandates are forcing kickstand manufacturers to re-engineer material specifications and supply chain transparency protocols across European distribution channels.
Growth Catalysts
- E-bike fleet replacement cycles:Netherlands commuter bike-share operators are driving aftermarket demand for reinforced side stands rated above 25 kilograms.
- REACH chromate restrictions:The European Chemicals Agency's surface treatment prohibitions are accelerating anodized aluminum adoption among Taiwanese OEM suppliers.
- Industrial cluster concentration:Stuttgart and Munich manufacturing zones are consolidating procurement for utility cycling OEMs seeking fatigue-tested center stand configurations.
Market Restraints
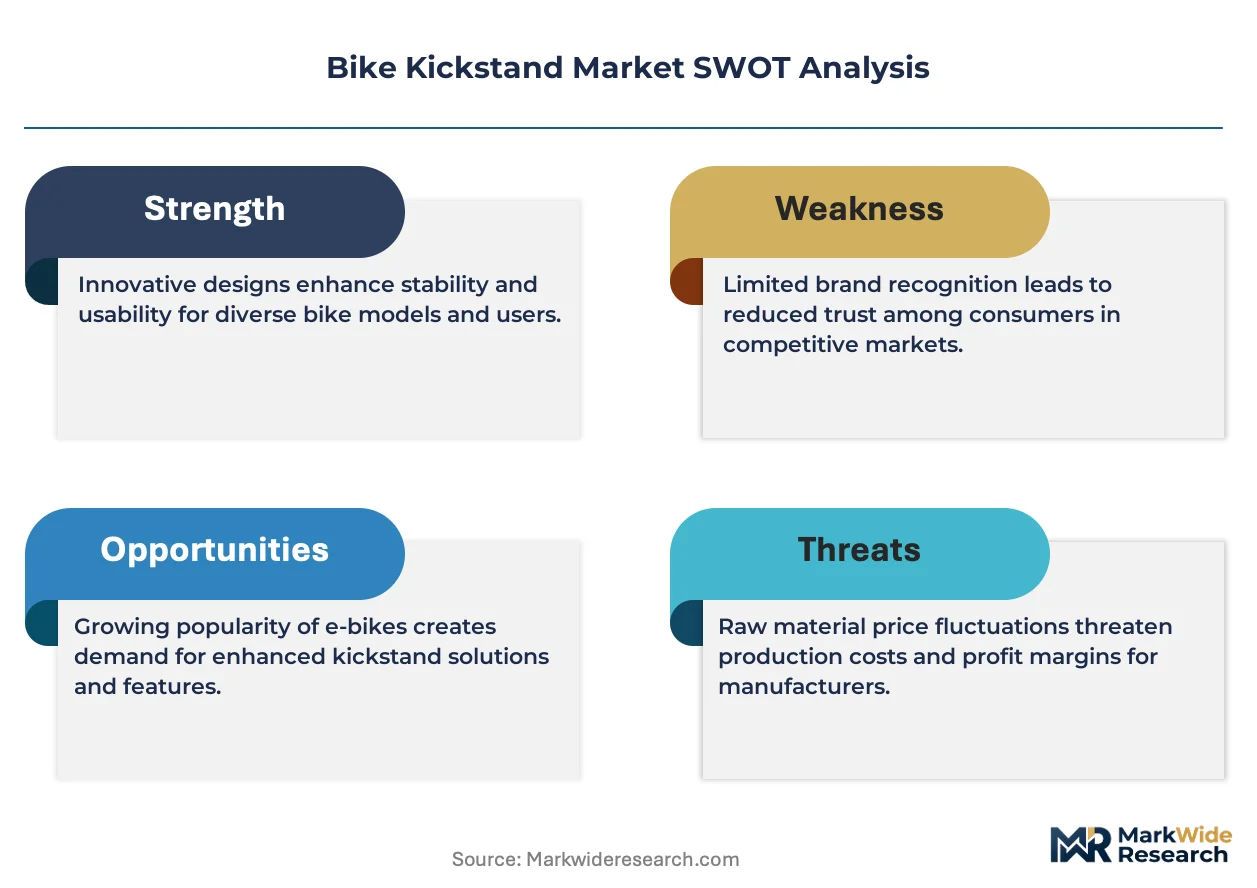
- Aluminum alloy price volatility:Primary aluminum input costs fluctuate with energy pricing, compressing margin buffers for mid-tier fabricators.
- Taiwanese foundry concentration:Taichung and Kaohsiung production clusters create single-source vulnerability for European and North American distributors.
- Carbon fiber cost barriers:Weight-optimized integrated designs remain economically inaccessible outside racing enthusiast niches.
Strategic Opportunities
- German industrial utility cycling:Cargo e-bike commercial fleets represent underpenetrated demand for premium center stand stability during loading operations.
- EU embodied carbon reporting:The Green Deal's material transparency requirements create first-mover advantage for OEMs with documented supply chain audits.
- Direct-to-retail channel expansion:Vertical integration through sporting goods chains bypasses traditional distributor markups in price-sensitive adjustable stand segments.
Industry Challenges
- JIS fatigue certification timelines:Japan's bicycle accessory standards require extended testing protocols that delay market entry for uncertified producers.
- Legacy steel-to-aluminum retooling:Permanent mount production lines demand capital-intensive equipment upgrades to meet lightweighting specifications.
- Cross-border compliance fragmentation:Divergent surface treatment regulations between REACH, JIS, and emerging national standards multiply certification overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bike Kickstand Market |
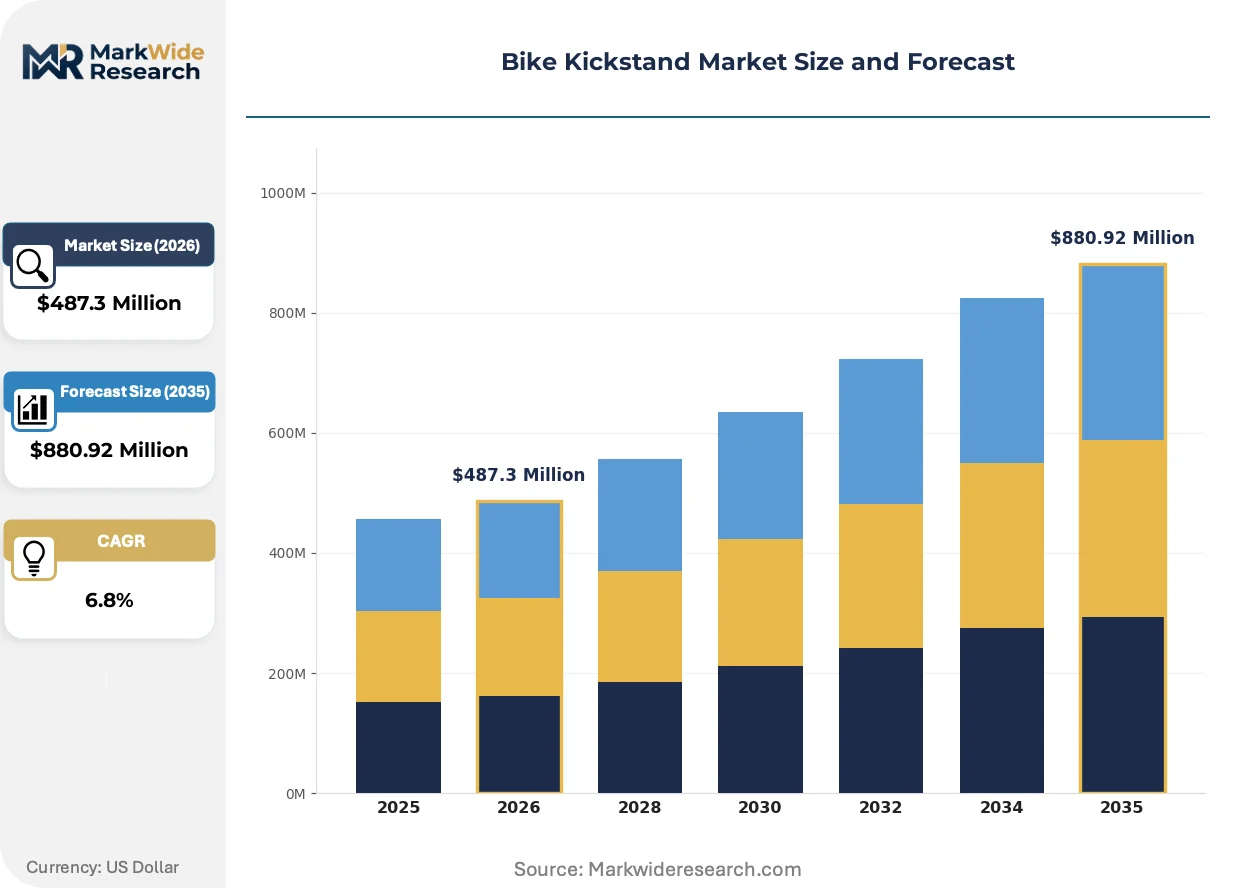
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Side Stand, Center Stand, Adjustable Stand, Double Leg Stand Material: Aluminum Alloy, Steel, Plastic, Carbon Fiber Installation: Permanent Mount, Quick Release, Clamp-on, Integrated Design End User: Recreational Cyclists, Commuters, Racing Enthusiasts, Repair Shops |
| Companies Covered | Pletscher, Decathlon, SCOTT, Greenfield Industries, BV, Wald, Hebie, Ursus, Zefal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bike Kickstand Market Evolving Landscape
Material science advances and regulatory transparency mandates are converging to reshape kickstand design priorities, with weight reduction and recyclability now core engineering constraints rather than secondary specifications.
Smart load-sensing hinge mechanisms are digitizing kickstand deployment feedback for e-bike fleet operators. These integrated sensors transmit parking stability data to maintenance management systems, enabling predictive replacement scheduling. Commercial bike-share operators in Northern Europe are digitizing their entire kickstand procurement specifications around real-time monitoring capability.
REACH surface treatment restrictions are eliminating hexavalent chromate conversion coatings from European-bound production lines. Anodized aluminum finishes now dominate premium SKU specifications, with Taiwanese foundries retooling plating facilities to maintain market access. German distributors are auditing supplier certificates of compliance as a gatekeeping mechanism for contract eligibility.
Fleet procurement managers are consolidating vendor relationships around single-source accountability for component lifecycle performance. Traditional multi-tier distribution through independent wholesalers is contracting as direct OEM-fleet agreements capture volume discounts and technical support integration. This concentration is most visible in Netherlands municipal bike-share tenders requiring unified warranty coverage across frame and accessory subsystems.
Bike Kickstand Market Segmentation
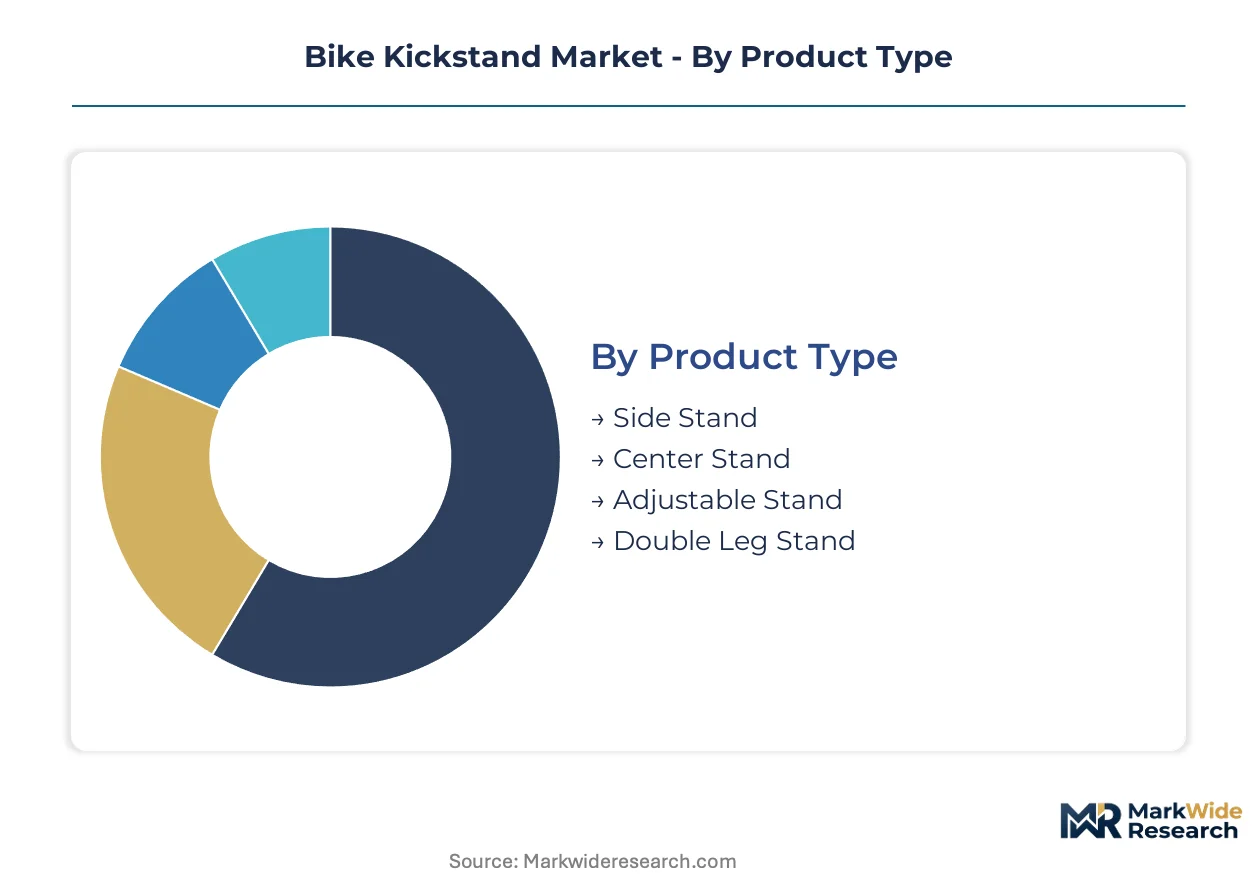
Kickstand procurement patterns diverge sharply across rider profiles and frame integration requirements. Material specifications and mounting complexity create distinct margin tiers that reshape manufacturer portfolio priorities.
Product Type:
Application context determines structural load requirements and deployment mechanics across bicycle categories.
- Side Stand:A single-arm pivot mechanism attaching near the rear dropout supports the bicycle at an inclined angle. Netherlands commuter fleets specify reinforced variants rated above 25 kilograms for e-bike stability. REACH-compliant anodized finishes dominate European procurement specifications.
- Center Stand:Dual-arm scissor or parallel linkage designs elevate both wheels for maintenance access and loading stability. German cargo e-bike commercial operators pay margin premiums for fatigue-tested configurations during freight operations. Stuttgart industrial clusters consolidate vendor relationships around unified warranty coverage.
- Adjustable Stand:Telescoping leg mechanisms accommodate variable frame geometries and terrain angles. Sporting goods chains control pricing through vertical retail integration of these SKUs.
- Double Leg Stand:Twin contact points distribute load across paved surfaces for heavy utility bicycles. Municipal bike-share tenders in Northern Europe increasingly specify this configuration for fleet standardization.
Side Stand holds installed capacity. Center Stand is rotating up the share rankings.
Material:
Cost tier and weight targets drive alloy selection, with regulatory transparency mandates now filtering supplier eligibility.
- Aluminum Alloy:Extruded 6061-T6 tubing delivers strength-to-weight ratios for mid-premium road and commuter segments. Taiwanese foundries in Taichung and Kaohsiung dominate European-bound production with REACH-compliant anodized surface treatments. EU Green Deal embodied carbon reporting requirements pressure documented supply chain audits.
- Steel:Chromoly or high-tensile tubing provides durability at lower unit costs for aftermarket replacement demand. North American channels favor permanent mount lines from established fabricators. Energy pricing volatility in primary aluminum markets periodically restores steel competitiveness.
- Plastic:Glass-reinforced nylon or thermoplastic composites serve lightweight recreational and children's bicycle categories. Injection molding economies suit high-volume adjustable stand production for mass-market retailers.
- Carbon Fiber:Prepreg layup or filament-wound structures achieve maximum weight reduction for racing applications. Cost barriers restrict addressable demand to enthusiast niches seeking integrated frame-specific designs.
Aluminum Alloy commands volume leadership. Carbon Fiber is climbing the fastest despite base effects.
Installation:
Mounting permanence reflects trade-offs between frame integrity, theft deterrence, and field serviceability.
- Permanent Mount:Braze-on or bolt-fixed attachments welded or threaded directly to frame dropouts. Legacy steel production lines require capital-intensive retooling to meet lightweighting specifications for aluminum variants.
- Quick Release:Lever-actuated clamps enable tool-free removal for racing or transport scenarios. Fleet procurement managers avoid these configurations due to theft exposure and liability fragmentation.
- Clamp-on:Band-style or bracket attachments secure to seatstays or chainstays without frame modification. Aftermarket channels favor this flexibility for multi-bike households.
- Integrated Design:Kickstand mechanisms concealed within frame tubes or bottom bracket shells. Racing enthusiasts represent the concentrated addressable niche for these weight-optimized proprietary systems.
Permanent Mount anchors OEM supply agreements. Clamp-on is gaining share fastest in aftermarket channels.
End User:
Customer type dictates performance specifications, price sensitivity, and channel access patterns.
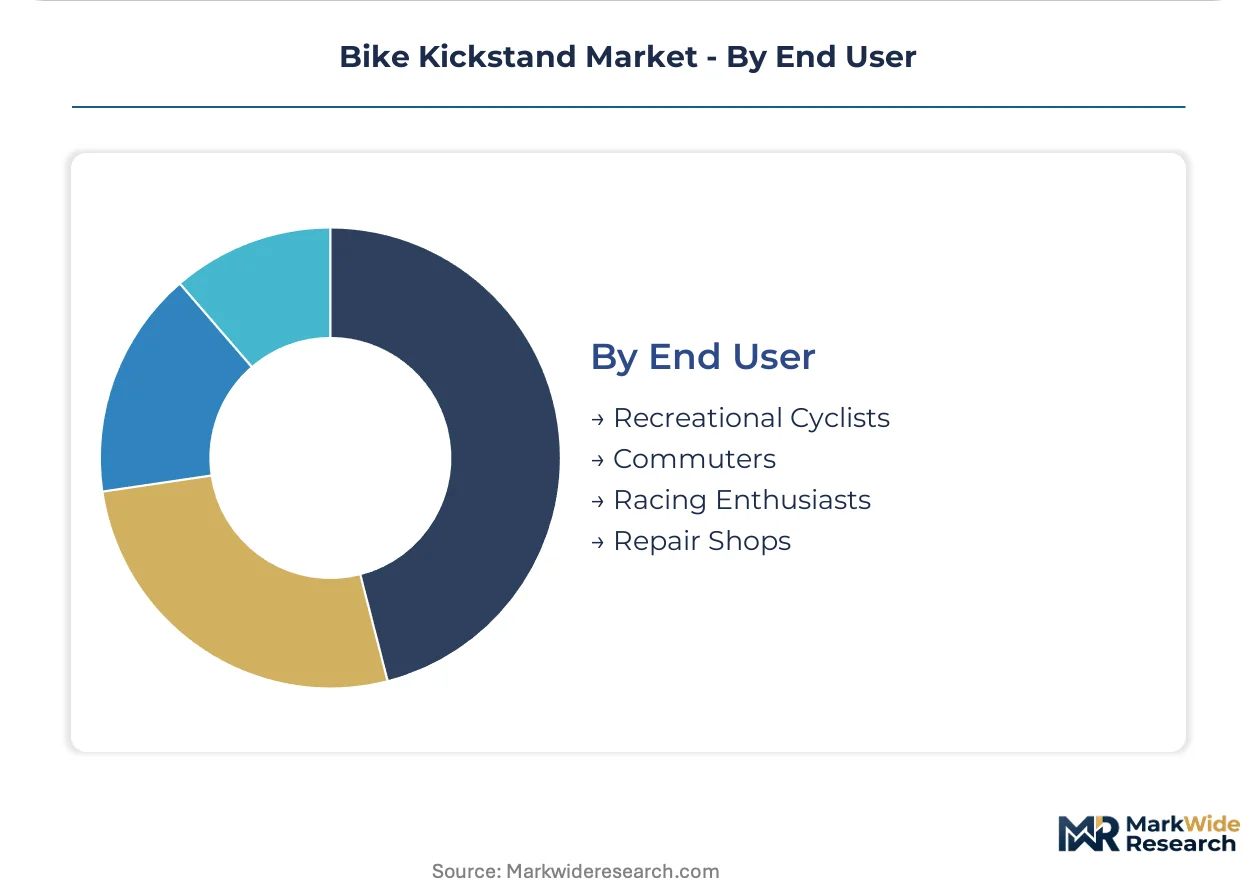
- Recreational Cyclists:Weekend riders prioritize convenience and aesthetic integration over load ratings. Adjustable stand SKUs dominate this price-sensitive segment through sporting goods retail.
- Commuters:Daily utility cyclists demand durability for parking stability in urban environments. Netherlands bike-share operators drive replacement demand with digitized procurement specifications around real-time monitoring capability.
- Racing Enthusiasts:Competitive cyclists reject kickstands entirely or demand carbon fiber integrated designs below 100 grams. This niche sustains premium pricing for Swiss-engineered side stand variants.
- Repair Shops:Independent mechanics stock universal-fit clamp-on and adjustable configurations for walk-in service revenue. Consolidating vendor relationships around single-source accountability is reshaping wholesale procurement.
Commuters concentrate replacement volume. Racing Enthusiasts sustain margin extraction at the premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese foundries in Taichung and Kaohsiung concentrate global kickstand fabrication capacity, creating supply dependencies for European and North American distributors seeking REACH-compliant aluminum components.
Germany
Stuttgart and Munich industrial clusters consolidate procurement for cargo e-bike commercial fleets requiring fatigue-tested center stand configurations. EU Green Deal embodied carbon reporting mandates pressure distributors to audit Taiwanese OEM supply chains. Baden-Württemberg manufacturing zones anchor premium utility cycling OEM relationships.
Netherlands
Municipal bike-share operators in Amsterdam and Utrecht drive replacement demand for reinforced side stands rated above 25 kilograms. Digitized procurement specifications now require real-time monitoring capability for fleet maintenance systems. Randstad urban corridors concentrate commuter cycling infrastructure investment.
Taiwan
Taichung and Kaohsiung foundries dominate European-bound production of anodized aluminum kickstand variants. REACH chromate restrictions forced retooling of plating facilities to maintain market access. Kaohsiung industrial districts specialize in high-volume extrusion for adjustable stand SKUs.
United States
North American aftermarket channels favor steel-based permanent mount lines from established fabricators. Energy pricing volatility in primary aluminum markets periodically restores steel competitiveness for price-sensitive replacement demand. Midwest distribution hubs consolidate inventory for independent repair shop networks.
Japan
JIS fatigue certification requirements create extended testing timelines that limit market access for uncertified producers. METI standards for bicycle accessories enforce rigorous kickstand lifecycle protocols. Osaka manufacturing zones concentrate domestic OEM supply relationships around certified component sourcing.
Bike Kickstand Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base spans three tiers: vertically integrated sporting goods retailers, regional foundry operations, and niche engineering houses. Swiss-engineered specialists and Taiwanese scale producers represent distinct strategic archetypes. Capacity expansion in anodized aluminum finishing and direct OEM-fleet contracting constitute the dominant competitive moves reshaping channel relationships.
Among European premium-tier specialists, Pletscher occupies a position exemplifying Swiss-engineered side stand design. Greenfield Industries represents North American aftermarket concentration around steel-based permanent mount configurations. Decathlon anchors vertical retail integration, controlling pricing across adjustable stand SKUs through backward integration into component sourcing.
| Leading Market Players |
|---|
| Pletscher |
| Decathlon |
| SCOTT |
| Greenfield Industries |
| BV |
| Wald |
| Hebie |
| Ursus |
| Zefal |
| Others |
Value Network & Pricing Analysis
Taichung and Kaohsiung foundry concentration anchors global kickstand fabrication, directing margin pools toward REACH-compliant anodized aluminum finishers and fleet-direct contract holders who bypass traditional distribution markups.
Pricing Analysis
EU Green Deal embodied carbon reporting dictates the pricing tier structure across European distribution channels. Three-tier pricing structure across premium, standard, and economy levels separates fatigue-tested center stands for German cargo fleets from adjustable SKUs in mass retail. Certification grade and volume scale drive price differentiation, with JIS-compliant variants commanding premiums against uncertified alternatives. Cost compression in mid-tier aluminum fabricators is intensifying because energy pricing volatility erodes margin buffers. Municipal bike-share operators exhibit lowest price sensitivity due to unified warranty requirements, while recreational cyclists through sporting goods chains remain most price-sensitive.
Supply Chain Analysis
Extended payment terms from Taiwanese OEMs to German distributors now stretch 90-120 days, reflecting supply-chain finance facilities that concentrate liquidity risk downstream. Kickstand production draws from Taiwan, China, and Vietnam, with 6061-T6 aluminum extrusion, hardened rubber foot compounds, and spring-loaded hinge mechanisms as critical inputs. Single-source vulnerability around Taichung plating facilities for REACH-compliant anodized finishes creates structural exposure. Distribution runs through direct OEM-fleet contracting that is displacing traditional independent wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kickstand procurement is entering a cyclical recovery phase as Netherlands e-bike fleet replacement cycles accelerate aftermarket demand for reinforced side stands rated above 25 kilograms.
For Market Incumbents: Build certification moats around JIS fatigue testing and REACH anodized finishing capabilities to exclude uncertified Taiwanese competitors. Deepen backward integration into captive aluminum extrusion capacity in Taichung industrial districts. Consolidate vendor relationships around single-source lifecycle accountability to match Netherlands municipal tender requirements. For New Entrants and Emerging Players: Build out white-space positions in carbon fiber integrated designs for racing enthusiasts and smart load-sensing hinge mechanisms for Northern European fleet operators. North American steel-based aftermarket channels offer the most penetrable entry point against established Greenfield Industries dominance. Pursue direct-to-repair-shop distribution through clamp-on universal-fit configurations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Taiwanese foundry operations seeking European distribution acquisitions to capture Green Deal transparency premiums. Five-to-ten year viability hinges on aluminum alloy price stabilization and e-bike weight classification stability. Monitor Netherlands municipal bike-share tender awards as inflection indicator for fleet-direct channel shift velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Anodized Aluminum Finishing Capacity Expansion | Taichung foundries retool plating lines to maintain REACH market access against chromate restrictions. |
| Direct OEM-Fleet Contracting | Netherlands bike-share operators consolidate procurement around unified warranty coverage and real-time monitoring integration. |
| JIS Fatigue Certification Investment | Japanese METI standards enforcement limits market access for uncertified producers seeking Osaka OEM relationships. |
| Smart Load-Sensing Hinge Development | Commercial fleet operators digitize kickstand specifications around predictive maintenance and stability feedback systems. |
| Carbon Fiber Integrated Design Launch | Swiss-engineered specialists capture racing enthusiast niches with sub-100 gram proprietary frame-specific systems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with kickstand procurement managers at Netherlands bike-share operators, German cargo e-bike fleet directors, Taiwanese foundry operations heads, and North American aftermarket distributors; and secondary validation through EU Green Deal regulatory filings, ECHA REACH substance restrictions, JIS bicycle accessory standards documentation, and aluminum alloy trade flow data. Bottom-up volume modeling triangulated against top-down market sizing across material grade and installation type segments.
Forecast inputs included e-bike fleet replacement cycle timing, embodied carbon reporting compliance costs, and aluminum energy pricing volatility across the projection horizon. Segmentation dimensions spanned product type, material alloy, installation method, and end-user category. CAGRs were derived from regression analysis against historical fleet penetration rates and regulatory phase-in schedules. Industry-specific inputs captured JIS certification timeline delays and REACH surface treatment transition costs.
Stress conditions across aluminum alloy price bands, e-bike weight classification regulatory shifts, and Taiwanese foundry capacity utilization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around fleet electrification pace and circular economy mandate enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Australia E- Bike Market
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Denmark E-Bike Market
Bikes and Motorcycles
Europe Two-Wheeler Market
Bikes and Motorcycles
Europe Bicycle Market
Bikes and Motorcycles
Latin America Bike Sharing Market
Bikes and Motorcycles
Sweden E-Bike Market
Bikes and Motorcycles
Motorcycle Accessories Market
Bikes and Motorcycles
Africa Two-Wheeler Market
Bikes and Motorcycles
Europe E-Cargo Bike Market
Bikes and Motorcycles
Motorcycle Wheels Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Maxi Scooter Market
Bikes and Motorcycles
Latin America Two-Wheeler Market
Bikes and Motorcycles
Bicycle Trip Market
Bikes and Motorcycles
Mountain Bike Suspension Market