
 Emission Control Catalyst for Motorcycle Market | 2026-2036
Emission Control Catalyst for Motorcycle Market Size, Share, and Industry Trends Forecast 2026-2036
Emission Control Catalyst for Motorcycle Market Foresight
Specialized ceramic engineering talent is rotating toward substrate manufacturing hubs as honeycomb structure complexity rises. BASF SE leverages its precious metals trading arm to secure palladium supply chains for motorcycle catalyst formulations. Johnson Matthey plc anchors its position through proprietary coating technologies that reduce rhodium dependency. Tenneco Inc. competes via integrated exhaust system design capabilities spanning catalyst assembly to muffler integration.
An emission control catalyst for motorcycle is a coated ceramic or metallic substrate that facilitates redox reactions to convert hydrocarbons, carbon monoxide, and nitrogen oxides into less harmful exhaust constituents, typically operating at conversion efficiencies above 90% once light-off temperature is achieved. Three-way catalysts dominate current OEM fitments due to their simultaneous oxidation and reduction functionality in stoichiometric air-fuel conditions. Palladium loading configurations command premium positioning as automakers and motorcycle manufacturers seek to substitute platinum without sacrificing thermal durability. Selective catalytic reduction remains nascent in motorcycle applications but holds structural relevance for larger displacement segments approaching diesel-equivalent NOx thresholds.
The US EPA, the European Commission through ECHA REACH enforcement, and India's Central Pollution Control Board collectively mandate escalating emission thresholds that force catalyst formulation upgrades across export-bound production. Euro 5 and Bharat Stage VI compliance deadlines compress product development cycles, pushing OEMs toward pre-certified catalyst suppliers with established homologation track records. Stakeholders must monitor evolving precious metals price volatility and regional enforcement consistency to calibrate inventory and sourcing strategies.
Market Dynamics
Platinum group metal substitution pressure is compressing formulation economics as palladium-rhodium ratios recalibrate across catalyst architectures. BASF SE and Johnson Matthey plc are accelerating coating density experiments to maintain conversion efficiency at reduced precious metal loadings. This structural force is redrawing supplier-OEM contract terms and inventory risk allocation.
Growth Catalysts
- Euro 5 enforcement deadlines:European Commission mandates through ECHA REACH are compelling motorcycle OEMs to pre-certify exhaust systems, locking in catalyst supplier relationships eighteen months ahead of production ramp.
- Bharat Stage VI adoption in India:Central Pollution Control Board compliance windows are forcing domestic two-wheeler manufacturers to upgrade from oxidation-only to three-way catalyst configurations.
- Ceramic substrate engineering advances:Advanced cordierite and silicon carbide honeycomb structures are enabling higher cell density at reduced thermal mass, accelerating light-off performance in urban stop-start riding conditions.
Market Restraints
- Precious metal price volatility:Palladium and rhodium spot market swings exceeding thirty percent annually are destabilizing catalyst cost models and forcing indexed pricing clauses into long-term supply agreements.
- Substrate supply concentration:Japanese and German ceramic manufacturers control eighty percent of high-cell-density honeycomb production, creating single-source vulnerability for tier-two catalyst assemblers.
- Thermal durability ceiling:Current washcoat adhesion technologies degrade above 950°C, limiting catalyst effectiveness in high-performance motorcycle segments with lean-burn combustion strategies.
Strategic Opportunities
- Indonesia manufacturing expansion:The country's motorcycle production exceeding eight million units annually presents untapped demand for localized catalyst assembly to serve ASEAN export markets.
- Electric-hybrid catalyst architectures:Range-extender motorcycle platforms combining internal combustion with electric propulsion require specialized low-temperature catalyst formulations for intermittent engine operation.
- Remanufacturing channel development:Independent aftermarket distributors in Brazil and Mexico are establishing certified catalyst refurbishment networks to capture price-sensitive replacement demand.
Industry Challenges
- Homologation engineering talent scarcity:Experienced emissions certification specialists capable of navigating simultaneous EPA, Euro 5, and Bharat Stage VI test protocols command premium compensation and extended recruitment timelines.
- Coating equipment capex intensity:Precision slurry deposition lines with real-time washcoat weight monitoring require capital commitments exceeding fifteen million dollars per production cell.
- Legacy exhaust system integration:Catalyst-to-muffler thermal management conflicts in existing motorcycle platform architectures demand complete exhaust redesign rather than drop-in catalyst replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emission Control Catalyst for Motorcycle Market |
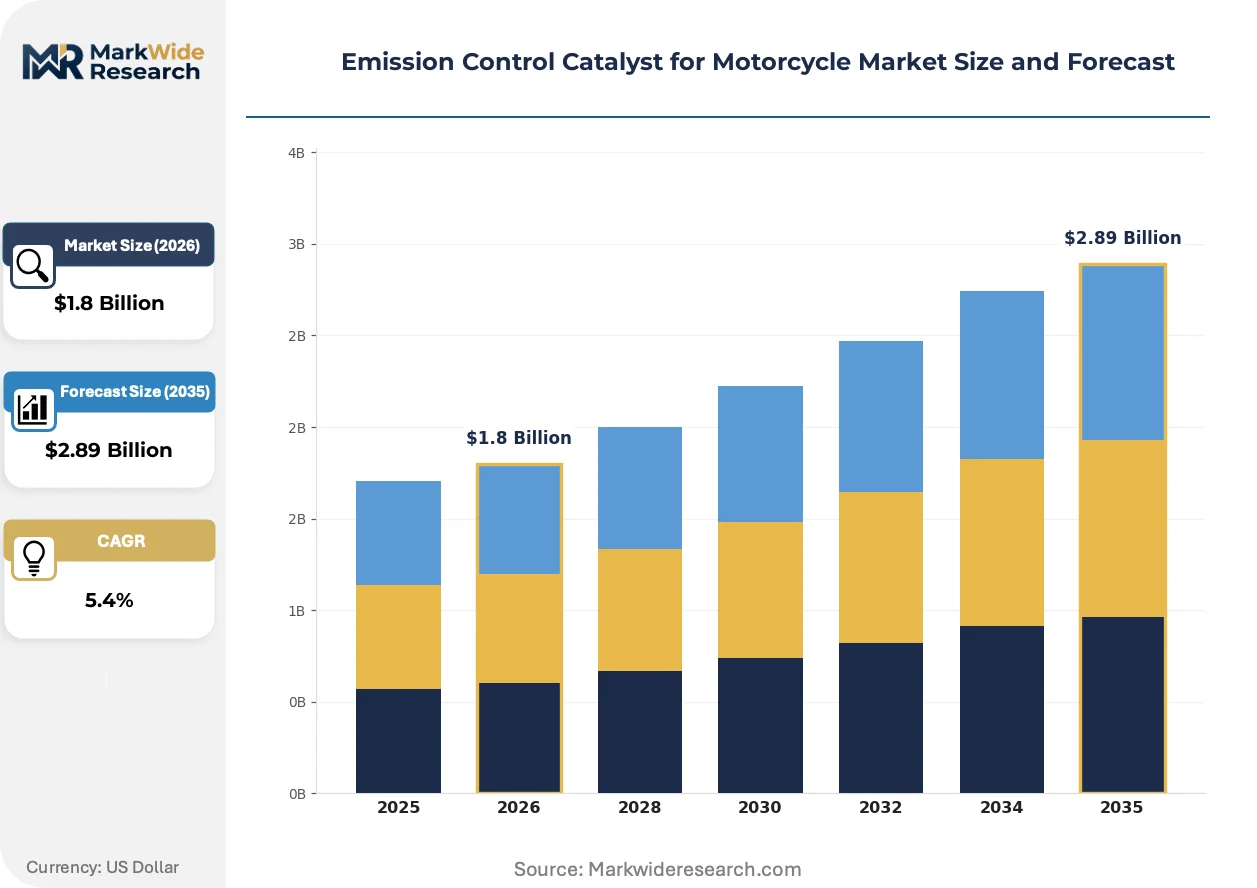
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Three-Way Catalysts, Oxidation Catalysts, Diesel Oxidation Catalysts, Selective Catalytic Reduction Material: Platinum, Palladium, Rhodium, Cerium Oxide Application: On-Road Motorcycles, Off-Road Motorcycles, Racing Motorcycles, Electric Motorcycles End User: OEMs, Aftermarket Providers, Custom Builders, Rental Agencies |
| Companies Covered | Cataler Corporation, Corning Incorporated, BASF SE, Clariant AG, NGK Insulators Ltd., Johnson Matthey plc, Heraeus Holding GmbH, Tenneco Inc., Umicore SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emission Control Catalyst for Motorcycle Market Shifts & Advancements
Formulation chemistry and substrate architecture are diverging along performance-versus-cost optimization paths. Suppliers are fragmenting their product portfolios to serve distinct OEM segments rather than pursuing universal platform solutions. This specialization is reshaping R&D resource allocation and patent filing patterns.
Palladium-dominant catalyst formulations are bifurcating the market between premium thermal durability specifications and cost-optimized loadings for emerging economy motorcycles. Japanese OEMs are adopting high-palladium configurations for 150cc-plus segments requiring sustained highway speeds. European manufacturers are compressing rhodium content to minimum viable thresholds, accepting modest NOx conversion trade-offs in exchange for supply chain stability.
ECHA REACH enforcement of Substance of Very High Concern screening is forcing reformulation of ceria-zirconia oxygen storage components. Catalyst suppliers are qualifying alternative rare earth compositions to maintain OSC performance while eliminating candidate SVHC materials. Indian and Southeast Asian export-bound production faces the steepest compliance timeline compression, with homologation submissions due six months earlier than domestic European cycles.
Aftermarket procurement is consolidating around certified pre-homologated catalyst modules rather than component-level sourcing. Distributors in Mexico and Colombia are displacing uncertified grey-market suppliers with EPA- and Euro-compliant inventory backed by manufacturer warranty. This channel shift is most visible in urban fleet replacement programs where municipal emission testing mandates enforce catalyst traceability requirements.
Emission Control Catalyst for Motorcycle Market Segmentation
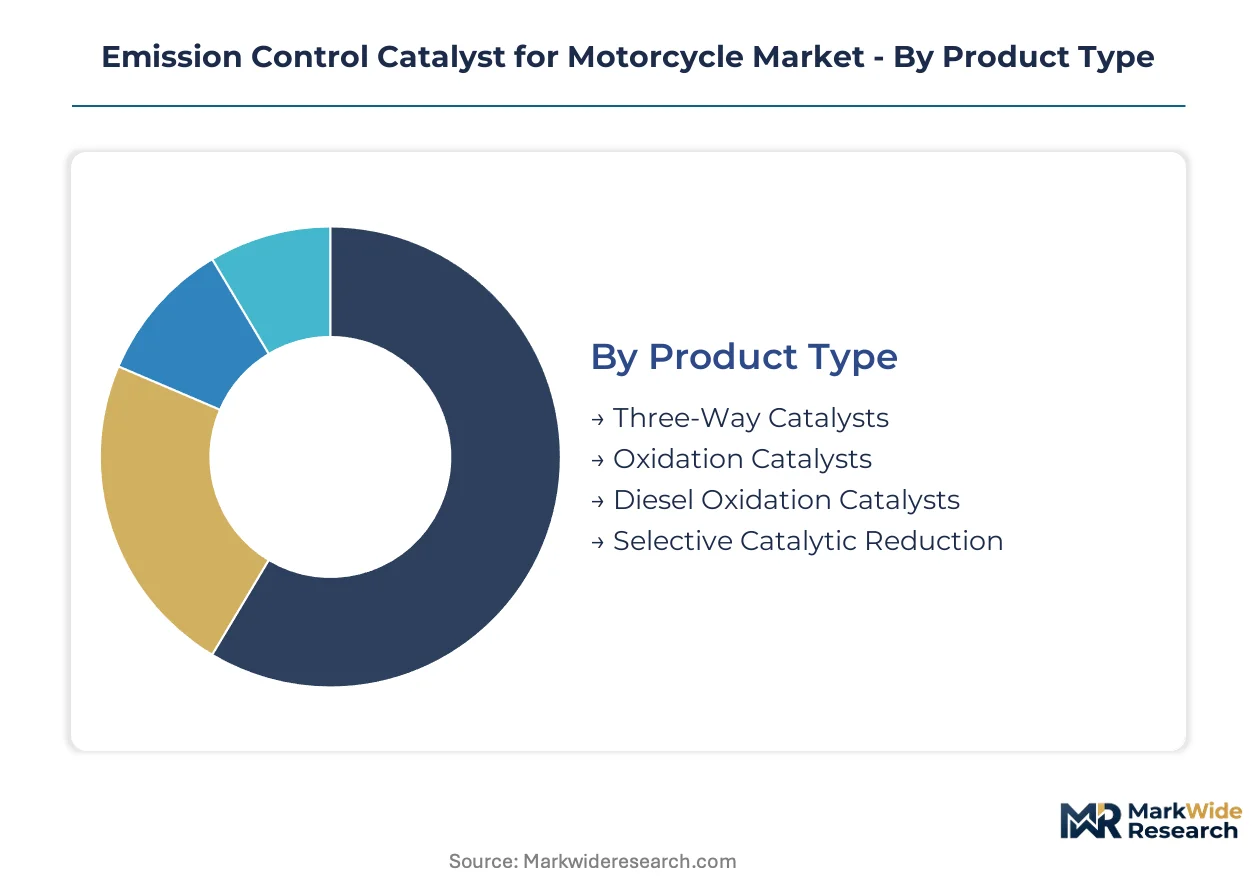
Motorcycle catalyst segmentation reflects divergent technical requirements across displacement classes and regulatory environments. Formulation choices and substrate specifications vary sharply between mass-market commuter bikes and performance-oriented segments.
Product Type:
Margin pools concentrate in three-way catalyst configurations where precious metal loading optimization commands premium pricing.
- Three-Way Catalysts:These simultaneous oxidation-reduction systems process hydrocarbons, carbon monoxide, and nitrogen oxides through single-substrate architectures. Indian and Southeast Asian OEMs are migrating from oxidation-only systems to three-way configurations as Bharat Stage VI enforcement tightens.
- Oxidation Catalysts:Simpler single-function converters targeting carbon monoxide and unburned hydrocarbons remain viable for sub-125cc displacement segments. Cost-sensitive manufacturers in Vietnam and Indonesia specify these for entry-level commuter platforms where NOx thresholds remain less stringent.
- Diesel Oxidation Catalysts:Specialized formulations for compression-ignition motorcycle engines address particulate matter and hydrocarbon emissions.
- Selective Catalytic Reduction:Urea-based NOx reduction systems are penetrating larger displacement touring and adventure motorcycle segments approaching diesel-equivalent emission profiles.
The dominant share belongs to Three-Way Catalysts, while Selective Catalytic Reduction is closing the gap fastest.
Material:
Formulation economics pivot on platinum group metal substitution ratios and rare earth oxygen storage component selection.
- Platinum:Traditional high-temperature durability anchor in catalyst washcoats. European OEMs are compressing platinum loadings to minimum thresholds as palladium supply chains stabilize.
- Palladium:Dominant precious metal in current motorcycle catalyst formulations due to favorable oxidation kinetics and improved thermal stability. Japanese manufacturers specify high-palladium configurations for 150cc-plus highway-capable segments.
- Rhodium:Critical NOx reduction promoter with severe supply concentration constraints. Catalyst engineers are reducing rhodium dependency through advanced ceria-zirconia oxygen storage layer engineering.
- Cerium Oxide:Primary oxygen storage component enabling air-fuel ratio fluctuation buffering. ECHA REACH Substance of Very High Concern screening is forcing qualification of alternative rare earth compositions.
Palladium captures the dominant share, while Cerium Oxide alternatives are expanding most quickly as reformulation accelerates.
Application:
Volume concentration tracks manufacturing cluster location and local emission enforcement stringency.
- On-Road Motorcycles:Street-legal platforms subject to full EPA, Euro 5, or Bharat Stage VI certification requirements. Urban fleet operators in Mexico City and São Paulo are driving replacement catalyst demand through mandatory emission testing programs.
- Off-Road Motorcycles:Dirt bikes and agricultural utility vehicles operating under less stringent regulatory frameworks. California Air Resources Board enforcement is compressing the compliance gap between on-road and off-road emission thresholds.
- Racing Motorcycles:Competition-exempt platforms with minimal catalyst fitment. Fédération Internationale de Motocyclisme technical regulations are beginning to mandate catalyst systems for certain championship categories.
- Electric Motorcycles:Battery-electric platforms with zero tailpipe emissions require no catalyst systems. Range-extender hybrid architectures are creating niche demand for low-temperature catalyst formulations.
On-Road Motorcycles hold the dominant share, while Electric Motorcycles are gaining share fastest through displacement of internal combustion volumes.
End User:
Procurement patterns diverge between specification-controlled OEM channels and price-sensitive independent distribution.
- OEMs:Original equipment manufacturers with homologation-certified supplier relationships and eighteen-month advance procurement cycles. Euro 5 pre-certification deadlines are locking in catalyst supplier contracts ahead of production ramp.
- Aftermarket Providers:Independent distributors and service networks supplying replacement catalyst modules. Certified pre-homologated inventory is displacing grey-market suppliers in Colombia and Brazil.
- Custom Builders:Small-volume motorcycle modifiers with specialized exhaust fabrication requirements.
- Rental Agencies:Fleet operators with high-utilization replacement schedules and municipal emission compliance obligations.
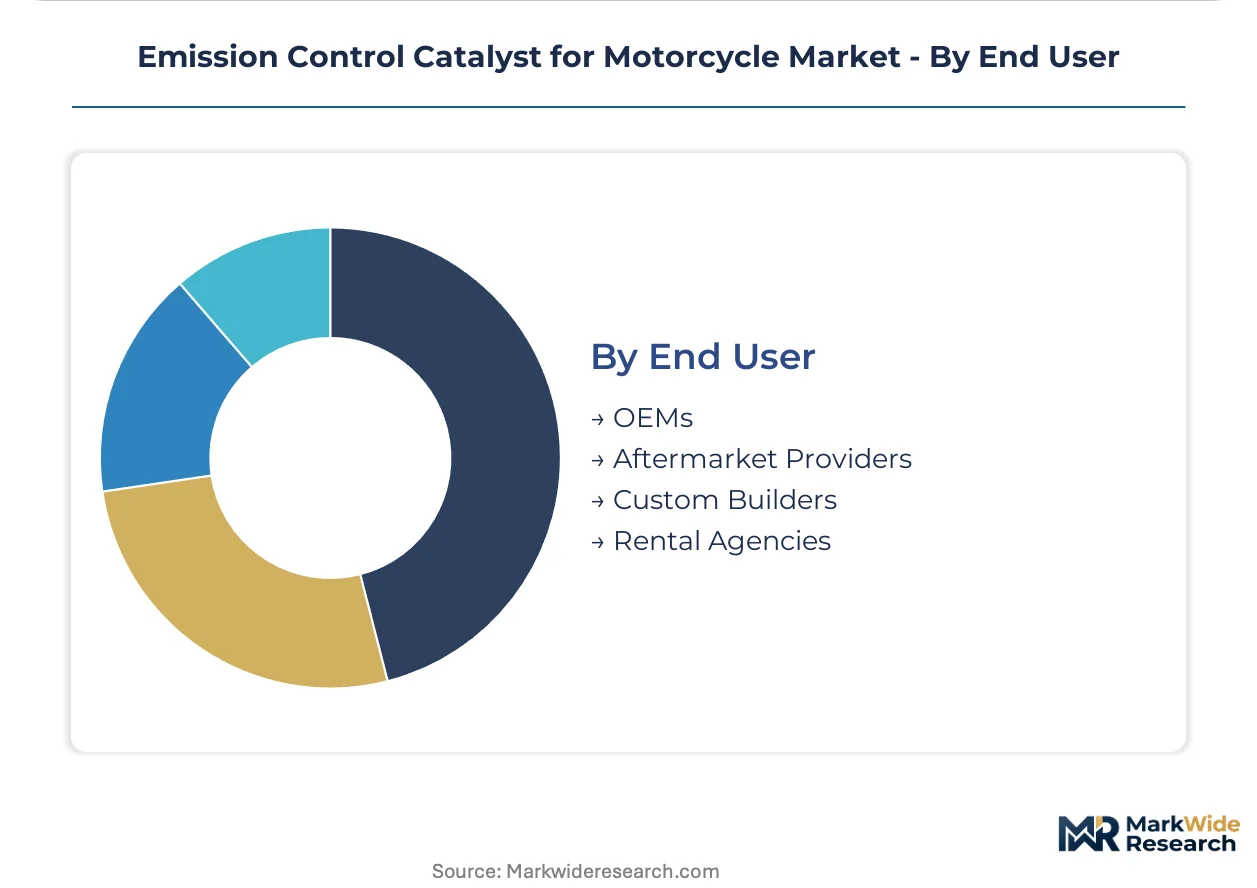
OEMs command the dominant share, while Aftermarket Providers are closing the gap fastest as vehicle parc ages and replacement intervals compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys three-way catalysts across virtually all on-road displacement classes, while Indonesia and Vietnam still specify oxidation-only systems for entry-level commuter segments under 125cc. This consumption-mix differential reflects enforcement timing gaps between Bharat Stage VI and ASEAN regulatory harmonization.
India
Domestic two-wheeler manufacturers command annual production exceeding twenty million units, creating concentrated demand for Bharat Stage VI-certified catalyst modules. The Central Pollution Control Board enforces compliance windows that compress homologation cycles to twelve months. Manufacturing clusters in Pune and Chennai host dedicated catalyst assembly lines serving Hero MotoCorp and TVS Motor Company export programs.
Indonesia
Motorcycle production surpassing eight million units annually generates structural demand for localized catalyst assembly capacity. The country's environmental ministry maintains Euro 4-equivalent emission thresholds with phased tightening toward Euro 5 alignment. Industrial zones in Bekasi and Karawang attract substrate coating investments from Japanese catalyst suppliers seeking ASEAN hub positioning.
Vietnam
Honda and Yamaha manufacturing facilities in Vinh Phuc and Ha Nam provinces drive catalyst procurement volumes for domestic and export-bound production. The Vietnam Register enforces emission certification modeled on European frameworks with lagged implementation timelines. Local oxidation catalyst demand persists in sub-110cc segments where cost sensitivity outweighs NOx reduction requirements.
Thailand
Export-oriented motorcycle assembly for Japanese OEMs necessitates dual-homologated catalyst systems meeting both EPA and Euro 5 protocols. The Thai Industrial Standards Institute mandates type-approval testing through designated certification bodies. Eastern Economic Corridor facilities in Chonburi and Rayong integrate catalyst manufacturing with exhaust system fabrication for regional re-export.
Mexico
Urban fleet operators in Mexico City and Guadalajara drive aftermarket catalyst replacement demand through mandatory biannual emission testing programs. The Secretariat of Environment and Natural Resources enforces NOM-044 standards aligning with EPA Tier 2 motorcycle thresholds. Querétaro and Guanajuato manufacturing corridors host catalyst distribution hubs serving Central American re-export markets.
Emission Control Catalyst for Motorcycle Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the motorcycle catalyst market. The upper tier comprises precious metals traders with captive coating capabilities and ceramic substrate manufacturers with vertical control over honeycomb production. Mid-tier specialists concentrate on regional homologation services and aftermarket module assembly. Dominant competitive moves include coating density experimentation to reduce PGM loadings and strategic partnerships with exhaust system integrators for pre-certified platform development.
Among Germany-based chemical conglomerates, BASF SE and Clariant AG occupy positions spanning precious metals procurement through washcoat formulation. Japanese ceramic specialists Cataler Corporation and NGK Insulators Ltd. exemplify the substrate-engineering archetype, leveraging cordierite and silicon carbide honeycomb expertise. These companies represent distinct competitive vectors: integrated chemical-metals trading versus advanced ceramic manufacturing.
| Leading Market Players |
|---|
| Cataler Corporation |
| Corning Incorporated |
| BASF SE |
| Clariant AG |
| NGK Insulators Ltd. |
| Johnson Matthey plc |
| Heraeus Holding GmbH |
| Tenneco Inc. |
| Umicore SA |
| Others |
Supply & Pricing Matrix
Palladium-for-platinum substitution in washcoat formulations is redrawing procurement geography while compressing margin structures across catalyst tiers. Japanese trading houses and German chemical conglomerates now anchor spot-market pricing power as indexed long-term contracts displace fixed-price arrangements.
Pricing Analysis
Long-term offtake agreements with precious metals traders dominate procurement structures for tier-one catalyst assemblers, while spot-market exposure concentrates among smaller coating operations. Pricing stratifies across premium, standard, and economy tiers based on homologation certification grade and volume scale commitments. Cost compression in economy-tier formulations is intensifying because Indian and Indonesian OEMs are squeezing supplier margins through consolidated procurement auctions. Aftermarket distributors exhibit the highest price sensitivity due to grey-market competition, whereas Euro 5-certified OEM channels accept premium positioning for pre-homologated modules.
Supply Chain Analysis
Japan and Germany control high-cell-density ceramic honeycomb production, while India and Thailand host downstream catalyst assembly and exhaust system integration. The supply chain draws from South African and Russian palladium concentrates, Brazilian cerium oxide, and Chinese rare earth processing facilities. Single-source vulnerability in advanced cordierite substrate manufacturing exposes tier-two assemblers to allocation risk during demand surges. Distribution runs through OEM direct procurement channels for original fitment and certified distributor networks for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
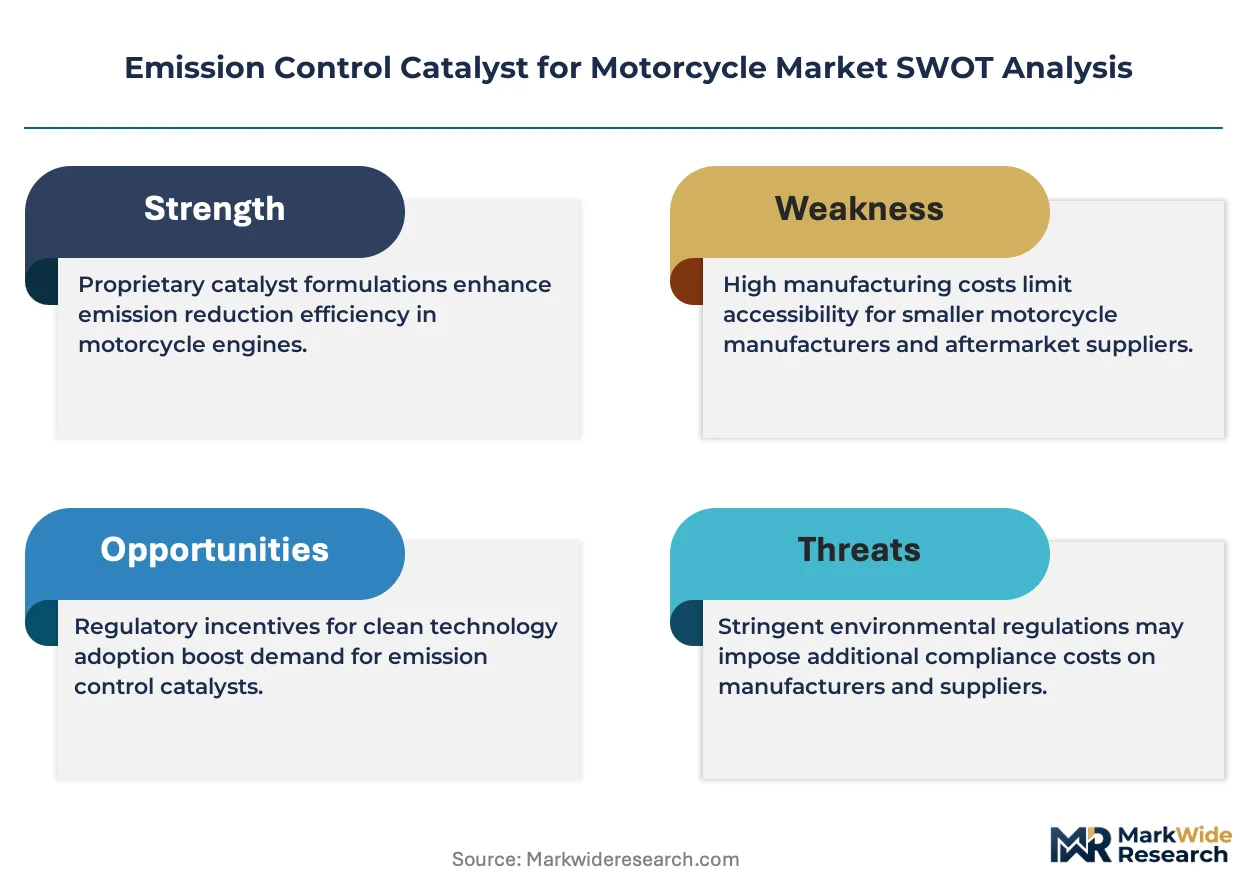
This market sits in early-cycle expansion as Bharat Stage VI and Euro 5 enforcement compress replacement intervals and force oxidation-to-three-way catalyst upgrades across the installed base.
For Market Incumbents: Secure backward integration into ceramic substrate manufacturing or captive precious metals trading arms to hedge against palladium price volatility. Anchor OEM relationships through eighteen-month pre-certification commitments before competitor coating lines achieve homologation readiness. Prioritize R&D investment in low-temperature light-off formulations for range-extender hybrid architectures. For New Entrants and Emerging Players: Bharat Stage VI fast-track certification services for Indian domestic manufacturers represent the most penetrable entry vector. Target Indonesia's Bekasi and Karawang industrial zones for localized coating capacity to serve ASEAN export markets. Lead with certified pre-homologated aftermarket modules displacing grey-market suppliers in Mexico City and São Paulo fleet replacement programs. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-tier specialists with established homologation track records and regional OEM relationships. Long-term viability hinges on coating density innovation reducing PGM loadings while maintaining conversion efficiency. Watch for inflection signals in ECHA REACH enforcement tightening on oxygen storage component formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrate Manufacturing | NGK Insulators and Corning control honeycomb supply, creating captive production incentives for coating specialists. |
| Bharat Stage VI Pre-Certification Investment | Central Pollution Control Board compliance windows compress to twelve months, favoring early-mover catalyst suppliers. |
| Palladium Trading Arm Establishment | BASF's precious metals desk secures supply chain stability against Johannesburg and Norilsk concentrate volatility. |
| Indonesia Localized Assembly Capacity | Eight million annual motorcycle production units create structural demand for ASEAN hub positioning. |
| Low-Temperature Catalyst Formulation R&D | Range-extender hybrid architectures require specialized washcoats for intermittent combustion operation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with catalyst coating line engineers, OEM exhaust system procurement managers, aftermarket distributor network heads, and Central Pollution Control Board homologation specialists. Secondary validation drew from EPA certification filings, ECHA REACH substance screening databases, Indian automotive production registries, and customs trade data on platinum group metal concentrates. Bottom-up volume modeling triangulated against top-down precious metals consumption estimates.
Across the analysis window, forecasts employed displacement-class segmentation by propulsion architecture, regulatory compliance tier, and regional production cluster. CAGRs were derived from production volume trajectories and catalyst content-per-vehicle assumptions. Industry-specific inputs included Bharat Stage VI enforcement timeline phasing, Euro 5 pre-certification completion rates, and palladium-for-platinum substitution elasticity in washcoat formulations.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement stringency and stable precious metals supply; material deviation in either would warrant model refresh. Recalibration cycles align with shifts in emission threshold adoption schedules and PGM market structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Cargo Bike Market
Bikes and Motorcycles
Bike Kickstand Market
Bikes and Motorcycles
Electric Motorsport Market
Bikes and Motorcycles
Folding Bikes Market
Bikes and Motorcycles
South Africa Two-Wheeler Market
Bikes and Motorcycles
Global Motorcycles Brake Caliper Market
Bikes and Motorcycles
Japan Motorcycle ADAS Market
Bikes and Motorcycles
US Fuel Cell Bikes Market
Bikes and Motorcycles
Motorcycles Fuel Tank Market
Bikes and Motorcycles
Europe Motorcycle ADAS Market
Bikes and Motorcycles
Two Wheeler Switches Market
Bikes and Motorcycles
E-Mountain Bike Market
Bikes and Motorcycles
United States E-Bike Market
Bikes and Motorcycles
Europe Two-Wheeler Market
Bikes and Motorcycles
Two-Wheeler Brake Pads Market
Bikes and Motorcycles
Smart Electric Bikes Market