
 Dome Shrink Basket Bags Market | 2026-2036
Dome Shrink Basket Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Dome Shrink Basket Bags Market Outlook
Capital-intensity divergence between automated blown-film extrusion capabilities and conventional converting operations is redrawing competitive boundaries in dome shrink basket bags. Sealed Air Corporation leverages integrated resin-to-film production networks across multiple North American facilities. Berry Global Inc. anchors its position through high-volume polyethylene formulations tailored to retail display performance. Smurfit Kappa Group competes via fiber-based hybrid solutions that address sustainability mandates in European grocery channels.
Dome shrink basket bags are heat-shrinkable polyethylene or polypropylene films formed over rigid basket substrates to create tamper-evident, visually enhanced retail packaging for perishable goods, typically operating at shrink temperatures between 120°C and 160°C. Polyethylene grades dominate material selection for their clarity and seal strength in automated wrapping lines, while PVC alternatives face structural decline amid phthalate scrutiny and recycling incompatibility. Food retail represents the established revenue base, though e-commerce fulfillment applications for gift and specialty baskets are expanding fastest as direct-to-consumer channels require damage-resistant presentation packaging.
FDA compliance under 21 CFR 177.1520 governs olefin polymer food-contact layers, while EPA guidelines on plastic waste streams influence post-consumer recycling infrastructure investments that affect resin sourcing decisions. California's SB 54 extended producer responsibility framework and similar state-level packaging reduction statutes are forcing reformulation toward recyclable mono-material structures. Stakeholders must monitor evolving thermoforming energy standards and retailer-specific sustainability scorecards that increasingly gate shelf access for non-compliant packaging formats.
Market Dynamics
California's SB 54 extended producer responsibility framework is forcing mono-material reformulation across polyethylene film supply chains, compressing margins for converters dependent on multi-layer barrier structures.
Growth Catalysts
- State plastic reduction mandates:California and Texas supermarket operators face procurement quotas that accelerate adoption of recyclable dome shrink formats. Retailers prioritize compliant packaging to maintain shelf access under evolving statutes.
- Blown-film automation:Heat-shrinkable polyethylene films operating at 120°C–160°C enable faster line speeds in fresh produce wrapping operations. Food retail chains capture labor efficiency gains through integrated extrusion-to-converting systems.
- E-commerce fulfillment expansion:Direct-to-consumer gift basket channels require damage-resistant presentation packaging. Specialty food shippers in Texas and California drive specification changes for puncture-resistant film grades.
Market Restraints
- Resin price volatility:Ethylene feedstock fluctuations transmit directly to polyethylene film margins. Converters without backward integration into resin production face compressed profitability during feedstock spikes.
- Multi-layer recycling incompatibility:Legacy barrier structures combining polyethylene with adhesive layers fail current mechanical recycling streams. California's post-consumer infrastructure rejects these formats, limiting end-market options.
- PVC structural decline:Phthalate scrutiny under EPA guidelines accelerates displacement of polyvinyl chloride alternatives. Former PVC users must absorb reformulation costs to meet FDA 21 CFR 177.1520 olefin polymer standards.
Strategic Opportunities
- Mono-material thermoforming convergence:Heat-shrinkable polyethylene films paired with rigid basket substrates create fully recyclable packaging systems. California-based retailers pilot these configurations to preempt SB 54 compliance deadlines.
- Specialty food e-commerce penetration:Gift basket subscription services in Texas require tamper-evident dome formats with visual shelf appeal. Direct-to-consumer channels represent underdeveloped volume relative to traditional retail.
- Fiber-based hybrid formats:Smurfit Kappa Group's European grocery solutions demonstrate paper-film combinations that satisfy sustainability scorecards. US retailers may import these specifications as their own scorecards tighten.
Industry Challenges
- Food-contact certification timelines:FDA 21 CFR 177.1520 compliance documentation for new olefin formulations extends 18–24 months. Product development cycles compress against state-mandated packaging reduction deadlines.
- Blown-film extrusion capex intensity:Automated multi-layer lines require $8–15 million per installation. Mid-tier converters face capital access constraints when scaling to serve national retail chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dome Shrink Basket Bags Market |
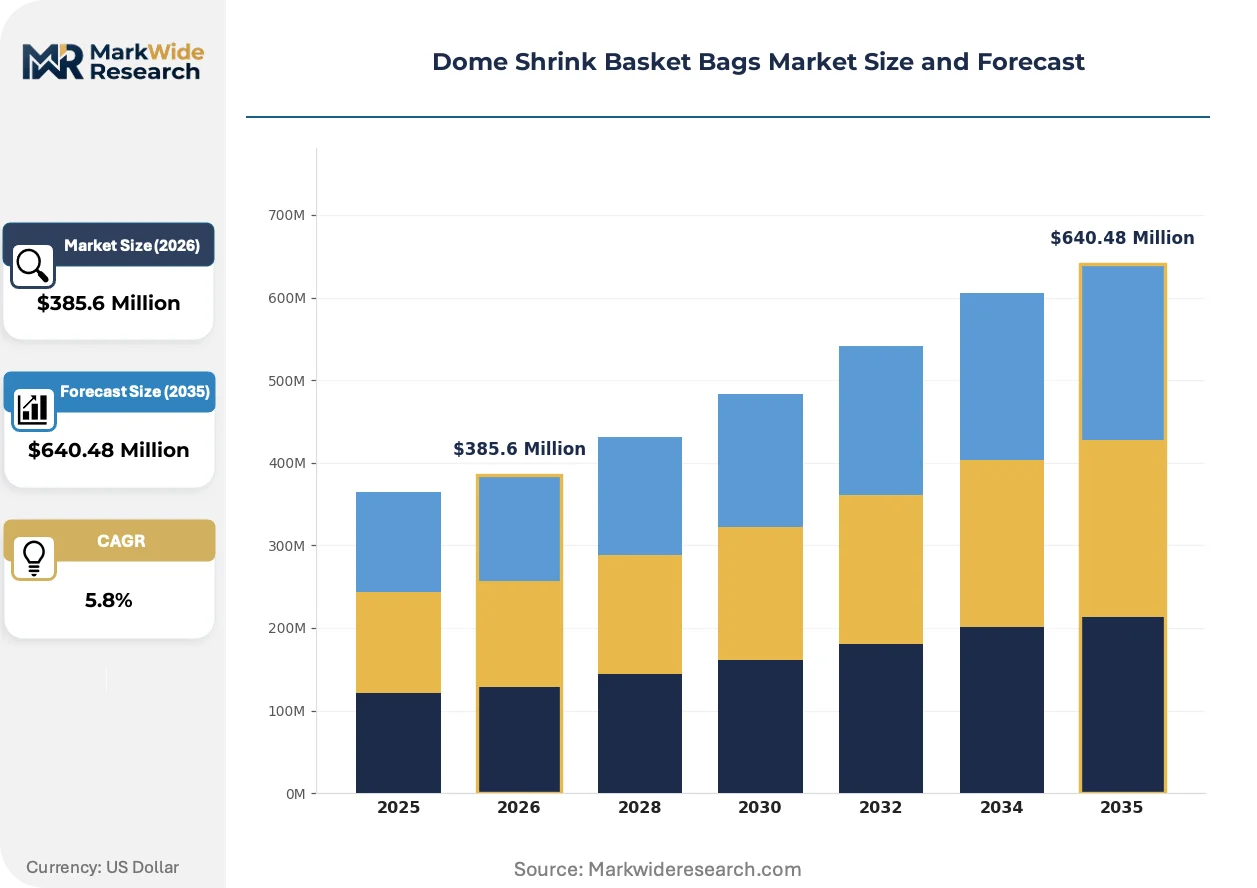
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, PVC, Others Size: Small, Medium, Large, Extra Large End User: Food Retail, E-commerce, Grocery Stores, Bakeries Packaging Type: Flexible Packaging, Rigid Packaging, Bulk Packaging, Pouch |
| Companies Covered | Sealed Air Corporation, Amcor Limited, Berry Global Inc., Coveris, Smurfit Kappa Group, Transcontinental Inc., Graphic Packaging International, Sonoco Products Company, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dome Shrink Basket Bags Market Strategic Shifts
Active reformulation toward recyclable mono-material structures is compressing traditional multi-layer barrier technology while opening specification windows for integrated resin-to-film producers.
High-clarity metallocene polyethylene grades are supplanting conventional linear low-density polyethylene in automated shrink-wrapping lines. Texas-based supermarket operators specify these materials for enhanced optical properties in produce display. The shift enables thinner gauge films without sacrificing seal strength, reducing resin consumption per unit.
EPA guidelines on plastic waste streams are redirecting capital toward post-consumer recycling infrastructure investments. Resin sourcing decisions now incorporate recyclability certifications as gate criteria for retail procurement. California's supermarket operators increasingly require mass-balance documentation for polyethylene feedstocks.
Direct procurement relationships between retail chains and film converters are displacing traditional distribution intermediaries. California and Texas grocery operators negotiate volume commitments directly with extrusion facilities. This channel compression demands converters maintain technical service capabilities previously handled by distributors.
Dome Shrink Basket Bags Market Segmentation
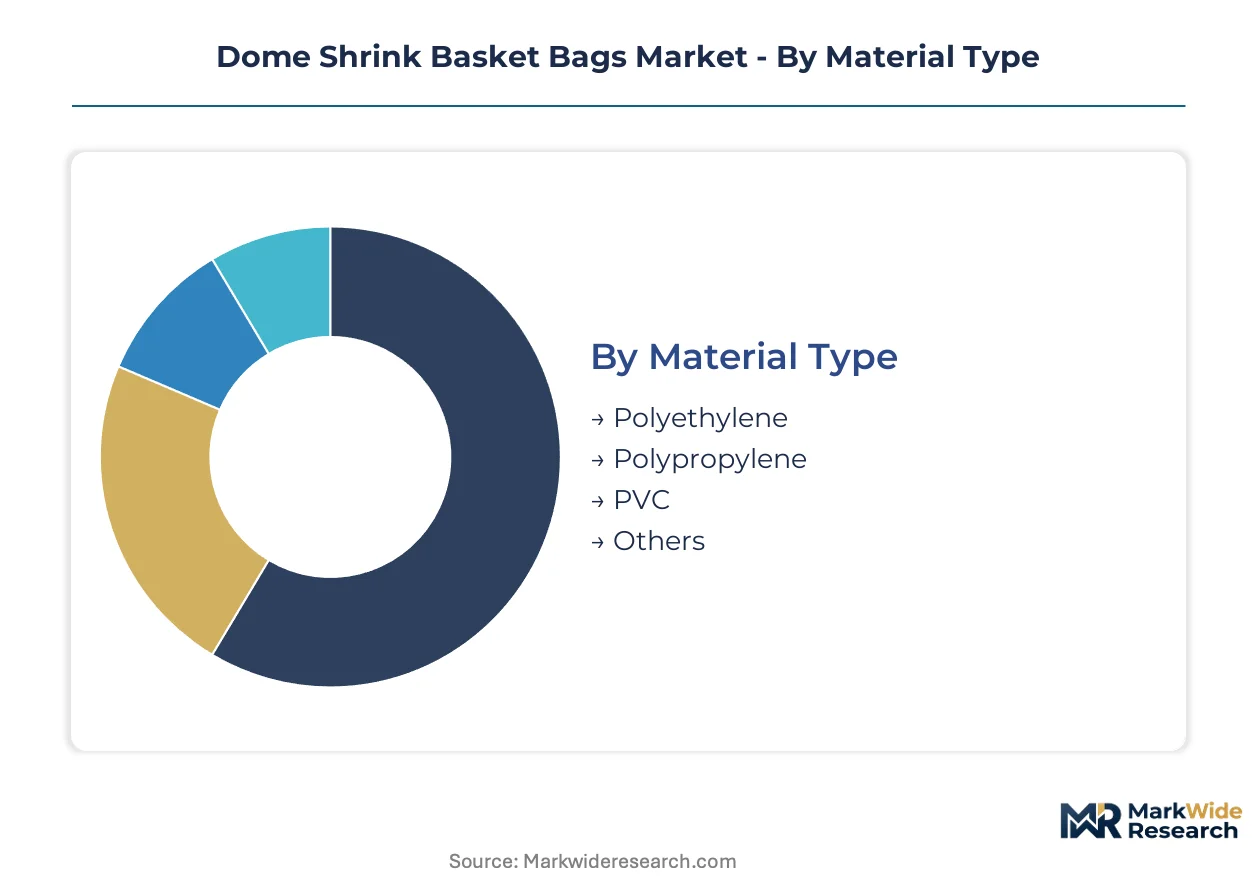
Material compliance pathways and automation requirements create distinct specification tiers across dome shrink basket bags. Segmentation reveals how FDA olefin polymer standards and state-level plastic mandates partition demand across technical and application dimensions.
Material Type:
FDA 21 CFR 177.1520 compliance tiers separate food-contact approved olefins from legacy formulations facing regulatory displacement.
- Polyethylene:Metallocene and linear low-density grades dominate fresh produce wrapping for their clarity at 120°C–160°C shrink temperatures. California supermarket operators specify these materials for automated lines under SB 54 recyclable packaging procurement quotas.
- Polypropylene:Higher thermal stability suits specialty food baskets requiring extended display durability. Texas-based gift basket e-commerce channels drive specification for puncture-resistant biaxially oriented grades in direct-to-consumer fulfillment.
- PVC:Phthalate scrutiny under EPA guidelines accelerates structural decline. Former users absorb reformulation costs to migrate toward olefin alternatives.
- Others:Bio-based and recycled-content experimental grades occupy niche sustainability pilot programs.
Polyethylene handles the majority of throughput; polypropylene is expanding most quickly on share as e-commerce channels scale.
Size:
Automation compatibility and basket substrate dimensions determine volume concentration across gauge specifications.
- Small:Single-serve specialty food and confectionery baskets. Bakeries in Texas specify these for portion-controlled retail displays.
- Medium:Standard fresh produce baskets dominate supermarket throughput. California grocery operators run these dimensions across integrated extrusion-to-converting lines.
- Large:Family-size produce and specialty gift configurations. E-commerce fulfillment channels in California drive demand for damage-resistant film grades at this scale.
- Extra Large:Bulk retail and institutional food service baskets. Limited automation compatibility constrains volume relative to smaller gauges.
Medium dimensions carry the highest line-speed efficiency; large formats are climbing the fastest as direct-to-consumer channels expand basket sizes.
End User:
Channel-specific performance requirements create divergent specification clusters across retail and fulfillment networks.
- Food Retail:Established revenue base concentrated in California and Texas supermarket operators. Automated shrink-wrapping lines demand high-clarity metallocene polyethylene for produce display optimization.
- E-commerce:Fastest-growing channel requiring puncture-resistant presentation packaging. Texas-based gift basket subscription services specify tamper-evident dome formats with visual shelf appeal.
- Grocery Stores:Independent operators and smaller chains with mixed automation levels. Procurement concentrates through regional distribution intermediaries.
- Bakeries:Fresh bread and pastry basket applications with shorter shelf-life requirements. Smaller volume per outlet limits dedicated line investment.
Food retail maintains the installed base; e-commerce is gaining share fastest as fulfillment infrastructure scales.
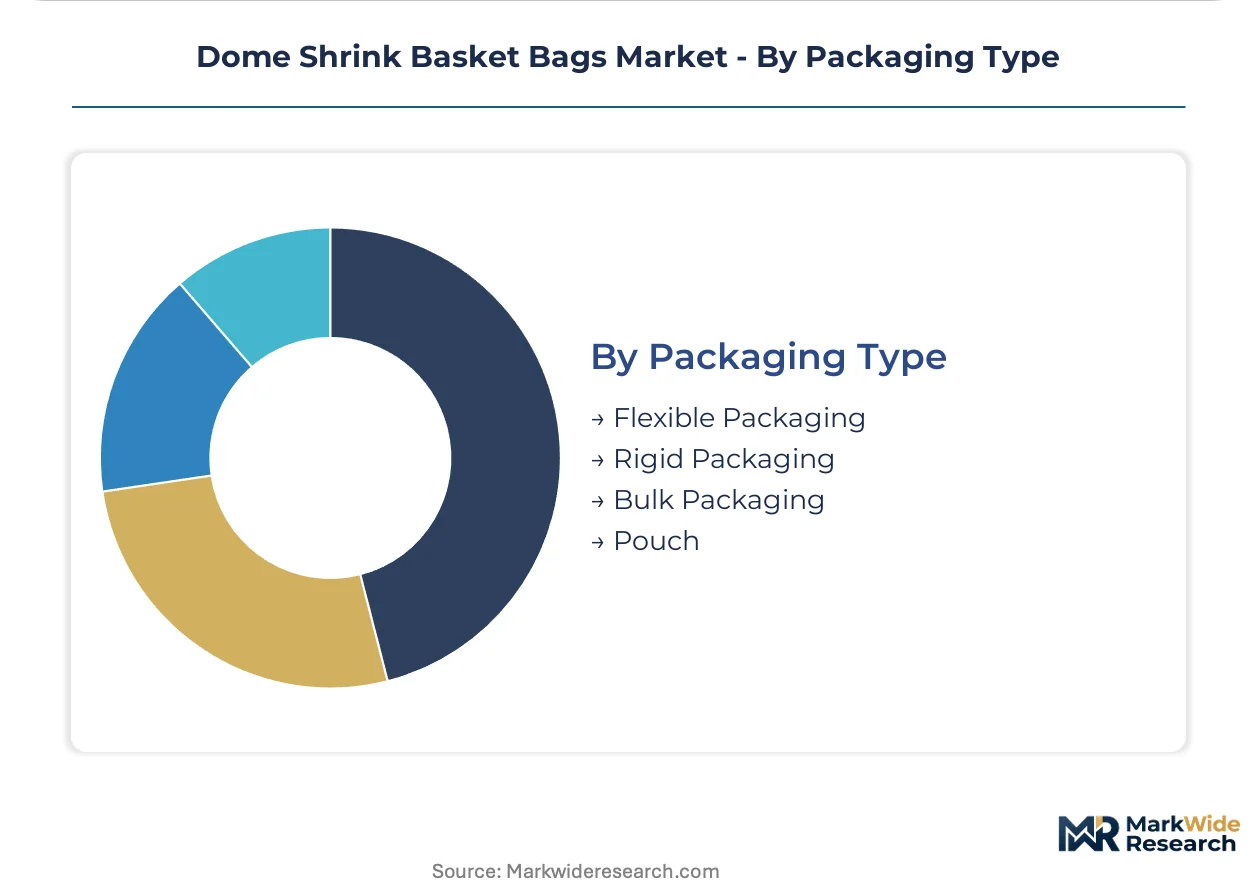
Packaging Type:
Structural integration with rigid basket substrates determines recyclability compliance and automation compatibility.
- Flexible Packaging:Heat-shrinkable polyethylene films formed over rigid substrates. California retailers pilot mono-material configurations to preempt SB 54 deadlines.
- Rigid Packaging:Pre-formed domes with integrated sealing mechanisms. Higher unit costs limit adoption to premium gift and specialty food segments.
- Bulk Packaging:Multi-unit configurations for institutional and club retail channels. Volume efficiency trades off against display aesthetics.
- Pouch:Flat-bottom and stand-up alternatives for non-basket specialty applications. Limited overlap with core dome shrink use cases.
Flexible formats handle the majority of throughput; rigid configurations are expanding most quickly in premium e-commerce gift segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage concentrates with United States converters commanding premium rates for FDA-certified olefin formulations, while European suppliers absorb sustainability-driven cost compression under EPR frameworks. This asymmetry reshapes cross-border procurement patterns for dome shrink basket bags.
United States
California and Texas supermarket chains drive specification standards for high-clarity metallocene polyethylene in automated produce lines. FDA 21 CFR 177.1520 compliance documentation gates supplier qualification, extending 18–24 month certification timelines. Dallas-Fort Worth extrusion clusters anchor national supply for e-commerce fulfillment channels requiring puncture-resistant gift basket formats.
Germany
Retail sustainability scorecards from Rewe and Edeka force mono-material reformulation across flexible packaging supply chains. ECHA REACH restrictions on phthalate additives accelerate displacement of legacy PVC structures. The Rhine-Ruhr industrial corridor hosts blown-film specialists serving Dutch and Belgian grocery export markets with recyclable polyethylene configurations.
China
Domestic fresh produce retail modernization creates demand for tamper-evident dome formats in Hema Fresh and 7FRESH supermarket networks. SAMR food-contact material standards tighten import substitution pressures on foreign resin suppliers. Yangtze River Delta converting clusters near Shanghai scale automated wrapping line integration for regional grocery chains.
France
Carrefour and Intermarché procurement mandates prioritize mass-balance certified polyethylene under extended producer responsibility schedules. ANSM oversight of food-contact polymers adds compliance layers beyond EU baseline requirements. The Lyon-Auvergne-Rhône-Alpes packaging belt specializes in premium gift and specialty food basket applications for export.
United Kingdom
Tesco and Sainsbury's plastic reduction commitments compress specification windows toward recyclable mono-material structures. Post-Brexit divergence from EU packaging regulations creates parallel compliance tracks for cross-channel suppliers. The Midlands converting corridor concentrates capacity for bakery and confectionery basket segments with shorter development cycles.
Dome Shrink Basket Bags Market Competitive Environment
Concentration sits with integrated resin-to-film producers wielding backward integration advantages over pure-play converters. The competitive structure stratifies across three tiers: multinational packaging conglomerates with captive polyethylene production, regional blown-film specialists serving single-country retail networks, and niche hybrid-format innovators addressing sustainability mandates. Dominant competitive moves include capacity expansion in automated multi-layer extrusion lines and strategic partnerships between film converters and rigid basket substrate manufacturers.
Within the multinational tier, Sealed Air Corporation and Berry Global Inc. exemplify integrated production architectures spanning resin compounding through finished film. Smurfit Kappa Group occupies a distinct position as a fiber-based hybrid specialist, representing the sustainability-driven archetype competing via paper-film combinations rather than pure polymer formulations. These three anchors illustrate divergent strategic postures: resin integration versus material substitution versus channel-specific sustainability compliance.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Amcor Limited |
| Berry Global Inc. |
| Coveris |
| Smurfit Kappa Group |
| Transcontinental Inc. |
| Graphic Packaging International |
| Sonoco Products Company |
| WestRock Company |
| Others |
Value Chain & Pricing Dynamics
Metallocene polyethylene substitution for conventional linear low-density grades simultaneously redraws supply geography toward Texas and California extrusion clusters and compresses pricing economics through thinner-gauge equivalence. FDA 21 CFR 177.1520 certification tiers now partition supplier access, with certified olefin converters commanding premium positioning against uncertified competitors facing regulatory displacement.
Pricing Analysis
Customization-premium spreads separate configured-to-order metallocene formulations from standard linear low-density polyethylene grades. Three-tier pricing structure across premium metallocene, standard LLDPE, and economy PVC-alternative levels reflects FDA certification status and optical clarity performance. Cost compression in standard grades is intensifying because California SB 54 procurement quotas favor certified suppliers. Supermarket operators in Texas demonstrate highest price sensitivity due to volume scale, while specialty food e-commerce channels in California absorb premiums for puncture-resistant biaxially oriented polypropylene.
Supply Chain Analysis
Port congestion along Los Angeles-Long Beach trade lanes elevates inbound logistics costs for Asian resin shipments to California converting facilities. Supply concentrates in the United States, China, and Germany, with domestic extrusion clusters drawing from Gulf Coast ethylene feedstock and imported metallocene catalyst systems. Raw material dependencies rest on ethylene monomer, metallocene catalysts, and calcium carbonate masterbatch additives. Single-source vulnerability sits with specialized metallocene catalyst suppliers. Distribution runs through direct procurement relationships between retail chains and film converters, displacing traditional distribution intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
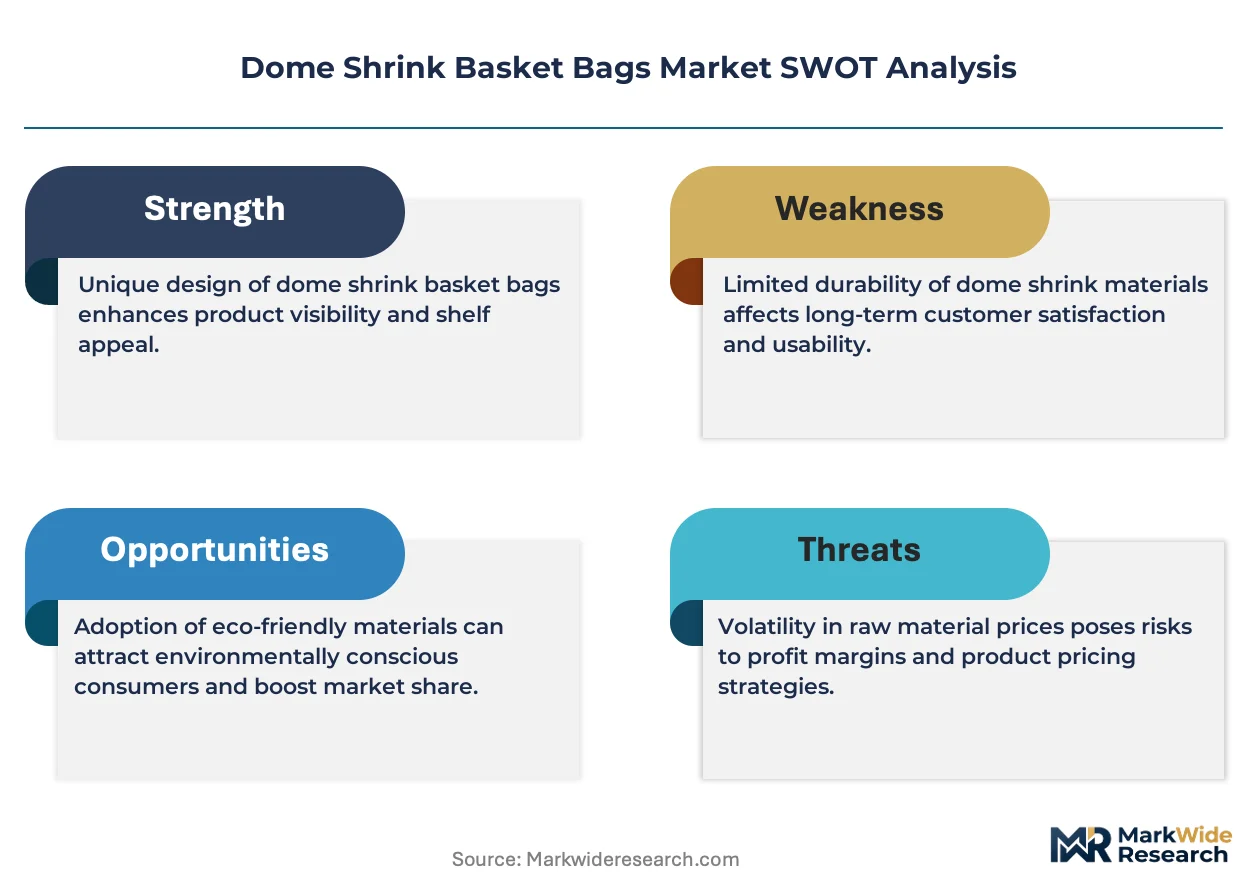
Dome shrink basket bags function as a regulatory-entrenchment defensive moat, where FDA 21 CFR 177.1520 certification timelines and state-level plastic mandates create switching costs that protect qualified suppliers from rapid competitive displacement.
For Market Incumbents: Shield market position through accelerated mono-material thermoforming R&D to preempt California SB 54 compliance deadlines, and secure backward integration into metallocene catalyst supply chains to defend margins against resin price volatility. The threat of fiber-based hybrid substitution from European competitors demands technical service capabilities that match direct procurement relationships retail chains now require.
For New Entrants and Emerging Players: Anchor in Texas e-commerce fulfillment channels where gift basket subscription services drive specification changes for puncture-resistant film grades with limited incumbent saturation. The most penetrable white-space sits in specialty food direct-to-consumer segments requiring tamper-evident dome formats. A go-to-market angle through sustainability-certified mono-material pilots with California-based retailers offers qualification pathway acceleration.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier blown-film converters possessing FDA certification but lacking automated multi-line capacity. Long-term viability over a five-to-ten year horizon hinges on successful mono-material transition completion. The acquisition target archetype centers on California or Texas-based converters with established retail relationships and underutilized extrusion infrastructure. The signal to watch as inflection indicator is mass-balance certification adoption rates among supermarket procurement departments.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Thermoforming Convergence | California retailers pilot recyclable polyethylene-rigid substrate combinations to preempt SB 54 deadlines. |
| Backward Integration into Resin Production | Converters with captive ethylene supply chains defend margins during feedstock volatility spikes. |
| E-commerce Fulfillment Specification Development | Texas gift basket subscription services drive demand for puncture-resistant biaxially oriented grades. |
| FDA Certification Timeline Acceleration | Early olefin polymer submission under 21 CFR 177.1520 gates supplier qualification before state mandates tighten. |
| Fiber-Based Hybrid Format Licensing | European paper-film combinations from Smurfit Kappa demonstrate sustainability scorecard compliance transferable to US retail. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR submission databases, state-level packaging statute filings, and retail procurement documentation. Interviews with blown-film plant managers, supermarket category buyers, specialty food e-commerce fulfillment directors, and resin procurement leads informed demand-side validation. Secondary sources included SEC 10-K filings of integrated packaging conglomerates, American Chemistry Council resin production reports, and California Department of Resources Recycling and Recovery regulatory filings. Bottom-up volume estimates from extrusion line capacity assessments triangulated against top-down retail packaging spend allocation models.
Segmentation dimensions modeled span material type, basket size configuration, end-user channel, and packaging structural format across the projection horizon. The analytical framework incorporated food retail automation adoption curves, e-commerce fulfillment infrastructure buildout rates, and state-level extended producer responsibility implementation schedules. CAGRs derived from regression analysis of historical polyethylene film demand against produce retail volume and gift basket shipment indices.
Decision-makers should treat outputs as directional under assumptions of steady California SB 54 enforcement progression and stable ethylene feedstock availability; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Quad Seal Bag Market
Bags and Containers
Clay Desiccant Bag Market
Bags and Containers
Inner Bulk Liners Market
Bags and Containers
Aluminum Beverage Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
Breather Bags Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Archive Boxes Market
Bags and Containers
Freezing Bags Market
Bags and Containers
Pre-Made Bags Market
Bags and Containers
Baggage Packaging Service Market
Bags and Containers
Net Bags Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Bag-In-Box Container Market