
 Heat Sealing Bags Market | 2026-2036
Heat Sealing Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Sealing Bags Market Outlook
Food services is restructuring demand patterns across the Heat Sealing Bags Market as quick-service chains and meal-kit platforms scale portion-controlled packaging needs. Amcor Plc leverages its global manufacturing footprint to sustain supply consistency across multiple continents. Mondi anchors European demand through specialized barrier film capabilities aligned with shelf-life extension requirements. Sonoco Products Company differentiates via rigid-flexible hybrid formats that serve dual temperature environments.
Heat sealing bags are thermoplastic enclosures sealed through the application of heat and pressure, typically constructed from polyethylene, polypropylene, or multilayer barrier films with seal strengths ranging from 15 to 50 N/15mm depending on application criticality. These containers serve primarily to exclude oxygen, moisture, and contaminants during storage, transport, and retail display of perishable and sensitive goods. Polyethylene formulations occupy the largest volume share due to cost efficiency and broad process compatibility across form-fill-seal lines. Barrier films represent the fastest-expanding material category as pharmaceutical and electronics end users impose stricter moisture-vapor transmission rate thresholds. Double-track closure configurations command premium positioning where resealability drives consumer convenience metrics in retail channels.
FDA food contact notification requirements govern material migration limits for U.S.-destined heat sealing bags, while REACH compliance obligations within Europe restrict certain phthalate plasticizers and mandate substance registration for imported films. ISO 11607 standards for sterile barrier systems further shape medical-grade product development pathways. Stakeholders must monitor evolving extended producer responsibility frameworks that transfer end-of-life accountability upstream to converters and resin suppliers.
Market Dynamics
Food service procurement consolidation is compressing supplier margins while mandating lot-level traceability and standardized portion formats across quick-service and meal-kit channels.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are accelerating recyclable mono-material adoption among converters serving European retail channels.
- Meal-kit subscription models:Portion-controlled packaging specifications from Blue Apron-style platforms are pulling demand for precision-sealed barrier formats with printed cooking instructions.
- Pharmaceutical cold chain expansion:Biologics distribution growth is driving moisture-vapor transmission rate requirements below 0.1 g/m²/day for sterile barrier systems.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin prices swing with naphtha-cracker margins in the US Gulf Coast and Middle East, squeezing converter profitability on fixed-price contracts.
- Barrier film supply concentration:EVOH and metallized substrate production clusters in Japan and Germany create single-source vulnerability for North American converters.
- REACH substance restrictions:ECHA's evolving candidate list for phthalate plasticizers forces reformulation cycles that delay product launches by 12-18 months.
Strategic Opportunities
- India food processing corridors:FSSAI-mandated packaging standards in Maharashtra and Gujarat processing zones are creating first-mover advantage for barrier-certified suppliers.
- RFID-embedded intelligent packaging:Temperature-logging seal interfaces are converging with blockchain traceability for pharmaceutical and premium food applications.
- Direct-to-consumer frozen specialty channels:E-commerce fulfillment specifications for 48-hour thermal protection are opening niche demand for insulated heat-sealed pouch formats.
Industry Challenges
- ISO 11607-1 sterile barrier certification:Medical-grade validation protocols require 18-24 month qualification timelines that strain working capital for mid-scale converters.
- Legacy form-fill-seal line retrofitting:Ultrasonic and impulse sealing module upgrades demand capex outlays that conflict with 3-5 year equipment depreciation schedules.
- Cross-functional barrier engineering talent:Scarcity of polymer scientists with both food contact compliance and high-speed converting experience limits R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Sealing Bags Market |
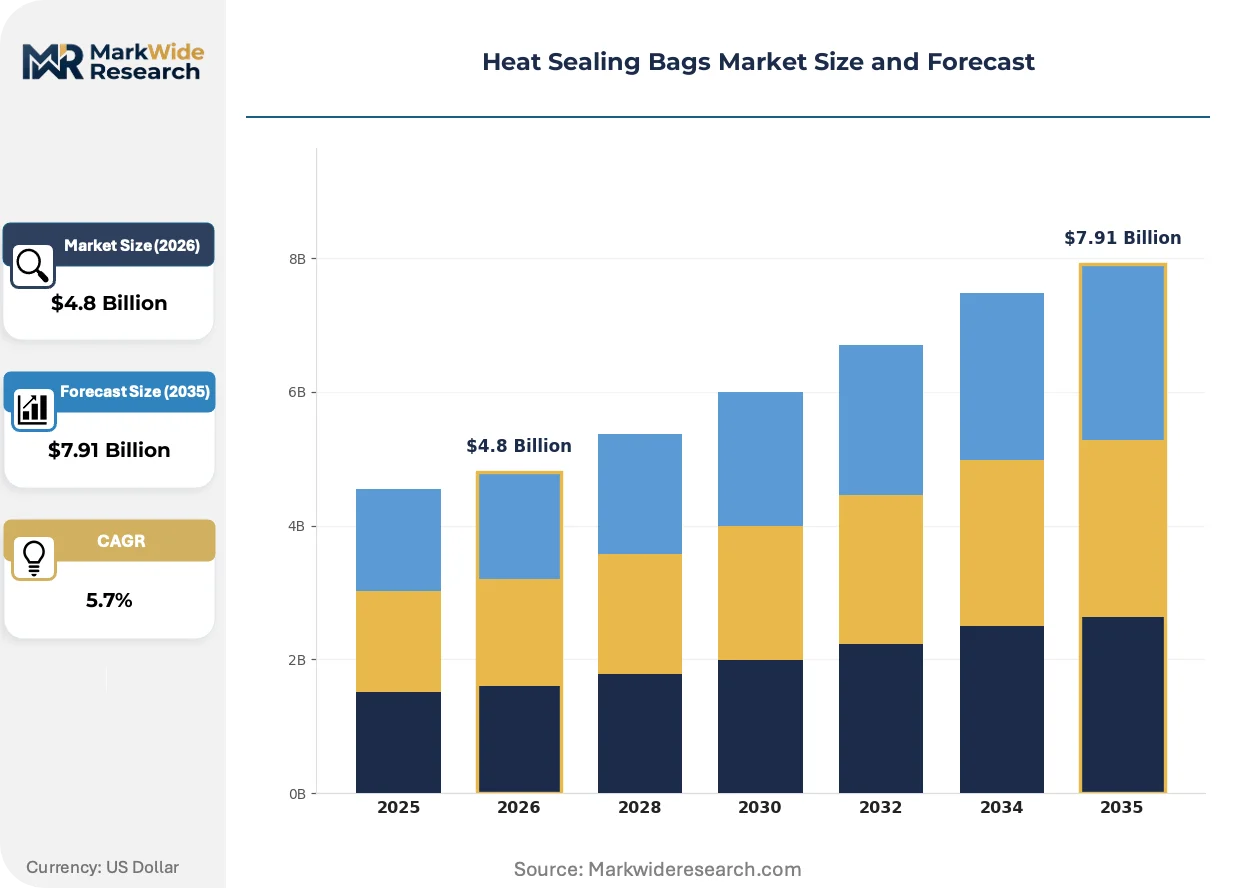
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyethylene, Polypropylene, Nylon, Barrier Films Closure Type: Single Track, Double Track, Triple Track, Zipper Application: Food Packaging, Medical Supplies, Electronics, Industrial Materials End User: Retail, Food Services, Healthcare, Manufacturing |
| Companies Covered | Amcor Plc, Heritage Packaging, Sonoco Products Company, Huhtamaki, Mondi, Constantia Flexibles, Clearview Packaging, TedPack Company Limited, Saint-Gobain Performance Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Sealing Bags Market Strategic Shifts
Active barrier technologies and digital printing integration are redefining performance benchmarks and supply chain responsiveness across heat sealing bag applications.
Multilayer coextrusion with tie-layer adhesion optimization is consolidating the position of high-barrier films in pharmaceutical and electronics packaging. Medical device manufacturers are adopting these formats at accelerated qualification cycles to meet ISO 11607 sterile barrier requirements. This consolidation is compressing demand for conventional metallized laminates in moisture-sensitive applications.
REACH authorization procedures for intentionally added microplastics are forcing reformulation of slip agents and anti-block additives in European-sourced films. Converters must submit substance dossiers to ECHA or pivot to bio-based alternatives with equivalent coefficient-of-friction performance. Pharmaceutical and organic food segments are absorbing premium pricing for compliant material sets to maintain EU market access.
Consolidated procurement through food service buying cooperatives is displacing fragmented distributor relationships in North American quick-service restaurant supply chains. Centralized specification-setting by Yum! Brands and Domino's Pizza procurement teams is standardizing pouch dimensions and print formats across regional supplier bases. This concentration is most visible in the US Southeast poultry processing corridor, where Tyson Foods and Pilgrim's Pride operations now dictate seal-strength testing protocols.
Heat Sealing Bags Market Segmentation
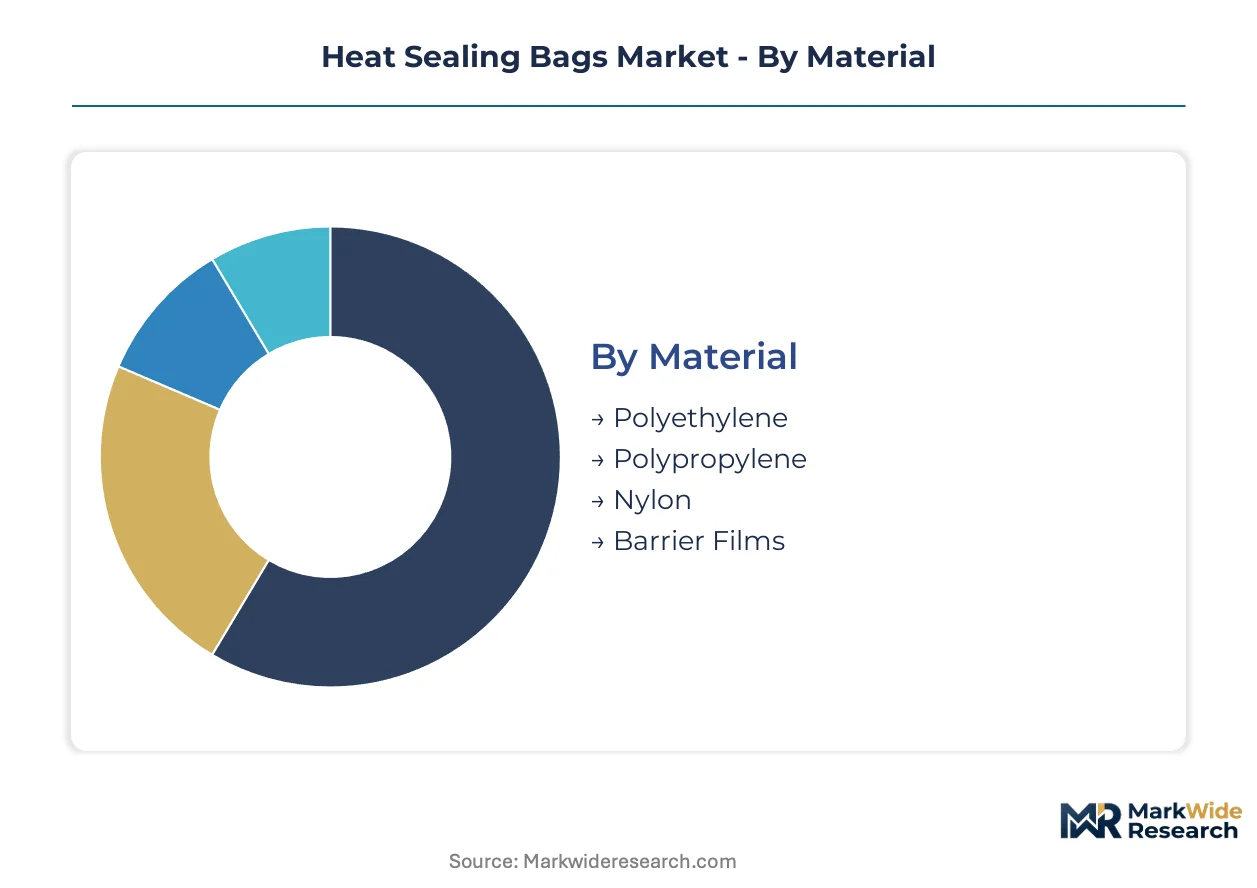
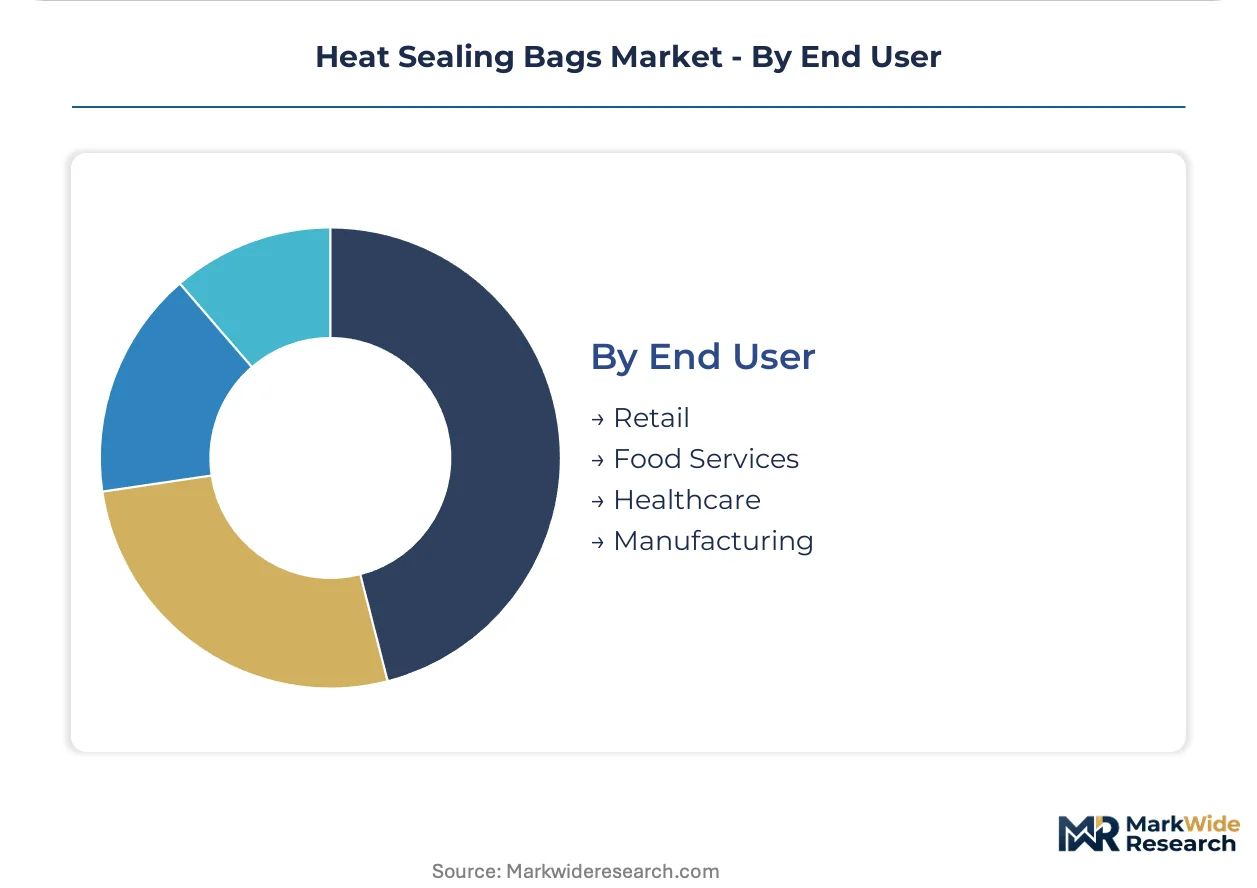
Material selection dictates seal integrity thresholds and regulatory compliance pathways across heat sealing bag applications. Closure configurations differentiate convenience metrics and resealability performance in retail versus institutional channels.
Material:
Upgrade cycles favor mono-material formats that simplify recycling streams without sacrificing barrier performance.
- Polyethylene:Linear low-density and high-density formulations dominate form-fill-seal line compatibility. Cost efficiency drives procurement across US quick-service restaurant supply chains and German discount retail private-label programs.
- Barrier Films:Multilayer coextrusions with EVOH or metallized substrates achieve moisture-vapor transmission rates below 0.1 g/m²/day. Pharmaceutical cold chain expansion in Switzerland and electronics moisture protection in South Korea concentrate demand for these specifications.
- Polypropylene:Cast and oriented films offer higher temperature resistance for retort and hot-fill applications. FDA food contact notification compliance is straightforward for homopolymer grades.
- Nylon:Biaxially oriented polyamide delivers puncture resistance for bone-in meat and industrial hardware packaging. REACH substance restrictions on certain additives complicate European sourcing.
Volume placements concentrate in polyethylene; the faster expansion belongs to barrier films.
Closure Type:
Customer type determines whether resealability justifies material cost premiums in the final specification.
- Single Track:Basic heat-sealed seams suit one-time-use industrial and medical sterilization pouches. Manufacturing segments in Maharashtra and Gujarat processing zones specify these for cost-minimized throughput.
- Double Track:Parallel seal lines provide redundancy for liquid containment and extended shelf-life foods. Meal-kit platforms specify these with printed cooking instructions for portion-controlled proteins.
- Zipper:Press-to-close interlocking profiles enable consumer resealability in snack and frozen vegetable retail. Premium pricing absorbs slider assembly costs in North American club store channels.
- Triple Track:Maximum seal integrity for hazardous materials and biologics transport. ISO 11607 sterile barrier validation requirements extend qualification timelines.
Food services procurement standardizes on double-track formats; retail channels are climbing the fastest toward zipper integration.
Application:
Application segmentation tracks how barrier requirements and regulatory exposure vary across end-use environments.
- Food Packaging:Oxygen exclusion and moisture control for fresh, frozen, and shelf-stable products. FSSAI-mandated standards in Indian processing corridors and EU Packaging Waste Regulation recyclability targets reshape material specifications.
- Medical Supplies:Sterile barrier systems for devices and pharmaceutical components. ISO 11607-1 certification demands 18-24 month validation cycles that strain converter working capital.
- Electronics:Desiccant-compatible pouches for semiconductors and sensitive components. Japan and Germany substrate production clusters create supply concentration risk for North American converters.
- Industrial Materials:Chemical resistance and containment for abrasives, powders, and hardware. Lower regulatory burden permits recycled content incorporation.
Food packaging retains the dominant placement volume; medical supplies exhibit the steepest expansion trajectory.
End User:
Margin structures diverge sharply between consolidated food service buying cooperatives and fragmented retail distributor networks.
- Food Services:Quick-service chains and meal-kit platforms mandate lot-level traceability and standardized portion formats. Yum! Brands and Domino's Pizza procurement teams dictate seal-strength testing protocols across US Southeast poultry processing corridors.
- Healthcare:Hospital systems and pharmaceutical distributors impose sterile barrier validation and cold chain documentation. EMA and FDA dual compliance requirements govern material migration limits.
- Retail:Supermarkets and e-commerce fulfillment channels prioritize shelf presence and resealability convenience. Private-label concentration in German discount retail drives specification standardization.
- Manufacturing:Industrial converters and original equipment manufacturers specify functional performance over aesthetic requirements. Lower switching costs intensify price competition.
Food services procurement consolidation is accelerating; healthcare compliance requirements are gaining share fastest among premium-tier suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's food processing special economic zones concentrate converter activity near Mumbai-Pune logistics corridors. FSSAI-mandated packaging standards in these zones reshape procurement specifications for barrier-certified suppliers. Dense poultry and seafood processing clusters drive precision-sealed format demand across western India.
United States
Quick-service restaurant procurement consolidation centers on the US Southeast poultry processing corridor. FDA food contact notification requirements govern material migration limits for domestic converters. Tyson Foods and Pilgrim's Pride operations in Arkansas and Georgia dictate seal-strength testing protocols across regional supplier bases.
Germany
Discount retail private-label concentration drives specification standardization in polyethylene formats. REACH compliance obligations restrict certain phthalate plasticizers and mandate substance registration for imported films. The dense food processing cluster in Lower Saxony imposes stringent barrier-performance standards that filter across European supply chains.
China
Electronics moisture protection demand concentrates in Yangtze River Delta semiconductor fabrication zones. GB standards and SAMR oversight govern food contact material safety for domestic and export-bound production. Suzhou and Wuxi substrate processing hubs create supply concentration for EVOH and metallized film converters serving North American markets.
India
FSSAI-mandated packaging standards in Gujarat processing zones create first-mover advantage for barrier-certified suppliers. The country's national food regulator enforces compliance timelines that accelerate converter qualification cycles. Ahmedabad and Surat industrial corridors attract multilayer coextrusion investments from European film suppliers seeking tariff-advantaged production.
Switzerland
Pharmaceutical cold chain expansion drives moisture-vapor transmission rate requirements below 0.1 g/m²/day. Swissmedic oversight of sterile barrier systems shapes medical-grade product development pathways for converters serving European hospital systems. Basel's biologics distribution hub concentrates demand for ISO 11607-validated pouch formats.
Heat Sealing Bags Market Competitive Environment
Top-tier vendors anchor global supply consistency through multi-continent manufacturing footprints, while mid-scale specialists occupy regional niches with certified barrier capabilities. The competitive structure stratifies across three tiers: integrated packaging conglomerates with resin-to-pouch vertical control, regional converters with FDA or EMA compliance specializations, and commodity suppliers competing on form-fill-seal line compatibility. M&A activity targets barrier film technology access, particularly EVOH coextrusion capabilities. Capacity expansion concentrates in India and Southeast Asia to capture food processing corridor growth.
Within the integrated packaging tier, Amcor Plc and Mondi exemplify scale-driven positioning with broad geographic coverage and specialized barrier film portfolios. Sonoco Products Company occupies a distinctive niche through rigid-flexible hybrid format capabilities. Among European specialists, Constantia Flexibles represents the regional converter archetype with EMA-aligned compliance pathways. Heritage Packaging and Clearview Packaging sit within the North American mid-tier segment focused on quick-service restaurant supply chain integration. These five entities collectively illustrate the competitive spectrum from global supply assurance to regional certification specialization.
| Leading Market Players |
|---|
| Amcor Plc |
| Heritage Packaging |
| Sonoco Products Company |
| Huhtamaki |
| Mondi |
| Constantia Flexibles |
| Clearview Packaging |
| TedPack Company Limited |
| Saint-Gobain Performance Plastics |
| Others |
Value Chain & Pricing Dynamics
Quick-service restaurant procurement consolidation across the US Southeast poultry processing corridor is compressing supplier margins and mandating standardized portion formats, forcing converters to absorb certification costs while competing on form-fill-seal line compatibility. This buyer-driven specification tightening creates pricing asymmetry between barrier-certified specialists and commodity polyethylene suppliers.
Pricing Analysis
Short lead-time premiums of 15-25% apply to ISO 11607-validated sterile barrier formats for pharmaceutical cold chain applications, while spot inventory discounts emerge for standard polyethylene grades in oversupplied quarters. Three-tier pricing structure across premium, standard, and economy levels separates FDA-tier barrier films from industrial-grade mono-materials from commodity recycled-content formats. Cost compression in the standard tier is intensifying because ethylene feedstock volatility squeezes fixed-price contract profitability. Food service buying cooperatives exhibit highest price sensitivity due to centralized procurement, while pharmaceutical distributors absorb premiums for validated sterile barrier systems.
Supply Chain Analysis
Workforce availability constraints in Maharashtra and Gujarat processing zones are slowing multilayer coextrusion capacity ramp-ups despite FSSAI-mandated packaging standards accelerating demand. Supply concentrates in China for EVOH substrate production, Germany for metallized film conversion, and India for tariff-advantaged pouch manufacturing. Raw material dependencies include polyethylene resin from US Gulf Coast crackers, EVOH from Japan-Germany production clusters, and slip agents subject to REACH authorization. Single-source vulnerability for metallized substrates creates supply chain risk. Distribution runs through food service buying cooperatives in North America, discount retail private-label networks in Germany, and pharmaceutical distributor hubs in Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier film technology transition from metallized laminates to multilayer coextrusion is displacing legacy converter capabilities and reshaping competitive positioning across pharmaceutical and electronics applications.
For Market Incumbents: Deploy backward integration into EVOH coextrusion capabilities to defend against Japanese-German substrate supply concentration. Capture meal-kit platform procurement consolidation through dedicated portion-controlled format lines. Counter REACH substance restriction delays by pre-qualifying bio-based additive alternatives with equivalent coefficient-of-friction performance. For New Entrants and Emerging Players: Direct-to-consumer frozen specialty e-commerce channels represent an underserved buyer archetype with 48-hour thermal protection specifications creating niche demand for insulated pouch formats. Target India's FSSAI-mandated processing corridors in Gujarat where barrier-certified supplier gaps persist. Pursue RFID-embedded intelligent packaging partnerships with blockchain traceability providers as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale converters possessing ISO 11607 sterile barrier validation given pharmaceutical cold chain expansion driving moisture-vapor transmission rate requirements below 0.1 g/m²/day. Long-term viability over a 5-10 year window favors specialists with dual FDA-EMA compliance pathways. Monitor ECHA microplastic authorization timelines as the signal to watch for material substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Coextrusion | Captive supply of high-barrier substrates reduces dependence on Japan-Germany production clusters. |
| ISO 11607 Sterile Barrier Certification | 18-24 month validation cycles create defensible positioning in pharmaceutical cold chain expansion. |
| RFID-Embedded Intelligent Packaging Partnership | Temperature-logging seal interfaces converge with blockchain traceability for premium applications. |
| India Food Processing Corridor Capacity Expansion | FSSAI-mandated standards in Gujarat and Maharashtra accelerate first-mover advantage capture. |
| Bio-Based Additive Reformulation Program | REACH-compliant material sets maintain EU market access amid microplastic authorization procedures. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with converter plant managers, food service procurement leads, pharmaceutical packaging engineers, and film R&D directors. FDA food contact notifications, ECHA substance dossiers, FSSAI compliance timelines, and ISO 11607 certification databases provided regulatory validation. Bottom-up capacity assessments across Maharashtra, Gujarat, and Yangtze River Delta manufacturing zones were cross-checked against top-down demand estimates from quick-service restaurant supply chain disclosures.
Data-stream reconciliation across material grade, closure configuration, application, and end-user dimensions produced volume and value estimates across the analysis window. CAGRs were derived from segmented growth rate differentials weighted by base-year share. Forecast inputs included ethylene feedstock price trajectory assumptions, EVOH capacity expansion timelines in China and Germany, and meal-kit subscription platform growth projections.
Revisions become necessary when REACH substance restrictions expand beyond phthalate plasticizers, when FSSAI accelerates compliance timelines, or when pharmaceutical cold chain specifications tighten further. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Mattress and Furniture Bags Market
Bags and Containers
Craft Bags Market
Bags and Containers
Flip-Up Vacuum Pack Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Bin Liners Market
Bags and Containers
Compression Baggers Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Isothermal Bags Market
Bags and Containers
Lay Flat Bags Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Hermetic Storage Bags Market
Bags and Containers
Bags and Containers Market
Bags and Containers
Anti-Static Polyethylene Bag Market