
 Matcha Tea Market | 2026-2036
Matcha Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Matcha Tea Market Intelligence
Wellness center procurement of matcha-based beverages and supplements is expanding faster than traditional tea house consumption. Ippodo leverages centuries-old Kyoto milling techniques to sustain premium positioning in ceremonial-grade supply. Mizuba Tea Co. anchors direct-to-consumer channels with organic-certified Uji-sourced product lines. Marukyu Koyamaen dominates bulk culinary-grade contracts with food and beverage manufacturers across North America and Europe.
Matcha tea comprises finely ground powder from shade-grown Camellia sinensis leaves, with particle size typically below 10 microns and chlorophyll content elevated through 20-30 days of pre-harvest shading. Ceremonial-grade matcha commands the highest margin pool due to limited first-flush harvest volumes and labor-intensive stone-grinding requirements. Culinary-grade supply leads total volume through penetration into confectionery and beverage manufacturing, while organic-grade certification is accelerating fastest among specialty retailers responding to clean-label procurement standards. Distribution through online retail channels is reshaping price transparency and origin traceability expectations.
Japan's Ministry of Agriculture, Forestry and Fisheries enforces geographic indication protocols for Uji and Nishio production zones, while the USDA National Organic Program and EU Organic Regulation govern import eligibility for North American and European markets. FDA food additive classifications and EFSA novel food assessments shape matcha inclusion thresholds in dietary supplements and fortified beverages. Stakeholders must monitor evolving pesticide maximum residue limits across import jurisdictions and invest in blockchain traceability systems to defend premium positioning against adulteration risks.
Market Dynamics
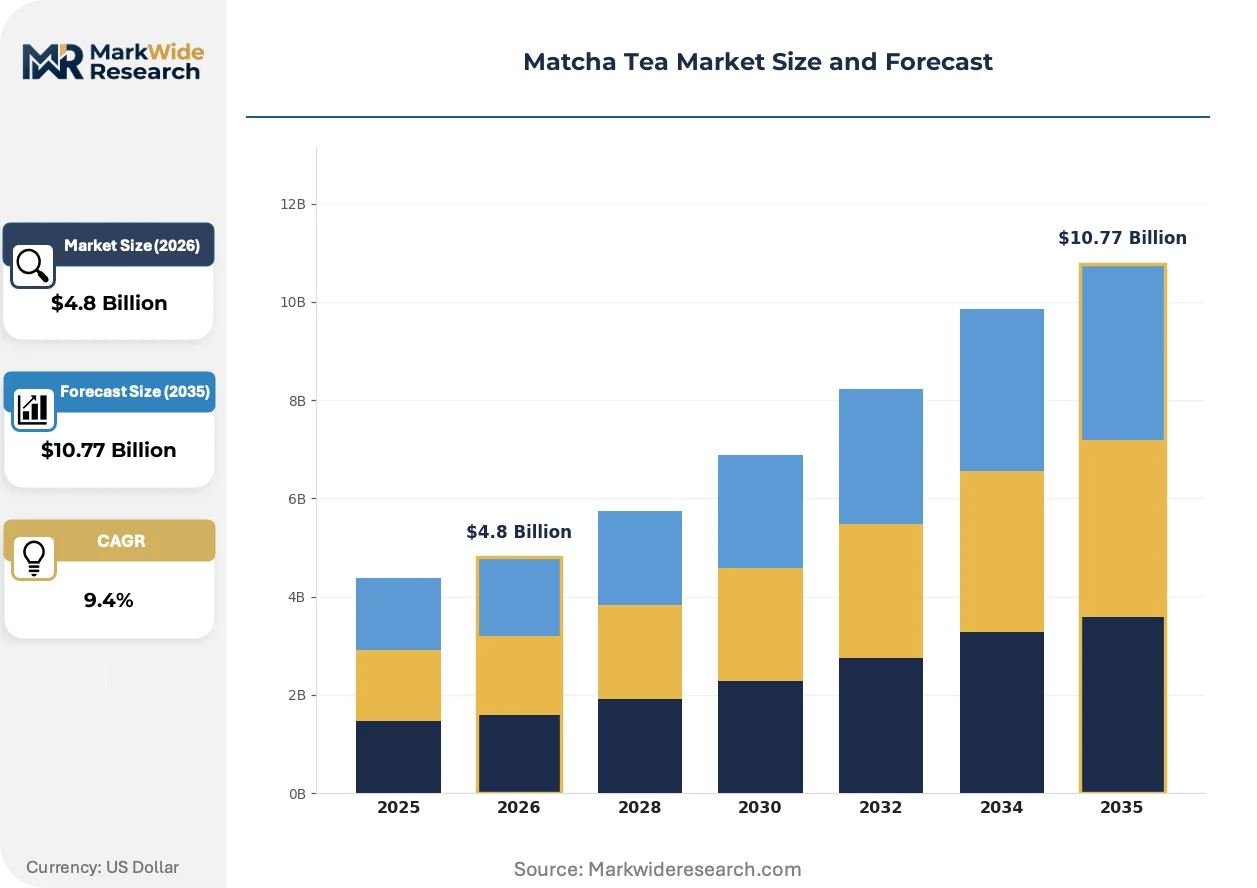
Shade-grown cultivation protocols and geographic indication enforcement by Japan's Ministry of Agriculture are concentrating supply authenticity verification, while North American wellness centers and beverage manufacturers pull procurement toward traceable, certified-grade powder.
Growth Catalysts
- USDA National Organic Program certification:Clean-label procurement standards at specialty retailers accelerate organic-grade matcha sourcing. Premium positioning defends margin pools against conventional alternatives.
- Ready-to-drink beverage manufacturing:Food and beverage producers expand ceremonial-grade matcha procurement for functional drink formulations. This application segment commands higher value per kilogram than bulk culinary supply.
- Uji and Nishio production zones:Japan's geographic indication protocols create export quality benchmarks that authenticate origin claims. These zones concentrate first-flush harvest volumes with elevated chlorophyll content.
Market Restraints
- Labor-intensive stone-grinding requirements:Ceremonial-grade production depends on traditional milling techniques that limit throughput scaling. Kyoto-based processors face capacity constraints during peak harvest windows.
- Shade-grown tea input volatility:Twenty to thirty day pre-harvest shading periods require precise climate conditions. Weather disruption in Kagoshima and Shizuoka prefectures compresses viable cultivation windows.
- EFSA novel food assessment thresholds:European inclusion limits for matcha in dietary supplements create formulation complexity. Fortified beverage developers must navigate additive classification reviews.
Strategic Opportunities
- Blockchain traceability systems:Origin verification technology addresses adulteration risks in premium segments. Producers deploying distributed ledger protocols capture price premiums from transparency-demanding buyers.
- Direct-to-consumer channel expansion:Online retail platforms reshape price discovery and geographic reach. Specialty brands bypass traditional import distributors to serve wellness center and home consumer segments directly.
- Confectionery application development:Culinary-grade matcha penetration into baking and dessert manufacturing extends volume demand beyond beverage categories. This application diversifies revenue concentration from drink formulations.
Industry Challenges
- Pesticide maximum residue limit harmonization:Divergent import jurisdiction standards between FDA, EFSA, and Japan's agricultural ministry create compliance complexity. Exporters must maintain multiple certification tracks.
- Particle size consistency at sub-10 micron specification:Stone-grinding expertise scarcity limits producer scaling. Traditional milling knowledge concentrates among Kyoto-based craft processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Matcha Tea Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceremonial Grade, Culinary Grade, Premium Grade, Organic Grade Application: Beverages, Confectionery, Dietary Supplements, Cosmetics End User: Tea Houses, Food & Beverage Manufacturers, Wellness Centers, Specialty Retailers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Stores |
| Companies Covered | Ippodo, Mizuba Tea Co., Marukyu Koyamaen, Hawa Matcha, Nami Matcha, Hatoya, Horii Shichimeien, Daylight Matcha, Kanbayashi Shunsho, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Matcha Tea Market Strategic Shifts & Innovations
Processing technology and verification systems are compressing supply chain opacity, while regulatory frameworks on both sides of the Atlantic reshape formulation eligibility and import protocols.
Near-infrared spectroscopy is integrating into origin authentication workflows for shade-grown leaf verification. Third-party certification bodies deploy these systems to validate chlorophyll concentration and geographic source claims. The technology is integrating quality assurance timelines, reducing laboratory testing bottlenecks that previously delayed container release at port.
Japan's Ministry of Agriculture, Forestry and Fisheries tightened geographic indication enforcement for Uji and Nishio zone labeling in 2023. Export shipments now require documented prefecture-of-origin chain-of-custody records. North American specialty retailers and direct-to-consumer brands face heightened documentation requirements, redirecting procurement toward established Japanese trading houses with compliance infrastructure.
Clean-label preference compression is displacing conventional-grade matcha in premium wellness channels. Specialty retailers now demand organic certification, heavy metal testing, and radiation screening documentation. This behavioral shift concentrates procurement among Japanese producers with multi-certification capabilities, marginalizing smaller cultivators lacking compliance investment capacity.
Matcha Tea Market Segmentation
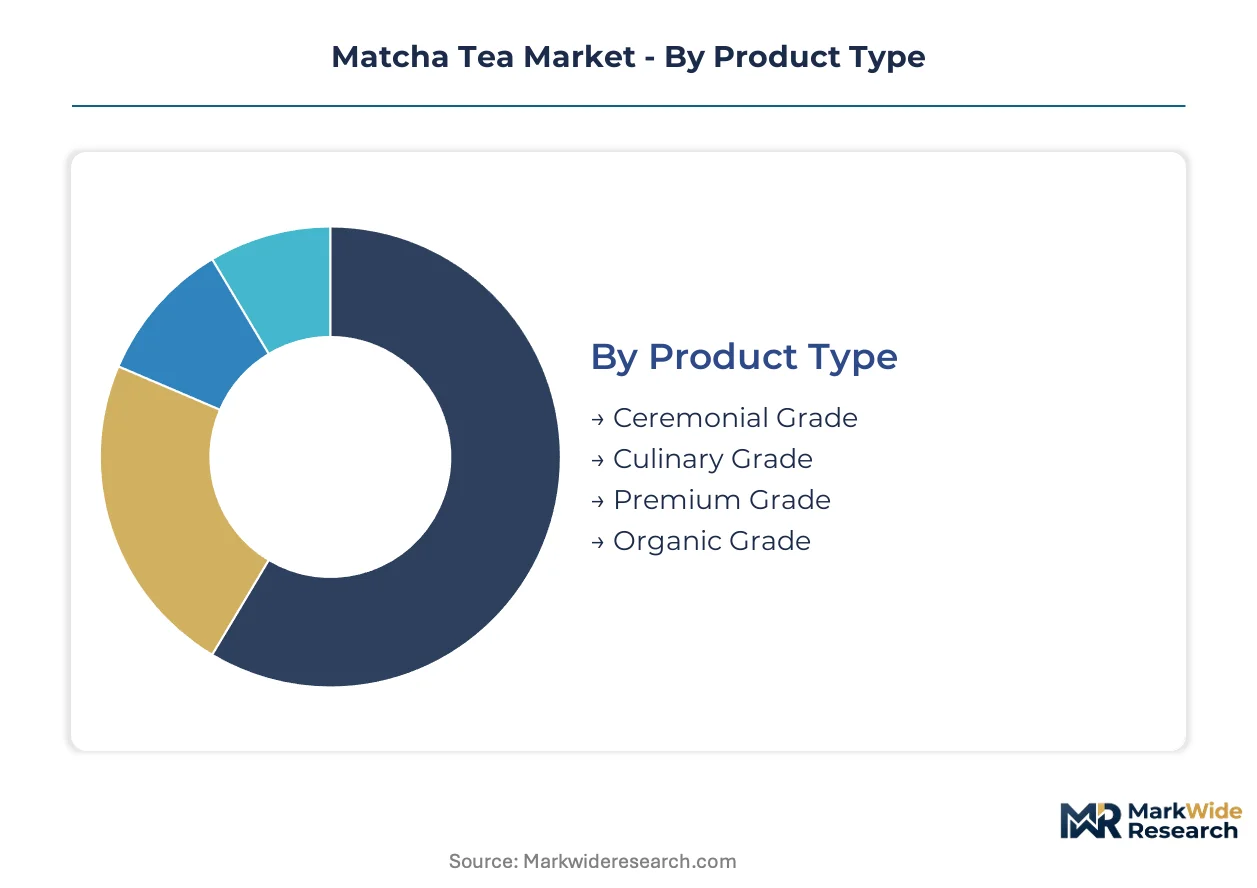
Grade-based segmentation governs procurement economics in matcha, with certification tiers commanding distinct margin pools and end-use specifications determining volume concentration across beverage, confectionery, and wellness channels.
Product Type:
Upgrade cycles in matcha procurement track evolving consumer sophistication, with buyers trading up from culinary blends toward certified ceremonial and organic grades as palates develop and wellness claims harden.
- Ceremonial Grade:First-flush shade-grown leaves stone-ground below 10 microns deliver maximum chlorophyll concentration and umami depth. Kyoto-based processors supply wellness centers and premium tea houses in the United States and Japan where ritual consumption commands price premiums.
- Organic Grade:USDA National Organic Program and EU Organic Regulation certification eliminates synthetic pesticide residues through verified cultivation protocols. Specialty retailers in Germany and France accelerate procurement as clean-label procurement standards displace conventional alternatives.
- Culinary Grade:Second and third harvest leaves with bolder astringency suit baking and beverage manufacturing applications.
- Premium Grade:Mid-tier positioning bridges ceremonial quality with culinary-scale pricing for specialty café formulations.
Culinary Grade sits at the top of the volume ranking, with Organic Grade climbing the fastest.
Application:
Application segmentation reveals how matcha migrates from traditional consumption into functional formulation, with beverage manufacturers and confectionery developers pulling procurement toward specific particle size and solubility specifications.
- Beverages:Ready-to-drink formulations and specialty café lattes require sub-15 micron particle suspension stability. Food and beverage manufacturers in the United States concentrate procurement of ceremonial-grade powder for functional drink lines targeting wellness center distribution.
- Confectionery:Baking, chocolate, and dessert applications leverage culinary-grade color stability and cost efficiency. Japanese and French patisserie suppliers drive volume through matcha-infused ganache and mochi product lines.
- Dietary Supplements:Capsule and powder formulations face EFSA novel food assessment thresholds in Europe and FDA food additive classifications in the United States.
- Cosmetics:Topical antioxidant applications in Korean and Japanese skincare lines utilize culinary-grade powder for mask and serum formulations.
Beverages holds the largest volume position, though Confectionery is gaining share fastest as bakery chains expand matcha SKUs.
End User:
End-user concentration shows wellness infrastructure and specialty retail displacing traditional tea house channels, with procurement authority shifting toward institutional buyers with certification and traceability requirements.
- Food & Beverage Manufacturers:Industrial-scale procurement of culinary-grade matcha for RTD production and confectionery ingredient supply. North American contract manufacturers demand documented prefecture-of-origin chain-of-custody records under tightened Japanese geographic indication enforcement.
- Wellness Centers:Functional beverage bars and holistic health clinics source ceremonial and organic grades for antioxidant-focused consumption. United States coastal metropolitan markets concentrate demand for traceable Uji and Nishio zone product.
- Specialty Retailers:Direct-to-consumer and boutique channels emphasize origin storytelling and organic certification.
- Tea Houses:Traditional consumption venues in Kyoto and Tokyo sustain ceremonial-grade ritual preparation.
Food & Beverage Manufacturers dominate procurement volume, while Wellness Centers are expanding most quickly.
Distribution Channel:
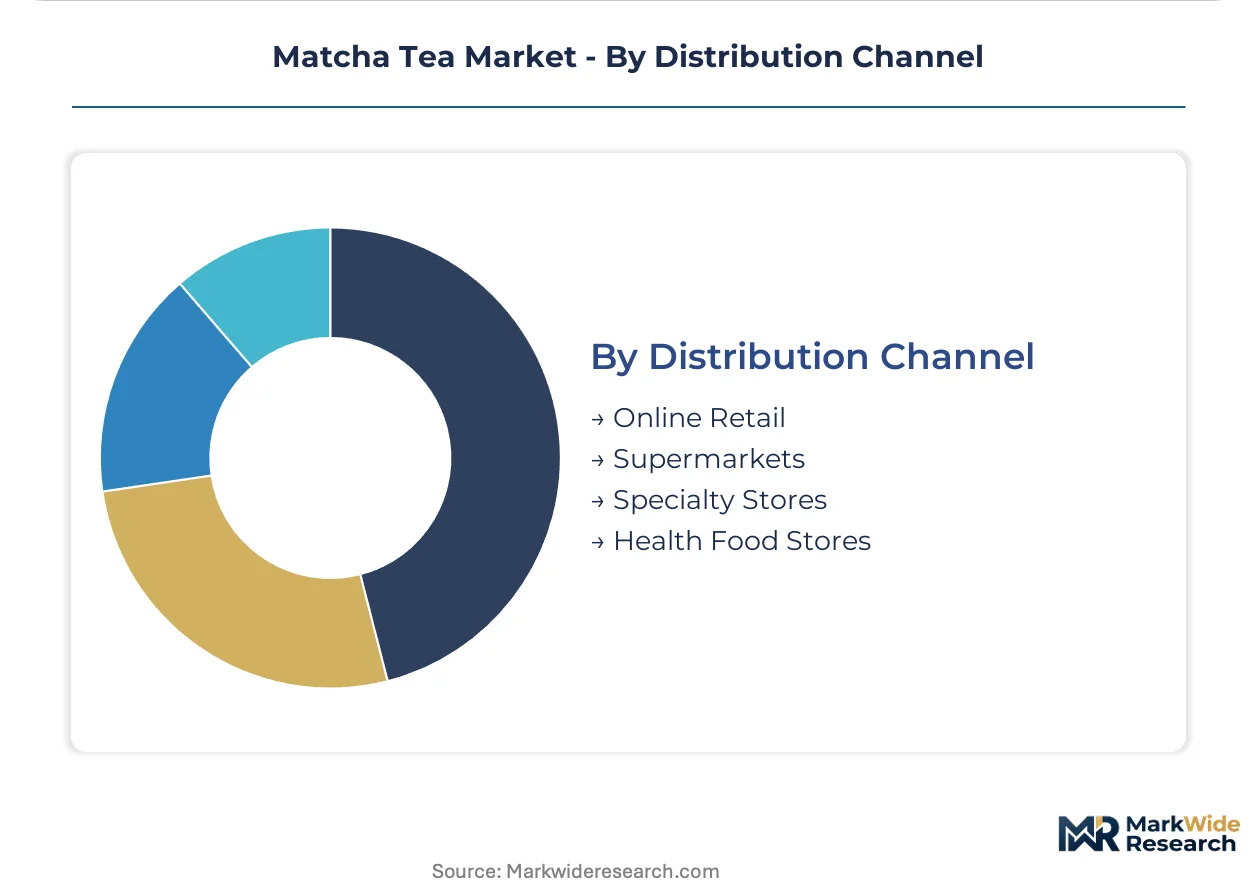
Channel structure compresses supply chain opacity, with digital platforms reshaping price discovery and origin verification expectations while health food stores concentrate certified-grade assortment.
- Online Retail:Direct-to-consumer platforms enable Japanese producers to bypass import distributors and serve United States and European buyers with blockchain-verified origin documentation. Mizuba Tea Co. and comparable specialty brands anchor this channel with organic-certified Uji-sourced lines.
- Specialty Stores:Curated assortments emphasize ceremonial-grade inventory and brewing equipment. Paris, London, and New York boutiques concentrate premium positioning with Kyoto processor relationships.
- Health Food Stores:United States and German chains demand organic certification, heavy metal testing, and radiation screening documentation.
- Supermarkets:Mass retail carries culinary-grade culinary and premium tier SKUs for home baking and casual preparation.
Supermarkets maintain the highest volume throughput, yet Online Retail is climbing the fastest as traceability technology enables premium direct sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Japan's strict geographic indication enforcement and the USDA National Organic Program certification gap is redirecting procurement flows toward North American and European markets with cleaner compliance pathways.
United States
Wellness centers in Los Angeles and New York Metro drive ceremonial-grade procurement for functional beverage bars. FDA food additive classifications govern matcha inclusion thresholds in dietary supplements. Pacific Northwest direct-to-consumer brands leverage blockchain traceability to bypass traditional import distributors.
Japan
Kyoto-based stone-grinding processors supply domestic tea houses and export markets with limited first-flush volumes. The Ministry of Agriculture, Forestry and Fisheries enforces tightened geographic indication protocols for Uji and Nishio zone labeling. Kagoshima prefecture concentrates shade-grown cultivation despite climate compression risks.
Germany
Specialty retailers in Berlin and Munich accelerate organic-grade sourcing under EU Organic Regulation standards. EFSA novel food assessments create formulation complexity for fortified beverage developers. Clean-label procurement standards displace conventional matcha across wellness channels.
France
Paris patisserie suppliers integrate culinary-grade matcha into ganache and mochi product lines. REACH compliance requirements intersect with food contact material regulations for packaging. Île-de-France boutique channels emphasize origin storytelling with Kyoto processor relationships.
United Kingdom
London specialty cafés bridge ceremonial quality with culinary-scale pricing for matcha latte formulations. The Food Standards Agency coordinates with EFSA on novel food assessments for supplement applications. Southeast England health food chains demand heavy metal testing and radiation screening documentation.
Matcha Tea Market Key Industry Players
Portfolio diversification dominates the current landscape as processors extend from traditional tea house supply into ready-to-drink manufacturing and direct-to-consumer channels. The vendor base clusters around three strategic archetypes: heritage Kyoto millers with centuries-old stone-grinding expertise, organic-certified specialists with multi-certification compliance infrastructure, and bulk culinary-grade suppliers serving food and beverage manufacturers. Geographic indication enforcement and blockchain traceability investment represent the two dominant competitive moves separating premium positioning from commodity alternatives.
Within the heritage milling tier, Ippodo and Marukyu Koyamaen exemplify contrasting scale strategies. Ippodo occupies a position anchored in Kyoto-based ceremonial-grade supply with limited volume expansion. Marukyu Koyamaen represents the bulk contract specialist archetype, serving North American and European food and beverage manufacturers with documented prefecture-of-origin chain-of-custody records. Mizuba Tea Co. sits within the organic-certified direct-to-consumer segment, leveraging Uji-sourced product lines to capture transparency-demanding buyers bypassing traditional import distributors.
| Leading Market Players |
|---|
| Ippodo |
| Mizuba Tea Co. |
| Marukyu Koyamaen |
| Hawa Matcha |
| Nami Matcha |
| Hatoya |
| Horii Shichimeien |
| Daylight Matcha |
| Kanbayashi Shunsho |
| Others |
Cost & Logistics Intelligence
Wellness center procurement concentration in Los Angeles and New York Metro anchors premium ceremonial-grade pricing power, with direct-to-consumer brands compressing distributor margins through blockchain-verified origin documentation that bypasses traditional import channels.
Pricing Analysis
Distributor margin layers in ceremonial-grade supply face compression as Mizuba Tea Co. and comparable direct-to-consumer brands capture price premiums through online retail platforms. Three-tier pricing structure across ceremonial, organic, and culinary certification levels separates first-flush stone-ground powder from second-harvest culinary supply. Pricing pressure stems from Kyoto-based processors facing capacity constraints during peak harvest windows. Food and beverage manufacturers exhibit highest price sensitivity due to volume-scale procurement, while specialty retailers defend premium positioning through origin storytelling.
Supply Chain Analysis
Dual-sourcing requirements from North American wellness centers and European specialty retailers mandate documented prefecture-of-origin chain-of-custody records alongside USDA National Organic Program or EU Organic Regulation certification. Geographic supply concentrates in Japan's Uji, Nishio, and Kagoshima prefectures, with limited first-flush volumes from Kyoto-based stone-grinding processors. Raw material dependencies rest on shade-grown Camellia sinensis leaf, granite millstone availability, and organic cultivation substrate. Supply chain risk centers on weather disruption compressing viable twenty-to-thirty day pre-harvest shading periods. Distribution runs through Japanese trading houses with compliance infrastructure, direct-to-consumer platforms, and specialty retail boutiques.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The matcha market reads as a late-cycle quality story as clean-label procurement standards displace conventional-grade supply across wellness channels and specialty retail.
For Market Incumbents: Anchor premium positioning through blockchain traceability investment defending against adulteration risks in ceremonial-grade segments. Deepen backward integration into shade-grown cultivation in Kagoshima prefecture to secure first-flush volumes amid climate compression threats. Fortify multi-certification capabilities spanning USDA National Organic Program, EU Organic Regulation, and Japan's geographic indication protocols to marginalize smaller cultivators lacking compliance investment capacity. For New Entrants and Emerging Players: Capture white-space opportunity in organic-certified direct-to-consumer channels where transparency-demanding buyers bypass traditional import distributors. Target European specialty retailers in Germany and France accelerating procurement under clean-label procurement standards. Deploy near-infrared spectroscopy authentication workflows as go-to-market differentiation validating chlorophyll concentration and geographic source claims. For Investors and Strategic Acquirers: Food and beverage manufacturers with RTD formulation capabilities are the most active acquirer in this space, seeking backward integration into traceable ceremonial-grade supply. Long-term viability hinges on securing Kyoto-based stone-grinding expertise scarcity and multi-certification infrastructure. Watch for EFSA novel food assessment threshold relaxation as inflection indicator unlocking dietary supplement formulation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Deployment | Distributed ledger protocols defend premium positioning against adulteration risks in ceremonial-grade segments. |
| Direct-to-Consumer Channel Expansion | Online retail platforms enable Japanese producers to bypass import distributors and serve transparency-demanding buyers. |
| Organic Certification Investment | USDA National Organic Program and EU Organic Regulation compliance captures clean-label procurement acceleration. |
| Confectionery Application Development | Culinary-grade penetration into baking and dessert manufacturing diversifies revenue concentration from beverage categories. |
| Geographic Indication Compliance Infrastructure | Documented prefecture-of-origin chain-of-custody records satisfy tightened Japanese Ministry of Agriculture enforcement. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Kyoto-based stone-grinding processors, North American wellness center procurement directors, European specialty retail buyers, Japanese agricultural ministry officials, and food and beverage manufacturer R&D leads with secondary validation from FDA food additive classifications, EFSA novel food assessments, Japan's Ministry of Agriculture geographic indication protocols, USDA National Organic Program standards, and EU Organic Regulation frameworks. Bottom-up volume modeling and top-down value triangulation cross-validated segment outputs.
Segment-weighting across grade tier, application channel, end-user archetype, and distribution format governed the analytical framework across the projection horizon. CAGRs derived from historical shipment trajectories, procurement pattern shifts, and certification adoption curves. Forecast inputs incorporated shade-grown cultivation yield volatility, stone-grinding capacity constraints, and regulatory threshold evolution.
Climate disruption in Kagoshima and Shizuoka prefectures, EFSA novel food assessment threshold modification, and blockchain traceability technology cost curves are the dominant revision risks. Deviation in weather patterns compressing viable pre-harvest shading periods would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Kombucha Tea Market
Tea
North America Ready-To-Drink Tea Market
Tea
Nitro Tea Market
Tea
Mate Tea Market
Tea
Fermented Tea Market
Tea
Detox Tea Market
Tea
Europe Ready-To-Drink Tea Market
Tea
Global Catechin Market
Tea
Europe Tea Market
Tea
Global Tea Market
Tea
Instant Tea Market
Tea
Global Ready-To-Drink Green Tea Market
Tea
Africa Tea Market
Tea
White Tea Extract Market
Tea
Bottled Tea Market
Tea
Herbal Tea Market