
 Europe Ready-To-Drink Tea Market | 2026-2036
Europe Ready-To-Drink Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ready-To-Drink Tea Market Foresight
Subscription-based replenishment models for home-delivered RTD tea assortments is recalibrating how brands secure recurring revenue and consumer loyalty. Unilever plc leverages its Lipton heritage and direct-to-consumer infrastructure to sustain repeat purchase cycles across Northern Europe. Nestlé SA anchors its portfolio through specialized wellness-positioned lines that compete in the functional beverage space. Danone S.A. differentiates via chilled distribution networks that dominate premium channels in France and Benelux markets.
Europe ready-to-drink tea comprises brewed, packaged tea beverages preserved through hot-fill processing or aseptic cold filling, typically formulated with pH levels between 2.5 and 4.2 for shelf stability and consumer safety. These products serve commercial and retail channels requiring portable, consistent-quality alternatives to freshly prepared tea. Green tea and herbal tea segments capture expanding margin pools as consumers prioritize functional ingredients and reduced caffeine formulations. Bottle packaging leads volume throughput while carton formats gain traction in sustainability-focused retail assortments across German and Scandinavian supermarkets.
EU F-Gas Regulation and national packaging directives in Germany and France mandate reduced carbon footprints in refrigeration and recyclable material thresholds, reshaping manufacturing investments and product specifications. EFSA nutrition and health claims oversight constrains functional positioning, requiring substantiated ingredient narratives from market participants. Stakeholders must monitor evolving Extended Producer Responsibility schemes and carbon border adjustments that will determine competitive access and cost structures across European distribution networks.
Market Dynamics
The EU Single-Use Plastics Directive is compressing packaging formats toward recyclable cartons and refillable bottle systems, forcing capital reallocation across chilled and ambient distribution networks.
Growth Catalysts
- EFSA substantiation pathways:Functional ingredient claims for L-theanine and polyphenol content now clear regulatory review, unlocking premium positioning for wellness-oriented formulations.
- Urban convenience channel expansion:Metro rail station kiosks and airport retail in Germany and the United Kingdom are dedicating refrigerated space to functional RTD tea assortments.
- Refillable bottle infrastructure:Reverse vending systems in Scandinavian markets are normalizing deposit-return loops that reduce per-unit packaging costs.
Market Restraints
- Aluminum and rPET input volatility:Can and bottle raw material costs fluctuate with energy pricing, compressing margin stability for aseptic filling operations.
- Cold chain concentration in Benelux:Chilled distribution hubs cluster around Rotterdam and Antwerp, creating single-point vulnerability for premium product flows.
- EFSA health claim substantiation timelines:Novel functional ingredient approvals require 18-24 month safety dossier reviews, delaying product launches.
Strategic Opportunities
- Subscription replenishment models:Direct-to-consumer platforms in the United Kingdom are capturing recurring revenue through personalized flavor curation and flexible delivery cadences.
- Extended Producer Responsibility schemes:German packaging fee structures reward lightweight carton adoption, tilting investment toward hot-fill carton lines.
- Functional ingredient convergence:Adaptogenic botanicals combined with fermented tea bases are opening positioning whitespace between beverage and supplement categories.
Industry Challenges
- Aseptic filling technician scarcity:Specialized cold-chain equipment maintenance requires certified personnel that Northern European markets struggle to source.
- Legacy ERP integration with traceability systems:Batch-level ingredient tracking for EFSA compliance demands middleware investment that mid-sized bottlers delay.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ready-To-Drink Tea Market |
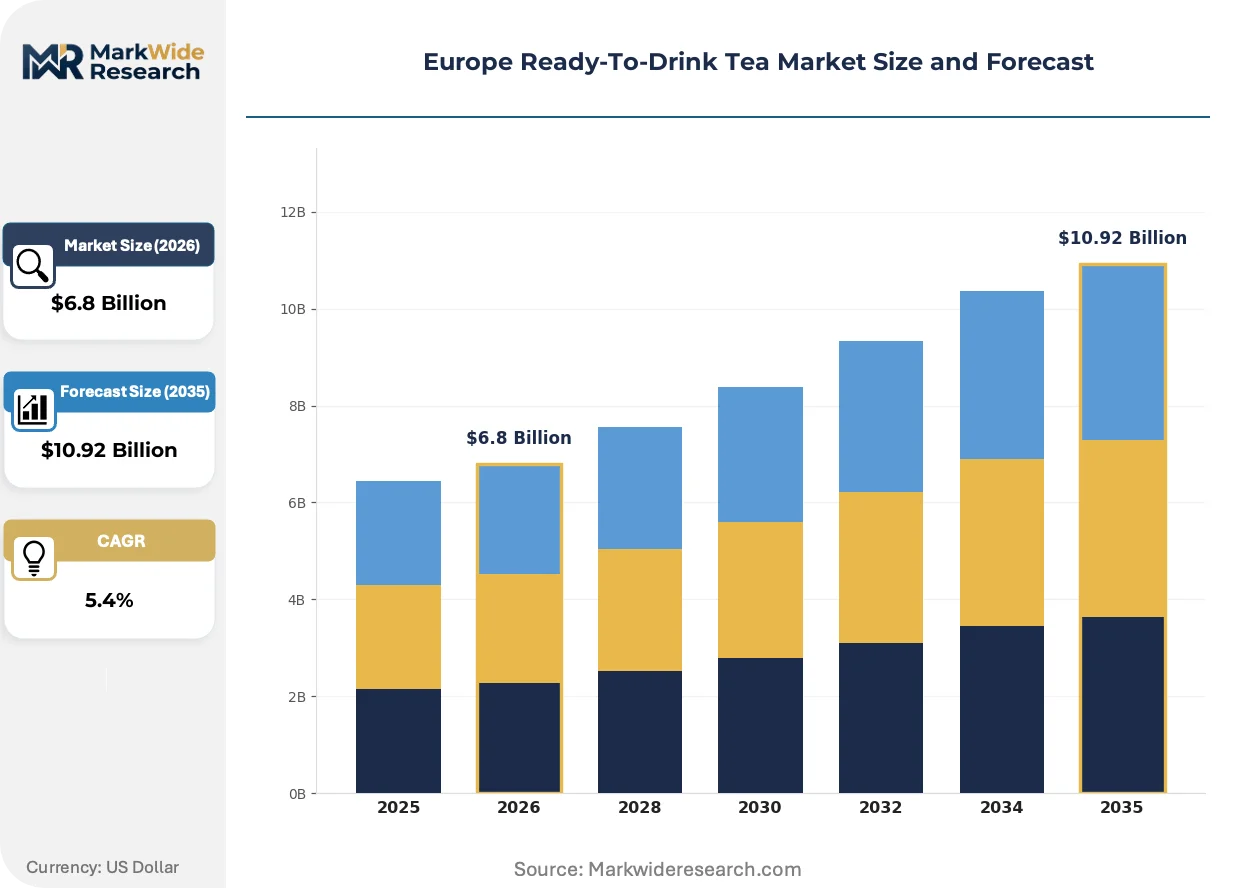
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Tea, Green Tea, Herbal Tea, Flavored Tea Packaging Type: Bottle, Can, Carton, Sachet Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores End User: Retail Consumers, Food Service, Cafes, Hotels |
| Companies Covered | Unilever plc, The Coca-Cola Company, Nestlé SA, Suntory Beverage & Food Ltd, PepsiCo, Inc., Arizona Beverage Company, Danone S.A., Hermann Pfanner Getränke GmbH, Rauch Fruchtsäfte GmbH & Co OG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ready-To-Drink Tea Market Shifts & Advancements
Automation and regulatory compliance are converging to reshape formulation, filling, and fulfillment architectures across European RTD tea manufacturing.
High-speed aseptic cold filling lines with integrated clean-in-place systems are automating changeover sequences between SKUs. German and Dutch bottling facilities deploy these systems to compress downtime from flavor rotation. The technology is automating labor out of high-mix production environments while tightening microbial safety margins.
EU F-Gas Regulation phase-down schedules are accelerating hydrocarbon and CO2 refrigeration adoption. Chilled RTD tea warehousing in France and Italy now faces retrofit deadlines that favor centralized distribution over dispersed cold storage. Premium green tea variants with temperature-sensitive catechin stability are most exposed to this infrastructure shift.
Urban consumers in London, Berlin, and Amsterdam are consolidating beverage purchases into weekly subscription boxes. Direct-to-consumer platforms displace impulse buys at convenience stores with curated assortments delivered to residential addresses. This pattern concentrates most visibly in the United Kingdom, where postal density and payment infrastructure support recurring delivery models.
Europe Ready-To-Drink Tea Market Segmentation
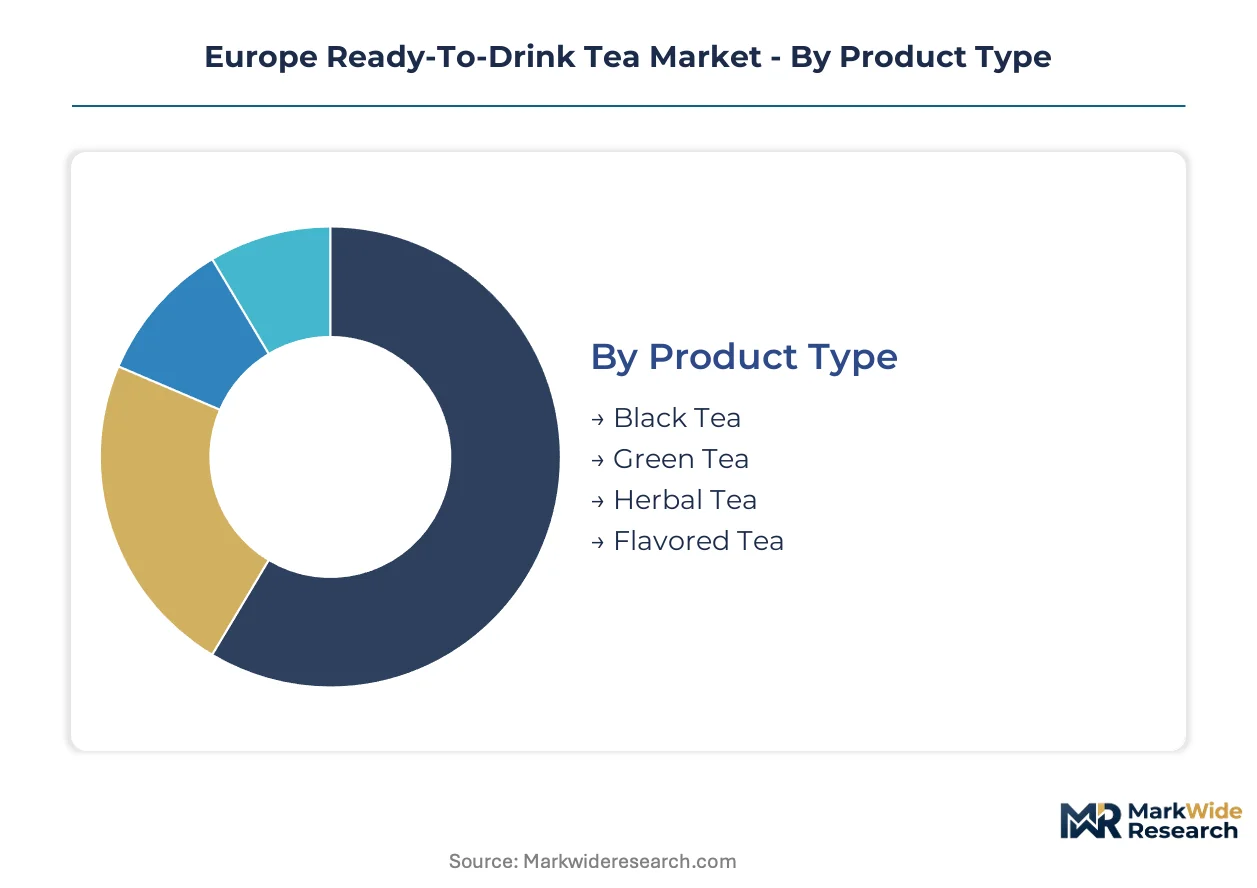
RTD tea segmentation reveals how formulation choices, packaging economics, and channel access determine margin capture across European markets. Volume leaders compete on shelf efficiency while premium tiers monetize wellness positioning and sustainability credentials.
Product Type:
Volume concentration favors mass-market black tea formulations, yet premium pricing power concentrates in functional green and herbal variants with substantiated health claims.
- Black Tea:Traditional fermented leaf formulations dominate ambient shelf-stable production with standardized pH stabilization between 2.8 and 3.5. German and British retail consumers sustain baseline demand through familiar flavor profiles and price accessibility in supermarket channels.
- Green Tea:Unoxidized leaf processing preserves catechin content for EFSA-aligned functional positioning. Urban convenience channels in London and Amsterdam dedicate refrigerated space to these variants as consumers prioritize polyphenol intake and reduced caffeine alternatives.
- Herbal Tea:Rooibos, chamomile, and hibiscus infusions target caffeine-free occasions. French and Benelux markets show concentration in pharmacy and wellness retail.
- Flavored Tea:Fruit and botanical additions mask bitterness in low-sugar formulations. Innovation pipelines favor Mediterranean citrus and Nordic berry profiles.
Mature deployment sits with Black Tea. Newer deployment is concentrated in Green Tea.
Packaging Type:
Cost tier separation runs from premium chilled bottles through economy ambient cartons, with material regulations reshaping investment priorities.
- Bottle:PET and rPET formats dominate chilled distribution with transparent branding surfaces and resealability. Rotterdam cold-chain hubs process the majority of premium green tea volumes for Benelux and French retail.
- Carton:Aseptic hot-fill cartons reduce per-unit material costs and align with German Extended Producer Responsibility fee structures favoring lightweight recyclable formats. Scandinavian supermarket assortments show fastest adoption.
- Can:Aluminum formats suit ambient distribution and outdoor consumption occasions. Input cost volatility constrains margin stability.
- Sachet:Single-serve powder and liquid concentrates target food service portion control. Hotel breakfast operations in Spain and Italy represent core demand.
Margin compression is deepest in Can. Margin expansion is concentrated in Carton.
Distribution Channel:
Customer type separation distinguishes planned pantry stocking from impulse and experiential purchase occasions.
- Supermarkets:Multi-SKU planogram placement drives volume throughput with promotional dependency. German chains enforce sustainability scoring that favors carton and refillable formats.
- Convenience Stores:Grab-and-go chilled placement captures commuter traffic in Berlin U-Bahn stations and London rail terminals. Refrigerated space constraints limit assortment breadth.
- Online Retail:Subscription replenishment models in the United Kingdom consolidate weekly deliveries with personalized curation. Postal density supports recurring revenue capture.
- Specialty Stores:Premium organic and biodynamic assortments command shelf space in Parisian and Amsterdam wellness retailers. Staff consultation drives trial conversion.
Scale concentration sits with Supermarkets. Growth velocity is highest in Online Retail.
End User:
Application separation distinguishes at-home consumption rituals from away-from-home refreshment and hospitality service.
- Retail Consumers:Home pantry stocking and personal consumption occasions dominate volume. Health-conscious demographics in Germany and Britain drive functional formulation demand.
- Food Service:Casual dining chains and contract caterers specify bulk formats with consistent quality and cost predictability. EFSA traceability requirements constrain supplier selection.
- Cafes:Independent coffee shops and tea houses offer curated RTD alternatives to brewed service. Chilled premium variants support margin recovery in high-rent urban locations.
- Hotels:Minibar and breakfast buffet placement demands portion-controlled formats with extended ambient stability. Mediterranean resort properties favor local herbal infusions.
Volume maturity sits with Retail Consumers. Penetration expansion is concentrated in Cafes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam-Antwerp corridor anchors European RTD tea distribution through integrated cold-chain hubs serving premium chilled variants across Benelux and Northern France.
Germany
Health-conscious consumers in Berlin and Hamburg expand purchases of low-sugar functional green teas through urban convenience channels. Extended Producer Responsibility fee structures under national packaging directives reward lightweight carton adoption. Bavarian bottling facilities deploy hot-fill aseptic lines to align with sustainability scoring enforced by major retail chains.
United Kingdom
London postal density supports subscription replenishment models displacing traditional convenience store purchases. EFSA nutrition and health claims oversight constrains functional positioning requiring substantiated ingredient narratives. Midlands distribution centers process curated assortments for recurring home delivery across Greater London and Southeast England.
France
Parisian wellness retailers command premium shelf space for organic herbal variants targeting pharmacy and specialty channels. EU F-Gas Regulation phase-down schedules accelerate hydrocarbon refrigeration adoption in chilled warehousing. Île-de-France logistics clusters face retrofit deadlines favoring centralized distribution over dispersed cold storage.
Netherlands
Amsterdam metro rail kiosks dedicate refrigerated space to functional RTD tea assortments capturing commuter traffic. Reverse vending systems normalize deposit-return loops reducing per-unit packaging costs in Scandinavian-influenced sustainability frameworks. Rotterdam port infrastructure processes majority of premium green tea volumes for re-export across continental markets.
Italy
Mediterranean resort properties in Tuscany and Campania favor local herbal infusions for hotel minibar and breakfast buffet placement. EFSA traceability requirements constrain supplier selection for food service and hospitality channels. Northern Italian bottling corridors near Milan leverage aseptic filling expertise for ambient-stable portion-controlled formats.
Europe Ready-To-Drink Tea Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation, filling, and fulfillment architectures. The market structure consolidates around multinational beverage conglomerates with integrated cold-chain assets and specialized regional bottlers with flexible aseptic capabilities. Three archetypes dominate: heritage tea brands leveraging direct-to-consumer infrastructure, diversified nutrition companies anchoring wellness-positioned lines, and chilled distribution specialists commanding premium channels. Competitive moves concentrate on subscription platform acquisition and hot-fill carton line investment to capture Extended Producer Responsibility advantages.
Within the heritage-brand tier, Unilever plc and Nestlé SA exemplify multinational scale with recurring revenue infrastructure across Northern European markets. Danone S.A. occupies a distinct position through chilled distribution dominance in French and Benelux premium channels. Among diversified beverage conglomerates, The Coca-Cola Company and PepsiCo, Inc. represent scale-driven portfolios with ambient distribution reach. Suntory Beverage & Food Ltd anchors Japanese-origin functional positioning. Regional specialists Hermann Pfanner Getränke GmbH and Rauch Fruchtsäfte GmbH & Co OG exemplify Central European bottling expertise with flexible aseptic capabilities.
| Leading Market Players |
|---|
| Unilever plc |
| The Coca-Cola Company |
| Nestlé SA |
| Suntory Beverage & Food Ltd |
| PepsiCo, Inc. |
| Arizona Beverage Company |
| Danone S.A. |
| Hermann Pfanner Getränke GmbH |
| Rauch Fruchtsäfte GmbH & Co OG |
| Others |
Supply & Pricing Matrix
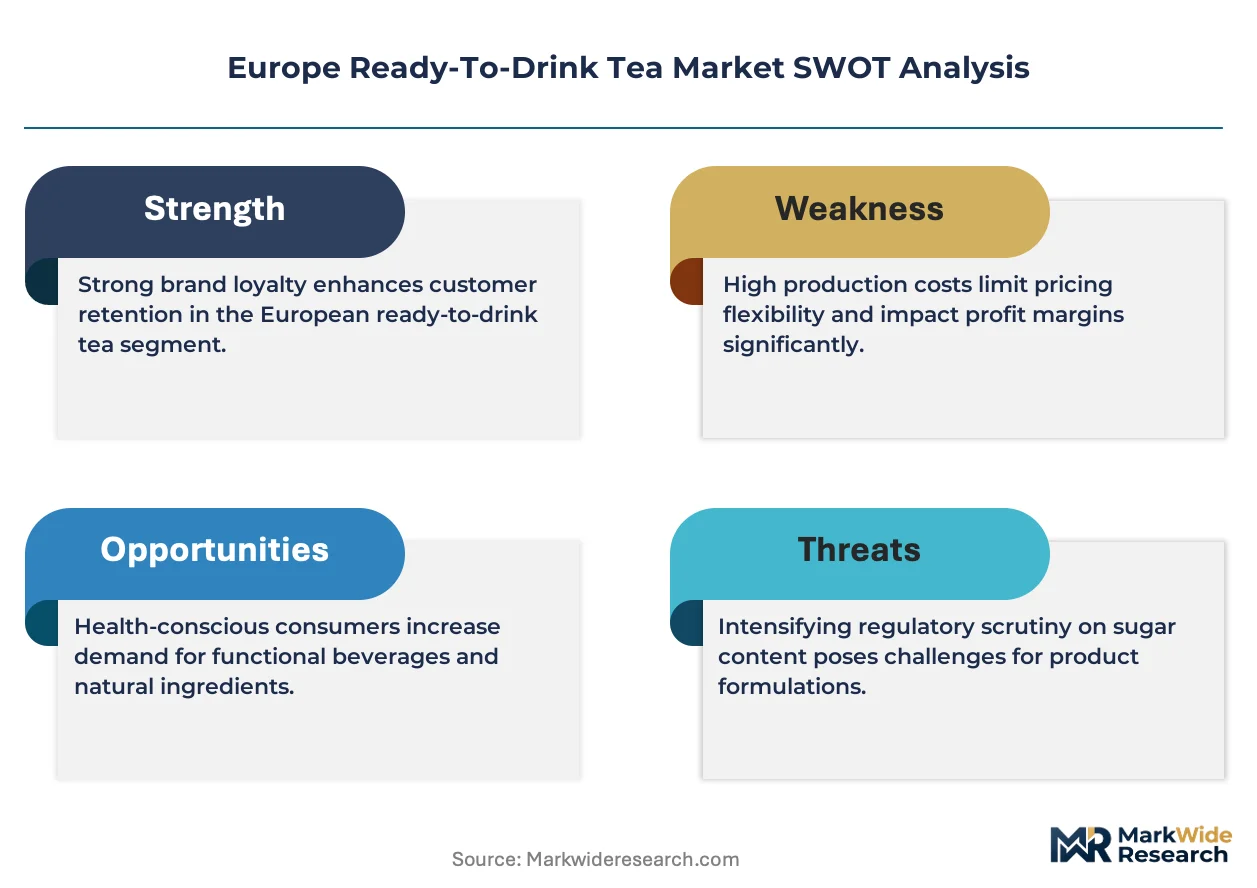
German supermarket sustainability scoring and French Extended Producer Responsibility fee structures are compressing packaging choices toward lightweight cartons and refillable formats, forcing bottlers to absorb retrofit costs or surrender shelf access. This procurement pressure concentrates margin leverage with retailers while fragmenting supplier pricing power across chilled and ambient distribution tiers.
Pricing Analysis
Margin tightening in premium chilled bottles reflects aluminum and rPET input volatility tied to energy pricing swings. Three-tier pricing structure across premium functional green teas, standard black tea formulations, and economy private-label assortments separates EFSA-substantiated wellness variants from commodity blends. Cost-down pressure on mid-tier SKUs accelerates because German retail chains enforce sustainability scoring that penalizes heavy packaging. Food service buyers exhibit highest price sensitivity due to bulk contract structures, while specialty wellness retailers absorb premiums for traceable botanical sourcing.
Supply Chain Analysis
EU Single-Use Plastics Directive implementation and German national packaging mandates are reshaping material sourcing toward domestic carton converters and Benelux-based aseptic filling equipment. Supply concentration rests in Germany, Netherlands, and France for hot-fill processing infrastructure, with green tea leaf imports drawing from China and Japan for catechin-standardized cultivars. Single-source vulnerability concentrates around Rotterdam-Antwerp cold-chain hubs for premium chilled distribution. Distribution runs through supermarket centralized procurement in Germany, subscription platforms in the United Kingdom, and convenience rail kiosks in Netherlands urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive supply of temperature-sensitive catechin extracts and proprietary subscription fulfillment infrastructure to lock in recurring revenue.
For Market Incumbents: Anticipate margin compression from private-label entrants by securing exclusive organic botanical contracts with Mediterranean and Nordic growers. Extend backward integration into aseptic carton manufacturing to capture German Extended Producer Responsibility fee advantages. Channel control through direct-to-consumer platform acquisition offers defensive positioning against subscription-native challengers. For New Entrants and Emerging Players: Launch via United Kingdom subscription replenishment models where postal density and payment infrastructure support recurring revenue capture without chilled distribution assets. Target pharmacy and wellness retail channels in France and Benelux where staff consultation drives trial conversion and price elasticity remains lowest. White-space exists in adaptogenic botanical blends positioned between beverage and supplement categories with EFSA-aligned functional claims. For Investors and Strategic Acquirers: The window for entry favors specialized regional bottlers with flexible aseptic capabilities and established wellness-brand portfolios. Long-term viability hinges on regulatory navigation capacity across EFSA substantiation pathways and EU packaging directive compliance. Watch for inflection signals in Extended Producer Responsibility fee structure revisions that would accelerate carton format adoption and consolidate manufacturing scale advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Fill Carton Line Investment | German Extended Producer Responsibility fee structures reward lightweight recyclable formats, tilting capital allocation. |
| Direct-to-Consumer Platform Acquisition | United Kingdom postal density supports subscription replenishment models displacing traditional convenience store purchases. |
| EFSA-Aligned Functional Substantiation | L-theanine and polyphenol claim approvals unlock premium positioning for wellness-oriented green tea formulations. |
| Reverse Vending Infrastructure Partnership | Scandinavian deposit-return loops reduce per-unit packaging costs and normalize sustainable consumption patterns. |
| Organic Botanical Supply Contracting | Mediterranean citrus and Nordic berry sourcing secures traceable ingredient narratives for pharmacy channel placement. |
Research Methodology
Document review covered EFSA nutrition and health claims registers, EU F-Gas Regulation implementation schedules, and national packaging directive filings, complemented by interviews with bottling plant managers, supermarket category buyers, cold-chain logistics operators, and wellness retail procurement leads. Secondary validation drew from customs trade data, Nielsen retail audit figures, and SEC filings of multinational beverage conglomerates. Bottom-up volume modeling triangulated against top-down category spend estimates across the analysis window.
Output generation employed segmented projection frameworks spanning product type, packaging format, distribution channel, and end-user application dimensions over the projection horizon. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points. Forecast inputs incorporated EFSA substantiation timeline probabilities, Extended Producer Responsibility fee schedule revisions, and cold-chain infrastructure retrofit completion rates.
The model assumes a particular technology adoption path for hydrocarbon and CO2 refrigeration systems; alternative pathways for synthetic refrigerant preservation would alter the outlook for premium chilled green tea shelf stability. Forecasts reflect assumptions around EFSA claim approval velocities and EU packaging directive enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Bottled Milk Tea Market
Tea
High Protein Tea Market
Tea
US RTD Organic Tea Market
Tea
Green Tea Extract Market
Tea
Matcha Market
Tea
Tea Concentrate Market
Tea
Asia-Pacific Tea Market
Tea
Green Tea Leaves Market
Tea
RTD Tea Market
Tea
Global Tea Bag Market
Tea
Asia-Pacific Organic Tea Market
Tea
Europe Green Tea Market
Tea
Tea Essence Market
Tea
Global Tea Market
Tea
Asia-Pacific Ready to Drink Tea Market
Tea
US Ready to Drink Tea Market