
 Asia-Pacific Green Tea Market | 2026-2036
Asia-Pacific Green Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Green Tea Market Analytics
Specialty retail and direct-to-consumer channels are rewriting how premium green tea reaches buyers across Asia-Pacific. ITO EN leverages its vertical integration from Japanese tea gardens to bottled distribution, sustaining quality control through the entire value chain. Tata Consumer Products Limited anchors its position through deep sourcing relationships with Assam and Darjeeling estates, while Unilever PLC competes via mass-market bagged formats stocked in supermarkets from Mumbai to Manila.
Asia-Pacific green tea comprises Camellia sinensis leaves processed through steaming or pan-firing to preserve polyphenol content, primarily catechins such as epigallocatechin gallate, with primary applications spanning functional beverages, nutraceuticals, and traditional consumption. Matcha and extracts command the highest margin pools due to concentrated bioactive content and premium positioning in wellness and cosmetics applications. Bagged formats occupy the volume leadership position across household and food service channels, though loose-leaf grades retain stronger pricing power in ceremonial and gift segments.
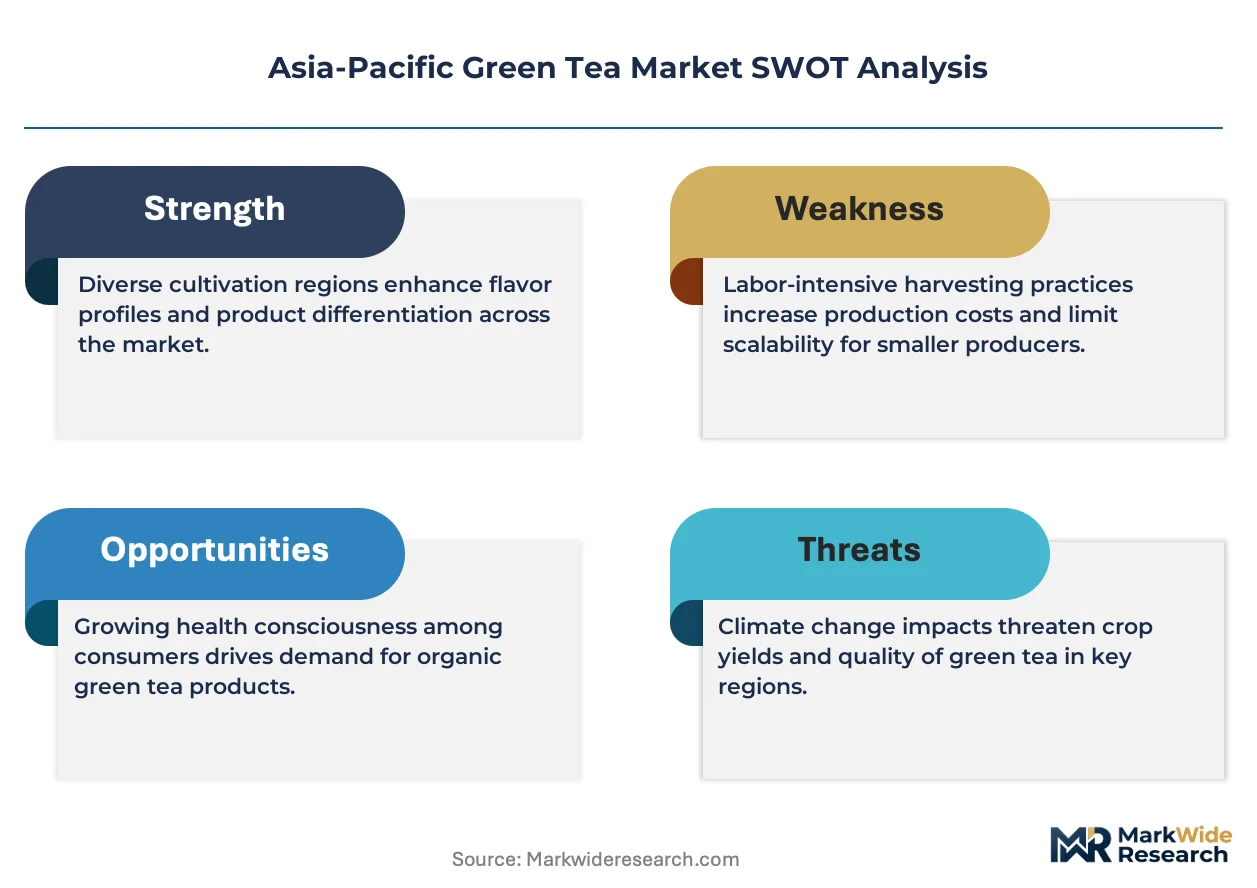
Japan's Ministry of Agriculture, Forestry and Fisheries enforces strict agricultural chemical residue limits that shape cultivation practices and export eligibility for regional producers. China's SAMR and NMPA oversee food safety certifications and health claim validations that determine market access for functional green tea products. India's FSSAI and Tea Board regulations govern pesticide thresholds and geographical indication protections that influence sourcing decisions. Stakeholders must monitor evolving phytosanitary standards and traceability mandates as certification requirements fragment across national boundaries.
Market Dynamics
China's GB 2763 pesticide residue standards are forcing cultivation consolidation across Zhejiang and Fujian provinces, squeezing smallholders while favoring certified organic estates that can absorb compliance costs and maintain export eligibility to Japan and South Korea.
Growth Catalysts
- Functional beverage expansion:Energy and wellness drink manufacturers in Japan and South Korea are expanding green tea extract procurement for polyphenol-enriched formulations targeting metabolic health positioning.
- Japan's agricultural chemical regulations:Strict residue limits enforced by the Ministry of Agriculture, Forestry and Fisheries are creating premium tier separation that rewards compliant exporters with price premiums in ceremonial and gift segments.
- Organic cultivation clusters:Zhejiang and Fujian provinces are consolidating certified organic production zones that supply premium loose-leaf grades to domestic urban consumers and export buyers seeking traceability guarantees.
Market Restraints
- Input cost volatility:Fertilizer and organic certification expenses have risen sharply, compressing margins for smallholder farmers unable to achieve economies of scale in cultivation and processing.
- Supply concentration risk:Premium matcha and extract supply concentrates in Uji and Nishio regions of Japan, creating vulnerability to climate events and single-origin dependency for high-margin product lines.
- Regulatory friction:Divergent phytosanitary standards between China's SAMR and Japan's MAFF create dual compliance burdens that fragment export pathways and extend certification timelines.
Strategic Opportunities
- Underpenetrated Vietnam:Northern Vietnamese highland provinces offer untapped organic cultivation potential with favorable agro-climatic conditions and emerging FSSAI-recognized export infrastructure for Indian market access.
- Cosmetics application expansion:Epigallocatechin gallate extraction for topical antioxidant formulations is opening margin pools beyond traditional beverage channels into Korean and Japanese skincare supply chains.
- Direct-to-consumer channel innovation:Subscription-based loose-leaf curation services are bypassing traditional wholesale layers, enabling estate-direct relationships with premium buyers in Shanghai, Tokyo, and Seoul metropolitan markets.
Industry Challenges
- Certification timeline compression:Organic and geographical indication certifications require multi-year conversion periods that mismatch working capital cycles for smallholder cooperatives seeking premium market access.
- Skill gap in processing technology:Steam fixation and stone grinding expertise for matcha-grade powder concentrates in limited supply, constraining quality-consistent capacity expansion outside traditional production zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Green Tea Market |
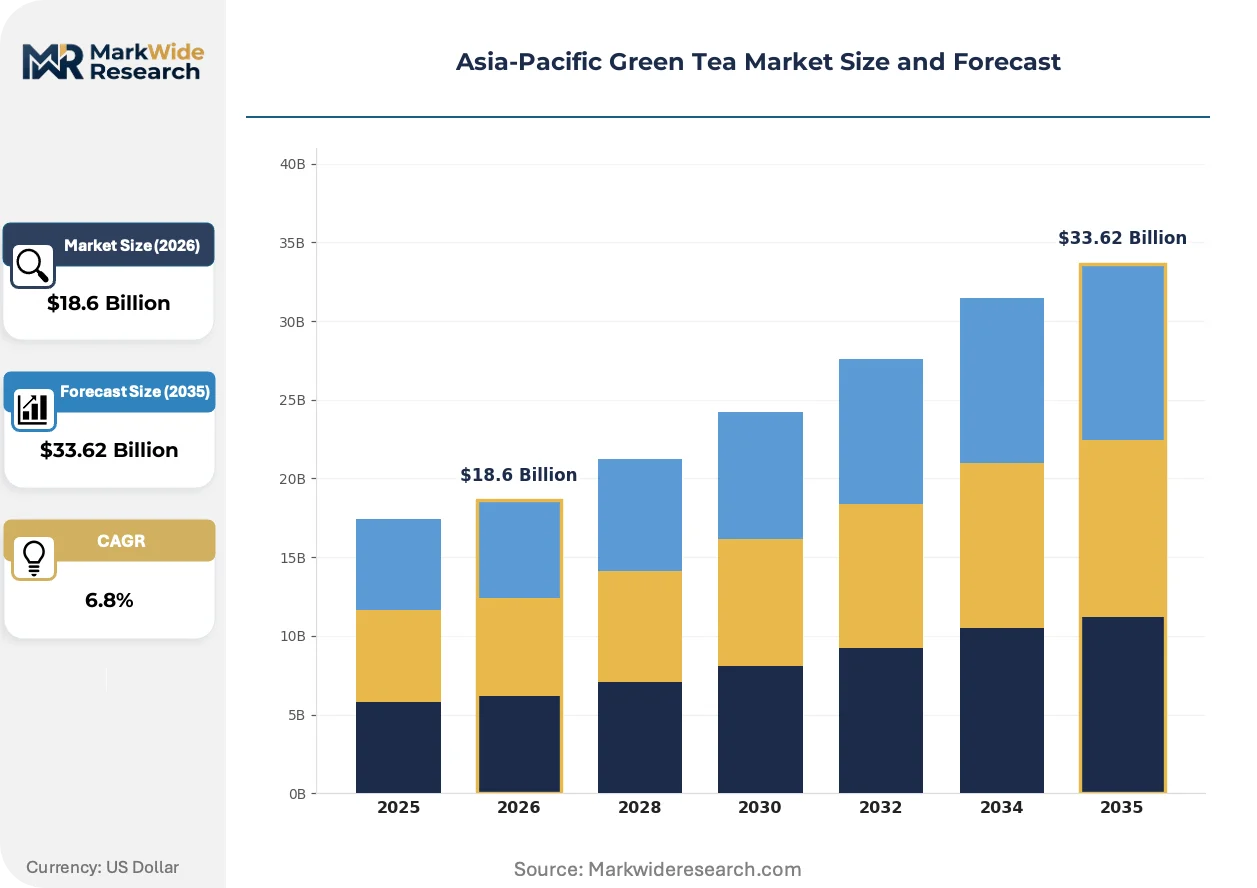
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Leaf, Bagged, Instant, Matcha End User: Household, Food Service, Retail, Online Form: Dried, Powdered, Concentrated, Extracts Packaging Type: Bottles, Tins, Pouches, Cartons |
| Companies Covered | Unilever PLC, Tata Consumer Products Limited, ITO EN, Nestlé S.A., The Coca-Cola Company, Associated British Foods plc, Dilmah Ceylon Tea Company PLC, The Republic of Tea, Organic India, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Green Tea Market Evolving Landscape
Processing technology convergence and procurement digitization are compressing traditional value chain layers across Asia-Pacific green tea supply networks. These shifts are redistributing margin capture toward upstream quality controllers and downstream direct-access platforms.
Flash-freezing combined with nitrogen-ambient grinding is collapsing the quality degradation window between harvest and powder production. Premium matcha manufacturers in Uji and Nishio are adopting these integrated systems to preserve catechin integrity. The technology is collapsing traditional seasonal supply constraints and enabling year-round premium positioning previously limited to spring-harvest ceremonial grades.
Japan's MAFF agricultural chemical residue limits are tightening detection thresholds for neonicotinoid and pyrethroid compounds annually. This regulatory trajectory is accelerating investment in biocontrol cultivation methods and integrated pest management protocols. Export-oriented estates in Fujian province are responding by segregating Japan-bound production lines with dedicated traceability documentation and third-party laboratory verification.
Urban consumers in Shanghai, Seoul, and Tokyo metropolitan areas are migrating from supermarket bagged formats toward estate-direct subscription channels. Specialty retailers and tea sommelier curation services are displacing conventional wholesale distribution for premium loose-leaf and single-origin matcha segments. This behavioral shift is most visible in China's tier-one cities where WeChat-integrated direct purchasing now captures significant ceremonial-grade transaction volume.
Asia-Pacific Green Tea Market Segmentation
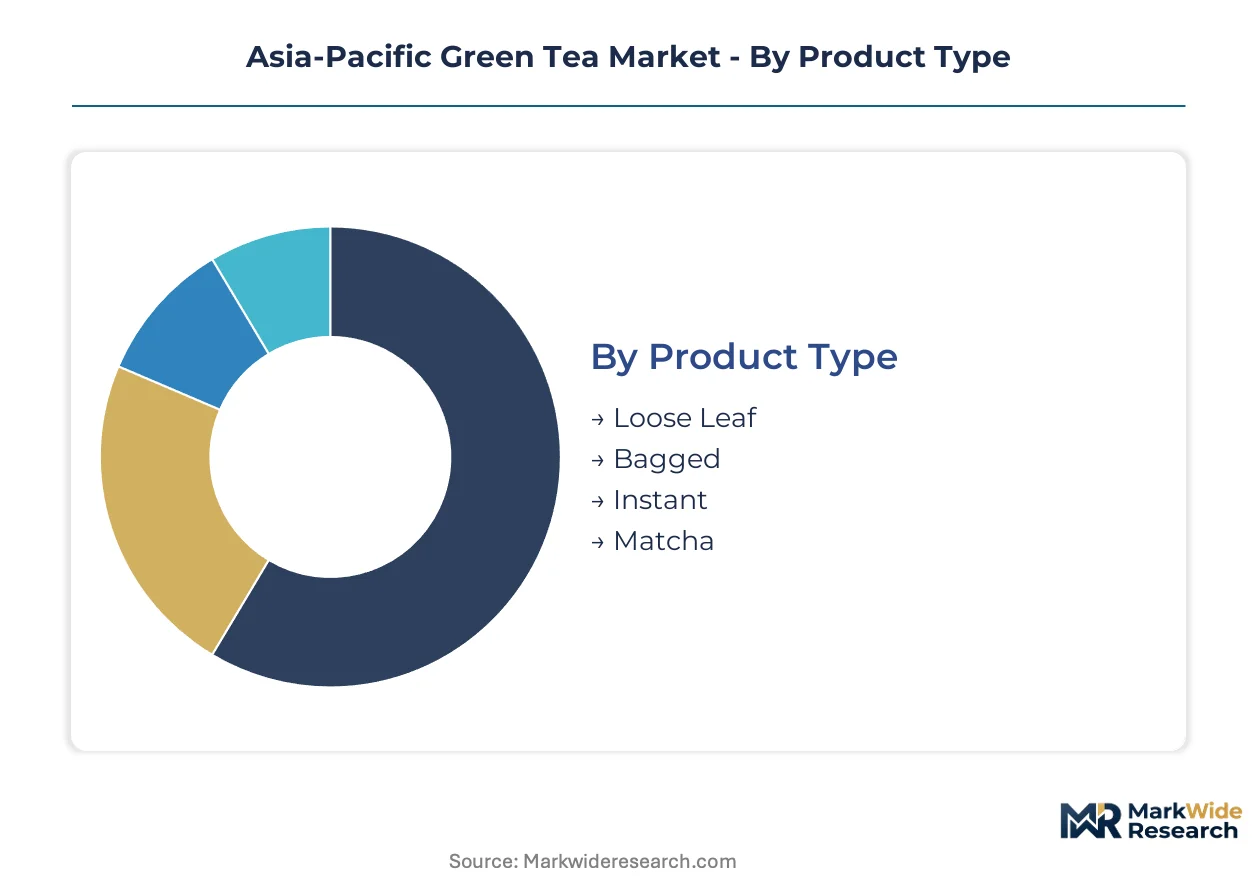
Green tea segmentation in Asia-Pacific reflects divergent margin structures across traditional consumption and functional applications. Product form and packaging choices determine compliance burdens, shelf stability, and access to premium distribution channels.
Product Type:
Mature formats dominate household penetration while emerging categories capture functional beverage and wellness positioning.
- Loose Leaf:Unprocessed whole leaves retaining maximum catechin integrity and terroir expression. Demand concentrates in Zhejiang and Fujian organic clusters supplying ceremonial-grade procurement for Tokyo and Seoul metropolitan buyers seeking traceability documentation.
- Matcha:Stone-ground shade-grown tencha powder with concentrated epigallocatechin gallate content. Food service channels in Japan and South Korea are expanding matcha procurement for beverage formulations and dessert applications targeting antioxidant positioning.
- Bagged:Cut-tear-curl leaves in filter paper sachets optimized for convenience brewing. Mass-market supermarket distribution across India and Southeast Asia.
- Instant:Spray-dried or freeze-dried soluble granules for rapid dissolution. Single-serve hospitality and airline catering procurement.
Bagged formats handle the majority of throughput; Matcha is the fastest mover on share.
End User:
Volume concentration sits with institutional procurement while margin capture shifts toward direct-access channels.
- Household:Individual consumers purchasing for daily consumption across urban and rural demographics. Supermarket and e-commerce distribution in China and India.
- Food Service:Restaurants, cafes, and hotels brewing for on-premise consumption. Specialty tea houses in Kyoto and Taipei driving ceremonial-grade loose-leaf procurement.
- Retail:Branded packaged goods for resale through grocery and convenience store networks. Mass-market bagged formats stocked from Mumbai to Manila.
- Online:Direct-to-consumer subscription and marketplace platforms bypassing traditional wholesale layers. WeChat-integrated estate-direct purchasing capturing premium transaction volume in Shanghai and Beijing tier-one markets.
Food Service anchors volume absorption; Online is expanding most quickly as subscription curation displaces conventional distribution.
Form:
Processing intensity determines bioactive concentration and regulatory classification for health claim eligibility.
- Dried:Traditional pan-fired or steamed leaves with preserved polyphenol structure. Ceremonial and daily consumption across Japan and China.
- Powdered:Finely milled leaf material for suspension in liquid or incorporation into food matrices. Matcha-grade powders command premium positioning in wellness applications.
- Concentrated:Liquid preparations with reduced water content for dilution. Ready-to-drink beverage manufacturing input.
- Extracts:Solvent or supercritical CO2-derived catechin isolates for nutraceutical and cosmetic formulations. Epigallocatechin gallate extraction for Korean and Japanese skincare supply chains.
Dried forms maintain the highest shipment volumes; Extracts are climbing the fastest as functional ingredient demand accelerates.
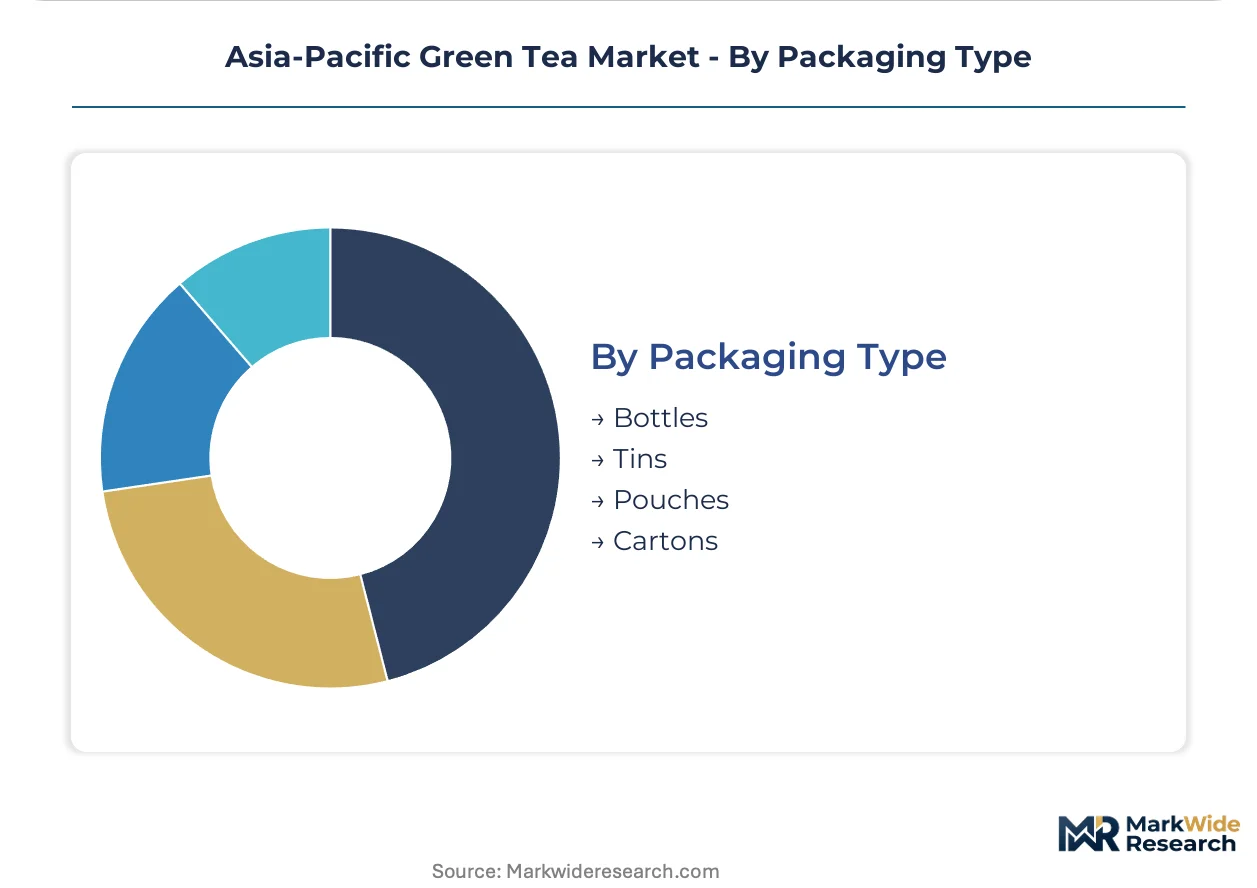
Packaging Type:
Material selection shapes shelf life extension, premium perception, and compliance with phytosanitary documentation requirements.
- Tins:Airtight metal caddies protecting against moisture and oxidation for premium loose-leaf grades. Gift segment positioning in Japan and Chinese tier-one cities.
- Pouches:Flexible laminated films with nitrogen flushing for cost-efficient distribution. Supermarket bagged format standard across India and Southeast Asia.
- Bottles:PET or glass containers for ready-to-drink liquid formulations. Convenience store and vending machine distribution in Japan and South Korea.
- Cartons:Paperboard secondary packaging for multi-unit retail presentation. Mass-market household stock-up occasions.
Pouches handle the majority of unit volume; Tins are gaining share fastest as premium positioning intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR and Japan's MAFF anchor regulatory frameworks that shape cultivation protocols and export eligibility across the Asia-Pacific green tea supply network. National standards on pesticide residues and organic certification create divergent compliance pathways that fragment procurement strategies.
China
Urban consumers in Shanghai and Beijing drive ceremonial-grade loose-leaf procurement through WeChat-integrated direct channels. GB 2763 pesticide residue standards enforced by SAMR are consolidating production in Zhejiang and Fujian provinces. Organic cultivation clusters in Anji County supply traceability-guaranteed grades to Japan and South Korea.
Japan
MAFF agricultural chemical regulations enforce strict neonicotinoid and pyrethroid detection thresholds that reward compliant exporters with ceremonial-segment price premiums. Matcha-grade powder demand concentrates in Tokyo and Osaka metropolitan food service channels. Uji and Nishio regions maintain stone-grinding expertise for concentrated epigallocatechin gallate extraction.
South Korea
MFDS oversight of health claim validations determines market access for functional green tea beverages targeting metabolic positioning. Seoul-based energy drink manufacturers are expanding extract procurement for polyphenol-enriched formulations. Boseong tea fields in South Jeolla Province supply domestic loose-leaf demand and cosmetic-grade raw material.
India
FSSAI pesticide thresholds and Tea Board geographical indication protections influence sourcing decisions for Assam and Darjeeling estates. Tata Consumer Products leverages deep estate relationships to anchor premium positioning. Urban households in Mumbai and Delhi-NCR are migrating from mass-market bagged formats toward specialty retail channels.
Vietnam
Northern highland provinces including Lào Cai and Yên Bái offer untapped organic cultivation potential with favorable agro-climatic conditions. Emerging FSSAI-recognized export infrastructure is opening Indian market access for Vietnamese estates. Thai Nguyen Province tea cooperatives are investing in steam fixation capacity to meet Japanese import standards.
Asia-Pacific Green Tea Market Competitive Landscape
Vertically integrated beverage conglomerates and estate-anchored specialty producers split the market into distinct competitive spheres. Concentration is moderate at the premium tier where traceability documentation and organic certification create entry barriers, while mass-market bagged segments exhibit price-driven fragmentation. Two archetypes dominate: garden-to-bottle integrators controlling quality through captive cultivation, and multi-brand portfolio operators leveraging scale economies in procurement and distribution. Capacity expansion in certified organic zones and backward integration into highland cultivation represent the dominant competitive moves.
Among Japanese garden-to-bottle integrators, ITO EN exemplifies vertical control from tea cultivation through bottled distribution. Tata Consumer Products Limited anchors estate-direct sourcing relationships with Assam and Darjeeling producers. Unilever PLC occupies the scale-driven mass-market tier with supermarket-distributed bagged formats across India and Southeast Asia.
| Leading Market Players |
|---|
| Unilever PLC |
| Tata Consumer Products Limited |
| ITO EN |
| Nestlé S.A. |
| The Coca-Cola Company |
| Associated British Foods plc |
| Dilmah Ceylon Tea Company PLC |
| The Republic of Tea |
| Organic India |
| Others |
Value Network & Pricing Analysis
Zhejiang and Fujian organic cultivation clusters anchor Asia-Pacific green tea supply capacity, concentrating premium loose-leaf production among certified estates that command ceremonial-grade price premiums in Tokyo and Seoul metropolitan markets. Their compliance with Japan's MAFF residue limits and China's GB 2763 standards creates tiered pricing power that smallholders cannot replicate.
Pricing Analysis
Price spreads between Uji-origin matcha and mass-market bagged formats from Assam estates span three orders of magnitude, with three-tier pricing structure across premium, standard, and economy levels. Certification grade under Japan's agricultural chemical regulations and organic conversion status drive price differentiation most acutely. Pricing pressure stems from fertilizer cost compression hitting smallholder cooperatives in Vietnam's northern highlands. Food service channels in Seoul and Tokyo show least price sensitivity, while Indian mass-market households absorb bagged format costs with minimal brand loyalty.
Supply Chain Analysis
Extended payment terms from Japanese beverage manufacturers to Fujian estate cooperatives are tightening working capital cycles, forcing supply-chain finance facility adoption among mid-tier processors. Raw material flows concentrate in China, Japan, and Vietnam, with tencha leaf and shade-grown cultivation expertise anchoring high-margin matcha production. Single-source vulnerability runs through Uji and Nishio grinding capacity for ceremonial-grade powder. Distribution runs through supermarket networks for bagged formats, while direct-to-consumer subscription channels capture premium loose-leaf and matcha segments in tier-one Chinese cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among WeChat-integrated direct-to-consumer platforms and Japanese garden-to-bottle integrators, fragmenting traditional wholesale layers and compressing margin capture for undifferentiated processors.
For Market Incumbents: Pre-empt estate-direct subscription channel displacement by securing captive organic cultivation in Zhejiang's Anji County and Vietnam's Lào Cai highlands. Invest in flash-freezing and nitrogen-ambient grinding capacity to preserve catechin integrity through year-round production. Certification investment in Japan's MAFF-compliant traceability documentation defends against emerging Vietnamese entrants with FSSAI-recognized export infrastructure. For New Entrants and Emerging Players: Northern Vietnamese highland provinces with favorable agro-climatic conditions and limited organic conversion history represent the most penetrable entry point for India-facing supply. Thai Nguyen Province cooperatives investing in steam fixation capacity offer partnership targets for Japanese market access. Cosmetics-grade epigallocatechin gallate extraction for Korean skincare supply chains provides a go-to-market angle bypassing saturated beverage channels. For Investors and Strategic Acquirers: Long-term, this sits as a wellness-premiumization play because functional beverage and nutraceutical applications are displacing traditional consumption with higher catechin concentration requirements. Acquisition targets should cluster around certified organic estates with established Japan export pathways and stone-grinding technical capacity. Monitor MAFF detection threshold tightening for neonicotinoid and pyrethroid compounds as the signal for accelerated biocontrol cultivation investment.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | Japan's MAFF residue limits reward compliant exporters with ceremonial-segment price premiums. |
| Flash-Freezing Technology Adoption | Uji manufacturers preserve catechin integrity through integrated harvest-to-powder systems. |
| Direct-to-Consumer Channel Launch | WeChat-integrated subscription services bypass wholesale layers in Shanghai and Beijing. |
| Cosmetics Extraction Capacity Buildout | Korean and Japanese skincare supply chains absorb epigallocatechin gallate isolates. |
| Vietnamese Highland Cultivation Partnership | FSSAI-recognized export infrastructure opens Indian market access for emerging estates. |
Research Methodology
Cross-validation between plantation operations executives and specialty retail channel heads anchors the qualitative findings in this study. Primary interviews with organic certification auditors, tea sommelier curation services, and food service procurement managers at Seoul-based energy drink manufacturers combined with secondary validation from SAMR food safety filings, MAFF agricultural chemical residue reports, customs and trade data, and FSSAI geographical indication registrations. Bottom-up estate capacity modeling and top-down regional consumption estimates triangulate volume outputs.
Calibration against historical organic conversion timelines and certification approval patterns shapes the analytical framework across the analysis window. Segmentation dimensions include product form, end-user channel, processing intensity, and packaging material, with regional regulatory cluster and cultivation zone agro-climatic profile as industry-specific layers. CAGRs derive from compounding annual procurement growth rates observed in functional beverage extract demand and subscription channel penetration in Chinese tier-one cities.
Practitioners should monitor MAFF detection threshold revisions and SAMR health claim validation shifts for early signals of compliance burden redistribution. Forecasts reflect assumptions regarding organic certification pipeline velocity and climate event frequency in Uji and Nishio production zones. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
North America Tea Market
Tea
Global Tea Bag Market
Tea
Tea Infuser Market
Tea
Tea Polyphenols Market
Tea
Matcha Market
Tea
Global Tea Market
Tea
Africa Ready to Drink Tea Market
Tea
Global Ready-To-Drink Green Tea Market
Tea
Matcha Products Market
Tea
Global Tea Extract Market
Tea
Smart Tea Set Market
Tea
Probiotic Tea Market
Tea
Green Tea Market
Tea
Africa Tea Market
Tea
Pu-Erh Tea Market
Tea
Out of Home Tea Market