
 Heat Sealing Tape Market | 2026-2036
Heat Sealing Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Sealing Tape Market Outlook
Industrial distribution through specialty packaging distributors is fragmenting as direct procurement from converter networks gains share. 3M Company leverages its materials science portfolio to sustain premium positioning in high-temperature adhesive formulations. DuPont Teijin Films USA Limited Partnership anchors North American supply through PET film substrates engineered for heat-seal compatibility. National Plastics, Inc. competes on conversion speed and regional logistics density.
Heat sealing tape comprises pressure-sensitive or hot-melt adhesive coatings applied to polymeric backings, typically achieving seal initiation temperatures between 90°C and 150°C depending on substrate chemistry. Polyethylene formulations dominate volume throughput in food and consumer goods packaging where hermetic barrier properties prevent moisture ingress. Polypropylene tapes capture expanding share in electronics manufacturing driven by low-outgassing requirements and dielectric stability. Medical-grade PVC tapes command concentrated margin pools despite regulatory certification burdens.
FDA enforces biocompatibility and sterility validation for medical-device packaging tapes under 21 CFR Part 820 quality system regulations. REACH restricts phthalate plasticizers in PVC tape formulations sold across EU member states, compelling reformulation investments. OSHA workplace exposure limits for solvent-based adhesive curing influence installation method preferences toward automated dispensing systems. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions that threaten incumbent release liner chemistries.
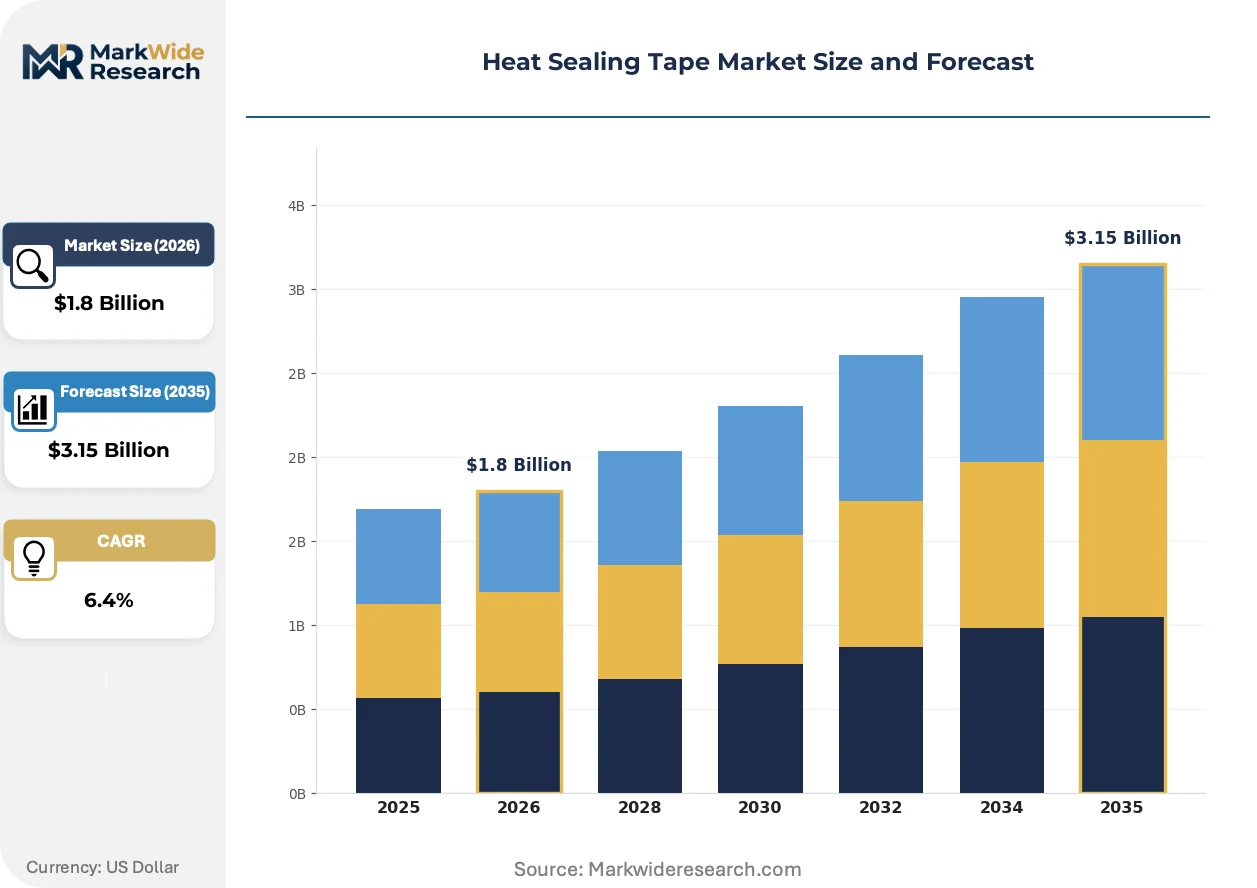
Market Dynamics
Medical sterilization protocols are compressing specification cycles for heat sealing tape converters, forcing simultaneous compliance with FDA 21 CFR Part 820 and EU MDR biocompatibility mandates while PET substrate supply concentrates in East Asian film extrusion corridors.
Growth Catalysts
- EU MDR sterilization mandates:Class III medical device packaging now requires validated heat-seal integrity documentation, pulling certified tape volumes into German and Swiss converter networks.
- Electronics low-outgassing specifications:Semiconductor cleanroom assembly lines in Taiwan and South Korea specify polypropylene tape formulations to prevent volatile organic compound contamination of wafer surfaces.
- Pharmaceutical cold-chain expansion:mRNA vaccine distribution infrastructure requires hermetic pouch seals capable of maintaining barrier properties through cryogenic temperature cycling.
Market Restraints
- Phthalate substitution costs:REACH Annex XVII restrictions on plasticizer chemistries force PVC tape reformulation, raising raw material expenses by 15-25% for European converters.
- Release liner supply concentration:Silicone-coated paper and film substrates for tape carriers depend on a narrow base of Finnish and Japanese specialty paper mills.
- Hot-melt adhesive temperature ceiling:Current ethylene-vinyl acetate formulations fail above 135°C, excluding them from high-temperature retort pouch applications.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO's tightening sterilization validation requirements for export-oriented formulation facilities create certified tape demand in Mumbai-Pune and Hyderabad clusters.
- Bio-based adhesive platforms:Converters integrating polylactic acid backings with rosin-derived hot-melt coatings access EU Green Deal procurement preferences.
- Automated dispensing integration:Tape slitting and application equipment vendors partner with packaging line OEMs to capture aftermarket service revenue in North American dairy processing plants.
Industry Challenges
- Adhesive chemist talent scarcity:Formulation expertise spanning pressure-sensitive, hot-melt, and UV-curable platforms concentrates among retiring specialists at Midwest US tape converters.
- ISO 13485 certification timelines:Medical-grade tape qualification protocols extend 18-24 months, freezing converter capacity allocations before volume commitments materialize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Sealing Tape Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, PVC, Others Application: Packaging, Electronics, Automotive, Medical End User: Manufacturers, Retailers, Distributors, Contractors Installation Method: Manual, Automated, Semi-Automated, Industrial |
| Companies Covered | DuPont Teijin Films USA Limited Partnership, National Plastics, Inc., Heat Seal, LLC, Prairie State Group, Venus Packaging, Blisterpak, Inc., Petra Manufacturing Company, Janco Inc., LLC, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Sealing Tape Market Strategic Shifts
Active material science convergence is dissolving boundaries between commodity packaging tapes and functional films, with substrate-adhesive combinations now engineered for specific sterilization modalities rather than generic heat-seal compatibility.
Coextruded multilayer barrier films are hybridizing heat sealing tape functionality with oxygen and moisture vapor transmission control. Pharmaceutical blister pack manufacturers in Switzerland and Germany adopt these structures to eliminate separate lidding film and sealing tape components. The convergence is compressing converter margins on standalone tape products while rewarding integrated film-tape suppliers.
REACH authorization procedures for per- and polyfluoroalkyl substances are eliminating silicone release liner alternatives dependent on fluoropolymer coatings. Tape converters serving EU medical device markets accelerate migration to plasma-treated paper liners or UV-curable silicone systems. German packaging engineers report 12-18 month qualification cycles for liner substitutions, freezing specification changes until regulatory certainty solidifies.
Direct procurement from substrate extruders and adhesive compounders is displacing distributor intermediaries in North American food packaging. Large meat and dairy processors in Wisconsin and California negotiate annual volume contracts with DuPont Teijin Films and Avery Dennison, capturing 8-12% cost reductions versus spot distributor purchases. The pattern concentrates price discovery power among buyers with dedicated packaging engineering staff.
Heat Sealing Tape Market Segmentation
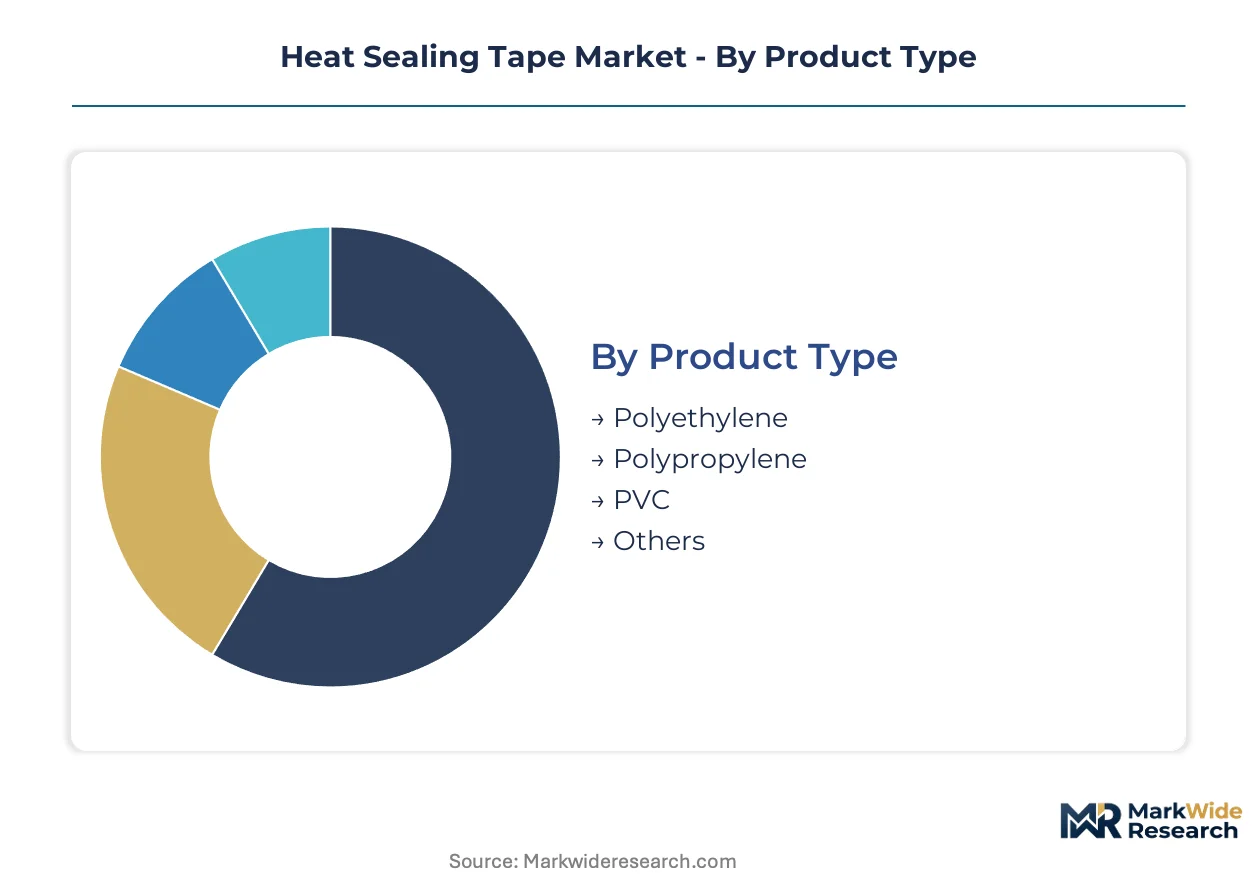
Heat sealing tape segmentation reveals divergent service intensity requirements across product chemistries and end-use certifications. Converter networks must maintain distinct technical support capabilities for medical-grade qualification protocols versus commodity packaging specifications.
Product Type:
After-sales service intensity escalates with regulatory certification burden, separating medical-grade formulations from commodity packaging grades.
- Polyethylene:Low-density and linear low-density formulations dominate food packaging throughput with seal initiation temperatures between 90°C and 120°C. Hermetic barrier specifications for meat and dairy processors in Wisconsin and California concentrate volume demand, though margin compression from direct procurement contracts limits converter profitability.
- Polypropylene:Biaxially oriented substrates deliver dielectric stability and minimal volatile organic compound outgassing for semiconductor assembly operations. Cleanroom specifications in Taiwan and South Korea drive qualification cycles exceeding 18 months, embedding converter technical staff directly at customer facilities.
- PVC:Medical-grade plasticized formulations face REACH Annex XVII phthalate restrictions requiring reformulation investment.
- Others:PET and specialty fluoropolymer tapes serve retort pouch and aerospace applications with narrow specification tolerances.
Polyethylene holds the largest share; momentum sits with polypropylene as electronics manufacturing expands.
Application:
Application segmentation maps directly to certification infrastructure investment, with medical and electronics segments demanding dedicated quality systems.
- Packaging:Food, pharmaceutical, and consumer goods applications represent the foundational volume base. Cold-chain expansion for mRNA distribution infrastructure pulls hermetic pouch seal specifications into cryogenic temperature cycling validation.
- Electronics:Semiconductor and display manufacturing specify low-outgassing polypropylene formulations to prevent wafer surface contamination.
- Automotive:Battery pack assembly and interior trim applications require flame-retardant adhesive systems meeting OEM material specifications.
- Medical:Class III device packaging under FDA 21 CFR Part 820 and EU MDR mandates demands validated heat-seal integrity documentation with 18-24 month qualification timelines.
Packaging maintains volume leadership; medical commands the steepest expansion trajectory through sterilization protocol tightening.
End User:
End user type determines procurement channel structure and technical service delivery model.
- Manufacturers:OEM packaging engineers at pharmaceutical and electronics firms negotiate direct annual volume contracts with substrate extruders, bypassing distributor intermediaries.
- Retailers:Private-label food brands consolidate tape procurement through co-manufacturer arrangements with limited specification autonomy.
- Distributors:Specialty packaging distributors fragment as converter networks build direct regional logistics density.
- Contractors:Installation and maintenance service providers in industrial processing plants specify tape grades based on equipment OEM recommendations.
Manufacturers capture the greatest pricing leverage; distributors face margin erosion from direct channel displacement.
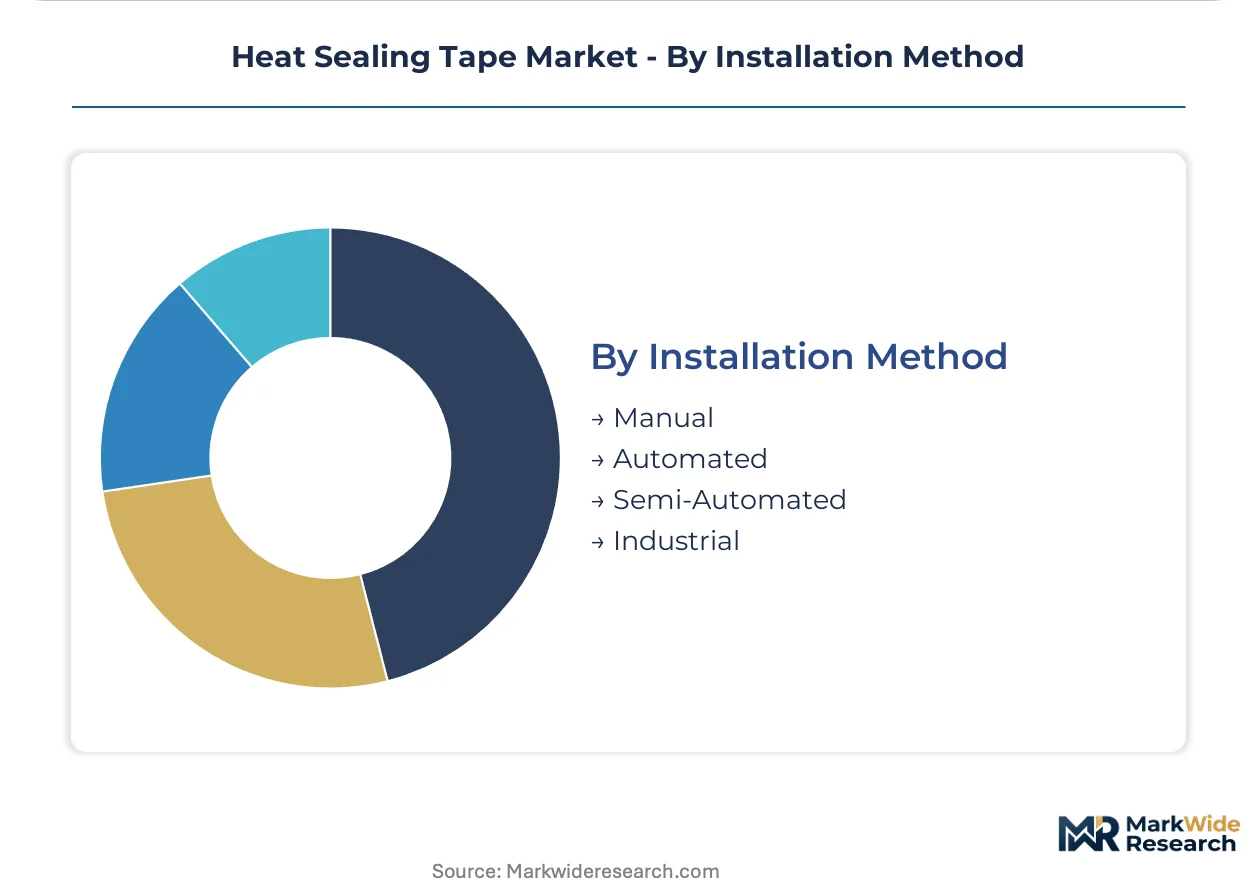
Installation Method:
Installation segmentation reflects capital equipment intensity and labor skill requirements across end-use environments.
- Manual:Hand-applied tape operations persist in short-run pharmaceutical packaging and prototype electronics assembly where changeover frequency exceeds automation justification.
- Automated:High-speed rotary and reciprocating heat-seal systems in dairy processing and meat packaging lines demand precision tension control and temperature uniformity.
- Semi-Automated:Batch-mode sealing stations bridge manual and fully automated throughput for mid-volume medical device manufacturers.
- Industrial:Continuous web processing lines integrate slitting, coating, and sealing operations with real-time quality monitoring.
Automated systems claim the dominant installed base; semi-automated configurations gain traction among emerging medical device contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine freight corridor sustains Germany's industrial packaging throughput, while Taiwan's Kaohsiung port complex anchors semiconductor tape demand. India's pharmaceutical export infrastructure at Jawaharlal Nehru Port drives sterilization-grade specifications. These logistics arteries concentrate converter networks and certification requirements.
United States
FDA 21 CFR Part 820 enforcement tightens medical-device packaging validation requirements. Wisconsin and California dairy processors negotiate direct annual contracts with substrate suppliers, bypassing distributor intermediaries. The Midwest converter corridor faces adhesive chemist talent scarcity as formulation specialists retire.
Germany
EU MDR sterilization mandates pull certified tape volumes into converter networks concentrated along the Rhine industrial belt. REACH Annex XVII phthalate restrictions force PVC tape reformulation investment. Swissmedic-aligned certification protocols in Baden-Württemberg extend qualification timelines to 18-24 months.
China
NMPA biocompatibility standards for medical-device packaging converge with international sterilization protocols. Yangtze River Delta film extrusion corridors concentrate PET substrate supply for regional converter networks. Shanghai pharmaceutical exporters adopt hermetic pouch seals for mRNA cold-chain distribution.
India
CDSCO tightening sterilization validation requirements for export-oriented formulation facilities creates certified tape demand. Mumbai-Pune and Hyderabad pharmaceutical clusters drive specification adoption. The country's national pharmaceutical regulator aligns with WHO prequalification standards for packaging integrity.
South Korea
MFDS medical-device packaging regulations intersect with semiconductor cleanroom specifications for low-outgassing polypropylene tapes. Busan-Ulsan manufacturing corridors host display and wafer assembly operations requiring dielectric stability. Taiwanese converter technical staff embed directly at customer facilities for 18-month qualification cycles.
Heat Sealing Tape Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in substrate and adhesive formulation. The vendor base organizes around three archetypes: integrated film-tape suppliers, standalone converters, and specialty adhesive compounders. Consolidation pressures concentrate among distributors as direct procurement channels expand. Dominant competitive moves include backward integration into substrate extrusion and geographic expansion through regional logistics density.
Among North American fabricators, DuPont Teijin Films USA Limited Partnership occupies a position exemplifying integrated film-tape supply, while 3M Company represents the materials science platform archetype. National Plastics, Inc. sits within the regional converter tier focused on logistics density. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| DuPont Teijin Films USA Limited Partnership |
| National Plastics, Inc. |
| Heat Seal, LLC |
| Prairie State Group |
| Venus Packaging |
| Blisterpak, Inc. |
| Petra Manufacturing Company |
| Janco Inc., LLC |
| 3M Company |
| Others |
Value Chain & Pricing Dynamics
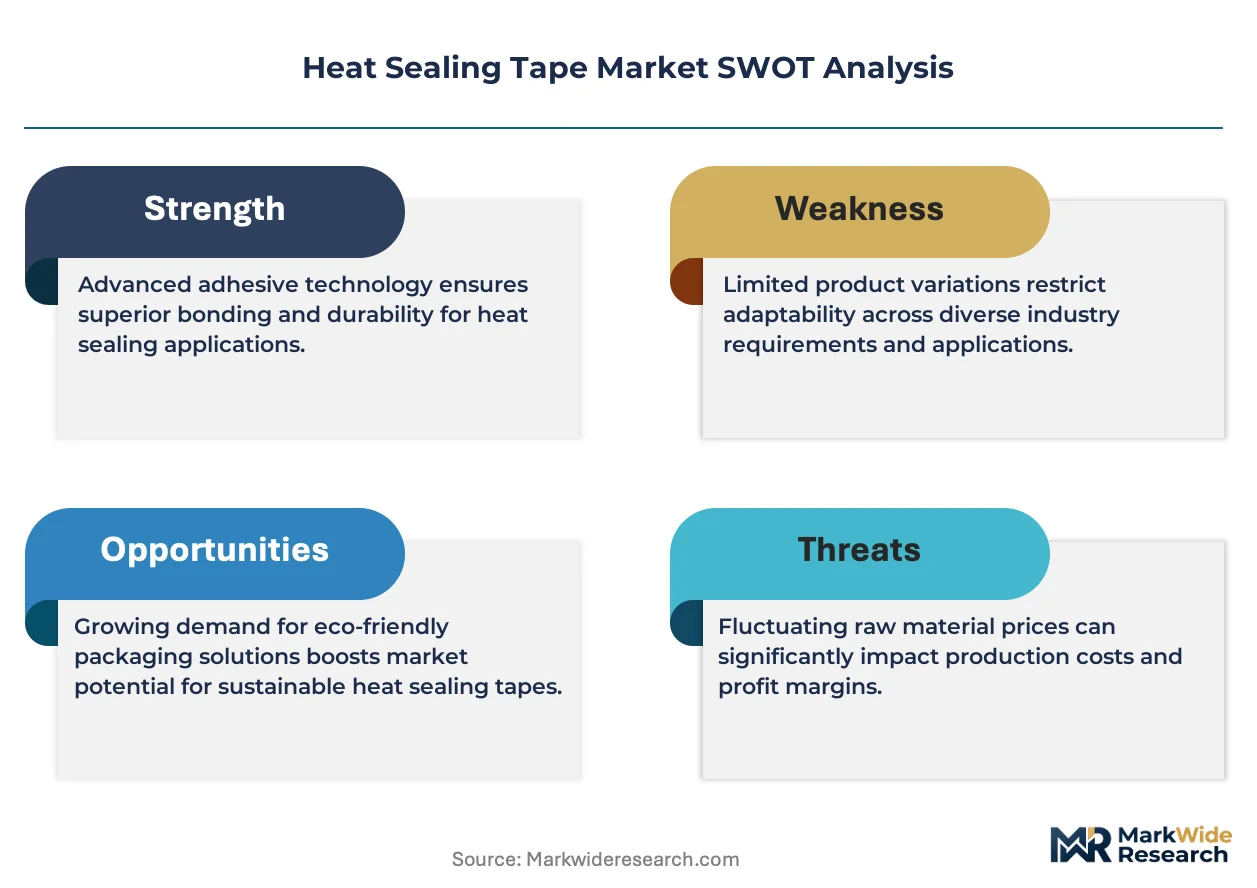
REACH Annex XVII phthalate restrictions determine both pricing tier spreads and supply chain shape by forcing European PVC tape converters into 15-25% raw material cost inflation while compressing margins on standard grades. Medical-grade certification burdens widen spreads between qualified and commodity formulations as German and Swiss converter networks capture premium positioning.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical OEM annual contracts from spot distributor purchases, with direct procurement capturing 8-12% cost reductions. Certification grade and volume scale drive price differentiation, with ISO 13485-qualified medical grades commanding substantial premiums over food-packaging standards. Pricing pressure stems from direct channel displacement as Wisconsin and California dairy processors bypass intermediaries. Food packaging buyers exhibit highest price sensitivity; medical device OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Tariff exposure between East Asian film extrusion corridors and European converter networks dominates supply chain risk assessment for PET substrate dependency. Raw material sourcing draws from German industrial packaging corridors, Taiwanese semiconductor cleanroom specifications, and Finnish specialty paper mills for silicone-coated release liners. Silicone-coated paper substrate concentration in Finnish and Japanese mills creates single-source vulnerability for tape carriers. Distribution runs through converter networks building direct regional logistics density, displacing specialty packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among pharmaceutical OEMs and large food processors with dedicated packaging engineering staff, fragmenting distributor intermediaries and compressing converter margins.
For Market Incumbents: Build certification moats by accelerating ISO 13485 qualification timelines and embedding technical staff directly at semiconductor cleanroom facilities in Taiwan and South Korea. Backward integration into PET substrate extrusion secures supply continuity against East Asian concentration risks. Defensive priority rests on capturing aftermarket service revenue through automated dispensing equipment partnerships. For New Entrants and Emerging Players: Pursue Indian pharmaceutical packaging clusters in Mumbai-Pune and Hyderabad where CDSCO tightening creates certified tape demand without entrenched incumbent relationships. Bio-based adhesive platforms combining polylactic acid backings with rosin-derived coatings offer procurement preference access under EU Green Deal frameworks. Go-to-market angle targets export-oriented formulation facilities requiring WHO-aligned packaging integrity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated film-tape suppliers over standalone converters. Long-term viability across the next decade hinges on substrate-adhesive convergence eliminating separate component procurement. Acquisition focus centers on mid-cap converters with embedded medical-grade certification infrastructure. Signal to monitor: qualification timeline compression as FDA and EU MDR harmonization accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Extrusion | Captive PET film supply secures heat-seal compatibility specifications against East Asian concentration. |
| Medical-Grade Certification Investment | ISO 13485 qualification embeds converters into 18-24 month pharmaceutical OEM validation cycles. |
| Automated Dispensing Partnership | Equipment vendor alliances capture aftermarket service revenue in North American dairy processing plants. |
| Bio-Based Platform Development | Polylactic acid and rosin-derived formulations access EU Green Deal procurement preferences. |
| Regional Logistics Density Buildout | Direct converter networks displace distributor intermediaries in Wisconsin and California food packaging. |
Study Parameters
A standing panel of adhesive formulation chemists, pharmaceutical packaging engineers, semiconductor cleanroom managers, and specialty tape converters provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with converter technical directors and procurement leads at dairy processing and medical device OEMs. Secondary validation drew from FDA 21 CFR Part 820 guidance documents, ECHA REACH restriction updates, SEC filings of substrate suppliers, and customs trade data for PET film imports. Bottom-up volume modeling triangulated against top-down market sizing from packaging equipment installation records.
Scenario-bracketing framed projections across sterilization protocol tightening, phthalate substitution cost trajectories, and electronics manufacturing expansion rates. Segmentation dimensions spanned product chemistry, application certification tier, end-user procurement channel, and installation method capital intensity. CAGRs derived from elasticity-adjusted demand curves for medical sterilization and semiconductor cleanroom specifications. Industry-specific inputs included pharmaceutical cold-chain infrastructure buildout rates and mRNA distribution pouch seal validation requirements.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or medical device FDA approval velocities would shift the trajectory. Forecasts reflect documented assumptions on regulatory harmonization timing and substrate supply concentration persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Security Tape Market
Tapes
Kraft Paper Tapes Market
Tapes
Thermal Release Tapes Market
Tapes
Wire Harness Tape Market
Tapes
Release Tape Market
Tapes
Seam Tapes Market
Tapes
Self-Adhesive Tear Tape Market
Tapes
Acoustic Tape Market
Tapes
Building and Construction Tapes Market
Tapes
Hand Wrappers Market
Tapes
Wing Walk Tapes Market
Tapes
Global Specialty Tapes Market
Tapes
BOPP Packaging Tapes Market
Tapes
Flocking Tape Market
Tapes
Filament Tapes Market
Tapes
Hot Melt Adhesive Tapes Market