
 Flatback Tapes Market | 2026-2036
Flatback Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Flatback Tapes Market Analysis
China's Yangtze River Delta manufacturing belt is reconfiguring flatback tape supply chains as domestic converters expand coating capacity. 3M Company leverages its St. Paul-based polymer science infrastructure to sustain North American leadership in high-temperature flatback formulations. Intertape Polymer Group anchors its position through backward integration into film extrusion, while tesa SE competes via specialized automotive die-cut solutions for European OEMs.
Flatback tapes consist of a paper-based backing substrate coated with pressure-sensitive adhesive, typically formulated with rubber or acrylic chemistries, engineered for conformable masking, splicing, and temporary holding applications across temperatures ranging from 60°C to 180°C. Single-sided paper flatback tapes dominate packaging and general industrial holding due to cost efficiency and clean removability, while reinforced variants capture structural splicing margins in paper mill and corrugated board operations. Polyester-backed flatback tapes represent the fastest-expanding material category, displacing vinyl in electrical insulation applications where thermal stability and thin-gauge precision matter.
EPA regulations on volatile organic compound emissions from adhesive manufacturing constrain solvent-based coating operations in the United States, while REACH substance restrictions in Europe limit certain phthalate plasticizers and heavy metal stabilizers in tape formulations. OSHA workplace exposure standards for isocyanates and formaldehyde resins additionally shape adhesive chemistry selection and personal protective equipment protocols in tape converting facilities. Stakeholders must monitor evolving PFAS restrictions across multiple jurisdictions, as fluorinated release coatings and certain adhesive additives face prospective phase-outs that would force reformulation investments across the flatback tape value chain.
Market Dynamics
EV battery thermal management requirements are forcing adhesive tape specifications toward higher temperature tolerances and dielectric stability, compressing product development cycles across coating operations in Germany, Japan, and China.
Growth Catalysts
- REACH substance restrictions:Phthalate plasticizer bans in Europe are accelerating acrylic adhesive reformulation investments, opening premium positioning for compliant European converters.
- China's eastern manufacturing corridor:Electronics contract manufacturing concentration in the Yangtze River Delta sustains volume demand for thin-gauge precision flatback tapes in semiconductor packaging workflows.
- Hot-melt coating technology:Solvent-free adhesive deposition methods are displacing solvent-based systems in North American converting facilities, reducing VOC exposure liability and permitting faster line speeds.
Market Restraints
- Crude oil derivative volatility:Synthetic rubber and petroleum-based resin feedstocks expose margin structures to petrochemical price swings without effective hedging instruments at mid-tier converter scale.
- Coating capacity concentration:Backward-integrated film extrusion capabilities cluster among top-five suppliers, constraining independent converters' access to substrate cost parity.
- Silicone adhesive substitution:High-temperature electrical insulation applications increasingly specify silicone-coated polyimide tapes, eroding polyester flatback tape share above 150°C operating thresholds.
Strategic Opportunities
- India's electronics manufacturing clusters:PLI scheme incentives for mobile device and component assembly in Tamil Nadu and Karnataka create import-substitution openings for localized flatback tape slitting and distribution.
- EU Green Deal procurement mandates:Public sector buying rules favoring recycled content and bio-based feedstocks reward early movers with certified circular adhesive formulations.
- Digital inventory platforms:B2B marketplace procurement for MRO supplies is compressing distributor layers, enabling direct converter relationships with mid-size industrial end-users.
Industry Challenges
- Adhesive polymer chemistry expertise:Formulation talent scarcity constrains development of high-temperature acrylic systems that meet both automotive OEM specifications and REACH compliance timelines.
- PFAS testing and certification backlog:Prospective fluorinated compound restrictions across multiple jurisdictions force preemptive reformulation investments ahead of confirmed regulatory scope, tying up R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flatback Tapes Market |
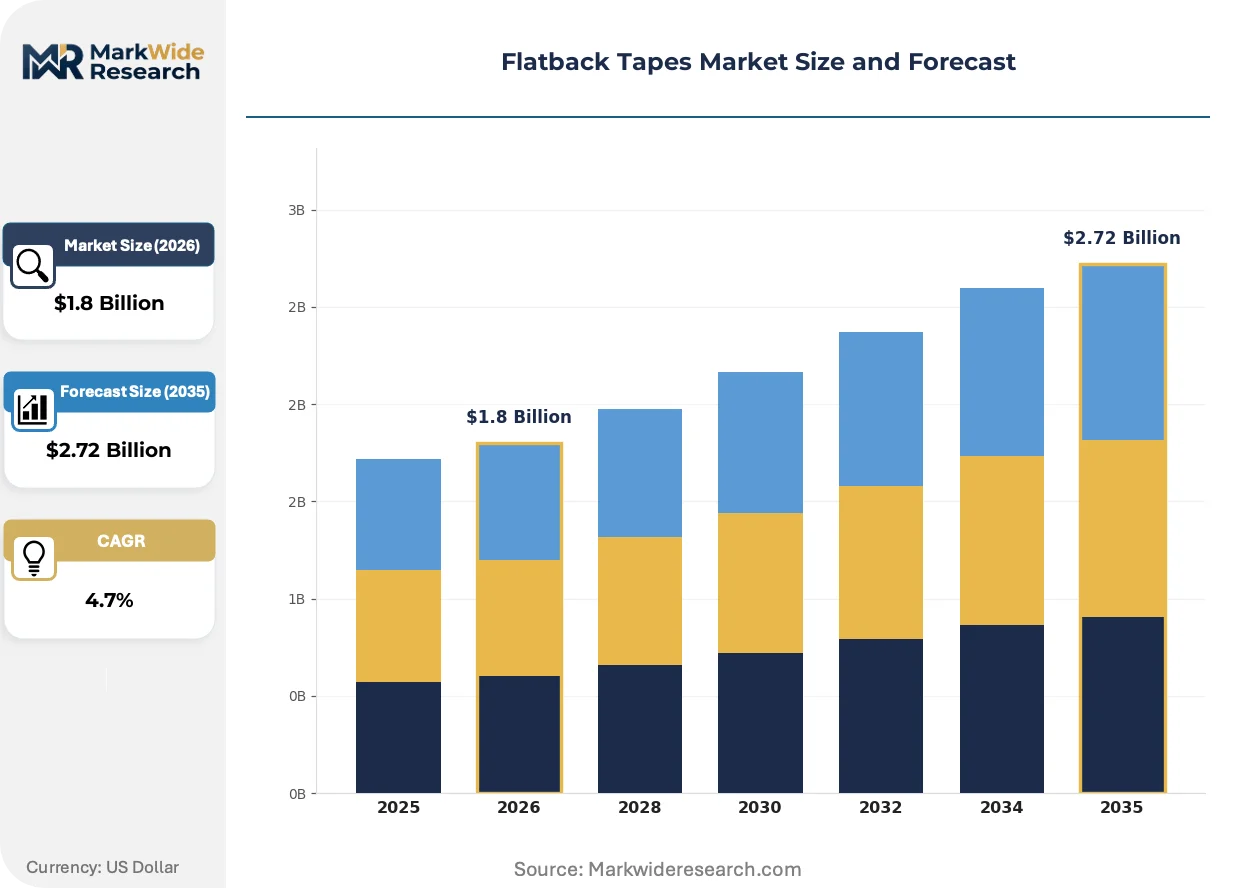
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Reinforced, Die-Cut Application: Packaging, Electrical, Construction, Automotive Material: Paper, Polypropylene, Polyester, Vinyl End User: Consumer Goods, Industrial, Electronics, Healthcare |
| Companies Covered | 3M Company, Intertape Polymer Group, Shurtape Technologies, tesa SE, Nitto Denko Corporation, Berry Global, Scapa Group, Pro Tapes & Specialties, Avery Dennison, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flatback Tapes Market Emerging Trajectories
Coating technology convergence with digital process control is compressing development cycles and enabling mass-customization of adhesive properties. Three developments merit particular attention.
Waterborne acrylic emulsion systems with hybrid crosslinking chemistries are virtualizing the traditional solvent-based coating infrastructure, enabling automotive OEMs in Germany and Japan to specify tapes meeting 180°C thermal stability without VOC exposure liability. Tier-one suppliers adopting these systems report 40% faster qualification cycles with EV battery module assemblers.
EPA enforcement of maximum achievable control technology standards for adhesive manufacturing is forcing solvent recovery system investments or line conversions among US-based converters. Small and mid-size operations lacking capital access face consolidation pressure, while integrated manufacturers with captive coating capacity capture incremental share in North American industrial distribution.
Specification consolidation among automotive OEMs is compressing approved vendor lists from regional diversity toward global qualification standards. Procurement teams at German and Japanese headquarters now mandate single-source tape approvals across multiple assembly plants, favoring converters with transnational certification capabilities and testing laboratory networks spanning three continents.
Flatback Tapes Market Segmentation
Flatback tape specifications diverge sharply across thermal tolerance, conformability, and dielectric requirements. Each segment carries distinct adhesive chemistry constraints and regulatory compliance burdens that shape converter investment priorities.
Product Type:
Mature formats dominate volume throughput while emerging constructions capture specification upgrades in high-temperature applications.
- Single-Sided:Paper backing with one adhesive face serves masking, temporary holding, and light-duty splicing across 60°C to 120°C ranges. Packaging workflows in China's Yangtze River Delta manufacturing belt sustain volume demand for thin-gauge variants with clean removability.
- Double-Sided:Adhesive coating on both substrate faces enables laminating and mounting applications where mechanical fasteners are prohibited. EV battery module assemblers in Germany and Japan specify these constructions for thermal interface bonding, driving acrylic reformulation investments.
- Reinforced:Fiberglass or filament scrim embedded within paper backing delivers tensile strength for structural splicing in corrugated board operations.
- Die-Cut:Precision-slit shapes eliminate hand-trimming labor in automated assembly lines.
Single-Sided handles the majority of throughput; Double-Sided is climbing the fastest on share as automotive thermal management specifications tighten.
Application:
Cost tier stratification separates commodity packaging grades from certified electrical and automotive constructions commanding formulation premiums.
- Packaging:General industrial sealing and carton closing consume the highest tape volumes at narrowest margins. REACH-compliant acrylic systems are displacing solvent-based rubber adhesives in European distribution channels.
- Electrical:Insulation and coil winding applications specify thin-gauge polyester backings with dielectric stability above 150°C. Silicone-coated polyimide tapes are eroding polyester flatback share in the highest thermal tiers.
- Construction:Temporary surface protection and masking during painting and finishing operations.
- Automotive:Wire harness bundling and interior trim attachment with OEM qualification requirements.
Packaging moves the largest absolute volumes; Electrical applications show the steepest expansion trajectory as EV power electronics proliferate.
Material:
Supply concentration in film extrusion capabilities shapes substrate cost parity across converter tiers.
- Paper:Crepe and flatback kraft substrates provide conformability and cost efficiency for masking and splicing. Paper mill operations in the United States and Germany specify reinforced grades for web splicing at line speeds exceeding 800 meters per minute.
- Polypropylene:Oriented film backings deliver moisture resistance and tensile strength for outdoor electrical applications. Hot-melt coating compatibility enables solvent-free adhesive deposition, reducing VOC exposure liability for North American converters.
- Polyester:Biaxially oriented polyethylene terephthalate provides dimensional stability and thin-gauge precision for semiconductor packaging workflows.
- Vinyl:Plasticized polyvinyl chloride retains flexibility at low temperatures for cold-climate construction applications.
Paper substrates carry the bulk of tonnage; Polyester is gaining share fastest as electronics miniaturization demands thinner insulating layers.
End User:
Customer type determines specification stringency, with industrial and electronics segments driving certification requirements that commodity consumer grades bypass.
- Consumer Goods:Retail packaging and household applications prioritize cost minimization over thermal performance. Big-box retailers in the United States specify repulpable adhesives to support sustainability claims and reduce landfill diversion costs.
- Industrial:Manufacturing maintenance and MRO procurement demands consistent adhesive performance across humidity and temperature swings. Digital inventory platforms are compressing distributor layers, enabling direct converter relationships with mid-size industrial end-users.
- Electronics:Semiconductor packaging and PCB assembly require particulate-free removal and ionic purity. Cleanroom specifications in South Korean and Taiwanese fabrication facilities exclude standard rubber-based adhesives.
- Healthcare:Sterile packaging and medical device assembly applications.
Industrial end users absorb the largest share of volume; Electronics customers are expanding most quickly as contract manufacturing concentrates in China's eastern corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of maximum achievable control technology standards anchors the United States as the regulatory benchmark shaping coating facility investments worldwide. The market distributes across five manufacturing geographies where tape specifications diverge by thermal tolerance and compliance burden.
United States
EV battery module assembly lines in Michigan and Ohio specify high-temperature acrylic flatback tapes for thermal interface bonding. OSHA workplace exposure standards for isocyanates constrain adhesive chemistry selection in converting facilities across the Midwest. The Southeast manufacturing corridor from Georgia to Tennessee attracts coating capacity relocations seeking lower energy costs and right-to-work labor frameworks.
Germany
Automotive OEM headquarters in Stuttgart and Munich mandate REACH-compliant tape formulations for wire harness bundling across European assembly plants. ECHA substance restrictions on phthalate plasticizers accelerate acrylic adhesive reformulation investments among Baden-Württemberg converters. The Ruhr industrial belt hosts paper mill operations specifying reinforced flatback grades for web splicing at line speeds exceeding 800 meters per minute.
China
Electronics contract manufacturing in the Yangtze River Delta sustains volume demand for thin-gauge polyester flatback tapes in semiconductor packaging workflows. MIIT industrial standards for adhesive products shape domestic converter certification requirements. Suzhou and Wuxi coating facilities expand waterborne acrylic capacity to serve Korean and Taiwanese fabrication customers requiring ionic purity specifications.
Japan
Automotive thermal management specifications from Toyota and Honda compress product development cycles for tape suppliers in Aichi and Shizuoka prefectures. METI energy efficiency guidelines incentivize hot-melt coating technology adoption to reduce solvent consumption. The Kansai industrial region around Osaka maintains specialized die-cutting operations for precision electronics assembly.
India
PLI scheme incentives for mobile device assembly in Tamil Nadu and Karnataka create import-substitution openings for localized flatback tape slitting and distribution. BIS certification requirements for adhesive products constrain rapid market entry by unqualified converters. The Sriperumbudur electronics cluster near Chennai attracts tape distributors establishing direct relationships with Foxconn and Dixon Technologies assembly facilities.
Flatback Tapes Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around backward-integrated film extruders holding substrate cost parity, independent converters competing on formulation specialization, and regional slitting operations serving logistics-sensitive end users. Three archetypes dominate: integrated polymer science platforms, automotive die-cut specialists, and electronics-focused precision coaters. Competitive moves center on solvent-to-hot-melt line conversions and transnational certification laboratory investments.
Among integrated manufacturers with captive coating infrastructure, 3M Company exemplifies the polymer science platform archetype through its St. Paul-based formulation development. Intertape Polymer Group anchors the backward-integrated tier with in-house film extrusion capabilities supporting North American distribution networks. Tesa SE occupies a position representing European automotive specialization, with die-cut solutions qualifying across German and Japanese OEM approved vendor lists. These three entities represent distinct competitive vectors rather than direct substitutes, with positioning divergence reflecting end-use certification requirements rather than price convergence.
| Leading Market Players |
|---|
| 3M Company |
| Intertape Polymer Group |
| Shurtape Technologies |
| tesa SE |
| Nitto Denko Corporation |
| Berry Global |
| Scapa Group |
| Pro Tapes & Specialties |
| Avery Dennison |
| Others |
Supply Flow & Price Mechanics
Crude oil derivative volatility in synthetic rubber and petroleum-based resin feedstocks compresses margin structures across converter tiers while simultaneously widening price spreads between backward-integrated majors and independent coaters lacking hedging instruments.
Pricing Analysis
European automotive OEMs in Stuttgart and Munich pay formulation premiums for REACH-compliant acrylic systems that eliminate phthalate plasticizers, while Chinese electronics contract manufacturers in the Yangtze River Delta negotiate thin-gauge polyester tape volumes on commodity terms. Pricing stratifies across automotive certification tiers, industrial MRO grades, and packaging economy levels, with cost compression in standard-grade paper tapes intensifying as waterborne acrylic emulsion systems displace solvent-based coating infrastructure. Tier-one automotive buyers exhibit lowest price sensitivity due to single-source qualification requirements, whereas consumer goods packaging purchasers drive aggressive annual cost-down targets.
Supply Chain Analysis
Synthetic rubber feedstocks from South Korea and Japan, acrylic resin precursors from Germany, and biaxially oriented polyester film from China form the upstream backbone of flatback tape manufacturing. Coating operations concentrate in China's eastern manufacturing corridor, Germany's Baden-Württemberg region, and the United States Southeast, with substrate cost parity favoring converters with captive film extrusion capabilities. Single-source vulnerability in high-temperature adhesive polymer chemistry expertise constrains rapid qualification of alternative suppliers. Distribution runs through industrial distributors serving MRO procurement, direct converter relationships with automotive OEMs, and digital B2B platforms compressing traditional channel layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flatback tape demand sits at an early-cycle expansion phase driven by EV battery thermal management specifications that are forcing adhesive reformulation investments ahead of confirmed regulatory scope.
For Market Incumbents: Pre-empt silicone-coated polyimide substitution in high-temperature electrical insulation by accelerating waterborne acrylic emulsion qualification with German and Japanese automotive OEMs, while securing backward integration into film extrusion to defend substrate cost parity against coating capacity concentration among top-five suppliers. For New Entrants and Emerging Players: India's Tamil Nadu and Karnataka electronics manufacturing clusters offer import-substitution openings for localized slitting and distribution operations targeting Foxconn and Dixon Technologies assembly facilities, with BIS certification requirements creating defensible positioning against unqualified competitors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated polymer science platforms with transnational certification laboratory networks spanning three continents, with long-term viability hinging on waterborne coating technology transitions; monitor PFAS restriction scope clarity across EPA and ECHA jurisdictions as the primary inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Acrylic Emulsion Transition | Eliminates VOC exposure liability for North American converters facing EPA enforcement of maximum achievable control technology standards. |
| Backward Integration into Film Extrusion | Captures substrate cost parity essential for competing against Intertape Polymer Group and integrated majors in industrial distribution. |
| Transnational Certification Laboratory Investment | Enables single-source tape approvals across German and Japanese OEM assembly plants compressing approved vendor lists. |
| Hot-Melt Coating Capacity Expansion | Reduces solvent consumption in alignment with METI energy efficiency guidelines while permitting faster line speeds. |
| PFAS-Free Formulation Development | Preempts prospective fluorinated compound restrictions forcing reformulation investments across the value chain. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with coating facility managers, automotive OEM procurement leads, electronics contract manufacturing engineers, and industrial distribution channel partners; and secondary validation through customs trade data, MIIT industrial standards documentation, EPA enforcement records, and SEC filings from publicly traded converters. Bottom-up volume modeling across adhesive chemistry tiers, substrate material categories, and end-use applications was cross-checked against top-down market sizing derived from regional production capacity assessments and import-export flow analysis.
Forecast inputs considered EV battery module assembly growth trajectories, REACH substance restriction implementation timelines, and hot-melt coating technology adoption curves across the projection horizon. Segmentation dimensions modeled include product type construction, thermal tolerance grade, adhesive chemistry family, substrate material, and end-use industry vertical. CAGRs were derived from regression analysis of historical volume trends against identified demand drivers, with scenario weighting applied to regulatory compliance investment cycles and coating capacity expansion announcements.
Practitioners should monitor ECHA substance restriction scope expansions, EPA maximum achievable control technology enforcement intensity, and PFAS testing certification backlogs for early signals of forecast revision triggers. Cross-checking against MIIT industrial standards publication schedules and automotive OEM approved vendor list consolidation announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Carry Handle Tape Market
Tapes
Global Specialty Tapes Market
Tapes
Edge Band Tapes Market
Tapes
Removal Strips Market
Tapes
Tabletop Tape Dispensers Market
Tapes
Dicing Tapes Market
Tapes
Wire Harness Tape Market
Tapes
Hand Wrappers Market
Tapes
Umbilical Tapes Market
Tapes
Electrical Shielding Tape Market
Tapes
Dry Wall Tapes Market
Tapes
Self-Fusing Silicone Tapes Market
Tapes
Security Tape Market
Tapes
Global Acrylic Foam Tapes Market
Tapes
Vinyl Electrical Tapes Market
Tapes
Filament Tapes Market