
 Narrow Band IoT Tracker Market | 2026-2036
Narrow Band IoT Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Narrow Band IoT Tracker Market Intelligence
Chinese module manufacturers is repositioning production capacity toward NB-IoT chipsets with integrated GNSS, compressing lead times for tracker OEMs worldwide. Sierra Wireless leverages its certified module portfolio to anchor premium supply contracts with North American fleet operators. Quectel Wireless Solutions competes on manufacturing scale, sustaining cost leadership across personal tracker and asset tracker segments. Teltonika dominates European vehicle tracker channels through backward integration into firmware development and cloud platform control.
Narrow Band IoT Tracker denotes a location-aware device transmitting position data over 3GPP-standardized NB-IoT cellular radio, typically operating in 200 kHz licensed spectrum bands with uplink rates below 62.5 kbps and deep indoor penetration exceeding 20 dB link budget improvement over legacy GPRS. These devices serve commercial applications requiring multi-year battery life and minimal data payload transmission, including stolen vehicle recovery, cold chain compliance verification, and lone worker safety alerting. Asset tracker hardware claims the dominant margin pool due to enterprise willingness to pay for tamper-detection enclosures and multi-mode fallback connectivity, while personal tracker volumes expand fastest among child safety and elderly assistance use cases where subscription bundling with mobile network operators reduces upfront purchase friction. Fleet management applications lead current revenue concentration, though supply chain monitoring is accelerating as pharmaceutical distributors adopt temperature-logging NB-IoT tags for lane-level shipment visibility.
FCC Part 15 and Part 22 rules govern radio emission limits and licensed band operation for NB-IoT trackers sold in the United States, while ETSI EN 301 908 harmonizes spectrum access across EU member states and CE marking mandates radio equipment directive compliance for market entry. China's MIIT enforces GB/T national standards for cellular IoT terminal radio frequency performance, and India's WPC requires IMEI registration for all imported cellular tracking devices. Stakeholders must monitor evolving cybersecurity certification requirements in major economies, as regulators increasingly mandate firmware update capabilities and encrypted payload transmission as preconditions for type approval.
Market Dynamics
Automotive OEM mandates for embedded cellular connectivity are compressing hardware certification timelines and forcing tracker suppliers to pre-integrate NB-IoT modems at the factory level rather than retrofit aftermarket devices.
Growth Catalysts
- 3GPP Release 13:Standardized narrowband operation in licensed spectrum accelerates type approval cycles for tracker hardware across multiple jurisdictions.
- Fleet electrification:Electric vehicle fleet operators require continuous location telemetry for battery state monitoring and charge station routing.
- Cold chain compliance:Pharmaceutical distributors deploy temperature-logging NB-IoT tags to satisfy GDP guidelines for lane-level shipment visibility.
Market Restraints
- Licensed spectrum fees:Recurring carrier subscription costs exceed total hardware expenditure over a five-year device lifecycle.
- Module supply concentration:Chinese chipset foundries control wafer allocation for integrated GNSS-NB-IoT silicon.
- Uplink bandwidth ceiling:62.5 kbps theoretical maximum constrains firmware over-the-air update payloads and diagnostic data richness.
Strategic Opportunities
- Indian logistics modernization:WPC IMEI registration requirements favor certified module suppliers with established import documentation capabilities.
- Lone worker safety mandates:EU member states are expanding employer duty-of-care legislation to cover isolated field personnel.
- LPWA convergence:Dual-mode NB-IoT and LTE-M chipsets allow single-SKU hardware to roam across heterogeneous carrier footprints.
Industry Challenges
- RF engineering scarcity:Deep indoor penetration optimization requires specialized antenna tuning expertise that contract manufacturers rarely retain in-house.
- Multi-regional certification backlog:FCC Part 15, ETSI EN 301 908, and MIIT GB/T testing queues extend hardware launch timelines by eight to fourteen months.
Report Scope
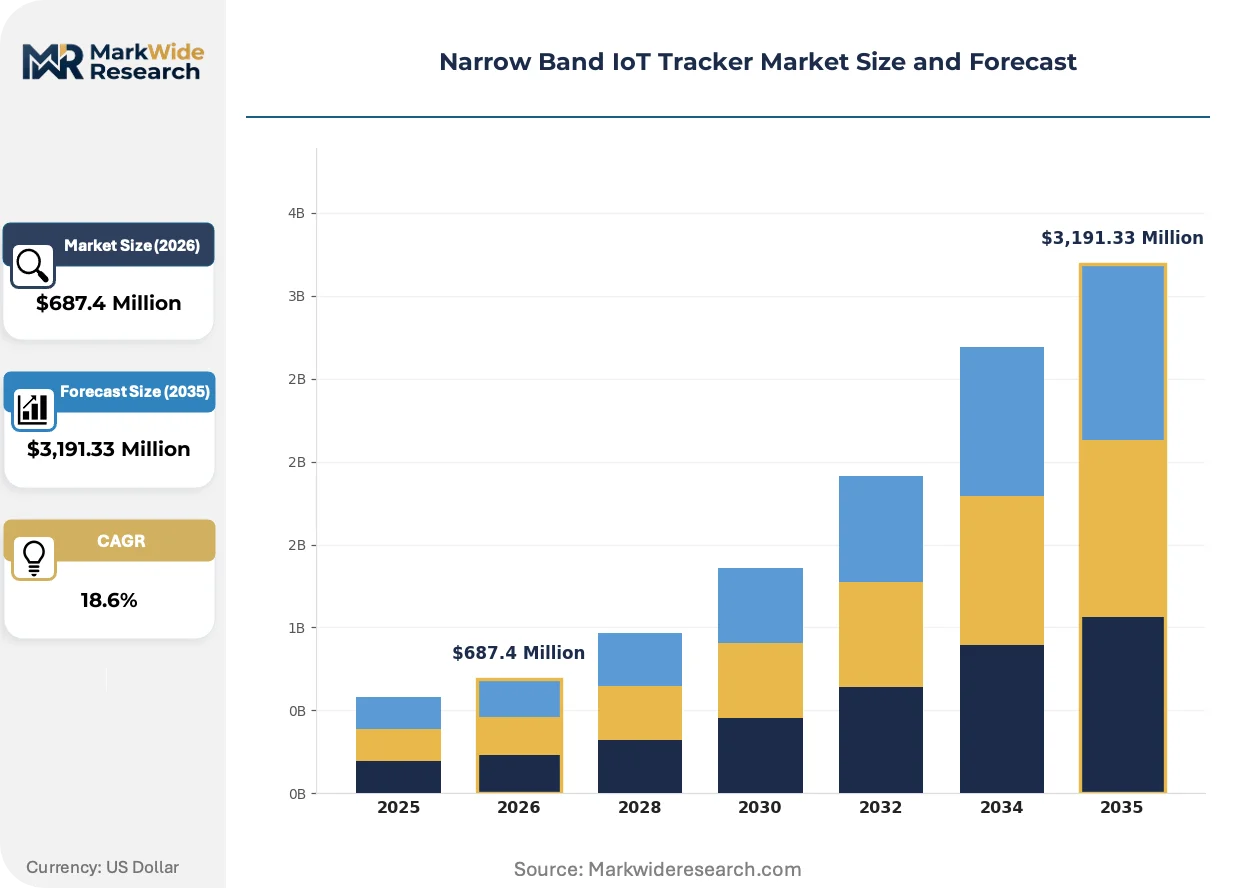
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Narrow Band IoT Tracker Market |
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $3,191.33 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Personal Tracker, Asset Tracker, Vehicle Tracker, Pet Tracker, Wearable Tracker Connectivity Technology: Narrowband IoT, LTE-M, Sigfox, LoRaWAN, Zigbee Use Case: Fleet Management, Supply Chain Monitoring, Child Safety, Elderly Assistance, Equipment Tracking End User: Logistics Providers, Telecommunications, Emergency Services, Healthcare Facilities, Sports Organizations |
| Companies Covered | Sierra Wireless, Huawei Technologies Co., Ltd, Ericsson, u-blox AG, Quectel Wireless Solutions, Qualcomm Technologies, Nokia Corporation, Teltonika, Vodafone Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Narrow Band IoT Tracker Market Strategic Shifts & Innovations
Tracker hardware architecture is absorbing adjacent sensing capabilities while cloud platforms compress analytics latency from hours to minutes, reshaping how fleet operators consume location intelligence.
Multi-constellation GNSS receivers with integrated dead reckoning are absorbing inertial measurement unit functions previously housed in separate automotive-grade sensors. Cold chain fleet operators in Germany and the Netherlands are adopting these fused modules to maintain position lock through tunnels and refrigerated warehouse interiors. The structural consequence is absorbing discrete component suppliers into consolidated module vendors capable of delivering turnkey location subsystems.
EU Cybersecurity Resilience Act requirements are mandating firmware update capabilities and encrypted payload transmission as preconditions for CE marking of radio equipment. Hardware vendors must redesign legacy tracker enclosures to accommodate secure element chips and OTA management stacks. Personal tracker segments face the steepest compliance cost escalation due to price-sensitive consumer channels.
Subscription bundling with mobile network operators is displacing upfront hardware purchases in elderly assistance and child safety use cases. MNOs in Spain and Italy are absorbing device costs into monthly service fees, compressing customer acquisition friction. This channel shift favors module suppliers with direct carrier technical approval relationships over independent tracker OEMs lacking operator certification resources.
Narrow Band IoT Tracker Market Segmentation
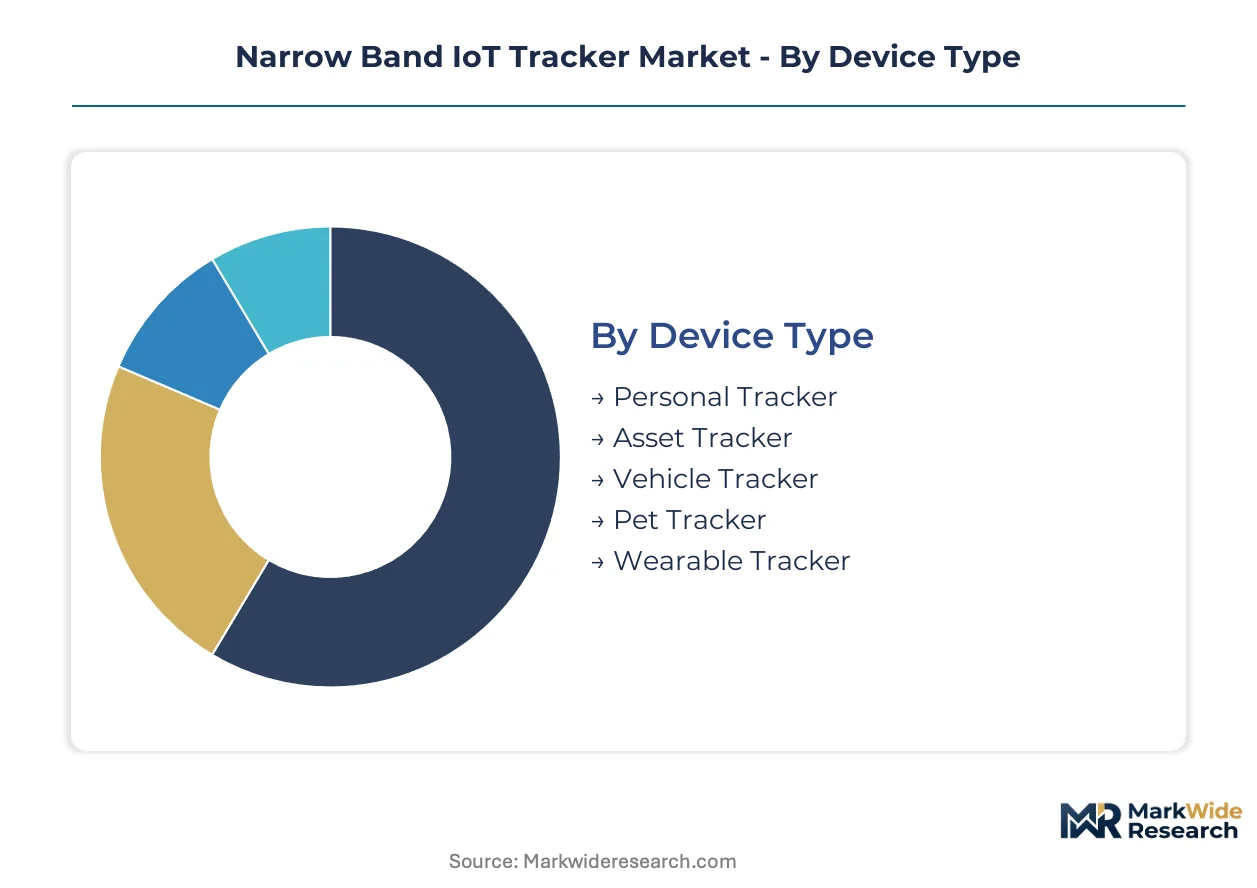
NB-IoT tracker segmentation reveals divergent certification burdens across device categories, with automotive-integrated hardware facing multi-jurisdictional type approval while consumer wearables navigate streamlined personal electronics pathways. Understanding these structural divides clarifies where margin pools concentrate versus where volume scales fastest.
Device Type:
FCC Part 15 and ETSI EN 301 908 compliance timelines vary dramatically across form factors, with vehicle-integrated units requiring NHTSA safety validation alongside radio certification while personal trackers qualify under simplified CE marking routes.
- Personal Tracker:Compact battery-powered units with integrated accelerometers and SOS alerting functions. Demand concentrates in Germany and France among mobile network operator subscription bundles for child safety applications, though elderly assistance programs in Italy are accelerating volume expansion through social services procurement.
- Asset Tracker:Ruggedized enclosures with tamper-detection circuits and multi-mode fallback connectivity. Cold chain operators in the Netherlands and pharmaceutical distributors in Switzerland absorb premium pricing for GDP-compliant temperature logging, generating the dominant margin pool across all device categories.
- Vehicle Tracker:Hardwired installations with CAN bus integration and ignition-sensing capabilities. Automotive OEM mandates in Germany compress certification cycles through factory-level pre-integration rather than aftermarket retrofit.
- Pet Tracker:Lightweight collar-mounted devices with geofencing and activity monitoring. Pet insurance bundling in the United Kingdom reduces upfront purchase friction through veterinary clinic distribution channels.
- Wearable Tracker:Wrist-worn form factors with biometric sensing and fall detection. Healthcare reimbursement pathways in France favor medical-grade certification over consumer electronics classification.
Asset Tracker sits at the top of the volume ranking, with Personal Tracker climbing the fastest.
Connectivity Technology:
Licensed versus unlicensed spectrum choices reshape total cost of ownership calculations, with cellular technologies incurring recurring carrier fees but eliminating private infrastructure deployment.
- Narrowband IoT:3GPP-standardized operation in 200 kHz licensed bands with deep indoor penetration exceeding 20 dB link budget improvement over legacy GPRS. Fleet management operators in Germany mandate embedded NB-IoT for leased vehicle pools, while logistics integrators require cross-border freight visibility without roaming complexity.
- LTE-M:Higher bandwidth cellular alternative supporting voice and mobility handover. North American fleet operators prioritize LTE-M for driver communication integration, though dual-mode chipsets are displacing single-technology procurement.
- Sigfox:Ultra-narrowband proprietary network with national coverage obligations. French industrial asset tracking deployments leverage established national infrastructure for low-payload sensor applications.
- LoRaWAN:Unlicensed spectrum protocol with private gateway deployment options. Warehouse operators in Belgium and Denmark favor captive network control over carrier dependency for indoor inventory tracking.
- Zigbee:Short-range mesh networking for localized proximity awareness. Healthcare facilities in Sweden integrate Zigbee trackers with existing building automation infrastructure for equipment location services.
NB-IoT captures the dominant revenue share, while dual-mode NB-IoT/LTE-M configurations are expanding most quickly.
Use Case:
Regulatory mandates and insurance requirements differentiate commercial from consumer deployment economics, with employer duty-of-care legislation creating non-discretionary procurement in specific verticals.
- Fleet Management:Continuous location telemetry for route optimization and driver behavior monitoring. Electric vehicle fleet operators require battery state integration for charge station routing, with Germany's automotive OEMs mandating embedded connectivity for leased pools.
- Supply Chain Monitoring:Lane-level shipment visibility with temperature and shock logging. Pharmaceutical distributors deploy GDP-compliant tags for cross-border freight, with Swiss and Dutch cold chain operators absorbing premium hardware costs for regulatory documentation.
- Child Safety:Geofencing and SOS alerting for parental peace of mind. Spanish and Italian mobile network operators bundle device costs into monthly subscriptions, compressing customer acquisition friction through retail channel partnerships.
- Elderly Assistance:Fall detection and emergency response for aging-in-place scenarios. French healthcare reimbursement pathways favor medical-grade certification, while German social services programs drive volume through municipal procurement.
- Equipment Tracking:Construction and healthcare asset location for utilization optimization. Swedish healthcare facilities integrate short-range mesh protocols with existing building infrastructure to reduce deployment complexity.
Fleet Management generates the largest revenue concentration, though Supply Chain Monitoring is gaining share fastest on pharmaceutical compliance mandates.
End User:
Procurement sophistication varies from carrier-managed subscription services to in-house IoT platform development, reshaping vendor relationship requirements across customer categories.
- Logistics Providers:Third-party freight and warehousing operators requiring cross-border visibility. German logistics integrators mandate embedded cellular tracking for leased vehicle pools, with certification documentation required for multi-jurisdictional operation.
- Telecommunications:Mobile network operators bundling hardware into service subscriptions. Spanish and Italian MNOs absorb device costs into monthly fees, favoring module suppliers with direct carrier technical approval relationships.
- Emergency Services:Public safety agencies requiring lone worker protection and asset tracking. EU member states are expanding employer duty-of-care legislation to cover isolated field personnel, creating non-discretionary procurement.
- Healthcare Facilities:Hospitals and aged care providers integrating location services with patient care workflows. French reimbursement pathways favor medical-grade device certification over consumer electronics classification.
- Sports Organizations:Professional and amateur athletic programs tracking equipment and participant safety. Retail channel distribution through specialized sporting goods vendors dominates this fragmented demand segment.
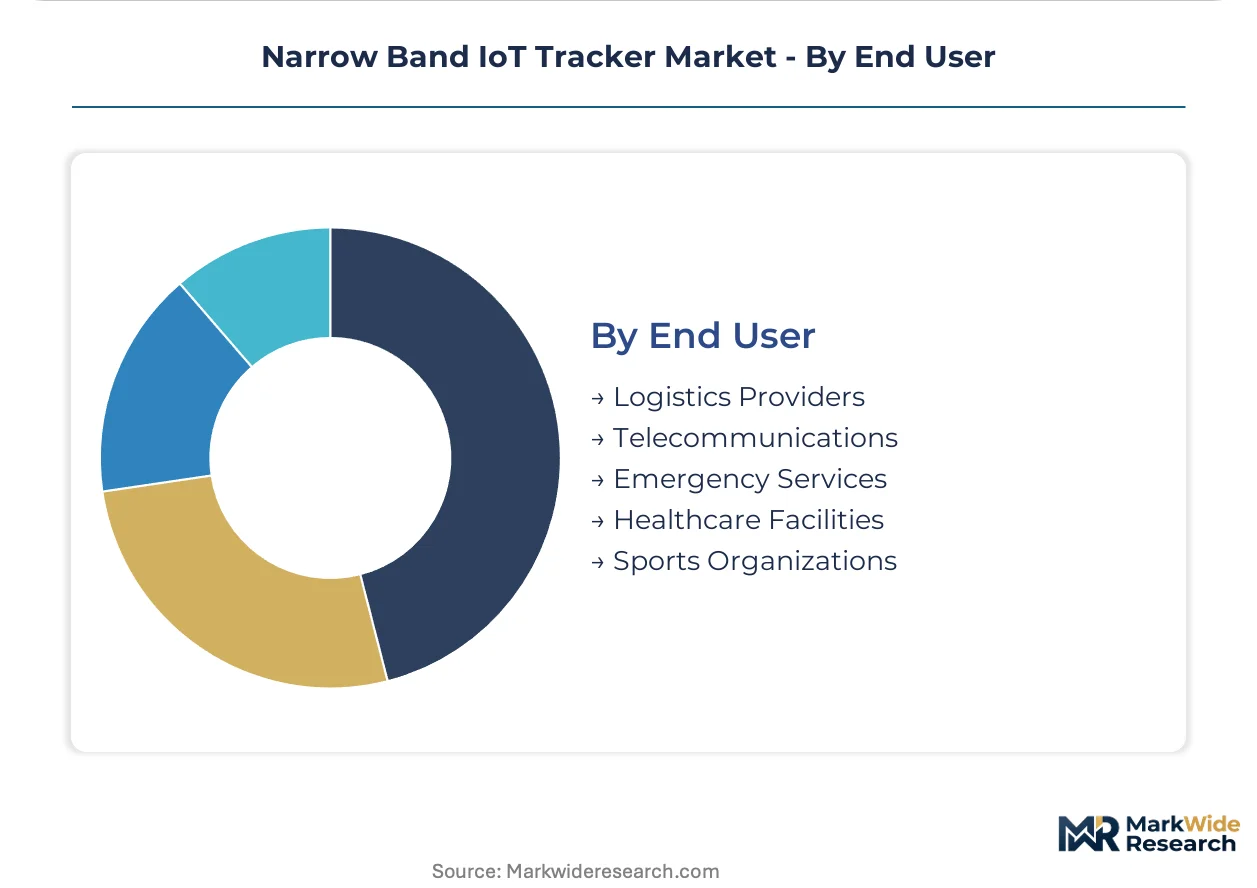
Logistics Providers represent the most concentrated demand base, with Healthcare Facilities expanding most quickly on aging-in-place policy support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive OEM mandates for embedded NB-IoT connectivity contrast with India's logistics modernization push through WPC IMEI registration requirements, revealing how regulatory frameworks reshape deployment economics across mature and emerging tracker markets.
United States
FCC Part 15 and Part 22 rules govern radio emission limits for NB-IoT trackers, with North American fleet operators prioritizing LTE-M integration for driver communication. Sierra Wireless anchors premium supply contracts through certified module portfolios, while logistics providers in the Midwest and Southeast absorb hardware costs into operational budgets for cross-border freight visibility.
Germany
Automotive OEMs and logistics integrators mandate embedded cellular tracking for leased vehicle pools and cross-border freight, compressing hardware certification timelines through factory-level pre-integration. KBA vehicle safety standards intersect with ETSI EN 301 908 radio harmonization, creating multi-jurisdictional approval requirements that favor established module suppliers with regulatory documentation capabilities.
China
MIIT enforces GB/T national standards for cellular IoT terminal radio frequency performance, with module manufacturers repositioning production capacity toward NB-IoT chipsets with integrated GNSS. Shenzhen and Shanghai manufacturing clusters compress lead times for tracker OEMs worldwide, though wafer allocation concentration in domestic foundries creates supply vulnerability for foreign hardware vendors.
India
WPC requires IMEI registration for all imported cellular tracking devices, favoring certified module suppliers with established import documentation capabilities. Logistics modernization programs in Maharashtra and Gujarat accelerate fleet tracker deployments, while pharmaceutical distributors in Hyderabad and Bangalore adopt temperature-logging NB-IoT tags for GDP-compliant cold chain verification.
Netherlands
Cold chain operators absorb premium hardware costs for regulatory documentation, with Rotterdam port logistics and Amsterdam pharmaceutical distribution driving asset tracker demand. ETSI EN 301 908 harmonization enables seamless cross-border operation into Belgian and German freight corridors, reinforcing the country's position as a European logistics integration hub.
Narrow Band IoT Tracker Market Key Industry Players
Chinese producers anchor the manufacturing scale tier; European specialists hold the premium certification tier. The vendor base organizes around module supply concentration, with three to four integrated chipset foundries controlling wafer allocation for GNSS-NB-IoT silicon. Two strategic archetypes dominate: module suppliers with direct carrier technical approval relationships, and tracker OEMs with backward integration into firmware development and cloud platform control. Competitive moves center on M&A for certification portfolio expansion and capacity expansion for integrated GNSS-NB-IoT silicon production.
Within the module supplier tier, Sierra Wireless and Quectel Wireless Solutions occupy positions at opposite ends of the premium-scale spectrum. Sierra Wireless exemplifies the certified module portfolio archetype anchoring North American fleet contracts, while Quectel Wireless Solutions represents the manufacturing scale archetype sustaining cost leadership across personal and asset tracker segments. Teltonika sits within the European vehicle tracker channel archetype, leveraging in-house firmware development and cloud platform control to dominate regional distribution.
| Leading Market Players |
|---|
| Sierra Wireless |
| Huawei Technologies Co., Ltd |
| Ericsson |
| u-blox AG |
| Quectel Wireless Solutions |
| Qualcomm Technologies |
| Nokia Corporation |
| Teltonika |
| Vodafone Group plc |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between automotive-integrated hardware and consumer-grade personal trackers manifests in both pricing stratification and supply chain configuration across German OEM mandates and Asian manufacturing clusters. Premium asset trackers command substantial markups for tamper-detection enclosures and multi-mode fallback connectivity, while subscription bundling through Spanish and Italian mobile network operators compresses upfront hardware costs into recurring service fees.
Pricing Analysis
Distributor margins in European vehicle tracker channels absorb 15-25% of factory gate pricing before fleet operator procurement, while direct-to-OEM contracts for German automotive integrators bypass intermediary layers entirely. Three-tier pricing structure across premium, standard, and economy levels separates GDP-compliant cold chain hardware with temperature logging from basic geofencing personal trackers. Cost compression in consumer wearables intensifies because Chinese module manufacturers reposition production capacity toward integrated GNSS-NB-IoT silicon at scale. Fleet management operators demonstrate lowest price sensitivity due to regulatory mandates and insurance requirements, whereas elderly assistance programs through municipal procurement face acute budget constraints.
Supply Chain Analysis
RF engineering talent scarcity in Shenzhen and Shanghai manufacturing clusters constrains antenna tuning optimization for deep indoor penetration specifications. Wafer allocation for integrated GNSS-NB-IoT silicon concentrates in Chinese foundries, South Korean semiconductor fabrication, and Taiwanese packaging facilities. Component sourcing draws from German automotive-grade sensor suppliers for CAN bus integration, Dutch cold chain enclosure specialists, and Japanese inertial measurement unit vendors. Single-source vulnerability in Chinese chipset foundry capacity creates supply risk for foreign hardware vendors lacking established allocation agreements. Distribution runs through certified module suppliers with direct carrier technical approval relationships rather than independent tracker OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Narrow Band IoT Tracker Market operates as a stable compounder anchored by regulatory mandates for embedded cellular connectivity in leased vehicle pools and cross-border freight visibility requirements.
For Market Incumbents: Extend certification portfolio coverage across FCC Part 15, ETSI EN 301 908, and MIIT GB/T jurisdictions to compress multi-regional approval timelines from fourteen months toward eight. Deepen backward integration into firmware development and cloud platform control to defend margin position against module suppliers encroaching on tracker OEM territory. Address dual-mode NB-IoT and LTE-M convergence as a defensive capability to maintain single-SKU hardware relevance across heterogeneous carrier footprints. For New Entrants and Emerging Players: Enter via Indian logistics modernization programs where WPC IMEI registration requirements favor certified module suppliers with established import documentation capabilities. Target pharmaceutical cold chain monitoring as the most penetrable vertical, where GDP compliance mandates create non-discretionary procurement with premium pricing tolerance. Pursue carrier subscription bundling partnerships in Southern European markets to bypass upfront hardware purchase friction and accelerate customer acquisition velocity. For Investors and Strategic Acquirers: Consolidation pressure builds where module supply concentration in Chinese foundries meets fragmented tracker OEM distribution channels lacking direct carrier relationships. Position the sector for 5-10 year viability through fleet electrification tailwinds and lone worker safety mandate expansion across EU member states. Prioritize acquisition targets with established ETSI EN 301 908 regulatory documentation and in-house secure element chip integration capabilities. Monitor 3GPP Release 14 and beyond standardization timelines as the critical signal for firmware architecture obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdictional Certification Investment | ETSI EN 301 908 and FCC Part 15 pre-approval accelerates German automotive OEM factory integration timelines. |
| Dual-Mode Chipset Integration | NB-IoT and LTE-M convergence enables single-SKU hardware roaming across North American and European carrier footprints. |
| Carrier Technical Approval Partnerships | Direct MNO relationships in Spain and Italy unlock subscription bundling channels for personal tracker volume expansion. |
| Secure Element Chip Architecture | EU Cybersecurity Resilience Act compliance mandates encrypted payload transmission for CE marking eligibility. |
| Backward Integration into Firmware | In-house OTA management stack development differentiates European vehicle tracker vendors from module-only suppliers. |
Research Approach
Bottom-up fleet operator and logistics provider modeling reconciled against top-down module shipment and chipset foundry tracking forms the analytical core of this study. Primary interviews with cellular module procurement directors, fleet management technology officers, automotive OEM platform engineers, and pharmaceutical supply chain compliance managers were cross-validated against secondary sources including 3GPP release documentation, FCC equipment authorization databases, ETSI harmonized standards filings, and carrier network coverage disclosures. Trade data from customs authorities in Germany, China, and India provided volume triangulation for import certification pathways.
Input-output matrices mapping NB-IoT modem integration rates, GNSS receiver adoption curves, and temperature sensor attachment frequencies drove segment-level projections across the analysis window. Modeled dimensions span device type, connectivity technology, use case, and end user procurement sophistication, with CAGRs derived from regression against 3GPP standardization milestone timing and automotive OEM embedded connectivity mandate rollouts. Forecast inputs include wafer allocation announcements from integrated chipset foundries and carrier network deployment capex disclosures for licensed spectrum coverage expansion.
Inputs from primary fieldwork and regulatory filing databases were available through the study window; gaps in real-time carrier subscription bundling contract terms introduce uncertainty bands around personal tracker volume assumptions. Forecasts reflect documented assumptions regarding 3GPP Release 13 hardware certification cycle compression and fleet electrification telemetry requirements. Material deviation in Chinese foundry wafer allocation policy or EU cybersecurity certification timeline acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
M2M Communication Market
Internet of Things (IoT)
IIOT Gateway for Utility Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
IoT Communication Technologies Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
Global Satellite Enabled IoT Software Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Wifi IoT Market
Internet of Things (IoT)
Middle East and Africa IoT Node and Gateway Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
Massive Machine Type Communication Market
Internet of Things (IoT)
Global IoT in Warehouse Market
Internet of Things (IoT)
IoT Gateway Devices Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
IoT IAM Market