
 Mass Spectroscopy Market | 2026-2036
Mass Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
Mass Spectroscopy Market Outlook
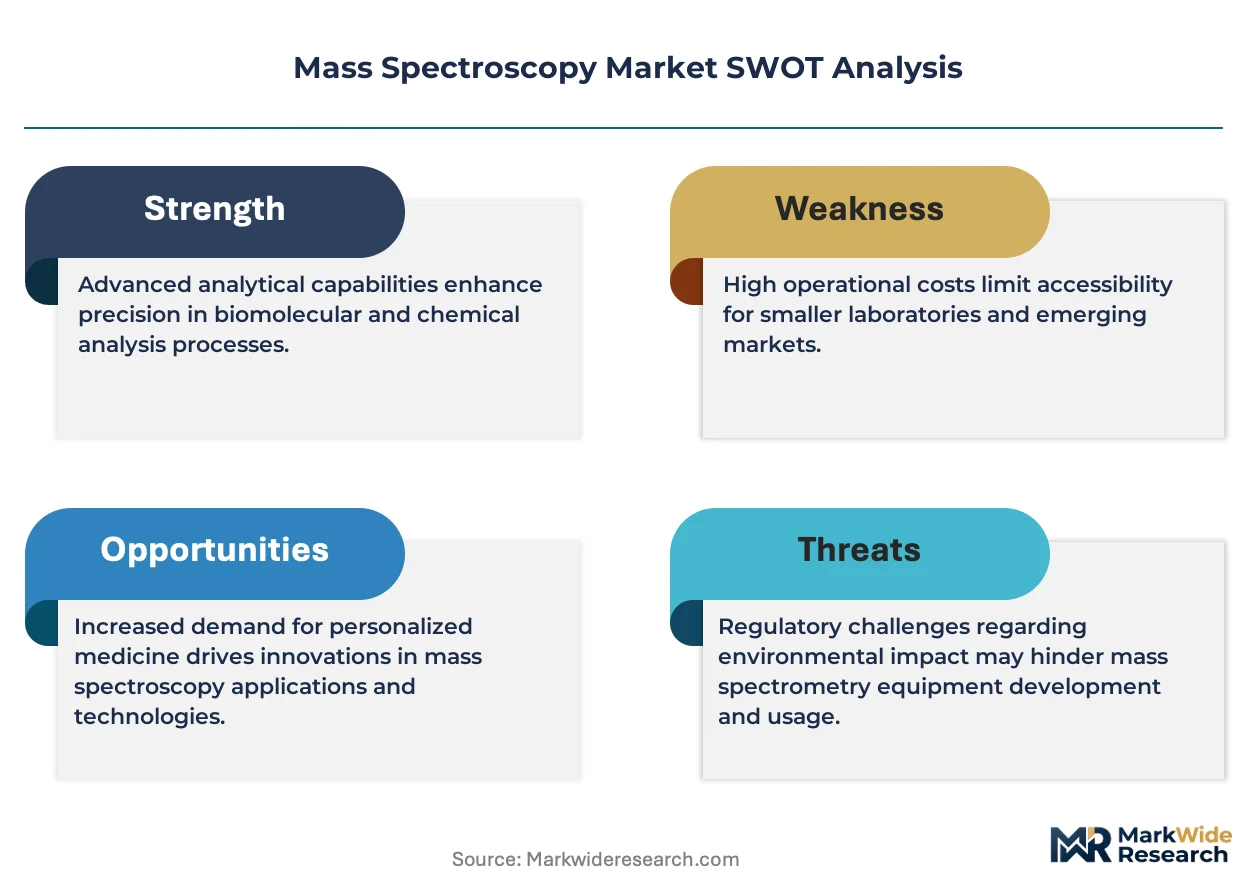
The EU Green Deal is broadening requirements for contaminant traceability across industrial supply chains. Thermo Fisher Scientific leverages its vertical integration in chromatography-mass spectrometry workflows to sustain premium positioning in pharmaceutical quality control. Agilent Technologies anchors its competitive stance through R&D intensity in quadrupole time-of-flight platforms. Danaher Corporation differentiates via geographic dominance in clinical diagnostics laboratories across North America and Europe.
Mass spectroscopy identifies molecules by measuring mass-to-charge ratios of ionized particles, typically achieving resolution below 1 ppm in Orbitrap configurations and enabling quantification at femtogram sensitivity levels for proteomics and metabolomics applications. Triple quadrupole systems dominate routine pharmaceutical analysis due to established validation protocols and reproducible quantification workflows. Time-of-flight technology leads growth in biotherapeutic characterization where exact mass determination of large proteins and antibody-drug conjugates determines regulatory submission success. Ion trap platforms occupy a mature position in academic research settings where cost constraints outweigh throughput requirements.
FDA bioanalytical method validation guidelines and EMA ICH Q2(R1) standards shape instrument procurement criteria for pharmaceutical companies seeking regulatory approval across multiple jurisdictions. EPA methods under the Safe Drinking Water Act and REACH substance authorization requirements in Europe mandate specific detection limits that directly determine mass spectrometer sensitivity specifications. ISO 17025 accreditation requirements for testing laboratories further constrain vendor selection to platforms with documented compliance packages. Stakeholders must monitor evolving PFAS regulatory thresholds and gene therapy analytical guidance documents to anticipate platform upgrade cycles and service revenue opportunities.
Market Dynamics
Regulatory enforcement across multiple jurisdictions is compressing instrument replacement cycles as laboratories race to meet tightening detection thresholds for contaminants and biotherapeutics. This structural pressure overrides traditional capital equipment longevity norms.
Growth Catalysts
- EPA PFAS monitoring mandates:The Safe Drinking Water Act now requires sub-parts-per-trillion detection capabilities, forcing water utilities and environmental labs to upgrade from legacy GC-MS platforms to high-resolution accurate mass systems.
- Biopharma characterization complexity:Antibody-drug conjugates and gene therapy vectors demand exact mass determination for regulatory submission, pulling triple quadrupole users toward time-of-flight and Orbitrap architectures.
- China's dual carbon goals:MEE enforcement of industrial emissions monitoring is accelerating domestic procurement of portable mass spectrometry for real-time stack monitoring and fugitive emission detection.
Market Restraints
- Helium supply concentration:Qatar and the United States control over 75% of global helium production, creating input cost volatility for gas chromatography-mass spectrometry systems dependent on high-purity carrier gas.
- Technical limitation in ambient ionization:Reproducibility challenges in direct analysis in real time and desorption electrospray ionization methods constrain deployment outside controlled laboratory environments.
- REACH authorization friction:ECHA substance authorization timelines for novel ionization reagents delay method validation and commercial rollout of next-generation workflows.
Strategic Opportunities
- India's PLI scheme for pharmaceuticals:Domestic API manufacturing incentives are creating demand for in-house quality control laboratories requiring LC-MS/MS systems for impurity profiling.
- Clinical diagnostics convergence:Mass spectrometry is penetrating newborn screening and therapeutic drug monitoring workflows previously dominated by immunoassay platforms.
- EU AI Act compliance infrastructure:Automated spectral interpretation and machine learning-driven compound identification tools must meet transparency requirements, creating service revenue for validated algorithm deployment.
Industry Challenges
- Mass spectrometrist talent scarcity:Universities produce insufficient PhD-level analytical chemists capable of method development for complex biotherapeutic characterization.
- ISO 17025 accreditation timelines:Testing laboratories face 12-18 month validation periods for new platforms, delaying revenue generation post-procurement.
- Legacy data system integration:Enterprise LIMS architectures from the 2000s lack native support for high-resolution data file formats, requiring middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mass Spectroscopy Market |
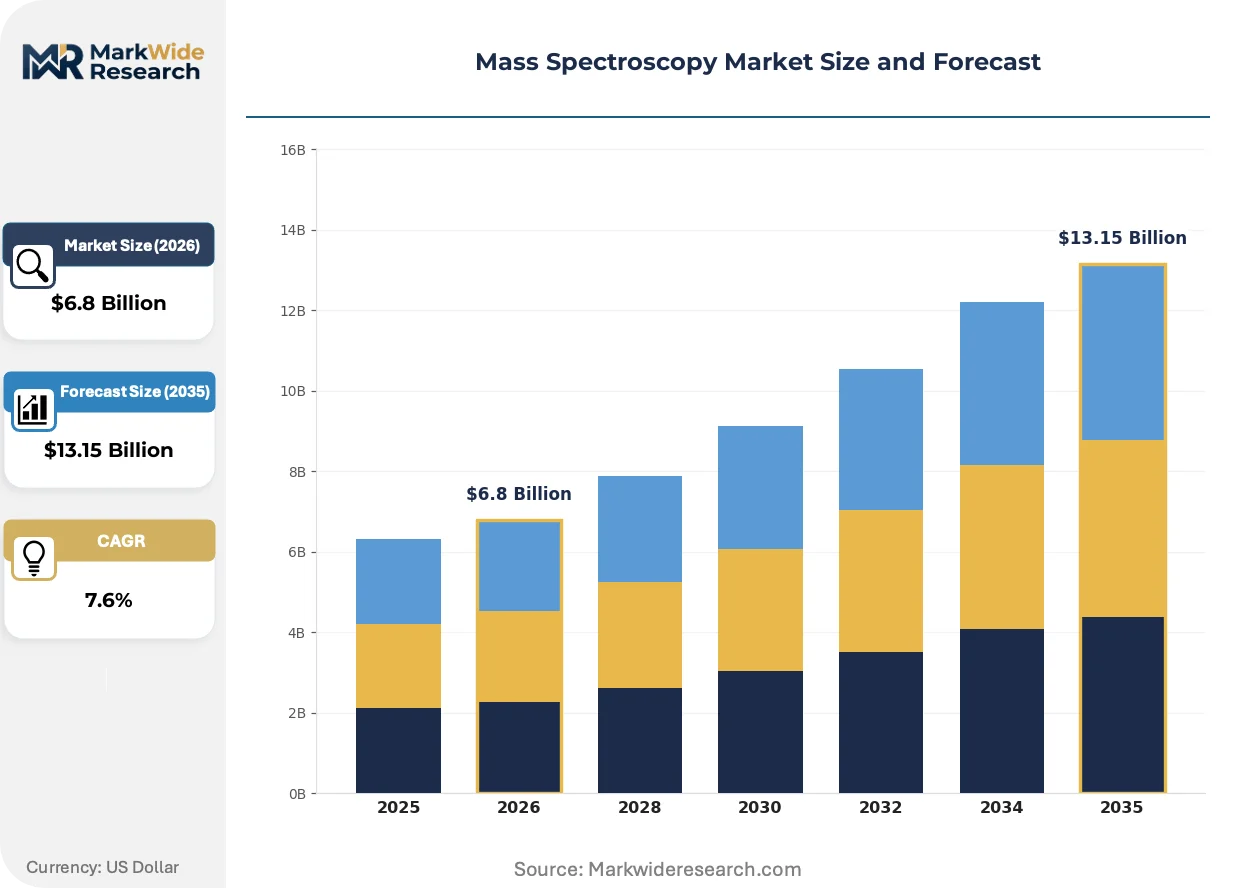
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Quadrupole, Triple Quadrupole, Time-of-Flight, Ion Trap Application: Pharmaceutical Analysis, Environmental Testing, Food Safety, Forensic Analysis End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Contract Research Organizations Technology: Matrix-Assisted Laser Desorption Ionization, Electrospray Ionization, Gas Chromatography Coupling, Liquid Chromatography Coupling |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies Inc., Danaher Corporation, Waters Corporation, Bruker Corporation, Shimadzu Corporation, PerkinElmer Inc., JEOL Ltd., Rigaku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mass Spectroscopy Market Strategic Shifts
Workflow automation and artificial intelligence integration are compressing method development timelines while expanding operator accessibility beyond specialist PhD users. These shifts are reconfiguring competitive differentiation away from raw sensitivity specifications.
High-resolution accurate mass spectrometry is consolidating routine pharmaceutical analysis workflows previously fragmented across multiple platforms. Contract development and manufacturing organizations are standardizing on quadrupole time-of-flight systems for both small molecule and large molecule characterization. This platform convergence is compressing vendor switching costs while elevating service and software capabilities as primary selection criteria.
REACH substance authorization requirements and EPA method updates are synchronizing detection limit specifications across Atlantic regulatory regimes. Industrial laboratories serving multinational pharmaceutical clients must now validate methods against both EMA ICH Q2(R1) and FDA bioanalytical guidance simultaneously. This regulatory harmonization pressure is favoring vendors with pre-packaged compliance documentation and multi-jurisdiction validation support.
After-sales service unbundling is disrupting traditional instrument procurement models in academic and government laboratory segments. Buyers are separating hardware acquisition from maintenance contracts and software subscriptions, pressuring vendor recurring revenue streams. This behavioral shift is most visible in German and United States research universities where centralized procurement offices now mandate multi-vendor service benchmarking.
Mass Spectroscopy Market Segmentation
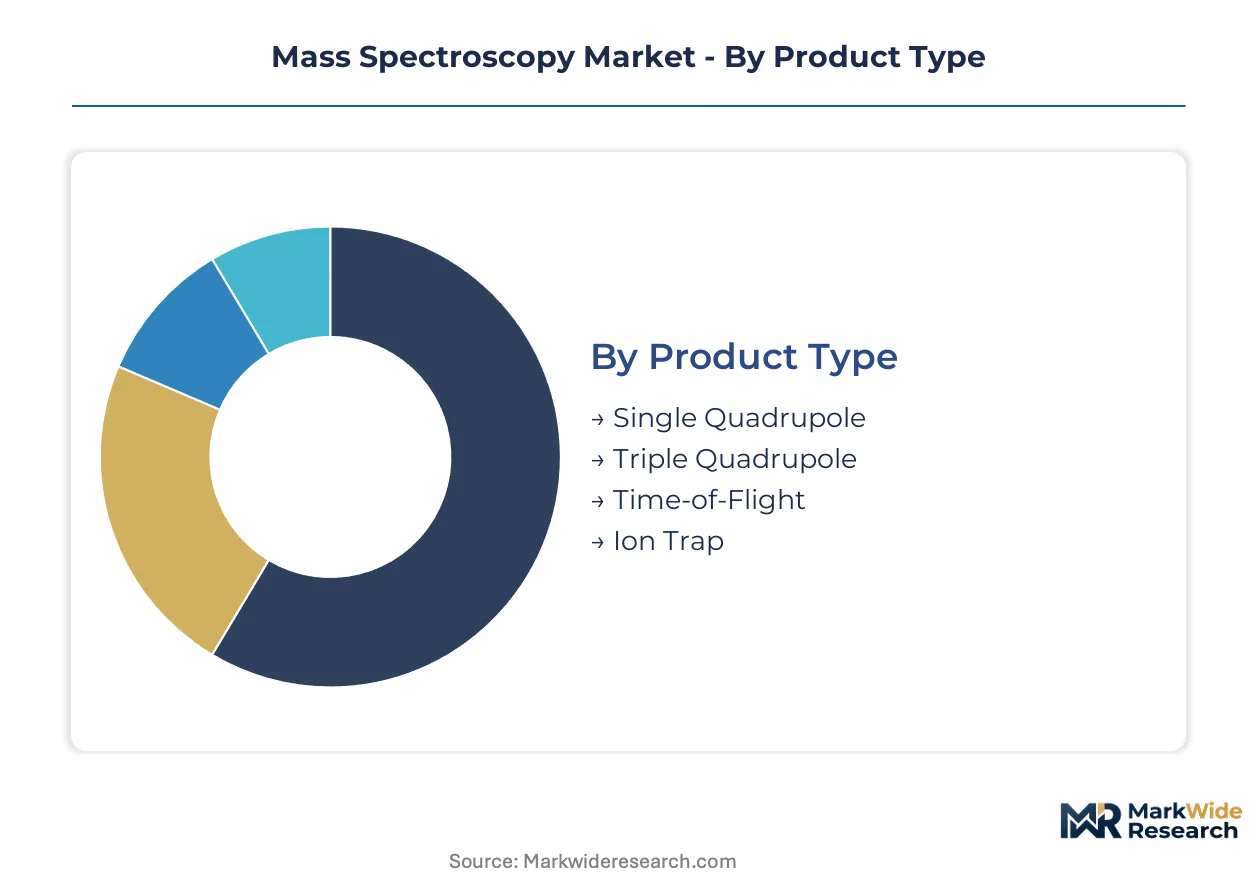
Mass spectrometry segmentation reveals distinct procurement patterns across integration depths. Standalone systems dominate high-throughput pharmaceutical workflows while coupled configurations expand in environmental and food safety applications where sample complexity demands chromatographic separation.
Product Type:
Standalone architectures anchor routine quantification workflows, while hybrid platforms embed into multi-technique analytical suites for biotherapeutic characterization.
- Triple Quadrupole:Tandem mass filtering enables selective reaction monitoring with established validation protocols under FDA bioanalytical guidelines. Pharmaceutical quality control laboratories in the United States and Germany standardize on these platforms for bioanalytical method validation, driven by reproducible quantification requirements for generic drug submissions.
- Time-of-Flight:Exact mass determination at sub-5 ppm resolution supports intact protein analysis and antibody-drug conjugate characterization. Biopharma CMOs in Switzerland and Massachusetts concentrate procurement here, pulled by EMA and FDA demands for molecular weight confirmation in regulatory filings.
- Single Quadrupole:Unit mass resolution suits routine environmental screening where cost constraints limit capital expenditure.
- Ion Trap:MSn fragmentation capabilities serve academic research settings with limited throughput demands.
Volume placements concentrate in Triple Quadrupole systems; the faster expansion belongs to Time-of-Flight platforms.
Application:
Regulatory enforcement intensity creates divergent margin profiles across use cases, with pharmaceutical and environmental segments commanding premium pricing for compliance documentation.
- Pharmaceutical Analysis:Impurity profiling, bioanalytical method validation, and biotherapeutic characterization consume over half of high-resolution system placements. FDA ICH Q3D elemental impurity guidelines and EMA forced degradation study requirements drive replacement cycles in United States and European quality control laboratories.
- Environmental Testing:EPA PFAS monitoring mandates under the Safe Drinking Water Act compel sub-ppt detection capabilities. Commercial laboratories in California and North Rhine-Westphalia upgrade from legacy GC-MS to LC-HRMS architectures, constrained by helium supply volatility affecting gas chromatography workflows.
- Food Safety:Pesticide residue screening and veterinary drug detection align with EU Regulation 396/2005 maximum residue limits.
- Forensic Analysis:Toxicology confirmation and seized substance identification operate under ISO 17025 accreditation timelines that delay platform validation.
Revenue concentration sits with Pharmaceutical Analysis; Environmental Testing claims the steepest expansion trajectory as detection thresholds tighten.
End User:
Procurement authority varies by organizational scale, with centralized purchasing offices in academic consortia unbundling service contracts from hardware acquisition.
- Pharmaceutical Companies:In-house analytical development groups prioritize vendor compliance packages supporting multi-jurisdiction submissions. Roche, Novartis, and Pfizer operations in Basel and New Jersey standardize on quadrupole time-of-flight systems for both small and large molecule workflows.
- Contract Research Organizations:Platform flexibility determines competitive positioning for bioanalytical service contracts. WuXi AppTec and Charles River facilities in China and Massachusetts concentrate investment in triple quadrupole redundancy to meet sponsor audit requirements.
- Clinical Laboratories:Newborn screening and therapeutic drug monitoring applications displace immunoassay platforms in state public health laboratories.
- Research Institutions:Grant-funded principal investigators face delayed replacement cycles due to federal budget uncertainty affecting NIH and DFG allocations.
Capital deployment concentrates in Pharmaceutical Companies; CROs are climbing the fastest as sponsor outsourcing accelerates.
Technology:
Ionization source selection constrains sample compatibility, with electrospray dominating polar analytes and MALDI enabling spatially resolved tissue imaging.
- Liquid Chromatography Coupling:Reverse-phase separation combined with electrospray ionization addresses non-volatile pharmaceuticals and biologics. Waters and Agilent installations in Boston and Cambridge clusters default to this configuration for proteomics and metabolomics workflows.
- Electrospray Ionization:Soft ionization preserves non-covalent protein complexes for native mass spectrometry applications. Structural biology facilities at the Scripps Research Institute and Max Planck Institute deploy these sources for cryo-EM validation studies.
- Matrix-Assisted Laser Desorption Ionization:Spatial resolution at 10-50 micrometers supports MALDI imaging mass spectrometry for tissue-based biomarker discovery.
- Gas Chromatography Coupling:Volatile and semi-volatile analysis persists in environmental laboratories despite helium supply constraints driving hydrogen carrier gas method redevelopment.
Installed base concentrates in Liquid Chromatography Coupling; MALDI is gaining share fastest in spatial omics applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and Cambridge anchor pharmaceutical mass spectrometry procurement in the United States, with Basel and New Jersey following as secondary concentration nodes for biopharma characterization workflows.
United States
EPA PFAS monitoring mandates under the Safe Drinking Water Act compel water utilities and environmental laboratories to upgrade from legacy GC-MS to high-resolution accurate mass systems. FDA bioanalytical method validation guidelines shape instrument procurement criteria for pharmaceutical companies seeking multi-jurisdiction approval. Roche and Pfizer operations in New Jersey standardize on quadrupole time-of-flight platforms for both small and large molecule workflows.
Germany
North Rhine-Westphalia environmental laboratories face REACH substance authorization timelines that delay method validation for novel ionization reagents. EMA ICH Q2(R1) standards drive replacement cycles in quality control facilities serving generic drug manufacturers. Bavarian research universities unbundle service contracts from hardware acquisition, pressuring vendor recurring revenue through centralized procurement benchmarking.
China
MEE enforcement of industrial emissions monitoring accelerates domestic procurement of portable mass spectrometry for real-time stack monitoring. Dual carbon goals tighten detection thresholds for fugitive emission detection across manufacturing corridors. WuXi AppTec facilities concentrate investment in triple quadrupole redundancy to meet sponsor audit requirements for bioanalytical service contracts.
Switzerland
Novartis and Roche analytical development groups prioritize vendor compliance packages supporting EMA and FDA simultaneous submissions. Swissmedic regulatory demands for biotherapeutic characterization pull contract manufacturing organizations toward time-of-flight architectures. Basel pharmaceutical clusters drive exact mass determination requirements for antibody-drug conjugate regulatory filings.
India
PLI scheme incentives for domestic API manufacturing create demand for in-house quality control laboratories requiring LC-MS/MS systems. CDSCO impurity profiling standards align with ICH Q3D elemental impurity guidelines for pharmaceutical exports. Maharashtra and Gujarat pharmaceutical manufacturing zones concentrate procurement of triple quadrupole platforms for generic drug quality control.
Mass Spectroscopy Market Competitive Environment
The competitive structure tilts toward diversified life science conglomerates with chromatography-mass spectrometry workflow integration. Three archetypes dominate: full-platform integrators coupling hardware with compliance documentation, component specialists advancing ionization source architectures, and regional service organizations capturing maintenance contract unbundling trends. M&A activity concentrates on software and spectral database assets, while geographic expansion targets India's PLI-driven laboratory buildout and China's domestic procurement preferences.
Among diversified instrument conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify full-platform integration archetypes, while Agilent Technologies Inc. occupies a position within the analytical workflow specialist tier. These entities anchor competitive dynamics through service infrastructure scale and multi-jurisdiction validation support capabilities rather than hardware specifications alone.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| Danaher Corporation |
| Waters Corporation |
| Bruker Corporation |
| Shimadzu Corporation |
| PerkinElmer Inc. |
| JEOL Ltd. |
| Rigaku Corporation |
| Others |
Value Chain & Pricing Dynamics
EPA PFAS monitoring mandates forcing sub-parts-per-trillion detection specifications compel environmental laboratories and water utilities toward high-resolution accurate mass systems, reshaping supplier pricing power around compliance documentation bundles rather than hardware specifications alone. This procurement preference shift elevates vendors with pre-packaged FDA and EMA validation support while compressing margins for platforms lacking multi-jurisdiction certification packages.
Pricing Analysis
Value-based pricing anchored to regulatory submission success dominates pharmaceutical procurement, with quadrupole time-of-flight platforms commanding premium positioning based on exact mass determination capabilities for antibody-drug conjugate characterization. Price differentiation rests on ISO 17025 accreditation tier and after-sales service bundling, with academic buyers unbundling maintenance contracts to drive cost compression. Pricing pressure intensifies in the single quadrupole segment as helium supply volatility elevates total cost of ownership for gas chromatography-mass spectrometry workflows. Contract research organizations exhibit highest price sensitivity due to sponsor audit cost pass-through constraints, while biopharma quality control laboratories prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Refurbishment and remanufacturing flows for ion trap and single quadrupole systems extend asset lifecycles in academic settings, creating secondary market pressure on new equipment pricing. Component manufacturing concentrates in the United States, Germany, and Japan, with precision mass analyzer fabrication drawing from specialized vacuum technology and high-voltage electronics suppliers. Raw material dependencies include high-purity helium for gas chromatography coupling, rare earth magnets for ion optics, and specialized ceramics for detector assemblies. Single-source vulnerability in helium supply from Qatar and the United States creates input cost volatility. Distribution runs through direct sales teams for pharmaceutical accounts and regional distributors serving environmental testing laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mass spectrometry market sits in a technology-transition phase as time-of-flight and Orbitrap architectures displace triple quadrupole dominance in biopharma characterization workflows, compressing replacement cycles and reconfiguring vendor competitive positioning around software and service capabilities.
For Market Incumbents: Acquire spectral database and machine learning algorithm assets to differentiate beyond hardware specifications as artificial intelligence integration reshapes method development workflows. Consolidate service infrastructure in India's PLI-driven pharmaceutical manufacturing zones and China's domestic procurement corridors to defend against regional challengers. Counter the threat of after-sales contract unbundling by embedding compliance documentation into subscription-tiered software offerings that lock in recurring revenue streams. For New Entrants and Emerging Players: Contract research organizations in India and China represent the most penetrable channel partner type, given sponsor outsourcing acceleration and limited incumbent service density. Target portable mass spectrometry for China's MEE industrial emissions monitoring enforcement as a white-space application with domestic procurement preference tailwinds. Pursue a service-first go-to-market angle unbundling maintenance from hardware acquisition to exploit centralized procurement benchmarking trends in German and United States research universities. For Investors and Strategic Acquirers: Re-rating potential sits with software-centric mass spectrometry specialists given EU AI Act compliance infrastructure requirements for automated spectral interpretation tools. Long-term viability over the next decade favors vendors with validated algorithm deployment capabilities and multi-jurisdiction regulatory submission support. Monitor PFAS regulatory threshold tightening and gene therapy analytical guidance document releases as inflection indicators for platform upgrade cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Spectral Database Assets | Machine learning-driven compound identification meets EU AI Act transparency requirements for automated interpretation tools. |
| Service Infrastructure Expansion | India's PLI scheme for domestic API manufacturing creates demand for in-house quality control laboratory buildout. |
| Compliance Documentation Bundling | FDA bioanalytical guidelines and EMA ICH Q2(R1) standards shape instrument procurement criteria for multi-jurisdiction submissions. |
| Portable System Development | China's MEE enforcement of industrial emissions monitoring accelerates domestic procurement for real-time stack monitoring. |
| Software Subscription Tiering | After-sales service unbundling in academic segments pressures vendors to embed recurring revenue in validated algorithm deployment. |
Study Parameters
FDA 510(k) filings, EMA scientific advice letters, and EPA method update notifications formed the secondary backbone, cross-referenced against SEC 10-K instrument revenue disclosures and NIH procurement databases. Primary interviews with analytical development directors at biopharma quality control laboratories, regulatory affairs leads at contract manufacturing organizations, and service operations managers at environmental testing facilities validated demand-side assumptions. Bottom-up triangulation across instrument placement volumes by technology type converged with top-down market sizing derived from vendor-reported segment revenues.
Historical trendline analysis across triple quadrupole, time-of-flight, and Orbitrap installation bases established baseline penetration rates, with forward projections incorporating technology substitution elasticity between platforms. Segmentation dimensions modeled include product architecture, application workflow, end-user organizational type, and ionization source configuration, with regional regulatory enforcement intensity serving as an additional geographic overlay. CAGRs were derived from replacement cycle compression analysis and detection threshold tightening trajectories, incorporating helium supply volatility and mass spectrometrist talent scarcity as supply-side constraints.
Several conditions sit outside the modeled scope, including unforeseen breakthroughs in ambient ionization reproducibility and radical shifts in federal research funding allocations affecting academic procurement. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and vendor compliance package standardization. Practitioners should monitor EPA PFAS method finalization dates and ECHA substance authorization decisions for early signals of platform upgrade acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Portable Infrared Digital Thermometer Market
Analytical Instruments
Thermoluminescent Dosimeter (TLD) System Market
Analytical Instruments
Atomic Spectroscopy Market
Analytical Instruments
Elemental Analyzer Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Global Potentiostat Market
Analytical Instruments
Global Q-TOF Mass Spectrometry Market
Analytical Instruments
Flame Spectrometers Market
Analytical Instruments
Abbe Refractometers Market
Analytical Instruments
Spectrometry Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market
Analytical Instruments
Infrared Spectroscopy Devices Market
Analytical Instruments
Electrochemistry Meters Market
Analytical Instruments
Europe Surface Analysis Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Real-Time Spectrum Analysis Market