
 Spectrometry Market | 2026-2036
Spectrometry Market Size, Share, and Industry Trends Forecast 2026-2036
Spectrometry Market Intelligence
Aftermarket service and consumables revenue is fragmenting as third-party providers challenge original equipment manufacturer contracts. Thermo Fisher Scientific, Inc. leverages its extensive installed base to secure long-term service agreements. Agilent Technologies, Inc. competes by offering integrated workflow solutions that bundle instruments with specialized software and support. Shimadzu Corporation differentiates through its focus on specific high-growth applications in Asia-Pacific markets.
Spectrometry is the analytical technique used to measure the interaction of matter with electromagnetic radiation. Instruments operate by quantifying the absorption, emission, or scattering of energy at specific wavelengths to identify and quantify substances. Mass spectrometers command the largest revenue share due to their high sensitivity and broad use in pharmaceutical research. In terms of application, environmental analysis and food safety testing represent the fastest-growing segments, driven by heightened regulatory scrutiny.
Regulatory frameworks are a primary market accelerant, with mandates from the US EPA and the EU's REACH regulation dictating testing protocols. Compliance with China's GB standards for food and environmental safety also necessitates advanced spectrometry equipment. Instrument vendors must decide whether to pursue broad, multi-application platforms or specialize in high-margin, niche analytical workflows.
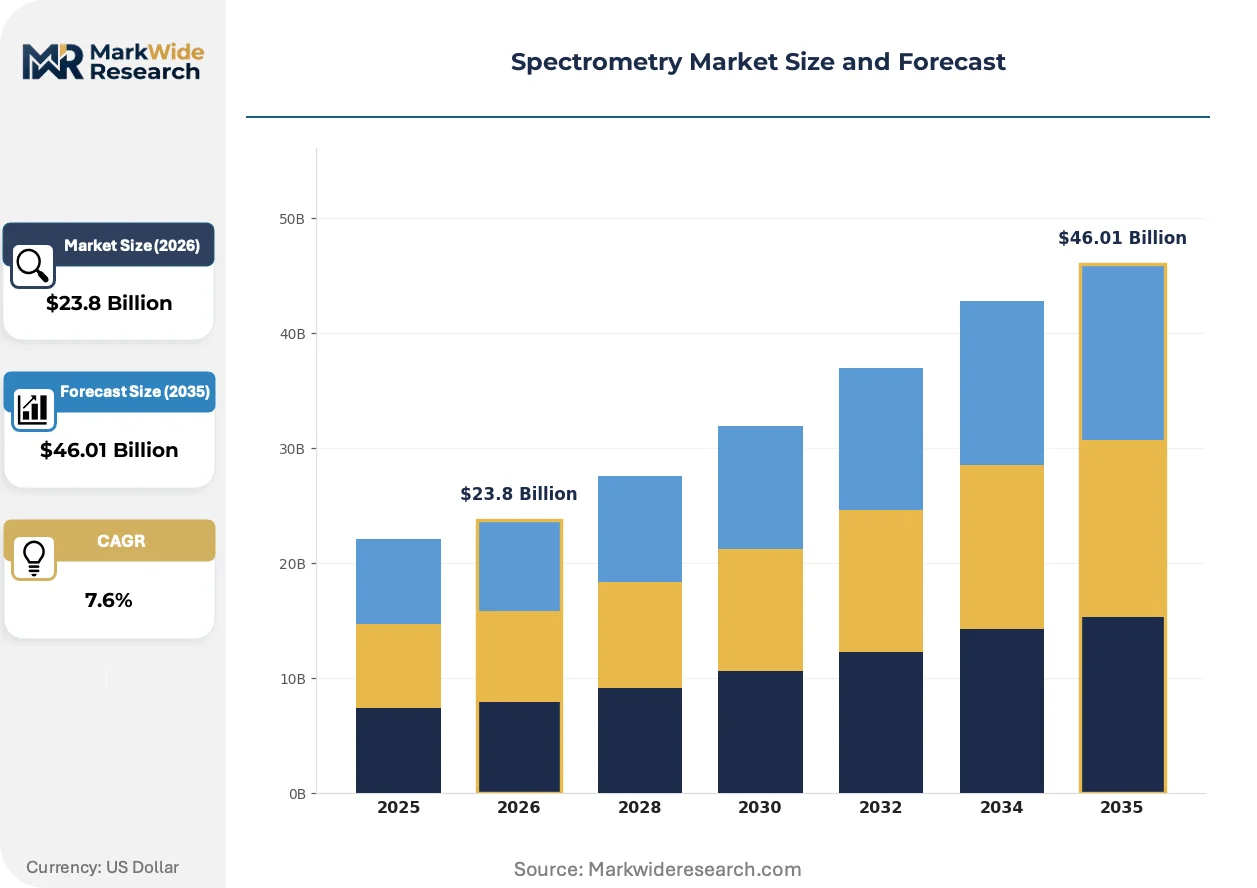
Market Dynamics
The expansion of regulatory mandates, particularly the US EPA's methods for PFAS analysis and the EU's REACH framework, is the central force compelling investment in higher-performance spectrometry instruments across industrial and environmental laboratories.
Growth Catalysts
- Expanding Regulations:Stricter contaminant limits under the EU's REACH and China's GB standards require investment in more sensitive detection technology for compliance.
- Pharmaceutical Research:Growth in biologics research sustains demand for high-resolution mass spectrometry in drug discovery and quality control workflows.
- CRO Growth in Asia:The concentration of contract research organizations in India and China provides localized demand for analytical instrumentation.
Market Restraints
- High Capital Cost:The significant upfront investment for high-performance mass spectrometers limits adoption by smaller, budget-constrained laboratories and academic institutions.
- Specialized Labor Requirement:Advanced systems demand highly skilled operators for method development and data interpretation, creating a talent bottleneck for end-users.
- Component Bottlenecks:Supply of critical parts like specialized detectors is concentrated among a few vendors, posing a risk to instrument production schedules.
Strategic Opportunities
- Portable Systems:Miniaturization enables portable spectrometers for on-site environmental testing and food authentication, opening new field-based applications.
- AI-Powered Analytics:Integrating AI and machine learning automates spectral interpretation, reducing analysis time and reliance on expert-level human review.
- Service Expansion in LATAM:Building direct service infrastructure in Brazil and Mexico can capture demand from their growing pharmaceutical and environmental testing industries.
Industry Challenges
- Data Integration Complexity:Integrating high-throughput spectrometry data with existing Laboratory Information Management Systems (LIMS) presents significant software and workflow challenges for labs.
- Method Standardization Delays:A lack of standardized methods for new analytes like microplastics delays regulatory acceptance and slows commercial test adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spectrometry Market |
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $46.01 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mass Spectrometers, Atomic Absorption Spectrometers, Infrared Spectrometers, UV-Visible Spectrometers, Nuclear Magnetic Resonance Spectrometers Technology: Time-of-Flight, Quadrupole, Ion Trap, Fourier Transform, Laser Induced Breakdown Application: Environmental Analysis, Food Safety Testing, Pharmaceutical Research, Petrochemical Evaluation, Material Characterization End User: Academic Institutions, Contract Research Organizations, Biotech Enterprises, Chemical Manufacturers, Quality Control Laboratories |
| Companies Covered | Thermo Fisher Scientific, Inc., Agilent Technologies, Inc., PerkinElmer, Inc., Waters Corporation, Shimadzu Corporation, Bruker Corporation, JEOL Ltd., MKS Instruments, Inc., Rigaku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spectrometry Market Strategic Shifts & Innovations
The convergence of hardware miniaturization with intelligent data processing is transforming spectrometry from a centralized laboratory function to a distributed analytical capability. This shift prioritizes speed-to-result and operational simplicity in a growing number of applications.
Advanced software incorporating artificial intelligence now automates spectral library matching and peak deconvolution. Contract testing laboratories and academic research groups are adopting these tools to accelerate data interpretation. This automated analysis is rendering obsolete the time-consuming manual review of complex datasets by highly trained specialists, compressing project timelines.
Regulatory frameworks in Asia are creating specific instrument requirements for market access. For instance, China's updated GB standards for food safety mandate lower detection limits for pesticides and veterinary drug residues. This forces food exporters and domestic producers to upgrade from older HPLC systems to more sensitive LC-MS/MS platforms to ensure compliance.
Service and support models are unbundling from instrument sales, challenging the traditional OEM-dominated ecosystem. Large pharmaceutical and chemical companies are increasingly using qualified third-party independent service organizations (ISOs) for routine maintenance and calibration. This shift is most prominent in mature markets like North America and Western Europe, where cost optimization is a primary focus.
Spectrometry Market Segmentation
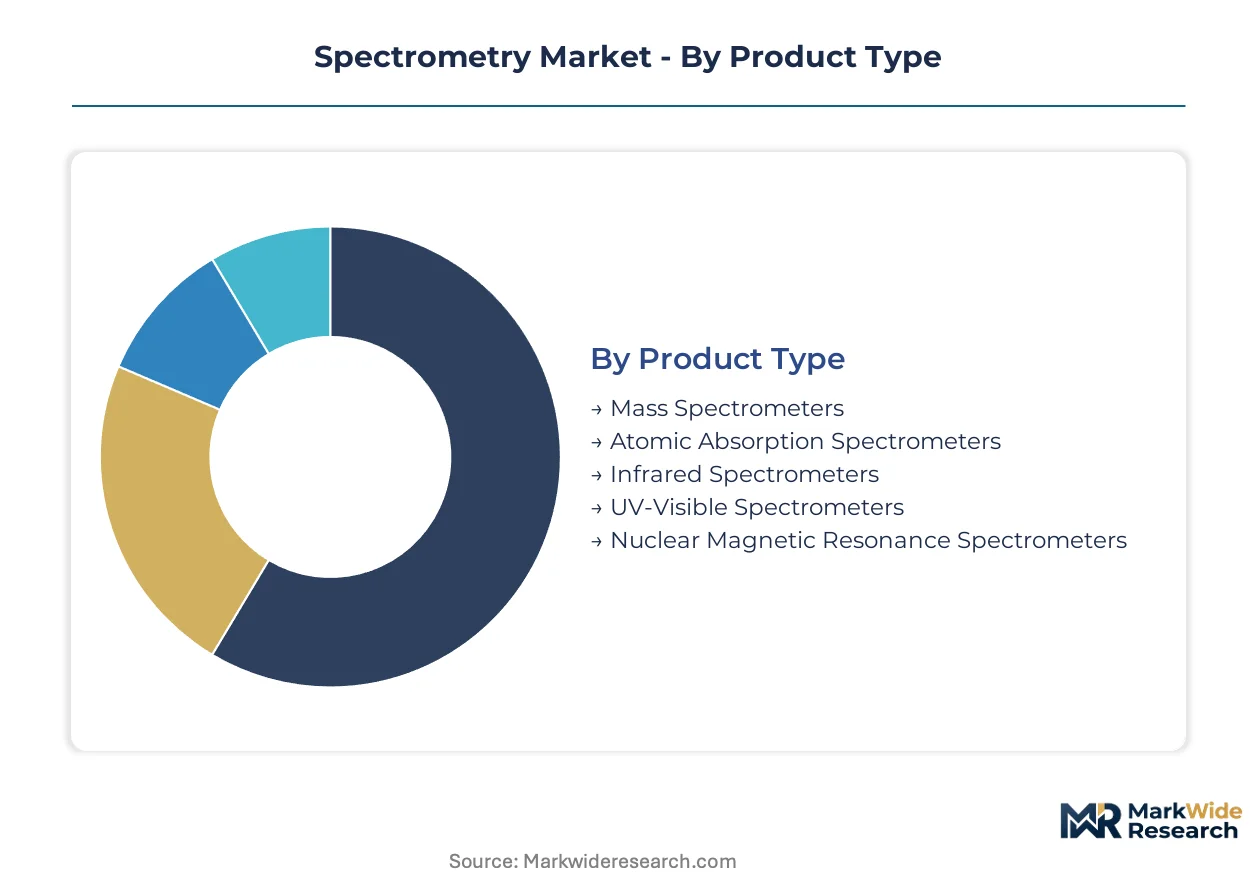
The spectrometry market's diverse segmentation reflects varying technical requirements and end-user priorities across industries. Understanding these distinct segments is crucial for instrument manufacturers to tailor product development and service offerings effectively. Each category highlights specific demand patterns and operational characteristics within the analytical landscape.
Product Type:
Product type segmentation reveals a spectrum of instrument turnover rates, from rapidly evolving high-throughput systems to established, long-lifecycle analytical workhorses.
- Mass Spectrometers:These instruments quantify mass-to-charge ratios of ions, offering high sensitivity and specificity for molecular identification. Pharmaceutical research in the US drives demand for high-resolution mass spectrometry in drug discovery.
- UV-Visible Spectrometers:Measuring light absorption in ultraviolet and visible regions, these systems provide versatile quantitative analysis for various compounds. Quality control laboratories in China adopt UV-Vis for routine purity checks.
- Atomic Absorption Spectrometers:These instruments detect elemental concentrations by measuring light absorbed by free atoms. Environmental analysis uses AAS for heavy metal detection.
- Infrared Spectrometers:Infrared spectrometers identify functional groups in molecules through their vibrational modes. Material characterization relies on IR for polymer analysis.
- Nuclear Magnetic Resonance Spectrometers:NMR systems determine molecular structure by exploiting magnetic properties of atomic nuclei. Academic institutions employ NMR for advanced chemical research.
Mass Spectrometers anchors the volume base while UV-Visible Spectrometers gains share at the steepest rate.
Technology:
Technology segmentation highlights distinct cost structures and performance capabilities, from entry-level systems to highly specialized, capital-intensive platforms.
- Time-of-Flight:ToF measures ion flight time through a vacuum to determine mass-to-charge ratio, offering high resolution and fast data acquisition. Biotech enterprises demand ToF for rapid protein identification and metabolomics studies.
- Quadrupole:Quadrupole mass filters separate ions based on stability in an oscillating electric field, known for robustness and cost-effectiveness. Environmental analysis in the EU employs quadrupole systems for routine contaminant screening.
- Ion Trap:Ion trap technology confines ions in a small volume for mass analysis, enabling multiple stages of mass spectrometry. Pharmaceutical research uses ion traps.
- Fourier Transform:Fourier Transform systems achieve ultra-high resolution and mass accuracy by analyzing transient signals. Academic research groups leverage FT for detailed molecular characterization.
- Laser Induced Breakdown:LIBS uses a high-energy laser to ablate a sample, generating a plasma for elemental analysis. Material characterization in India applies LIBS for rapid in-situ composition.
The market for Time-of-Flight technologies is expanding most quickly, driven by demand for high-throughput analysis.
Application:
Application segmentation delineates the varying analytical volumes and regulatory stringencies that define market demand across different sectors.
- Pharmaceutical Research:This application involves spectrometry for drug discovery, development, and quality control, including compound identification and impurity profiling. The US FDA's stringent requirements sustain high demand for advanced mass spectrometry.
- Environmental Analysis:Spectrometry in environmental analysis focuses on detecting pollutants and contaminants in air, water, and soil matrices. The US EPA's methods for PFAS analysis drive significant investment.
- Food Safety Testing:This application uses spectrometry to detect pesticides, additives, and contaminants in food products. China's GB standards for food safety mandate advanced equipment.
- Petrochemical Evaluation:Spectrometry in petrochemicals analyzes crude oil, refined products, and natural gas for composition and quality. Chemical manufacturers use these systems for process optimization.
- Material Characterization:This application uses spectrometry to determine chemical composition and structural properties of various materials. Quality control laboratories employ spectrometry for polymer analysis.
Regulatory mandates from the US EPA and China's GB standards are propelling the Environmental Analysis and Food Safety Testing segments forward.
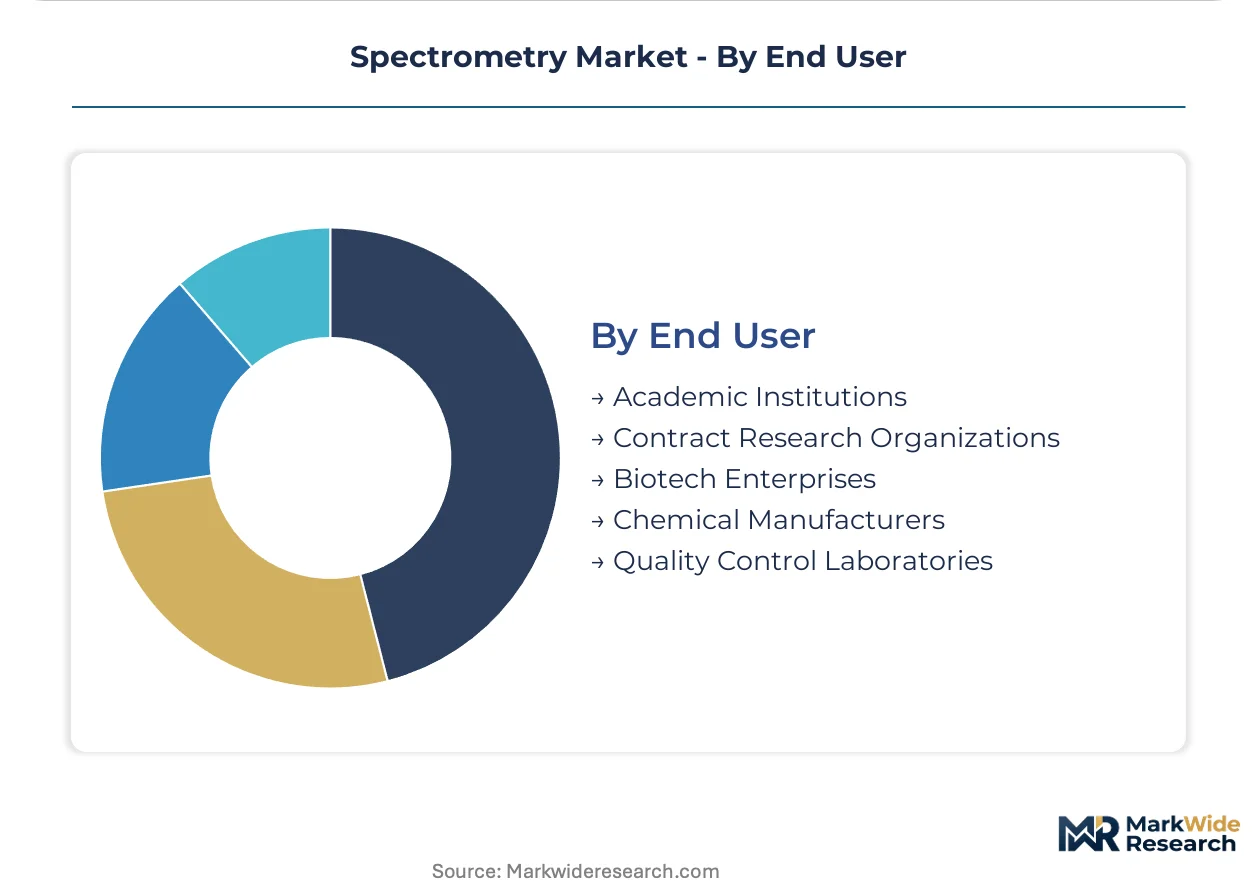
End User:
End-user segmentation differentiates customer types based on their operational scale, research focus, and budget constraints for analytical instrumentation.
- Contract Research Organizations:CROs provide outsourced research services to pharmaceutical and biotech companies, driving demand for high-throughput and regulatory-compliant spectrometry. Their concentration in India and China generates localized demand.
- Quality Control Laboratories:These laboratories perform routine testing to ensure product quality and compliance with industry standards and regulations. Stricter mandates from the US FDA compel these labs to upgrade to more sensitive technologies.
- Academic Institutions:Universities and research institutes use spectrometry for fundamental scientific research and training. Budget constraints often influence adoption of cutting-edge systems.
- Biotech Enterprises:Biotech companies utilize spectrometry for biopharmaceutical development, protein characterization, and drug discovery. Their rapid innovation cycles require versatile analytical tools.
- Chemical Manufacturers:Chemical producers employ spectrometry for process monitoring, quality assurance, and product development. These users prioritize robust, high-throughput systems.
Contract Research Organizations contribute significantly to market expansion, while Quality Control Laboratories represent a stable, compliance-driven demand base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for spectrometry instruments varies across global markets; price sensitivity is higher for mature applications in established economies, while growing industries in developing nations prioritize advanced capabilities regardless of initial cost.
United States
Pharmaceutical research and environmental analysis drive substantial demand for spectrometry instruments. The US FDA mandates stringent quality control for drug manufacturing, compelling technology upgrades for impurity profiling. Furthermore, US EPA methods for PFAS analysis continue to drive significant investment in high-performance systems. The Boston biotech cluster and California's research institutions lead in high-resolution mass spectrometry adoption.
China
Food safety testing and contract research organizations fuel considerable demand for advanced spectrometry. China's GB standards for food and environmental safety necessitate advanced equipment for contaminant detection. The Yangtze River Delta region, with its dense CRO presence, generates localized demand for high-throughput analytical instrumentation. This concentrated activity supports continuous market expansion.
Germany
Advanced chemical manufacturing and pharmaceutical research and development sustain a robust market for spectrometry. The EU's REACH regulation dictates comprehensive testing protocols for industrial chemicals, requiring sophisticated analytical tools. EMA guidelines also influence pharmaceutical quality assurance processes. Bavaria's strong automotive and chemical industries invest in material characterization and process monitoring technologies.
India
Contract research organizations and petrochemical evaluation contribute significantly to market growth. India's FSSAI standards for food products and CDSCO regulations for pharmaceuticals compel technology upgrades across various laboratories. Hyderabad and Bengaluru, as major pharmaceutical and biotech hubs, show significant demand for high-throughput systems. This localized concentration supports instrument sales.
Japan
Academic research and advanced materials science applications underpin stable demand for spectrometry equipment. JIS standards influence quality control and R&D processes in various manufacturing sectors. PMDA requirements impact pharmaceutical development workflows. The Kanto region, encompassing Tokyo, hosts numerous research institutions and electronics manufacturers utilizing advanced spectrometry for innovation.
Spectrometry Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered competitive structure within the spectrometry market. The market exhibits consolidation among established players offering broad portfolios across multiple technologies. Strategic archetypes include integrated solution providers, niche technology specialists, and regional value-focused suppliers. Dominant competitive moves involve strategic partnerships for software integration, targeted portfolio diversification into high-growth application areas, and geographic expansion into emerging economies.
On the premium-tier vector, Thermo Fisher Scientific, Inc. and Agilent Technologies, Inc. exemplify companies with extensive installed bases and integrated workflow offerings. These US-based corporations focus on comprehensive analytical solutions, often bundling instruments with specialized software and long-term service agreements. Shimadzu Corporation, a Japan-based entity, occupies a strong position by differentiating through its focus on specific high-growth applications, particularly within Asia-Pacific markets. These players anchor the market's innovation and quality benchmarks, driving continuous advancements in spectrometry capabilities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Agilent Technologies, Inc. |
| PerkinElmer, Inc. |
| Waters Corporation |
| Shimadzu Corporation |
| Bruker Corporation |
| JEOL Ltd. |
| MKS Instruments, Inc. |
| Rigaku Corporation |
| Others |
Cost & Logistics Intelligence
Underutilized manufacturing capacity in specialized detector production influences supplier behavior and instrument pricing. This dynamic impacts the ability of vendors to offer competitive rates for high-performance spectrometry systems.
Pricing Analysis
Aftermarket service and long-term contracts represent a significant portion of instrument lifetime value for spectrometry vendors. The dominant pricing structure is value-based, bundling instruments with specialized software and support. Price differentiation arises from customization levels for specific analytical workflows and the brand premium associated with established OEMs. Pricing softness stems from increasing competition from third-party service providers. Academic institutions exhibit the highest price sensitivity, while large pharmaceutical companies show the least.
Supply Chain Analysis
Extended payment terms for critical components like specialized detectors often shape the supply chain for spectrometry instruments. Geographic supply concentration for these advanced parts centers in Germany, Japan, and the United States. Key raw material dependencies include high-purity optical components and specific electronic sub-assemblies. Single-source vulnerability for specialized detectors poses a structural risk to instrument production schedules. Distribution runs through direct sales channels and specialized regional distributors, particularly for high-end systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spectrometry market requires a substitution defense as incumbents navigate the threat of distributed analytical capabilities. Miniaturized portable systems and AI-powered analytics challenge traditional centralized laboratory functions.
For Market Incumbents: Harden intellectual property around proprietary spectral libraries and advanced data processing algorithms to counter emerging software solutions. Pursue strategic partnerships with AI firms to integrate automated spectral interpretation directly into instrument platforms, offsetting the talent bottleneck for end-users. Invest in capacity expansion for high-resolution mass spectrometry components to mitigate component bottlenecks and secure supply.
For New Entrants and Emerging Players: Niche applications in on-site environmental testing and rapid food authentication represent the most penetrable entry points for portable spectrometry. Develop specialized AI-driven software for specific regulatory compliance needs, such as China's GB standards for food safety. A direct-to-consumer digital sales model for portable, user-friendly devices can capture demand from smaller laboratories and field operations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated solution providers offering bundled software and long-term service agreements. Long-term viability rests on platforms that can adapt to evolving regulatory mandates and integrate advanced data analytics. Target mid-sized technology specialists with strong intellectual property in AI-powered spectral interpretation or miniaturized sensor development. The signal to watch is the market acceptance rate for portable, field-deployable spectrometry solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating AI-powered analytics into existing spectrometry platforms accelerates data interpretation and reduces reliance on expert operators. |
| Geographic Expansion | Targeting Latin American markets like Brazil and Mexico captures demand from growing pharmaceutical and environmental testing sectors. |
| Licensing Agreement | Securing licenses for specialized detector technology mitigates component bottleneck risks and diversifies supply sources. |
| Product Launch | Introducing miniaturized, portable spectrometry systems opens new field-based applications for environmental and food safety testing. |
| Strategic Partnership | Collaborating with contract research organizations in Asia-Pacific strengthens localized demand for high-throughput analytical instrumentation. |
Research Approach
A spread of perspectives from R&D directors, quality control managers, procurement leads, and academic researchers converged on the working assumptions for this spectrometry market analysis. This involved combining primary interviews with industry stakeholders and validating insights through extensive secondary research. Secondary data sources included regulatory filings from the US FDA and EMA, scientific publications, and trade association reports. Bottom-up market sizing was reconciled with top-down industry trends through iterative triangulation.
Demand-supply-balance modeling formed the core of the quantitative analytical framework applied across the analysis window. Segmentation dimensions modeled included product type, technology, application, and end-user, alongside regional regulatory clusters. Compound annual growth rates were derived from historical data analysis and projected market drivers. Key forecast inputs included anticipated regulatory changes, such as new US EPA methods for PFAS analysis, and the expansion of pharmaceutical research budgets.
Macroeconomic conditions sit as an overlay; deviation in global R&D spending or supply chain stability would shift the trajectory. Forecasts reflect assumptions documented regarding technological advancements and regulatory enforcement. Geopolitical events or unforeseen component shortages also represent specific risk factors. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Particle Counters Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
Fluorescence Spectroscopy Market
Analytical Instruments
Portable Particle Counter Market
Analytical Instruments
Global Atomic Absorption Spectrometer Market
Analytical Instruments
Seawater Refractometers Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Europe Handheld Spectrum Analyzer Market
Analytical Instruments
North America Liquid Chromatography Devices Market
Analytical Instruments
Microchip Electrophoresis Market
Analytical Instruments
Global TOC Analyzer Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Surface Plasmon Resonance Instrument Market