
 Thermoluminescent Dosimeter (TLD) System Market | 2026-2036
Thermoluminescent Dosimeter (TLD) System Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoluminescent Dosimeter (TLD) System Market Insights
Lithium fluoride is recalibrating cost-performance tradeoffs across passive dosimetry platforms. Mirion Technologies leverages its installed base in nuclear power utilities to sustain service revenue streams. Fuji Electric anchors its position through backward integration into phosphor crystal manufacturing. Thermo Fisher Scientific differentiates via channel control across hospital group purchasing organizations in North America.
A thermoluminescent dosimeter system measures ionizing radiation exposure by detecting light emitted from crystalline materials—typically lithium fluoride or calcium fluoride—when heated following radiation absorption, with sensitivity thresholds reaching microgray precision for clinical applications. The system's primary commercial purpose centers on regulatory-mandated personnel monitoring and treatment verification in medical radiation environments. Multi-element dosimeters capture the fastest-growing application share as proton therapy and stereotactic body radiotherapy demand multi-point depth-dose profiling. Hospitals represent the most mature end-user category, while research institutions occupy the margin-rich frontier for custom TLD array configurations.
The FDA enforces 21 CFR Part 1020 performance standards for diagnostic x-ray equipment, directly shaping TLD accuracy requirements and calibration protocols for clinical dosimetry providers. The Nuclear Regulatory Commission mandates 10 CFR Part 20 personnel monitoring rules that institutionalize quarterly TLD badge exchange cycles across licensed medical and industrial facilities. Stakeholders must monitor NRC's anticipated rulemaking on cumulative occupational dose limits, as stricter thresholds would compress replacement cycles and expand addressable unit volumes across hospital radiation safety programs.
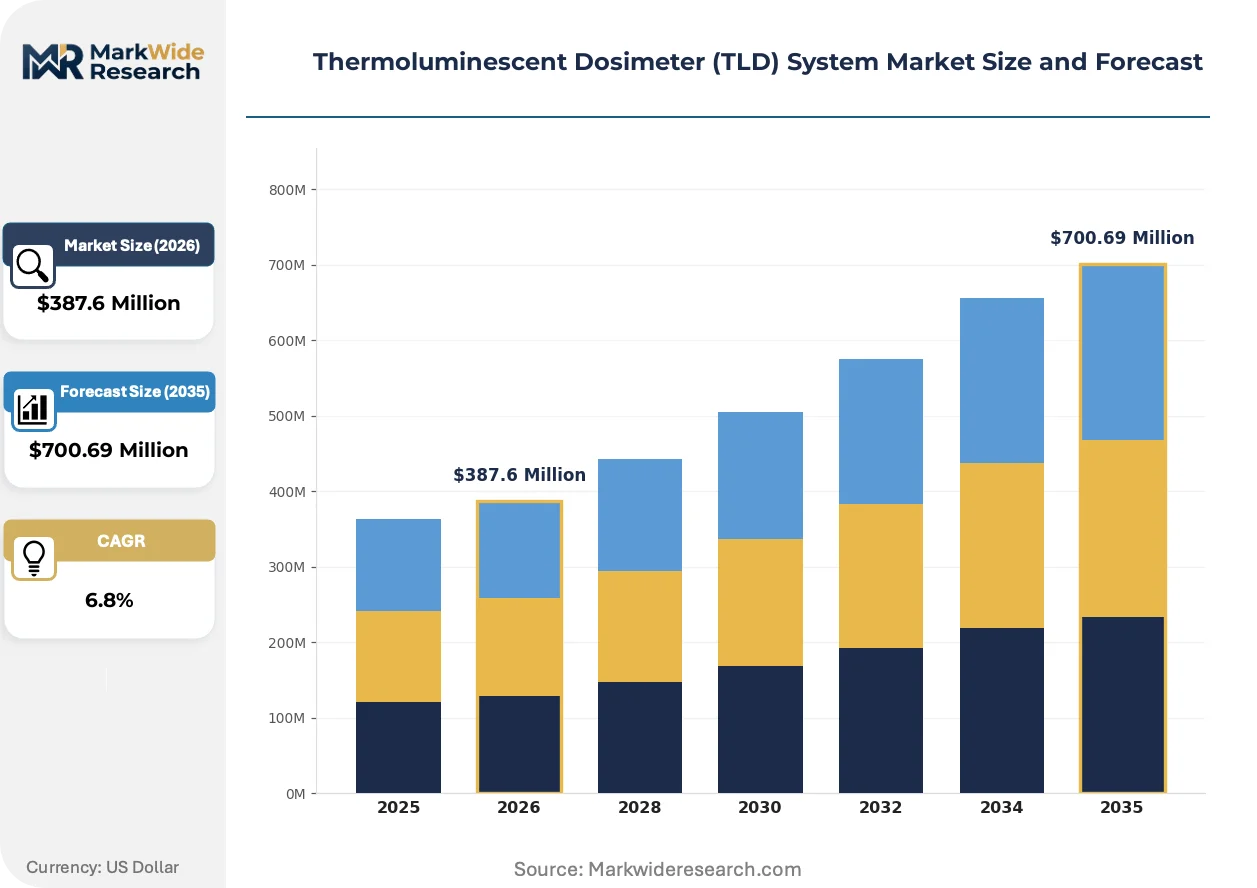
Market Dynamics
Proton therapy center construction is compressing replacement cycles for legacy film-badge systems across academic medical centers, while lithium fluoride phosphor manufacturing concentrates among three integrated suppliers.
Growth Catalysts
- FDA 21 CFR Part 1020:Tightening accuracy requirements for diagnostic x-ray systems are forcing hospitals to upgrade dosimetry calibration protocols, expanding TLD verification service contracts.
- Multi-element dosimeter arrays:Stereotactic body radiotherapy and proton therapy facilities require depth-dose profiling across multiple tissue-equivalent points, driving badge complexity per user.
- Nuclear Regulatory Commission 10 CFR Part 20:Mandatory quarterly personnel monitoring cycles institutionalize recurring badge exchange revenue across licensed medical and industrial facilities.
Market Restraints
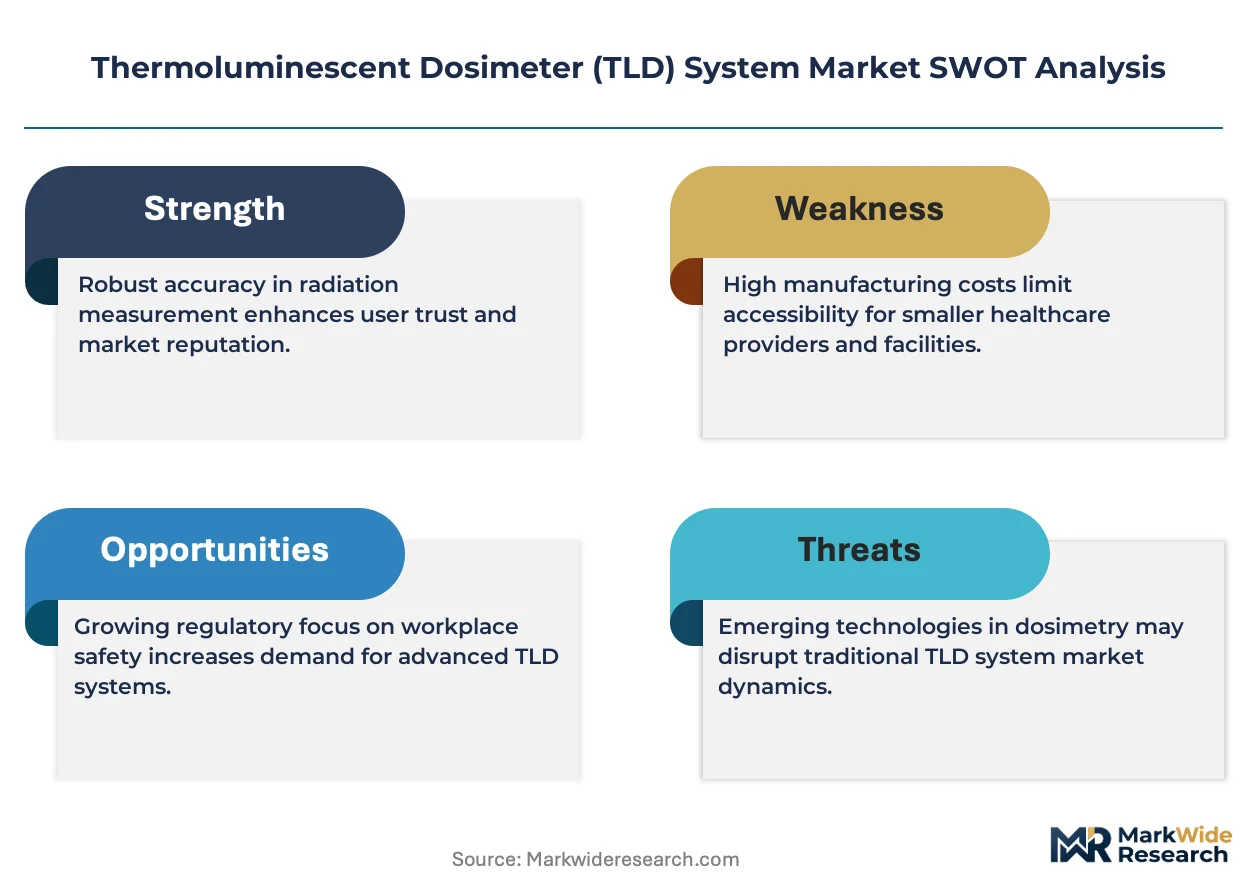
- Phosphor crystal supply concentration:Backward integration into lithium fluoride manufacturing limits qualified supplier pool to three integrated producers, creating single-source vulnerability for specialty dopant formulations.
- Optically stimulated luminescence substitution:OSL badges from Landauer and Mirion offer instant readout without heating infrastructure, threatening TLD's installed base in high-throughput occupational monitoring programs.
- Heater element maintenance burden:TLD readers require periodic thermocouple calibration and platinum resistance validation, elevating total cost of ownership versus solid-state alternatives.
Strategic Opportunities
- Carbon ion therapy expansion:Japan's National Institute of Radiological Sciences and Germany's Heidelberg Ion Beam Therapy Center are piloting TLD arrays for mixed-field dosimetry where neutron contribution complicates passive measurements.
- Research institution customization:Custom TLD array configurations for microbeam radiography and FLASH dose-rate experiments command 40-60% margin premiums over standard personnel badges.
- NRC cumulative dose rulemaking:Anticipated tightening of occupational exposure thresholds would compress replacement cycles from quarterly to monthly across interventional radiology suites.
Industry Challenges
- Annealing protocol standardization:Pre-irradiation thermal treatment cycles vary by phosphor batch and reader geometry, complicating multi-site clinical trial dosimetry reconciliation.
- Legacy reader integration:Hospital radiation safety offices maintain 15-20 year-old Harshaw 3500 and 4500 readers, creating firmware incompatibility with modern lithium fluoride chip geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoluminescent Dosimeter (TLD) System Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Element Dosimeters, Multi-Element Dosimeters, Rechargeable Dosimeters, Non-Rechargeable Dosimeters Application: Radiation Therapy, Nuclear Medicine, Radiology, Environmental Monitoring End User: Hospitals, Research Institutions, Industrial Facilities, Academic Institutions Technology: Optically Stimulated Luminescence, Thermoluminescent Detection, Passive Dosimetry, Real-Time Monitoring |
| Companies Covered | Fuji Electric, ATOMTEX, Mirion Technologies, Unfors RaySafe, Aloka, Landauer, IBA Dosimetry, Tracerco, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoluminescent Dosimeter (TLD) System Market Trends and Innovations
Digital integration is reshaping how passive dosimetry data flows into hospital information systems, while phosphor material science unlocks sensitivity thresholds previously reserved for active detectors.
Carbon-doped aluminum oxide is electrifying ultra-high sensitivity applications by delivering nanogray resolution for diagnostic reference dosimetry. Major proton therapy centers in the United States and Germany are validating OSL-based systems for annual calibration audits. This convergence is compressing the performance gap between passive and active dosimetry, forcing TLD manufacturers to defend position through NIST-traceable calibration networks rather than raw sensitivity specifications.
Europe's Medical Device Regulation is reclassifying TLD readers from Class I to Class IIa, imposing clinical evidence requirements and notified body involvement on hardware manufacturers. The 2017/745 MDR transition deadlines have already triggered portfolio rationalization among smaller European dosimetry service providers. German and French hospital procurement offices are consolidating vendor lists to suppliers with full MDR technical documentation, favoring integrated service providers over component specialists.
Hospital group purchasing organizations are unbundling dosimetry badge supply from reader maintenance contracts, enabling radiation safety officers to negotiate separate service-level agreements for hardware uptime versus phosphor logistics. This disintermediation is most visible in the United States, where Premier and Vizient members now source badges directly from Mirion while contracting regional service technicians for annual reader calibration.
Thermoluminescent Dosimeter (TLD) System Market Segmentation
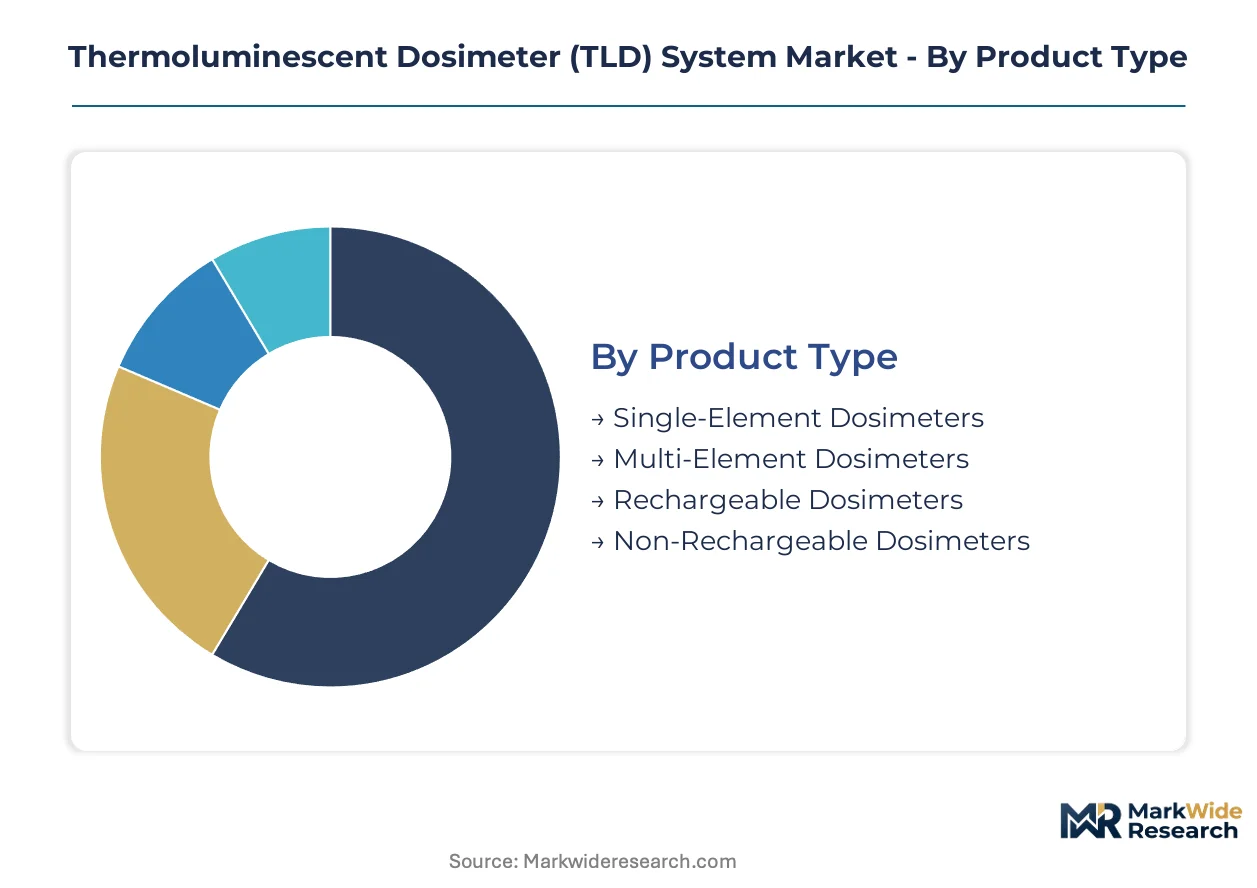
TLD procurement decisions hinge on precision requirements and regulatory exposure. Buyers weigh phosphor sensitivity against reader infrastructure costs, while proton therapy expansion reshapes badge complexity demands across medical end-uses.
Product Type:
Cost-performance tradeoffs dominate buyer selection, with therapy precision requirements dictating element count and recharge economics.
- Single-Element Dosimeters:Lithium fluoride chips in standard geometry provide baseline personnel monitoring for occupational exposure compliance. Demand concentrates in industrial radiography facilities across the United States, where quarterly badge exchange cycles and cost minimization override multi-point profiling needs.
- Multi-Element Dosimeters:Stacked phosphor layers with copper and tin filters enable depth-dose reconstruction across tissue-equivalent depths. Proton therapy centers at Massachusetts General Hospital and Heidelberg Ion Beam Therapy Center drive specification intensity, as spread-out Bragg peak verification requires simultaneous measurement at multiple depths.
- Rechargeable Dosimeters:Annealable lithium fluoride rods permit hundreds of reuse cycles through controlled thermal treatment.
- Non-Rechargeable Dosimeters:Single-use phosphor chips eliminate annealing infrastructure for low-volume monitoring programs.
Volume sits with single-element designs; growth tilts toward multi-element configurations.
Application:
Regulatory scrutiny intensity varies sharply by exposure environment, with therapeutic applications commanding premium calibration protocols.
- Radiation Therapy:Stereotactic body radiotherapy and intensity-modulated radiation therapy require microgray-precision verification for treatment planning validation. Academic medical centers in the United States and Germany anchor specification leadership, where FDA 21 CFR Part 1020 and EU MDR clinical evidence requirements elevate dosimetry service contracts.
- Nuclear Medicine:Technetium-99m and fluorodeoxyglucose handling in cyclotron facilities demands personnel monitoring with photon-beta discrimination. Hospital nuclear medicine departments in France and Japan concentrate procurement, as ANSM and PMDA dose limit enforcement tightens quarterly reporting granularity.
- Radiology:Diagnostic x-ray quality assurance uses TLD for annual output constancy checks.
- Environmental Monitoring:Passive dosimeter networks track fallout and background radiation trends.
Revenue concentrates in radiation therapy; nuclear medicine is climbing the fastest.
End User:
Procurement sophistication scales with regulatory exposure and research intensity, separating institutional buyers into distinct service tiers.
- Hospitals:Radiation safety offices manage mixed badge populations across diagnostic, therapeutic, and interventional departments. Group purchasing organizations like Premier and Vizient consolidate vendor selection in the United States, unbundling hardware maintenance from phosphor logistics.
- Research Institutions:Custom TLD array configurations for FLASH dose-rate and microbeam experiments command configuration premiums. Japan's National Institute of Radiological Sciences and Germany's GSI Helmholtz Centre define specification frontiers.
- Industrial Facilities:Non-destructive testing and sterilization operations prioritize cost-minimized quarterly compliance.
- Academic Institutions:Teaching hospitals blend clinical service with training program standardization.
Hospital procurement dominates unit volume; research institutions yield the steepest margin expansion.
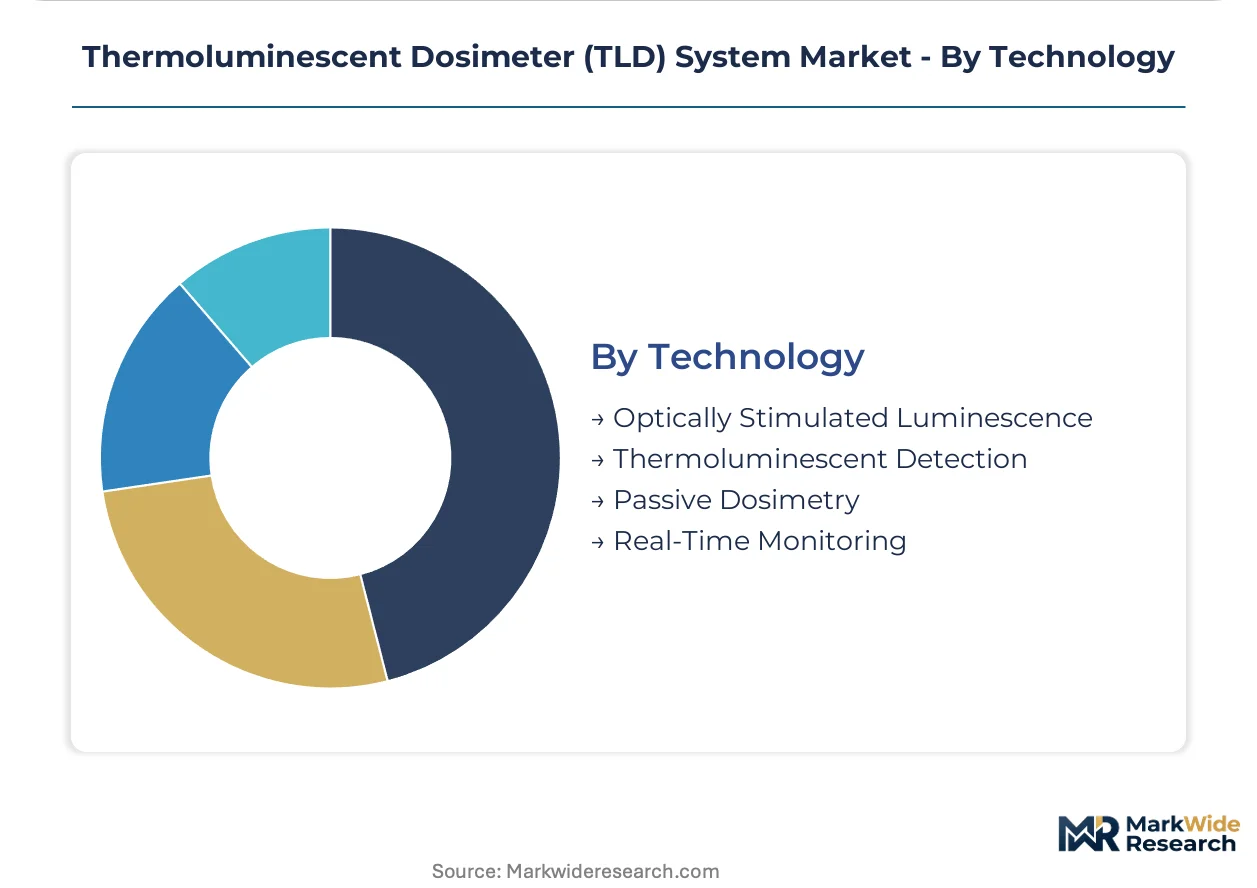
Technology:
Detection modality selection determines infrastructure investment and readout latency tradeoffs.
- Thermoluminescent Detection:Heating-induced light emission from lithium fluoride and calcium fluoride phosphors delivers NIST-traceable accuracy for regulatory audits. FDA-mandated calibration protocols in the United States institutionalize this technology in hospital radiation safety programs despite reader maintenance burdens.
- Optically Stimulated Luminescence:LED-stimulated carbon-doped aluminum oxide enables instant readout without thermal cycling. Landauer and Mirion deployments in high-throughput occupational monitoring threaten TLD's installed base.
- Passive Dosimetry:Non-electronic operation suits remote and high-electromagnetic-interference environments.
- Real-Time Monitoring:Electronic personal dosimeters complement passive systems for immediate alarm functions.
Installed base favors thermoluminescent detection; OSL is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Proton therapy center construction in the United States, Germany, and Japan concentrates TLD procurement around academic medical clusters and specialized radiation facilities.
United States
Massachusetts General Hospital and MD Anderson Cancer Center anchor proton therapy TLD demand for multi-element depth-dose verification. FDA 21 CFR Part 1020 tightens calibration accuracy requirements for diagnostic x-ray quality assurance programs. Premier and Vizient group purchasing organizations consolidate vendor selection across hospital radiation safety offices in the Northeast and Texas medical corridors.
Germany
Heidelberg Ion Beam Therapy Center and GSI Helmholtz Centre drive specification intensity for carbon ion and FLASH dose-rate experiments. EU Medical Device Regulation 2017/745 reclassifies TLD readers to Class IIa, triggering portfolio consolidation among smaller dosimetry service providers. Bavaria and Baden-Württemberg hospital procurement offices favor integrated suppliers with full MDR technical documentation.
Japan
National Institute of Radiological Sciences pilots custom TLD arrays for mixed-field dosimetry in carbon ion therapy validation. PMDA enforcement of occupational dose limits tightens quarterly reporting granularity for hospital nuclear medicine departments. Chiba and Hyogo prefectures concentrate cyclotron facility construction and associated personnel monitoring procurement.
France
ANSM dose limit enforcement accelerates replacement cycles for legacy film-badge systems in Paris and Lyon hospital networks. Medical Device Regulation transition deadlines compress vendor qualification timelines for radiation safety officers. Île-de-France academic hospitals unbundle badge supply from reader maintenance contracts through regional purchasing consortia.
United Kingdom
London teaching hospitals blend clinical service requirements with training program standardization for TLD calibration protocols. MHRA alignment with EU MDR clinical evidence requirements elevates service contract specifications for dosimetry verification. Southeast England proton therapy planning concentrates multi-element badge demand around Royal Marsden and University College Hospital clusters.
Thermoluminescent Dosimeter (TLD) System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated phosphor producers commanding premium positioning in multi-element therapy applications while regional service providers compete on badge logistics efficiency. Three archetypes dominate: backward-integrated crystal manufacturers, reader hardware specialists with captive calibration networks, and pure-play dosimetry service operators with distributed annealing infrastructure. Consolidation pressure intensifies as hospital procurement offices unbundle hardware maintenance from phosphor logistics, favoring scale players with NIST-traceable calibration capabilities and MDR-compliant technical documentation.
Among integrated phosphor manufacturers, Fuji Electric anchors the backward-integrated tier through captive lithium fluoride crystal production. Mirion Technologies occupies a position spanning reader hardware and service revenue streams inherited from nuclear power utility installations. Thermo Fisher Scientific exemplifies channel-control strategy through hospital group purchasing organization relationships in North America. These three represent contrasting archetypes for defending position as optically stimulated luminescence alternatives gain share in high-throughput occupational monitoring.
| Leading Market Players |
|---|
| Fuji Electric |
| ATOMTEX |
| Mirion Technologies |
| Unfors RaySafe |
| Aloka |
| Landauer |
| IBA Dosimetry |
| Tracerco |
| Thermo Fisher Scientific |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up dosimetry service providers have consolidated regional badge logistics networks across the United States and Western Europe, compressing margins for standalone hardware manufacturers while concentrating pricing power among integrated suppliers with captive lithium fluoride crystal production.
Pricing Analysis
Premium-mid-economy pricing differentiation separates multi-element therapy verification arrays from standard occupational monitoring badges. Short lead times for quarterly NRC-mandated badge exchanges command 15-25% premiums over standard delivery windows, while spot inventory of annealed lithium fluoride chips trades at discounts in off-peak quarters. Price differentiation hinges on NIST-traceable calibration certification and phosphor dopant formulation precision. Pricing pressure stems from optically stimulated luminescence substitution in high-throughput industrial monitoring, where Landauer and Mirion instant-readout systems undercut TLD total cost of ownership. Industrial radiography facilities exhibit highest price sensitivity, while proton therapy centers prioritize accuracy over unit cost.
Supply Chain Analysis
Reverse-logistics flows for quarterly badge collection, annealing, and redistribution anchor TLD service economics, with specialized carriers handling radiation-contaminated returns under DOT hazardous materials protocols. Phosphor crystal manufacturing concentrates in Japan, the United States, and Germany, where three integrated producers control lithium fluoride dopant formulation. Raw material dependencies include high-purity lithium carbonate, magnesium dopants for tissue equivalence, and platinum heater elements for reader thermal cycling. Single-source vulnerability for specialty phosphor batches poses structural supply risk, particularly for carbon ion therapy validation arrays requiring neutron-sensitive formulations. Distribution runs through hospital group purchasing organizations in North America and regional dosimetry service consortia in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into phosphor crystal manufacturing has become the decisive competitive lever, separating margin-defensible integrated suppliers from component-assemblers exposed to raw material cost volatility and certification compliance burdens.
For Market Incumbents: Extend NIST-traceable calibration network density to defend against optically stimulated luminescence substitution in occupational monitoring. Lock in multi-year service contracts with proton therapy centers before EU MDR clinical evidence requirements trigger vendor consolidation. Prioritize firmware compatibility upgrades for legacy Harshaw 3500 and 4500 reader installations to retain hospital radiation safety office relationships. For New Entrants and Emerging Players: Begin with custom TLD array configurations for FLASH dose-rate and microbeam radiography experiments at Japan's National Institute of Radiological Sciences and Germany's GSI Helmholtz Centre, where 40-60% margin premiums offset low volumes. Target research institution procurement offices with configuration flexibility that integrated incumbents cannot match. Pursue direct phosphor crystal sourcing partnerships with Japanese specialty chemical producers to bypass established supplier gatekeeping. For Investors and Strategic Acquirers: Distressed-cycle entries favor European dosimetry service providers facing EU MDR 2017/745 transition compliance costs, particularly in France and Germany where notified body involvement has triggered portfolio rationalization. Long-term viability hinges on captive lithium fluoride manufacturing or exclusive phosphor supply agreements. Monitor NRC cumulative occupational dose rulemaking progress as inflection indicator for replacement cycle compression from quarterly to monthly frequency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphor Manufacturing | Fuji Electric's captive lithium fluoride crystal production insulates margin position against raw material volatility. |
| MDR Technical Documentation Investment | Full EU 2017/745 compliance enables German and French hospital procurement office vendor list retention. |
| Proton Therapy Center Partnership | Multi-element depth-dose verification contracts at Massachusetts General Hospital anchor specification leadership. |
| Legacy Reader Firmware Modernization | Compatibility upgrades for Harshaw 3500 and 4500 systems defend installed base against displacement. |
| Research Institution Custom Array Development | FLASH dose-rate and microbeam configurations at Japan's NIRS command 40-60% margin premiums. |
Research Methodology
Multi-period observation of FDA 21 CFR Part 1020 enforcement patterns, NRC 10 CFR Part 20 compliance cycle data, and EU MDR 2017/745 transition timelines anchored the trend analysis, supplemented by interviews with radiation safety officers at academic medical centers, biomedical engineers at proton therapy facilities, GPO contracts managers at Premier and Vizient, and phosphor manufacturing technical directors. Secondary validation drew from FDA warning letter databases, NRC regulatory guidance documents, EU notified body technical file assessments, and hospital procurement database extracts. Bottom-up unit demand estimates across single-element and multi-element badge configurations were triangulated against top-down service revenue projections.
Segment-weighting approaches applied differential growth assumptions across radiation therapy, nuclear medicine, radiology, and environmental monitoring applications, with proton therapy center construction pipelines and carbon ion therapy validation programs receiving distinct modeling treatment. Product type segmentation incorporated rechargeable versus non-rechargeable phosphor economics and reader infrastructure depreciation schedules. Technology substitution curves between thermoluminescent detection and optically stimulated luminescence were calibrated against historical occupational monitoring program conversion data. CAGRs were derived from installed base replacement cycles, regulatory-mandated exchange frequencies, and emerging therapy modality penetration rates.
Phosphor crystal supply disruptions, NRC cumulative dose limit rulemaking acceleration, and optically stimulated luminescence cost-performance breakthroughs are the dominant revision risks for TLD demand forecasts. Forecasts reflect assumptions regarding quarterly badge exchange cycle stability and EU MDR compliance timeline adherence. Practitioners should monitor NRC docket activity, Japanese lithium fluoride export licensing patterns, and carbon-doped aluminum oxide sensitivity threshold announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Atomic Magnetometers Market
Analytical Instruments
X-Ray Fluorescence Analyzer Market
Analytical Instruments
Fluorescence Spectroscopy Market
Analytical Instruments
Lab-On-A-Chip Device Market
Analytical Instruments
Digital Vernier Caliper Market
Analytical Instruments
Digital Turbidity Meter Market
Analytical Instruments
Global Laboratory Electronic Balance Market
Analytical Instruments
Electron Probe Microanalyzers (EPMA) Market
Analytical Instruments
Terahertz Spectroscopic System Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Bolometer Market
Analytical Instruments
High-Sensitivity Luminometers Market
Analytical Instruments
Metallurgical Microscope Market
Analytical Instruments
Trace Oxygen Analyzer Market
Analytical Instruments
Laser Diffraction Analyzer Market