
 Global Potentiostat Market | 2026-2036
Global Potentiostat Market Size, Share, and Industry Trends Forecast 2026-2036
Global Potentiostat Market Foresight
China is narrowing its reliance on imported electrochemical test equipment through domestic manufacturing expansion in Shenzhen and Shanghai clusters. Metrohm AG leverages its Swiss precision engineering heritage to dominate high-end corrosion research installations across European refineries. Danaher Corp sustains broad portfolio coverage by embedding potentiostat modules within larger analytical workflow platforms. Ivium Technologies BV specializes in compact, field-deployable instruments that occupy the portable electrochemistry niche.
A potentiostat is an electronic instrument that controls the voltage difference between a working electrode and a reference electrode while measuring the resulting current flow, typically operating with potential resolution down to microvolt precision and current measurement ranges spanning nanoamperes to amperes. It serves as the foundational measurement tool for electrochemical analysis, enabling corrosion rate determination, battery material characterization, sensor development, and biosensor validation across industrial and academic settings. Multi-channel configurations are capturing expanding share as pharmaceutical companies parallelize compound screening workflows, while USB-controlled interfaces are displacing legacy GPIB connections due to simplified laptop integration and reduced laboratory infrastructure costs. Digital technology architectures lead the installed base but hybrid analog-digital designs are gaining traction where ultra-low current noise floors prove critical for single-molecule detection applications.
FDA validation protocols for electrochemical biosensors in diagnostic applications are tightening traceability requirements across the supply chain, while REACH chemical registration in Europe constrains electrode material sourcing for manufacturers serving EU laboratories. EPA corrosion monitoring mandates for pipeline infrastructure in the United States sustain baseline demand for ruggedized field potentiostats. ISO 17025 accreditation requirements are propagating from Germany into broader European procurement specifications, reshaping vendor qualification criteria. Stakeholders must monitor how China's GB standard harmonization with IEC electrochemical measurement protocols reshapes export competitiveness for instruments manufactured in Shenzhen and Dongguan production zones.
Market Dynamics
Multi-channel potentiostat architectures are compressing capital expenditure cycles for battery material screening operations while REACH chemical registration protocols in Europe and FDA validation requirements in the United States simultaneously elevate vendor qualification barriers.
Growth Catalysts
- Battery R&D intensity:Solid-state electrolyte development programs at automotive OEMs and energy storage startups are accelerating orders for parallel electrochemical testing configurations. Cell manufacturers in Shenzhen and Dongguan clusters are scaling in-house characterization capabilities.
- EPA pipeline mandates:Corrosion monitoring requirements for interstate natural gas transmission infrastructure sustain replacement demand for ruggedized field-deployable instruments. Pipeline operators must demonstrate continuous potential monitoring compliance.
- ISO 17025 propagation:Laboratory accreditation standards originating in Germany are reshaping procurement specifications across European refineries and chemical plants. Third-party testing facilities require traceable calibration chains.
Market Restraints
- Precision analog component concentration:Ultra-low-noise operational amplifiers and high-stability reference electrodes depend on specialized Japanese and German suppliers. Geographic concentration of these input sources creates vulnerability.
- REACH electrode material constraints:Mercury and cadmium restrictions in European chemical registration frameworks limit traditional reference electrode chemistries. Manufacturers must reformulate product lines for EU laboratory access.
- Optical spectroscopy substitution:Raman and infrared techniques are capturing share in certain corrosion and coating analysis applications where spatial resolution outweighs electrochemical kinetic data requirements.
Strategic Opportunities
- Indian pharmaceutical expansion:CDSCO regulatory pathways for biosensor diagnostics are stimulating electrochemical sensor validation demand. Contract research organizations in Hyderabad and Bangalore are building captive testing infrastructure.
- USB interface standardization:Laptop-native control architectures are displacing dedicated workstation requirements. Academic laboratories and field inspection teams are adopting simplified connectivity.
- Green hydrogen R&D:Electrolyzer membrane and catalyst development programs are creating new high-current potentiostat applications. Research consortia in Germany and Denmark are funding specialized instrumentation procurement.
Industry Challenges
- Electrochemical software expertise scarcity:Firmware development for impedance spectroscopy and pulse techniques requires specialized skill sets. Vendors compete for embedded systems engineers with signal processing backgrounds.
- FDA validation timeline compression:Diagnostic biosensor developers face extended documentation cycles for 510(k) submissions. Potentiostat manufacturers must provide enhanced calibration certificates and audit trails.
- Legacy GPIB infrastructure integration:Established university laboratories retain aging data acquisition systems. New USB-controlled instruments require adapter layers or complete workstation replacement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Potentiostat Market |
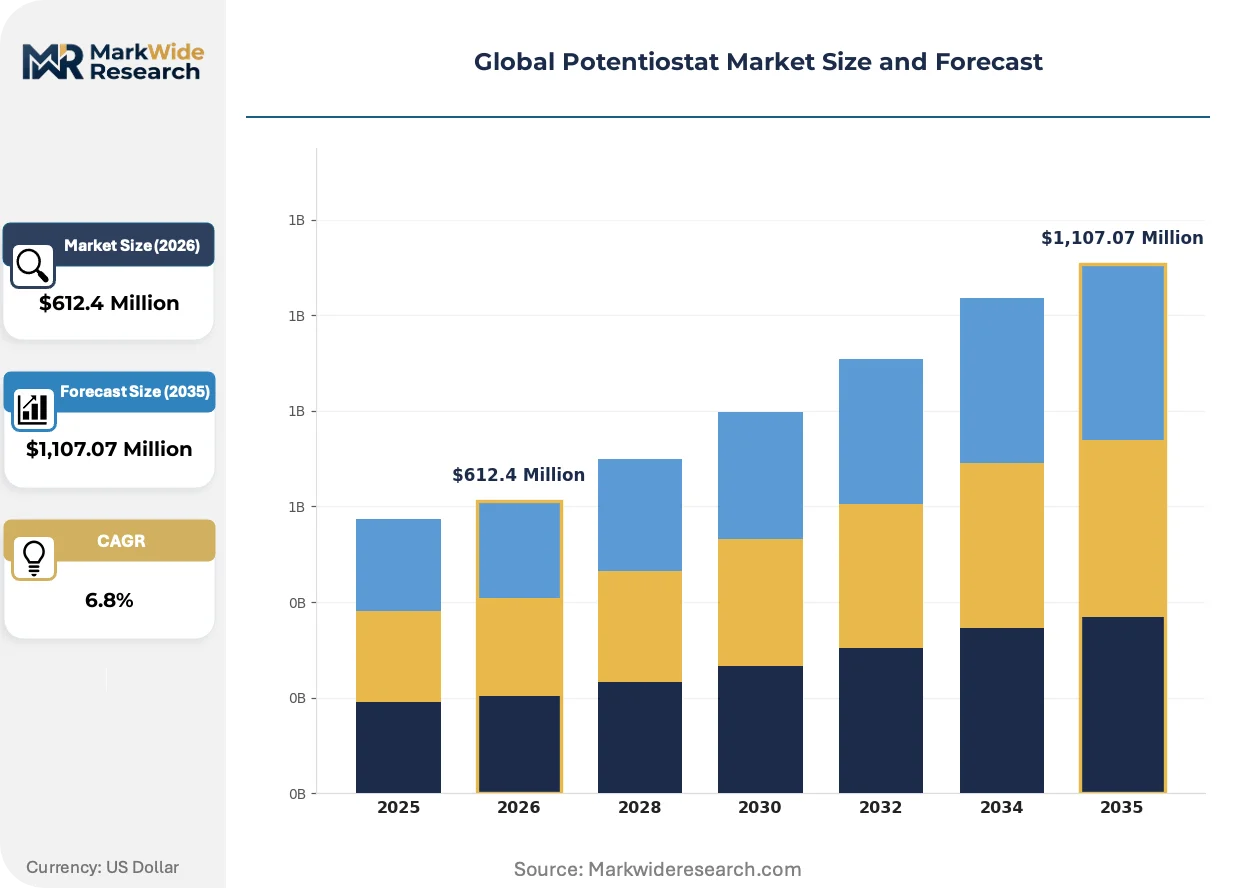
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Channel, Multi-Channel, GPIB Controlled, USB Controlled Technology: Digital, Analog, Hybrid, Integrated End User: Research Institutions, Pharmaceutical Companies, Academic Laboratories, Industrial Applications Integration Level: Standalone, Modular, Embedded, Software Integrated |
| Companies Covered | Danaher Corp, Harvard Bioscience Inc., Metrohm AG, PalmSens BV, Ivium Technologies BV, AMETEK Inc., Gamry Instruments, Stanford Research Systems, BioLogic Sciences Instruments SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Potentiostat Market Shifts & Advancements
Cloud-native data architectures and embedded machine learning inference are restructuring how electrochemical experiments are designed, executed, and interpreted across distributed research networks.
Software-defined potentiostat platforms are virtualizing instrument hardware functions through firmware abstraction layers. Battery startups in California and Massachusetts are adopting these architectures to run identical test protocols across heterogeneous hardware fleets. This approach is virtualizing capital allocation by enabling remote instrument sharing and subscription-based access models.
REACH chemical registration amendments are tightening substance restrictions on mercury-based reference electrodes. European analytical instrument distributors are accelerating inventory transitions to solid-state alternatives. Corrosion monitoring service providers in Germany and the Netherlands are retrofitting installed bases to maintain laboratory access compliance.
Research consortia are consolidating electrochemical testing through shared core facility models rather than individual laboratory purchases. Academic institutions in the United Kingdom and Switzerland are unbundling instrument ownership from experimental access through hourly booking systems. Pharmaceutical compound screening operations in Cambridge and Basel are driving this behavioral shift toward operational expenditure frameworks.
Global Potentiostat Market Segmentation
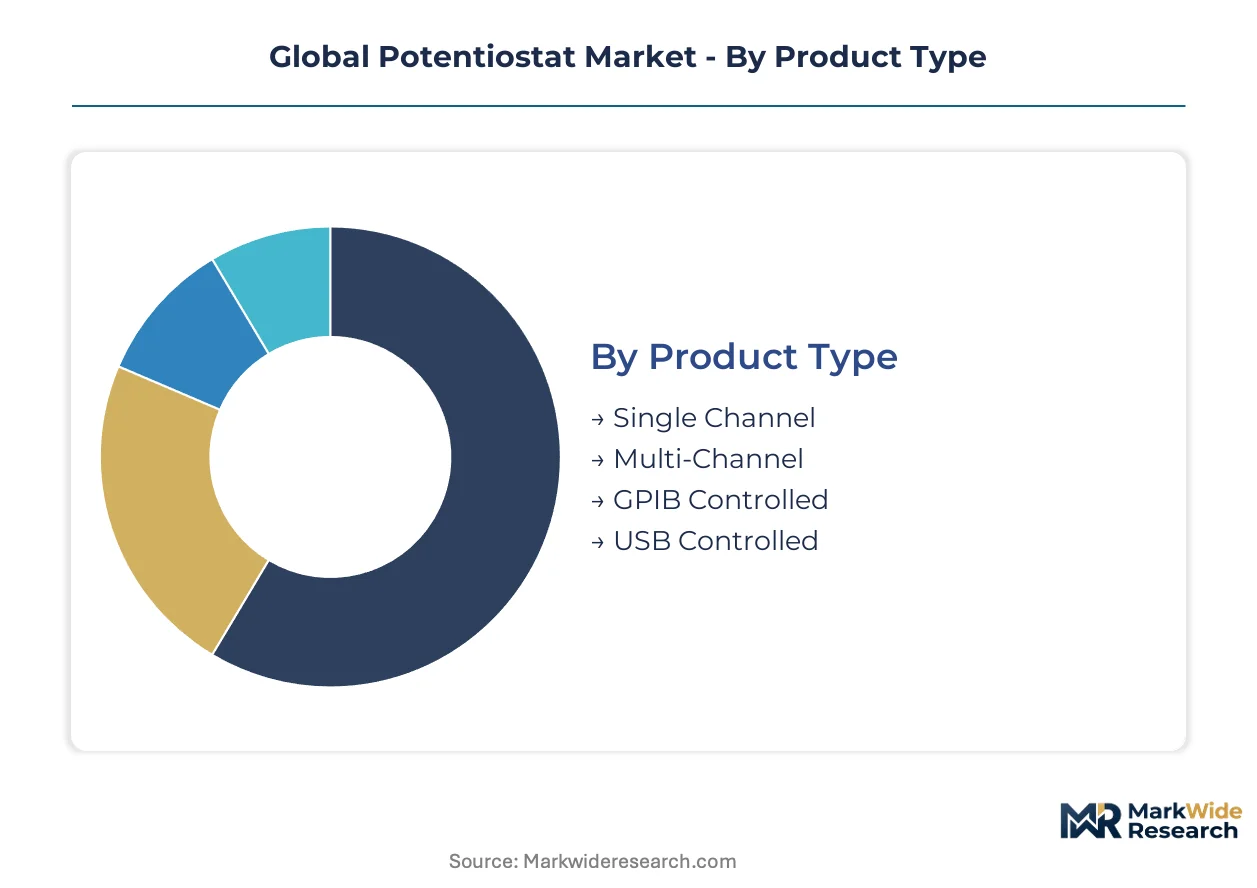
Potentiostat procurement cycles vary dramatically across configuration types, with portable units refreshing every 3-4 years versus industrial rack systems operating for 8-12 years. Understanding these replacement rhythms helps vendors align service contracts and upgrade pathways with customer capital planning.
Product Type:
Multi-channel configurations compress experimental cycle times while single-channel instruments sustain longer depreciation schedules in budget-constrained settings.
- Single Channel:Entry-level instruments with one working electrode interface serve individual researchers and teaching laboratories. Academic institutions in India and Brazil prioritize these units for undergraduate electrochemistry curricula where capital budgets limit per-station investment.
- Multi-Channel:Parallel testing architectures accommodate 8-16 independent electrochemical cells simultaneously. Battery material screening operations at automotive OEMs in Germany and Japan drive procurement volumes as solid-state electrolyte programs accelerate candidate evaluation throughput.
- GPIB Controlled:Legacy IEEE-488 interface instruments persist in established university laboratories with existing data acquisition infrastructure. Replacement decisions hinge on complete workstation overhaul timelines rather than incremental upgrades.
- USB Controlled:Native laptop connectivity eliminates dedicated controller hardware requirements. Field inspection teams at pipeline operators across the United States and Canada favor these simplified deployment models for corrosion monitoring surveys.
Single Channel dominates installed base. Multi-Channel is where expansion concentrates.
Technology:
Cost tiers separate precision analog architectures from digitally streamlined alternatives, with hybrid designs commanding premium positioning for specialized applications.
- Digital:FPGA-based signal generation and acquisition enable software-defined functionality updates without hardware replacement. Pharmaceutical compound screening facilities in Switzerland and the United Kingdom standardize on these platforms for protocol flexibility across therapeutic programs.
- Analog:Discrete component signal paths achieve lowest noise floors for single-molecule detection research. Neuroscience laboratories at Max Planck Institutes and Rockefeller University maintain demand for these precision instruments despite higher per-unit costs.
- Hybrid:Analog front-end conditioning combined with digital back-end processing balances noise performance with computational versatility. Biosensor validation labs navigating FDA submission requirements favor these configurations for traceable measurement chains.
- Integrated:System-on-chip architectures miniaturize potentiostat functions for point-of-care diagnostic devices. Wearable sensor startups in California and Massachusetts drive development partnerships for credit-card form factor implementations.
Digital platforms capture volume leadership. Hybrid architectures claim the steepest expansion trajectory as precision requirements intensify.
End User:
Customer type determines specification priorities, with industrial buyers emphasizing ruggedization and regulatory documentation versus academic purchasers prioritizing cost and software accessibility.
- Research Institutions:National laboratories and government research centers operate multi-instrument facilities with centralized technical support. CERN and Argonne National Laboratory procurement specifications influence vendor roadmap decisions for high-channel-count systems.
- Pharmaceutical Companies:GxP-compliant environments demand validated software, audit trails, and IQ/OQ/PQ documentation packages. Roche and Novartis electrochemical sensor development groups require enhanced calibration certificates for regulatory submissions.
- Academic Laboratories:Principal investigator grants drive discrete purchase decisions with 5-7 year replacement horizons. European Research Council funding cycles correlate with instrument refresh waves across chemistry departments.
- Industrial Applications:Corrosion monitoring services, battery manufacturers, and coating suppliers operate instruments in non-laboratory environments. Pipeline operators under EPA mandates require IP-rated enclosures and extended temperature specifications.
Academic Laboratories anchor cumulative unit shipments. Pharmaceutical Companies represent the fastest-climbing revenue tier as biosensor diagnostics expand.
Integration Level:
Supply concentration in modular subsystems creates vendor differentiation opportunities against standalone commodity competition.
- Standalone:Complete instruments with integrated power supplies, cell connections, and user interfaces constitute the traditional product form. Metrohm and PalmSens compete primarily in this configuration tier.
- Modular:Rack-mountable units with interchangeable input modules adapt to varying electrode configurations and current ranges. Battery testing service providers in Shenzhen deploy these for flexible capacity allocation across customer projects.
- Embedded:OEM potentiostat boards integrate into larger analytical systems or production equipment. Glucose meter manufacturers source these subsystems for factory calibration stations.
- Software Integrated:API-accessible instruments embed within laboratory information management systems and automated workflow platforms. Thermo Fisher and Danaher bundle these into broader analytical suites.
Standalone instruments retain the largest installed base. Modular configurations are gaining share fastest as service-oriented business models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision analog component manufacturing clusters in Germany and Japan supply critical operational amplifiers and reference electrodes to instrument builders worldwide. Shenzhen and Shanghai electronics manufacturing zones in China are scaling domestic potentiostat assembly capacity. Corrosion monitoring service providers in the Netherlands and pipeline operators across the United States sustain replacement demand for field-deployable units.
United States
EPA pipeline corrosion mandates sustain baseline procurement for ruggedized field instruments at interstate natural gas transmission operators. FDA validation protocols for electrochemical biosensors tighten documentation requirements for diagnostic device developers. Greater Boston and California biotech clusters drive demand for multi-channel screening configurations in pharmaceutical R&D facilities.
Germany
ISO 17025 laboratory accreditation standards originating from German metrology institutes reshape procurement specifications across European refineries. REACH chemical registration constrains mercury-based reference electrode formulations for EU market access. Ruhr industrial region corrosion monitoring services and Baden-Württemberg automotive battery research consortia concentrate instrument deployment.
China
Domestic manufacturing expansion in Shenzhen and Dongguan electronics clusters narrows reliance on imported electrochemical test equipment. GB standard harmonization with IEC electrochemical measurement protocols reshapes export competitiveness for instruments manufactured in Pearl River Delta production zones. Solid-state battery R&D programs at automotive OEMs accelerate orders for parallel testing configurations.
Japan
Ultra-low-noise operational amplifier supply concentration in Japanese semiconductor fabs creates input source vulnerability for precision instrument builders. METI funding for hydrogen electrolyzer research stimulates high-current potentiostat applications. Nagoya and Osaka industrial corridors host specialized component suppliers serving global instrument manufacturers.
India
CDSCO regulatory pathways for biosensor diagnostics stimulate electrochemical sensor validation demand at contract research organizations. Hyderabad and Bangalore pharmaceutical service providers are building captive testing infrastructure. Academic institutions prioritize single-channel entry-level instruments for undergraduate electrochemistry curricula under constrained capital budgets.
Global Potentiostat Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base separates into consolidated analytical instrumentation conglomerates with broad portfolio coverage and focused electrochemical specialists with deep technical expertise. Three archetypes dominate: Swiss-German precision engineering houses, Dutch compact instrument innovators, and diversified life science conglomerates embedding potentiostat modules within larger workflow platforms. Competitive moves center on USB interface standardization to displace legacy GPIB connections and modular rack-mountable architectures enabling flexible capacity allocation.
Among diversified analytical instrumentation groups, Danaher Corp and AMETEK Inc. occupy positions bundling potentiostat functions within broader laboratory platform ecosystems. Metrohm AG exemplifies the precision engineering archetype with heritage positioning in high-end corrosion research installations. Ivium Technologies BV and PalmSens BV represent the compact portable instrument specialization, anchoring field-deployable and USB-native connectivity segments. These named entities illustrate how geographic origin and corporate structure correlate with strategic positioning across the technology spectrum.
| Leading Market Players |
|---|
| Danaher Corp |
| Harvard Bioscience Inc. |
| Metrohm AG |
| PalmSens BV |
| Ivium Technologies BV |
| AMETEK Inc. |
| Gamry Instruments |
| Stanford Research Systems |
| BioLogic Sciences Instruments SA |
| Others |
Supply & Pricing Matrix
Shenzhen and Dongguan electronics manufacturing clusters are scaling domestic potentiostat assembly capacity, compressing import-dependent pricing premiums while elevating bargaining power for buyers sourcing from Pearl River Delta production zones. This geographic capacity expansion interacts with REACH electrode material constraints to reshape cost structures across certification tiers.
Pricing Analysis
REACH chemical registration dictates the pricing tier structure across European laboratory procurement, separating mercury-free certified instruments from legacy formulations barred from EU market access. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 17025 accreditation status and FDA validation documentation depth. Cost compression in economy tiers is intensifying because Chinese domestic manufacturers are absorbing margin pressure to secure market share. Academic laboratories in India and Brazil exhibit highest price sensitivity, while pharmaceutical GxP environments demonstrate lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Export-control restrictions on precision analog semiconductors limit flows of ultra-low-noise operational amplifiers from Japanese fabs to instrument builders worldwide. Manufacturing concentrates in China, Germany, and Japan, with component sourcing drawing from specialized suppliers in Nagoya and Osaka industrial corridors. Raw material dependencies span high-stability reference electrodes, FPGA signal processors, and mercury-free electrode chemistries. Single-source vulnerability persists for Japanese operational amplifier supply. Distribution runs through analytical instrument distributors and direct OEM relationships with battery testing service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams including calibration certificates, audit trail software subscriptions, and IQ/OQ/PQ documentation packages are expanding faster than hardware unit sales, transforming vendor economics toward recurring-revenue models.
For Market Incumbents: Harden defensive positioning by embedding potentiostat modules within broader laboratory information management system workflows to counter USB-native portable instrument substitution. Deepen backward integration into solid-state reference electrode manufacturing to circumvent REACH material restrictions. Prioritize certification investment for FDA 510(k) validation support services. For New Entrants and Emerging Players: Indian pharmaceutical contract research organization clusters offer the most penetrable geographic underpenetration, with CDSCO regulatory pathways stimulating captive testing infrastructure buildouts. Target battery material screening operations at automotive OEMs seeking parallel electrochemical testing configurations. Pursue software-defined potentiostat platform partnerships with California and Massachusetts battery startups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among modular rack-mountable instrument providers serving service-oriented business models. Long-term viability favors vendors with embedded machine learning inference capabilities and cloud-native data architectures. Acquisition target archetype: compact portable specialists with USB-native connectivity and field-deployable IP-rated enclosures. Watch for GB standard harmonization completion as inflection indicator for Chinese export competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Platform Launch | Virtualizes hardware functions, enabling subscription access models for battery startups in California and Massachusetts. |
| REACH Compliance Certification Investment | Secures EU laboratory access by reformulating mercury-free reference electrode product lines for German distributors. |
| USB Interface Standardization | Displaces legacy GPIB connections, simplifying laptop integration for field inspection teams at pipeline operators. |
| Modular Rack-Mountable Architecture | Enables flexible capacity allocation across customer projects for battery testing service providers in Shenzhen. |
| Cloud-Native Data Architecture Partnership | Restructures experimental design and interpretation across distributed research networks at UK and Swiss academic consortia. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted, combining primary interviews with electrochemistry laboratory directors, pharmaceutical regulatory affairs leads, battery R&D program managers, corrosion monitoring service technicians, and analytical instrument procurement officers. Secondary validation drew from FDA 510(k) submission databases, EPA pipeline compliance filings, REACH chemical registration records, and ISO 17025 accreditation directories. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across the analysis window.
Calibration anchored volume and value outputs to observed procurement cycles, with replacement rhythm assumptions varying by configuration type from 3-4 years for portable units to 8-12 years for industrial rack systems. Segmentation dimensions modeled include channel configuration, signal processing architecture, end-user environment, and integration level. CAGRs were derived from slope analysis of normalized growth trajectories. Industry-specific forecast inputs incorporated solid-state battery R&D program announcements and hydrogen electrolyzer research consortium funding disclosures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified life science conglomerates embedding potentiostat modules would shift outcomes. Material shifts in GB standard harmonization timelines or REACH chemical registration amendments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
ESR Analyzer Market
Analytical Instruments
Global Mass Spectrometry Market
Analytical Instruments
Trace Chemical Detector Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Digital Vernier Caliper Market
Analytical Instruments
Asia-Pacific Dissolved Gas Analyzer Market
Analytical Instruments
Signal Analyzer Market
Analytical Instruments
Europe Dissolved Gas Analyzer Market
Analytical Instruments
Portable Particle Counter Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
Spectrum Analyzer Market
Analytical Instruments
Global Laboratory Electronic Balance Market
Analytical Instruments
Visualization Instruments for MIS Market