
 Signal Analyzer Market | 2026-2036
Signal Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Signal Analyzer Market Analytics
The signal analyzer market is consolidating around a sharp divergence between premium benchtop systems and commoditized USB-tethered modules. Keysight Technologies leverages its calibration ecosystem and software-defined architecture to command the high-performance tier, while Rohde & Schwarz sustains dominance in European defense and aerospace certification workflows. National Instruments competes through modular PXI platforms that appeal to research institutions seeking configurable test stacks.
A signal analyzer measures amplitude, frequency, phase, and modulation characteristics of electrical signals across radio frequency and microwave bands, typically operating from kilohertz to millimeter-wave frequencies with resolution bandwidths down to one hertz. Vector signal analyzers decode complex modulation formats for 5G and satellite communications, making them indispensable for base station and terminal validation. Software-defined technology is capturing the fastest expansion as end users replace dedicated hardware with FPGA-based platforms that upgrade through firmware, while spectrum analyzers remain the mature revenue base sustained by regulatory compliance mandates in telecommunications and broadcasting.
FCC Part 15 emissions rules in the United States, CE marking under the EU Radio Equipment Directive, and ETSI harmonized standards collectively shape product certification requirements and force analyzer manufacturers to pre-validate test routines. Defense agencies in multiple jurisdictions now require TEMPEST and MIL-STD-461 compliance documentation that only calibrated laboratory-grade equipment can generate. Stakeholders must monitor how 3GPP Release 18 specifications and subsequent 6G study items redefine the measurement bandwidth and dynamic range thresholds that instruments must satisfy.
Market Dynamics
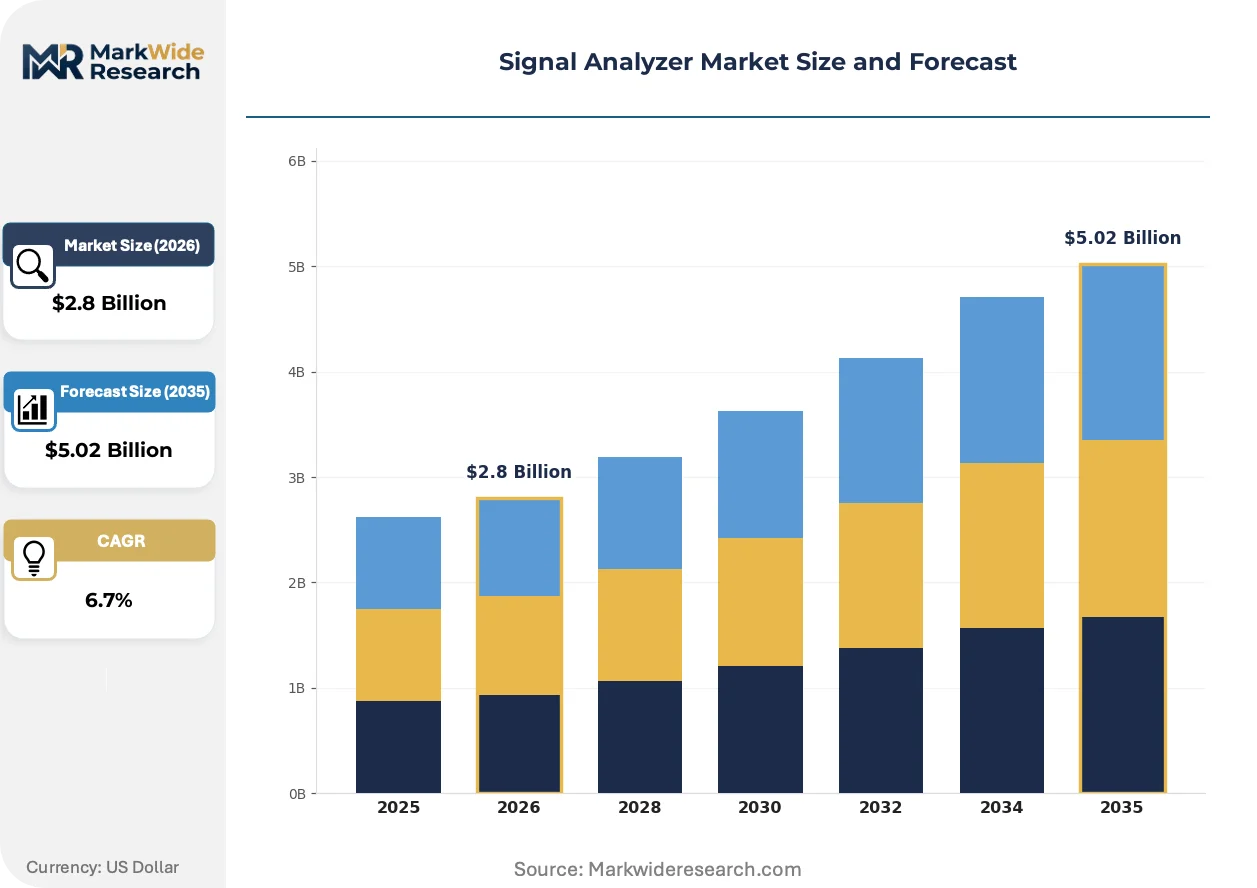
The signal analyzer market is bifurcating around software-defined architectures that enable firmware-upgradable measurement platforms, compressing traditional hardware refresh cycles while extending instrument service life across defense and telecommunications procurement programs.
Growth Catalysts
- 5G-Advanced Research Mandates:3GPP Release 18 specifications are forcing base station manufacturers to validate wider bandwidths and higher-order modulation schemes, driving vector signal analyzer demand in South Korea and Germany.
- MIL-STD-461 Compliance Expansion:NATO defense procurement programs now require electromagnetic interference documentation that only laboratory-grade spectrum analyzers can generate, anchoring equipment budgets across member states.
- FPGA-Based Platform Convergence:Field-programmable gate array technology is enabling real-time signal processing upgrades without hardware replacement, appealing to research institutions seeking configurable test stacks.
Market Restraints
- Precision Component Concentration:High-frequency analog-to-digital converters and low-noise amplifiers concentrate among specialized semiconductor foundries in Taiwan and Japan, creating supply vulnerability for millimeter-wave instruments.
- Calibration Infrastructure Costs:Traceable calibration to national metrology institutes requires recurring capital expenditure and skilled technician labor, elevating total cost of ownership beyond initial acquisition.
- USB-Tethered Module Commoditization:Low-cost software-defined radio dongles are capturing basic spectrum monitoring applications, compressing margins at the entry tier of the market.
Strategic Opportunities
- 6G Study Item Participation:Early involvement in ITU-R and 3GPP 6G standardization processes positions instrument vendors to define measurement bandwidth thresholds before specifications crystallize.
- India Telecom Manufacturing:Production-linked incentive schemes for domestic 5G equipment manufacturing are creating demand for localized test and certification infrastructure in Bangalore and Hyderabad.
- Cloud-Native Analyzer Architectures:Remote access to centralized high-performance measurement systems via secure network interfaces is opening subscription-based revenue models for enterprise and academic users.
Industry Challenges
- RF Engineer Talent Scarcity:Specialized expertise in microwave circuit design and electromagnetic compatibility testing is concentrating among aging workforces in Germany and the United States, constraining vendor expansion and customer implementation capacity.
- Multi-Standard Certification Complexity:Simultaneous compliance with FCC Part 15, CE marking under the EU Radio Equipment Directive, and ETSI harmonized standards extends product validation timelines and strains engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Signal Analyzer Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vector Signal Analyzers, Real-Time Analyzers, Portable Analyzers, Spectrum Analyzers Technology: Digital Technology, Analog Technology, Mixed-Signal Technology, Software-Defined Technology End User: Aerospace, Telecommunications, Defense, Research Institutions Application: Signal Monitoring, Spectrum Management, Interference Analysis, Compliance Testing |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Anritsu Corporation, National Instruments, Tektronix, Viavi Solutions, Advantest Corporation, Yokogawa Electric Corporation, Teledyne Lecroy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Signal Analyzer Market Evolving Landscape
Measurement instrumentation is converging around software-defined platforms that decouple hardware acquisition from capability expansion, while regulatory pressure and procurement model evolution reshape how buyers acquire and deploy test assets.
Artificial intelligence-assisted signal classification is electrifying automated interference detection and modulation analysis workflows. Cellular network operators in Japan and South Korea are deploying these capabilities to reduce manual troubleshooting of 5G base station performance anomalies. The technology is compressing mean-time-to-repair metrics and shifting technician roles toward system-level optimization rather than repetitive measurement tasks.
The EU AI Act's risk classification framework is mandating documentation of automated decision-making in safety-critical communications infrastructure. Signal analyzer manufacturers must now embed audit trails and explainability features into interference detection algorithms sold into European markets. Aerospace and defense contractors in France and Germany are prioritizing instruments with built-in compliance logging to accelerate certification timelines.
Enterprise buyers are unbundling after-sales service contracts from hardware procurement, negotiating standalone calibration and software maintenance agreements. Research institutions in the United States are driving this shift, seeking competitive bidding for multi-vendor instrument fleets rather than captive service relationships. The model is visible most acutely in university research parks around Boston and Austin, where shared test facilities pool calibration schedules across departmental budgets.
Signal Analyzer Market Segmentation
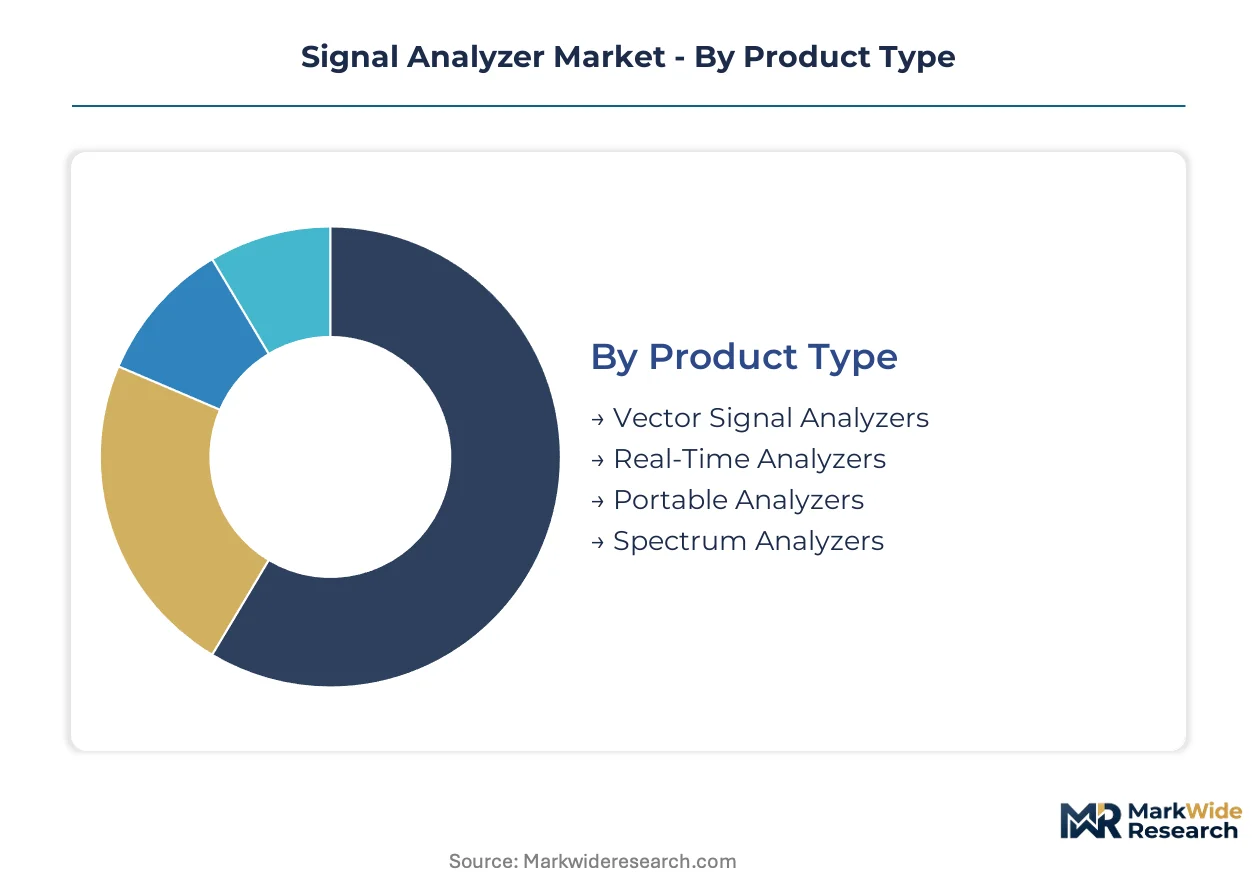
Signal analyzer procurement bifurcates sharply between laboratory-grade validation systems and field-deployable units, with technology architecture and certification requirements driving divergent specification demands across defense, telecommunications, and research verticals.
Product Type:
Frequency range and measurement bandwidth specifications determine instrument selection, with vector capabilities commanding premium positioning against traditional spectrum monitoring platforms.
- Vector Signal Analyzers:These instruments decode complex modulation formats through digital signal processing, capturing amplitude and phase information simultaneously. Base station manufacturers in South Korea deploy these for 5G-Advanced validation, compelled by 3GPP Release 18 bandwidth requirements.
- Spectrum Analyzers:Frequency-domain measurement instruments dominate regulatory compliance workflows, sweeping across RF and microwave bands to identify emissions signatures. Broadcasting authorities in Germany and telecommunications regulators in the United States specify these for FCC Part 15 and ETSI harmonized standard verification.
- Real-Time Analyzers:Continuous acquisition architectures capture transient signals without gaps, essential for radar pulse analysis and electronic warfare testing.
- Portable Analyzers:Battery-operated units with reduced specifications serve field maintenance crews and installation technicians.
Mature deployment sits with spectrum analyzers. Newer deployment is concentrated in vector signal analyzers.
Technology:
Hardware-software integration depth separates upgradeable platforms from fixed-capability instruments, reshaping procurement economics and vendor relationships.
- Software-Defined Technology:FPGA-based architectures enable firmware-upgradable measurement capabilities without hardware replacement. Research institutions in the United States favor these for configurable test stacks that evolve with protocol standards.
- Digital Technology:High-speed ADCs and DSP engines deliver precision measurements with digital calibration stability. Defense procurement programs across NATO members mandate these for MIL-STD-461 compliance documentation.
- Mixed-Signal Technology:Hybrid architectures balance analog front-end sensitivity with digital processing flexibility.
- Analog Technology:Traditional swept-tune architectures persist in cost-sensitive spectrum monitoring applications.
Established infrastructure relies on analog and mixed-signal foundations. Capacity expansion is climbing the fastest in software-defined platforms.
End User:
Procurement authority and certification stringency vary dramatically across institutional buyers, with defense and aerospace mandating traceable calibration chains unavailable to commercial segments.
- Defense:Electromagnetic compatibility testing and electronic warfare validation require TEMPEST-compliant instrumentation with documented calibration chains to national metrology institutes.
- Telecommunications:Network equipment manufacturers and mobile operators purchase analyzers for base station commissioning and interference troubleshooting.
- Aerospace:Avionics testing and satellite payload validation demand extended temperature range specifications and shock-resistant packaging.
- Research Institutions:University laboratories and government research centers acquire modular platforms for protocol development and standardization research.
Volume concentration rests with telecommunications. Specification complexity peaks in defense.
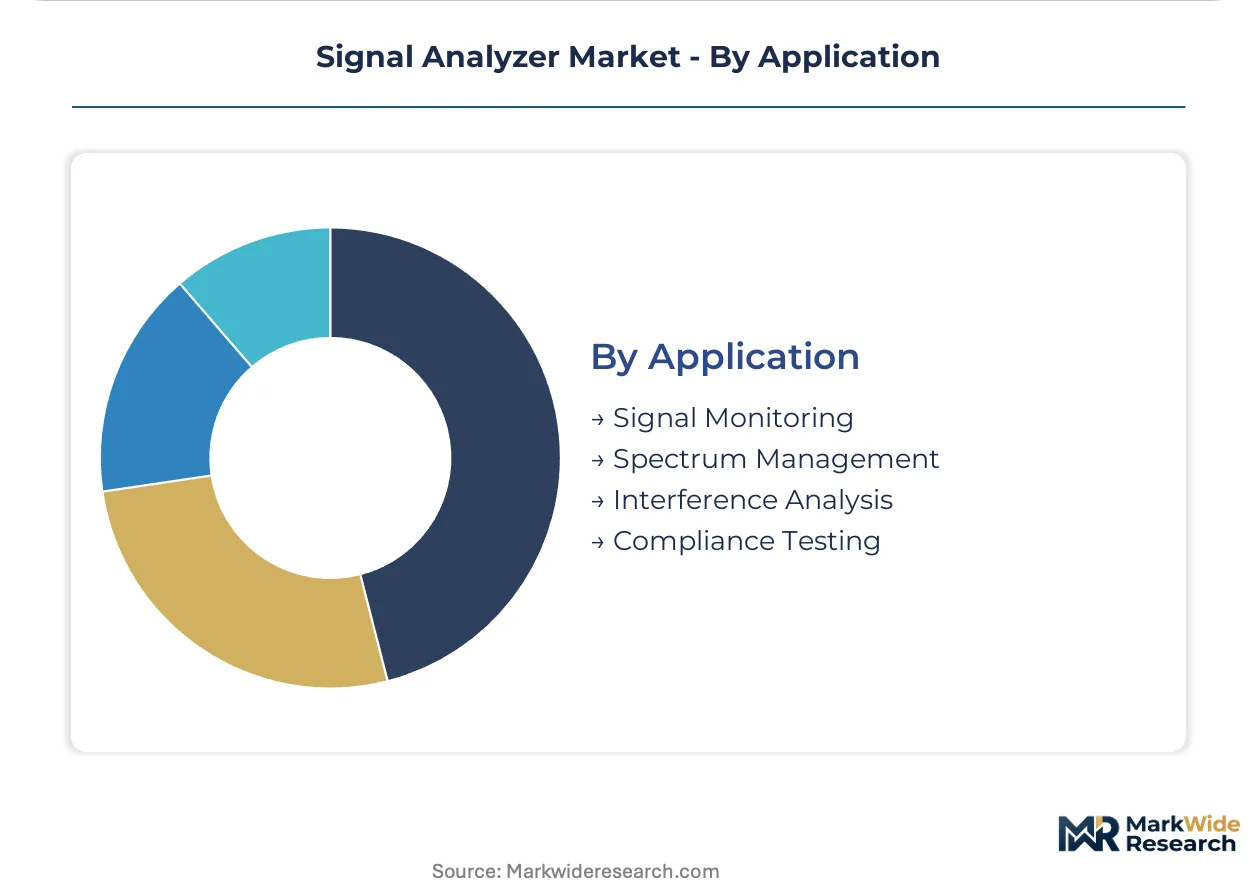
Application:
Measurement objective determines instrument configuration, with regulatory compliance imposing stricter documentation requirements than diagnostic or optimization use cases.
- Compliance Testing:Formal verification against FCC Part 15, CE marking under the EU Radio Equipment Directive, and ETSI standards requires calibrated laboratory-grade equipment with traceable uncertainty budgets.
- Interference Analysis:Identification and geolocation of spurious emissions drives demand for portable and real-time capable instruments.
- Spectrum Management:National regulatory authorities monitor frequency allocations and license compliance.
- Signal Monitoring:Continuous surveillance of designated frequency bands supports security and intelligence operations.
Regulatory mandate anchors compliance testing. Operational flexibility is expanding most quickly in interference analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European signal analyzer demand through Rohde & Schwarz headquarters and the surrounding Bavarian aerospace cluster. Defense procurement programs across NATO members funnel equipment budgets through German certification workflows. The United States, South Korea, Japan, and India concentrate complementary demand drivers spanning telecommunications infrastructure and research institutions.
United States
5G-Advanced research at MIT Lincoln Laboratory and Stanford drives vector signal analyzer procurement for millimeter-wave validation. FCC Part 15 emissions rules mandate calibrated laboratory-grade equipment for device certification. The Boston-Austin corridor hosts shared university test facilities pooling calibration schedules across multi-vendor instrument fleets.
Germany
Defense and aerospace certification workflows sustain premium benchtop system demand through TEMPEST and MIL-STD-461 compliance requirements. The EU AI Act mandates audit trails for automated interference detection algorithms sold into European markets. Bavaria's Munich-Stuttgart axis concentrates Rohde & Schwarz production and 3GPP standards development participation.
South Korea
Base station manufacturers validate 3GPP Release 18 bandwidth requirements through vector signal analyzer deployment. The national regulator enforces harmonized standards alignment with ETSI specifications for 5G-Advanced equipment. Seoul's Digital Media City cluster concentrates Samsung and LG network equipment testing facilities.
Japan
Cellular network operators deploy AI-assisted signal classification to compress mean-time-to-repair metrics for 5G base station anomalies. METI funding priorities target 6G study item participation and measurement instrumentation refresh cycles. The Yokohama-Tokyo corridor hosts NTT DoCoMo research laboratories defining next-generation protocol validation requirements.
India
Production-linked incentive schemes for domestic 5G equipment manufacturing create demand for localized test infrastructure. TRAI spectrum management mandates drive regulatory compliance analyzer procurement for network monitoring. Bangalore and Hyderabad concentrate telecom manufacturing clusters requiring certification-grade instrumentation deployment.
Signal Analyzer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered market structure where calibration ecosystems and software-defined architectures determine premium positioning. The vendor base separates into three strategic archetypes: integrated measurement platform specialists, modular test stack providers, and commoditized USB-tethered module suppliers. Consolidation pressure concentrates among high-frequency component suppliers in Taiwan and Japan. Dominant competitive moves include FPGA-based platform convergence and geographic expansion into Indian telecom manufacturing clusters.
Within the integrated platform tier, Keysight Technologies and Rohde & Schwarz exemplify calibration-anchored competitive positioning. National Instruments occupies a position representing modular PXI platform alternatives for research institutions. These three entities anchor distinct strategic approaches spanning software-defined architecture, European defense certification workflows, and configurable test stack flexibility respectively.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Anritsu Corporation |
| National Instruments |
| Tektronix |
| Viavi Solutions |
| Advantest Corporation |
| Yokogawa Electric Corporation |
| Teledyne Lecroy |
| Others |
Value Network & Pricing Analysis
Family-owned precision instrumentation specialists in Germany and Japan anchor supply discipline through captive calibration laboratories and multi-decade service relationships, creating pricing power that resists commoditization pressure from USB-tethered module competitors.
Pricing Analysis
Value-based pricing anchored to measurement throughput and uptime guarantees dominates procurement contracts for defense and aerospace certification workflows. Three-tier pricing structure across premium laboratory-grade, standard benchtop, and economy portable levels separates TEMPEST-compliant systems from basic spectrum monitoring units. Cost compression in the entry tier intensifies as software-defined radio dongles capture routine interference detection tasks. Research institutions exhibit highest price sensitivity due to grant-funded capital cycles, while NATO defense procurement programs demonstrate lowest sensitivity given MIL-STD-461 compliance mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from base station manufacturers, while authorized distributors serve mid-tier telecommunications operators and research institutions. High-frequency analog-to-digital converters and low-noise amplifiers concentrate among specialized semiconductor foundries in Taiwan, Japan, and the United States, creating single-source vulnerability for millimeter-wave instruments. FPGA supply draws from Xilinx and Intel programmable logic facilities in Malaysia and Costa Rica. Tariff exposure on precision microwave components threatens margin stability for vendors dependent on cross-border component flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over calibration infrastructure and FPGA firmware development determines margin capture across software-defined platform generations.
For Market Incumbents: Anticipate displacement pressure from modular PXI platforms by deepening captive supply of precision ADCs and LNAs through partnerships with Taiwan-based foundries. Secure defense procurement lock-in through TEMPEST-certified service depots in Germany and the United States. Cloud-native analyzer architectures represent the priority R&D allocation to capture subscription revenue from enterprise and academic users. For New Entrants and Emerging Players: Cloud-based remote access platforms offer the lowest barrier to white-space penetration in India's production-linked incentive telecom manufacturing clusters. Target field-deployable portable analyzers for 5G infrastructure maintenance crews in South Korea and Japan where incumbents underinvest in battery-optimized form factors. Pursue calibration-as-a-service bundling to differentiate from hardware-centric pricing models. For Investors and Strategic Acquirers: 3GPP Release 18 specification finalization is the leading indicator that vector signal analyzer demand will accelerate beyond current production capacity. Focus acquisition screening on FPGA firmware specialists with 6G measurement algorithm libraries and established relationships with NTT DoCoMo or Samsung research laboratories. Watch for TRAI spectrum auction timing in India as inflection signal for localized test infrastructure deployment.| Strategic Initiative | Industry Significance |
|---|---|
| FPGA Platform Convergence | Enables firmware-upgradable capabilities without hardware replacement for 5G-Advanced validation. |
| Calibration Infrastructure Expansion | Captures recurring revenue through traceable national metrology institute certification chains. |
| 6G Study Item Participation | Positions vendors to define ITU-R measurement bandwidth thresholds before specifications crystallize. |
| India Telecom Manufacturing Entry | Accesses PLI scheme-driven demand for localized 5G equipment test infrastructure in Bangalore. |
| Cloud-Native Architecture Development | Opens subscription revenue models via secure remote access to centralized measurement systems. |
Research Methodology
SEC 10-K filings, ETSI harmonized standards documentation, and defense procurement budget disclosures formed the secondary backbone, supplemented by customs trade data on high-frequency component flows. Primary interviews with RF test engineering directors, calibration laboratory managers, semiconductor foundry account executives, and telecommunications procurement officers validated demand assumptions. Bottom-up instrument shipment analysis triangulated against top-down defense and telecommunications capital expenditure estimates.
Historical trendline analysis of vector signal analyzer adoption rates informed projection modeling across the analysis window. Segmentation dimensions included product architecture, frequency range tier, end-user vertical, and geographic regulatory cluster. CAGRs derived from weighted average of technology refresh cycle compression and procurement program budget trajectories. 5G-Advanced specification timelines and 6G research funding allocations served as industry-specific forecast inputs.
The model holds under stable NATO defense spending and continuous 3GPP standardization progress; deviation in semiconductor foundry capacity constraints or EU AI Act enforcement intensity would shift trajectory. Forecasts reflect documented assumptions regarding FPGA cost curves and calibration technician labor availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Fluorescence Spectroscopy Market
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Abbe Refractometers Market
Analytical Instruments
Laser Diffraction Analyzer Market
Analytical Instruments
Surface Plasmon Resonance Market
Analytical Instruments
North America Surface Analysis Market
Analytical Instruments
Global Ultrapycnometer Market
Analytical Instruments
Semiconductor X-Ray Diffractometers Market
Analytical Instruments
Boron Analyzer Market
Analytical Instruments
Precision Balances Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Trace Chemical Detector Market
Analytical Instruments
Tunable Diode Laser Analyzer Market
Analytical Instruments
Global Raman Spectroscopy Market
Analytical Instruments
Ph Meters Market