
 Global Q-TOF Mass Spectrometry Market | 2026-2036
Global Q-TOF Mass Spectrometry Market Size, Share, and Industry Trends Forecast 2026-2036
Global Q-TOF Mass Spectrometry Market Foresight
Biotechnology firms are redrawing demand patterns as they displace academic research centers as the dominant buyer archetype for Q-TOF systems. Waters Corporation leverages its installed base in biopharma QC laboratories to sustain recurring revenue from service contracts. Bruker Corporation differentiates through high-resolution devices tailored for native mass spectrometry workflows. SCIEX anchors its position in North America with strong relationships at government laboratories requiring forensic-grade precision.
Quadrupole time-of-flight mass spectrometry combines quadrupole mass filtering with time-of-flight detection, achieving mass accuracies below 5 ppm and resolving powers exceeding 40,000 for exact-mass confirmation of complex biomolecules. The technology serves pharmaceutical profiling and proteomics applications where unambiguous molecular identification determines regulatory submission success. Benchtop systems dominate unit shipments due to their smaller footprint and reduced capital burden for contract research organizations. Hybrid analyzers command premium positioning as biotechnology firms demand seamless integration between liquid chromatography separation and high-resolution mass detection.
FDA bioanalytical method validation guidelines and EMA ICH Q14 quality standards shape instrument specifications by mandating demonstrable mass accuracy and reproducibility for regulatory submissions. EPA methods for environmental monitoring and FSSAI food safety protocols in India further fragment compliance requirements across end-use verticals. Stakeholders must monitor evolving pharmacopeial standards and decide whether to prioritize modular platform architectures or application-specific configurations.
Market Dynamics
Biotechnology procurement is displacing academic research as the dominant demand source for Q-TOF systems, tightening instrument performance specifications around regulatory submission requirements and compressing replacement cycles for legacy quadrupole platforms.
Growth Catalysts
- FDA Bioanalytical Method Validation Guidelines:These standards mandate demonstrable mass accuracy below 5 ppm for biotherapeutic submissions, forcing pharmaceutical developers to upgrade from unit-mass resolution instruments to high-resolution Q-TOF platforms.
- Native Mass Spectrometry Workflows:Biopharma QC laboratories are adopting non-denaturing analytical methods for intact protein characterization, creating demand for instruments with extended mass range and specialized ion source configurations.
- China's Pharmaceutical R&D Clusters:Concentrated investment in biologics development in Shanghai and Suzhou is accelerating instrument procurement, with domestic contract research organizations expanding high-resolution mass spectrometry capacity.
Market Restraints
- Helium Supply Volatility:Price instability for this noble gas, essential for collision cell operation in hybrid analyzers, elevates operating costs and complicates long-term budgeting for high-throughput laboratories.
- Detector Component Concentration:Microchannel plate and electron multiplier manufacturing concentrates among a limited supplier base in Germany and Japan, creating vulnerability for instrument makers dependent on just-in-time sourcing.
- Orbitrap Technology Substitution:Thermo Fisher's competing high-resolution platform offers comparable mass accuracy with different operational economics, capturing share in proteomics applications where resolving power exceeds 100,000.
Strategic Opportunities
- India's Food Safety Infrastructure:FSSAI protocol expansion for pesticide residue testing and mycotoxin screening creates instrument demand among central and state testing laboratories with limited existing high-resolution mass spectrometry capacity.
- AI-Assisted Data Interpretation:Integration of machine learning algorithms for automated compound identification and spectral library matching addresses the analytical bottleneck in complex sample analysis, differentiating next-generation platforms.
- Service Contract Unbundling:Modular maintenance offerings allowing laboratories to self-perform routine calibration and source cleaning, purchasing only specialized service interventions, open margin expansion for vendors with established installed bases.
Industry Challenges
- Mass Spectrometrist Talent Scarcity:Specialized expertise in method development for large molecule analysis remains concentrated among experienced practitioners, constraining laboratory throughput and instrument utilization rates.
- Legacy Data System Migration:Integration of new Q-TOF platforms with existing laboratory information management systems and electronic laboratory notebooks requires costly customization, delaying deployment timelines.
- Multi-Site Method Harmonization:Biopharma companies operating decentralized R&D networks face difficulty maintaining consistent performance specifications across instruments at different global facilities, complicating regulatory submission packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Q-TOF Mass Spectrometry Market |
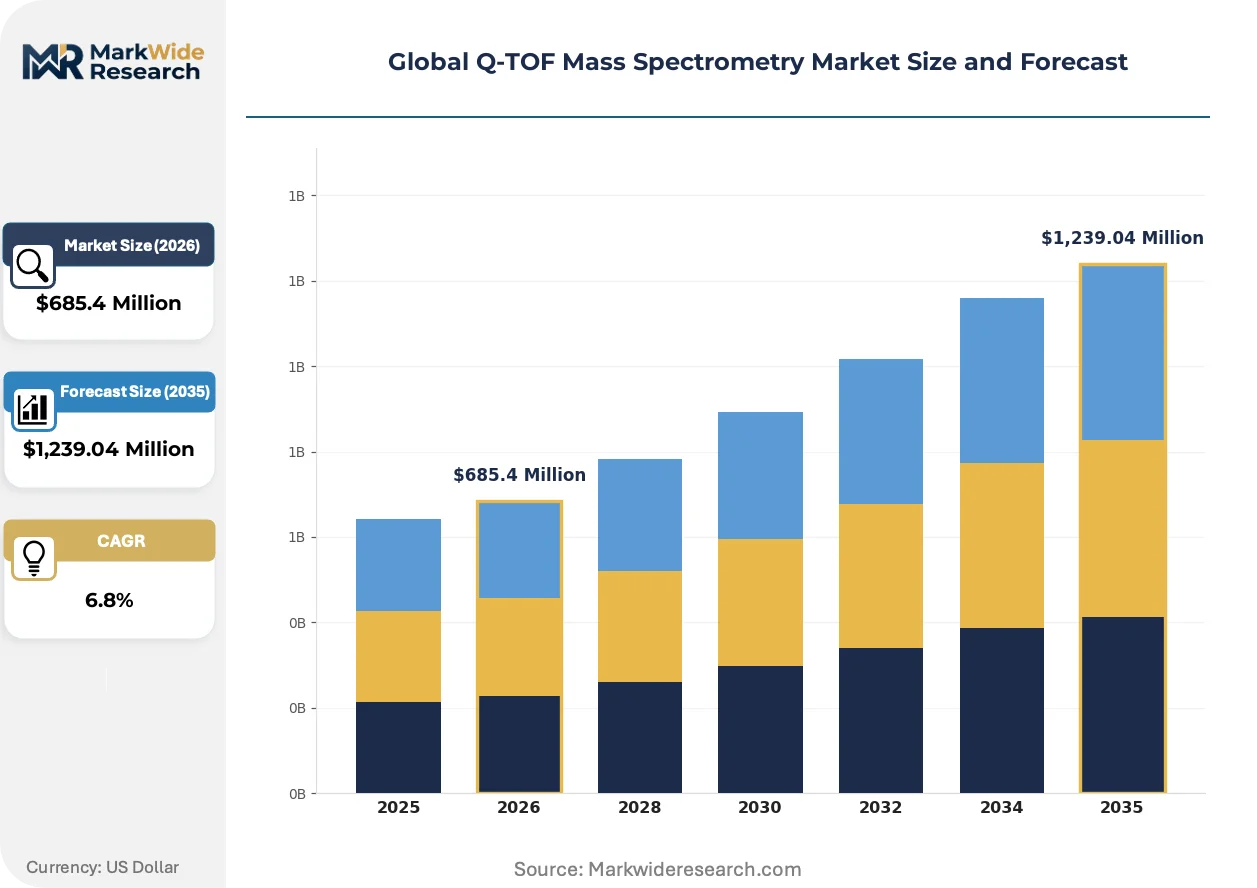
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Systems, Portable Instruments, High-Resolution Devices, Hybrid Analyzers, Vacuum Components Technology: Electrospray Ionization, Atmospheric Pressure Chemical Ionization, Matrix-Assisted Laser Desorption Ionization, Collision-Induced Dissociation, Time-of-Flight Analyzers Application: Pharmaceutical Profiling, Proteomics, Environmental Monitoring, Food Safety Testing, Petrochemical Analysis End User: Academic Research Centers, Biotechnology Firms, Government Laboratories, Contract Research Organizations, Forensic Units |
| Companies Covered | Waters Corporation, Agilent Technologies, SCIEX, Bruker Corporation, Shimadzu Corporation, Thermo Fisher Scientific, Danaher Corporation, PerkinElmer, Rigaku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Q-TOF Mass Spectrometry Market Shifts & Advancements
Instrument architecture is converging with artificial intelligence and automated sample handling, while regulatory pressure elevates data integrity requirements and buyer consolidation reshapes vendor-customer relationships.
Benchtop Q-TOF systems with integrated ion mobility separation are supplanting floor-standing hybrid platforms in contract research organization facilities. These compact configurations deliver comparable mass accuracy with reduced facility infrastructure requirements. CROs in the United States and Germany are standardizing on these systems to accelerate client onboarding and minimize method transfer validation burden.
EMA ICH Q14 quality guidelines are mandating analytical procedure lifecycle management with enhanced understanding of method performance characteristics. Pharmaceutical developers must demonstrate design space knowledge for mass spectrometry methods used in release testing. European biopharma QC laboratories are responding by investing in training programs and qualifying instrument platforms for extended operational ranges.
Consolidated procurement through centralized scientific sourcing functions is displacing decentralized laboratory purchasing authority. Large biotechnology firms are negotiating enterprise-wide service agreements and preferred vendor arrangements with standardized instrument configurations. This concentration is most visible among top-20 pharmaceutical companies headquartered in the United States, where procurement teams now mandate total cost-of-ownership analysis over initial capital expenditure evaluation.
Global Q-TOF Mass Spectrometry Market Segmentation
Q-TOF mass spectrometry segmentation reveals divergent margin structures across hardware configurations and ionization technologies. Procurement patterns in biotechnology and contract research drive premium positioning for certain configurations while commoditization pressures affect others.
Product Type:
Margin pools concentrate in high-resolution devices and hybrid analyzers where biopharma QC laboratories pay premiums for regulatory-grade performance specifications.
- Benchtop Systems:Compact configurations integrate quadrupole mass filtering with time-of-flight detection in footprint-optimized enclosures. Contract research organizations in Germany and the United States favor these systems for client onboarding flexibility and reduced facility infrastructure requirements. FDA bioanalytical method validation guidelines still mandate their performance thresholds for biotherapeutic submissions.
- Hybrid Analyzers:These platforms combine liquid chromatography separation with high-resolution mass detection in unified architectures. Biotechnology firms in China's Shanghai and Suzhou clusters demand seamless integration for intact protein characterization workflows. EMA ICH Q14 quality standards elevate their positioning for analytical procedure lifecycle management.
- High-Resolution Devices:Systems achieving mass accuracies below 5 ppm and resolving powers exceeding 40,000 command premium pricing in proteomics applications.
- Portable Instruments:Field-deployable configurations serve environmental monitoring and forensic screening with reduced performance specifications.
- Vacuum Components:Turbo molecular pumps and ion gauge assemblies represent recurring replacement demand in installed base maintenance.
Hybrid analyzers hold installed capacity. Benchtop systems are rotating up the share rankings.
Technology:
Technology selection determines method development flexibility and regulatory submission compatibility across end-use verticals.
- Electrospray Ionization:Soft ionization technique preserves non-covalent interactions for large molecule analysis. Native mass spectrometry workflows in biopharma QC laboratories depend on this technology for intact protein characterization. China's pharmaceutical R&D clusters are expanding capacity with ESI-equipped platforms.
- Collision-Induced Dissociation:Fragmentation method enables structural elucidation through controlled energy deposition. Proteomics applications requiring peptide sequencing drive demand in academic research centers and biotechnology firms. The technology underpins regulatory submission packages for biotherapeutic characterization.
- Atmospheric Pressure Chemical Ionization:Robust ionization for less polar compounds serves environmental monitoring and food safety testing protocols.
- Matrix-Assisted Laser Desorption Ionization:Pulsed laser desorption suits imaging mass spectrometry and high-molecular-weight analysis.
- Time-of-Flight Analyzers:Core detection technology delivering exact-mass confirmation with microsecond-scale measurement cycles.
Electrospray ionization dominates current procurement. Collision-induced dissociation is climbing the fastest in biopharma method development.
Application:
Application segmentation tracks regulatory pressure intensity and method standardization maturity across vertical markets.
- Pharmaceutical Profiling:Comprehensive characterization of drug candidates and biotherapeutics demands mass accuracies below 5 ppm. FDA bioanalytical method validation guidelines and EMA ICH Q14 standards mandate demonstrable reproducibility for release testing. Biotechnology firms in the United States and Germany concentrate procurement here.
- Proteomics:Large-scale protein identification and quantification requires resolving power exceeding 40,000 for complex mixture analysis. Academic research centers and government laboratories deploy these workflows for biomarker discovery. Orbitrap technology substitution creates competitive pressure in high-resolving-power applications.
- Environmental Monitoring:EPA methods for pollutant detection and pesticide residue screening shape instrument specifications.
- Food Safety Testing:FSSAI protocol expansion in India for mycotoxin screening drives demand among central testing laboratories.
- Petrochemical Analysis:Molecular characterization of complex hydrocarbon mixtures serves refinery optimization and product quality control.
Pharmaceutical profiling anchors revenue concentration. Food safety testing is gaining share fastest on regulatory infrastructure investment.
End User:
End user segmentation captures the shift from academic research dominance toward biotechnology firm procurement authority.
- Biotechnology Firms:These organizations now displace academic centers as the dominant buyer archetype for Q-TOF systems. Their procurement concentrates on high-resolution devices for biotherapeutic characterization with compressed replacement cycles for legacy quadrupole platforms. Consolidated sourcing functions at top-20 pharmaceutical companies headquartered in the United States negotiate enterprise-wide service agreements.
- Contract Research Organizations:CROs in the United States and Germany standardize on benchtop configurations to accelerate client onboarding and minimize method transfer validation burden. Their procurement prioritizes smaller footprint systems with reduced capital burden.
- Academic Research Centers:Budget constraints and shared instrument facility models constrain individual laboratory purchasing authority.
- Government Laboratories:Forensic-grade precision requirements in North America anchor SCIEX's regional positioning.
- Forensic Units:Toxicology screening and controlled substance identification demand ruggedized platforms with validated spectral libraries.
Biotechnology firms hold installed capacity. Contract research organizations are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrument manufacturing concentrates among German and Japanese component suppliers, while pharmaceutical R&D investment patterns determine regional demand intensity. FDA and EMA regulatory frameworks elevate performance requirements in mature markets, whereas China's biologics expansion and India's food safety infrastructure buildout reshape procurement geography.
United States
Biotechnology firms headquartered in Greater Boston and the San Francisco Bay Area drive procurement of high-resolution devices for biotherapeutic characterization. FDA bioanalytical method validation guidelines mandate mass accuracies below 5 ppm for regulatory submissions. Consolidated sourcing functions at top-20 pharmaceutical companies negotiate enterprise-wide service agreements with standardized instrument configurations.
Germany
Contract research organizations in Munich and Heidelberg standardize on benchtop systems to accelerate client onboarding and minimize method transfer validation burden. EMA ICH Q14 quality standards mandate analytical procedure lifecycle management with enhanced design space knowledge. Microchannel plate manufacturing concentrates in southern German industrial clusters, creating supply-side leverage for instrument makers.
China
Domestic contract research organizations in Shanghai and Suzhou expand high-resolution mass spectrometry capacity for biologics development. NMPA regulatory convergence with ICH standards elevates instrument performance specifications for local submissions. Yangtze River Delta pharmaceutical clusters concentrate procurement authority among state-backed biotech enterprises.
India
FSSAI protocol expansion for pesticide residue testing and mycotoxin screening drives instrument demand among central and state testing laboratories. CDSCO alignment with international bioanalytical standards tightens method validation requirements for generic drug approvals. Maharashtra and Gujarat-based pharmaceutical manufacturers invest in quality control infrastructure to access export markets.
Japan
PMDA quality guidelines for biotherapeutic approvals mirror EMA and FDA standards, necessitating high-resolution platforms for release testing. Tokyo and Osaka metropolitan areas host concentrated proteomics research facilities requiring resolving powers exceeding 40,000. Domestic instrument component suppliers in Nagoya industrial corridors maintain critical detector manufacturing capacity.
Global Q-TOF Mass Spectrometry Market Competitive Landscape
Concentration sits with diversified analytical instrument conglomerates and specialized mass spectrometry manufacturers competing across technology tiers. The vendor base separates into integrated platform providers, component specialists, and regional service organizations. Three archetypes dominate: full-spectrum analytical conglomerates with installed base leverage, precision instrument specialists with native mass spectrometry expertise, and chromatography-integrated platform builders. Competitive moves center on enterprise service contract expansion and modular architecture development for method transfer standardization.
Among diversified analytical instrument conglomerates, Waters Corporation and Agilent Technologies exemplify platform-integrated positioning, while Bruker Corporation represents specialized high-resolution device manufacturing. These three anchors demonstrate how vendor archetypes align with distinct buyer segments—biopharma QC laboratories, academic research centers, and government forensic facilities—through differentiated ion source configurations and service delivery models.
| Leading Market Players |
|---|
| Waters Corporation |
| Agilent Technologies |
| SCIEX |
| Bruker Corporation |
| Shimadzu Corporation |
| Thermo Fisher Scientific |
| Danaher Corporation |
| PerkinElmer |
| Rigaku Corporation |
| Others |
Supply & Pricing Matrix
Helium scarcity is prompting collision cell redesigns that simultaneously relocate component sourcing from German suppliers to Japanese alternatives and compress operating cost premiums for high-throughput laboratories. This substitution dynamic reconfigures procurement economics across hybrid analyzer tiers as buyers weigh capital expenditure against volatile noble gas expenditure.
Pricing Analysis
FDA bioanalytical method validation guidelines dictate the pricing tier structure by mandating mass accuracy thresholds that separate regulatory-grade platforms from research-use configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with biotechnology firms absorbing premium positioning for ICH Q14-compliant systems while contract research organizations gravitate toward footprint-optimized benchtop units. Cost compression in standard tiers is intensifying because detector component bottlenecks limit supplier competition. Academic research centers exhibit highest price sensitivity; top-20 pharmaceutical companies with consolidated sourcing functions demonstrate lowest sensitivity due to enterprise service agreement leverage.
Supply Chain Analysis
Germany and Japan anchor microchannel plate and electron multiplier manufacturing for detector assemblies essential to Q-TOF resolution performance. Instrument assembly draws from turbo molecular pump suppliers in southern German industrial clusters and specialized ion source fabricators in Nagoya corridors. Single-source vulnerability concentrates in MCP manufacturing, where just-in-time sourcing leaves instrument makers exposed to regional logistics disruptions. Distribution runs through direct vendor sales organizations serving biotechnology firms, with regional service subsidiaries handling contract research organization procurement in United States and German markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
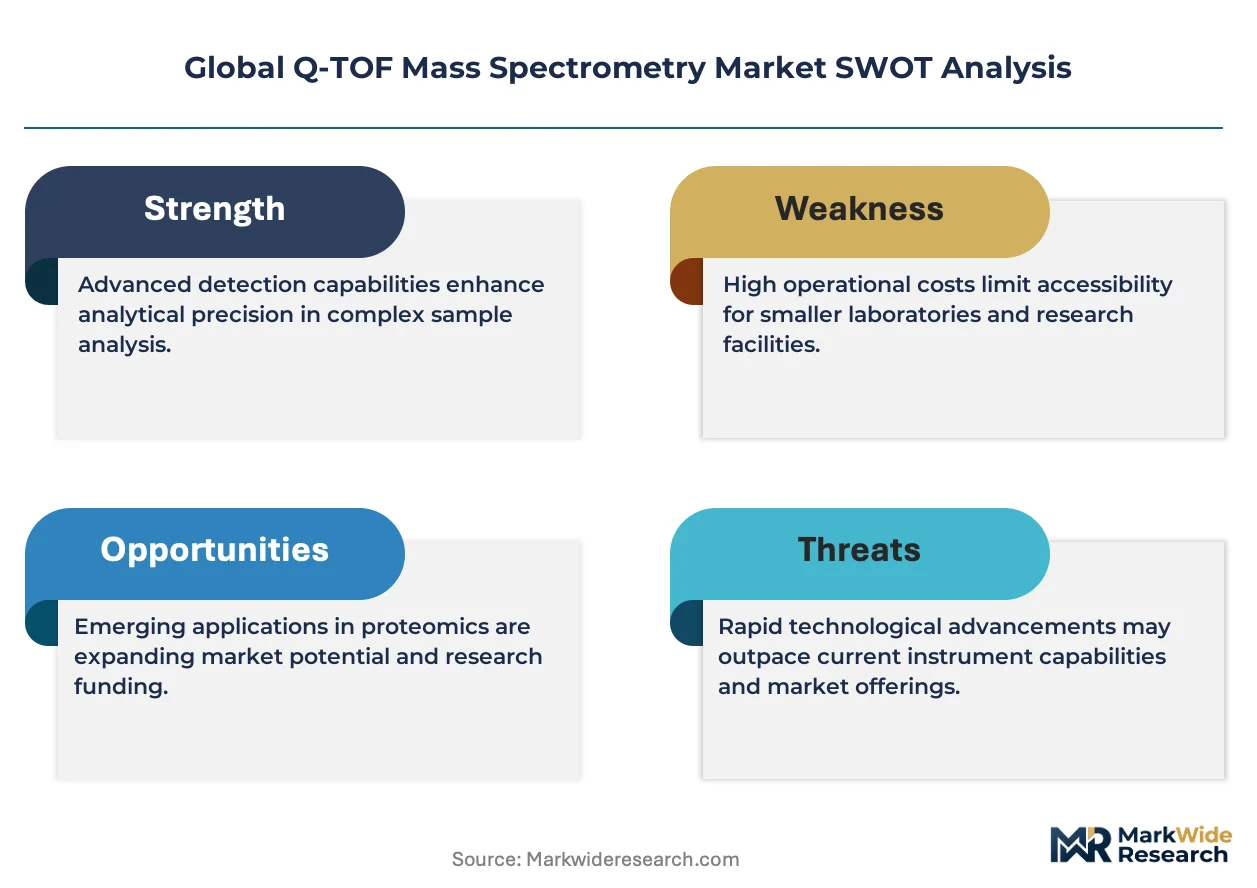
Orbitrap technology substitution represents the primary threat incumbents must neutralize through differentiated native mass spectrometry capabilities and service contract anchoring.
For Market Incumbents: Compound installed base leverage by unbundling service contracts to capture margin from self-performing laboratories while retaining specialized intervention revenue. Deepen backward integration into ion source manufacturing to reduce detector component dependency exposure. Neutralize Thermo Fisher's resolving power advantage by emphasizing seamless LC-MS integration for biopharma QC workflows.
For New Entrants and Emerging Players: Lead with AI-assisted data interpretation modules that address the analytical bottleneck in complex sample analysis, targeting India's central and state testing laboratories where FSSAI protocol expansion outpaces established vendor presence. White-space concentration exists in modular maintenance offerings for legacy quadrupole replacement cycles. Position through application-specific configurations rather than full-platform competition.
For Investors and Strategic Acquirers: Capital is best deployed toward precision instrument specialists with native mass spectrometry expertise and established relationships at government forensic facilities. Long-term viability hinges on regulatory convergence across FDA, EMA, and NMPA standards that sustains premium pricing for compliance-grade platforms. Monitor helium supply contract restructuring as inflection indicator for operating cost trajectory and collision cell technology transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Data Interpretation Integration | Machine learning algorithms differentiate next-generation platforms by automating compound identification in proteomics workflows. |
| Service Contract Unbundling | Modular maintenance offerings expand margin capture from laboratories performing routine calibration in-house. |
| Native Mass Spectrometry Capability Expansion | Extended mass range configurations secure positioning in biopharma QC laboratories adopting non-denaturing analytical methods. |
| Collision Cell Redesign for Helium Reduction | Alternative noble gas compatibility mitigates operating cost volatility and supply chain concentration risk. |
| Enterprise Sourcing Agreement Negotiation | Consolidated procurement at top-20 pharmaceutical companies locks in standardized instrument configurations and recurring revenue. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with mass spectrometry laboratory directors, biopharma QC managers, regulatory affairs specialists, and CRO procurement leads; and secondary validation through FDA bioanalytical method validation guidance documents, EMA ICH Q14 implementation reports, NMPA regulatory convergence notices, and instrument manufacturer SEC disclosures. Bottom-up triangulation cross-referenced unit shipment estimates with service contract renewal rates, while top-down verification anchored against pharmaceutical R&D expenditure patterns in United States, German, and Chinese clusters.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, ionization technology, application vertical, and end-user archetype, with particular attention to biotechnology firm procurement displacement of academic research centers. CAGRs derived from instrument replacement cycle compression rates and regulatory-driven upgrade mandates, incorporating helium price volatility scenarios and detector component supply constraints as sensitivity inputs.
Forecasts assume regulatory continuity in FDA, EMA, and NMPA regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Absorption Spectrometers Market
Analytical Instruments
Portable Particle Counter Market
Analytical Instruments
Metallurgical Microscope Market
Analytical Instruments
Process Analytical Instrumentation Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
ICP-MS System Market
Analytical Instruments
Global Electron Microscopes Market
Analytical Instruments
XRF Analyzer Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Conductivity Analyzers Market
Analytical Instruments
Logic Analyzer Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Atomic Magnetometers Market
Analytical Instruments
Real-Time Spectrum Analysis Market