
 Flame Spectrometers Market | 2026-2036
Flame Spectrometers Market Size, Share, and Industry Trends Forecast 2026-2036
Flame Spectrometers Market Foresight
Double-channel and triple-channel specification tiers is rotating demand away from legacy single-channel units in environmental and pharmaceutical testing workflows. PerkinElmer leverages its installed base in North American reference laboratories to sustain service contract renewals. Thermo Fisher Scientific anchors premium positioning through integrated software-analytics bundles. Shimadzu Corporation dominates price-competitive tenders across Asia-Pacific academic procurement channels.
Flame spectrometers are analytical instruments that atomize samples in a controlled flame environment to measure elemental concentrations via absorption or emission wavelengths, typically operating at temperatures between 2,000 and 3,000 Kelvin with detection limits reaching parts-per-billion for metals analysis. These systems serve as workhorse tools for regulatory compliance testing in water quality, food safety, and pharmaceutical raw material verification where rapid, cost-effective elemental screening remains essential. Bench-top configurations retain the largest installed base due to established laboratory infrastructure, while portable units are gaining traction in field-based geological survey and on-site environmental remediation monitoring. Atomic absorption technology leads in routine compliance applications, though inductively coupled variants command premium pricing for multi-element simultaneous detection in high-throughput quality assurance labs.
EPA Method 200 series protocols and ISO/IEC 17025 accreditation requirements in the United States, alongside REACH substance restrictions and EN standard harmonization across Europe, mandate traceable calibration chains and validated detection methodologies that directly influence instrument replacement cycles. China's GB national standards and NMPA pharmaceutical testing guidelines impose parallel technical barriers that favor suppliers with localized certification support. Stakeholders must weigh regulatory divergence against platform standardization when configuring regional product portfolios and service architectures.
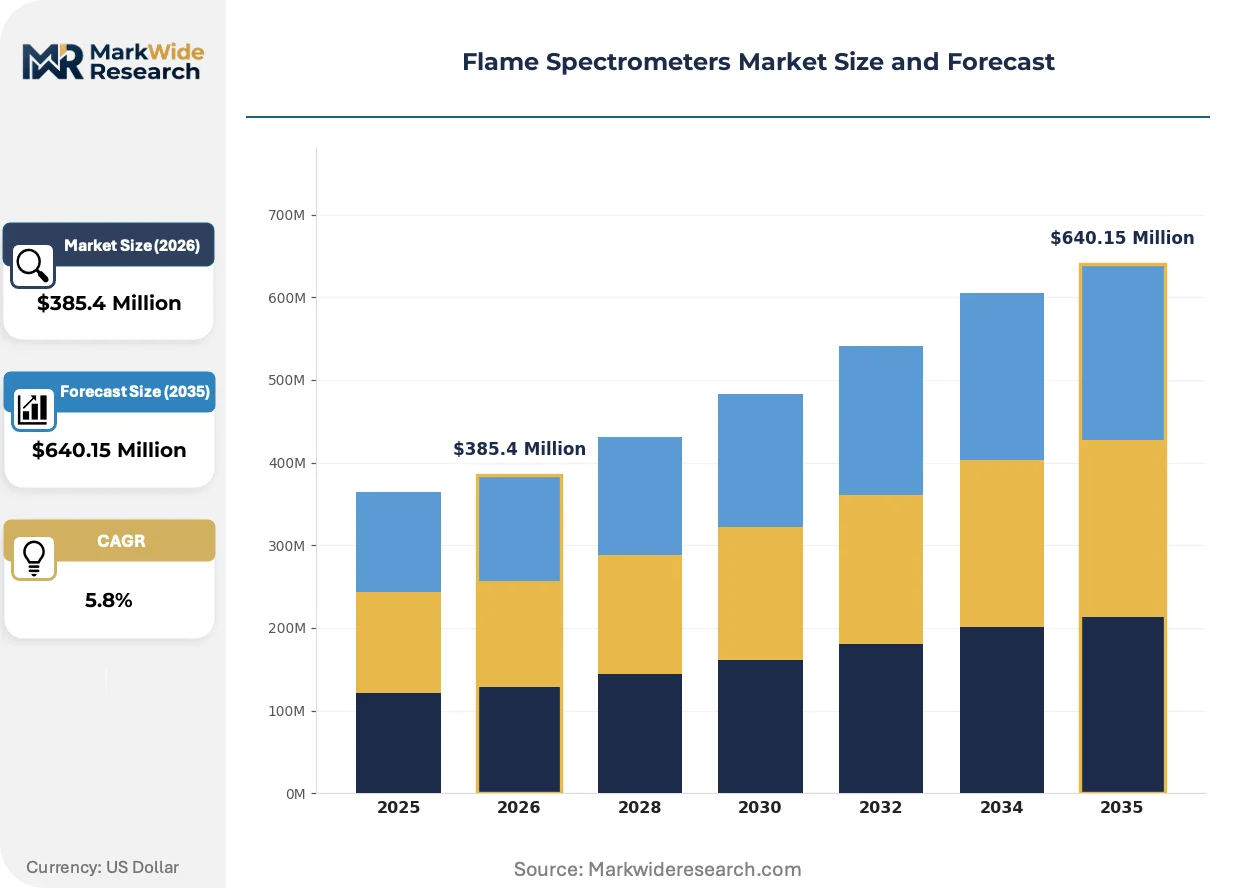
Market Dynamics
Multi-channel flame spectrometer architectures are compressing replacement cycles for legacy single-channel units across pharmaceutical and environmental testing workflows, while tightening EPA drinking water protocols and ISO/IEC 17025 accreditation mandates accelerate instrument refresh timelines.
Growth Catalysts
- EPA Method 200 series protocols:Drinking water compliance mandates in the United States require traceable calibration chains that favor validated flame atomic absorption systems over unverified alternatives.
- Pharmaceutical quality control laboratories:Purity verification protocols for raw material screening are expanding procurement of bench-top atomic absorption units with automated sample handling.
- China's environmental monitoring networks:Domestic manufacturers are scaling production of atomic absorption systems to supply provincial water quality testing stations under MEE supervision.
Market Restraints
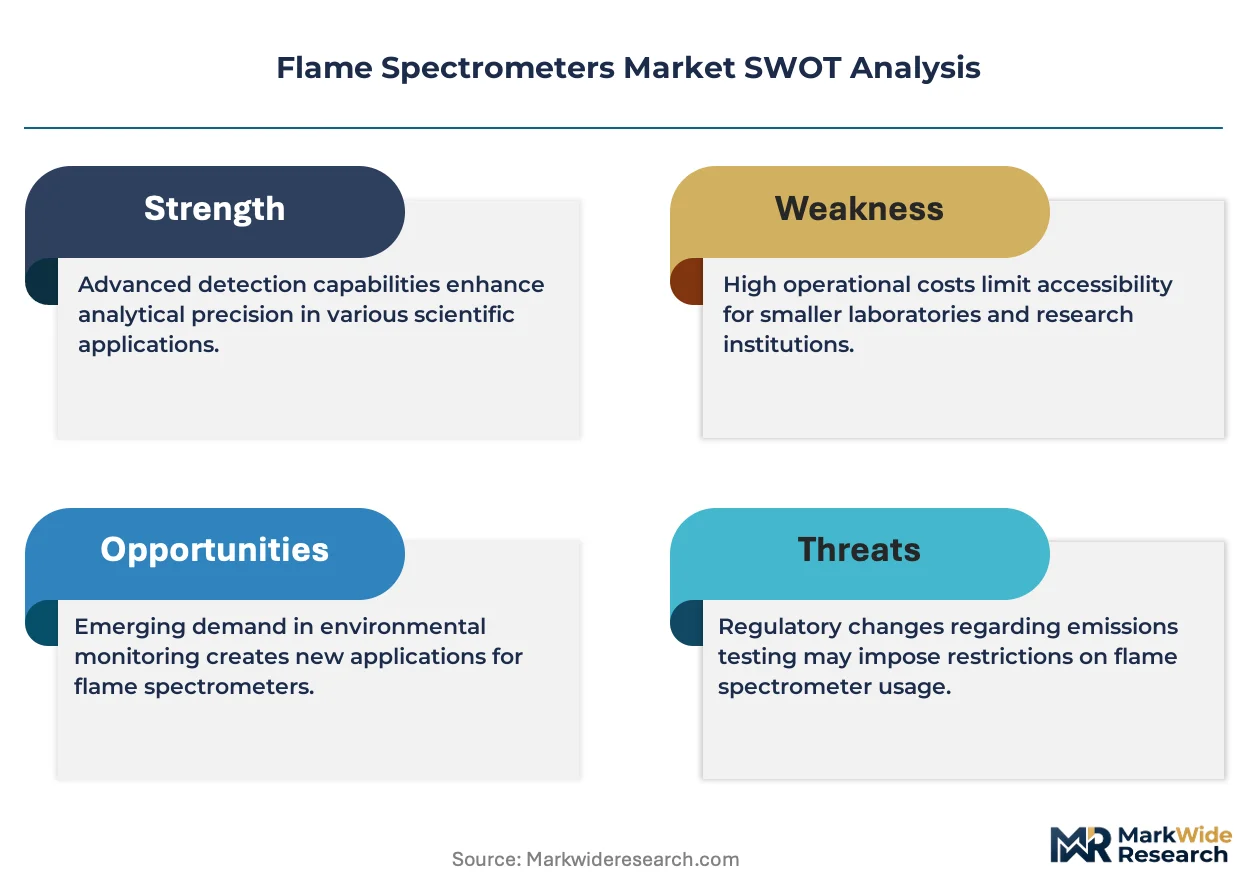
- Inductively coupled plasma substitution:ICP-OES and ICP-MS systems command premium positioning for multi-element simultaneous detection, constraining flame spectrometer pricing power in high-throughput quality assurance labs.
- Helium and argon supply volatility:Noble gas price fluctuations for plasma-based alternatives indirectly pressure flame spectrometer margins through competitive benchmarking.
- REACH substance restrictions:European chemical registration requirements impose documentation burdens on lamp and detector component sourcing, extending procurement timelines.
Strategic Opportunities
- Portable unit deployment:Field-based geological survey teams and on-site environmental remediation contractors are adopting battery-powered flame spectrometers for rapid metals screening outside laboratory infrastructure.
- GB standard harmonization:China's national standards alignment with ISO protocols creates certification pathways for dual-compliant instrument platforms serving domestic and export markets simultaneously.
- Software-analytics bundling:Integrated data management packages with automated reporting for regulatory submission represent unbundled revenue streams beyond hardware sales.
Industry Challenges
- Atomic spectroscopy technician scarcity:Specialized training requirements for flame optimization and interference correction limit operational scalability at contract testing organizations.
- Legacy LIMS integration complexity:Retrofitting multi-channel flame spectrometers into established laboratory information management systems demands custom middleware development.
- ISO/IEC 17025 accreditation timelines:Extended validation periods for method transfer and proficiency testing delay revenue recognition for instrument vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flame Spectrometers Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Channel, Double-Channel, Triple-Channel, Portable, Bench-Top Technology: Atomic Absorption, Emission, Plasma, Inductively Coupled, Laser-Based Application: Environmental Analysis, Food Testing, Pharmaceutical Quality Control, Geological Survey, Chemical Processing End User: Academic Laboratories, Research Institutions, Quality Assurance Labs, Government Agencies |
| Companies Covered | PerkinElmer, Agilent Technologies, Thermo Fisher Scientific, Shimadzu Corporation, Analytik Jena, Aurora Instruments, Beijing Haiguang Instrument, Shanghai Metash Instruments, Varian Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flame Spectrometers Market Shifts & Advancements
Automation and connectivity architectures are redefining how flame spectrometers generate value, shifting competitive differentiation from hardware specifications to integrated workflow solutions and regulatory-ready data packages.
Dual-channel and triple-channel optical configurations are decomposing the single-channel installed base by enabling simultaneous multi-element quantification without sequential lamp changes. Pharmaceutical quality control laboratories in North America and Europe are adopting these architectures for raw material release testing. The technology is decomposing traditional throughput bottlenecks in high-volume compliance environments, compressing per-sample analysis time and reducing operator intervention requirements.
EPA Method 200.7 and 200.9 revisions for trace metals in drinking water are mandating lower detection limits and stricter quality control criteria. These protocols force municipal water utilities and environmental testing firms to validate alternative methodologies or upgrade existing flame atomic absorption platforms. Instrument vendors are responding with enhanced background correction systems and automated dilution modules specifically configured for EPA compliance workflows.
Service contract unbundling is fragmenting traditional after-sales revenue models. Academic procurement channels in Asia-Pacific are negotiating à la carte maintenance agreements rather than comprehensive coverage, while reference laboratories in North America demand outcome-based uptime guarantees with penalty clauses. This behavioral shift concentrates margin pressure on vendors with limited field service density, favoring suppliers with established regional technical support networks.
Flame Spectrometers Market Segmentation
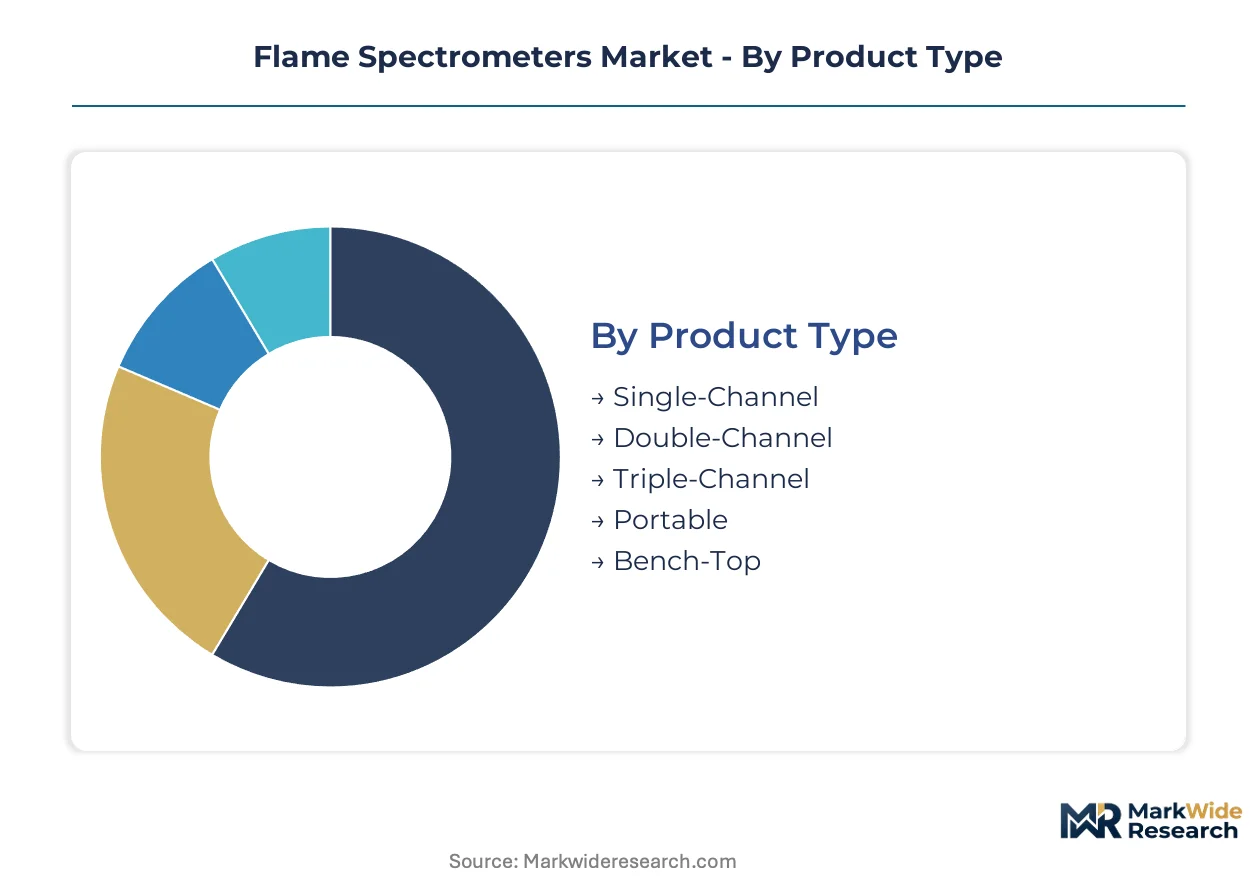
Flame spectrometer procurement patterns diverge sharply across specification tiers and deployment contexts. Regulatory compliance mandates and laboratory infrastructure constraints shape which configurations capture volume versus margin across end-use environments.
Product Type:
EPA Method 200 series protocols and ISO/IEC 17025 accreditation requirements create specification floors that disqualify entry-level units from municipal water testing contracts.
- Bench-Top:Fixed-installation systems dominate pharmaceutical quality control laboratories and reference testing facilities where automated sample handling integrates with LIMS infrastructure. North American and European compliance laboratories sustain replacement cycles through validated detection methodologies. Established volume favors Bench-Top; emerging adoption favors Portable.
- Double-Channel:Simultaneous dual-element quantification architectures compress per-sample analysis time in high-throughput environmental testing workflows. Pharmaceutical raw material release testing in FDA-regulated facilities drives specification upgrades from legacy single-channel platforms. These systems are displacing single-channel units fastest where EPA drinking water mandates enforce lower detection limits.
- Single-Channel:Legacy workhorse configuration retains presence in cost-constrained academic settings and developing-region water quality networks.
- Triple-Channel:Premium multi-element platforms serve specialized metallurgical analysis and advanced research applications requiring expanded optical range.
- Portable:Battery-powered units enable field-based geological survey teams and on-site environmental remediation contractors to execute rapid metals screening outside laboratory infrastructure.
Double-Channel specifications are climbing the fastest in regulated testing environments; Bench-Top retains the largest installed base.
Technology:
Cost tier differentiation separates routine compliance screening from premium multi-element detection capabilities.
- Atomic Absorption:Flame atomization with hollow cathode lamp excitation delivers parts-per-billion detection limits for metals analysis at operational temperatures between 2,000 and 3,000 Kelvin. Municipal water utilities under EPA supervision and provincial Chinese environmental monitoring stations anchor procurement volume for this mature technology base.
- Inductively Coupled:Plasma-based architectures command premium positioning in high-throughput quality assurance laboratories requiring simultaneous multi-element detection without sequential lamp changes. REACH substance restrictions and extended procurement timelines for noble gas supply chains constrain deployment scalability in European contract testing organizations.
- Emission:Flame emission photometry serves specialized alkali metal analysis in food safety and agricultural testing applications.
- Plasma:Broader plasma excitation platforms span environmental and industrial process control markets with expanded elemental coverage.
- Laser-Based:Emerging solid-state excitation technologies target portable deployment scenarios and reduced consumable dependencies.
Atomic Absorption captures the highest unit volume; Inductively Coupled commands the steepest expansion trajectory in premium laboratory segments.
Application:
Customer type concentration determines whether procurement prioritizes throughput, portability, or regulatory documentation depth.
- Environmental Analysis:Water quality testing stations under MEE supervision in China and EPA-regulated municipal utilities in the United States sustain demand for validated atomic absorption methodologies. Automated dilution modules and enhanced background correction systems address tightening detection limit requirements.
- Pharmaceutical Quality Control:Raw material purity verification protocols expand procurement of integrated software-analytics bundles with automated regulatory reporting capabilities. NMPA testing guidelines and FDA validation requirements favor suppliers with localized certification support.
- Food Testing:Alkali metal and heavy metal screening in agricultural product safety networks drives flame emission and atomic absorption deployment.
- Geological Survey:Field-based mineral exploration teams adopt portable configurations for rapid on-site elemental characterization.
- Chemical Processing:Industrial process control applications monitor catalyst composition and feedstock contamination in continuous manufacturing environments.
Environmental Analysis sustains the largest procurement base; Pharmaceutical Quality Control generates the fastest specification upgrade cycles.
End User:
Volume scale and margin structure invert across institutional procurement channels versus commercial testing services.
- Quality Assurance Labs:Commercial testing organizations serving pharmaceutical and food safety markets prioritize throughput optimization and regulatory-ready data packages. Outcome-based service contracts with uptime guarantees concentrate procurement toward vendors with established regional technical support density.
- Government Agencies:Provincial water quality networks and national environmental monitoring programs in China scale domestic atomic absorption system procurement under standardized GB certification requirements. Budget cycles and public tender processes extend procurement timelines relative to commercial channels.
- Academic Laboratories:Research and teaching institutions in Asia-Pacific negotiate à la carte maintenance agreements rather than comprehensive service coverage, fragmenting traditional after-sales revenue models.
- Research Institutions:Advanced method development and fundamental spectroscopy research drives demand for triple-channel and laser-based experimental platforms.
Government Agencies anchor volume procurement; Quality Assurance Labs drive premium specification adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for flame spectrometers clusters in China, Germany, Japan, and the United States, with domestic certification requirements and environmental monitoring procurement programs determining regional market penetration rates. Each geography imposes distinct regulatory specifications that favor suppliers with localized compliance infrastructure.
United States
EPA Method 200 series protocols for drinking water compliance sustain replacement demand at municipal utilities and environmental testing contractors. The agency's traceable calibration mandates disqualify unverified instruments from federal procurement. Reference laboratories in Greater Boston and the Research Triangle anchor service contract renewals for validated atomic absorption platforms.
China
Provincial water quality testing stations under MEE supervision scale procurement of domestic atomic absorption systems. GB national standards alignment with ISO protocols creates dual-compliant certification pathways. Beijing and Shanghai host the densest concentrations of instrument manufacturers serving both domestic environmental networks and export markets.
Germany
REACH substance restrictions and EN standard harmonization impose documentation burdens on component sourcing for lamp and detector assemblies. The country's chemical registration requirements extend procurement timelines for European contract testing organizations. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia concentrate precision optics manufacturing for spectroscopy components.
Japan
METI industrial standards and JIS certification requirements shape instrument specifications for domestic pharmaceutical quality control laboratories. The regulator's emphasis on automated sample handling integration drives specification upgrades in FDA-regulated facilities. Osaka-based analytical instrument manufacturers supply regional academic procurement channels across Asia-Pacific.
India
BIS technical standards for laboratory equipment and CDSCO pharmaceutical testing guidelines create parallel certification barriers for imported flame spectrometers. The country's environmental monitoring expansion under Central Pollution Control Board programs sustains demand for cost-optimized atomic absorption units. Maharashtra and Gujarat host the primary clusters of contract testing organizations driving instrument procurement volume.
Flame Spectrometers Market Competitive Landscape
Concentration sits with diversified analytical instrument conglomerates and specialized atomic spectroscopy manufacturers competing across distinct specification tiers. The vendor landscape organizes around three strategic archetypes: premium integrated-platform suppliers, mid-market regional specialists, and emerging domestic manufacturers in high-volume procurement markets. Competitive dynamics center on software-analytics bundling and service contract unbundling rather than pure hardware differentiation. Geographic expansion through localized certification support and outcome-based uptime guarantees represent the dominant competitive moves.
Within the premium-platform tier, PerkinElmer and Thermo Fisher Scientific occupy positions anchored by North American reference laboratory relationships and integrated regulatory reporting capabilities. Shimadzu Corporation exemplifies the Asia-Pacific specialist archetype with dense technical support networks across academic procurement channels. Among China-based manufacturers, Beijing Haiguang Instrument and Shanghai Metash Instruments represent the domestic-scale archetype serving provincial environmental monitoring networks under MEE programs with price-competitive atomic absorption platforms.
| Leading Market Players |
|---|
| PerkinElmer |
| Agilent Technologies |
| Thermo Fisher Scientific |
| Shimadzu Corporation |
| Analytik Jena |
| Aurora Instruments |
| Beijing Haiguang Instrument |
| Shanghai Metash Instruments |
| Varian Medical Systems |
| Others |
Supply & Pricing Matrix
Helium and argon substitution in plasma-based alternatives is compressing flame spectrometer pricing power while simultaneously shifting procurement geography toward domestic Chinese manufacturers and German precision optics clusters.
Pricing Analysis
EPA Method 200 series protocols dictate the pricing tier structure across municipal water testing contracts. Pricing stratifies across validated premium platforms, mid-range automated systems, and economy single-channel units. Cost compression in the economy tier is intensifying because domestic Chinese manufacturers are scaling production for provincial environmental networks. Academic laboratories in Asia-Pacific exhibit highest price sensitivity through à la carte service negotiations, while North American reference laboratories demonstrate lowest sensitivity due to outcome-based uptime guarantee demands.
Supply Chain Analysis
China, Germany, and Japan anchor flame spectrometer manufacturing through distinct specialization patterns. China scales atomic absorption platform assembly; Germany concentrates precision optics and hollow cathode lamp production; Japan supplies automated sample handling modules. Component sourcing draws from noble gas suppliers for plasma alternatives, optical-grade glass manufacturers, and specialized detector foundries. Single-source vulnerability concentrates in hollow cathode lamp rare earth element supply. Distribution runs through direct sales teams for pharmaceutical quality control laboratories and public tender processes for government environmental monitoring networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-analytics bundling and unbundled service contracts are expanding faster than hardware sales, creating a recurring-revenue layer that reshapes vendor economics and customer retention strategies.
For Market Incumbents: Consolidate field service density in North American reference laboratory corridors to defend against outcome-based contract penalties. Lock in hollow cathode lamp supply agreements to mitigate rare earth price volatility. Deepen backward integration into precision optics manufacturing to protect margin structure from German component cost escalation. For New Entrants and Emerging Players: Differentiate on portable battery-powered architectures for geological survey contractors and environmental remediation teams. Target China's provincial water quality networks under MEE supervision where domestic certification requirements favor local assembly partnerships. Pursue software-analytics bundling as primary go-to-market angle rather than hardware-only positioning. For Investors and Strategic Acquirers: EPA Method 200 series protocol revisions reshape the acquisition landscape by mandating detection limit upgrades that accelerate replacement cycles. Five-to-ten year viability favors vendors with integrated regulatory reporting capabilities and established ISO/IEC 17025 validation support. Target acquisition archetypes include regional service specialists with dense technical networks. Signal to monitor: GB standard harmonization progress enabling dual-compliant platform certification.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Analytics Bundling | Integrated regulatory reporting packages capture unbundled revenue beyond hardware transactions. |
| Portable Unit Development | Battery-powered architectures penetrate field-based geological survey and remediation monitoring applications. |
| Domestic Certification Investment | GB standard alignment and NMPA pharmaceutical testing support unlocks China provincial procurement channels. |
| Service Contract Unbundling | À la carte maintenance agreements address Asia-Pacific academic price sensitivity while preserving margin. |
| Backward Integration into Optics | In-house hollow cathode lamp production mitigates rare earth supply volatility and German component dependency. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with atomic spectroscopy technicians, laboratory managers at contract testing organizations, environmental compliance officers, and aftermarket service heads; alongside secondary validation through EPA protocol documentation, ISO/IEC 17025 accreditation records, Chinese GB standard filings, and customs trade data for analytical instrument imports. Bottom-up instrument shipment estimates triangulated against top-down laboratory infrastructure spending projections.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product architecture, detection technology, end-use application, and institutional procurement channel. CAGRs derived from replacement cycle compression rates, regulatory mandate adoption curves, and domestic manufacturing scale trajectories. Forecast inputs incorporated EPA protocol revision timelines and MEE provincial network expansion schedules.
Decision-makers should treat outputs as directional under assumptions of stable noble gas supply chains and continued EPA enforcement intensity; material deviation would warrant model refresh. Recalibration cycles align with material shifts in regulatory protocol adoption and domestic Chinese manufacturing scale milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Particle Counters Market
Analytical Instruments
EPR (ESR) Spectrometer Market
Analytical Instruments
High-Vacuum Gauge Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
Infrared Spectroscopy Devices Market
Analytical Instruments
Electron Microscope Sample Preparation Market
Analytical Instruments
Absorption Spectrometers Market
Analytical Instruments
Global IR Spectroscopy Market
Analytical Instruments
Turbidimeter Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Analytical Instrumentation Market
Analytical Instruments
Air Sampling Equipment Market
Analytical Instruments
X-Ray Fluorescence Analyzer Market
Analytical Instruments
Laser Probe Market
Analytical Instruments
Global Laboratory Electronic Balance Market