
 Infrared Spectroscopy Devices Market | 2026-2036
Infrared Spectroscopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Spectroscopy Devices Market Foresight
REACH is restructuring material compliance requirements for infrared spectroscopy devices sold into European pharmaceutical and environmental testing markets. Thermo Fisher Scientific leverages its vertical integration in optical component manufacturing to sustain margin control across FTIR and NIR product lines. Agilent Technologies anchors its position through deep channel partnerships with research institutions in North America and Asia. PerkinElmer differentiates via specialized software ecosystems that integrate spectral libraries with regulatory reporting workflows.
Infrared spectroscopy devices measure molecular absorption across the near-infrared, mid-infrared, and far-infrared regions, typically spanning wavelengths from 780 nm to 1 mm, to identify functional groups and quantify chemical composition. These instruments serve primary commercial purposes in pharmaceutical raw material verification, polymer identification, and environmental contaminant detection. FTIR spectrometers dominate installed base value due to their resolution advantages in research settings, while portable spectrometers represent the fastest-expanding demand pool as food safety inspectors and pharmaceutical field teams adopt handheld units for at-line testing. Quality control applications command the largest revenue share because batch release protocols mandate documented spectral analysis, though process monitoring is gaining traction as manufacturers implement continuous production lines.
FDA process analytical technology guidelines, EPA methods for environmental contaminant detection, and REACH substance identification requirements collectively shape product development priorities and validation protocols for device manufacturers. EMA good manufacturing practice standards for spectroscopic method validation create additional compliance layers for vendors targeting European pharmaceutical customers. Stakeholders must monitor evolving pharmacopeial standards for NIR method transferability as regulatory bodies harmonize acceptance criteria across jurisdictions.
Market Dynamics
Portable NIR spectrometers are electrifying pharmaceutical quality control workflows, compressing batch release timelines from days to minutes while forcing benchtop FTIR vendors to defend installed base positions through software differentiation rather than hardware performance alone.
Growth Catalysts
- FDA Process Analytical Technology:Inline spectroscopic monitoring mandates are restructuring pharmaceutical manufacturing compliance requirements, creating pull for real-time analytical devices across US production facilities.
- Food safety field inspection:Agricultural commodity inspectors in grain-exporting economies are adopting handheld units for at-line mycotoxin screening, expanding addressable demand beyond laboratory settings.
- Polymer recycling identification:Mechanical recycling facilities require rapid resin classification to meet ECHA substance identification protocols, driving portable mid-IR adoption in European waste processing plants.
Market Restraints
- Detector material concentration:Mercury-cadmium-telluride supply concentrates among a limited set of specialty chemical producers, exposing device manufacturers to input cost volatility and qualification delays.
- Method validation burden:EMA good manufacturing practice standards for spectroscopic method transferability impose multi-year certification timelines that extend sales cycles for European pharmaceutical customers.
- Raman spectroscopy substitution:Water-insensitive Raman systems are capturing applications in aqueous sample analysis where mid-IR faces fundamental physical limitations.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO quality control modernization initiatives are expanding procurement budgets for raw material verification systems at domestic generic API producers.
- Carbon capture solvent monitoring:Post-combustion amine scrubbing facilities require continuous CO2 loading measurement, creating emerging demand for process-embedded NIR analyzers in industrial emissions control.
- Cloud spectral library integration:Subscription-based reference database access is displacing perpetual-license software models, enabling recurring revenue streams and reducing customer acquisition friction.
Industry Challenges
- Chemometric modeling expertise scarcity:Multivariate calibration development requires specialized statistical competencies that outpace university analytical chemistry program output, constraining customer self-sufficiency in method deployment.
- Legacy LIMS integration complexity:Laboratory information management systems deployed in the 2000s lack native REST API architectures, forcing custom middleware development for spectral data pipeline connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Spectroscopy Devices Market |
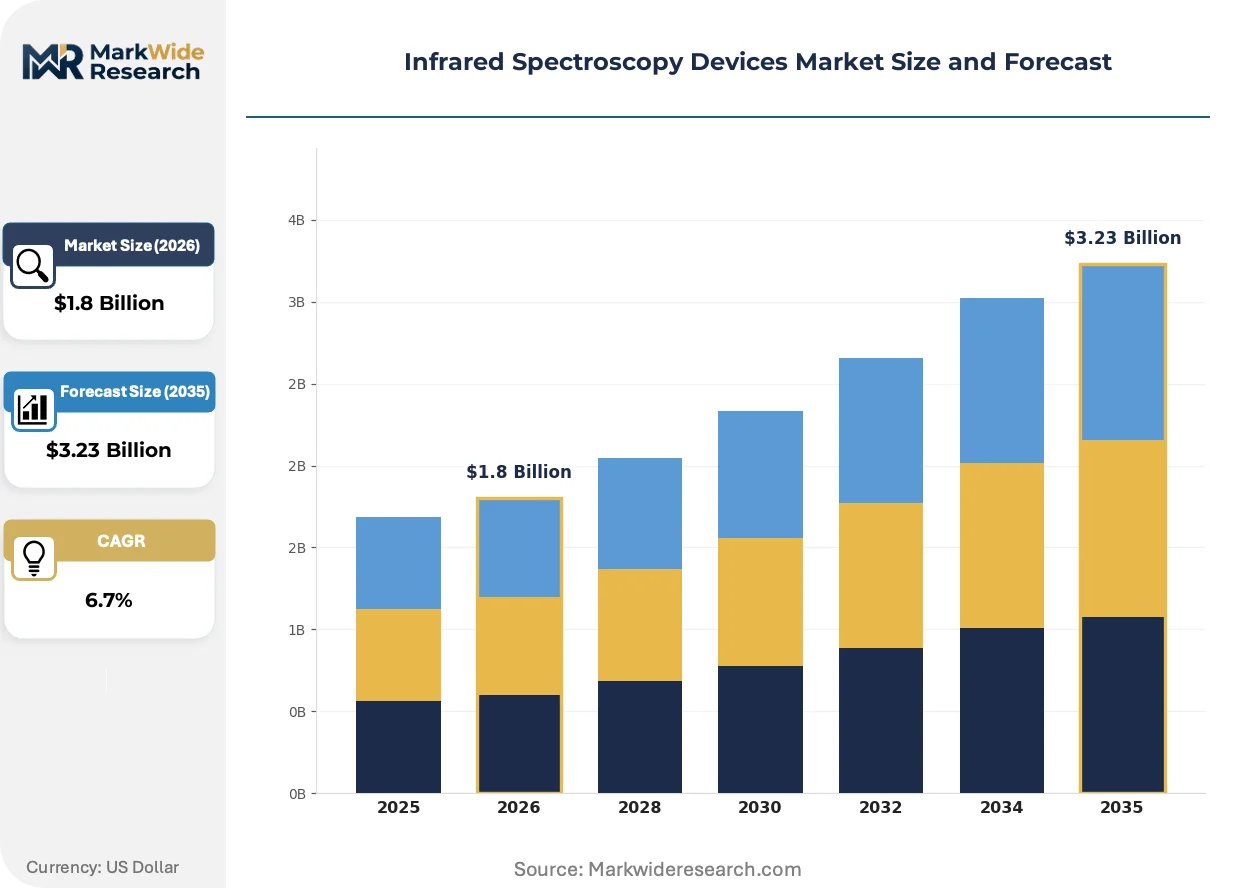
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FTIR Spectrometers, Dispersive Spectrometers, NIR Spectrometers, Portable Spectrometers End User: Pharmaceuticals, Food & Beverage, Environmental Testing, Research Institutions Application: Material Analysis, Quality Control, Research & Development, Process Monitoring Technology: Multi-Channel Detection, Micro Fourier Transform, Hollow Fiber Technology, Laser-Based Systems |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, PerkinElmer, Shimadzu Corporation, Bruker Corporation, ZEISS, HORIBA, Sartorius AG, JASCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Spectroscopy Devices Market Shifts & Advancements
Computational spectroscopy and miniaturized optical engines are compressing the performance gap between portable and laboratory-grade instruments, eroding traditional procurement hierarchies based on form-factor prestige.
MEMS-based Michelson interferometers are electrifying portable FTIR development by replacing macroscopic moving mirror assemblies with silicon-fabricated electrostatic actuators. Pharmaceutical field teams are adopting these units for raw material identification at receiving docks. The technology is compressing unit cost structures while maintaining resolution adequate for functional group fingerprinting.
REACH substance identification requirements are mandating analytical confirmation for imported chemical mixtures above specified tonnage thresholds. Testing laboratories must maintain documented spectral libraries traceable to certified reference materials. European environmental and pharmaceutical testing facilities are upgrading from dispersive to interferometric architectures to meet enhanced data integrity standards.
Instrument-as-a-service contracting is displacing capital purchase models among mid-sized contract research organizations. Monthly subscription fees bundle hardware, calibration maintenance, and cloud-based spectral library access. North American pharmaceutical outsourcing partners are driving this shift to preserve balance sheet flexibility amid pipeline funding volatility.
Infrared Spectroscopy Devices Market Segmentation
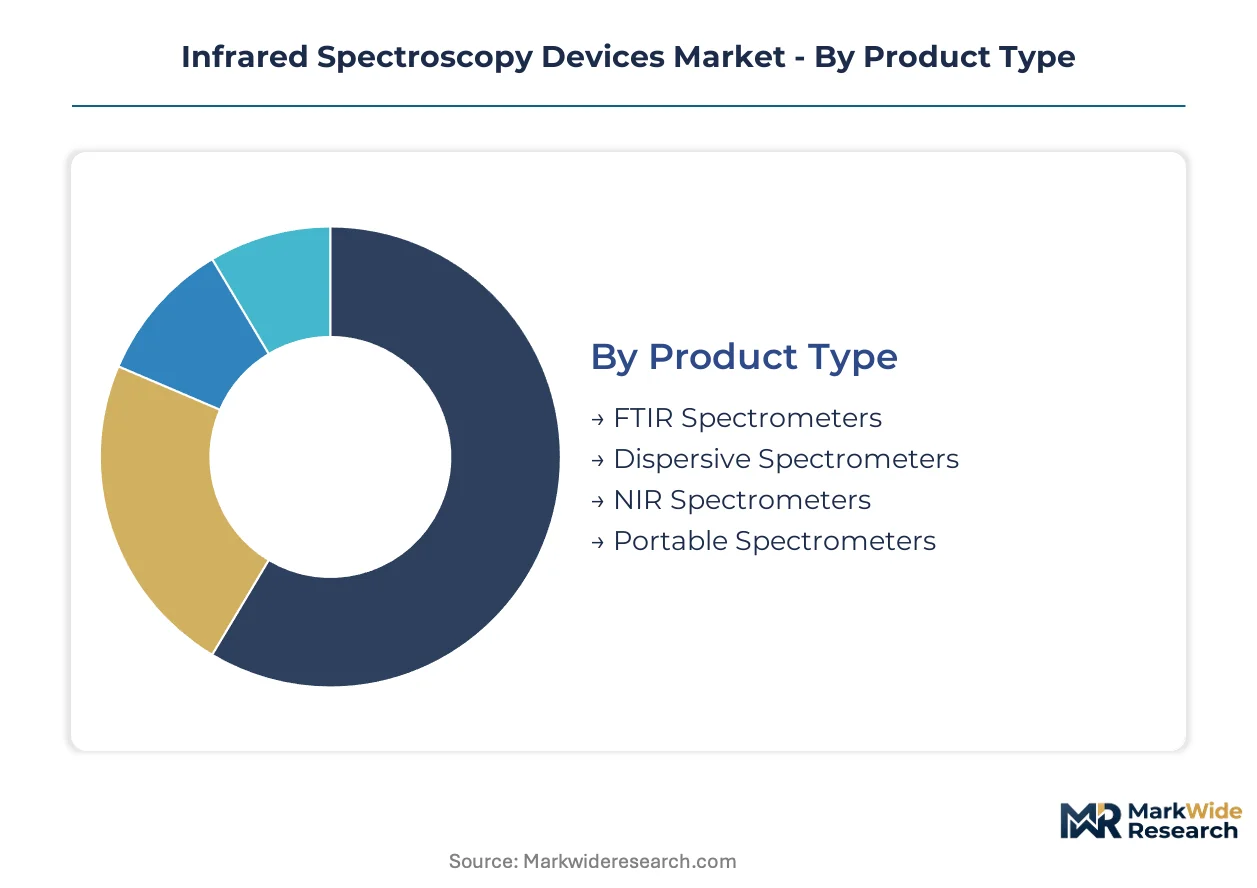
Segmentation reveals how infrared spectroscopy devices embed across laboratory, field, and production line contexts. Procurement patterns diver sharply between capital-intensive research installations and operational technology budgets for at-line verification.
Product Type:
Standalone benchtop systems dominate pharmaceutical quality control laboratories, while embedded process analyzers integrate directly into manufacturing lines for real-time compliance.
- FTIR Spectrometers:These interferometric systems deliver sub-wavenumber resolution through Michelson-based optical benches with cooled mercury-cadmium-telluride detectors. Demand concentrates in German pharmaceutical quality control laboratories where EMA good manufacturing practice standards mandate documented spectral traceability for batch release protocols.
- Portable Spectrometers:Handheld units employ solid-state optical engines and uncooled indium gallium arsenide detectors to enable field-deployable material verification. Agricultural commodity inspectors in grain-exporting economies are adopting these for at-line mycotoxin screening, compressing testing timelines from laboratory dispatch to dockside minutes.
- NIR Spectrometers:Near-infrared systems exploit overtone and combination bands for rapid quantitative analysis without sample preparation.
- Dispersive Spectrometers:Grating-based architectures persist in environmental monitoring stations requiring ruggedized continuous operation.
Volume placements concentrate in FTIR Spectrometers; the faster expansion belongs to Portable Spectrometers.
End User:
Customer procurement authority ranges from centralized research capital budgets to distributed operational technology spending in manufacturing facilities.
- Pharmaceuticals:Quality control departments deploy FTIR and NIR systems for raw material identification, polymorph screening, and finished product verification. CDSCO quality control modernization initiatives in India are expanding procurement budgets for raw material verification systems at domestic generic API producers.
- Environmental Testing:Commercial laboratories and regulatory agencies employ infrared spectroscopy for contaminant detection and emissions monitoring. EPA methods for environmental contaminant detection mandate specific interferometric configurations for compliance documentation.
- Food & Beverage:Processors utilize rapid compositional analysis for ingredient authentication and nutritional labeling verification.
- Research Institutions:Academic and government laboratories drive demand for high-resolution instrumentation in materials characterization and fundamental spectroscopy research.
Procurement volume clusters in Pharmaceuticals; the steepest expansion trajectory is emerging in Food & Beverage safety applications.
Application:
Use case segmentation distinguishes between discrete sample testing workflows and continuous process analytical technology implementations.
- Quality Control:Batch release protocols mandate documented spectral analysis for identity, purity, and potency verification. FDA Process Analytical Technology guidelines are restructuring compliance requirements for inline spectroscopic monitoring across US production facilities.
- Process Monitoring:Real-time analyzers embed within continuous manufacturing lines to enable immediate deviation detection. Post-combustion amine scrubbing facilities for carbon capture require continuous CO2 loading measurement, creating emerging demand for process-embedded NIR analyzers.
- Material Analysis:Identification and quantification of unknown substances supports forensic, regulatory, and research objectives.
- Research & Development:Method development and fundamental spectroscopic studies drive demand for highest-resolution instrumentation.
Quality Control commands the largest installed base; Process Monitoring is climbing the fastest as continuous manufacturing adoption accelerates.
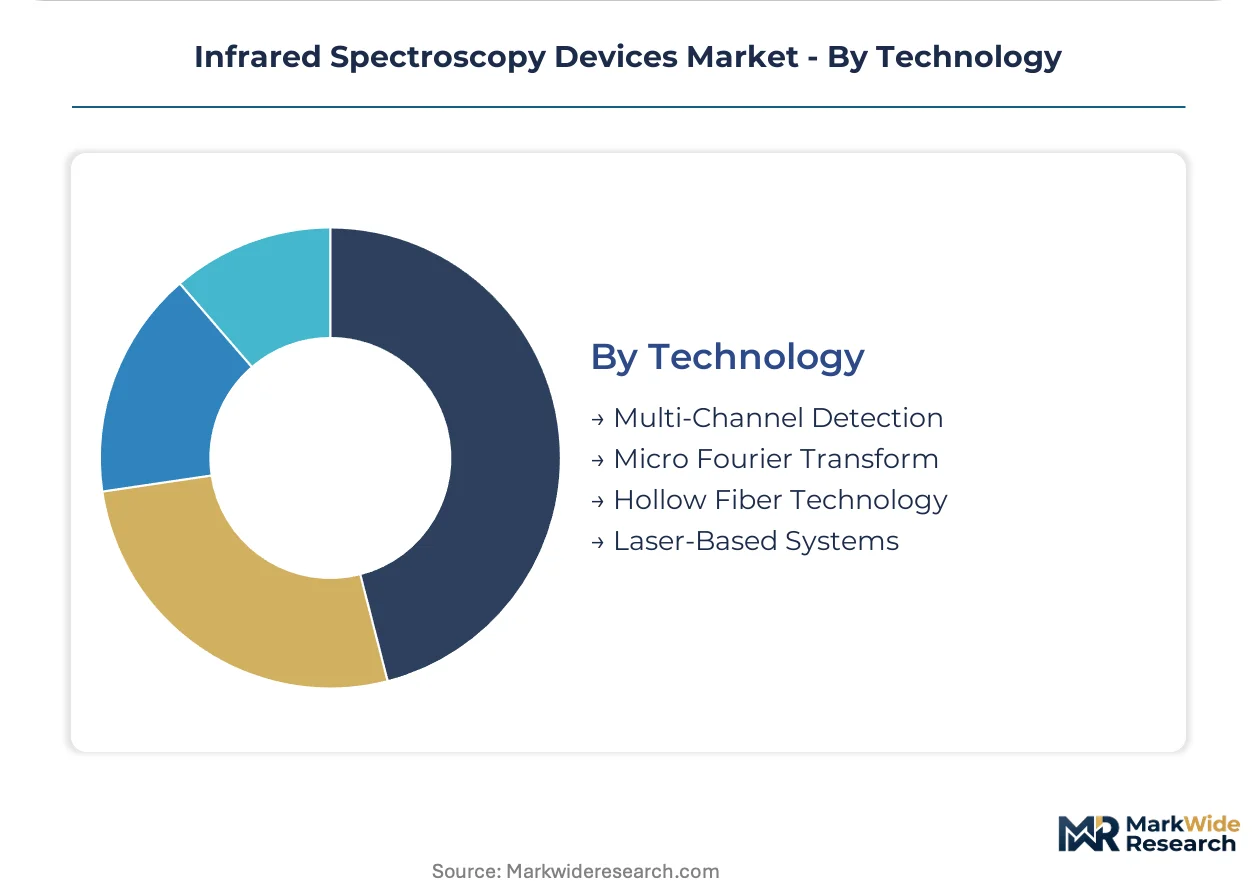
Technology:
Detection and interferometer architectures differentiate performance tiers and integration flexibility for specific analytical challenges.
- Multi-Channel Detection:Array detector configurations enable simultaneous spectral acquisition across broad wavelength ranges. Pharmaceutical field teams are adopting MEMS-based Michelson interferometers with multi-channel detection for raw material identification at receiving docks.
- Laser-Based Systems:Quantum cascade and interband cascade lasers provide tunable mid-infrared sources with high spectral brightness. Environmental monitoring networks in industrialized regions deploy these for trace gas detection with parts-per-billion sensitivity.
- Micro Fourier Transform:Miniaturized interferometric engines compress optical benches into handheld form factors.
- Hollow Fiber Technology:Gas-filled waveguides enable long-path absorption measurements for sensitive vapor-phase analysis.
Deployment volume centers on Multi-Channel Detection; Laser-Based Systems are gaining share fastest in emissions monitoring applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in pharmaceutical manufacturing hubs concentrate procurement authority for analytical instrumentation. India's pharmaceutical clusters, Germany's chemical corridor, and the US research triangle drive divergent specification requirements across regulatory jurisdictions.
United States
FDA Process Analytical Technology guidelines mandate inline spectroscopic monitoring across pharmaceutical production facilities. CDER quality control modernization programs expand procurement budgets for raw material verification systems at domestic API producers. Greater Boston's biotech corridor anchors demand for high-resolution FTIR systems in contract research organizations.
Germany
Merck KGaA and BASF operate large analytical chemistry procurement programs serving EMA good manufacturing practice compliance. REACH substance identification requirements mandate documented spectral libraries traceable to certified reference materials. The Rhine-Main chemical corridor concentrates demand for interferometric architectures in environmental and pharmaceutical testing facilities.
India
CDSCO quality control modernization initiatives expand procurement budgets for raw material verification systems at domestic generic API producers. BIS certification requirements for imported analytical instruments reshape vendor qualification protocols. Hyderabad's pharmaceutical manufacturing cluster drives adoption of portable NIR spectrometers for at-line testing workflows.
China
NMPA good manufacturing practice standards for spectroscopic method validation create compliance layers for domestic pharmaceutical manufacturers. MIIT industrial upgrading programs subsidize analytical instrumentation procurement in advanced materials sectors. The Yangtze River Delta's chemical industry corridor concentrates demand for process-embedded analyzers in continuous manufacturing lines.
Japan
METI carbon neutrality roadmaps drive demand for process analyzers in industrial emissions control applications. PMDA quality guidelines for pharmaceutical manufacturing reshape spectroscopic method validation requirements. The Kansai region's polymer and electronics manufacturing base sustains procurement of material identification systems for resin classification workflows.
Infrared Spectroscopy Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across instrument tiers, creating a bifurcated structure where scale-driven portfolio breadth confronts targeted application expertise. The vendor base organizes around three strategic archetypes: integrated life science conglomerates with captive optical component supply, mid-sized analytical instrumentation specialists with deep software ecosystems, and regional fabricators serving price-sensitive emerging market procurement. Dominant competitive moves include backward integration into detector material supply chains and cloud-based spectral library subscription models that displace perpetual-license software revenue.
Among diversified life science conglomerates, Thermo Fisher Scientific exemplifies the integrated archetype through captive optical component manufacturing, while Agilent Technologies occupies a position emphasizing channel depth with research institutions. PerkinElmer represents the specialized software ecosystem approach, anchoring differentiation through regulatory reporting workflow integration rather than hardware performance alone.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| PerkinElmer |
| Shimadzu Corporation |
| Bruker Corporation |
| ZEISS |
| HORIBA |
| Sartorius AG |
| JASCO |
| Others |
Supply & Pricing Matrix
Pharmaceutical quality control laboratories in Germany and the United States are mandating documented spectral traceability for batch release protocols, forcing device manufacturers to qualify mercury-cadmium-telluride detectors through extended validation timelines that compress margins on standard-tier instruments.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to FTIR systems with pre-qualified detector modules, while spot inventory of portable NIR units trades at discounts when agricultural commodity inspectors delay procurement. Three-tier pricing structure across premium, standard, and economy levels separates EMA-validated pharmaceutical systems from environmental monitoring configurations and price-sensitive educational bundles. Cost compression in the economy tier is intensifying because Chinese regional fabricators are flooding Asian markets with uncooled indium gallium arsenide alternatives. Contract research organizations exhibit the highest price sensitivity due to instrument-as-a-service contracting displacing capital purchase models, while German chemical conglomerates prioritize qualification speed over unit cost.
Supply Chain Analysis
Refurbishment flows for cooled mercury-cadmium-telluride detectors create secondary supply channels that extend component lifecycles and dampen new-detector pricing volatility. Optical bench fabrication concentrates in Germany, Japan, and the United States, with MEMS-based Michelson interferometer wafer processing anchored in Taiwan and South Korea. Mercury-cadmium-telluride supply draws from a limited set of specialty chemical producers in the United States and Belgium, exposing device manufacturers to input cost volatility and qualification delays. Tariff exposure on precision optical components shipped from German fabrication facilities to North American assembly plants represents the dominant structural risk. Distribution runs through authorized service organizations that bundle installation, validation, and cloud spectral library access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The infrared spectroscopy devices market is becoming a vertical-integration race as manufacturers pursue captive control over mercury-cadmium-telluride detector supply to defend margin structures against raw material volatility.
For Market Incumbents: Acquire specialty chemical producers with qualified mercury-cadmium-telluride capacity to secure detector supply chains against price volatility and qualification delays. Deepen software ecosystem integration with regulatory reporting workflows to differentiate beyond hardware performance as MEMS-based portable units erode benchtop resolution advantages. Raman spectroscopy substitution in aqueous sample analysis threatens mid-IR installed bases, requiring incumbents to anchor customer relationships through chemometric modeling service contracts that address expertise scarcity. For New Entrants and Emerging Players: Cloud-based spectral library subscription models offer the lowest customer acquisition friction for entrants lacking established field service networks. Target Indian generic API producers facing CDSCO quality control modernization mandates, where portable NIR verification systems remain underpenetrated relative to German and North American pharmaceutical clusters. Partner with agricultural commodity inspection agencies in grain-exporting economies to embed handheld units into at-line mycotoxin screening workflows, leveraging food safety field inspection growth to bypass entrenched laboratory relationships. For Investors and Strategic Acquirers: The window for entry favors mid-sized analytical instrumentation specialists with deep software ecosystems rather than diversified conglomerates facing portfolio complexity constraints. Long-term viability hinges on recurring revenue streams from cloud spectral library subscriptions displacing perpetual-license models. Monitor EMA good manufacturing practice standards for spectroscopic method transferability as the inflection indicator; accelerated harmonization across jurisdictions would compress multi-year certification timelines and unlock European pharmaceutical procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Materials | Captive mercury-cadmium-telluride supply insulates margins against specialty chemical producer concentration. |
| Cloud Spectral Library Subscription Launch | Recurring revenue models reduce customer acquisition friction among mid-sized contract research organizations. |
| MEMS-Based Portable FTIR Product Line | Silicon-fabricated electrostatic actuators compress unit costs while maintaining resolution for field deployment. |
| Regulatory Reporting Workflow Integration | Specialized software ecosystems differentiate PerkinElmer's positioning against hardware-centric competitors. |
| Indian Pharmaceutical Cluster Partnership | CDSCO quality control modernization initiatives expand addressable demand for raw material verification systems. |
Research Methodology
Multi-period observation of pharmaceutical batch release protocol changes, EPA method updates, and REACH substance identification threshold adjustments anchored the trend analysis, supplemented by interviews with analytical chemistry procurement managers at German chemical conglomerates, quality control directors at Indian generic API producers, regulatory affairs specialists at FTIR manufacturers, and food safety inspection agency equipment officers. Secondary validation drew from FDA Process Analytical Technology guidance documents, EMA good manufacturing practice standards, CDSCO quality control modernization circulars, customs trade data for optical component imports, and SEC filings of diversified life science conglomerates. Bottom-up triangulation across instrument shipment records and top-down reconciliation against end-user capital expenditure disclosures ensured cross-verification of market sizing.
Input-output matrices mapped detector material supply volumes to finished device production capacity across geographic clusters, with segmentation dimensions spanning product type, end user industry, application workflow, and detection technology architecture. CAGRs were derived from slope analysis of log-linear trend projections across the analysis window, incorporating carbon capture solvent monitoring adoption curves and polymer recycling identification mandate implementation timelines as industry-specific demand drivers.
The model holds under stable regulatory harmonization trajectories; deviation in EMA-FDA pharmacopeial standard convergence timelines or mercury-cadmium-telluride supply disruptions would shift deployment velocity assumptions. Practitioners should monitor CDSCO certification requirement changes and MIIT industrial upgrading program subsidy levels for early signals of geographic demand redistribution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Turbidimeter Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Global Electron Microscopes Market
Analytical Instruments
North America Surface Analysis Market
Analytical Instruments
Spectrometry Market
Analytical Instruments
Middle East and Africa Dissolved Gas Analyzer Market
Analytical Instruments
Global Mass Spectrometry Market
Analytical Instruments
Global Nuclear Magnetic Resonance (NMR) Spectrometer Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Surface and Field Analytics Market
Analytical Instruments
Nanoparticle Size Analysis Instruments Market
Analytical Instruments
Global Atomic Absorption Spectrometer Market
Analytical Instruments
Global Ion Mobility Spectrometry Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Single Cell Analysis System Market