
 Asia-Pacific Dissolved Gas Analyzer Market | 2026-2036
Asia-Pacific Dissolved Gas Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Dissolved Gas Analyzer Market Outlook
Cloud-based predictive maintenance subscriptions is realigning how dissolved gas analyzer vendors monetize hardware deployments. Qualitrol Company LLC leverages its North American service infrastructure to extend remote diagnostics capabilities into Asian utility accounts. Yokogawa Electric Corporation anchors its regional position through deep integration with Japanese transformer OEMs and local calibration networks. Siemens competes on software-defined analytics layers that layer machine learning atop chromatography baselines.
A dissolved gas analyzer detects and quantifies fault gases—hydrogen, methane, ethane, ethylene, acetylene, carbon monoxide, and carbon dioxide—dissolved in transformer insulating oil, typically measuring concentrations in parts per million via gas chromatography or photoacoustic spectroscopy to diagnose thermal and electrical faults before equipment failure. Online analyzers dominate installed base value due to their integration with SCADA systems and 24/7 monitoring protocols, though portable units capture growing share in retrofit markets where capital constraints limit fixed infrastructure investment. Chromatography technology leads precision benchmarks for utility compliance reporting, while optical sensors gain traction in cost-sensitive water treatment and chemical industry deployments where real-time trend detection outweighs laboratory-grade accuracy requirements.
China's MEE enforces emissions-linked equipment reliability standards that indirectly mandate dissolved gas monitoring for grid-scale transformers, while India's CEA stipulates periodic oil testing protocols that utilities increasingly automate through online analyzer networks. Japan's METI coordinates national smart grid roadmaps that embed dissolved gas analytics within digital twin architectures for transmission asset management. Stakeholders must weigh calibration localization requirements against centralized AI platform investments as regulatory fragmentation across Chinese provincial grids, Indian state electricity boards, and Japanese regional utilities complicates standardized service delivery models.
Market Dynamics
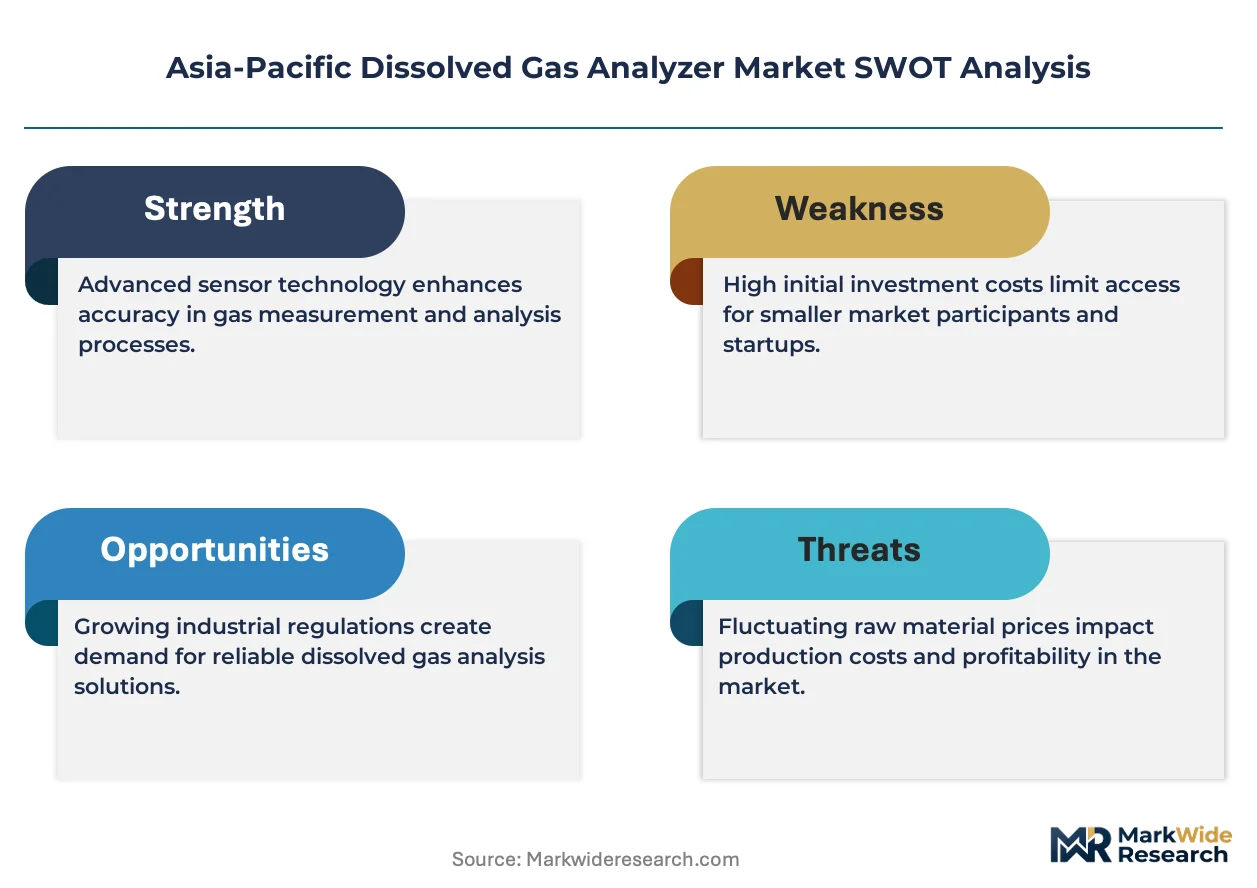
Power grid digitalization across China, India, and Japan is compressing maintenance cycles and forcing utilities to embed continuous dissolved gas monitoring within predictive asset management platforms. This structural shift from periodic manual testing to automated online analysis is redrawing competitive boundaries between chromatography incumbents and optical sensor challengers.
Growth Catalysts
- China's dual carbon goals:National emissions targets mandate ultra-high voltage transmission reliability, accelerating deployment of online dissolved gas analyzers across eastern coastal provinces.
- India's CEA mandates:Central Electricity Authority protocols require automated oil testing, pushing state electricity boards toward analyzer networks that replace laboratory workflows.
- Photoacoustic spectroscopy:This optical detection method cuts calibration frequency and footprint, appealing to chemical plants and water treatment facilities seeking real-time trend data.
Market Restraints
- Helium supply concentration:Gas chromatography systems depend on helium carrier gas, with supply bottlenecks in Qatar and the US creating input cost volatility for precision analyzer manufacturers.
- Calibration infrastructure gaps:Remote Indian states and Chinese western provinces lack certified reference gas facilities, forcing vendors to ship units to coastal calibration hubs.
- Optical accuracy ceilings:Photoacoustic sensors fail to match chromatography precision for sub-ppm acetylene detection, limiting their penetration in utility compliance reporting.
Strategic Opportunities
- Vietnam and Indonesia grid expansion:These underpenetrated markets are building transmission networks without legacy manual testing infrastructure, enabling direct online analyzer adoption.
- Digital twin integration:Japan's METI smart grid roadmaps embed dissolved gas data within asset simulation platforms, creating demand for API-ready analyzer outputs.
- Cloud-based predictive subscriptions:Remote diagnostics platforms let vendors monetize hardware through recurring revenue, reducing upfront capital barriers for capital-constrained utilities.
Industry Challenges
- SCADA integration complexity:Japanese utilities operate fragmented control system architectures, forcing analyzer vendors to maintain multiple protocol stacks.
- Provincial regulatory fragmentation:Chinese state grid subsidiaries enforce differing calibration intervals and data formats, complicating standardized service delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Dissolved Gas Analyzer Market |
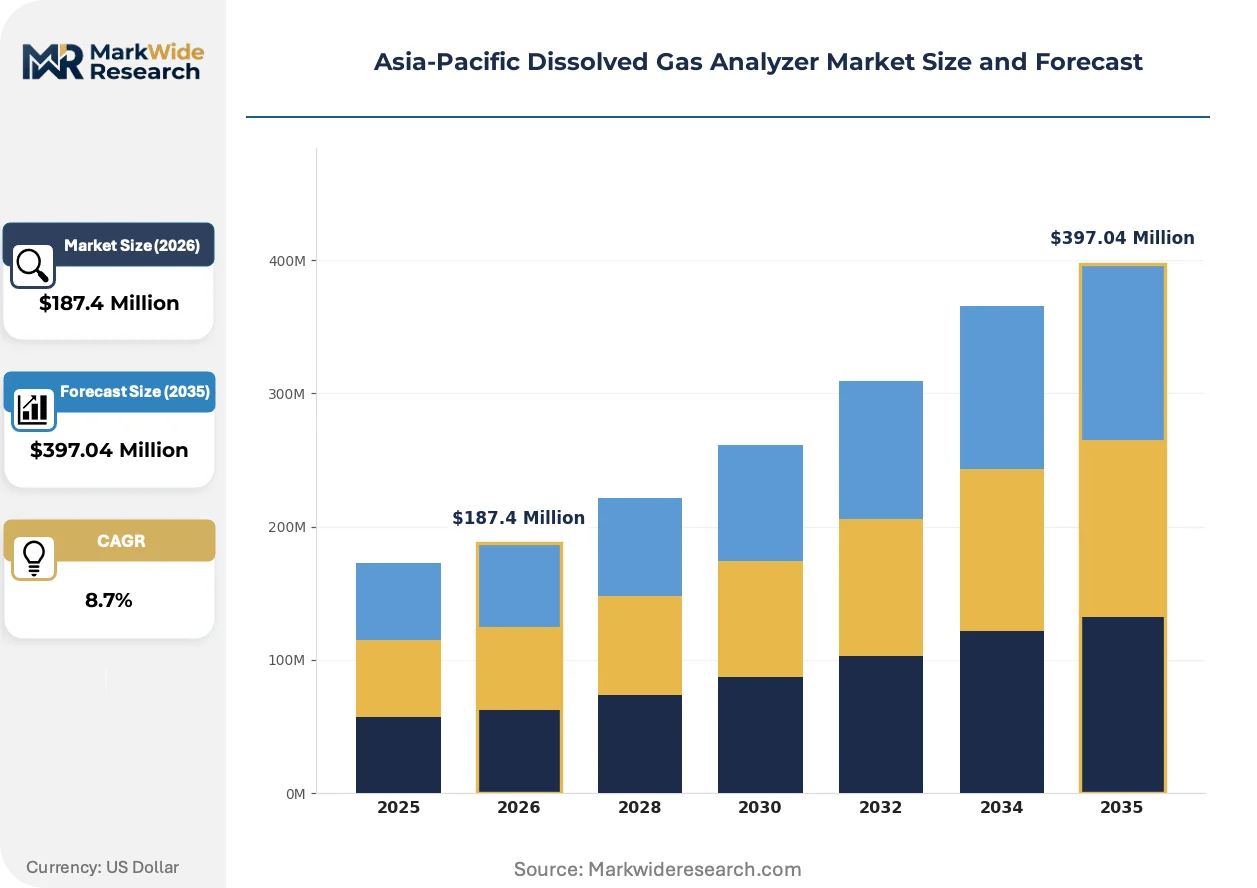
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Online Analyzers, Laboratory Analyzers, Fixed Analyzers End User: Electric Utilities, Oil & Gas, Chemical Industry, Water Treatment Technology: Chromatography, Spectroscopy, Electrochemical, Optical Sensors Application: Leak Detection, Quality Control, Process Monitoring, Environmental Compliance |
| Companies Covered | Qualitrol Company LLC, Vaisala, Doble Engineering Company, Yokogawa Electric Corporation, Hitachi Energy Ltd., General Electric Company, Siemens, Sieyuan Electric Co., Ltd., Advanced Energy Industries, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Dissolved Gas Analyzer Market Strategic Shifts
Machine learning analytics are overlaying chromatography baselines to distinguish incipient transformer faults from benign gas fluctuations. This convergence of hardware precision and software pattern recognition is compressing diagnostic timelines from days to minutes.
Edge computing modules embedded directly in dissolved gas analyzers are rewriting how utilities process transformer health data. Chinese ultra-high voltage operators deploy these units to filter noise and trigger alerts without cloud latency. The shift is compressing response windows and reducing bandwidth costs for remote substations.
India's CEA is tightening oil testing frequency requirements for transformers above 100 MVA, mandating quarterly dissolved gas reports that manual sampling cannot satisfy. State electricity boards in Maharashtra and Gujarat are automating compliance through online analyzer networks. This regulatory pressure is displacing laboratory service contracts with capital equipment procurement.
Asset managers at Japanese regional utilities now specify dissolved gas analyzers with open API architectures, unbundling hardware from proprietary software stacks. Procurement teams evaluate chromatography units on interoperability with existing digital twin platforms. This specification shift favors vendors offering modular analytics over integrated black-box systems.
Asia-Pacific Dissolved Gas Analyzer Market Segmentation
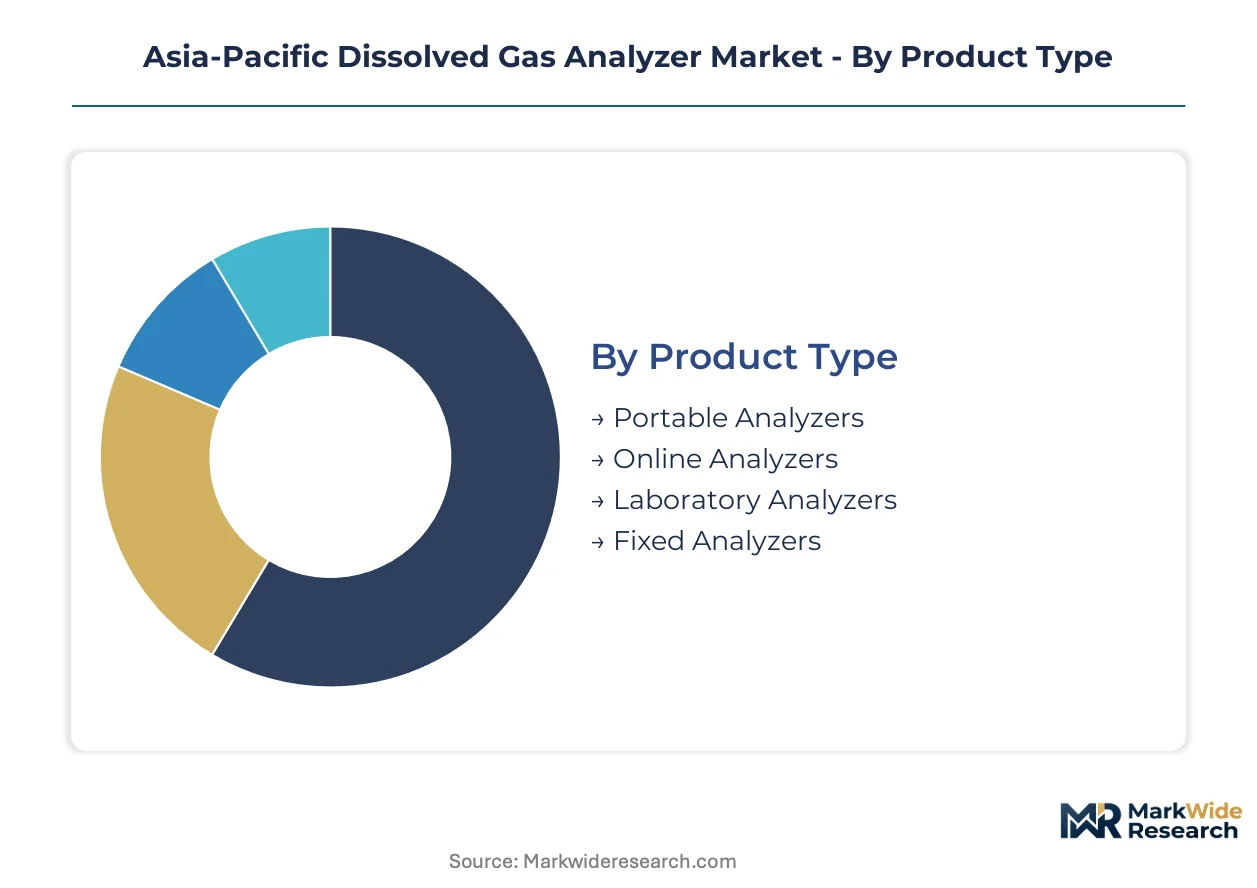
Dissolved gas analyzer procurement patterns diverge sharply across installation permanence, end-use reliability requirements, and detection precision thresholds. Supply concentration in chromatography components versus optical sensor commoditization creates tiered vendor strategies that reshape how segments compete for utility capital budgets.
Product Type:
Supply concentration in gas chromatography subsystems and photoacoustic sensor modules determines which product formats command premium pricing versus volume positioning.
- Online Analyzers:These permanently installed units integrate directly with SCADA architectures for continuous transformer oil monitoring. Chinese ultra-high voltage operators in Jiangsu and Zhejiang provinces deploy these across substation networks to satisfy MEE emissions-linked reliability mandates without manual sampling delays.
- Portable Analyzers:Handheld or cart-mounted units enable spot-checking across dispersed transformer fleets where fixed infrastructure proves uneconomical. Indian state electricity boards in Rajasthan and Madhya Pradesh favor these for aging distribution networks with irregular maintenance cycles and capital constraints.
- Laboratory Analyzers:Benchtop systems deliver reference-grade precision for dispute resolution and regulatory arbitration.
- Fixed Analyzers:Single-point installations serve critical assets without full network integration requirements.
Today's leader: Online Analyzers. Tomorrow's challenger: Portable Analyzers.
End User:
Cost tier differentiation separates mission-critical grid infrastructure from industrial process applications with alternative monitoring options.
- Electric Utilities:Transmission and distribution operators mandate the highest precision standards for dissolved gas detection. Japan's regional utilities under METI coordination specify chromatography-based units with open API architectures for digital twin integration.
- Chemical Industry:Petrochemical and specialty chemical plants prioritize trend detection speed over laboratory-grade accuracy. Photoacoustic spectroscopy units gain traction here due to reduced calibration burdens and smaller physical footprints.
- Oil & Gas:Refinery transformer fleets and pipeline compressor stations require intermittent monitoring with ruggedized field specifications.
- Water Treatment:Municipal and industrial water facilities deploy dissolved gas analysis for aeration system optimization and dissolved oxygen correlation.
Electric Utilities anchor current procurement volumes. Chemical Industry applications are climbing the fastest as optical sensor costs decline.
Technology:
Volume concentration in legacy chromatography installations contrasts with emerging optical alternatives reshaping mid-market competitive dynamics.
- Chromatography:Gas chromatography with flame ionization or thermal conductivity detection remains the precision benchmark for utility compliance reporting. Helium carrier gas dependency creates supply vulnerability given Qatar and US concentration, yet no alternative matches sub-ppm acetylene resolution for incipient fault diagnosis.
- Optical Sensors:Photoacoustic spectroscopy and infrared absorption methods eliminate consumable carrier gases entirely. These systems penetrate cost-sensitive chemical and water treatment markets where real-time trend visibility outweighs absolute accuracy requirements.
- Spectroscopy:Advanced optical methods including cavity ring-down techniques target research and calibration laboratory applications.
- Electrochemical:Solid-state sensors offer compact form factors for portable and disposable monitoring scenarios.
Chromatography holds installed base dominance. Optical Sensors represent the steepest expansion trajectory as calibration localization challenges persist across remote Indian states and Chinese western provinces.
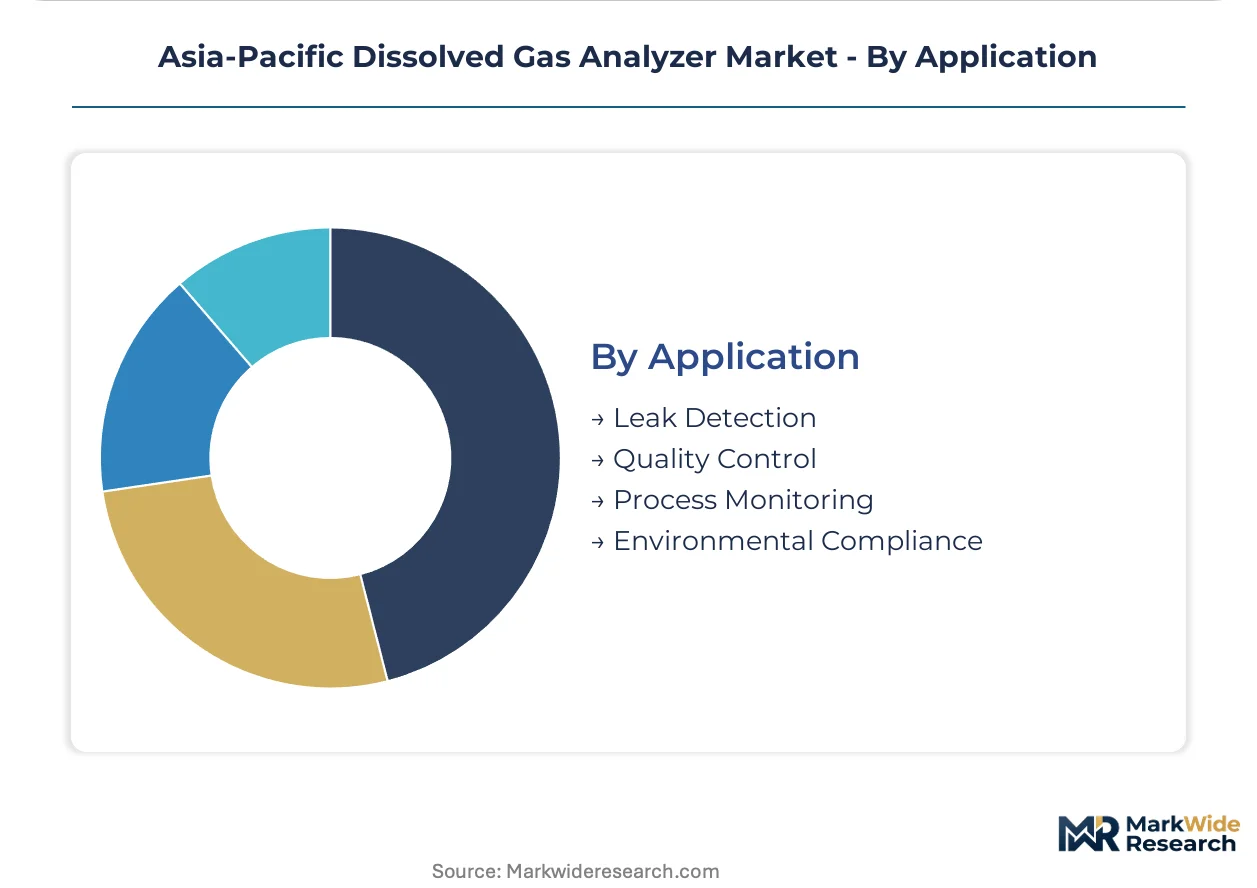
Application:
Customer type segmentation separates predictive maintenance platforms from quality assurance workflows and regulatory documentation requirements.
- Process Monitoring:Continuous dissolved gas tracking enables condition-based maintenance scheduling rather than calendar-driven interventions. Chinese state grid subsidiaries embed these capabilities within smart grid roadmaps for eastern coastal ultra-high voltage corridors.
- Environmental Compliance:Emissions-linked equipment reliability standards from China's MEE and India's CEA indirectly mandate dissolved gas documentation for grid-scale transformers. Automated reporting replaces laboratory service contracts in Maharashtra and Gujarat state electricity boards.
- Leak Detection:Pressure vessel and pipeline integrity applications utilize dissolved gas signatures to identify seal degradation.
- Quality Control:Incoming oil testing and refurbishment verification support transformer manufacturing and repair operations.
Process Monitoring commands current investment priority. Environmental Compliance is gaining share fastest as quarterly testing mandates displace manual sampling workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys dissolved gas analyzers across ultra-high voltage corridors at scale India cannot yet match, though India's CEA mandates are accelerating faster than China's provincial fragmentation allows.
China
Eastern coastal provinces drive dissolved gas analyzer procurement for Jiangsu and Zhejiang ultra-high voltage networks. MEE emissions-linked equipment reliability standards indirectly mandate continuous monitoring for grid-scale transformers above 220 kV. State Grid subsidiaries in Shanghai and Guangdong embed online analyzers within smart substation architectures.
India
State electricity boards in Maharashtra and Gujarat automate quarterly dissolved gas testing through analyzer networks replacing laboratory workflows. CEA protocols for transformers above 100 MVA mandate reporting frequencies manual sampling cannot satisfy. Western and northern states lack certified reference gas facilities, forcing calibration shipments to coastal hubs.
Japan
METI coordinates national smart grid roadmaps embedding dissolved gas analytics within digital twin architectures for transmission asset management. Regional utilities specify open API architectures unbundling hardware from proprietary software stacks. Kansai and Chubu utilities lead procurement for condition-based maintenance platforms.
South Korea
KEPCO's grid modernization programs incorporate dissolved gas monitoring for aging transformer fleets in Seoul Capital Area substations. National renewable energy integration targets demand higher transmission reliability, expanding analyzer deployment beyond legacy thermal plants. Busan-Ulsan industrial corridors adopt portable units for chemical plant transformer fleets.
Vietnam
Grid expansion programs build transmission networks without legacy manual testing infrastructure, enabling direct online analyzer adoption. EVN's northern and southern power projects specify continuous monitoring for new 500 kV substations. Foreign equipment suppliers partner with local integrators for calibration and service localization.
Asia-Pacific Dissolved Gas Analyzer Market Competitive Environment
Top-tier vendors anchor chromatography-based precision systems, while mid-tier challengers compete on optical sensor cost structures and reduced calibration burdens. The vendor base stratifies across three archetypes: integrated industrial conglomerates with software-analytics layers, specialized test equipment manufacturers with deep utility relationships, and emerging optical sensor specialists attacking mid-market chemical applications. Competitive moves concentrate on cloud-based predictive maintenance subscriptions and API-ready platform architectures that unbundle hardware from proprietary software.
Within the integrated conglomerate tier, Siemens and Hitachi Energy Ltd. exemplify vendors layering machine learning analytics atop chromatography baselines. Yokogawa Electric Corporation anchors the specialized equipment archetype through deep Japanese transformer OEM relationships. These three occupy positions where hardware precision converges with software-defined service monetization, representing competitive positioning that smaller optical specialists cannot replicate without calibration infrastructure investments.
| Leading Market Players |
|---|
| Qualitrol Company LLC |
| Vaisala |
| Doble Engineering Company |
| Yokogawa Electric Corporation |
| Hitachi Energy Ltd. |
| General Electric Company |
| Siemens |
| Sieyuan Electric Co., Ltd. |
| Advanced Energy Industries, Inc. |
| Others |
Value Chain & Pricing Dynamics
Helium carrier gas costs cascade through chromatography-based dissolved gas analyzer pricing tiers, with Qatari supply concentration compressing margins for precision-tier manufacturers serving Chinese ultra-high voltage operators while optical sensor vendors in South Korea and Japan capture mid-market chemical plant demand through reduced consumable dependencies.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for photoacoustic spectroscopy modules, forcing chromatography incumbents to unbundle software analytics from hardware premiums. Three-tier pricing structure across precision-calibration, standard-compliance, and economy-trending levels separates electric utility procurement from chemical plant deployments. Cost compression in the economy tier intensifies because Indian state electricity boards negotiate volume bundles for portable analyzer fleets. Chemical industry buyers exhibit highest price sensitivity, while Japanese regional utilities under METI coordination accept premium positioning for open API architectures.
Supply Chain Analysis
Calibration certification gating restricts qualified suppliers to chromatography subsystem manufacturers with IEC 61850 protocol validation and MEE emissions-linked equipment reliability documentation. Component manufacturing concentrates in China, Japan, and Germany, with flame ionization detectors and thermal conductivity sensors drawing from specialized semiconductor foundries. Single-source vulnerability persists for helium carrier gas feedstock from Qatar and US extraction facilities. Distribution runs through transformer OEM channel partnerships and direct utility procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in dissolved gas analyzers rests on software-defined service monetization compressing hardware payback periods, with cloud-based predictive maintenance subscriptions shifting Indian and Vietnamese utilities from capital expenditure to operational expenditure frameworks.
For Market Incumbents: Anticipate photoacoustic spectroscopy challengers eroding mid-market share by embedding edge computing modules that bypass chromatography calibration infrastructure. Defend precision-tier positioning through backward integration into certified reference gas production, eliminating coastal hub dependencies for remote Chinese and Indian deployments. Prioritize API-ready platform architectures that unbundle hardware from proprietary analytics stacks.
For New Entrants and Emerging Players: Begin with Vietnam and Indonesia grid expansion programs building transmission networks without legacy manual testing infrastructure, enabling direct online analyzer adoption without displacement costs. Target chemical plant transformer fleets in Busan-Ulsan and Gujarat industrial corridors where real-time trend detection outweighs laboratory-grade accuracy requirements. Pursue local integrator partnerships for calibration and service localization.
For Investors and Strategic Acquirers: Consolidation pressure builds where calibration infrastructure scarcity meets provincial regulatory fragmentation across Chinese state grid subsidiaries. Long-term viability favors vendors with hybrid chromatography-optical portfolios spanning utility compliance and industrial process monitoring. Acquisition target archetype: optical sensor specialists with edge computing capabilities and existing Japanese transformer OEM relationships. Watch for CEA mandate expansion to transformers below 100 MVA as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Predictive Maintenance Platform | Recurring revenue models reduce upfront capital barriers for Indian state electricity boards. |
| API-Ready Analyzer Architecture | Open interoperability satisfies Japanese METI digital twin integration requirements. |
| Calibration Infrastructure Localization | In-house reference gas production eliminates coastal hub dependencies for remote deployments. |
| Edge Computing Module Integration | On-device processing compresses response windows for Chinese ultra-high voltage operators. |
| Optical Sensor Cost Reduction Program | Photoacoustic spectroscopy penetration accelerates in Vietnam and Indonesia greenfield grids. |
Study Parameters
Multiple input streams — utility asset manager interviews, transformer OEM technical consultations, regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary discussions with maintenance directors at Chinese state grid subsidiaries, calibration service heads at Indian state electricity boards, and procurement leads at Japanese regional utilities informed demand-side assumptions. Secondary validation drew from MEE emissions standards documentation, CEA oil testing protocol amendments, METI smart grid roadmap publications, and customs trade data for chromatography subsystem imports.
Historical deployment trajectories were cross-referenced against expert panel assessments of regulatory enforcement intensity. Segmentation modeling spanned product type permanence, end-user reliability requirements, technology precision thresholds, and application workflow integration across the projection horizon. CAGRs were derived from unit installation forecasts weighted by average selling price evolution in each tier. Industry-specific inputs included helium supply elasticity estimates and provincial smart grid capital allocation patterns.
Several conditions sit outside the modeled scope, including abrupt helium supply disruptions from Qatar geopolitical events and unannounced CEA mandate scope expansions. Forecasts reflect assumptions regarding calibration infrastructure buildout timelines and optical sensor accuracy improvement trajectories. A model refresh is warranted upon material change in MEE emissions-linked enforcement intensity or METI digital twin standardization pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Flashpoint Analyzer Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Flame Ionization Detectors Market
Analytical Instruments
Gas Chromatography Systems Market
Analytical Instruments
Process Analytical Instrumentation Market
Analytical Instruments
Global Electron Microscopes Market
Analytical Instruments
Flame Photometer Market
Analytical Instruments
Seawater Refractometers Market
Analytical Instruments
High-Sensitivity Luminometers Market
Analytical Instruments
Thermogravimetric Analyzer Market
Analytical Instruments
Near Infrared Spectrum Instruments Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Automatic Polarimeter Market
Analytical Instruments
Mass Spectrometer Market
Analytical Instruments
XRF Analyzer Market