
 Asia-Pacific Leisure Boat Marine Coating Market | 2026-2036
Asia-Pacific Leisure Boat Marine Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Leisure Boat Marine Coating Market Analytics
Japanese and South Korean coating formulators is shifting capacity toward low-VOC water-based systems for leisure craft. Chugoku Marine Paints leverages its century-long shipyard relationships to dominate technical service networks across Osaka and Busan. Kansai Paint anchors its position through captive resin production for two-component polyurethane topcoats. Hempel A/S competes by extending its distribution reach into emerging marina developments along Vietnam's central coast.
Asia-Pacific leisure boat marine coatings comprise film-forming protective systems engineered from acrylic, polyurethane, or epoxy chemistries with dry-film thickness specifications typically ranging from 100 to 400 microns, designed to prevent biofouling, osmotic blistering, and UV degradation on fiberglass, wood, or aluminum hulls. Anti-fouling formulations lead volume demand among product types due to mandatory dry-dock intervals in tropical waters, while specialty coatings represent the fastest-expanding margin pool as superyacht owners seek ceramic-enhanced gloss retention. Water-based technology segments are gaining share against solvent-based alternatives as Thailand and Indonesia implement harbor-side VOC restrictions.
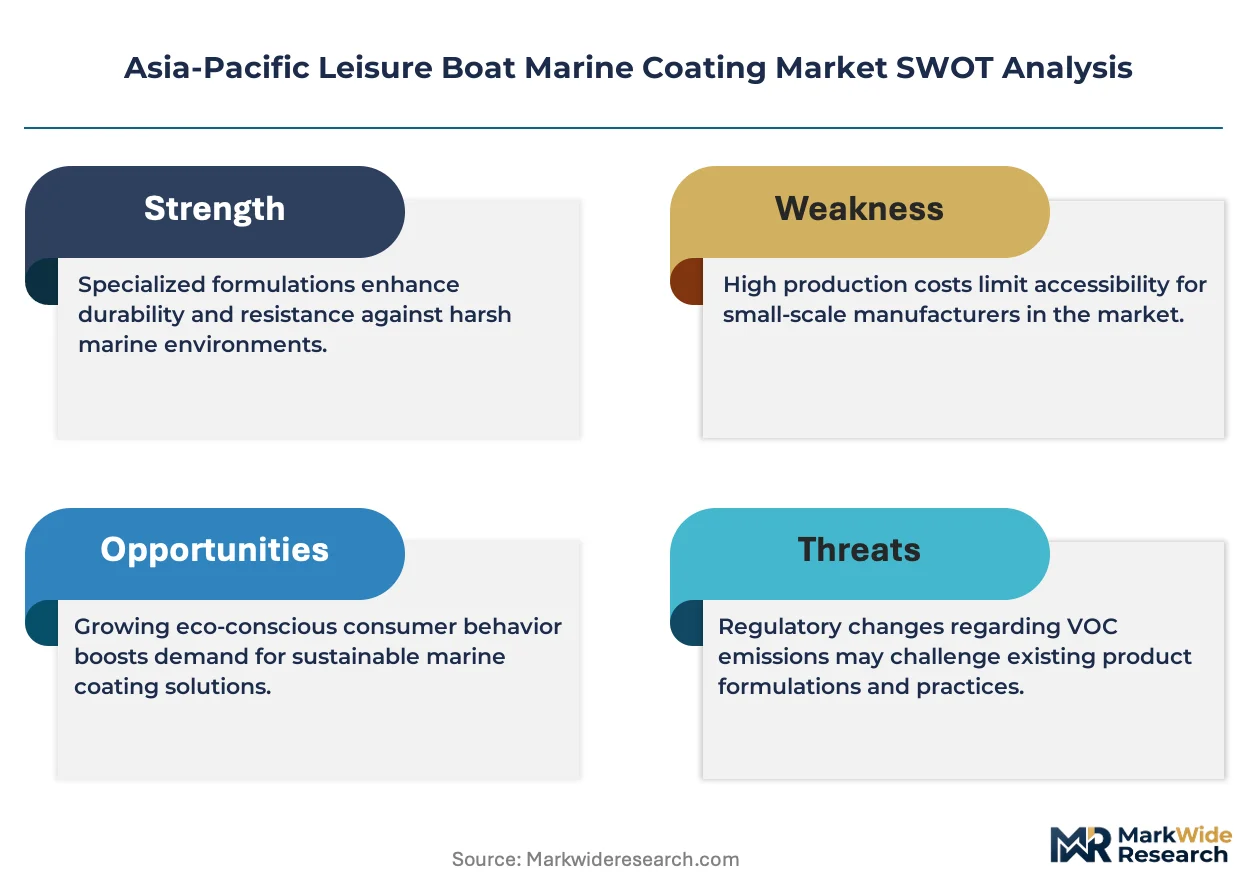
Japan's METI, China's MEE, and Australia's equivalent environmental protection agencies enforce divergent emission standards that fragment product registration requirements across the region. REACH-aligned formulations from European parent companies face additional toxic substance disclosure rules when imported into South Korea and Taiwan. Stakeholders must monitor regulatory harmonization talks between ASEAN maritime authorities and decide whether to maintain country-specific SKUs or pursue unified eco-label certification.
Market Dynamics
Japan's METI VOC limits for marine maintenance yards are compressing formulation timelines and forcing coating suppliers to accelerate water-based system commercialization across Osaka, Yokohama, and Busan production clusters.
Growth Catalysts
- Thailand's harbor-side VOC restrictions:Bangkok's port authority mandates low-emission coatings for dry-dock operations, compelling fleet operators to schedule refurbishment cycles earlier than historical intervals.
- Fiberglass hull production:Coastal Chinese provinces are expanding marina infrastructure that requires anti-fouling protection, concentrating demand in Fujian and Zhejiang manufacturing zones.
- Superyacht ceramic topcoat demand:Owners in Australia's Gold Coast and Phuket marinas specify nano-enhanced gloss retention systems that command premium application service contracts.
Market Restraints
- Epoxy resin supply concentration:Feedstock for two-component polyurethane systems depends on petrochemical complexes in South Korea's Ulsan industrial corridor, exposing formulators to naphtha price volatility.
- REACH-aligned disclosure requirements:European parent companies face additional toxic substance registration rules when importing formulations into Taiwan's Kaohsiung port facilities, extending product approval timelines.
- Silicone foul-release substitution:Biocide-free alternatives threaten conventional copper-based anti-fouling volumes in Singapore's Sentosa Cove and Sydney Harbour superyacht segments.
Strategic Opportunities
- Vietnam's central coast marina developments:Danang and Nha Trang yacht harbors lack established coating service networks, creating first-mover positioning for technical support infrastructure.
- Water-based polyurethane convergence:Hybrid acrylic-urethane chemistries combine spray-application convenience with compliance flexibility for Indonesia's emerging harbor regulations.
- ASEAN maritime authority harmonization talks:Unified eco-label certification frameworks would reduce country-specific SKU proliferation across Philippines, Malaysia, and Thai markets.
Industry Challenges
- Certified applicator scarcity:Two-component polyurethane topcoat specifications require skilled technicians trained in humidity-controlled spray environments, creating bottlenecks during peak dry-dock seasons in tropical ports.
- Legacy solvent-based inventory:Distributors in Jakarta and Manila hold obsolete stock that cannot satisfy tightened VOC thresholds, forcing write-downs and working capital strain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Leisure Boat Marine Coating Market |
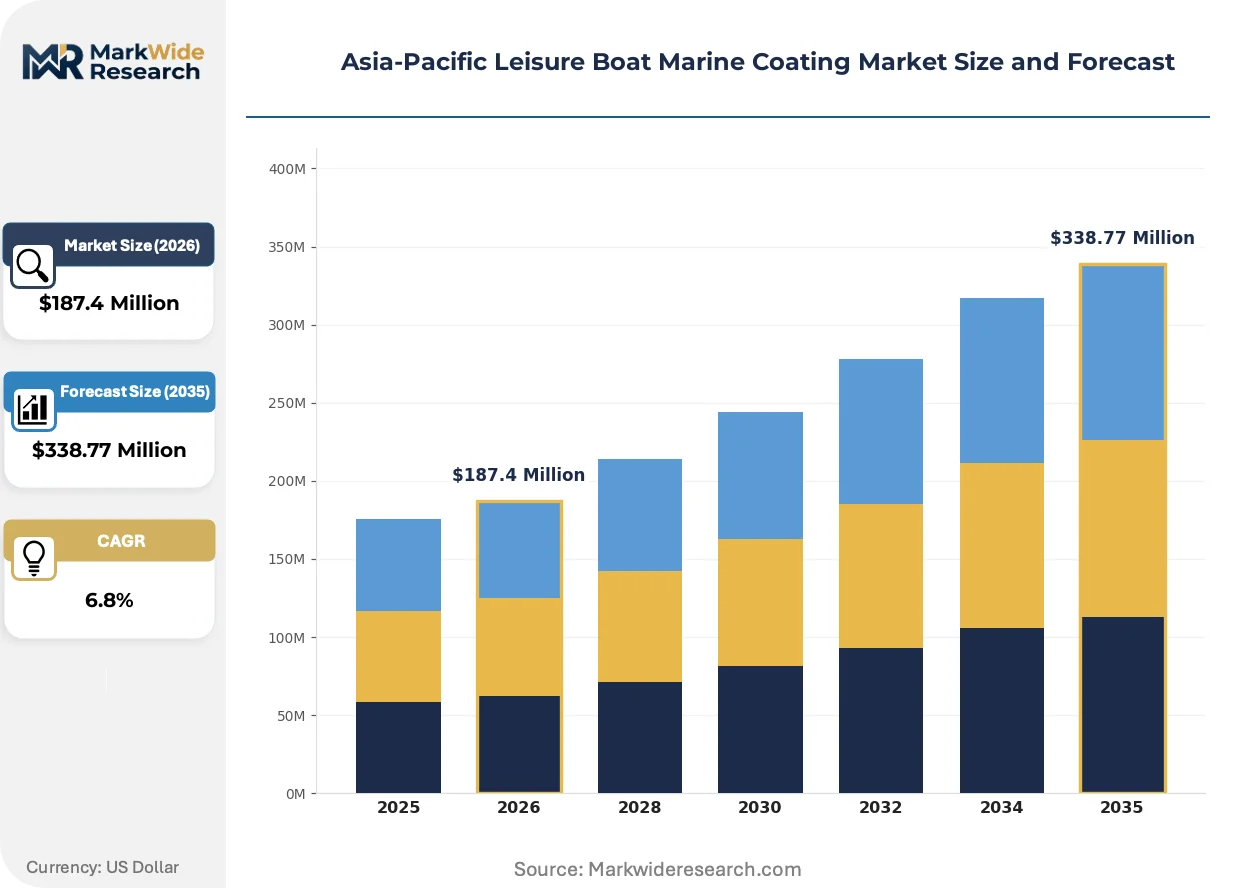
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-fouling, Primer, Topcoat, Specialty Coating Application: Yachts, Sailboats, Motorboats, Jet Skis End User: OEMs, Repair Shops, Boat Dealers, DIY Enthusiasts Technology: Water-based, Solvent-based, Eco-friendly, Two-component |
| Companies Covered | Chugoku Marine Paints, Ltd., Kansai Paint Co. Ltd., Nippon Paint Marine Coatings Co. Ltd., Hempel A/S, Jotun, PPG Industries, AkzoNobel N.V., The Sherwin-Williams Company, NIPSEA GROUP, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Leisure Boat Marine Coating Market Evolving Landscape
Formulation automation and regulatory data integration are compressing product development cycles while reshaping how coating suppliers engage fleet maintenance contractors across Asia-Pacific marina networks.
Robotic spray application systems for two-component polyurethane topcoats are automating hull coating processes in high-volume shipyards. Australian and Thai fleet operators are adopting these platforms to reduce labor dependency during peak refurbishment seasons. The technology is automating thickness uniformity control that previously required manual technician oversight, compressing dry-dock intervals by standardizing 150-400 micron dry-film specifications.
China's MEE is tightening volatile organic compound disclosure requirements for imported marine coatings entering Shanghai and Shenzhen port facilities. The regulation forces European and Japanese parent companies to submit expanded toxic substance documentation before product registration approval. Anti-fouling formulations containing copper oxide biocides face the most intensive scrutiny, compelling suppliers to accelerate silicone foul-release alternatives for Yangtze River delta yacht clubs.
Superyacht owners in Australia's Gold Coast and Phuket marinas are unbundling coating application from yard maintenance contracts, selecting independent certified applicators through direct procurement platforms. This disintermediation pressures traditional shipyard revenue models that previously captured margin on subcontracted coating services. The pattern is most visible among 30-50 meter fiberglass hull segments where owners prioritize ceramic-enhanced gloss retention specifications over bundled yard packages.
Asia-Pacific Leisure Boat Marine Coating Market Segmentation
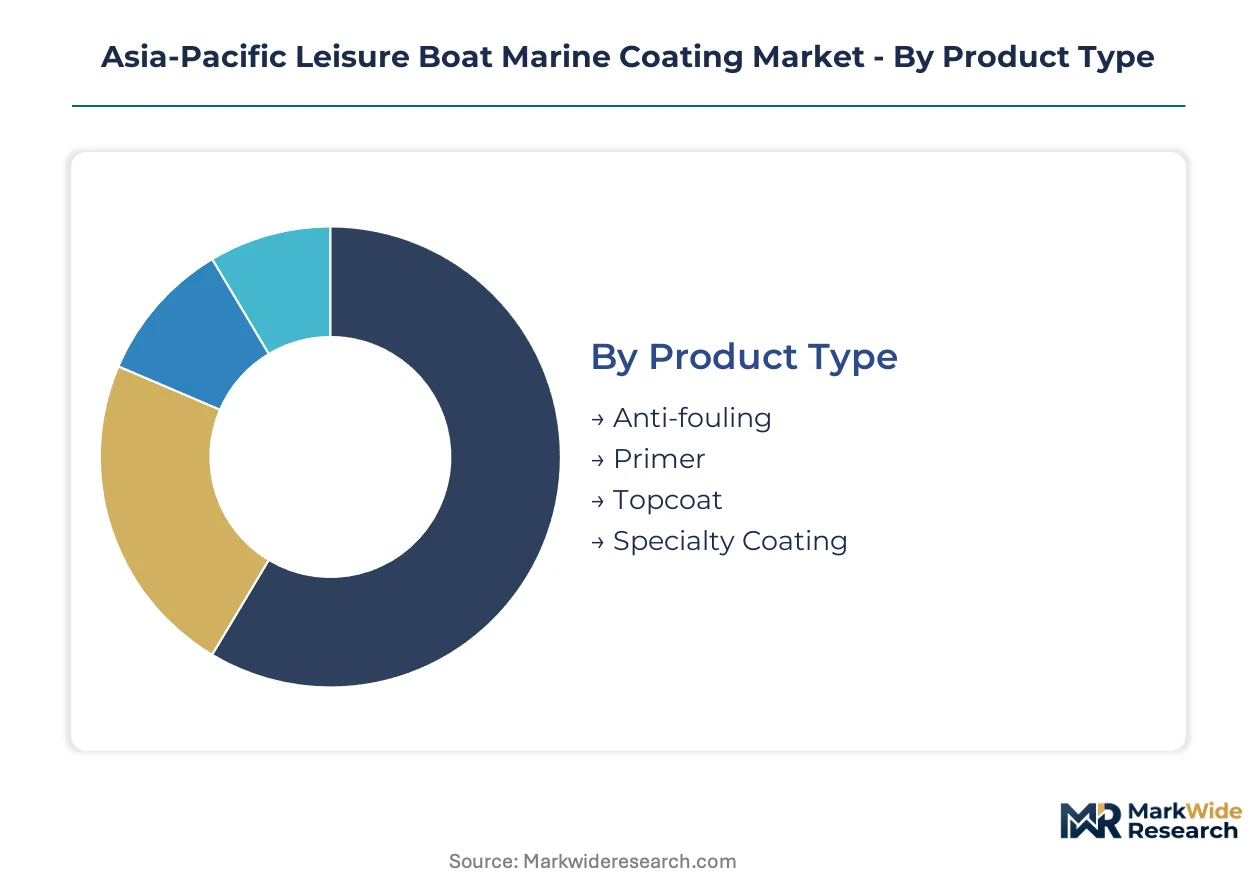
Segmentation in marine coatings determines specification requirements across hull geometries, operational environments, and regulatory jurisdictions. Product chemistry, application method, and end-user technical capability create distinct margin profiles that suppliers must navigate across Asia-Pacific marina networks.
Product Type:
Volume concentrates in anti-fouling systems driven by mandatory dry-dock intervals, while premium margins accumulate in specialty formulations for superyacht gloss retention.
- Anti-fouling:Copper oxide and silicone foul-release chemistries prevent biofouling accumulation on fiberglass hulls operating in tropical waters. Demand clusters in Thailand's Phuket marinas and Australia's Gold Coast where warm-water organisms accelerate hull degradation.
- Specialty Coating:Nano-ceramic enhanced systems deliver 400+ micron dry-film specifications for UV degradation resistance and gloss retention. Superyacht owners in Sydney Harbour and Singapore's Sentosa Cove specify these for premium appearance maintenance between dry-dock cycles.
- Primer:Epoxy-based barrier coats prevent osmotic blistering on fiberglass substrates.
- Topcoat:Polyurethane systems provide color stability and weathering resistance for above-waterline applications.
Today's leader: Anti-fouling. Tomorrow's challenger: Specialty Coating.
Application:
Hull geometry and operational intensity create divergent coating performance requirements across vessel categories.
- Yachts:Fiberglass and aluminum superstructures require multi-layer systems with 150-400 micron cumulative specifications. Fleet operators in Japan's Osaka Bay and South Korea's Busan harbor schedule refurbishment cycles around METI VOC compliance deadlines.
- Motorboats:High-speed planing hulls experience abrasive wear patterns that accelerate coating degradation. Coastal Chinese provinces concentrate manufacturing of these vessels, concentrating primer and topcoat demand in Fujian and Zhejiang industrial zones.
- Sailboats:Displacement hulls with long waterlines prioritize anti-fouling performance over speed-dependent formulations.
- Jet Skis:Small-craft polyethylene hulls require flexible coating systems resistant to impact damage.
Volume gravitates toward Motorboats. Margin concentrates in Yachts.
End User:
Technical capability and procurement scale separate specification authority across the value chain.
- OEMs:Original equipment manufacturers in China's coastal provinces specify coating systems during hull lamination, locking in multi-year supply agreements. These buyers demand batch consistency and technical service support for production line integration.
- Repair Shops:Certified applicators in Vietnam's emerging Danang and Nha Trang marinas control refurbishment quality for imported European hulls. VOC restrictions in Bangkok's port authority are compressing their solvent-based inventory turnover.
- Boat Dealers:Distribution intermediaries stock fast-moving primer and topcoat SKUs for warranty repair work.
- DIY Enthusiasts:Retail consumers purchase single-component water-based systems for minor touch-up applications.
Procurement power clusters with OEMs. Service differentiation belongs to Repair Shops.
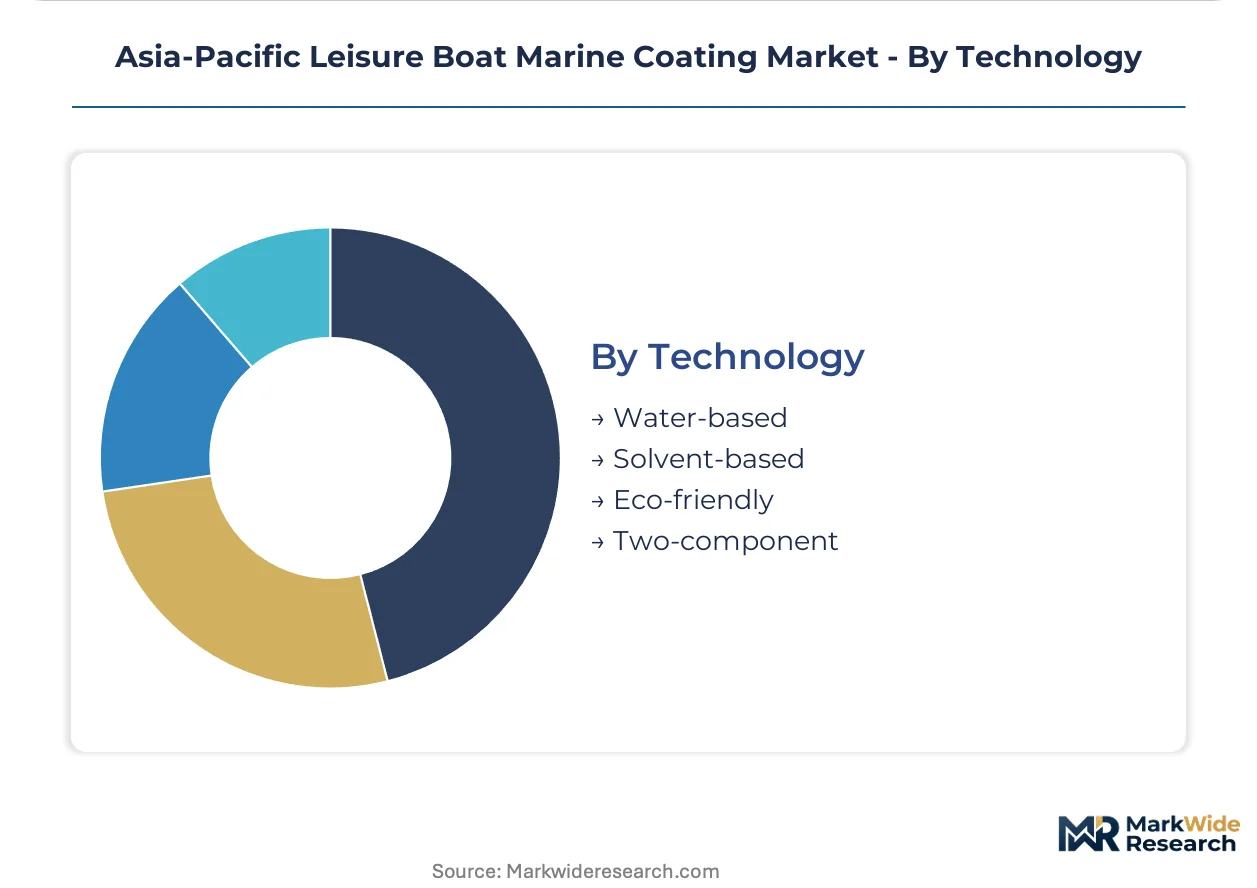
Technology:
Regulatory pressure is accelerating formulation transitions across Asia-Pacific harbor jurisdictions.
- Water-based:Low-VOC acrylic-urethane hybrids enable spray application in humidity-controlled environments. Japan's METI limits and Thailand's harbor-side restrictions are expanding addressable market for these systems across Osaka, Yokohama, and Bangkok maintenance yards.
- Two-component:Polyurethane topcoats deliver maximum gloss retention and chemical resistance for premium yacht segments. Application requires certified technician training and controlled spray booth conditions, creating capability bottlenecks during peak dry-dock seasons.
- Solvent-based:Legacy formulations face phased elimination under tightening environmental standards.
- Eco-friendly:Biocide-free silicone foul-release alternatives are gaining regulatory preference in sensitive marine ecosystems.
Compliance momentum favors Water-based. Performance ceiling belongs to Two-component.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as coating formulators migrate capacity toward jurisdictions with phased VOC implementation timelines. Cost-of-compliance gaps between early-adopter and lagging-enforcement markets are concentrating investment in South Korea and Vietnam while compressing margins in Japan's mature regulatory environment.
Japan
Yacht refurbishment demand concentrates in Osaka Bay and Yokohama harbor clusters where fleet operators schedule dry-dock cycles around METI VOC compliance deadlines. METI's tightened emission limits for marine maintenance yards are forcing accelerated water-based system commercialization across production facilities. Kansai-based formulators leverage century-long shipyard relationships to dominate technical service networks.
China
Marina infrastructure multiplication in Fujian and Zhejiang coastal provinces is concentrating anti-fouling demand among fiberglass hull manufacturers. MEE disclosure requirements for imported coatings entering Shanghai and Shenzhen ports are extending product registration timelines for European parent companies. Yangtze River delta yacht clubs are driving scrutiny of copper oxide biocide formulations.
Australia
Superyacht owners in Gold Coast marinas specify ceramic-enhanced gloss retention systems that command premium application service contracts. The country's environmental protection agencies enforce harbor-side standards that align with tightening ASEAN norms. Sydney Harbour's superyacht segments are testing biocide-free silicone foul-release alternatives.
South Korea
Busan harbor production clusters anchor two-component polyurethane supply for premium yacht segments. Formulators face naphtha price volatility from Ulsan industrial corridor petrochemical complexes that feed epoxy resin production. Kansai Paint anchors regional position through captive resin production for topcoat systems.
Vietnam
Danang and Nha Trang yacht harbor developments lack established coating service networks, creating first-mover positioning for technical support infrastructure. Emerging harbor regulations are compressing formulation timelines for water-based polyurethane convergence. Hempel A/S competes by extending distribution reach into these central coast developments.
Asia-Pacific Leisure Boat Marine Coating Market Competitive Landscape
Japanese and South Korean producers anchor the premium formulation tier; European specialists hold REACH-aligned import positions across ASEAN markets. The vendor base clusters around three strategic archetypes: integrated petrochemical-coating conglomerates with captive resin production, marine-focused specialists leveraging shipyard technical relationships, and diversified industrial coating players extending leisure craft portfolios. Competitive moves concentrate on water-based capacity expansion and harbor-side service network densification in emerging marina developments.
Within the integrated conglomerate tier, Chugoku Marine Paints and Kansai Paint exemplify producers combining century-long shipyard relationships with captive raw material production. Kansai Paint's position sits within the two-component polyurethane segment where in-house resin manufacturing creates supply security. Hempel A/S occupies a distribution-focused archetype, extending technical service infrastructure into Vietnam's central coast developments where established networks remain thin. These three anchors represent divergent strategic postures: backward-integrated manufacturing, formulation specialization, and geographic expansion through service density.
| Leading Market Players |
|---|
| Chugoku Marine Paints, Ltd. |
| Kansai Paint Co. Ltd. |
| Nippon Paint Marine Coatings Co. Ltd. |
| Hempel A/S |
| Jotun |
| PPG Industries |
| AkzoNobel N.V. |
| The Sherwin-Williams Company |
| NIPSEA GROUP |
| Others |
Value Network & Pricing Analysis
Captive resin production at Kansai Paint and Chugoku Marine Paints anchors both supply security and premium pricing power across Osaka and Busan manufacturing clusters. This backward integration insulates formulators from naphtha volatility in South Korea's Ulsan corridor while enabling margin capture on two-component polyurethane topcoats specified by superyacht owners.
Pricing Analysis
Distributor margin compression in Jakarta and Manila is forcing pricing stratification across premium, standard, and economy tiers. OEMs in Fujian and Zhejiang provinces negotiate volume-based direct procurement that bypasses traditional markup layers, while independent certified applicators in Thailand's Phuket marinas command premium service fees for ceramic-enhanced gloss retention specifications. Price erosion runs through solvent-based inventory held by legacy distributors unable to meet Bangkok's harbor-side VOC thresholds.
Supply Chain Analysis
Certified applicator scarcity in Vietnam's Danang and Nha Trang yacht harbors is constraining coating service network expansion. Epoxy resin feedstock draws from South Korea's Ulsan petrochemical complexes, while acrylic-urethane hybrid precursors source from Japan's Kansai industrial belt. Single-source vulnerability in biocide supply chains exposes anti-fouling formulators to regulatory restriction cascades. Distribution runs through shipyard-anchored technical service networks rather than open merchant channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on water-based formulation cost-down curves and superyacht owners' willingness to pay premium application fees for ceramic-enhanced specifications.
For Market Incumbents: Hedge against silicone foul-release substitution by accelerating biocide-free alternative R&D while locking in multi-year resin supply agreements with Ulsan petrochemical complexes. Defensive consolidation of certified applicator training programs in Vietnam's emerging marinas protects service revenue from direct-procurement disintermediation. For New Entrants and Emerging Players: Direct-to-owner procurement platforms offer the lowest channel friction for penetrating Australia's Gold Coast superyacht segments where owners already unbundle coating from yard contracts. White-space exists in Indonesia's harbor-side VOC compliance advisory services, where fleet operators lack technical guidance on hybrid acrylic-urethane system selection. For Investors and Strategic Acquirers: Consolidation pressure builds where distributors hold obsolete solvent-based inventory that cannot satisfy tightening ASEAN emission standards. Long-term viability favors targets with captive water-based capacity and established METI registration pathways. Watch for harmonization talks between ASEAN maritime authorities as inflection signal for unified eco-label certification plays.| Strategic Initiative | Industry Significance |
|---|---|
| Water-based Capacity Expansion | Osaka and Yokohama production clusters gain compliance flexibility under METI's tightened VOC limits. |
| Technical Service Network Densification | Danang and Nha Trang marina developments lack established coating applicator infrastructure. |
| Captive Resin Production Investment | In-house epoxy and polyurethane precursor manufacturing insulates against Ulsan naphtha volatility. |
| Ceramic-enhanced Formulation Launch | Superyacht owners in Sydney Harbour and Sentosa Cove specify nano-ceramic gloss retention systems. |
| ASEAN Eco-label Certification Program | Unified frameworks would reduce country-specific SKU proliferation across Philippines and Thai markets. |
Research Methodology
Coverage spans Japan, China, Australia, South Korea, and Vietnam, with primary inputs from each market's coating formulators, marina operators, and fleet maintenance contractors. Interviews with shipyard technical directors, certified applicators, and OEM procurement managers combined with secondary validation from customs trade data, MEE disclosure filings, and METI regulatory registers. Bottom-up hull refurbishment cycle analysis triangulated against top-down marina infrastructure investment tracking.
Rate-of-change decomposition separated volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product chemistry tier, application method complexity, end-user procurement scale, and harbor jurisdiction regulatory cluster. CAGRs derived from hull-in-service fleet growth, dry-dock interval compression, and technology substitution curves for water-based versus solvent-based systems.
The model assumes a particular technology adoption path; alternative pathways for silicone foul-release biocide alternatives would alter the outlook. Forecasts reflect assumptions about ASEAN regulatory harmonization progress and naphtha feedstock cost trajectories. Material deviation in METI enforcement intensity or MEE disclosure timeline expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Beacon Market
Marine
Deep-V Boat Market
Marine
Marine Engine Cooling Systems Market
Marine
Marine AIS Monitoring System Market
Marine
Marine Trenchers Market
Marine
Marine Airbags Market
Marine
Hydraulic Marine Cranes Market
Marine
Marine Turbocharger Market
Marine
Boat Control Lever Market
Marine
Marine LED Lights Market
Marine
US Fish Finders Market
Marine
Furnace Boats Market
Marine
GCC ROV Market
Marine
Marine Growth Removal Tool Market
Marine
Ship Heat Exchanger Market
Marine
Marine Suspension Seat Bases Market