
 Asia Pacific Nutraceuticals Market | 2026-2036
Asia Pacific Nutraceuticals Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Nutraceuticals Market Outlook
Sports nutrition among amateur athletes is expanding faster than traditional geriatric segments across Southeast Asia. Nestlé SA leverages its dairy-protein infrastructure to dominate ready-to-drink recovery formats. Herbalife International of America Inc. sustains a direct-sales network that controls access in Indonesia and Vietnam. Abbott Laboratories anchors hospital discharge protocols with clinical nutrition lines across India and the Philippines.
Asia Pacific nutraceuticals encompass bioactive compounds, concentrated nutrient extracts, and functional food ingredients formulated to deliver physiological benefits beyond basic nutrition. Manufacturers employ microencapsulation, spray-drying, and fermentation processes to stabilize probiotics, omega fatty acids, and plant sterols for shelf-stable delivery in pills, powders, and gummies. Vitamins and herbal supplements together capture the deepest margin pools, with gummy formats commanding price premiums over standard tablets in pediatric and elderly applications. Online retail channels are displacing pharmacy dominance in South Korea and Australia, while supermarket private-label lines erode branded shelf space in Japan.
Japan's Ministry of Health, Labour and Welfare maintains the Foods with Function Claims system, which demands clinical evidence dossiers that filter out unsubstantiated entrants. China's SAMR enforces GB standards for nutrient content and label accuracy, creating compliance costs that favor scaled producers over regional formulators. India's FSSAI notification requirements for novel ingredients slow product registration timelines. Stakeholders must monitor how Australia's TGA rescheduling of certain botanical extracts reshapes import eligibility across ASEAN mutual-recognition frameworks.
Market Dynamics
Pharmacy chains in China's tier-one cities now stock premium herbal supplements as primary distribution nodes, while India's FSSAI label-claim verification rules force reformulation cycles that compress product development timelines.
Growth Catalysts
- Sports nutrition demand:Amateur athletes across Southeast Asia drive ready-to-drink protein format adoption. Nestlé SA leverages existing dairy-protein infrastructure to capture this segment.
- GB standards enforcement:China's SAMR nutrient content and label accuracy requirements favor scaled producers with compliance capacity over regional formulators.
- Microencapsulation advances:Spray-drying and fermentation processes now stabilize probiotics and omega fatty acids for shelf-stable gummy delivery in pediatric applications.
Market Restraints
- Input cost volatility:Fish oil and plant sterol feedstock prices fluctuate with marine harvest cycles and agricultural commodity markets.
- Regulatory friction:India's FSSAI notification requirements for novel ingredients extend product registration timelines by 12-18 months.
- Supply concentration:Probiotic strain production clusters in South Korea and Japan, creating import dependency for ASEAN formulators.
Strategic Opportunities
- Online channel expansion:E-commerce platforms in South Korea and Australia displace pharmacy dominance for vitamin and supplement sales.
- Foods with Function Claims:Japan's MHLW system rewards clinical evidence investment with premium positioning and pharmacy shelf access.
- Supermarket private-label:Japanese retailers erode branded shelf space with house-brand functional food lines targeting cost-conscious elderly consumers.
Industry Challenges
- Clinical evidence generation:Japan's FFC dossier requirements demand trial investments that mid-tier formulators struggle to fund.
- Cross-border compliance:Australia's TGA rescheduling of botanical extracts creates import eligibility uncertainty across ASEAN mutual-recognition frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Nutraceuticals Market |
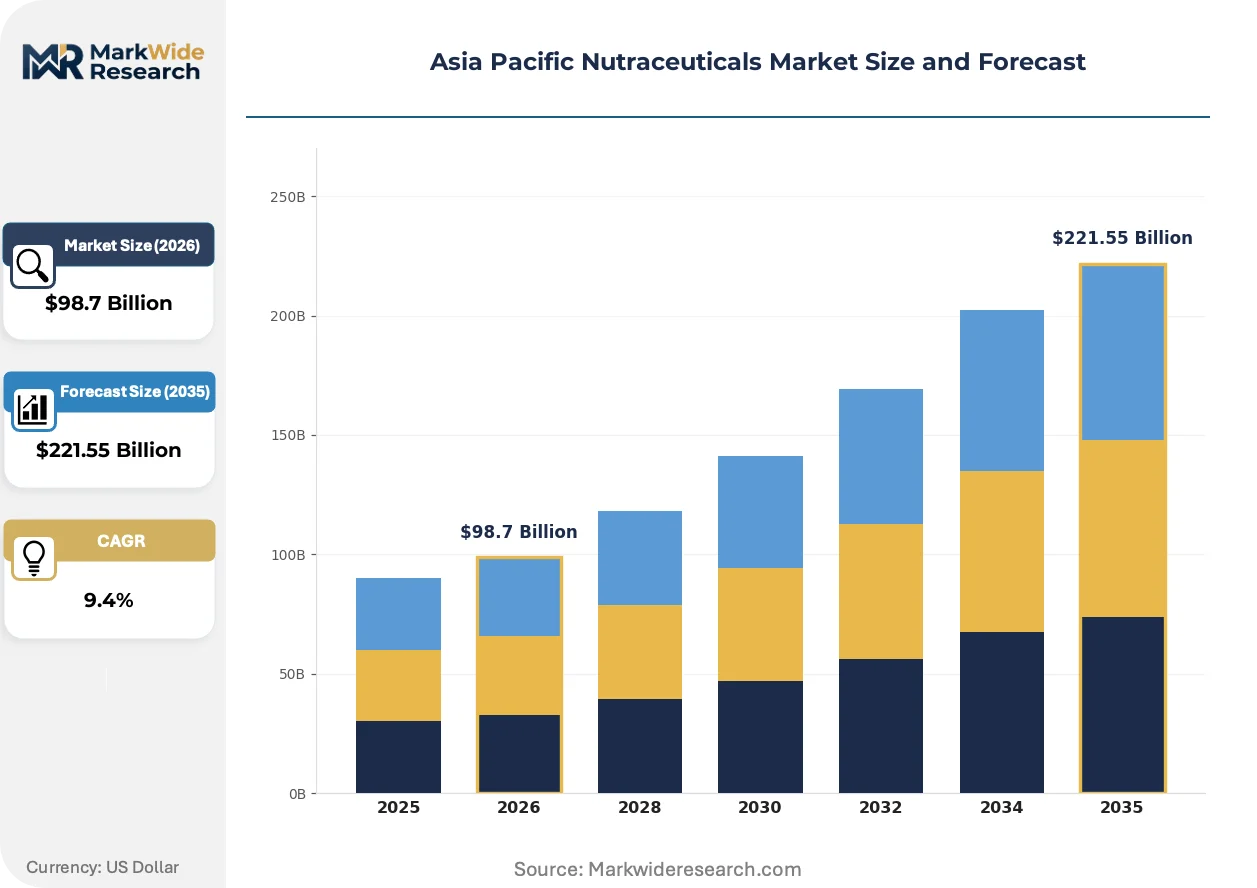
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $221.55 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Supplements, Amino Acids Form: Pills, Powders, Liquids, Gummies End User: Adults, Elderly, Athletes, Children Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Nestlé SA, PepsiCo Inc., Herbalife International of America Inc., Bayer AG, Abbott Laboratories, Amway Corp, ADM Company, Cargill Inc., Aland (Jiangsu) Nutraceutical Co., Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Nutraceuticals Market Strategic Shifts
Delivery format innovation and regulatory evidence frameworks are compressing competitive moats while channel fragmentation opens new customer access points across the Asia Pacific nutraceuticals landscape.
Microencapsulation technology is automating the stabilization of heat-sensitive bioactives for ambient-temperature distribution. Functional food manufacturers in Thailand and Malaysia adopt these systems to expand probiotic inclusion into bakery and beverage applications. The technology is automating quality consistency previously achievable only through refrigerated supply chains.
Japan's Foods with Function Claims system demands clinical evidence dossiers that filter unsubstantiated market entrants. The framework creates a two-tier market split between evidence-backed premium positioning and commodity supplement status. Chinese and Korean exporters targeting Japanese pharmacy chains must now commission domestic trial data to qualify for FFC registration.
Direct-to-consumer subscription models now capture recurring revenue from urban professional segments in Singapore and Hong Kong. Traditional multi-level marketing networks face displacement from app-based personalized nutrition platforms offering AI-formulated regimens. This behavioral shift concentrates highest lifetime-value customers in data-rich digital environments away from relationship-dependent sales channels.
Asia Pacific Nutraceuticals Market Segmentation
Segmentation in Asia Pacific nutraceuticals reveals how regulatory frameworks, delivery technology, and channel access fragment commercial opportunity. Each dimension carries distinct compliance burdens and margin profiles that shape manufacturer prioritization.
Product Type:
Vitamins and herbal supplements face divergent approval pathways across the region, with Japan's FFC system demanding clinical dossiers for functional claims while vitamins navigate simpler nutrient-content verification.
- Vitamins:Water-soluble and fat-soluble compounds formulated for deficiency correction and metabolic support. Demand concentrates in China's tier-one cities where pharmacy chains stock premium multivitamin lines for urban professionals facing dietary gaps. SAMR's GB standards for label accuracy create compliance costs that favor scaled producers with in-house testing laboratories.
- Herbal Supplements:Concentrated botanical extracts and traditional medicine formulations standardized for bioactive content. India's FSSAI tightened label-claim verification rules for functional foods, forcing reformulation cycles that compress development timelines for Ayurvedic and TCM-derived products. Leading the category by volume: Vitamins. Growing fastest: Herbal Supplements.
- Minerals:Chelated and inorganic salt forms targeting calcium, iron, and zinc supplementation.
- Amino Acids:Branched-chain and essential amino acid isolates for sports nutrition and clinical nutrition applications.
Leading the category by volume: Vitamins. Growing fastest: Herbal Supplements.
Form:
Delivery format selection determines supply chain requirements, with gummy formats demanding humidity-controlled packaging and powder formats enabling bulk ingredient sourcing economies.
- Gummies:Gelatin and pectin-based matrices incorporating microencapsulated bioactives for pediatric and elderly palatability. Demand concentrates in South Korea and Australia where online retail channels displace pharmacy dominance for vitamin sales. Microencapsulation advances now stabilize heat-sensitive compounds for ambient distribution.
- Pills:Compressed tablets and two-piece capsules offering dose precision and shelf stability. India's FSSAI notification requirements for novel ingredients extend registration timelines for innovative tablet coatings. Leading the category by volume: Pills. Expanding most quickly: Gummies.
- Powders:Bulk and single-serve sachet formats for protein and amino acid delivery.
- Liquids:Ready-to-drink and concentrated dropper formulations for rapid absorption.
Pills dominate manufacturing scale. Gummies command price premiums in pediatric applications.
End User:
User segmentation maps to distinct purchasing behaviors, with athletes driving subscription model adoption and elderly consumers remaining anchored to pharmacy relationships.
- Athletes:Amateur and semi-professional competitors across Southeast Asia driving ready-to-drink protein format adoption. Nestlé SA leverages dairy-protein infrastructure to capture this segment. Sports nutrition demand expands faster than traditional geriatric segments.
- Elderly:Age-related supplementation for bone density, cognitive function, and cardiovascular support. Japanese supermarket private-label lines erode branded shelf space targeting cost-conscious elderly consumers. Leading the category by volume: Adults. Gaining share fastest: Athletes.
- Adults:Working-age consumers pursuing general wellness and preventive health.
- Children:Pediatric formulations with palatability and safety as primary design constraints.
Adults represent the deepest volume pool. Athletes show steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture and customer data access, with e-commerce platforms offering direct relationships that pharmacy intermediaries fragment.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capturing recurring revenue through subscription models. Singapore and Hong Kong urban professionals concentrate in data-rich digital environments. Traditional multi-level marketing networks face displacement from app-based personalized nutrition platforms.
- Pharmacies:Chain and independent drugstores providing clinical credibility and pharmacist consultation. China's tier-one city pharmacy chains stock premium herbal supplements as primary distribution nodes. Leading the category by volume: Pharmacies. Climbing the fastest: Online Retail.
- Supermarkets:Mass-market retail with private-label penetration highest in Japan.
- Health Stores:Specialty retailers emphasizing organic and premium-positioned lines.
Pharmacies retain volume leadership. Online Retail shows strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port tax incentives for health product manufacturing are accelerating nutraceutical production concentration across the Asia Pacific region. These zones attract multinationals seeking tariff advantages for cross-border distribution into ASEAN markets.
China
Pharmacy chains in Shanghai and Beijing stock premium herbal supplements as primary distribution nodes for urban professionals. SAMR enforces GB standards for nutrient content and label accuracy, creating compliance costs that favor scaled producers over regional formulators. The Yangtze River Delta hosts concentrated softgel and tablet manufacturing facilities serving domestic and export demand.
Japan
Aging demographics drive sustained demand for functional foods targeting cognitive and cardiovascular support. METI and MHLW administer the Foods with Function Claims system demanding clinical evidence dossiers that filter out unsubstantiated entrants. The Kanto region around Tokyo anchors premium supplement R&D and pharmacy chain headquarters controlling shelf access.
India
Ayurvedic and traditional medicine formulations attract both domestic consumers and export markets seeking standardized botanical extracts. FSSAI tightened label-claim verification rules for functional foods, forcing reformulation cycles that compress product development timelines. Maharashtra and Gujarat host concentrated manufacturing clusters for herbal extract processing and formulation.
South Korea
Online retail channels displace pharmacy dominance for vitamin and supplement sales among digitally native consumers. MFDS regulates health functional foods with stringent safety and efficacy requirements. The Seoul Capital Area concentrates probiotic strain production facilities and fermented supplement innovation labs.
Australia
Sports nutrition demand among amateur athletes drives ready-to-drink protein format adoption through specialty retailers. TGA rescheduling of certain botanical extracts creates import eligibility uncertainty across ASEAN mutual-recognition frameworks. New South Wales and Victoria host formulation facilities serving Asia-Pacific export markets.
Asia Pacific Nutraceuticals Market Competitive Environment
Top-tier vendors anchor pharmacy and hospital channels, while mid-tier formulators compete on delivery format innovation and regional regulatory agility. The market structures around three tiers: multinational conglomerates with dairy-protein infrastructure, direct-sales networks controlling access in emerging markets, and specialized botanical extract processors. Strategic moves concentrate on clinical evidence generation for Japan's FFC system and microencapsulation technology licensing for gummy format expansion.
Within the multinational nutrition conglomerate tier, Nestlé SA and Abbott Laboratories exemplify divergent channel strategies. Nestlé leverages dairy-protein infrastructure to dominate ready-to-drink recovery formats across Southeast Asian sports nutrition. Abbott anchors hospital discharge protocols with clinical nutrition lines across India and the Philippines. Among direct-sales specialists, Herbalife International of America Inc. occupies a position controlling access in Indonesia and Vietnam through relationship-dependent networks now facing displacement from app-based personalized nutrition platforms.
| Leading Market Players |
|---|
| Nestlé SA |
| PepsiCo Inc. |
| Herbalife International of America Inc. |
| Bayer AG |
| Abbott Laboratories |
| Amway Corp |
| ADM Company |
| Cargill Inc. |
| Aland (Jiangsu) Nutraceutical Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Pharmacy chain procurement in China's tier-one cities anchors pricing power for premium herbal supplements, with volume commitments to Nestlé SA and Abbott Laboratories enabling contract-based offtake structures that compress margins for regional formulators lacking SAMR compliance infrastructure.
Pricing Analysis
Short lead-time premiums dominate contract negotiations for probiotic strains and omega fatty acid feedstocks, with ASEAN formulators paying spot-market markups when South Korean and Japanese suppliers face capacity constraints. Three-tier pricing structure across FFC-registered premium, standard pharmacy-grade, and supermarket private-label economy levels stratifies by clinical evidence depth and channel access. Cost compression in gummy format manufacturing is intensifying because microencapsulation technology licensing fees concentrate among Japanese and South Korean equipment vendors. Price sensitivity peaks among elderly Japanese consumers targeted by supermarket private-label lines, while amateur athletes in Southeast Asia show lowest elasticity for ready-to-drink recovery formats.
Supply Chain Analysis
Regional distribution centers in Shanghai, Tokyo, and Singapore orchestrate hub-and-spoke patterns for temperature-sensitive bioactives, with humidity-controlled warehousing commanding capacity premiums during monsoon seasons. Probiotic strain production clusters in South Korea and Japan, with herbal extract processing concentrating in Maharashtra and Gujarat. Raw material dependencies include fish oil from marine harvest cycles, plant sterols from agricultural commodity markets, and gelatin feedstocks for gummy matrices. Single-source vulnerability runs through South Korean fermentation facilities serving ASEAN formulators. Distribution runs through pharmacy chains in China's tier-one cities, online platforms in South Korea and Australia, and direct-sales networks in Indonesia and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
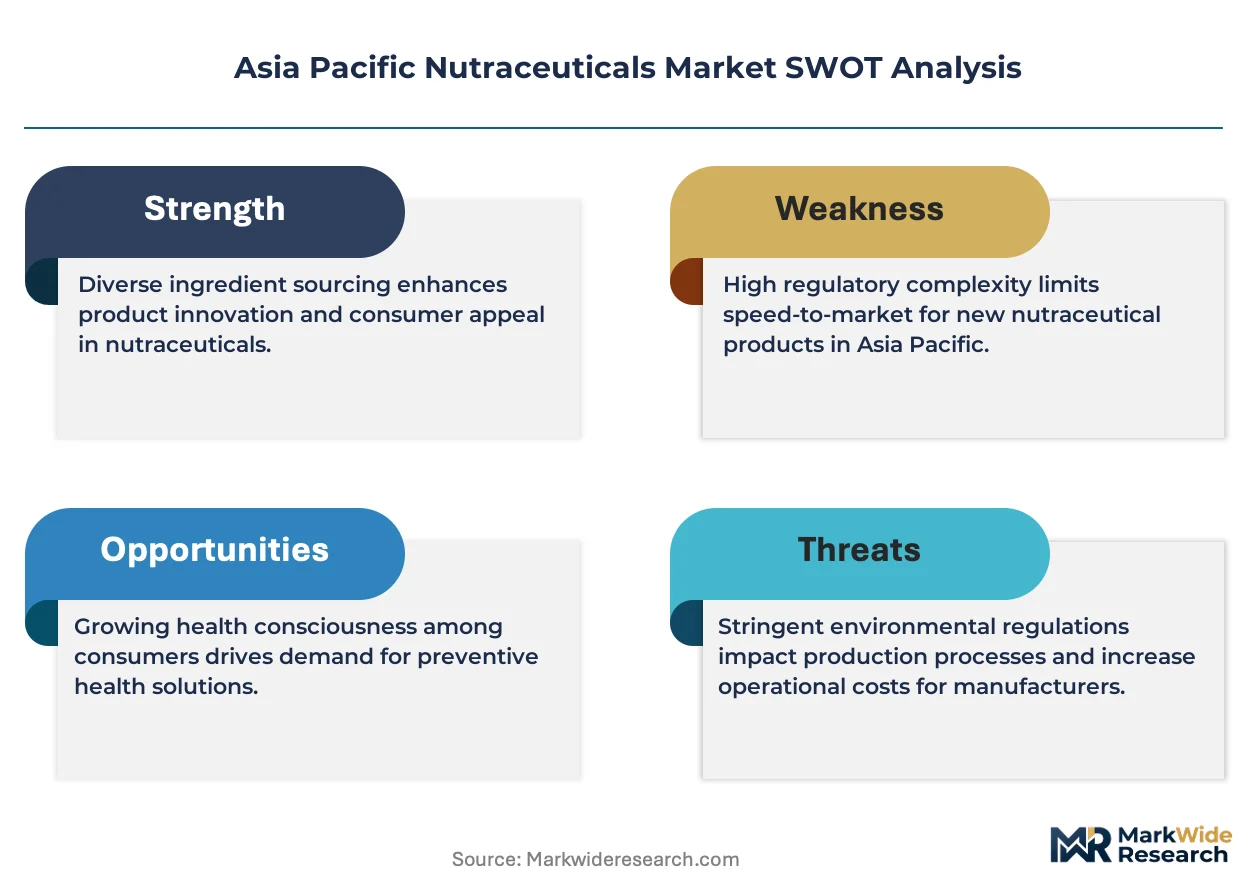
Japan's Foods with Function Claims system functions as a cost-of-compliance moat, with clinical evidence dossier requirements filtering out mid-tier formulators and concentrating premium positioning among scaled producers with dedicated trial investment capacity.
For Market Incumbents: Lock in pharmacy shelf access through exclusive distribution agreements with China's tier-one city chains before SAMR label accuracy enforcement tightens further. Deepen backward integration into probiotic strain cultivation to reduce import dependency on South Korean suppliers. Prioritize microencapsulation technology licensing to capture gummy format price premiums in pediatric applications. For New Entrants and Emerging Players: E-commerce aggregators in South Korea and Australia represent the most penetrable channel entry point for vitamin and supplement lines displacing pharmacy dominance. Target subscription-model adoption among Singapore and Hong Kong urban professionals seeking personalized nutrition platforms. Pursue white-label manufacturing partnerships with Thai and Malaysian functional food producers adopting spray-drying systems for ambient-temperature probiotic distribution. For Investors and Strategic Acquirers: The window for entry favors botanical extract processors with FSSAI-compliant facilities in Maharashtra and Gujarat ahead of India's tightened label-claim verification enforcement. Long-term viability hinges on acquisition targets with established FFC registration pathways or proprietary microencapsulation IP. Monitor Australia's TGA rescheduling decisions as an inflection indicator for ASEAN mutual-recognition framework disruptions.| Strategic Initiative | Industry Significance |
|---|---|
| FFC Clinical Evidence Investment | Japan's MHLW rewards dossier-backed entrants with pharmacy shelf access and premium positioning. |
| Microencapsulation Technology Licensing | Thai and Malaysian manufacturers gain ambient-temperature probiotic inclusion into bakery applications. |
| Online Channel Expansion | South Korean and Australian platforms displace pharmacy intermediaries with direct customer data capture. |
| Backward Integration into Strain Production | ASEAN formulators reduce South Korean import dependency through captive fermentation capacity. |
| Supermarket Private-Label Launch | Japanese retailers erode branded shelf space with house-brand functional foods for cost-conscious elderly. |
Study Parameters
Regulatory filings with Japan's MHLW, India's FSSAI notification databases, and China's SAMR GB standard publications formed the secondary backbone for compliance timeline mapping and competitive positioning assessment. Primary interviews with pharmacy chain procurement managers, nutraceutical formulators, and clinical trial coordinators validated demand segmentation and channel evolution hypotheses. Bottom-up modeling of product-type volumes combined with top-down macroeconomic triangulation anchored forecast integrity.
Historical trendline analysis of vitamin, herbal supplement, and sports nutrition demand patterns informed baseline trajectory establishment across the projection horizon. Segmentation dimensions modeled include product type, delivery form, end-user archetype, and distribution channel, with regulatory cluster overlays for FFC, GB standards, and FSSAI compliance tiers. CAGR derivation incorporated input cost volatility for fish oil and plant sterol feedstocks alongside channel shift velocities from pharmacy to online retail.
Caveats apply where Australia's TGA rescheduling decisions, marine harvest cycle disruptions, or FSSAI enforcement intensity shifts could materially shift the outlook for ASEAN import eligibility and product registration timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Energy Gel Products Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Vitamin K2 Market
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
Global Natural Health Supplements Market
Nutritional Supplements
Brain Health Supplement Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Fish Collagen Market
Nutritional Supplements
Fiber Supplements Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Nicotine Gum Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
L Carnitine Market