
 North America Digestive Health Supplements Market | 2026-2036
North America Digestive Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
North America Digestive Health Supplements Market Analytics
A capital-intensity divergence between probiotic strain development capabilities and generic formulation packaging is redrawing competitive boundaries in North American digestive health. Bayer AG leverages its pharmaceutical-grade manufacturing infrastructure to sustain quality differentiation against commodity competitors. NOW Health Group Inc. anchors its position through vertical integration into raw botanical sourcing. Pfizer Inc. competes by extending clinical validation protocols from its drug development heritage into supplement claims substantiation.
Digestive health supplements comprise ingestible products formulated with live microbial cultures, non-digestible fibers, or enzymatic compounds intended to modify gastrointestinal function, nutrient absorption, or microbiome composition. Probiotic formulations require strain-specific viability thresholds, typically measured in colony-forming units at manufacture and through shelf-life expiration, with industrial stability achieved via freeze-drying or microencapsulation against gastric acid degradation. Probiotics leads the product type landscape due to established consumer recognition and refrigerated supply chain maturation, while digestive enzymes represents the fastest-expanding category as athletic end users seek protein breakdown acceleration. Capsule formulations occupy the dominant share of formulation types, though gummies is displacing traditional delivery systems among children and convenience-oriented adults.
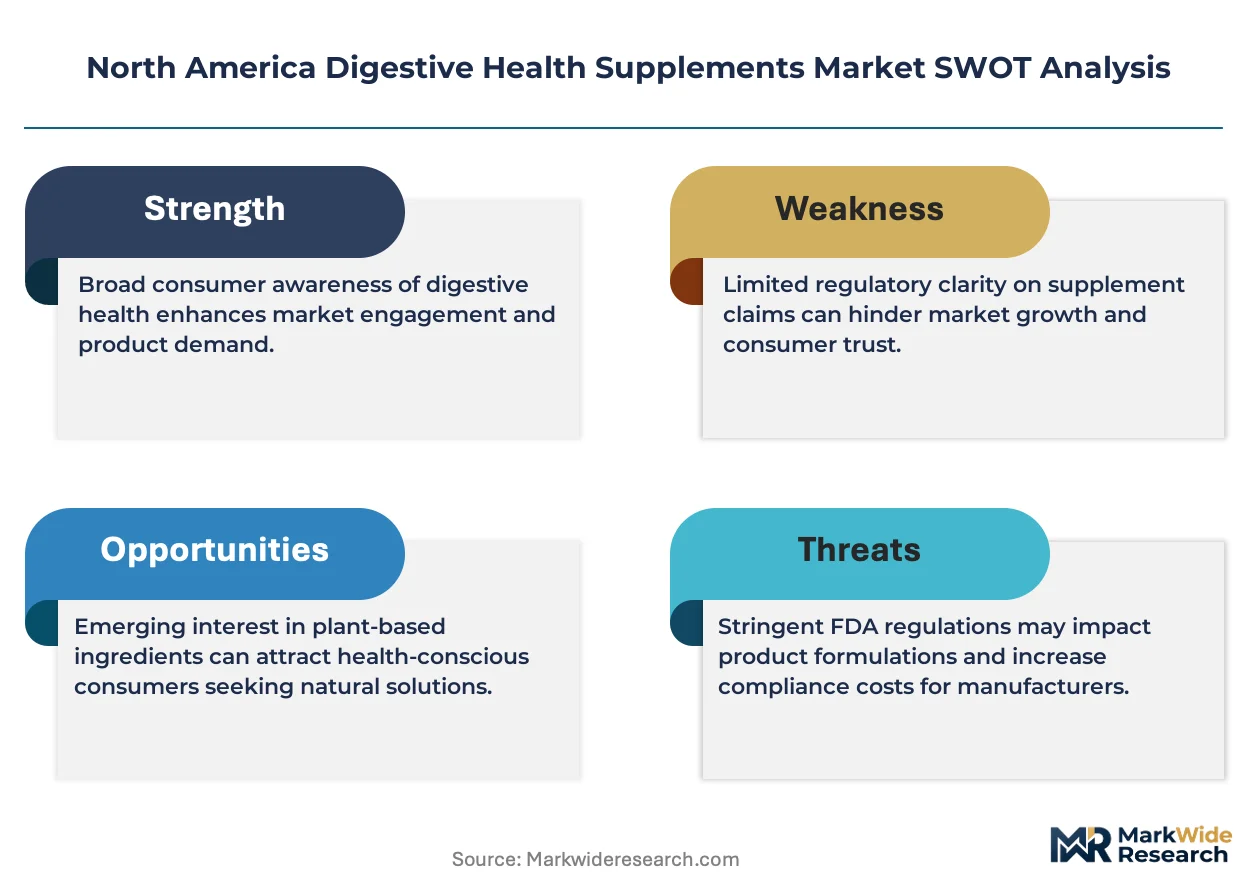
The FDA's Current Good Manufacturing Practice regulations and NDI notification requirements impose compliance costs that favor scaled manufacturers over emerging entrants. Health Canada's Natural and Non-prescription Health Products Directorate maintains parallel stricture through site licensing and product-specific Natural Product Numbers, creating dual-jurisdiction complexity for cross-border marketers. Stakeholders must monitor evolving probiotic-specific guidance documents from both regulators, as classification ambiguity between food, supplement, and therapeutic categories determines permissible health claims and channel access.
Market Dynamics
Strain-specific clinical validation requirements are bifurcating the North American digestive health supplements landscape, separating pharmaceutical-grade probiotic developers from commodity contract manufacturers unable to sustain viability testing investments.
Growth Catalysts
- FDA NDI notification pathway maturation:The notification framework now provides clearer pre-market substantiation routes, accelerating product launch timelines for compliant manufacturers in the United States.
- Athletic end-use protein digestion optimization:Competitive bodybuilders and endurance athletes drive enzymatic supplement adoption for nutrient timing precision and recovery acceleration.
- California metropolitan wellness corridor concentration:Los Angeles and San Francisco Bay Area consumers demonstrate disproportionate willingness to pay for microbiome-targeted functional foods.
Market Restraints
- Refrigerated cold chain cost structure:Probiotic viability maintenance requires continuous temperature-controlled logistics, elevating distribution expenses beyond ambient-stable supplement categories.
- Strain IP concentration among European culture banks:North American formulators depend on licensed access to clinically documented probiotic strains held by Danish and French repository institutions.
- Health Canada NNHPD site licensing reciprocity gaps:Dual-jurisdiction compliance creates cross-border market entry friction for US manufacturers seeking Canadian distribution.
Strategic Opportunities
- Mexico underpenetrated probiotic awareness:Latin American consumer education investments unlock first-mover positioning in Guadalajara and Monterrey metropolitan markets.
- Direct-to-physician channel development:Functional medicine practitioners increasingly recommend strain-specific formulations, creating prescriptive credibility bridges to skeptical consumers.
- Microencapsulation-3D printing convergence:Layered deposition technologies enable personalized dosage stacking with gastric acid protection tailored to individual pH profiles.
Industry Challenges
- Microbiome assay technician scarcity:Strain enumeration and shelf-life stability testing require specialized laboratory personnel in short supply across US quality control departments.
- Freeze-dryer capital equipment intensity:Industrial-scale probiotic viability preservation demands seven-figure lyophilization infrastructure investments prohibitive to mid-scale entrants.
- FDA probiotic guidance document ambiguity:Pending classification determinations between food, supplement, and therapeutic categories delay claim substantiation strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Digestive Health Supplements Market |
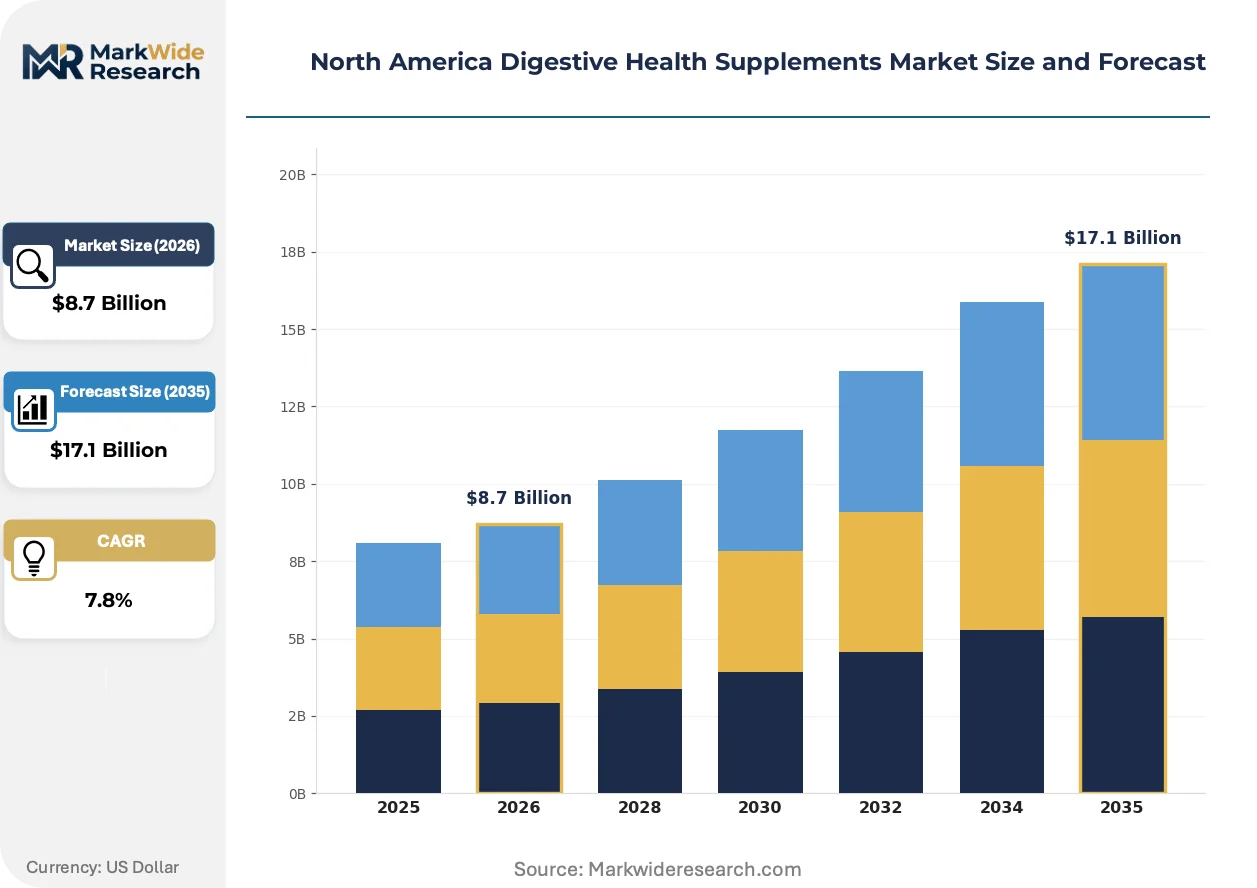
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Digestive Enzymes, Fiber Supplements End User: Adults, Children, Seniors, Athletes Formulation: Capsules, Powders, Gummies, Liquids Distribution Channel: Retail, Online, Pharmacies, Health Stores |
| Companies Covered | Bayer AG, NOW Health Group Inc., Herbalife Nutrition Ltd., Koninklijke DSM NV, Pfizer Inc., Amway Corporation, GlaxoSmithKline Plc, Nestlé SA, Danone SA, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Digestive Health Supplements Market Evolving Landscape
Bioprocessing advances and delivery system engineering are compressing the gap between pharmaceutical bioavailability standards and consumer supplement accessibility in North American digestive health.
Microencapsulation technology is miniaturizing protective matrices around live probiotic cultures, enabling ambient shelf stability without refrigeration dependency. Athletic and travel-oriented consumer segments adopt these formats fastest, driving formulation R&D investment away from traditional refrigerated supply chains toward convenience-optimized packaging.
Health Canada's evolving Natural and Non-prescription Health Products Directorate guidance on probiotic-specific claims is tightening substantiation requirements for Canadian market access. US manufacturers with existing FDA NDI documentation face parallel compliance investments, compressing margins for cross-border marketers while advantaging domestic Canadian licensees with established site credentials.
Subscription-based replenishment models displace traditional retail replenishment cycles among chronic digestive condition sufferers. Direct-to-consumer platforms capture recurring revenue from irritable bowel syndrome and celiac disease patient communities, with California and Colorado zip codes showing highest subscription retention rates and lowest price sensitivity to auto-ship premiums.
North America Digestive Health Supplements Market Segmentation
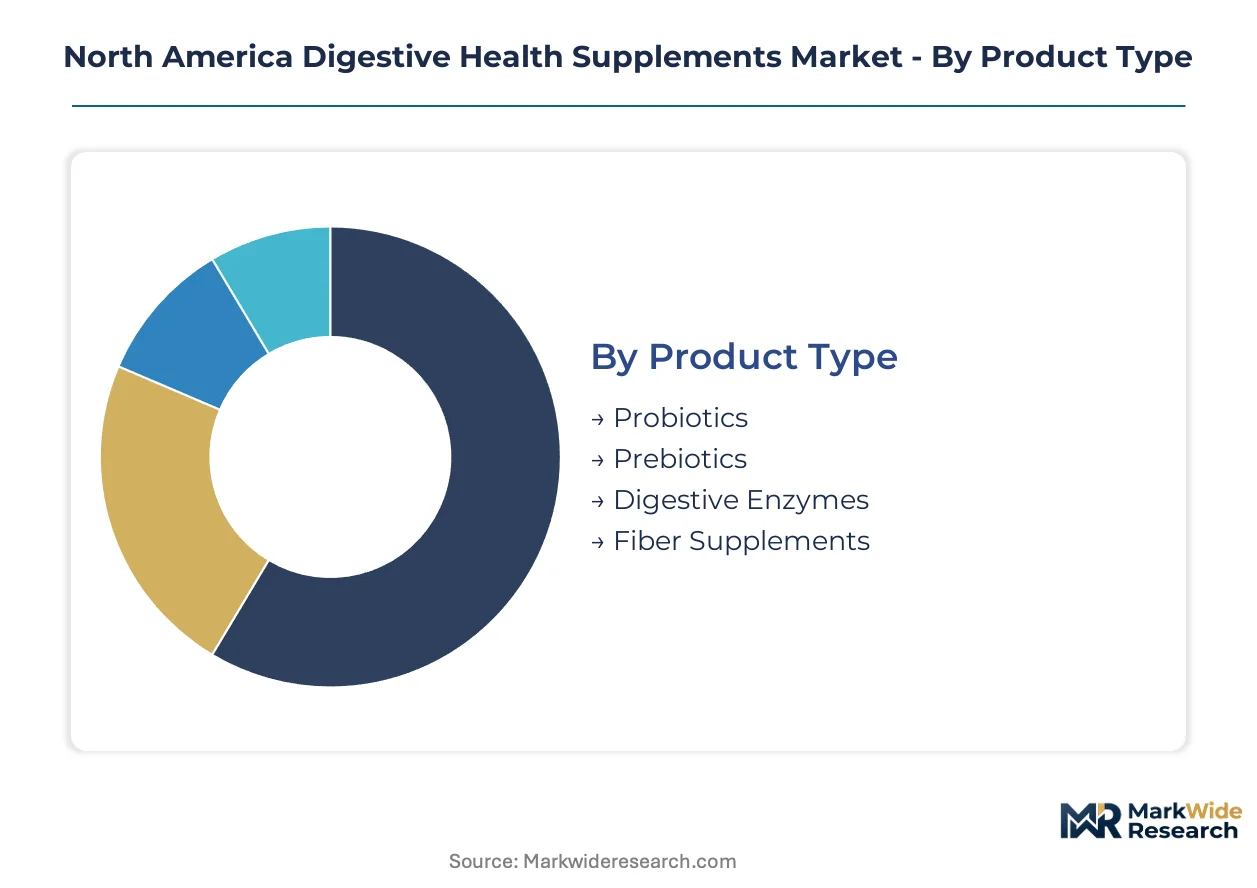
Strategic targeting in North American digestive health requires precise alignment between product format, consumer life stage, and channel accessibility. Segment boundaries determine viability thresholds, regulatory pathways, and margin sustainability across the value chain.
Product Type:
Margin pools concentrate in clinically validated strain portfolios where IP licensing creates pricing power, while commodity formulations compete on manufacturing scale alone.
- Probiotics:Live microbial cultures measured in colony-forming units require freeze-drying or microencapsulation for gastric acid survival. California metropolitan wellness corridors drive premium positioning for refrigerated and shelf-stable formats alike.
- Digestive Enzymes:Protease, lipase, and amylase formulations accelerate macronutrient breakdown. Competitive bodybuilders and endurance athletes in Colorado and Texas generate concentrated demand for protein digestion optimization.
- Prebiotics:Non-digestible fibers including inulin and oligosaccharides feed indigenous microbiota.
- Fiber Supplements:Psyllium husk and methylcellulose formulations address constipation and cholesterol management.
The dominant share belongs to Probiotics, while Digestive Enzymes is closing the gap fastest.
End User:
Adult chronic condition sufferers anchor volume, though pediatric and athletic niches command per-unit premiums through specialized delivery formats.
- Adults:Irritable bowel syndrome and celiac disease patients sustain subscription replenishment models through direct-to-consumer platforms. California and Colorado zip codes show highest auto-ship retention with minimal price sensitivity.
- Seniors:Age-related microbiome degradation and medication-induced digestive disruption create sustained demand for high-CFU probiotic regimens.
- Children:Gummy formulations displace traditional delivery systems where palatability determines compliance.
- Athletes:Nutrient timing precision requirements drive enzymatic supplement adoption for recovery acceleration.
Adults capture the largest addressable base, with Athletes expanding most quickly through performance-oriented positioning.
Formulation:
Convenience optimization and shelf-stability engineering are redistributing investment across delivery system categories.
- Capsules:Hard-shell gelatin and vegetable-based enclosures dominate institutional and clinical recommendation channels. Enteric coating investments protect acid-sensitive strains through gastric passage.
- Gummies:Gelatin and pectin matrices enable child compliance and adult convenience adoption. Los Angeles and San Francisco Bay Area consumers demonstrate disproportionate willingness to pay for palatable microbiome support.
- Powders:Bulk formats serve high-volume users and recipe integration applications.
- Liquids:Ready-to-drink formulations target travel and on-the-go consumption occasions.
Capsules hold the established position, though Gummies is gaining share fastest through demographic expansion beyond pediatric origins.
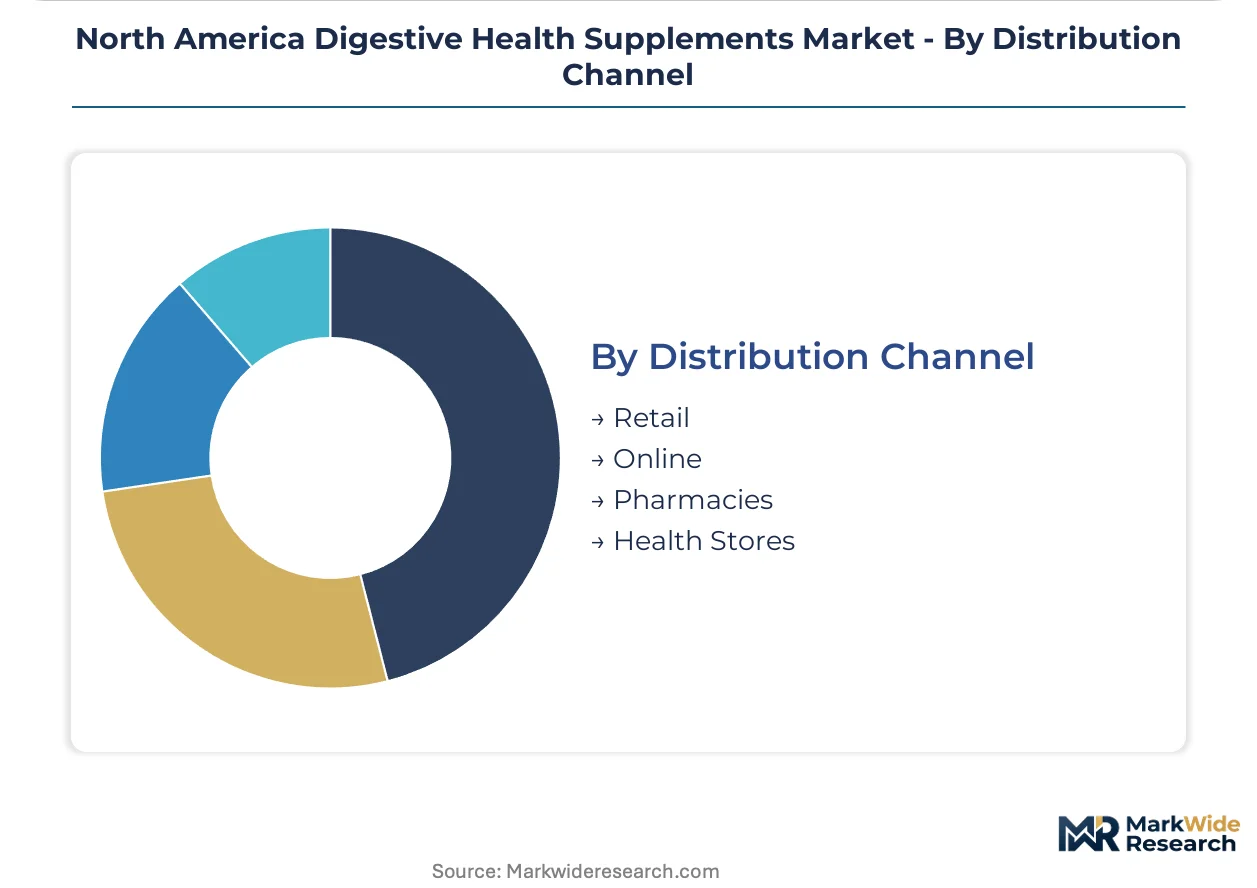
Distribution Channel:
Channel selection determines regulatory scrutiny intensity and claim substantiation flexibility.
- Retail:Mass merchandisers and grocery chains enforce slotting fee structures that favor scaled manufacturers with refrigerated logistics capabilities.
- Online:Direct-to-consumer platforms bypass intermediary markups while capturing subscription revenue from chronic condition communities. Auto-ship models show strongest traction in wellness-oriented metropolitan corridors.
- Pharmacies:Pharmacist recommendation channels lend clinical credibility to strain-specific formulations.
- Health Stores:Specialty retailers cater to educated consumers seeking third-party certification and clean label attributes.
Retail maintains volume leadership, while Online is climbing the fastest through subscription retention mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across North American markets, with Mexican consumers showing the highest elasticity and California metropolitan buyers demonstrating the lowest willingness-to-pay variance for clinically validated strains.
United States
FDA NDI notification pathway maturation accelerates product launch timelines for compliant manufacturers. The agency's Current Good Manufacturing Practice regulations impose compliance costs favoring scaled manufacturers over emerging entrants. Los Angeles and San Francisco Bay Area wellness corridors drive disproportionate willingness to pay for microbiome-targeted functional foods.
Canada
Health Canada's Natural and Non-prescription Health Products Directorate maintains strict site licensing through product-specific Natural Product Numbers. Dual-jurisdiction complexity creates cross-border market entry friction for US manufacturers seeking Canadian distribution. Toronto and Vancouver metropolitan clusters anchor domestic formulation demand.
Mexico
Underpenetrated probiotic awareness creates first-mover positioning opportunities in Guadalajara and Monterrey metropolitan markets. The country's national health regulator maintains evolving supplement classification standards. Mexico City Metro concentrates functional food retail expansion investments from multinational brands.
North America Digestive Health Supplements Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where pharmaceutical-grade manufacturers compete against commodity contract packagers. The market separates into three strategic groupings: multinational conglomerates with clinical validation infrastructure, vertically integrated botanical specialists, and regional private-label formulators. Dominant competitive moves include backward integration into raw material sourcing and geographic expansion through direct-to-physician channel development.
Among pharmaceutical heritage players, Bayer AG and Pfizer Inc. occupy positions exemplifying clinical-grade manufacturing infrastructure. NOW Health Group Inc. anchors the vertically integrated specialist tier through upstream control over raw botanical supply chains. These three entities represent the archetype spectrum spanning regulatory sophistication, manufacturing scale, and supply chain depth.
| Leading Market Players |
|---|
| Bayer AG |
| NOW Health Group Inc. |
| Herbalife Nutrition Ltd. |
| Koninklijke DSM NV |
| Pfizer Inc. |
| Amway Corporation |
| GlaxoSmithKline Plc |
| Nestlé SA |
| Danone SA |
| Others |
Value Network & Pricing Analysis
Freeze-dryer capacity utilization above 85% in US pharmaceutical-grade facilities creates natural price floors for probiotic formulations while squeezing mid-scale competitors toward contract manufacturing commoditization. This scale concentration permits incumbents to absorb FDA NDI compliance costs as fixed overhead, whereas emerging entrants face per-unit regulatory burdens that compress margins before refrigerated logistics even enter the equation.
Pricing Analysis
Subscription auto-ship revenue drives lifetime value for chronic condition sufferers, with California and Colorado zip codes showing minimal churn sensitivity to 15-20% premium tiers. Three-tier pricing structure across premium refrigerated strains, standard shelf-stable formats, and economy private-label generics reflects certification grade and cold-chain investment differentiation. Pricing pressure stems from Health Canada NNHPD site licensing reciprocity gaps that force dual compliance spend for cross-border marketers. Athletic end users in Texas and Colorado demonstrate lowest price sensitivity due to performance-linked willingness to pay, while mass retail channels in Mexico show highest elasticity.
Supply Chain Analysis
Denmark and France anchor clinically documented probiotic strain repositories, with North American formulators licensing IP from European culture banks under royalty-bearing agreements. Raw material dependencies center on freeze-dried culture concentrates, enteric coating polymers, and botanical fiber inputs from India and China. Single-source vulnerability concentrates in Danish strain documentation that determines FDA NDI notification acceptance. Distribution runs through temperature-controlled logistics partnerships for refrigerated formats, while ambient-stable microencapsulated products bypass cold-chain infrastructure through direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microencapsulation-3D printing convergence represents a technological inflection that will compress pharmaceutical-grade manufacturing timelines from years to months, reshaping competitive barriers across the North American landscape.
For Market Incumbents: Fortify strain-specific clinical validation portfolios against commodity contract manufacturers by extending FDA NDI documentation into Health Canada NNHPD parallel submissions. Lock in refrigerated logistics capacity through long-term carrier agreements before athletic-end-use demand spikes in Colorado and Texas exhaust regional cold-chain infrastructure. Prioritize backward integration into raw botanical sourcing to insulate margin positions from Indian and Chinese fiber input volatility. For New Entrants and Emerging Players: Differentiate on direct-to-physician channel development targeting functional medicine practitioners in Los Angeles and San Francisco Bay Area wellness corridors. Exploit Mexico's underpenetrated probiotic awareness through Spanish-language consumer education investments in Guadalajara and Monterrey metropolitan markets. Pursue white-label gummy formulation partnerships with established California-based contract manufacturers to bypass freeze-dryer capital intensity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive raw material supply and established site licensing credentials. Five-to-ten-year viability hinges on regulatory navigation capabilities across FDA and Health Canada dual jurisdictions rather than manufacturing scale alone. Monitor FDA probiotic guidance document publication as the critical inflection signal determining classification boundaries between food, supplement, and therapeutic categories.| Strategic Initiative | Industry Significance |
|---|---|
| Strain-Specific Clinical Validation Investment | FDA NDI notification acceptance accelerates product launch timelines for compliant manufacturers. |
| Microencapsulation Technology Licensing | Ambient shelf stability eliminates refrigerated logistics dependency for travel-oriented consumer segments. |
| Direct-to-Physician Channel Development | Functional medicine practitioner recommendations bridge credibility gaps to skeptical supplement consumers. |
| Health Canada NNHPD Site Licensing Expansion | Dual-jurisdiction compliance credentials capture Toronto and Vancouver metropolitan demand clusters. |
| Subscription Platform Auto-Ship Infrastructure | Recurring revenue mechanics from IBS and celiac patient communities minimize customer acquisition cost inflation. |
Research Methodology
A standing panel of probiotic R&D directors, regulatory affairs leads at FDA-registered facilities, functional medicine practitioners, and refrigerated logistics operators provided ongoing calibration across the study period. Primary interview data combined with secondary validation from FDA NDI notification databases, Health Canada NNHPD site licensing records, and Nielsen retail audit data for supplement categories. Bottom-up strain-level demand modeling triangulated against top-down category spend estimates from institutional procurement databases.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, end-user life stage, formulation format, and distribution channel complexity. CAGRs derived from probiotic CFU demand curves, enzymatic supplement athletic adoption rates, and gummy format displacement patterns. Industry-specific inputs included refrigerated supply chain cost trajectories and microencapsulation yield improvement curves.
Material uncertainties — FDA probiotic guidance document finalization timing, Health Canada NNHPD reciprocity agreement evolution, and freeze-dryer capacity expansion cycles — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and strain IP licensing continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Digestive Enzyme Complex Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
Whey Protein Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
Natural Colostrum Supplements Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Policosanol Market
Nutritional Supplements
Global Multivitamin Capsules and Tablets Market
Nutritional Supplements
Asia-Pacific Collagen Peptide Products Market