
 Global Hemp Protein Market | 2026-2036
Global Hemp Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hemp Protein Market Foresight
The split between cold-pressed premium hemp protein and solvent-extracted commodity grades is repositioning procurement priorities across the value chain. Manitoba Harvest Hemp Foods leverages its Canadian cultivation base to anchor supply security for North American buyers. Nutiva competes through organic certification density and clean-label positioning in natural retail channels. Navitas Organics specializes in superfood blending formats that extend hemp protein into smoothie and bowl applications beyond traditional powder.
Hemp protein consists of defatted hemp seed meal milled to 50% protein content, containing a complete amino acid profile with digestibility corrected scores comparable to soy. The manufacturing process employs mechanical pressing at temperatures below 45°C to preserve enzymatic activity and minimize lysine degradation. Sports nutrition and dietary supplements command the deepest margin pools as consumers pay formulation premiums for post-workout recovery positioning. Functional foods and bakery ingredients are gaining velocity as CPG manufacturers reformulate wheat-based products with partial hemp protein substitution for allergen reduction.
The FDA maintains hemp-derived ingredients under evolving GRAS notification requirements while Health Canada oversees cannabis and hemp processing under the Cannabis Act framework. EFSA's Novel Food catalogue entry for hemp seeds underpins standardized market access across EU member states. Stakeholders must monitor how THC threshold harmonization between jurisdictions reshapes cross-border ingredient trade and extraction facility siting decisions.
Market Dynamics
The cold-pressed versus solvent-extracted processing divide is reconfiguring procurement hierarchies as buyers segregate premium enzymatic-grade stock from commodity feed fractions.
Growth Catalysts
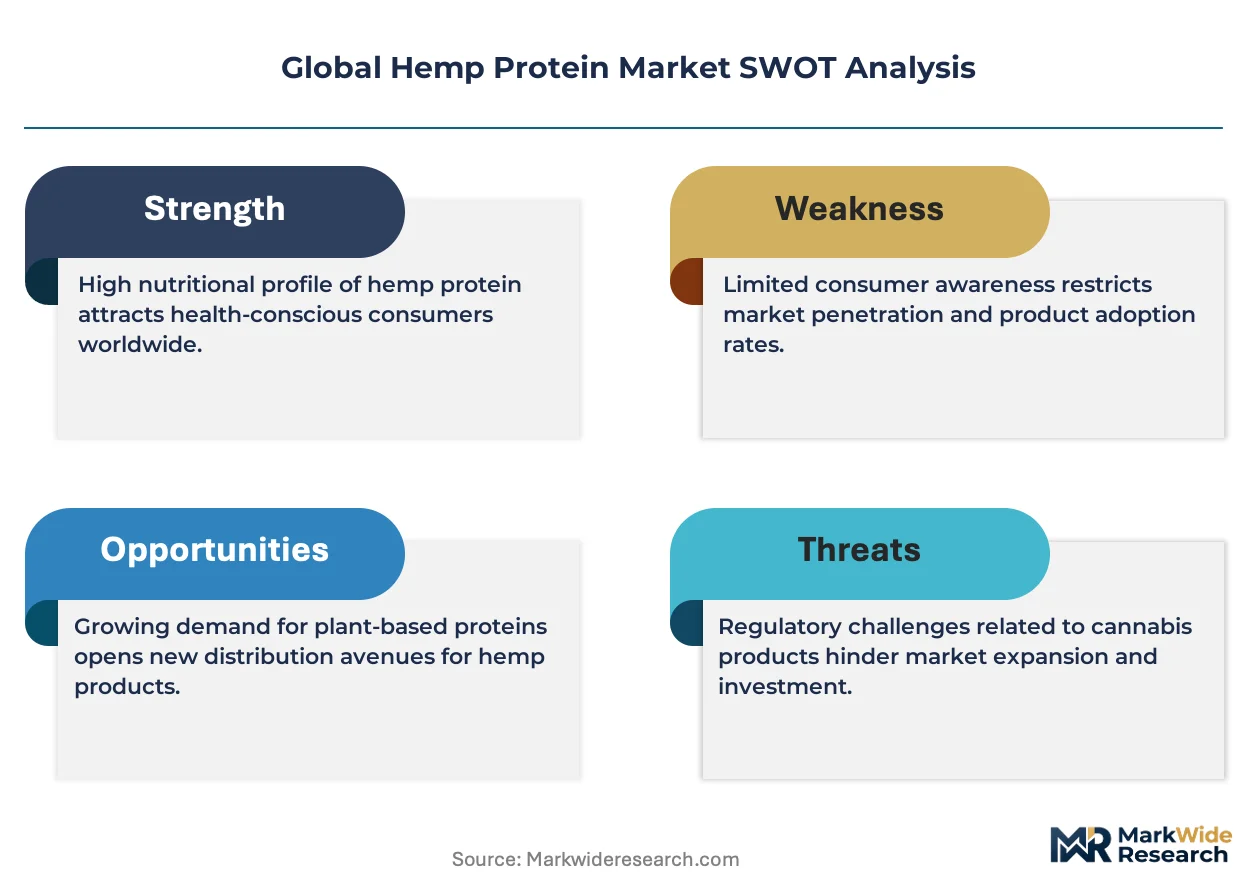
- EU Novel Food authorization:EFSA's standardized safety assessment for hemp seed derivatives eliminates member-state fragmentation, accelerating CPG formulation approvals across Germany, France, and the Netherlands.
- Sports nutrition pivot:Post-workout recovery brands are substituting whey isolates with hemp protein concentrates to capture lactose-intolerant athlete segments and clean-label positioning.
- Mechanical pressing below 45°C:Low-temperature extraction preserves lysine integrity and enzymatic activity, enabling premium pricing for functional food applications.
Market Restraints
- THC threshold harmonization gaps:Misalignment between Health Canada's 10 ppm limit and FDA's evolving hemp GRAS determinations complicates cross-border ingredient shipments and dual-facility siting.
- Input cost volatility:Hemp seed prices fluctuate with Canadian and Chinese cultivation cycles, squeezing margin stability for mechanical-pressing operators.
- Protein digestibility ceiling:Hemp's PDCAAS scores trail soy and pea isolates, restricting penetration into clinical nutrition and infant formula segments.
Strategic Opportunities
- Bakery allergen reduction:Partial wheat substitution with hemp protein in gluten-free bread and pastry formulations opens shelf-space in German and Austrian retail channels.
- Smoothie bowl superfood blending:Hemp-cacao-acai combinations are expanding distribution through specialty café chains and direct-to-consumer subscription models.
- US Farm Bill stability:Federally legal hemp cultivation infrastructure in Montana and Kentucky enables backward integration for ingredient processors seeking captive supply security.
Industry Challenges
- Organic certification timelines:Three-year transition periods for conventional hemp acreage delay supply responses to clean-label demand surges.
- Extraction technician scarcity:Specialized cold-press operation and temperature-controlled milling expertise concentrates in Manitoba and Saskatchewan, constraining facility scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hemp Protein Market |
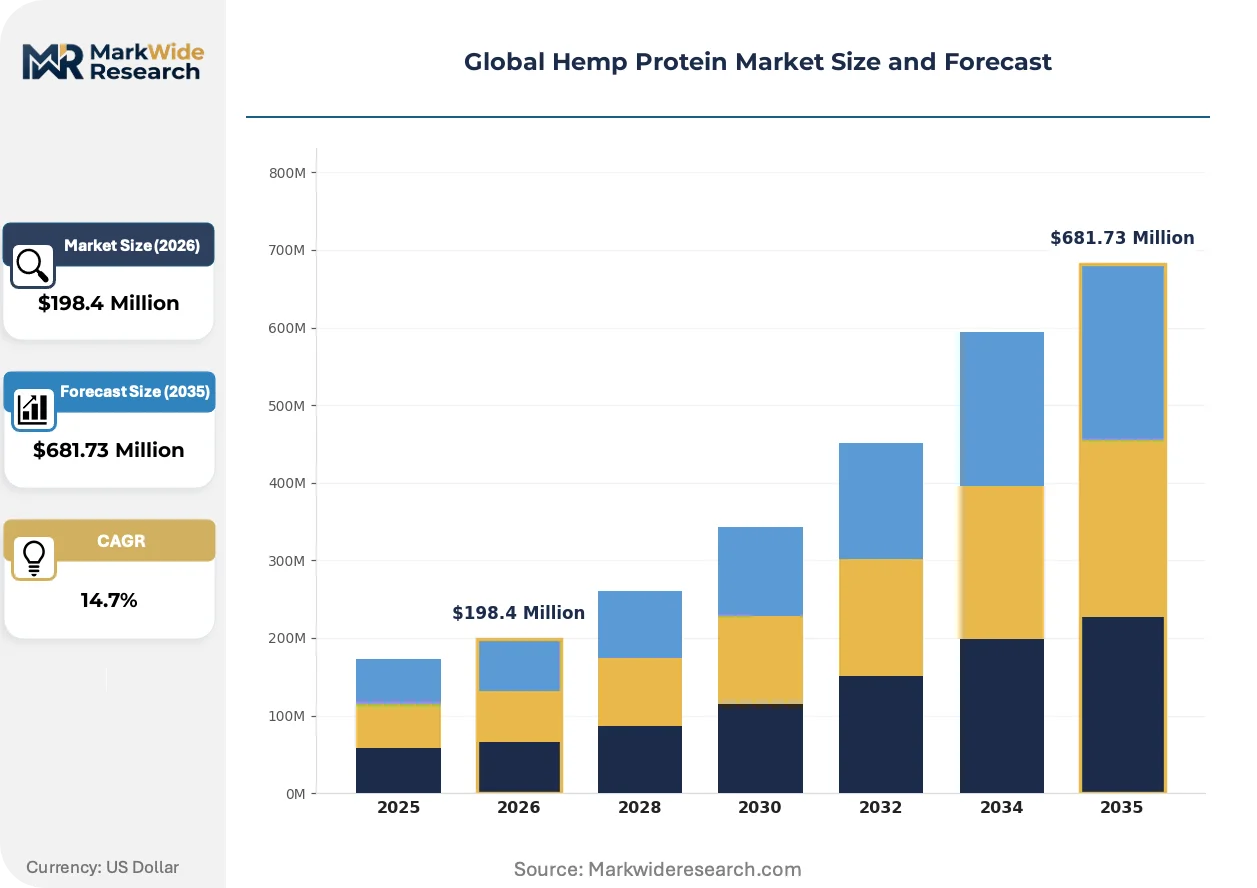
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $681.73 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Protein Powder, Concentrates, Isolates, Blended Products Application: Sports Nutrition, Animal Feed, Functional Foods, Dietary Supplements, Bakery Ingredients End User Industry: Food & Beverage Manufacturers, Nutraceutical Companies, Pet Food Producers, Personal Care Product Makers Packaging Type: Stand-up Pouches, Sachets, Bulk Bags, Resealable Bags, Glass Jars |
| Companies Covered | Axiom Foods Inc., Manitoba Harvest Hemp Foods, Martin Bauer Group, ETChem, Tilray Brands Inc., Navitas Organics, Nutiva, Evo Hemp, Victory Hemp Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hemp Protein Market Shifts & Advancements
Processing technology maturation and regulatory clarity are converging to reposition hemp protein from niche supplement aisles into mainstream CPG formulation.
Micro-milling and air-classification systems are expanding into 50-70% protein concentrate production with controlled particle size distribution. Sports nutrition manufacturers in the United States and Germany are adopting these systems at pilot scale. The technology is expanding into bakery and meat-alternative applications previously reserved for soy and pea isolates.
EFSA's consolidated Novel Food entry for hemp seeds underpins standardized market access, replacing the prior patchwork of national approvals. Food manufacturers now navigate a single compliance pathway for EU-wide distribution. German and Dutch CPG brands are responding fastest, accelerating hemp-fortified product launches ahead of 2025-2026 retail resets.
Clean-label certification is compressing supplier selection cycles as buyers prioritize organic and non-GMO verification over price. Natural retail channels and direct-to-consumer platforms are displacing conventional grocery distribution for premium hemp protein SKUs. This pattern is most visible in California and Pacific Northwest markets where consumer willingness-to-pay for traceability remains elevated.
Global Hemp Protein Market Segmentation
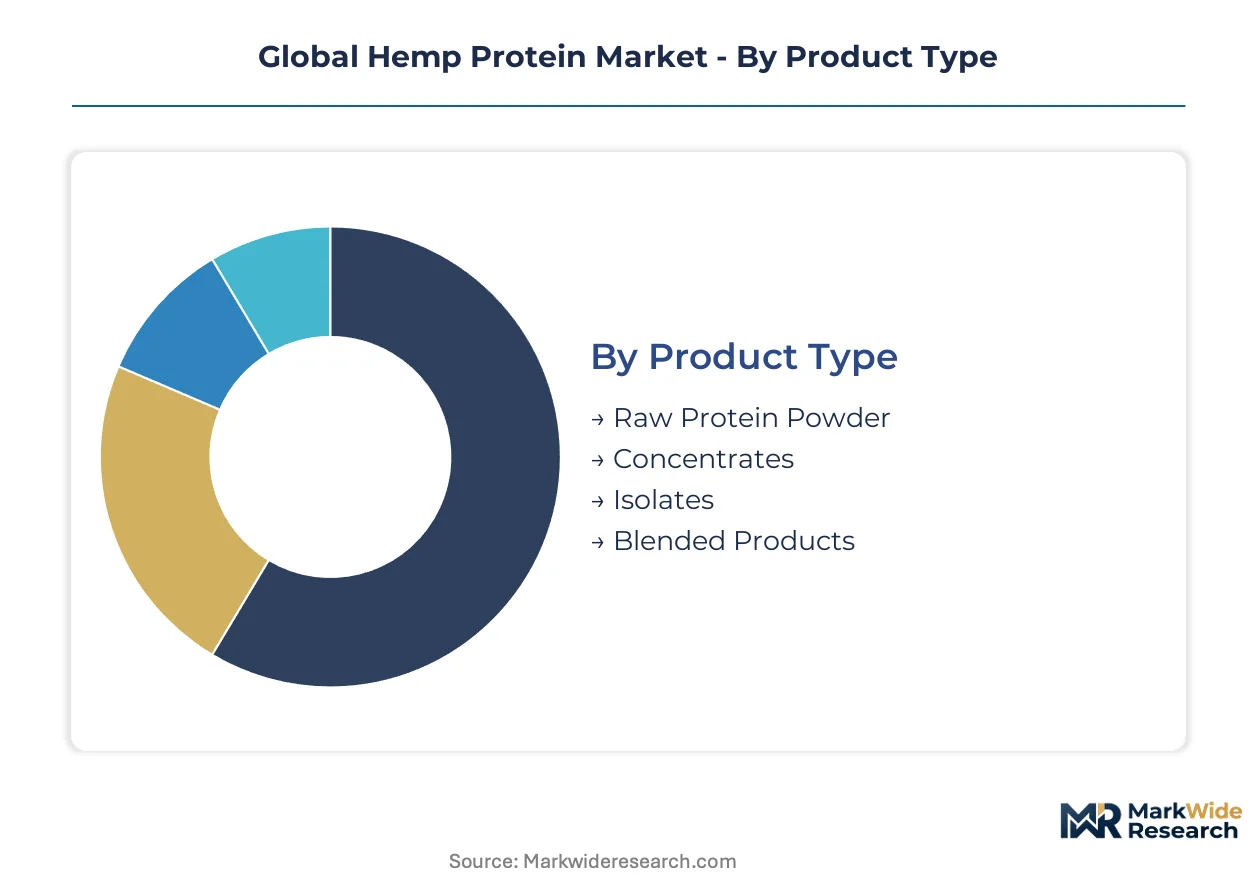
Hemp protein segmentation reveals how processing intensity, application requirements, and buyer sophistication split procurement budgets across distinct value tiers. Manufacturers navigate formulation trade-offs between protein concentration, enzymatic preservation, and cost targets that vary sharply by end-use.
Product Type:
Buyers segment procurement by protein concentration thresholds and processing temperature tolerances that determine functional performance in finished goods.
- Raw Protein Powder:Coarsely milled defatted hemp seed meal at 30-40% protein content serves cost-sensitive animal feed and bulk ingredient buyers. Pet food producers in Canada and Germany absorb the largest volumes where protein specification flexibility reduces input costs.
- Concentrates:Mechanical pressing at sub-45°C yields 50-70% protein fractions with preserved lysine integrity and enzymatic activity. Sports nutrition brands in the United States pay formulation premiums for cold-processed concentrates that support clean-label recovery product positioning.
- Isolates:Further processed to 80%+ protein through air-classification or mild solvent extraction, isolates command the highest purity tier for clinical nutrition applications.
- Blended Products:Pre-formulated combinations with pea, rice, or cacao proteins reduce R&D burden for mid-size CPG manufacturers entering plant-based categories.
Concentrates lead on scale; isolates lead on momentum.
Application:
Application segmentation tracks where protein digestibility scores and flavor masking requirements create divergent technical specifications and margin structures.
- Sports Nutrition:Post-workout recovery powders and ready-to-drink formulations demand complete amino acid profiles with PDCAAS scores competitive against whey isolates. German and US brands reformulate legacy whey SKUs to capture lactose-intolerant athlete segments.
- Functional Foods:Hemp protein integration into pasta, cereals, and meat alternatives accelerates as CPG manufacturers target EU-wide distribution under unified EFSA Novel Food compliance. Dutch and Austrian retail channels show fastest product velocity.
- Dietary Supplements:Capsule and tablet formats concentrate in direct-to-consumer subscription models where organic certification density drives supplier selection.
- Bakery Ingredients:Partial wheat substitution in gluten-free bread formulations expands shelf access in German and Austrian supermarkets.
- Animal Feed:Lower-grade protein fractions enter poultry and aquaculture feed rations where amino acid completeness matters less than cost per unit protein.
Sports nutrition dominates revenue concentration; functional foods exhibit the steepest expansion trajectory.
End User Industry:
End user segmentation reflects how regulatory familiarity, formulation expertise, and certification requirements reshape supplier-buyer contracting patterns.
- Food & Beverage Manufacturers:Large CPG houses with established GRAS notification capabilities and EU regulatory affairs teams integrate hemp protein into mainstream product lines. Multinational bakery and cereal brands in Germany and the Netherlands lead reformulation activity.
- Nutraceutical Companies:Specialized supplement houses concentrate demand for organic-certified concentrates with full traceability documentation. California and Pacific Northwest direct-to-consumer brands pay premiums for single-origin Canadian supply.
- Pet Food Producers:Premium pet nutrition brands in the United States adopt hemp protein for hypoallergenic formulations targeting grain-sensitive companion animals.
- Personal Care Product Makers:Cosmetic and skincare manufacturers utilize hemp protein hydrolysates for amino acid content in hair and skin conditioning applications.
Food and beverage manufacturers lead on scale; nutraceutical companies lead on momentum.
Packaging Type:
Packaging segmentation aligns with distribution channel economics, shelf-life requirements, and consumer convenience expectations across retail and foodservice endpoints.
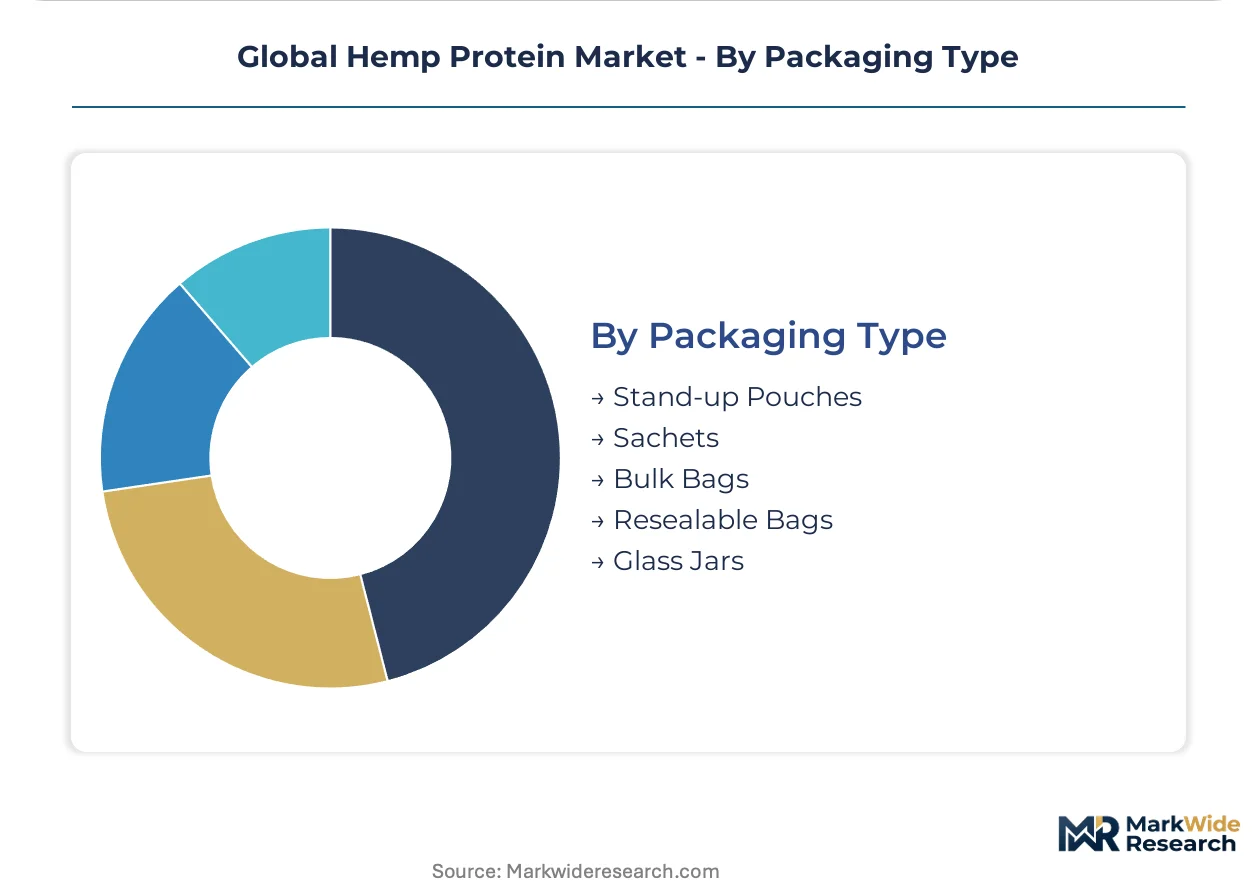
- Stand-up Pouches:Flexible packaging with high barrier properties dominates natural retail channel SKUs where resealability and shelf presence drive purchase decisions. US specialty grocers and German organic supermarket chains standardize on this format.
- Bulk Bags:Food manufacturers and pet food compounders procure 25-50kg woven polypropylene totes for in-house blending operations where packaging cost minimization outweighs consumer-facing presentation.
- Resealable Bags:Zip-lock polyethylene formats serve club store and online subscription models where portion control and storage convenience reduce product waste.
- Sachets:Single-serve 20-30g packets support sampling programs and travel-size distribution in sports nutrition.
- Glass Jars:Premium positioning in specialty food and personal care channels where material sustainability signaling justifies higher unit economics.
Bulk bags lead on scale; stand-up pouches lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in regulatory maturity, with German EFSA alignment enabling faster CPG adoption while US operators navigate evolving FDA GRAS pathways. Canada leverages its Cannabis Act framework to anchor supply security for North American buyers. China and Australia represent contrasting frontier markets where cultivation infrastructure and import regulations respectively determine access timelines.
United States
Sports nutrition brands in California and Colorado drive demand for cold-pressed hemp protein concentrates targeting lactose-intolerant athlete segments. The FDA maintains hemp-derived ingredients under evolving GRAS notification requirements that complicate interstate commerce standardization. Montana and Kentucky cultivation clusters enable backward integration for ingredient processors seeking captive supply security under Farm Bill stability.
Germany
Functional food manufacturers in Bavaria and North Rhine-Westphalia accelerate hemp-fortified bakery and cereal launches under unified EFSA Novel Food compliance. The EU Green Deal's sustainable protein transition programs provide public R&D co-funding for plant-based reformulation. Cologne and Hamburg anchor the deepest procurement budgets for organic-certified concentrates with full traceability documentation.
Canada
Manitoba and Saskatchewan concentrate the global supply of mechanical-pressing expertise and temperature-controlled milling infrastructure. Health Canada's Cannabis Act framework oversees hemp processing with standardized THC thresholds that exceed FDA stringency. Winnipeg and Regina host extraction facilities serving both North American domestic demand and EU export qualification.
China
Shandong and Yunnan provinces expand hemp seed cultivation for protein meal export to European compound feed markets. The country's national food safety regulator maintains evolving standards for hemp-derived ingredients that lag EFSA harmonization progress. Qingdao processing clusters specialize in solvent-extracted commodity grades for price-sensitive Asian aquaculture feed formulations.
Australia
Queensland and New South Wales pilot hemp cultivation under state-level licensing frameworks preceding federal Novel Food determination. TGA oversight of therapeutic goods creates parallel compliance pathways for supplement-grade protein concentrates. Melbourne specialty food manufacturers test smoothie bowl applications through direct-to-consumer subscription models ahead of mainstream retail authorization.
Global Hemp Protein Market Competitive Landscape
Top-tier vendors anchor premium organic and cold-pressed segments, while mid-scale operators compete on commodity-grade volume and regional distribution density. The vendor base stratifies across three strategic archetypes: vertically integrated cultivator-processors controlling seed-to-shelf traceability, specialist superfood blenders extending hemp into format-diverse applications, and contract manufacturers serving private-label CPG houses. Capacity expansion and certification density represent the dominant competitive moves, with players racing to secure organic transition acreage and EFSA-compliant processing infrastructure.
Within the cultivator-processor archetype, Manitoba Harvest Hemp Foods and Nutiva exemplify supply-secured positioning through Canadian cultivation bases and organic certification density respectively. Navitas Organics occupies the superfood blender tier, extending hemp protein into smoothie and bowl applications beyond traditional powder formats. Victory Hemp Foods and Evo Hemp represent mid-scale US operators leveraging Farm Bill stability for backward integration into Kentucky and Montana cultivation clusters.
| Leading Market Players |
|---|
| Axiom Foods Inc. |
| Manitoba Harvest Hemp Foods |
| Martin Bauer Group |
| ETChem |
| Tilray Brands Inc. |
| Navitas Organics |
| Nutiva |
| Evo Hemp |
| Victory Hemp Foods |
| Others |
Supply & Pricing Matrix
Family-owned Canadian processor networks anchor supply discipline through multi-generational cultivation relationships that limit spot-market volatility and sustain premium-tier pricing power for organic-certified concentrates.
Pricing Analysis
The bundled certification-and-traceability service split separates cold-pressed organic concentrates from commodity solvent-extracted grades. Three-tier pricing structure across premium, standard, and economy levels tracks protein concentration thresholds and enzymatic preservation. Cost compression in commodity tiers is intensifying because Chinese solvent-extracted supply is expanding into European compound feed channels. Sports nutrition brands in Germany and California exhibit the lowest price sensitivity, while pet food compounders in Canada absorb economy-grade volumes with minimal specification flexibility.
Supply Chain Analysis
Dual-sourcing qualification requirements from EU CPG manufacturers mandate parallel Canadian and US supplier validation to mitigate THC threshold harmonization risks. Supply concentrates in Manitoba, Saskatchewan, and Kentucky cultivation clusters with downstream milling in Winnipeg and Regina. Hemp seed feedstock draws from Canadian and Chinese growing cycles with weather-dependent yield variability. Single-source vulnerability concentrates in mechanical-pressing technician expertise anchored to Prairie provinces. Distribution runs through bulk woven totes for food manufacturers and stand-up pouches for natural retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hemp protein offers margin-expansion runway as cold-pressed enzymatic preservation commands widening premiums over solvent-extracted commodity grades, with mechanical-pressing capacity scarcity protecting pricing power.
For Market Incumbents: Lock in organic transition acreage in Montana and Kentucky before three-year certification timelines delay supply responses. Secure EFSA-compliant processing infrastructure ahead of German and Dutch CPG formulation waves. Defend against mid-scale US operators leveraging Farm Bill stability by anchoring captive supply through backward integration into Prairie province cultivation clusters. For New Entrants and Emerging Players: The premium-to-economy price-point gap in bakery allergen-reduction applications offers white-space entry with partial wheat substitution formulations for German and Austrian retail channels. Target smoothie bowl superfood blending through direct-to-consumer subscription models ahead of mainstream café chain authorization. Pursue co-manufacturing partnerships with established Canadian processors to bypass extraction technician scarcity constraints. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale US operators with Kentucky and Montana cultivation footprints awaiting organic certification completion. Long-term viability hinges on EFSA Novel Food compliance infrastructure and cold-pressing technical depth. Target acquisition archetypes: Prairie province-based mechanical-pressing specialists with temperature-controlled milling expertise. The signal to watch is EU-wide retail reset velocity for hemp-fortified functional foods.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | Three-year transition timelines in Canadian and US acreage lock in clean-label supply security ahead of demand surges. |
| Cold-Press Capacity Expansion | Mechanical pressing below 45°C preserves lysine integrity for sports nutrition premium positioning in German and California markets. |
| EFSA Compliance Infrastructure | Novel Food authorization pathways enable unified EU distribution for Bavarian and Dutch bakery reformulation programs. |
| Superfood Format Diversification | Hemp-cacao-acai blending extends distribution through specialty café chains and direct-to-consumer subscription models. |
| Backward Integration into Cultivation | Farm Bill-stable Kentucky and Montana hemp farming anchors captive supply security for North American ingredient processors. |
Research Methodology
Bottom-up sports nutrition and functional foods modeling reconciled against top-down hemp seed cultivation and processing capacity tracking forms the analytical core of this study. Primary interviews with sports nutrition brand formulators, EFSA regulatory affairs consultants, Canadian hemp processor operations managers, German CPG procurement directors, and natural retail channel category buyers combined with secondary validation from Health Canada Cannabis Act filings, FDA GRAS notification databases, EFSA Novel Food catalogue entries, and EU customs trade data. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of cold-pressed versus solvent-extracted processing adoption, protein concentration tier migration, and certification density expansion informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type tier, application end-use, protein concentration grade, and regional regulatory cluster. CAGRs derive from curve-fitting against processed volume trajectories and value-per-kilogram tier shifts, with hemp seed input cost volatility and THC threshold harmonization progress as key industry-specific forecast inputs.
Caveats apply where EFSA enforcement consistency, FDA GRAS pathway finalization, or Canadian-Chinese cultivation cycle synchronization could materially shift the outlook. Forecasts reflect documented assumptions about regulatory clarity timelines and clean-label demand elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Krill Oil Market
Nutritional Supplements
Global Reishi Mushroom Extracts Market
Nutritional Supplements
Mood Support Supplements Market
Nutritional Supplements
Milk Thistle Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Fatty Acid Supplements Market
Nutritional Supplements
Nutraceutical Gummies Market
Nutritional Supplements
Spirulina Purple Blend Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
South America Nutraceuticals Market
Nutritional Supplements
Bone Broth Protein Powder Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Vegan Collagen Protein Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Global Soluble Dietary Fibers Market
Nutritional Supplements
Vitamins Gummies Market