
 Apo-8 Carotenal Market | 2026-2036
Apo-8 Carotenal Market Size, Share, and Industry Trends Forecast 2026-2036
Apo-8 Carotenal Market Analytics
Buyer concentration among food and beverage manufacturers is rebalancing as multinational processors consolidate their supplier bases while niche nutraceutical startups fragment procurement across specialty distributors. BASF SE leverages its integrated vitamin and carotenoid production complex in Ludwigshafen to secure feedstock advantages for high-purity Apo-8 carotenal. DSM Nutritional Products anchors its position through biotechnology-driven fermentation routes that reduce batch-to-batch color variance. Divis Laboratories competes on cost-engineered synthetic pathways serving Indian and Southeast Asian formulation houses.
Apo-8 carotenal is a C30 apocarotenoid aldehyde derived from oxidative cleavage of beta-carotene, characterized by a single terminal aldehyde group and strong orange-red chromophoric activity at wavelengths near 460-470 nm; manufacturers produce it via chemical synthesis or enzymatic extraction for use as a colorant and provitamin A precursor in fortified foods and animal feed. Synthetic grades still dominate volume shipments due to lower unit costs and tighter specification control, though natural-extraction volumes from microbial fermentation are gaining share in premium nutraceutical and clean-label cosmetic applications. Powder formulations occupy the largest share of commercial transactions because of superior shelf stability and ease of standardization in dry premix operations, while liquid concentrates command higher margins in beverage emulsion systems where rapid dispersion matters.
EFSA sets maximum permitted levels for Apo-8 carotenal in food categories through its food additive panel, while REACH governs chemical registration and purity disclosure for imports into the European Union; the FDA regulates color additive petitions and batch certification requirements for U.S. food and drug applications, creating divergent compliance pathways that shape regional sourcing strategies. Stakeholders must monitor evolving natural-claim definitions and tightening purity thresholds, as regulatory arbitrage between jurisdictions will determine which production technologies and form factors capture the next wave of commercial approvals.
Market Dynamics
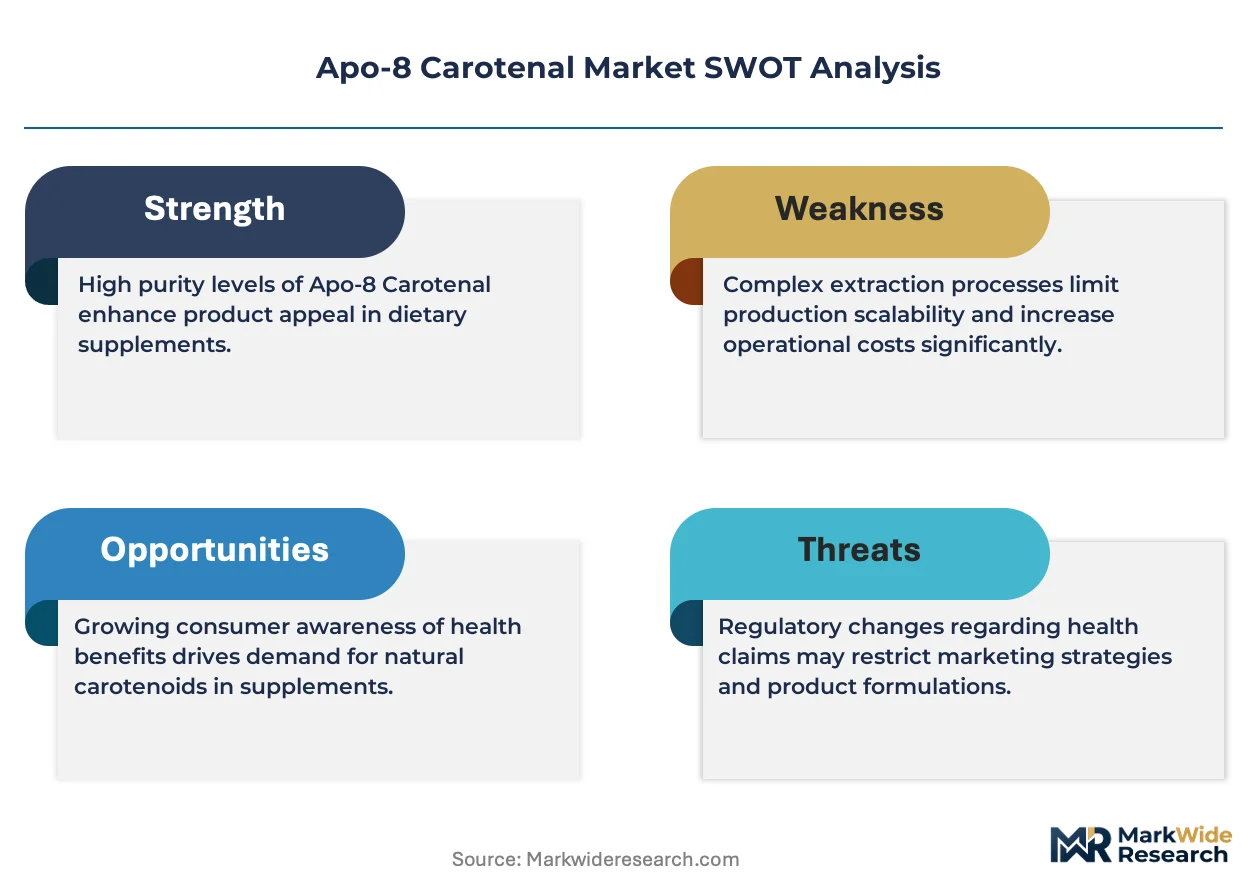
EFSA purity thresholds and REACH registration requirements are compressing supplier margins while simultaneously rewarding producers with integrated quality-assurance infrastructure, fundamentally restructuring competitive advantage around regulatory compliance capability rather than scale alone.
Growth Catalysts
- Clean-label beverage fortification:Dairy-alternative manufacturers in Germany and France are substituting synthetic azo dyes with Apo-8 carotenal to meet retailer natural-claim specifications without sacrificing shelf stability.
- REACH Article 33 disclosure mandates:Importers into the European Union must now document full supply-chain substance origins, creating preference pull toward vertically integrated producers with captive fermentation or synthesis capacity.
- Enzymatic extraction advancement:Lipase-mediated cleavage of beta-carotene is reducing solvent residue levels below 10 ppm, unlocking approval pathways for infant nutrition applications previously closed to synthetic grades.
Market Restraints
- Acetone and petrochemical feedstock volatility:Synthetic production routes depend on C1-C4 hydrocarbon derivatives whose price swings compress margin predictability for batch-scheduled manufacturers.
- Supplier concentration in the Rhine-Ruhr corridor:Three-quarters of European high-purity capacity clusters within 150 kilometers of Ludwigshafen, creating single-point-of-failure exposure for continental buyers.
- Natural astaxanthin substitution threat:Algae-derived alternatives with overlapping chromophoric profiles are capturing premium cosmetic and nutraceutical slots where color intensity requirements are less stringent.
Strategic Opportunities
- Indian formulation house expansion:Domestic nutraceutical contract manufacturers in Hyderabad and Ahmedabad are seeking qualified Apo-8 carotenal suppliers to serve export markets with FSSAI-plus-REACH dual certification.
- Precision fermentation scale-up:Microbial cell-factory platforms utilizing Yarrowia lipolytica are approaching cost parity with chemical synthesis for 99%+ purity grades, opening clean-label positioning at mid-market price points.
- Beverage emulsion system integration:Liquid concentrate formats with built-in dispersant packages are penetrating ready-to-drink fortified water channels previously dominated by powder premix supply.
Industry Challenges
- Dual-use export control navigation:Apo-8 carotenal's structural similarity to retinal intermediates triggers enhanced due diligence under EU dual-use regulation 2021/821, lengthening customs clearance timelines for non-EU destinations.
- Analytical method harmonization gaps:Discrepancies between HPLC and spectrophotometric assay protocols across EFSA, FDA, and FSSAI create lot-release disputes requiring redundant third-party verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apo-8 Carotenal Market |
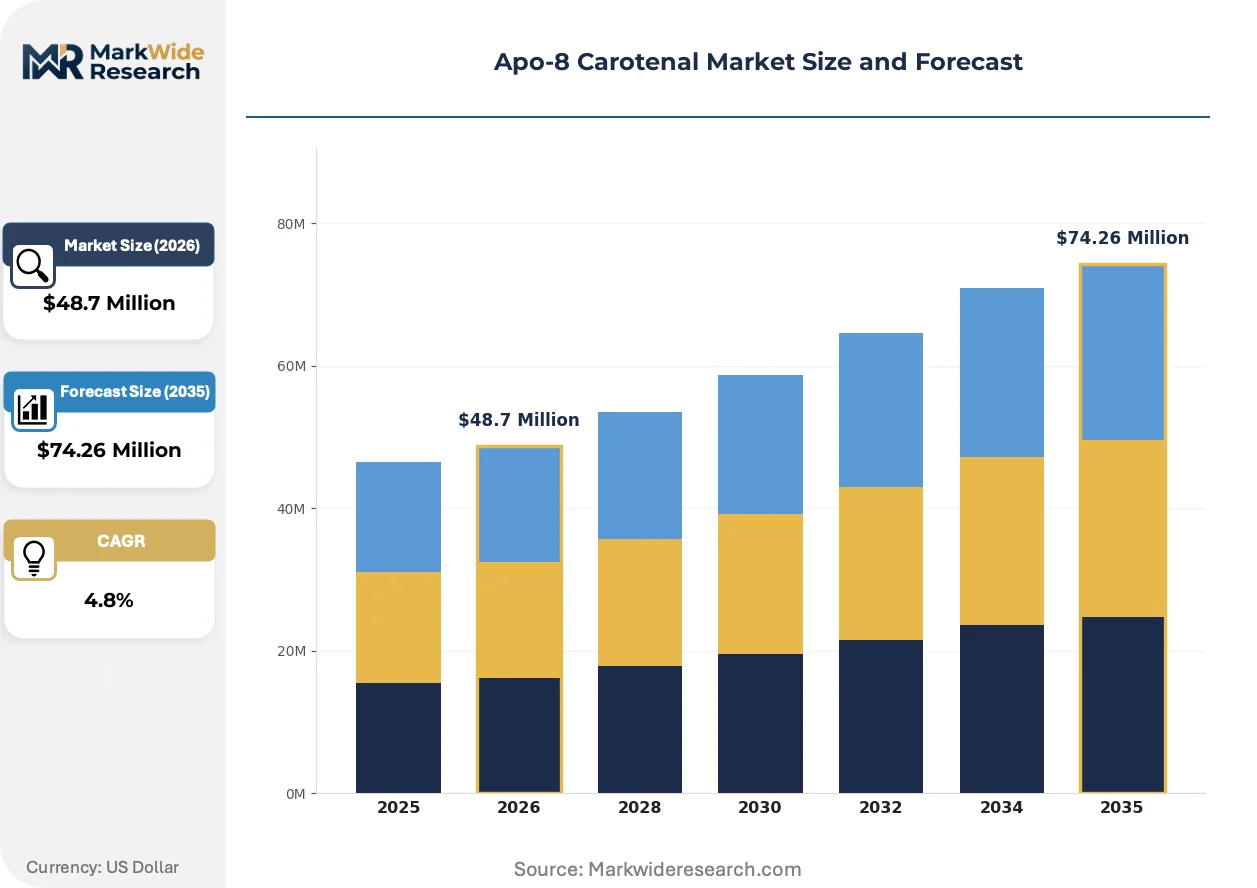
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $74.26 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Non-Organic Application: Food & Beverage, Nutraceuticals, Cosmetics, Pharmaceuticals End User: Manufacturers, Retailers, Distributors, Healthcare Providers Form: Powder, Liquid, Granules, Capsules |
| Companies Covered | Divis Laboratories, BASF SE, DSM Nutritional Products, Allied Biotech, Dhler Group, Sensient Technologies Corporation, D.D. Williamson & Co., Valensa International, Kanegrade Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apo-8 Carotenal Market Evolving Landscape
Production technology convergence with synthetic biology is displacing traditional chemical synthesis as the dominant innovation vector, while regulatory disclosure requirements and buyer procurement centralization reshape how value flows through distribution channels.
Precision fermentation utilizing metabolically engineered yeasts is expanding into commercial-scale Apo-8 carotenal production, with pilot facilities in the Netherlands and Denmark now achieving titers above 5 grams per liter. Nutraceutical contract manufacturers are qualifying these fermentation-derived grades for premium positioning, bypassing the petrochemical origin objections that constrain synthetic material in clean-label channels. This technology shift is compressing the historical price premium between natural-extraction and synthetic grades from 40-60% toward 15-25%.
REACH Annex XVII restrictions on residual solvent content are tightening maximum permissible levels for dichloromethane and hexane in colorant imports, forcing reformulation of extraction protocols across Asian toll manufacturers. The industrial consequence is accelerated capital deployment toward supercritical CO2 extraction infrastructure, particularly among suppliers serving German and Dutch ingredient houses. Powder-grade shipments from non-EU origins are experiencing extended batch-release timelines as ECHA-registered laboratories clear backlogs for updated impurity profiling.
Buyer consortiums among mid-sized beverage processors are consolidating procurement volumes to secure long-term offtake agreements with tier-one producers, displacing the fragmented spot-market purchasing that dominated 2018-2023. This concentration is compressing distributor margins and forcing specialty chemical traders to pivot toward technical service bundling rather than pure arbitrage. The Netherlands and Belgium host the most visible examples, where cooperative buying groups now represent 30-40% of regional volume.
Apo-8 Carotenal Market Segmentation
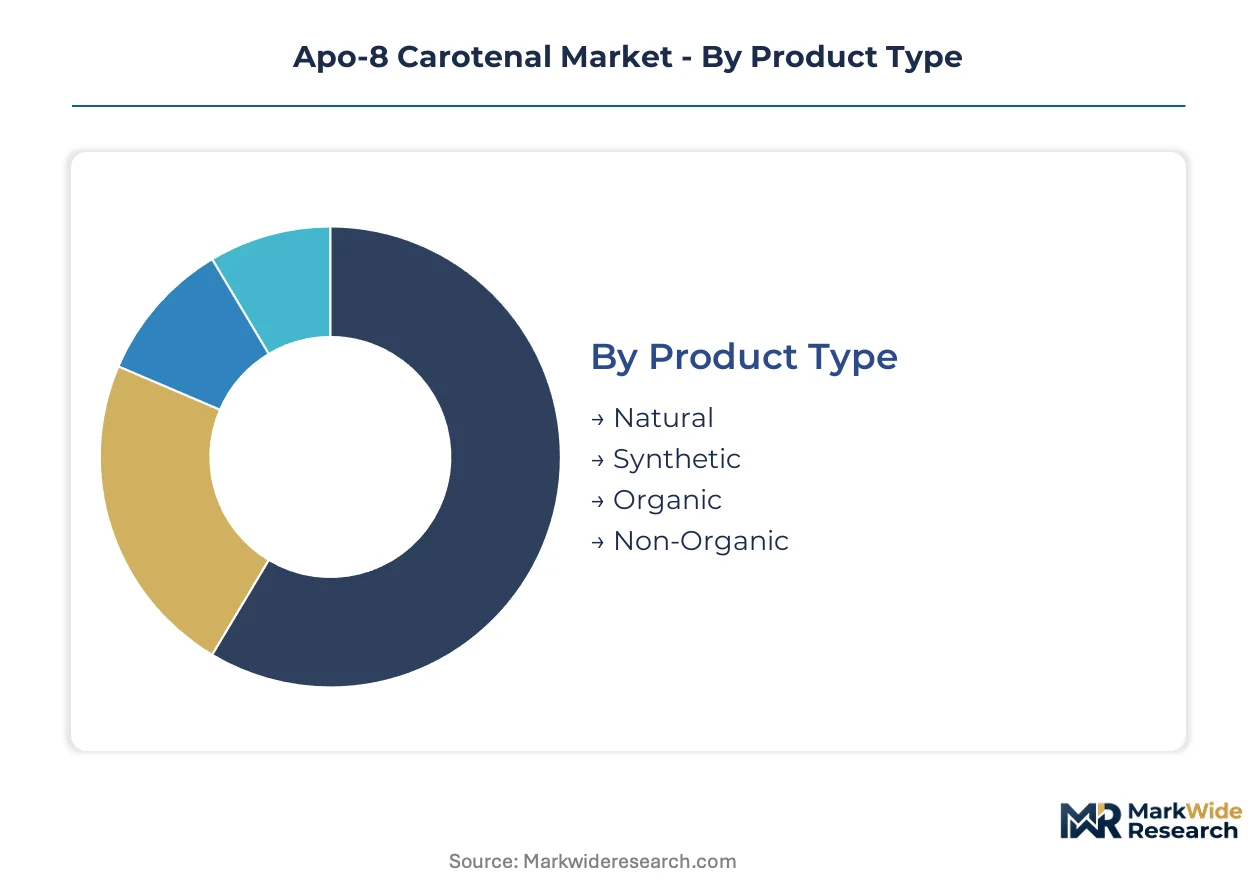
Segmentation in the Apo-8 carotenal market reveals how purity grades, regulatory pathways, and formulation requirements split procurement decisions across end-use verticals. Buyers prioritize different specifications based on whether their application faces EFSA scrutiny, clean-label mandates, or cost-engineered volume targets.
Product Type:
Cost tier determines supplier qualification thresholds and margin structure for procurement teams evaluating feedstock origins.
- Synthetic:Manufactured via oxidative cleavage of beta-carotene using petrochemical-derived precursors, achieving batch-to-batch color consistency within ±2% variance. Food and beverage manufacturers in Germany rely on synthetic grades for fortified dairy alternatives where REACH registration and EFSA purity documentation are mandatory, though acetone feedstock volatility compresses margin predictability.
- Natural:Derived from microbial fermentation using metabolically engineered Yarrowia lipolytica or enzymatic extraction from plant matrices, with residual solvent levels below 10 ppm unlocking infant nutrition approvals. Nutraceutical contract manufacturers in the Netherlands and Denmark are qualifying fermentation-derived natural grades for premium positioning where clean-label claims command price premiums.
- Organic:Sourced from certified organic feedstocks with full supply-chain traceability meeting EU organic regulation 2018/848.
- Non-Organic:Conventional cultivation and synthesis routes without organic certification burden, serving cost-sensitive formulation houses.
Synthetic leads on scale; natural leads on momentum.
Application:
Application focus shapes whether buyers prioritize color stability, bioavailability documentation, or cosmetic-grade solubility.
- Food & Beverage:Dominates commercial volume through use in fortified beverages, dairy alternatives, and confectionery where orange-red chromophoric activity at 460-470 nm replaces synthetic azo dyes. German retailers are driving substitution mandates that favor Apo-8 carotenal over tartrazine in clean-label product lines.
- Nutraceuticals:Provitamin A precursor applications in dietary supplements require bioavailability studies and stability data under ICH guidelines. Fermentation-derived grades are gaining share fastest in this channel as contract manufacturers seek dual FSSAI-plus-REACH certification for export markets.
- Cosmetics:Colorant applications in skincare and personal care products demand micronized particle sizes and emulsion compatibility.
- Pharmaceuticals:Active pharmaceutical ingredient and excipient uses face the most stringent purity thresholds and analytical method harmonization requirements across FDA, EMA, and national regulators.
Food and beverage dominates volume concentration; nutraceuticals show the steepest expansion trajectory.
End User:
Customer type determines whether procurement emphasizes technical service bundling, spot-market flexibility, or long-term offtake security.
- Manufacturers:Integrated food, beverage, and supplement producers with captive formulation capabilities and direct supplier relationships. Mid-sized beverage processors in the Netherlands and Belgium are consolidating into cooperative buying groups representing 30-40% of regional volume.
- Retailers:Private-label brand owners and supermarket chains setting clean-label specifications that cascade down to ingredient suppliers.
- Distributors:Specialty chemical traders pivoting from pure arbitrage toward technical service bundling as buyer consolidation compresses margins.
- Healthcare Providers:Hospital systems and clinical nutrition services with specialized requirements for pharmaceutical-grade material.
Manufacturers command procurement scale; distributors face the most acute margin pressure.
Form:
Form factor selection trades shelf stability against dispersion speed in target formulation systems.
- Powder:Spray-dried or crystalline formats with superior shelf stability and standardization ease in dry premix operations. Powder formulations occupy the largest share of commercial transactions due to compatibility with bulk handling infrastructure at ingredient houses.
- Liquid:Oil-based or emulsion concentrates with built-in dispersant packages for rapid incorporation into beverage systems. Liquid concentrates command higher margins in ready-to-drink fortified water channels where rapid dispersion matters more than storage efficiency.
- Granules:Agglomerated formats balancing flowability with reduced dusting for intermediate handling steps.
- Capsules:Pre-metered unit doses serving direct-to-consumer supplement brands and clinical trial supply.
Powder leads on transaction volume; liquid leads on margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the highest concentration of high-purity Apo-8 carotenal capacity in Europe, while India is emerging as the fastest-growing demand center for cost-engineered synthetic grades serving export formulation houses.
Germany
Food and beverage manufacturers in the Rhine-Ruhr corridor drive demand for REACH-registered synthetic grades in dairy-alternative fortification. EFSA purity thresholds under Regulation (EC) No 1333/2008 govern maximum permitted levels in food categories. Ludwigshafen anchors integrated vitamin and carotenoid production complexes serving continental European ingredient houses.
Netherlands
Nutraceutical contract manufacturers in Rotterdam and Utrecht seek fermentation-derived natural grades for premium clean-label positioning. ECHA registration requirements under REACH Article 33 mandate full supply-chain substance origin disclosure. Pilot facilities near Delft achieve commercial-scale precision fermentation titers above 5 grams per liter.
India
Domestic formulation houses in Hyderabad and Ahmedabad expand procurement of dual FSSAI-plus-REACH certified material for export markets. FSSAI standards under the Food Safety and Standards Act, 2006, align with international purity benchmarks for dietary supplement applications. Cost-engineered synthetic pathways from Divis Laboratories serve Southeast Asian contract manufacturers.
United States
Beverage processors in the Midwest and California substitute synthetic azo dyes with Apo-8 carotenal for clean-label retail specifications. FDA color additive petitions and batch certification requirements under 21 CFR 73 govern food and drug applications. Chicago-area ingredient distributors consolidate procurement volumes into cooperative buying groups.
Denmark
Biotechnology-driven fermentation specialists near Copenhagen scale Yarrowia lipolytica cell-factory platforms for 99%+ purity grades. Danish Veterinary and Food Administration regulations implement EU food additive directives with supplementary national purity protocols. Odense-area facilities approach cost parity with chemical synthesis for mid-market clean-label positioning.
Apo-8 Carotenal Market Competitive Landscape
German producers anchor one tier through integrated petrochemical-derived synthesis complexes; Indian specialists hold a parallel tier through cost-engineered batch manufacturing. The vendor base splits between consolidated multinational chemical conglomerates with captive feedstock advantages and fragmented regional distributors pivoting toward technical service bundling. Three strategic archetypes dominate: vertically integrated synthesis majors, precision fermentation biotechs, and toll-manufacturing intermediaries. Capacity expansion and regulatory certification stacking constitute the dominant competitive moves as buyers consolidate supplier bases.
Within the integrated synthesis tier, BASF SE exemplifies the Rhine-Ruhr production cluster model, while DSM Nutritional Products occupies a position bridging biotechnology and nutritional ingredient supply. Divis Laboratories represents the cost-engineered synthetic pathway archetype serving price-sensitive formulation markets. These three anchors illustrate how geographic concentration and production technology choices stratify competitive positioning across purity grades and regulatory compliance tiers.
| Leading Market Players |
|---|
| Divis Laboratories |
| BASF SE |
| DSM Nutritional Products |
| Allied Biotech |
| Dhler Group |
| Sensient Technologies Corporation |
| D.D. Williamson & Co. |
| Valensa International |
| Kanegrade Ltd. |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII solvent restrictions gate qualified supply for premium-tier pricing access, compressing margins for non-compliant Asian toll manufacturers while rewarding European producers with supercritical CO2 infrastructure. German beverage processors now pay 15-25% premiums for ECHA-registered fermentation grades that bypass petrochemical origin objections in clean-label channels.
Pricing Analysis
Capacity additions in Denmark and the Netherlands are reshaping price floors for natural-extraction grades, eroding the historical 40-60% premium over synthetic material. Contract-based long-term offtake agreements dominate procurement among Dutch cooperative buying groups, with price differentiation driven by REACH certification tier and volume scale. Cost compression in synthetic routes is intensifying because acetone feedstock volatility, while Indian formulation houses remain most price-sensitive and German nutraceutical contract manufacturers least.
Supply Chain Analysis
Dual-sourcing mandates from EFSA-regulated food manufacturers require qualification of at least two REACH-registered suppliers per production site, lengthening procurement cycles. Supply concentrates in Germany, India, and the Netherlands, with raw material dependencies spanning beta-carotene feedstock, C1-C4 hydrocarbon derivatives, and lipase enzymes. Single-source vulnerability runs through the Rhine-Ruhr corridor where three-quarters of European high-purity capacity clusters within 150 kilometers of Ludwigshafen. Distribution runs through specialty chemical traders pivoting toward technical service bundling as buyer consolidation compresses arbitrage margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Apo-8 carotenal market reads as a late-cycle quality story, with German retailer clean-label mandates shifting procurement toward fermentation-derived grades with full supply-chain traceability.
For Market Incumbents: Extend ECHA registration coverage into infant nutrition grades before enzymatic extraction rivals achieve cost parity, and secure captive beta-carotene supply through backward integration into fermentation feedstock production. Natural astaxanthin substitution threats from algae-derived alternatives demand accelerated R&D in color stability formulations for beverage emulsion systems. For New Entrants and Emerging Players: Precision fermentation platforms utilizing Yarrowia lipolytica offer the most penetrable wedge for mid-market clean-label positioning, targeting Indian formulation houses in Hyderabad and Ahmedabad seeking dual FSSAI-plus-REACH certification for export markets. A technology-first go-to-market angle emphasizing sub-10 ppm solvent residues unlocks previously closed infant nutrition applications. For Investors and Strategic Acquirers: Roll-up economics work for precision fermentation biotechs because EFSA purity thresholds and REACH disclosure mandates are simultaneously compressing commodity synthetic margins and rewarding integrated quality-assurance infrastructure. Acquisition targets should demonstrate commercial-scale titers above 5 grams per liter with qualified offtake agreements from Dutch or Belgian cooperative buying groups. The signal to watch is batch-release timeline compression at ECHA-registered laboratories as a leading indicator of supply-constraint resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Yarrowia lipolytica platforms approaching cost parity with chemical synthesis unlock mid-market clean-label positioning. |
| REACH Certification Investment | ECHA registration under Article 33 mandates full supply-chain disclosure, favoring vertically integrated producers. |
| Backward Integration into Feedstock | Captive beta-carotene supply secures margin predictability against petrochemical derivative volatility. |
| Supercritical CO2 Extraction Deployment | Non-solvent infrastructure meets tightening Annex XVII residual limits for dichloromethane and hexane. |
| Long-Term Offtake Agreements | Cooperative buying groups in the Netherlands and Belgium consolidate 30-40% of regional volume into contract structures. |
Research Methodology
Bottom-up food and beverage modeling reconciled against top-down fermentation capacity tracking forms the analytical core, combining primary interviews with procurement leads at German dairy-alternative manufacturers, regulatory affairs directors at Dutch nutraceutical contract manufacturers, and technical R&D heads at Indian formulation houses with secondary validation from EFSA food additive panel opinions, ECHA registration databases, and FSSAI purity standard notifications. Customs data on beta-carotene derivative trade flows and SEC filings from listed ingredient suppliers provide supply-side triangulation.
Historical trendline analysis across synthetic and natural production routes establishes baseline price convergence patterns, with segmentation dimensions spanning grade tier, application vertical, form factor, and regional regulatory cluster. CAGRs derive from elasticity-adjusted volume projections tied to clean-label substitution rates in beverage fortification and infant nutrition approval expansion, incorporating fermentation titer improvement curves and REACH compliance cost trajectories as industry-specific forecast inputs.
The model holds under stable EFSA purity threshold enforcement and REACH registration continuity; deviation in acetone feedstock pricing volatility or accelerated natural astaxanthin substitution would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Aquatic Feed Supplement Market
Nutritional Supplements
Asia-Pacific Beta-Glucan Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Pet Dietary Supplements Market
Nutritional Supplements
Global Egg Protein Market
Nutritional Supplements
Insoluble Dietary Fibers Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
DHA Oil Supplement Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Global Antioxidant Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Older Adults Health Supplements Market