
 Asia-Pacific Beta-Glucan Market | 2026-2036
Asia-Pacific Beta-Glucan Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Beta-Glucan Market Analysis
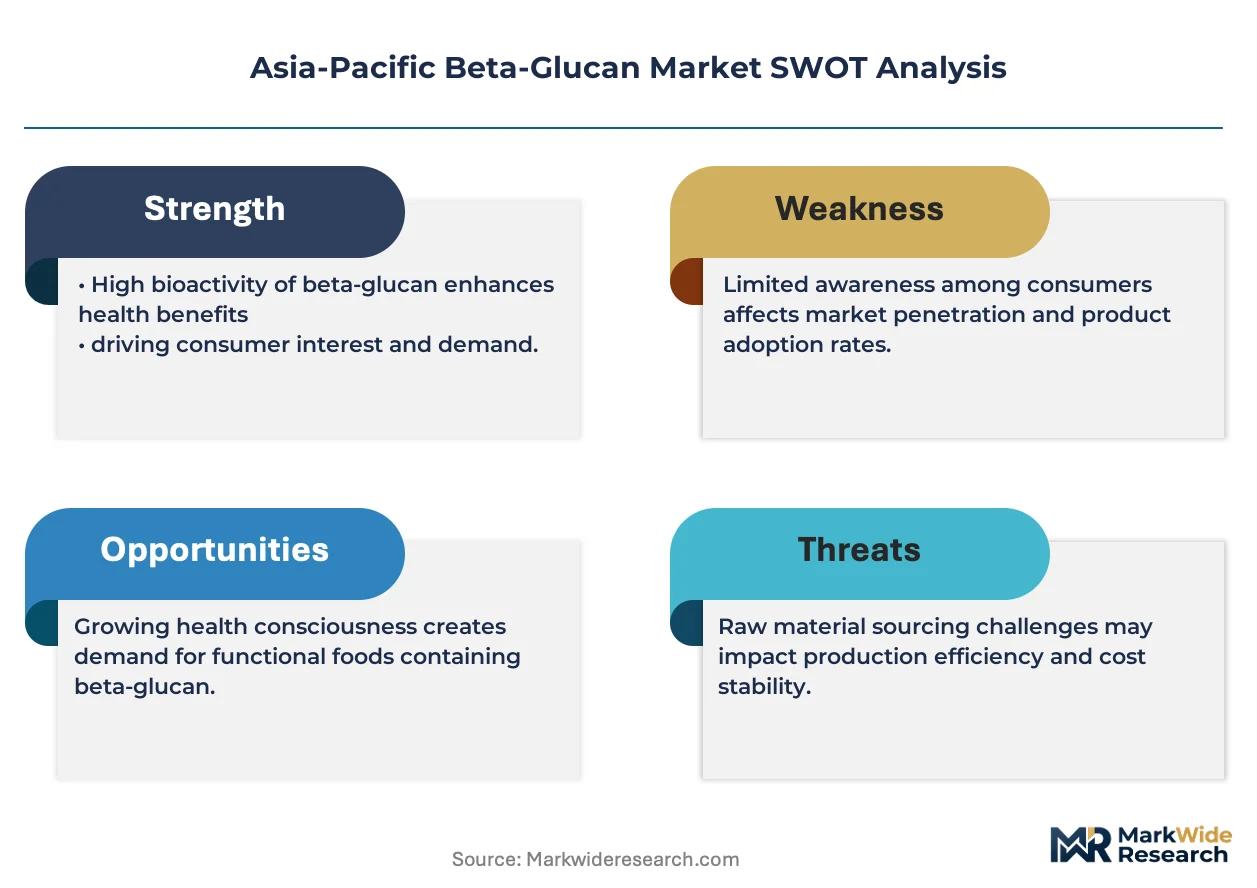
Pharmaceutical-grade specification tiers is bifurcating the competitive landscape as buyers demand validated immunomodulatory assays. Kerry Group leverages its enzyme technology platform to sustain high-purity extraction yields across Asian contract manufacturing networks. Angel Yeast Co. Ltd anchors regional supply through captive fermentation capacity in Hubei province. Koninklijke DSM N.V. differentiates via yeast beta-glucan strains qualified for EU novel food equivalence, extending its regulatory footprint into Australian and Japanese markets.
Beta-glucan comprises glucose polymers linked by beta-glycosidic bonds, typically extracted through aqueous alkaline or enzymatic methods from yeast cell walls, oat bran, or fungal mycelia, with molecular weight and branching ratio determining solubility and immunological activity. These specifications govern its primary function as a dietary fiber or biological response modifier in formulated consumer products. Powder formulations dominate volume throughput due to stability in dry-blend nutraceutical operations, while immune support applications command premium positioning over digestive health segments where commodity oat sources compete on cost. Yeast-derived material leads value pools given higher beta-1,3/1,6 branching content associated with macrophage activation claims.
FSSAI in India enforces purity thresholds for beta-glucan labeled as a nutraceutical ingredient, while TGA in Australia mandates therapeutic claim substantiation through clinical evidence packages. China's NMPA novel food registration pathway shapes market access timelines for imported yeast extracts. Stakeholders must monitor evolving immunomodulatory claim frameworks across Asia-Pacific jurisdictions to align product positioning with permissible health benefit communications.
Market Dynamics
Yeast-derived beta-glucan extraction technology is concentrating supply advantages among fermentation-capable producers, while regulatory divergence across Asia-Pacific jurisdictions fragments market access pathways and compels multi-track compliance investments.
Growth Catalysts
- NMPA novel food streamlining:China's National Health Commission has accelerated yeast beta-glucan approval timelines, reducing market entry barriers for imported ingredients and stimulating domestic formulation activity.
- Functional food fortification:Japanese nutraceutical manufacturers are embedding beta-glucan into beverage and dairy applications, expanding addressable consumption occasions beyond traditional supplement formats.
- Pharmaceutical-grade assay validation:Immunomodulatory bioassay standardization is enabling therapeutic claim substantiation, opening premium positioning channels previously restricted to commodity fiber applications.
Market Restraints
- Input cost volatility:Yeast biomass feedstock prices fluctuate with brewing industry output cycles, compressing margin stability for non-integrated extractors.
- Supply concentration risk:Hubei province fermentation capacity anchors regional yeast beta-glucan output, creating geographic single-point vulnerability for Asia-Pacific formulation networks.
- Regulatory friction:TGA therapeutic claim requirements demand clinical evidence packages that smaller nutraceutical brands cannot resource, segmenting market participation by compliance capital.
Strategic Opportunities
- India nutraceutical manufacturing:FSSAI purity threshold enforcement is professionalizing ingredient sourcing standards, creating first-mover advantage for certified yeast beta-glucan suppliers establishing local technical service presence.
- Clean-label convergence:Enzymatic extraction methods paired with non-GMO yeast strains satisfy dual demand vectors in Australian and Japanese premium consumer segments.
- Veterinary immunomodulation:Aquaculture and companion animal health applications remain underdeveloped relative to human nutrition, offering volume expansion with lower regulatory complexity.
Industry Challenges
- Bioassay standardization gaps:Macrophage activation assay protocols vary across contract laboratories, complicating batch-to-batch consistency documentation for pharmaceutical-grade specifications.
- Capex intensity:Captive fermentation capacity requires eight-figure infrastructure commitments that exclude mid-scale entrants from yeast-derived supply positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Beta-Glucan Market |
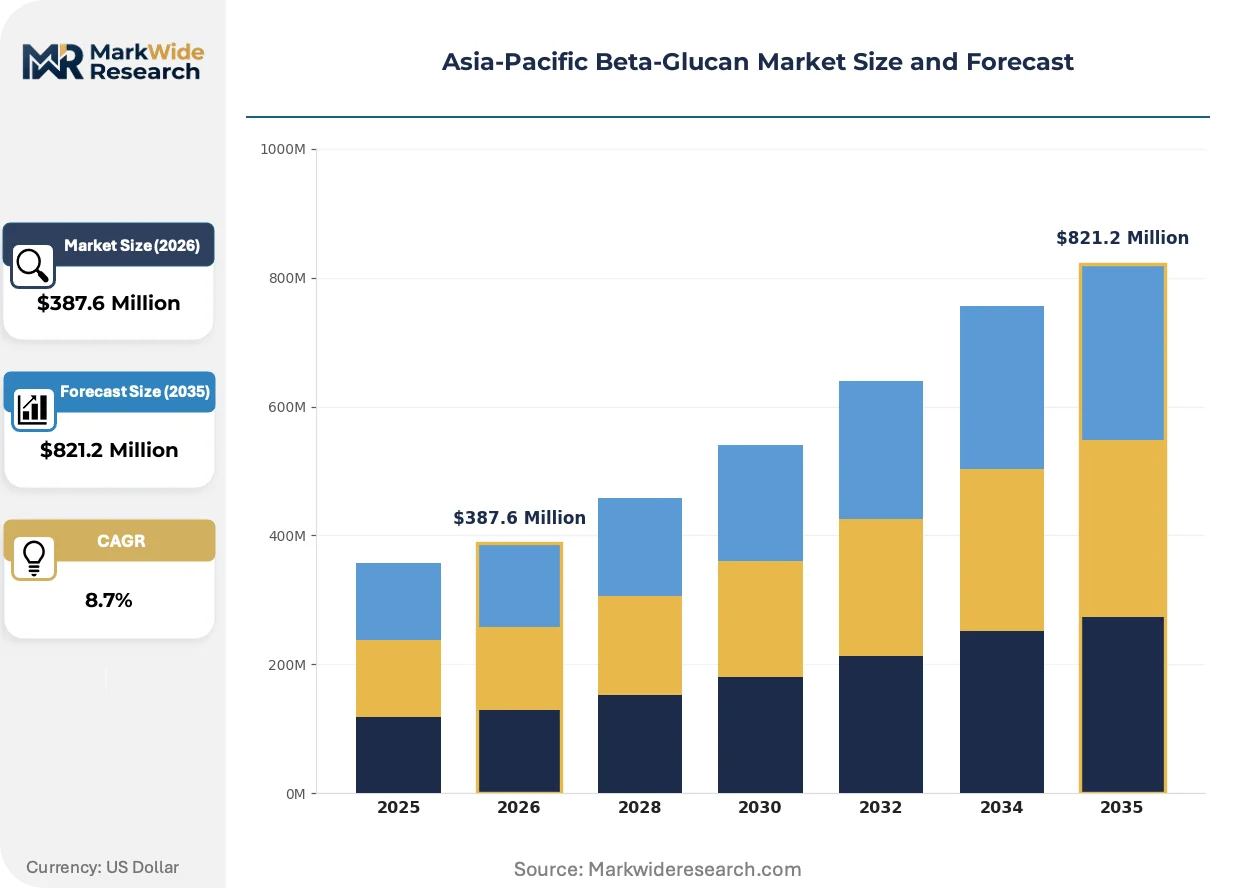
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granules, Capsules End User: Food & Beverages, Pharmaceuticals, Nutraceuticals, Cosmetics Source: Yeast, Mushroom, Oats, Barley Application: Immune Support, Digestive Health, Weight Management, Skin Care |
| Companies Covered | Tate & Lyle PLC, Kerry Group, Koninklijke DSM N.V., Associated British Foods Plc, Kemin Industries, Angel Yeast Co. Ltd, Lesaffre, Biotec Pharmacon ASA, Ceapro Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Beta-Glucan Market Emerging Trajectories
Enzymatic extraction protocols are supplanting traditional alkaline methods across Asia-Pacific production networks, driven by yield optimization pressures and clean-label positioning requirements in premium consumer segments.
Enzymatic cell-wall disruption preserves beta-1,3/1,6 branching integrity while reducing solvent residue burdens. Australian and Japanese formulators have adopted this technology fastest, prioritizing EU novel food equivalence qualifications. This transition is supplanting established aqueous alkaline extraction infrastructure, forcing contract manufacturers to retool or exit pharmaceutical-grade supply tiers.
China's NMPA has harmonized yeast beta-glucan novel food registration with SAMR food safety oversight, consolidating previously fragmented approval pathways. This regulatory compression accelerates import clearance timelines but demands simultaneous GB standards compliance testing. Japanese and Australian suppliers with pre-qualified strains capture first-mover positioning in reformulated functional food launches.
Ingredient buyers are consolidating supplier relationships around vertically integrated fermentation operators capable of delivering batch-specific bioactivity certificates. This procurement concentration displaces spot-market purchasing in India's nutraceutical manufacturing hubs. The shift is most visible among Mumbai and Hyderabad formulation houses serving export markets with TGA-registered finished products.
Asia-Pacific Beta-Glucan Market Segmentation
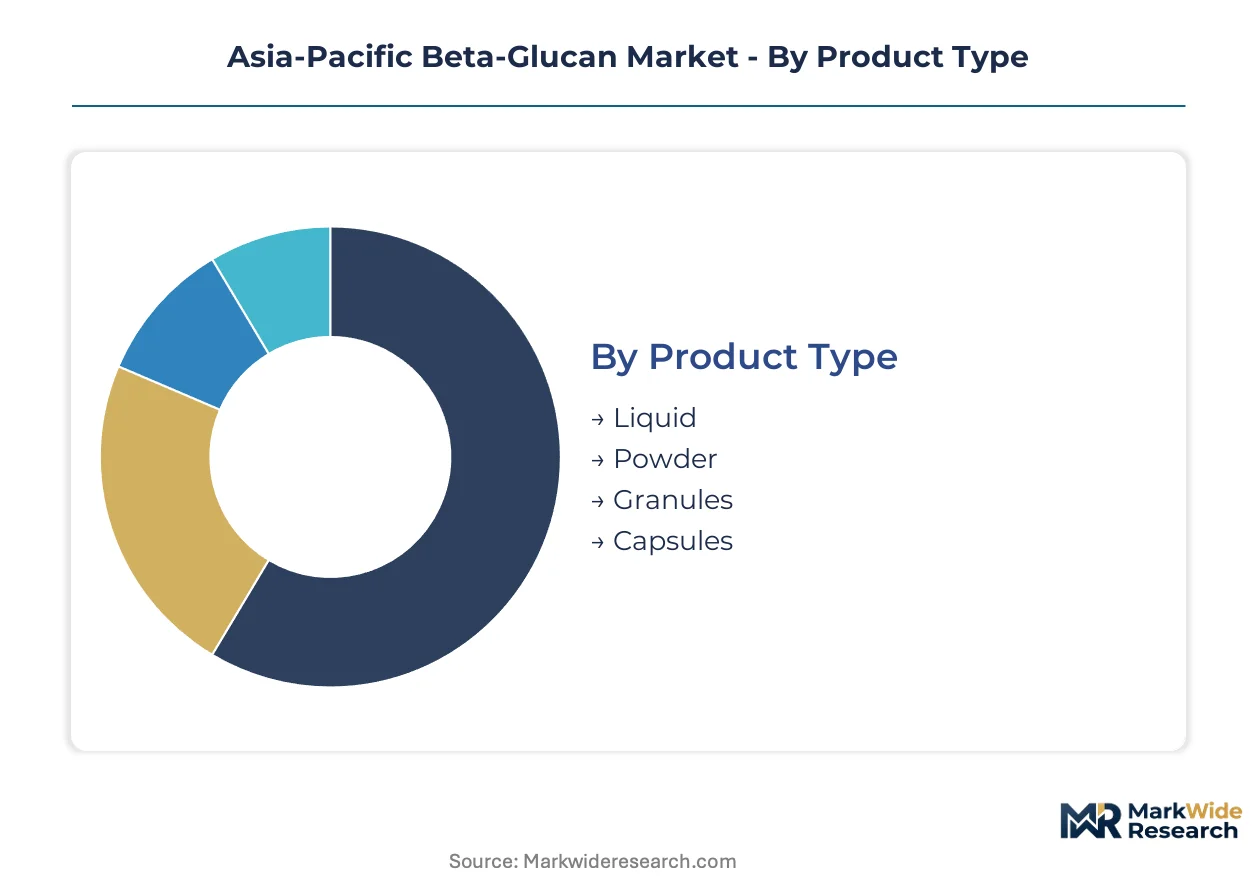
Beta-glucan specifications vary dramatically across molecular weight, branching patterns, and purity grades, creating distinct channel economics for each segment. Manufacturers must align formulation choices with end-use claim substantiation requirements and regional regulatory pathways.
Product Type:
Powder formulations dominate dry-blend nutraceutical operations through Mumbai and Hyderabad contract manufacturers, while liquid concentrates penetrate Japanese functional beverage channels where dissolution speed determines processing economics.
- Powder:Dry-blend stability and extended shelf life make this the default specification for Indian nutraceutical export houses and Chinese pharmaceutical clusters. FSSAI purity thresholds favor powder for certified ingredient sourcing in Mumbai formulation networks.
- Liquid:Beverage fortification applications in Japan and Australia demand hydrocolloid-stabilized concentrates with rapid dispersion characteristics. Enzymatic extraction methods preserve branching integrity in these higher-moisture formats.
- Granules:Intermediate flow properties suit tableting operations in South Korean supplement manufacturing.
- Capsules:Pre-metered dosing appeals to premium positioning in Australian pharmacy channels.
By volume, Powder leads. By growth pace, Liquid is ahead.
End User:
Cost tiers separate commodity fiber applications from validated immunomodulatory positioning, with pharmaceutical-grade specifications commanding manufacturing complexity premiums.
- Pharmaceuticals:TGA therapeutic claim requirements and NMPA novel food registrations demand batch-specific bioactivity certificates. Yeast-derived material with validated macrophage activation assays captures this premium tier in Australian and Japanese markets.
- Nutraceuticals:India's FSSAI enforcement is professionalizing sourcing standards, creating certified supplier advantages for Mumbai and Hyderabad formulation houses serving export markets.
- Food & Beverages:Japanese manufacturers embed beta-glucan into dairy and beverage applications, expanding consumption occasions beyond traditional supplement formats.
- Cosmetics:Skin barrier claims in South Korean personal care formulations utilize lower-molecular-weight fractions with topical bioavailability characteristics.
Pharmaceuticals command the steepest margin tier. Food & Beverages shows the broadest volume base.
Source:
Supply concentration in Hubei province fermentation capacity anchors yeast-derived output, while oat sourcing competes on cost in digestive health applications.
- Yeast:Beta-1,3/1,6 branching content drives macrophage activation claims. Angel Yeast's captive fermentation in Hubei province supplies regional formulation networks, though geographic concentration creates single-point vulnerability.
- Oats:Commodity pricing suits fiber-positioned digestive health products where immunomodulatory claims are not pursued. Australian and Japanese clean-label segments favor non-GMO oat sources.
- Mushroom:Traditional medicine positioning in Chinese and Japanese markets leverages lentinan and related beta-glucan fractions from Lentinula edodes mycelia.
- Barley:Brewing industry byproduct streams offer cost-competitive beta-glucan for bulk fiber fortification in price-sensitive Indian nutraceutical applications.
Yeast dominates value pools. Mushroom fractions are climbing fastest in premium positioning.
Application:
Customer type stratification separates clinical evidence-backed therapeutic positioning from wellness-oriented preventive consumption.
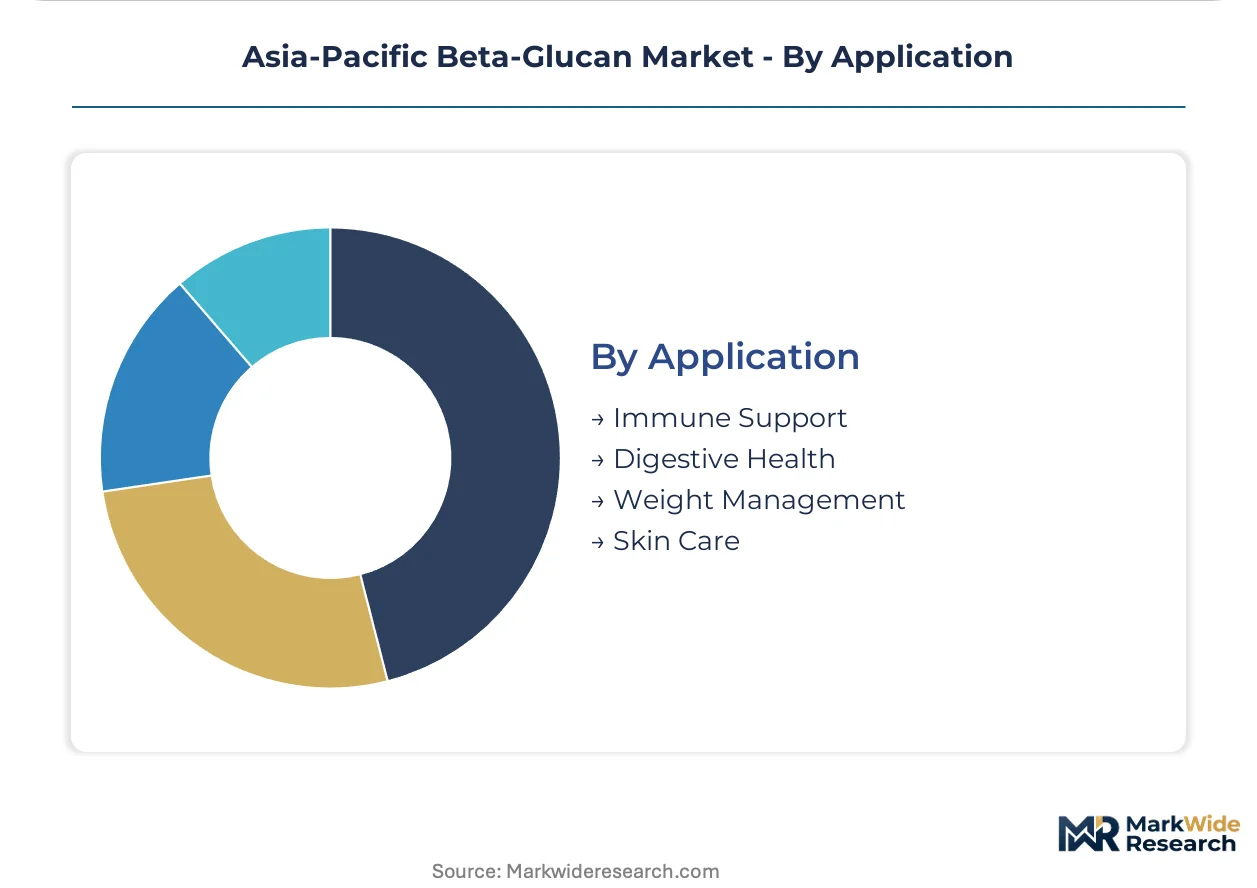
- Immune Support:Macrophage activation bioassays enable premium pricing in pharmaceutical and high-end nutraceutical channels. Kerry Group's enzyme technology platform sustains high-purity extraction yields for this specification tier.
- Digestive Health:Commodity oat and barley sources compete on cost in fiber-positioned applications with lower regulatory complexity and reduced claim substantiation requirements.
- Weight Management:Viscosity and satiety mechanisms drive formulation in Japanese functional foods and Australian meal-replacement products.
- Skin Care:Topical beta-glucan in South Korean cosmetics leverages moisture-retention and barrier-repair claims with distinct molecular weight specifications from oral applications.
Immune Support leads revenue concentration. Skin Care is expanding most quickly in regional personal care innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific's beta-glucan trade flows reflect a structural import dependency for pharmaceutical-grade material, with regional formulation hubs in India and Japan drawing heavily on Chinese fermentation output while domestic regulators tighten traceability mandates.
China
NMPA's novel food streamlining has compressed approval timelines for yeast-derived imports, triggering domestic capacity expansion in Hubei province's fermentation corridors. SAMR's consolidated oversight now demands simultaneous GB standards compliance, favoring suppliers with pre-qualified strains. Yangtze River Delta pharmaceutical clusters absorb the bulk of high-purity output for export-oriented formulation.
Japan
METI's functional food labeling framework incentivizes beta-glucan fortification across beverage and dairy channels, extending consumption occasions beyond traditional supplements. PMDA's therapeutic claim pathways remain stringent, segmenting the market between quasi-drug positioning and general wellness applications. Kanto region manufacturers lead enzymatic extraction adoption for clean-label product lines.
India
FSSAI's purity threshold enforcement is professionalizing sourcing standards across Mumbai and Hyderabad nutraceutical export houses. CDSCO's evolving novel food stance creates regulatory ambiguity for imported yeast extracts, delaying some launch timelines. Maharashtra's formulation corridors increasingly specify certified suppliers with local technical service presence.
Australia
TGA's therapeutic claim substantiation requirements demand clinical evidence packages that segment market participation by compliance capital. Clean-label demand in premium consumer segments favors enzymatic extraction methods paired with non-GMO verification. Sydney and Melbourne formulation networks serve as gateways for EU novel food-qualified material into Southeast Asian markets.
South Korea
MFDS regulates beta-glucan within functional food and cosmetic frameworks, with distinct molecular weight specifications governing oral versus topical applications. Seoul-based personal care manufacturers drive demand for lower-molecular-weight fractions with barrier-repair claims. Domestic supplement producers rely on imported pharmaceutical-grade material for immune positioning.
Asia-Pacific Beta-Glucan Market Vendor Landscape
Concentration sits with fermentation-capable producers commanding captive yeast biomass supply and validated bioassay documentation. The competitive landscape bifurcates between integrated extraction specialists and formulation-focused ingredient distributors. Three archetypes dominate: vertically integrated fermentation operators, enzyme technology licensors, and regional trading houses with regulatory navigation capabilities. Capacity expansion and portfolio diversification toward pharmaceutical-grade specifications represent the dominant competitive vectors.
Within the integrated fermentation tier, Angel Yeast Co. Ltd exemplifies geographic supply anchoring through Hubei province infrastructure. Kerry Group occupies a position bridging enzyme technology platforms with Asian contract manufacturing networks. Koninklijke DSM N.V. represents regulatory qualification leadership, with yeast strains holding EU novel food equivalence extending into Australian and Japanese market access. These three entities collectively illustrate the capability thresholds separating premium-tier suppliers from commodity-positioned competitors.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Kerry Group |
| Koninklijke DSM N.V. |
| Associated British Foods Plc |
| Kemin Industries |
| Angel Yeast Co. Ltd |
| Lesaffre |
| Biotec Pharmacon ASA |
| Ceapro Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Hubei province fermentation operators and Mumbai nutraceutical exporters lock in supply access while providing price visibility against yeast biomass feedstock cycles. These arrangements concentrate pricing power among vertically integrated producers capable of delivering batch-specific bioactivity certificates to TGA-registered formulation houses.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Asia-Pacific beta-glucan market. Pharmaceutical-grade specifications with validated macrophage activation assays command substantial premiums over commodity oat-derived fiber grades. Cost compression in standard-tier yeast extracts is intensifying because brewing industry output volatility squeezes non-integrated extractors. Price-sensitive Indian nutraceutical export houses serving FSSAI-certified markets drive volume negotiations, while Japanese functional beverage manufacturers show lowest sensitivity for enzymatic-extraction premium grades.
Supply Chain Analysis
China and India anchor Asia-Pacific beta-glucan supply, with Hubei province fermentation corridors feeding Yangtze River Delta pharmaceutical clusters and Mumbai-Hyderabad formulation networks. Yeast biomass, enzymatic extraction reagents, and hydrocolloid stabilizers constitute critical input dependencies. Single-source vulnerability concentrates in Hubei province's captive fermentation infrastructure, where geographic concentration creates disruption risk for regional formulation networks. Distribution runs through contract manufacturing relationships with certified technical service presence, displacing spot-market purchasing among export-oriented nutraceutical houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against emerging mushroom-derived beta-glucan fractions capturing traditional medicine positioning in premium Japanese and Chinese consumer segments. Incumbents must navigate lentinan and related mycelial extracts that compete on immunomodulatory claims with lower regulatory complexity.
For Market Incumbents: Secure backward integration into yeast biomass supply or captive fermentation capacity to defend margin position against brewing industry feedstock volatility. Invest in NMPA pre-qualified strain portfolios to accelerate novel food registration timelines before regulatory compression favors established suppliers. Pharmaceutical-grade assay validation capabilities represent the critical defensive moat separating premium-tier suppliers from commodity-positioned competitors facing price erosion.
For New Entrants and Emerging Players: Technical service gaps in India's FSSAI enforcement environment create entry pathways for certified suppliers establishing Mumbai or Hyderabad presence with batch-specific documentation capabilities. Veterinary immunomodulation applications in aquaculture and companion animal health offer underdeveloped volume expansion with lower regulatory complexity than human therapeutic positioning. Partner with Australian clean-label formulators seeking non-GMO enzymatic extraction alternatives to established alkaline-method suppliers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated fermentation operators with captive supply and validated bioassay documentation serving TGA-registered export markets. Long-term viability over the coming decade rests on regulatory qualification breadth across NMPA, TGA, and EU novel food equivalence pathways. Watch for consolidation signals when mid-scale extractors face retooling costs from enzymatic extraction transition pressures.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Extraction Technology Adoption | Kerry Group's platform preserves beta-1,3/1,6 branching integrity for clean-label positioning in Australian and Japanese premium segments. |
| Regulatory Qualification Expansion | Koninklijke DSM N.V.'s EU novel food equivalence strains accelerate market access into TGA and PMDA jurisdictions. |
| Captive Fermentation Capacity Addition | Angel Yeast Co. Ltd's Hubei province infrastructure anchors regional supply against geographic concentration risk. |
| Pharmaceutical-Grade Assay Validation | Batch-specific bioactivity certificates enable therapeutic claim substantiation under TGA and NMPA frameworks. |
| Veterinary Application Diversification | Aquaculture immunomodulation offers volume expansion with lower regulatory complexity than human pharmaceutical positioning. |
Methodological Framework
A spread of perspectives from fermentation technology directors, FSSAI regulatory consultants, Mumbai nutraceutical procurement managers, and enzymatic extraction R&D leads converged on the working assumptions underlying supply concentration and pricing dynamics. Secondary validation drew from NMPA novel food registration databases, TGA therapeutic goods listings, Indian customs import records, and SEC filings of listed ingredient suppliers. Bottom-up volume estimates from Hubei province capacity assessments and top-down demand sizing from Japanese functional food formulation data were triangulated to establish market boundaries.
Segmentation dimensions modeled include source type, product formulation, end-use application, and regional regulatory cluster across the analysis window. CAGRs were derived from growth driver elasticity analysis applied to base-year consumption estimates. Forecast inputs incorporated NMPA approval timeline compression effects, FSSAI purity threshold enforcement trajectories, and enzymatic extraction adoption curves in Australian and Japanese clean-label segments.
Forecasts assume regulatory continuity in NMPA novel food frameworks, TGA therapeutic claim pathways, and FSSAI nutraceutical enforcement; material policy shifts would require re-modeling. Specific risks include bioassay standardization protocol changes, Hubei province supply disruption events, and mushroom-derived substitute regulatory reclassification. Recalibration cycles align with material shifts in NMPA registration timelines and enzymatic extraction technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Direct Fed Microbials Market
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
Ashwagandha Market
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Diet Pills Market
Nutritional Supplements
Lactoferrin Products Market
Nutritional Supplements
Curcumin Market
Nutritional Supplements
North and South America Mineral Supplement Tablets Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Europe Nutraceutical Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Global Nutraceutical Market