
 Nutritional Analysis Service Market | 2026-2036
Nutritional Analysis Service Market Size, Share, and Industry Trends Forecast 2026-2036
Nutritional Analysis Service Market Insights
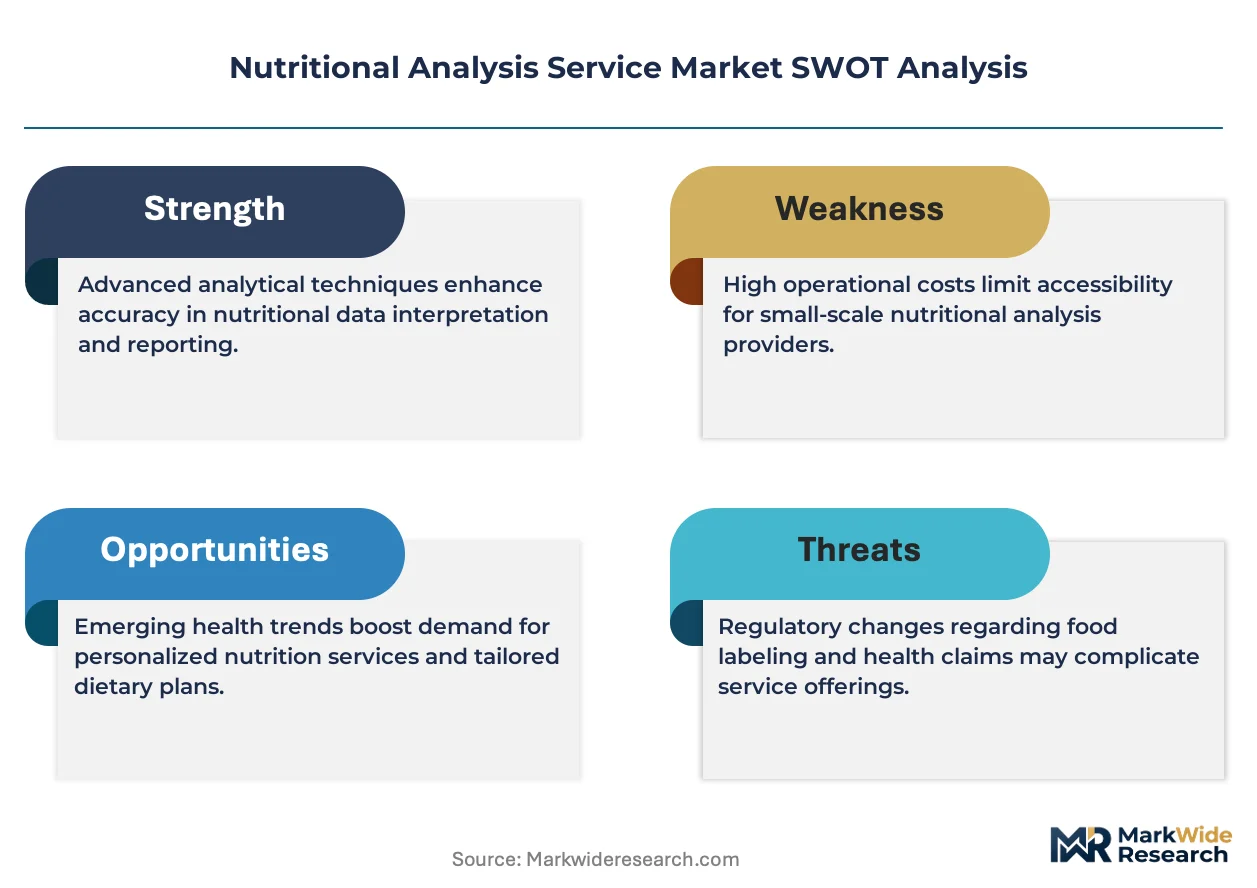
EU Regulation 1169/2011 on food information to consumers is restructuring the cost-of-entry calculus for nutritional testing across European supply chains. Eurofins Scientific leverages its pan-European laboratory network to sustain rapid turnaround on nutrient-panel validations. SGS SA anchors its competitive position through specialized allergen-detection protocols that meet evolving EFSA threshold requirements. Bureau Veritas differentiates by controlling accredited on-site testing infrastructure that reduces sample transit risk for perishable food clients.
Nutritional analysis services encompass the quantitative and qualitative assessment of macro-nutrients, micro-nutrients, and bioactive compounds in food matrices, employing chromatography, mass spectrometry, and spectrophotometric methods to achieve detection limits at parts-per-million or lower for label-claim substantiation. The primary commercial purpose centers on enabling food producers to satisfy mandatory disclosure rules, support health-position marketing, and manage liability from undeclared allergens or contaminant exceedances. Nutrient Testing and Allergen Testing command the largest current revenue pools due to universal regulatory mandates, while AI Tools within the Technology dimension represent the fastest-expanding capability layer as machine-learning models trained on spectral libraries reduce analytical labor intensity and expand remote interpretation capacity.
FDA enforcement of the Nutrition Labeling and Education Act, EFSA guidance on health claims under Regulation 1924/2006, and Japan's Food Labeling Act collectively shape demand by mandating specific nutrient declarations, substantiation dossiers, and standardized analytical methodologies that only accredited providers can reliably deliver. These frameworks create persistent compliance demand because non-conformity triggers product recalls, import refusals, and civil liability exposure that far exceed testing expenditure. Stakeholders must monitor how rapidly evolving AI validation standards and cross-border mutual recognition agreements between FDA, EFSA, and Japan's Consumer Affairs Agency reshape which laboratory credentials confer market access.
Market Dynamics
AI-assisted spectral analysis is compressing analytical turnaround times from weeks to days, forcing incumbent laboratories to restructure workflow architectures and pricing models around machine-learning interpretation capacity.
Growth Catalysts
- EU Regulation 1169/2011:Mandatory nutrient disclosure rules for packaged foods create persistent compliance demand across European supply chains, requiring accredited third-party verification for label-claim substantiation.
- Cloud-based analytical platforms:Remote data interpretation capabilities expand laboratory reach without proportional infrastructure investment, enabling smaller providers to serve multinational food manufacturers.
- Japan's aging-population dietary programs:Precision nutrition mandates for institutional foodservice and senior-care facilities intensify analytical workload requirements for micronutrient quantification.
Market Restraints
- Reference material costs:Certified reference standards for trace-level contaminant detection face supply concentration from German and US specialty chemical suppliers, creating input price volatility.
- Technical limitation in complex matrices:Polyphenol and bioactive compound quantification in fermented or highly processed foods remains methodologically constrained, limiting service expansion into functional food categories.
- Regulatory friction from mutual recognition gaps:Non-harmonized accreditation requirements between FDA, EFSA, and Japan's Consumer Affairs Agency force redundant testing for exporters.
Strategic Opportunities
- India's FSSAI enforcement expansion:Strengthened domestic food safety infrastructure creates demand for accredited nutritional testing as multinational brands localize production.
- Regulatory tailwind from EU AI Act:Algorithmic transparency requirements for AI-assisted analytical tools favor providers with documented validation protocols and audit-ready machine-learning pipelines.
- Technology convergence of mass spectrometry and blockchain:Immutable data trails for nutrient certificates address liability concerns in organic and premium food segments.
Industry Challenges
- Spectroscopic data science talent gap:Shortage of analysts capable of training and validating machine-learning models on spectral libraries constrains AI tool deployment timelines.
- ISO/IEC 17025 recertification cycles:Three-year accreditation renewals with scope extensions for novel methodologies create administrative burden and temporary service suspension risks.
- Integration complexity with legacy LIMS:Older laboratory information management systems require costly middleware development to ingest AI-generated spectral interpretations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutritional Analysis Service Market |
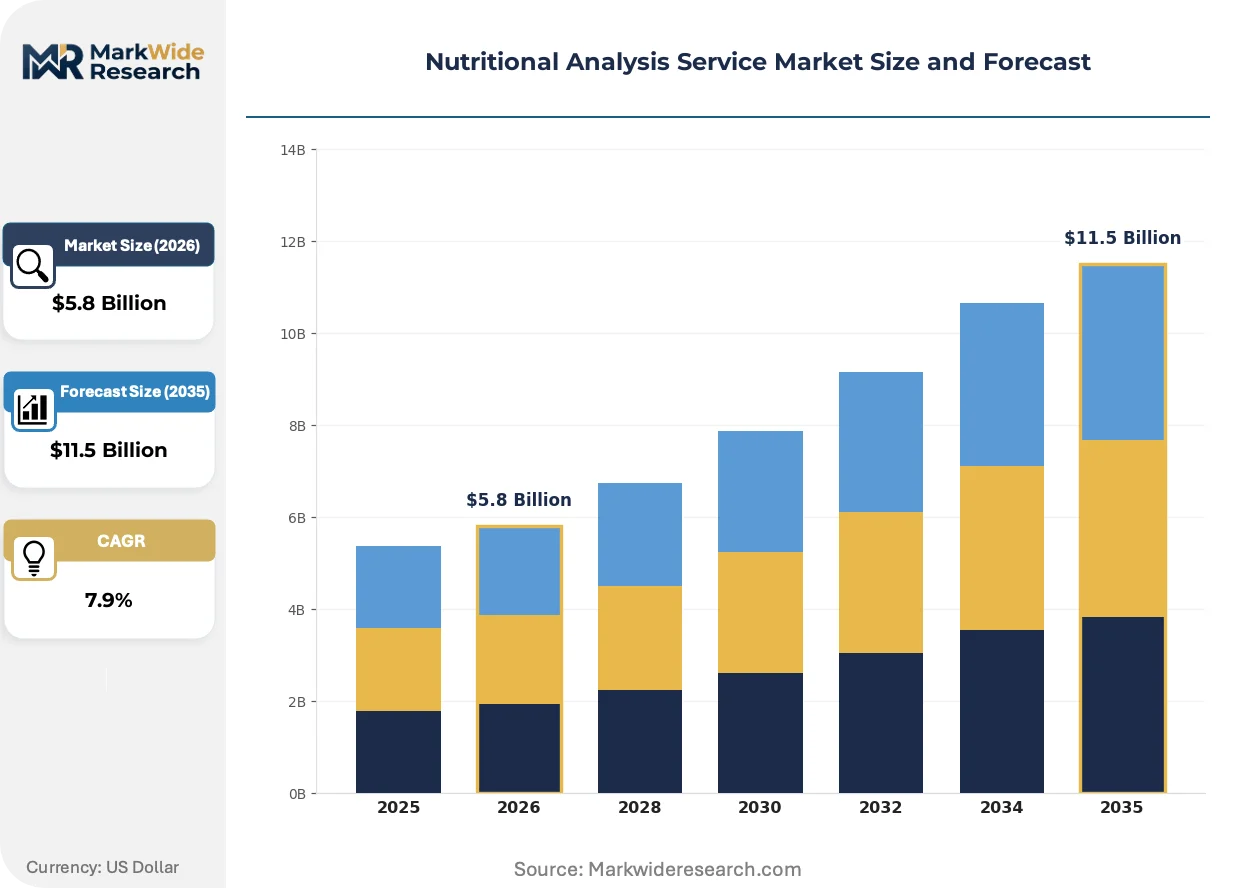
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Microbiological Testing, Nutrient Testing, Allergen Testing, Label Compliance End User: Food Manufacturers, Restaurants, Health Care Providers, Educational Institutions Technology: Laboratory Analysis, Mobile Applications, Cloud-Based Solutions, AI Tools Delivery Model: On-Site Testing, Remote Analysis, Subscription Services, Batch Services |
| Companies Covered | Eurofins Scientific, SGS SA, Intertek Group plc, Bureau Veritas, ALS Limited, Mérieux NutriSciences, Thermo Fisher Scientific, AsureQuality Limited, TÜV SÜD AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutritional Analysis Service Market Trends and Innovations
Spectral analysis automation is restructuring competitive economics by collapsing the labor component of nutrient quantification, while regulatory digitization and buyer procurement centralization reshape how testing contracts are awarded and fulfilled.
Near-infrared spectroscopy coupled with convolutional neural networks is unifying rapid screening and confirmatory testing into single-instrument workflows. Mid-sized contract laboratories in Germany and the United States are deploying these systems for routine macronutrient panels. This convergence is collapsing the traditional separation between high-throughput screening laboratories and specialized confirmatory facilities.
EFSA guidance on health claims under Regulation 1924/2006 now requires structured analytical dossiers with method traceability documentation. Food manufacturers must demonstrate that nutrient values on labels derive from validated protocols with measurement uncertainty calculations. Dairy and infant nutrition segments in France and the Netherlands are restructuring supplier qualification around these documentation requirements.
Consolidated procurement by multinational food manufacturers is displacing fragmented testing relationships with regional laboratories. Centralized vendor management programs now mandate pan-continental coverage and standardized data formats. This concentration is most visible in the United States, where national retail chains require uniform nutrient certificates across private-label suppliers regardless of production location.
Nutritional Analysis Service Market Segmentation
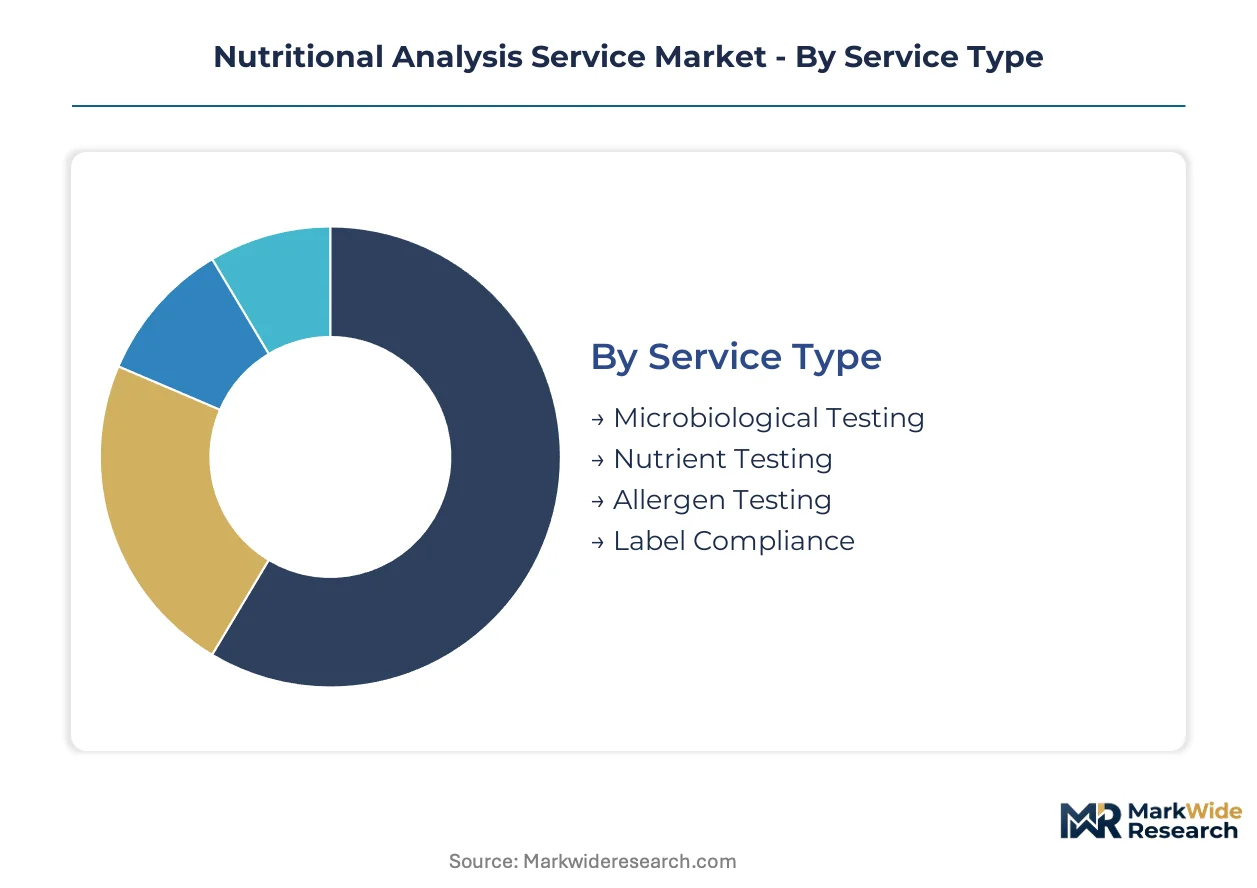
Nutritional analysis service providers structure offerings around four intersecting dimensions that determine pricing power, contract duration, and technical capability requirements. Service type and technology choices particularly reshape competitive economics as automation displaces labor-intensive methods.
Service Type:
Supply concentration in reference materials and accredited laboratory capacity favors established providers with multi-site networks and ISO/IEC 17025 scope breadth.
- Nutrient Testing:Quantitative assessment of macro-nutrients, micro-nutrients, and bioactive compounds using chromatography and mass spectrometry. Packaged food manufacturers in Germany and the United States drive volume as FDA and EFSA tighten label-claim verification requirements.
- Allergen Testing:Detection of undeclared proteins and residues at threshold levels mandated by EFSA and national regulators. Specialized protocols for gluten, nuts, and dairy command premium pricing due to liability exposure from recall events.
- Microbiological Testing:Pathogen and spoilage organism enumeration for shelf-life validation and HACCP compliance.
- Label Compliance:Verification that nutrient declarations match analytical results and meet jurisdiction-specific formatting rules.
Nutrient Testing absorbs the bulk of installed capacity; AI Tools within technology segments is expanding most quickly.
End User:
Customer procurement maturity separates price-sensitive transactional buyers from strategic partners demanding integrated compliance platforms.
- Food Manufacturers:Multinational brands and private-label suppliers require pan-continental testing coverage with standardized data formats. Centralized vendor management programs in the United States consolidate contracts around laboratories with cloud-based reporting capabilities.
- Health Care Providers:Hospitals and senior-care facilities in Japan analyze therapeutic diets for precision nutrition programs serving aging populations.
- Restaurants:Chain operators and foodservice management companies verify menu claims for calorie disclosure mandates.
- Educational Institutions:University dining services and research kitchens conduct periodic audits for institutional compliance.
Food Manufacturers dominate contract value; Health Care Providers are climbing the fastest as precision nutrition mandates proliferate.
Technology:
Capital intensity and talent requirements create tiered competitive barriers between automated platforms and conventional analytical methods.
- AI Tools:Machine-learning models trained on spectral libraries reduce interpretation labor and enable remote analysis. Near-infrared spectroscopy coupled with convolutional neural networks unifies screening and confirmatory workflows in German and United States laboratories.
- Cloud-Based Solutions:Distributed data infrastructure allows smaller providers to serve multinational clients without proportional laboratory investment.
- Laboratory Analysis:Chromatography, mass spectrometry, and spectrophotometric methods remain the reference standard for regulatory submissions.
- Mobile Applications:Consumer-facing nutrient scanners and simplified testing interfaces for non-technical users.
Laboratory Analysis retains the largest revenue base; AI Tools are gaining share fastest as spectral automation compresses turnaround economics.
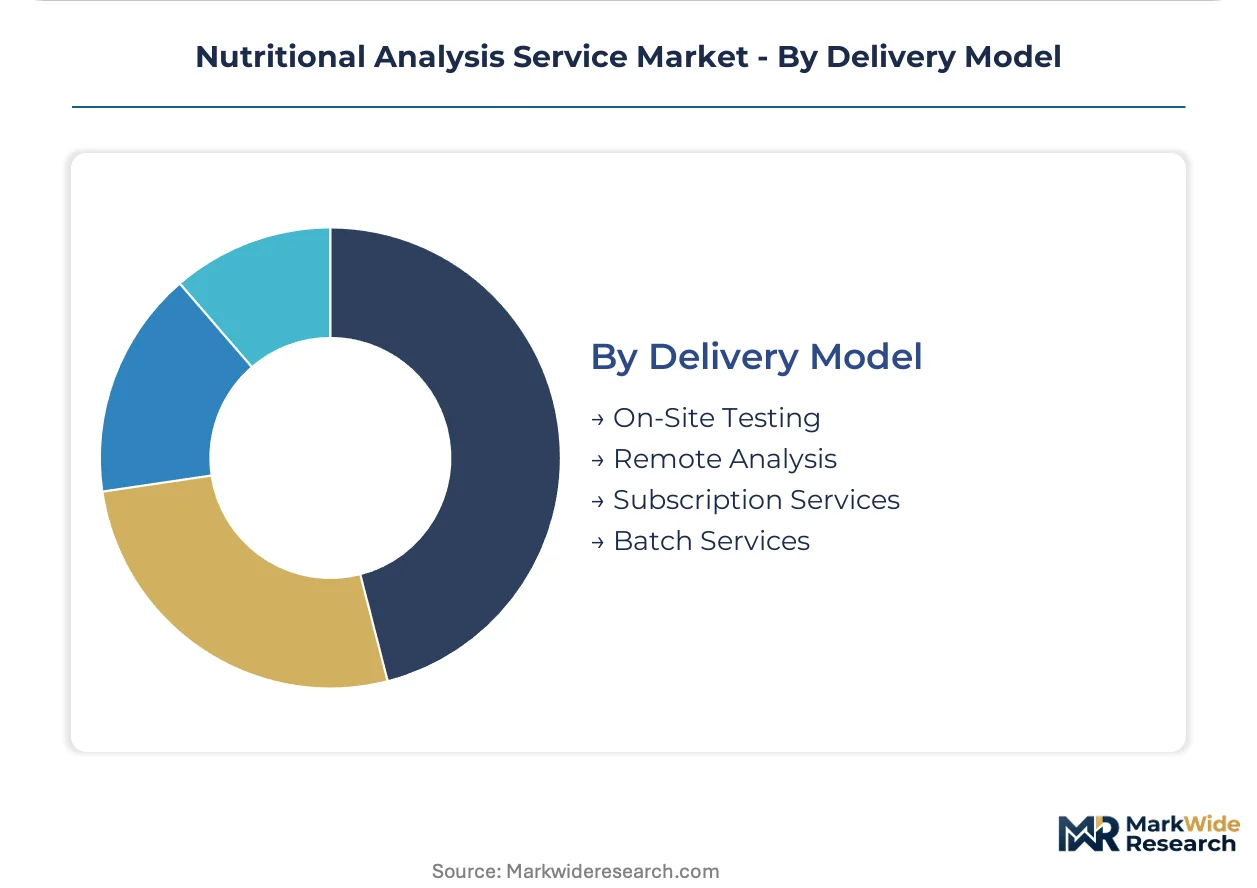
Delivery Model:
Asset location and contractual structure determine margin profiles and customer switching costs across service arrangements.
- Batch Services:Project-based testing for product launches, reformulations, and periodic compliance audits. Food manufacturers submit samples during NPD cycles and regulatory change windows.
- On-Site Testing:Accredited infrastructure deployed at client facilities reduces transit risk for perishable matrices and accelerates release decisions.
- Subscription Services:Recurring monitoring programs with scheduled sampling and trending analysis for quality assurance.
- Remote Analysis:Spectral data transmission to centralized interpretation centers for rapid screening without sample shipment.
Batch Services handle the majority of transaction volume; Subscription Services show the steepest expansion trajectory as manufacturers seek predictable compliance costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Singapore and Shenzhen concentrate cloud-based analytical platform development, drawing venture capital toward spectral automation startups that serve cross-border food manufacturers.
United States
FDA enforcement of the Nutrition Labeling and Education Act compels packaged food manufacturers to secure third-party nutrient verification for label-claim substantiation. Private-label suppliers to national retail chains now demand standardized nutrient certificates regardless of production location. Greater Chicago hosts dense laboratory clustering where cloud-based platforms compress turnaround economics for Midwestern food processors.
Germany
EFSA threshold requirements for allergen detection drive specialized protocol investments by laboratories serving pan-European supply chains. EU Regulation 1169/2011 mandates structured analytical dossiers with method traceability documentation for health claims. Bavaria's industrial corridor anchors accredited infrastructure that reduces sample transit risk for dairy and infant nutrition clients.
Japan
Precision nutrition mandates for institutional foodservice and senior-care facilities intensify analytical workload requirements for micronutrient quantification. The Consumer Affairs Agency enforces standardized methodologies that only accredited providers can reliably deliver. Tokyo and Osaka metropolitan areas concentrate health care provider demand for therapeutic diet analysis.
India
FSSAI enforcement expansion creates demand for accredited nutritional testing as multinational brands localize production to avoid import duty exposure. Strengthened domestic food safety infrastructure requires documented validation protocols for label compliance. Maharashtra and Gujarat host emerging laboratory networks that serve reformulated product launches for export-oriented food processors.
United Kingdom
Post-Brexit divergence from EU mutual recognition agreements forces redundant testing for exporters serving both markets simultaneously. The Food Standards Agency maintains parallel requirements for nutrient disclosure that preserve compliance complexity. London and the Southeast concentrate contract research organizations that manage dual-jurisdiction dossier preparation for multinational manufacturers.
Nutritional Analysis Service Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service categories. Pan-European networks and Asia-Pacific laboratory chains dominate high-volume nutrient testing through accredited multi-site coverage. Three archetypes define competitive positioning: diversified testing conglomerates with food safety divisions, specialized nutritional analysis pure-plays, and analytical instrument manufacturers extending into service provision. Capacity expansion through laboratory acquisitions and technology licensing partnerships constitute the dominant competitive moves reshaping market structure.
Among diversified testing conglomerates, Eurofins Scientific, SGS SA, and Bureau Veritas occupy positions that exemplify scale-driven competitive dynamics. Eurofins Scientific represents the pan-European network archetype with laboratory density across jurisdictions where EFSA and national regulators impose overlapping compliance burdens. SGS SA anchors the specialized protocol segment through allergen-detection capabilities that command premium pricing. Bureau Veritas sits within the on-site infrastructure tier, controlling accredited testing deployments that minimize perishable sample degradation risk. These three entities collectively illustrate how geographic coverage breadth and accreditation scope depth determine contract eligibility for multinational food manufacturers.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS SA |
| Intertek Group plc |
| Bureau Veritas |
| ALS Limited |
| Mérieux NutriSciences |
| Thermo Fisher Scientific |
| AsureQuality Limited |
| TÜV SÜD AG |
| Others |
Pricing and Supply Chain Analysis
Spectroscopic data science talent concentration in Germany and the United States widens pricing-tier spreads, as laboratories in these markets command premium rates for AI-assisted spectral interpretation while offshore providers compete on standardized nutrient panels.
Pricing Analysis
Short lead-time premiums separate expedited allergen-detection protocols from standard batch services, with EFSA-mandated threshold validations commanding the highest tier. Pricing stratifies across ISO/IEC 17025-accredited reference laboratories, mid-tier regional providers, and economy-tier screening facilities. Cost compression in routine macronutrient panels intensifies as near-infrared automation displaces chromatography labor. Private-label suppliers to US retail chains exhibit the greatest price sensitivity, while infant nutrition manufacturers in France and the Netherlands accept premium pricing for method-traceability documentation.
Supply Chain Analysis
Regional distribution centers in Greater Chicago, Bavaria's industrial corridor, and Tokyo-Osaka metropolitan areas anchor hub-and-spoke sample logistics for perishable matrices. Certified reference standards draw from German and US specialty chemical suppliers, creating input concentration for trace-level contaminant detection. Single-source vulnerability in reference material supply generates price volatility when batch certification delays cascade. Distribution runs through accredited laboratory networks with pan-continental coverage, though mutual recognition gaps between FDA, EFSA, and Japan's Consumer Affairs Agency force redundant routing for multinational clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO/IEC 17025-accredited laboratory capacity constraints prop pricing power for incumbent providers, as three-year recertification cycles and spectral data science shortages limit rapid supply expansion.
For Market Incumbents: Deploy cloud-based analytical platforms to compress turnaround economics and defend against AI-native entrants. Expand ISO/IEC 17025 scope extensions for novel methodologies ahead of EU AI Act algorithmic transparency requirements. Consolidate regional laboratory acquisitions to secure pan-continental coverage credentials demanded by multinational food manufacturers. For New Entrants and Emerging Players: Mid-sized contract laboratories in India's Maharashtra and Gujarat represent the most penetrable buyer archetype, as FSSAI enforcement expansion outpaces domestic accredited capacity. Target reformulated product launches for export-oriented food processors with subscription-based remote spectral analysis. Differentiate through blockchain-anchored nutrient certificates addressing organic segment liability concerns. For Investors and Strategic Acquirers: Re-rating potential sits with specialized nutritional analysis pure-plays given AI-assisted spectral automation adoption curves. Long-term viability favors laboratories with documented machine-learning validation protocols and audit-ready pipelines. Monitor cross-border mutual recognition agreement progress between FDA, EFSA, and Japan's Consumer Affairs Agency as inflection indicator for redundant testing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Acquisition | Pan-continental ISO/IEC 17025 coverage secures multinational food manufacturer contracts. |
| AI Tool Validation Investment | Documented machine-learning pipelines satisfy EU AI Act algorithmic transparency requirements. |
| Cloud Platform Deployment | Remote spectral interpretation expands reach without proportional infrastructure expenditure. |
| Blockchain Data Integration | Immutable nutrient certificates address liability exposure in organic and premium segments. |
| Reference Material Backward Integration | In-house certified standard production reduces input price volatility from German suppliers. |
Research Methodology
Multi-period observation of AI tool deployment timelines, cloud platform adoption curves, and laboratory accreditation scope expansions anchored the trend analysis, supplemented by interviews with food safety directors at multinational manufacturers, regulatory affairs leads at testing conglomerates, procurement managers at retail chains, and technical directors at contract laboratories. Secondary validation drew from FDA warning letter databases, EFSA guidance documents, ISO/IEC 17025 accreditation registries, and customs trade data on analytical instrument imports. Bottom-up service provider revenue estimates and top-down regulatory mandate sizing were triangulated to cross-check market boundaries.
Input-output matrices modeled segment interactions across service type, technology, and delivery model dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical laboratory capacity expansion against regulatory mandate intensity, with cross-segment elasticities calibrated to spectral automation adoption rates. Industry-specific inputs included reference material cost indices, ISO/IEC 17025 recertification cycle frequencies, and mutual recognition agreement negotiation status between major jurisdictions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AI validation standard evolution and cross-border accreditation harmonization progress. Outputs reflect documented assumptions around regulatory enforcement intensity and technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market
Nutritional Supplements
Folate Market
Nutritional Supplements
Digestive Enzyme Complex Market
Nutritional Supplements
Nutraceutical Flexible Packaging Market
Nutritional Supplements
Feed Prebiotics Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Ashwagandha Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Elderberry Supplements Market
Nutritional Supplements
Digestive Health Supplements Market
Nutritional Supplements
South Africa Nutraceuticals Market