
 Water Soluble Vitamin and Mineral Feed Supplements Market | 2026-2036
Water Soluble Vitamin and Mineral Feed Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Water Soluble Vitamin and Mineral Feed Supplements Market Intelligence
Mounting pressure from regulators like the FDA and EMA to curb antibiotic use in animal feed is repositioning the value of preventative health supplements. BASF SE leverages its chemical production scale to offer a wide portfolio of vitamins. Koninklijke DSM NV specializes in high-potency vitamin and enzyme formulations, commanding a premium. Alltech Inc. differentiates through its focus on organic trace minerals and yeast-based supplements.
Water soluble vitamin and mineral feed supplements are bioavailable additives designed for dissolution in animal drinking water or liquid feed. These formulations, typically powders or liquids, ensure rapid absorption and support precise dosing for preventative health, especially in young animals. Within product types, vitamins and amino acids command significant share, being essential for metabolic functions. The poultry segment represents the fastest-growing end-user market, driven by automated production and rapid growth cycles.
Regulatory frameworks from the US FDA and European Food Safety Authority (EFSA) dictate maximum nutrient levels and purity standards. In China, Ministry of Agriculture and Rural Affairs regulations and GB standards govern feed safety, influencing market access. Future competitive advantage will hinge on providing verifiable data on product efficacy and maintaining transparent, traceable supply chains.
Market Dynamics
Regulatory pressure to reduce antibiotic use in livestock, exemplified by the EU Green Deal and FDA directives, is the central force reshaping the market. This shifts the value proposition from treatment to preventative health, elevating the role of bioavailable nutrient supplementation.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal's Farm to Fork strategy restricts antibiotic use, directly boosting demand for preventative supplements in European poultry and swine operations to maintain animal health and productivity.
- Aquaculture Industrialization:Growth in aquaculture, particularly in Southeast Asia, creates demand for specialized water-soluble formulas that improve feed conversion ratios and disease resistance in high-density farming systems.
- Production Consolidation:China's consolidation of its pork and poultry sectors into large-scale industrial farms drives adoption of automated water-based delivery systems for vitamins and minerals to ensure herd-wide health consistency.
Market Restraints
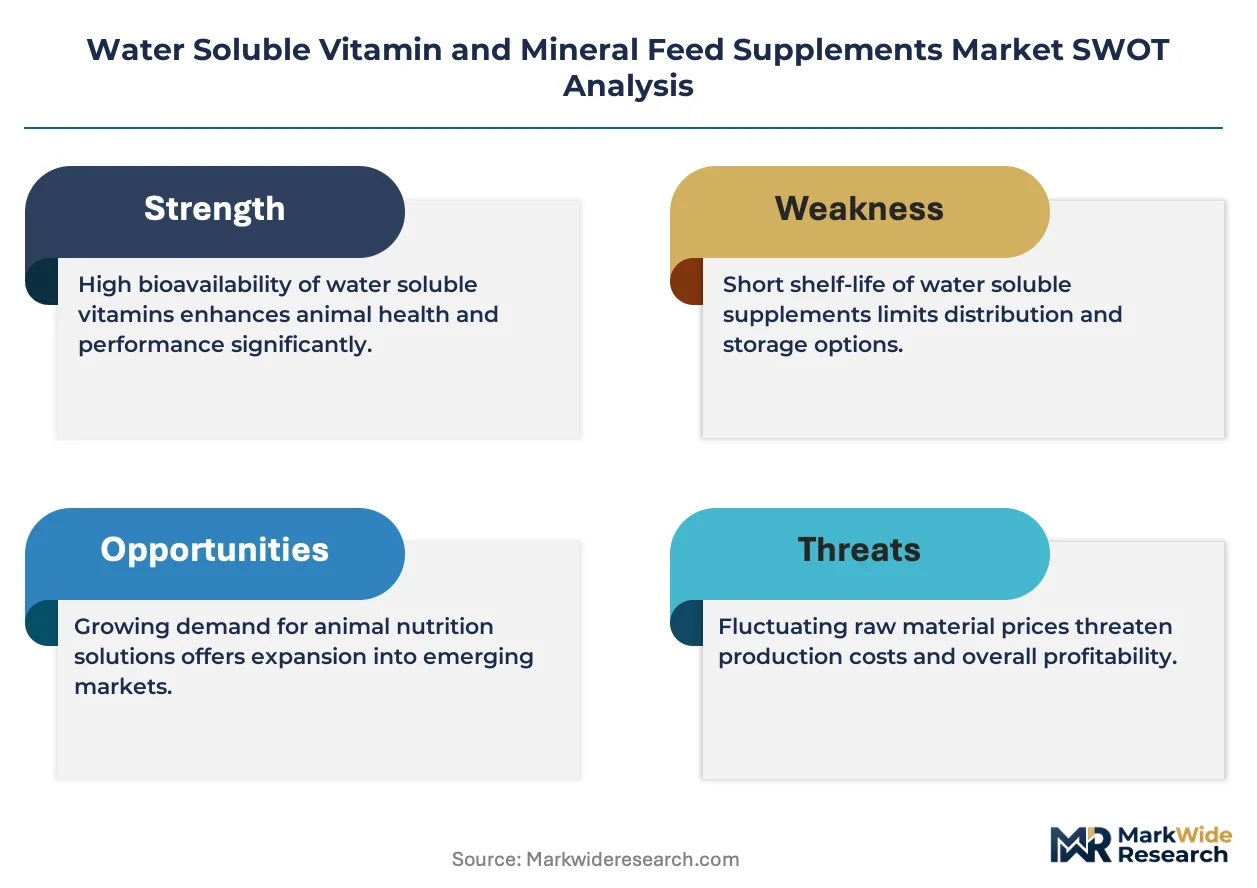
- Input Cost Volatility:Price fluctuations for raw materials used in synthetic vitamins, particularly energy-intensive Vitamin A and E, create pricing instability and margin pressure for supplement manufacturers.
- Formulation Complexity:Ensuring the stability and homogeneity of complex multi-vitamin and mineral premixes in liquid form presents significant technical challenges, risking nutrient degradation and inconsistent dosing.
- Substitution Threats:The increasing availability of alternative functional feed ingredients, such as probiotics and prebiotics, presents a substitution threat by offering different pathways to improve gut health and immunity.
Strategic Opportunities
- Geographic Expansion:The modernizing dairy and poultry sectors in sub-Saharan African countries like Nigeria and Ethiopia represent an underpenetrated market for basic water-soluble supplementation to improve livestock yields.
- Niche Applications:Developing species-specific formulations for high-value aquaculture, such as shrimp and salmonids, offers a path to premium pricing and differentiation from commodity products.
- Smart Farming Integration:Integrating supplement delivery with platforms that use sensors to monitor animal health allows for data-driven, automated, and precise nutrient dosing, creating a new service model.
Industry Challenges
- Regulatory Compliance Burden:Navigating the fragmented and evolving global regulations for feed additives, including disparate standards from EFSA, the FDA, and China's MARA, is a significant operational hurdle.
- Supply Chain Logistics:Establishing quality-controlled distribution networks, including cold chains where necessary, in developing regions is a logistical challenge for preserving the efficacy of liquid and sensitive powdered formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Soluble Vitamin and Mineral Feed Supplements Market |
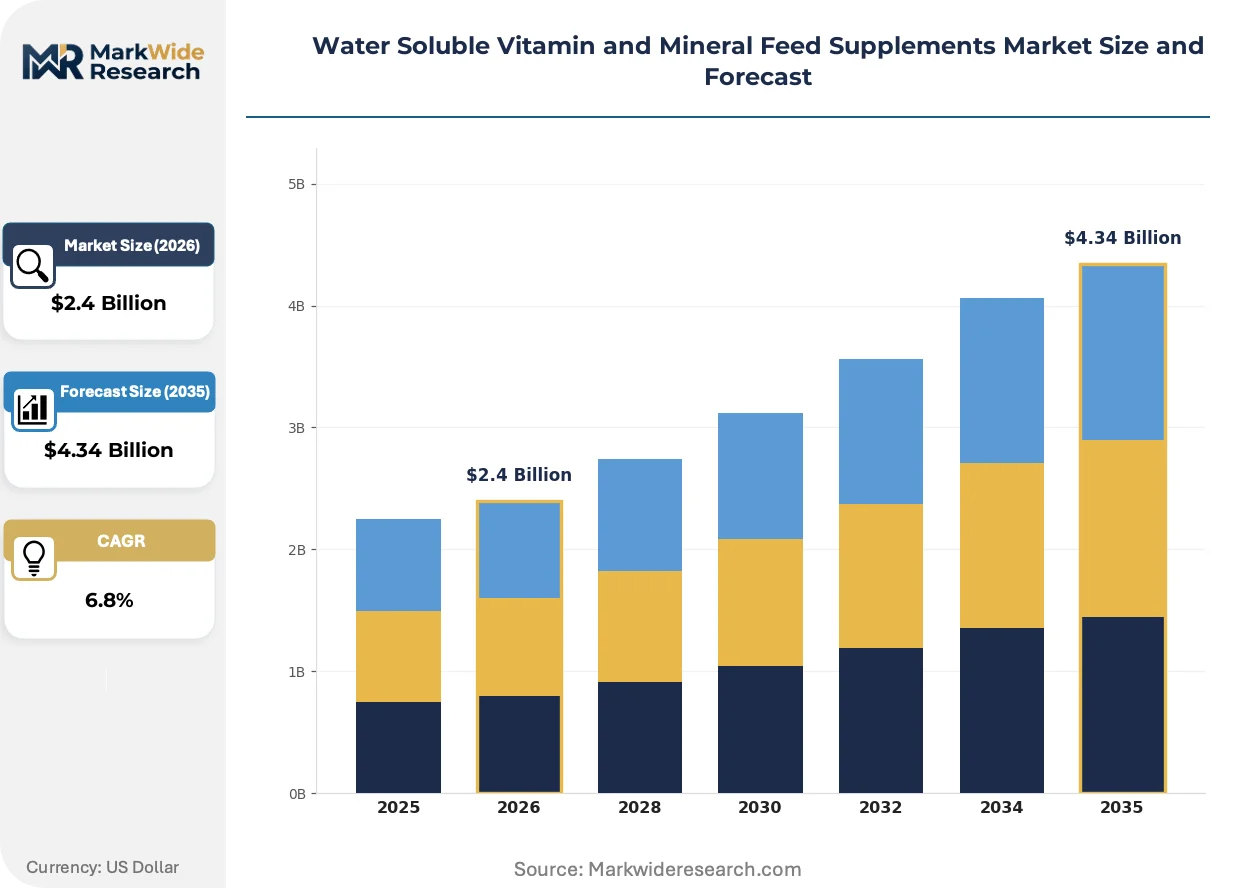
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Enzymes End User: Livestock, Poultry, Aquaculture, Companion Animals Distribution Channel: Online Retailers, Specialty Stores, Distributors, Importers Packaging Type: Bags, Bottles, Sachets, Bulk Containers |
| Companies Covered | Neovia Group, Archer Daniels Midland Company, Alltech Inc., Bluestar Adisseo Co., Kemin Industries Inc., Nutreco NV, BASF SE, Lonza Group AG, Koninklijke DSM NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Soluble Vitamin and Mineral Feed Supplements Market Strategic Shifts & Innovations
The market is evolving from broad-spectrum supplementation toward precision nutrition, driven by technology and a demand for verifiable outcomes. This transition prioritizes targeted delivery, bioavailability, and data integration to prove product efficacy in commercial farm settings.
Microencapsulation technology protects sensitive vitamins, like Vitamin C, and minerals from degradation, ensuring they reach the animal's digestive tract intact. Large-scale poultry and swine producers are adopting these enhanced formulations to reduce nutrient waste and improve dosing accuracy. This technology is expanding into combination products that bundle vitamins with other functional ingredients like organic acids, creating more complex health solutions.
Regulatory frameworks like the European Food Safety Authority’s (EFSA) quality standards and China's GB standards are imposing stricter requirements for supply chain transparency. These rules mandate clear documentation of raw material sourcing and manufacturing processes to ensure feed safety. The poultry segment, with its rapid production cycles and high biosecurity risks, is most affected, forcing producers to invest in verifiable, traceable supply chains.
Livestock producers are shifting preference from inorganic mineral salts to chelated or organic trace minerals, which offer higher bioavailability. This change disrupts the traditional commodity-driven purchasing model, replacing it with one based on proven performance data and lower inclusion rates. The trend is most visible in the European and North American dairy industries, where producers seek to maximize genetic potential and animal welfare.
Water Soluble Vitamin and Mineral Feed Supplements Market Segmentation
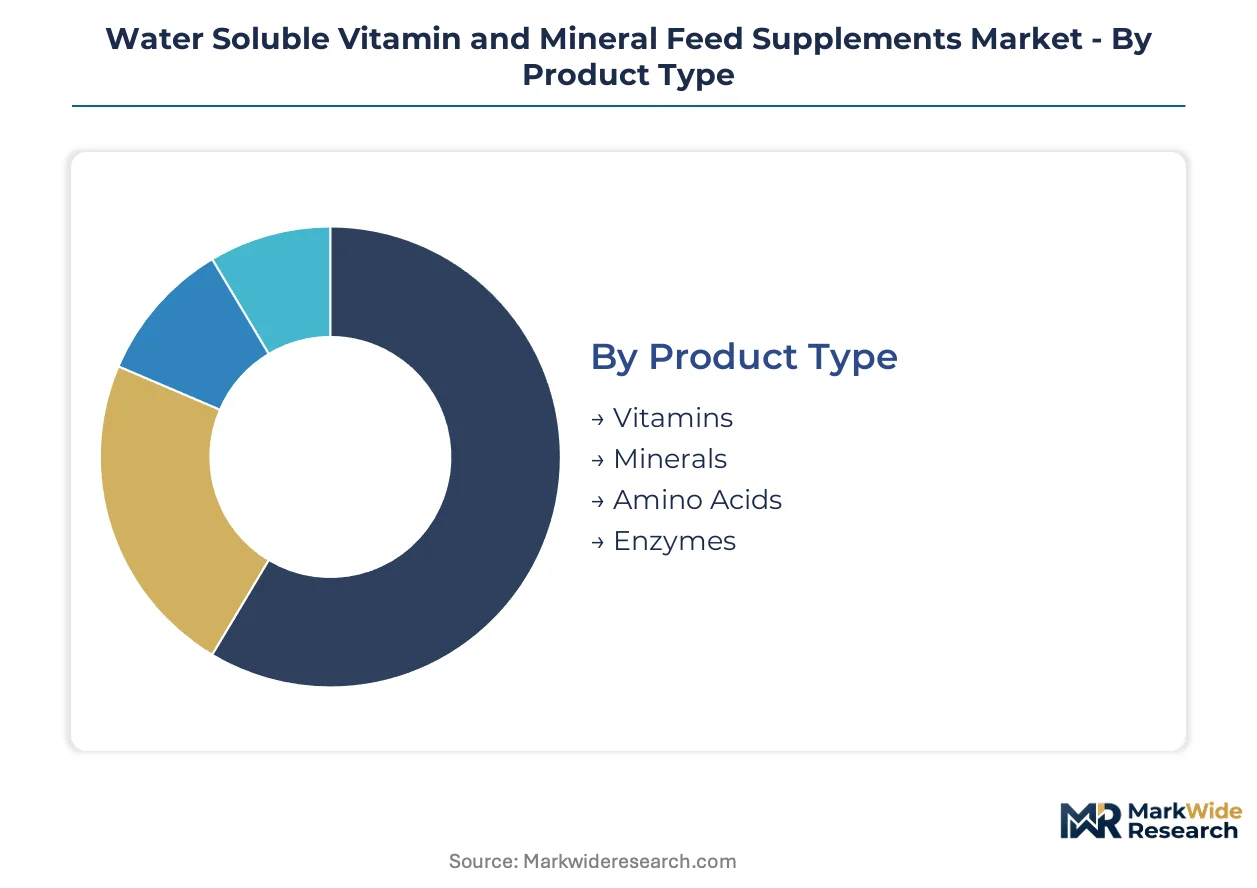
The water soluble vitamin and mineral feed supplements market segments reflect distinct product compositions, end-user requirements, and distribution dynamics. Understanding these categories is critical for manufacturers to tailor formulations and market strategies effectively.
Product Type:
Supply concentration for water soluble vitamin and mineral feed supplements significantly influences the availability and pricing across different product types.
- Vitamins:Vitamins, including A, D, E, and B-complex, are essential organic compounds supporting metabolic functions and immunity in animals. Demand concentrates in the poultry segment, where rapid growth cycles necessitate consistent nutrient delivery for health.
- Minerals:Minerals, such as calcium, phosphorus, and trace elements, are inorganic nutrients vital for bone health and enzymatic activity.
- Amino Acids:Amino acids are the building blocks of protein, crucial for muscle development and overall animal growth, often supplied as L-lysine or DL-methionine. The aquaculture sector drives demand, seeking optimized feed conversion ratios to maximize protein synthesis.
- Enzymes:Enzymes, like phytase and xylanase, improve feed digestibility and nutrient absorption, reducing anti-nutritional factors in feed ingredients.
Today's leader: Vitamins. Tomorrow's challenger: Amino Acids.
End User:
The volume of water soluble vitamin and mineral feed supplements consumed varies significantly across different end-user segments, reflecting distinct animal husbandry practices.
- Livestock:This segment includes cattle, swine, and other farm animals, where supplements support reproductive health and growth in large-scale operations.
- Poultry:Poultry represents the fastest-growing end-user segment, driven by automated production systems and rapid growth cycles requiring precise nutrient delivery. These operations prioritize supplements for disease resistance and feed efficiency.
- Aquaculture:Aquaculture operations, particularly in Southeast Asia, utilize specialized water-soluble formulas to improve feed conversion ratios and enhance disease resistance in high-density farming environments. This segment requires formulations stable in aquatic conditions.
- Companion Animals:Pet owners use water-soluble supplements for specific health benefits, often for older animals or those with dietary deficiencies.
Poultry represents the fastest-growing end-user segment, with Aquaculture also expanding quickly.
Distribution Channel:
Different distribution channels cater to distinct customer types, influencing market reach and service models for water soluble feed supplements.
- Online Retailers:Online platforms provide convenience and direct access for smaller farms and individual buyers, offering a wide range of specialized products. This channel is gaining traction for its ease of ordering and competitive pricing.
- Specialty Stores:These outlets focus on niche products and offer expert advice, serving specific customer needs like organic or species-specific formulations.
- Distributors:Distributors form the primary channel for large-scale farms and industrial buyers, providing bulk quantities, logistical support, and technical services. They manage complex supply chains to ensure timely delivery.
- Importers:Importers facilitate the cross-border movement of specialized feed supplements, connecting international manufacturers with local distribution networks.
Distributors ensure broad market access, while Online Retailers offer increasing convenience.
Packaging Type:
The cost tier of water soluble vitamin and mineral feed supplements often correlates with packaging type, reflecting varying scales of farm operations.
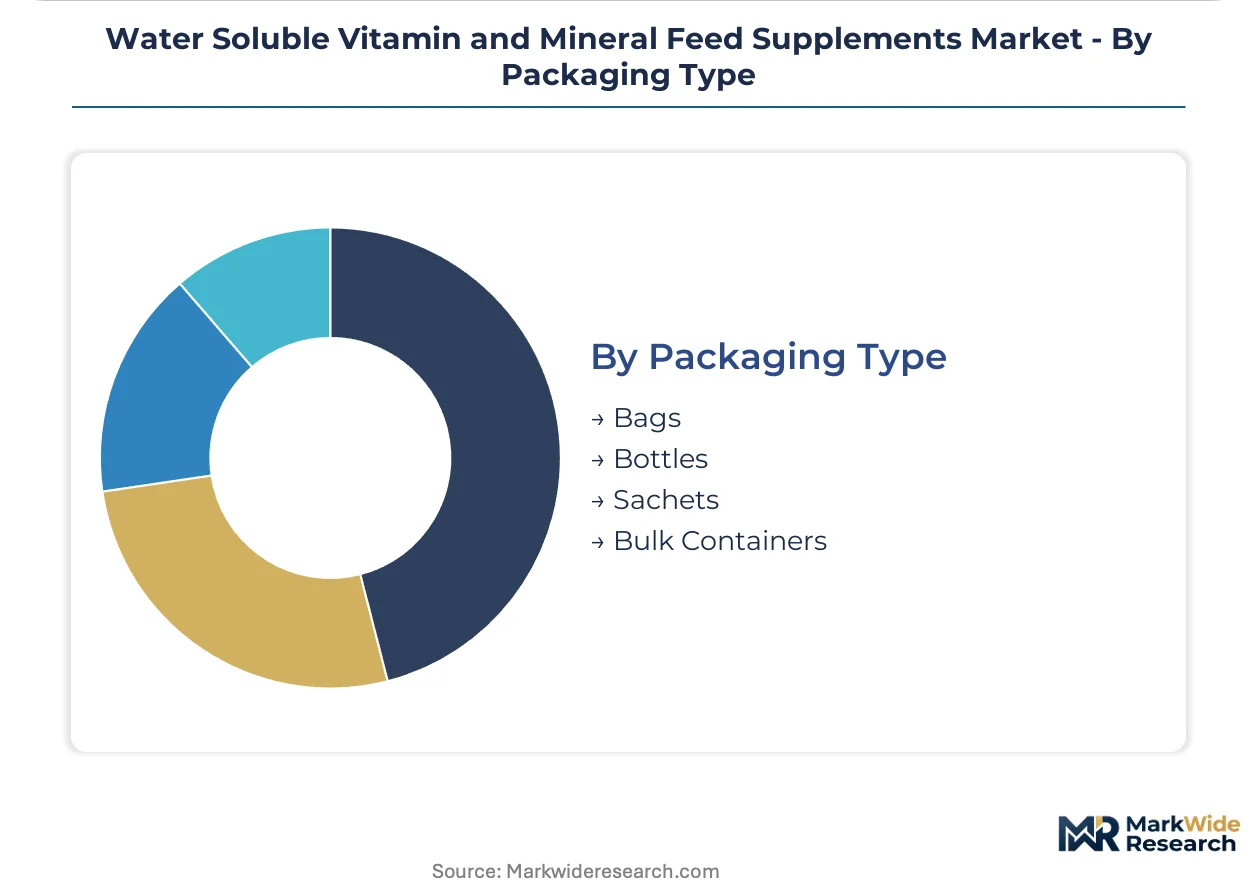
- Bags:Multi-layer bags protect powdered formulations from moisture and light, commonly used for medium-sized farm operations requiring convenient handling.
- Bottles:Bottles are typically used for liquid concentrates or smaller quantities, offering precise dosing and extended shelf life for specialty products.
- Sachets:Sachets provide pre-measured doses, ensuring accuracy and reducing waste, particularly beneficial for small-scale applications or individual animal treatments. This packaging type supports targeted interventions.
- Bulk Containers:Bulk containers, such as drums and large sacks, serve industrial-scale poultry and swine operations, optimizing cost-efficiency for high-volume usage. These containers streamline automated delivery systems.
Bulk Containers dominate industrial purchases, but Sachets are gaining favor for precision dosing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Talent concentrations in animal nutrition science and large-scale agricultural operations anchor demand for water soluble vitamin and mineral feed supplements across key global geographies. Regulatory shifts and industrial farming practices dictate regional market dynamics. These regions are investing in advanced feed formulations to enhance animal health and productivity.
China
China's industrialization of poultry and swine production drives significant demand for water-soluble supplements to support rapid growth cycles. Ministry of Agriculture and Rural Affairs regulations, including GB standards, govern feed safety and influence market access. The Yangtze River Delta region, a major agricultural processing hub, experiences high adoption of water-based delivery systems for herd health consistency.
United States
Preventative health strategies in the US livestock sector create consistent demand for bioavailable nutrient solutions. US FDA directives to reduce antibiotic use elevate the importance of feed supplements for animal welfare. The Midwest, particularly states within the Corn Belt, sees widespread integration of these products into large-scale beef and poultry operations.
Germany
Germany's focus on sustainable animal husbandry, particularly in poultry and swine, boosts demand for high-efficacy preventative supplements. The EU Green Deal's Farm to Fork strategy directly restricts antibiotic use, necessitating alternative health solutions. Lower Saxony, a region with dense livestock farming, actively adopts advanced water-soluble vitamin and mineral formulations.
Vietnam
Aquaculture industrialization across Vietnam, especially for shrimp and pangasius, requires specialized water-soluble formulas to improve feed conversion. The Ministry of Agriculture and Rural Development implements policies supporting sustainable aquaculture practices and disease prevention. The Mekong Delta, a critical aquaculture region, prioritizes supplements that enhance disease resistance in high-density farming environments.
Brazil
Brazil's vast livestock sector, including large-scale beef and poultry operations, generates substantial demand for feed supplements to optimize growth and reproductive health. The Ministry of Agriculture, Livestock and Food Supply (MAPA) enforces feed quality and safety standards for domestic consumption and export. Mato Grosso, a major cattle and grain producing state, integrates water-soluble nutrients into extensive animal feeding programs.
Water Soluble Vitamin and Mineral Feed Supplements Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the water soluble vitamin and mineral feed supplements market. The market structure exhibits a tiered consolidation, with global chemical giants and specialized nutrition companies dominating specific segments. Three strategic archetypes include large-scale chemical producers, high-potency vitamin formulators, and organic trace mineral specialists. Competitive moves center on portfolio diversification and strategic partnerships to expand geographic reach.
Global chemical powerhouses like BASF SE represent a foundational archetype, leveraging extensive chemical production scale to offer a broad range of vitamins. Koninklijke DSM NV occupies a premium position, exemplifying specialized nutrition companies focused on high-potency vitamin and enzyme formulations. Alltech Inc. sits within the niche specialist category, anchoring its offerings around organic trace minerals and yeast-based supplements for targeted animal health outcomes.
| Leading Market Players |
|---|
| Neovia Group |
| Archer Daniels Midland Company |
| Alltech Inc. |
| Bluestar Adisseo Co. |
| Kemin Industries Inc. |
| Nutreco NV |
| BASF SE |
| Lonza Group AG |
| Koninklijke DSM NV |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's Farm to Fork strategy gates access to premium European markets for feed supplements, demanding verifiable sustainability. This regulatory pressure drives up costs for compliant raw materials, influencing premium-tier pricing.
Pricing Analysis
Bundled solutions, integrating technical support and automated delivery systems, command premium pricing compared to unbundled commodity products. The dominant pricing structure involves contract-based long-term offtake for large industrial operations. Price differentiation is driven by verifiable product efficacy data and specific regulatory certifications like EFSA approval. Pricing pressure stems from input cost volatility, particularly for energy-intensive Vitamin A and E. Large industrial poultry and swine operations are highly price-sensitive, while niche aquaculture segments show lower sensitivity for specialized formulations.
Supply Chain Analysis
Single-source vulnerability sits with specialized API manufacturers in China and India for key vitamin precursors. Geographic supply concentration for raw materials like Vitamin C and B-complex vitamins centers heavily on China. Key raw material dependencies include synthetic vitamin intermediates and specific mineral salts. A structural supply chain risk is logistics chokepoints in Southeast Asia for aquaculture-specific ingredients. Distribution runs through a network of regional distributors and importers for bulk quantities to industrial farms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water soluble vitamin and mineral feed supplements market is a late-cycle quality story, driven by a demand shift towards precision nutrition. Regulatory mandates for antibiotic reduction amplify the need for verifiable efficacy and premium formulations.
For Market Incumbents: Anticipate continued regulatory pressure from the US FDA and EFSA by investing in advanced R&D for microencapsulation technologies. Diversify raw material sourcing beyond China to mitigate geopolitical supply chain risks. Focus on developing combination products that bundle vitamins with organic acids to counter substitution threats from alternative functional ingredients. Strengthen data integration capabilities to provide verifiable efficacy data, crucial for retaining large industrial clients.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for new entrants offering highly traceable and sustainably sourced feed supplements. Target underpenetrated sub-Saharan African dairy and poultry sectors with basic, cost-effective formulations. Focus on species-specific niche applications in high-value aquaculture, such as shrimp and salmonids, for premium pricing. A strong go-to-market angle involves offering integrated smart farming solutions.
For Investors and Strategic Acquirers: Roll-up economics work for specialized nutrition companies because fragmented regional markets present consolidation opportunities. The long-term viability of this market is strong, driven by sustained global protein demand and preventative health trends. Acquisition targets should be asset-light designers with strong R&D capabilities in organic trace minerals or enzyme formulations. The signal to watch is the increasing adoption rate of automated water-based delivery systems in emerging markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Expands market reach across various animal segments. |
| Strategic Partnerships | Facilitates access to new geographies and specialized technology. |
| Microencapsulation Investment | Enhances product stability and bioavailability for nutrients. |
| Data-Driven Efficacy Validation | Builds trust with producers seeking verifiable performance. |
| Supply Chain Traceability Upgrade | Meets stringent regulatory demands from EFSA and MARA. |
Research Approach
Direct dialogue with animal nutritionists, farm managers, feed formulators, and regulatory experts provided qualitative grounding. This primary fieldwork was triangulated with extensive secondary research from FDA filings and EFSA scientific opinions. Additional data came from industry association reports, agricultural statistics from USDA and China's MARA, and company financial disclosures. A bottom-up and top-down approach validated market sizing and growth projections.
The analytical lens applied both bottom-up aggregation of segment data and top-down validation against macroeconomic indicators across the analysis window. Segmentation dimensions modeled included product type, end-user, distribution channel, packaging type, and regional regulatory frameworks. CAGRs were derived from historical growth trends, technological advancements, and anticipated regulatory shifts. Key forecast inputs included global protein consumption trends and raw material price forecasts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen geopolitical events. All forecasts reflect assumptions regarding raw material stability and consistent regulatory enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Milk Powder for Pregnant Women Market
Nutritional Supplements
Fucoidan Market
Nutritional Supplements
Collagen Supplements Market
Nutritional Supplements
Asia-Pacific Nutraceutical Excipients Market
Nutritional Supplements
High-Selenium Yeast Market
Nutritional Supplements
Prenatal Supplements Market
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Dhea Supplement Market
Nutritional Supplements
Lion's Mane Market
Nutritional Supplements
Diet Shakes Market
Nutritional Supplements
North America Omega-3 Products Market
Nutritional Supplements
US Ketones Market
Nutritional Supplements
Green Supplement Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Plant Based Iron Supplements Market
Nutritional Supplements
Tea Tree Oil Market