
 Marine Seaweed Market | 2026-2036
Marine Seaweed Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Seaweed Market Analytics
Modular ingredient bundling is restructuring how nutraceutical buyers configure seaweed orders, shifting from single-species bulk contracts to blended powder portfolios with guaranteed polysaccharide profiles. Cargill Incorporated leverages its global agricultural supply infrastructure to secure long-term Ascophyllum harvesting rights in the North Atlantic. CP Kelco anchors its position through captive extraction technology for refined carrageenan and alginate derivatives. DuPont de Nemours competes via biotechnology investments in strain optimization for higher-yield kelp cultivation.
Marine seaweed comprises macroalgae species harvested from saltwater environments, containing structural polysaccharides such as alginates, carrageenans, and agars with molecular weights ranging from 10,000 to 600,000 Daltons, processed through washing, drying, milling, and solvent or mechanical extraction for use as gelling agents, thickeners, fertilizers, and bioactive compound sources. The food industry application dominates value capture due to established demand for hydrocolloid stabilizers in dairy and meat alternatives, while biofuels remain nascent with margin pools concentrated in pilot-scale third-generation ethanol projects. Laminaria and Porphyra product types lead volume throughput, though Ulva is gaining traction in aquaculture feed formulations where protein content commands premium positioning.
EU REACH and F-Gas Regulation frameworks constrain solvent-based extraction methods, while China's GB standards and SAMR oversight govern food-grade additive purity thresholds for domestic and export markets. The US FDA and USDA co-regulate seaweed imports through GRAS determinations and organic certification pathways, creating compliance complexity for multi-territory suppliers. Stakeholders must monitor evolving biosecurity protocols for wild harvest zones and assess captive cultivation investments against tightening wild-stock quotas.
Market Dynamics
The transition from solvent-based to cold-water mechanical extraction methods is restructuring processor capital allocation and procurement geography, as regulatory pressure on synthetic inputs intensifies across multiple jurisdictions.
Growth Catalysts
- EU F-Gas Regulation:Tightening restrictions on fluorinated extraction solvents are accelerating investment in mechanical cold-press systems across Atlantic processing facilities.
- Plant-based protein demand:Food manufacturers in East Asia are scaling Laminaria and Porphyra procurement for alternative meat and dairy stabilizer formulations.
- Jeolla aquaculture expansion:South Korea's government-backed coastal zones are increasing kelp cultivation acreage with subsidized infrastructure.
Market Restraints
- Wild-stock quota compression:Biosecurity protocols for North Atlantic Ascophyllum harvest zones are tightening annual allowable catch limits.
- Input cost volatility:Energy-intensive drying operations expose processors to natural gas price swings in European production clusters.
- Technical yield ceilings:Current strain optimization limits polysaccharide extraction efficiency below theoretical maximums for carrageenan recovery.
Strategic Opportunities
- Biofuel pilot scaling:Third-generation ethanol projects in coastal Norway are creating offtake agreements for kelp biomass previously discarded.
- Ulva feed premiumization:Aquaculture feed formulators are commanding price premiums for green macroalgae protein content in salmon diets.
- REACH solvent substitution:EU chemical safety frameworks are incentivizing supercritical CO2 extraction technology adoption with streamlined approval pathways.
Industry Challenges
- Phycologist talent scarcity:Specialized cultivation technicians with strain management expertise are concentrated in limited academic programs.
- Multi-territory compliance complexity:GRAS determinations, organic certification, and GB standard alignment create documentation bottlenecks for cross-border suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Seaweed Market |
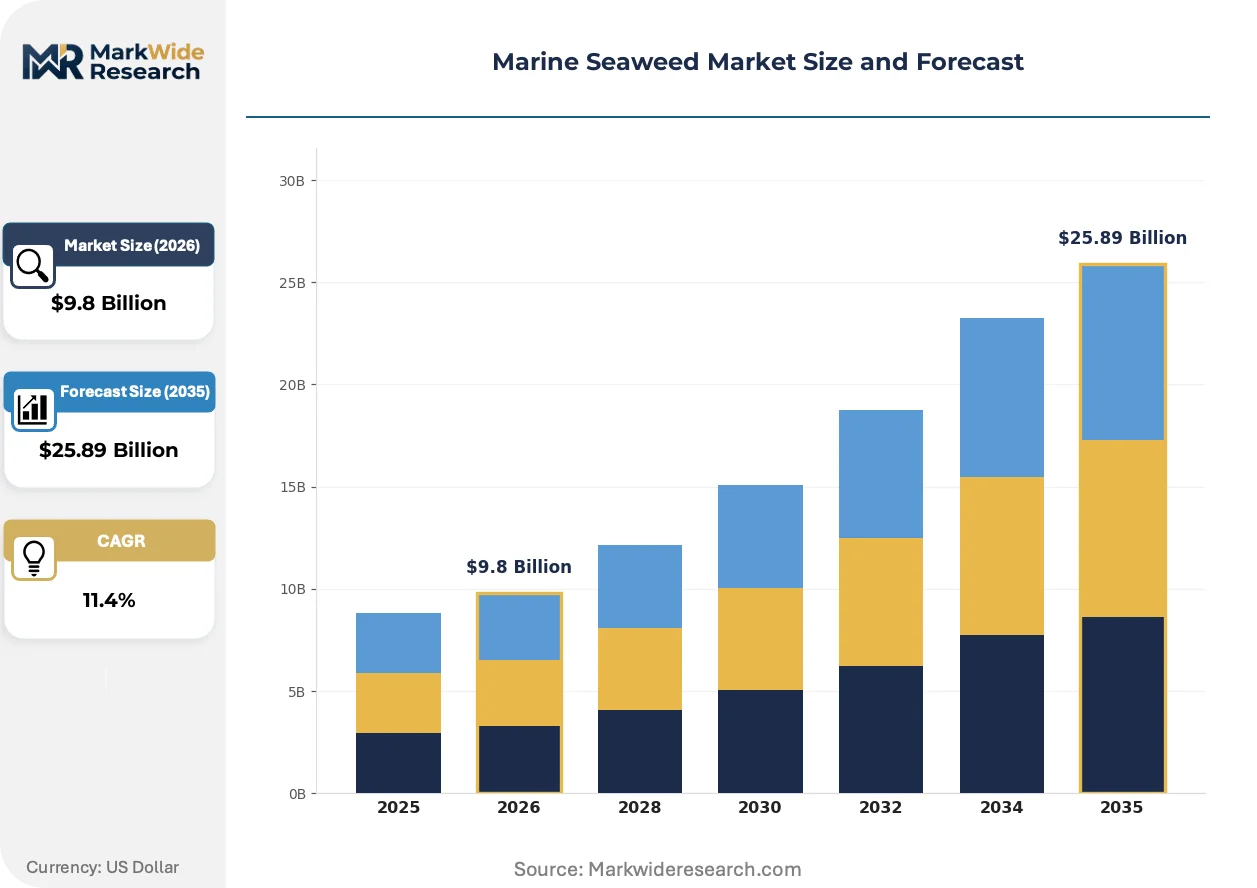
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ascophyllum, Laminaria, Porphyra, Ulva Application: Food Industry, Fertilizers, Cosmetics, Biofuels Form: Powder, Granules, Liquid Extract, Whole End User: Food Manufacturers, Nutraceuticals, Aquaculture, Pharmaceuticals |
| Companies Covered | Cargill Incorporated, CP Kelco, DuPont de Nemours, Gelymar, DSM, Algaia, Acadian Seaplants Limited, Ceamsa, Qingdao Bright Moon Seaweed Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Seaweed Market Evolving Landscape
Processing technology and procurement configuration are converging to reduce synthetic chemical dependence while fragmenting traditional bulk supply relationships into specification-driven contracts.
Supercritical CO2 extraction systems are automating the separation of bioactive fucoidans from Laminaria biomass without thermal degradation. Nutraceutical manufacturers in Germany and Japan are retrofitting existing facilities at pilot scale. This capital shift is automating quality consistency previously dependent on solvent batch variation, compressing the premium gap between wild-harvest and cultivated sourcing tiers.
REACH Annex XVII restrictions on halogenated solvents are forcing Atlantic processors to retire legacy extraction lines before depreciation cycles complete. The regulation's industrial consequence is a capital equipment replacement wave concentrated in Irish and Scottish processing clusters. Carrageenan refiners are responding by consolidating multi-species processing under single mechanical extraction platforms to spread capital recovery across alginate and agar product streams.
Ingredient buyers are unbundling long-term bulk contracts into quarterly specification tenders with guaranteed polysaccharide molecular weight profiles. Dairy alternative manufacturers in Denmark and the Netherlands are driving this shift, replacing annual Laminaria tonnage commitments with blended powder portfolios. This reconfiguration is most visible in Rotterdam and Hamburg trading corridors, where third-party certification laboratories are intermediating quality verification formerly handled by supplier relationships.
Marine Seaweed Market Segmentation
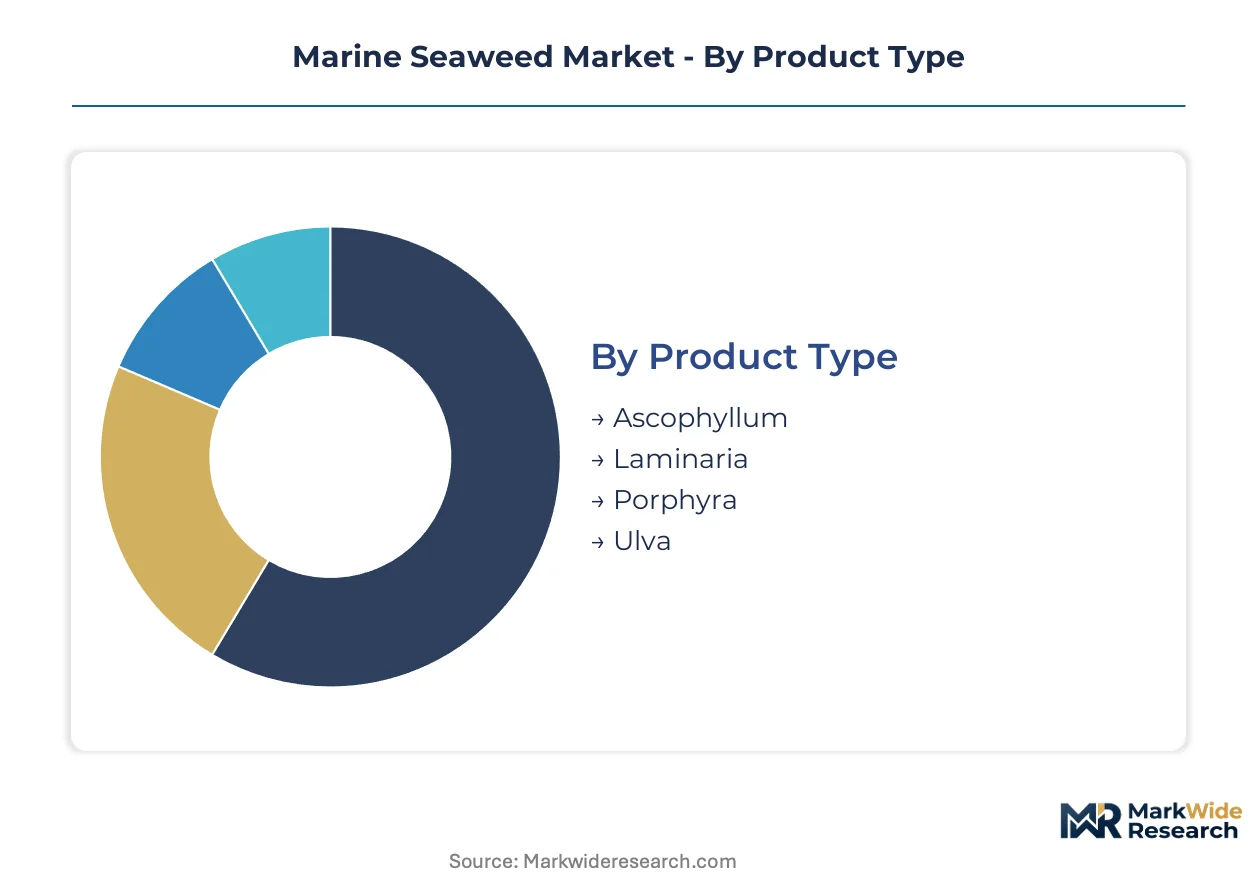
Seaweed procurement patterns diverge sharply between commodity bulk buyers and specification-driven formulators, with product chemistry and extraction method determining contract structures. Application-specific purity thresholds create tiered sourcing strategies that fragment what appears as a homogeneous biomass trade.
Product Type:
Some varieties function as standalone commodity inputs while others require embedded processing partnerships to unlock value.
- Laminaria:Brown kelp species containing alginates with molecular weights spanning 10,000 to 600,000 Daltons. Food manufacturers in South Korea's Jeolla coastal zone are scaling procurement for plant-based protein stabilizers, driven by government-subsidized aquaculture zone expansion.
- Porphyra:Red algae genus harvested for porphyran polysaccharides and protein content. East Asian food processors are concentrating orders for alternative meat and dairy formulation gelling agents, constrained by wild-stock quota compression in traditional harvest zones.
- Ascophyllum:North Atlantic brown algae with fucoidan bioactive compounds used in agricultural biostimulant formulations.
- Ulva:Green macroalgae gaining aquaculture feed traction where protein content commands salmon diet premiums.
Volume placements concentrate in Laminaria; the faster expansion belongs to Ulva.
Application:
Margin capture varies dramatically by processing depth, with hydrocolloid refinement commanding multiples over raw biomass offtake.
- Food Industry:Hydrocolloid stabilizers for dairy alternatives and meat substitutes. Danish and Dutch manufacturers are driving specification-tender procurement with guaranteed polysaccharide molecular weight profiles, replacing annual tonnage commitments.
- Fertilizers:Agricultural biostimulants and soil conditioners derived from Ascophyllum extracts. Norwegian coastal processors are securing offtake agreements for kelp biomass previously discarded from other extraction streams.
- Cosmetics:Bioactive compound applications in topical formulations with premium positioning.
- Biofuels:Third-generation ethanol pilot projects in coastal Norway creating nascent demand for carbohydrate-rich kelp varieties.
Food Industry maintains the dominant revenue share; Biofuels climbs the steepest expansion trajectory.
Form:
Processing intensity determines capital recovery cycles and customer switching costs across the value chain.
- Powder:Milled and dried biomass with standardized particle size for industrial formulation. Nutraceutical buyers in Germany and Japan are retrofitting facilities to handle blended powder portfolios with certified polysaccharide profiles.
- Liquid Extract:Solvent or mechanically extracted concentrates for high-purity applications. EU REACH Annex XVII restrictions on halogenated solvents are forcing Irish and Scottish processors to consolidate multi-species extraction under single mechanical platforms.
- Granules:Intermediate processing form for controlled-release agricultural applications.
- Whole:Unprocessed biomass for specialized aquaculture feed and traditional food preparation.
Powder commands the largest volume placement; Liquid Extract gains share fastest on premium positioning.
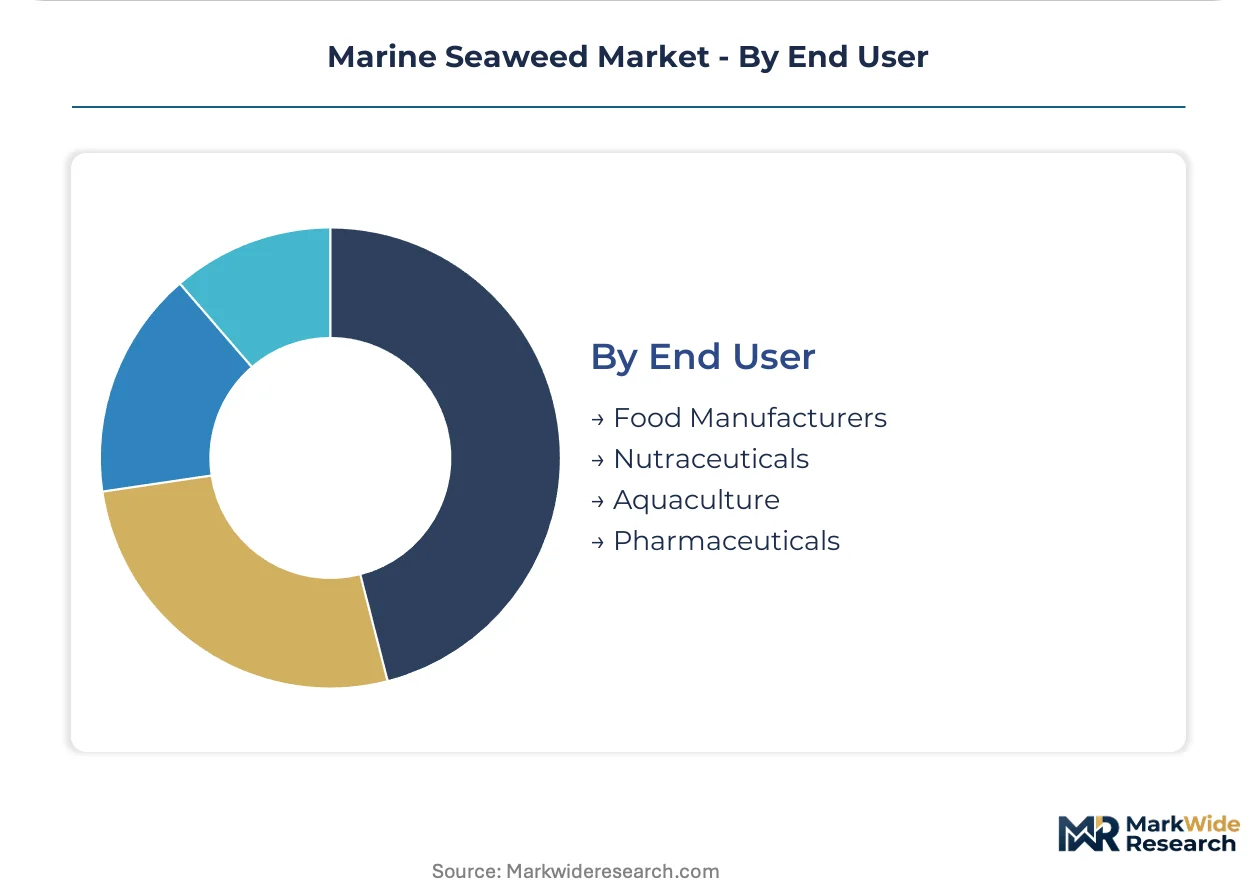
End User:
Procurement sophistication separates commodity biomass traders from specification-locked supply relationships.
- Food Manufacturers:Hydrocolloid buyers configuring quarterly specification tenders with third-party laboratory verification. Rotterdam and Hamburg trading corridors are intermediating quality assurance formerly handled through direct supplier relationships.
- Nutraceuticals:Bioactive compound formulators requiring guaranteed fucoidan and polysaccharide content. Supercritical CO2 extraction adoption is automating quality consistency previously dependent on solvent batch variation.
- Aquaculture:Feed formulators commanding price premiums for Ulva protein content in salmon diets.
- Pharmaceuticals:High-purity extract buyers with stringent compliance documentation requirements across FDA GRAS and EMA frameworks.
Food Manufacturers anchor volume demand; Nutraceuticals exhibits the steepest growth curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in cold-water coastal zones while consumption tilts toward East Asian food processing hubs and European nutraceutical formulators, creating distinct procurement corridors across the value chain.
South Korea
Jeolla coastal aquaculture zones are expanding kelp cultivation acreage through government-subsidized infrastructure programs. MFDS oversight governs food-grade additive purity thresholds for domestic processors and export markets. Wando and Haenam counties host the densest concentration of Laminaria mechanized harvesting operations, where cold-water mechanical extraction facilities are displacing legacy solvent-based systems.
China
Qingdao and Dalian processors dominate Porphyra refinement for plant-based protein stabilizers serving alternative meat formulators. GB standards and SAMR compliance requirements constrain extraction solvent specifications, pushing coastal facilities toward supercritical CO2 adoption. Shandong Peninsula clusters are consolidating multi-species processing platforms to spread capital recovery across alginate and agar product streams.
Norway
Coastal processors are securing offtake agreements for kelp biomass previously discarded from other extraction streams, feeding third-generation ethanol pilot projects. The country's national environmental regulator enforces stringent biosecurity protocols for wild harvest zones in Nordland and Trøndelag counties. Bergen-area extraction facilities are retrofitting for mechanical cold-press systems ahead of EU-aligned solvent restrictions.
Germany
Nutraceutical manufacturers in Hamburg and Bremen trading corridors are driving specification-tender procurement with guaranteed polysaccharide molecular weight profiles. ECHA REACH Annex XVII restrictions on halogenated solvents are forcing Irish and Scottish processors to consolidate extraction under single mechanical platforms, with German buyers intermediating quality verification through third-party certification laboratories.
United States
FDA GRAS determinations and USDA organic certification pathways create compliance complexity for multi-territory suppliers serving food and nutraceutical end users. Maine and Washington State host the primary Ascophyllum wild harvest operations, where tightening annual allowable catch limits are compressing supply availability. Boston-area biotechnology investments in strain optimization are targeting higher-yield kelp cultivation protocols.
Marine Seaweed Market Competitive Landscape
The competitive structure tilts toward diversified agricultural conglomerates with captive supply infrastructure and specialized hydrocolloid refiners with proprietary extraction technology. Three archetypes dominate: global agricultural traders securing long-term harvesting rights, captive extraction specialists controlling refined derivative production, and biotechnology investors optimizing cultivation yields. M&A activity concentrates on Atlantic harvesting rights consolidation, while capacity expansion focuses on mechanical cold-press retrofitting across European processing clusters.
Among North American agricultural conglomerates, Cargill Incorporated represents the integrated supply archetype through its global infrastructure reach. CP Kelco anchors the captive extraction specialist tier with concentrated technology ownership for refined carrageenan and alginate derivatives. DuPont de Nemours exemplifies the biotechnology investment vector, occupying a position in strain optimization for higher-yield kelp cultivation protocols. These three players illustrate the strategic divergence between supply control, processing depth, and biological innovation as competing vectors for margin capture.
| Leading Market Players |
|---|
| Cargill Incorporated |
| CP Kelco |
| DuPont de Nemours |
| Gelymar |
| DSM |
| Algaia |
| Acadian Seaplants Limited |
| Ceamsa |
| Qingdao Bright Moon Seaweed Group |
| Others |
Value Network & Pricing Analysis
North Atlantic Ascophyllum spot indices cascade through extraction processor margins into three-tier pricing structure across premium, standard, and economy levels, with cold-water mechanical methods commanding premiums over legacy solvent-based output as EU F-Gas Regulation compliance costs embed into contract structures.
Pricing Analysis
Margin tightening in standard-grade powder reflects energy-intensive drying cost exposure to natural gas price volatility across European production clusters. Price differentiation hinges on certified polysaccharide molecular weight profiles and third-party laboratory verification, with nutraceutical buyers least price-sensitive due to bioactive compound premiums while agricultural biostimulant formulators face acute cost-down pressure from commodity fertilizer alternatives.
Supply Chain Analysis
Refrigerated container freight rates from Jeolla coastal zones to Rotterdam and Hamburg trading corridors compress processor margins on transcontinental Laminaria shipments. Supply concentrates in South Korea, China, and Norway, with raw biomass flows drawing from government-subsidized aquaculture zones, wild harvest quotas in Nordland county, and Shandong Peninsula cultivation clusters. Single-source vulnerability concentrates in Ascophyllum wild-stock dependencies, while distribution runs through third-party certification laboratories intermediating quality verification formerly handled by direct supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical cold-press extraction technology is displacing solvent-based systems across Atlantic processing facilities, creating capital reallocation windows for stakeholders positioned ahead of REACH Annex XVII enforcement timelines.
For Market Incumbents: Cement long-term harvesting rights in North Atlantic zones before biosecurity protocols tighten annual allowable catch limits further. CP Kelco's captive extraction technology model demonstrates how proprietary carrageenan refinement platforms defend margin position against commodity biomass traders. Prioritize retrofitting Irish and Scottish facilities for multi-species mechanical extraction to spread capital recovery across alginate and agar product streams.
For New Entrants and Emerging Players: Direct-to-nutraceutical-manufacturer digital procurement platforms offer white-space entry around specification-tender intermediation previously controlled by Rotterdam and Hamburg trading corridors. Ulva aquaculture feed formulations present the most penetrable segment given salmon diet premiumization trends and limited incumbent cultivation expertise. Pursue supercritical CO2 extraction technology licensing as the go-to-market angle to bypass REACH solvent substitution barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Irish and Scottish processors with stranded solvent-based extraction assets facing premature depreciation under EU chemical safety frameworks. Long-term viability centers on backward integration into Jeolla-style government-subsidized aquaculture zones rather than wild-harvest quota dependence. Watch for fucoidan bioactive compound offtake agreement volumes from German nutraceutical manufacturers as the inflection signal for premium-tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Cold-Press Retrofitting | EU F-Gas Regulation compliance secures Atlantic processor operating licenses ahead of solvent phase-out deadlines. |
| Multi-Species Extraction Platform Consolidation | Irish and Scottish facilities spread capital recovery across alginate, carrageenan, and agar product streams simultaneously. |
| Jeolla Aquaculture Zone Partnership | South Korean government-subsidized infrastructure locks in Laminaria supply chains for plant-based protein stabilizer demand. |
| Supercritical CO2 Technology Licensing | German nutraceutical manufacturers automate fucoidan quality consistency without thermal degradation risks. |
| Third-Party Certification Laboratory Acquisition | Rotterdam and Hamburg intermediaries capture specification-tender verification fees from Danish dairy alternative formulators. |
Research Methodology
Trade flow databases, customs records, and ECHA REACH regulatory filings formed the secondary backbone, cross-referenced against primary interviews with extraction facility plant managers, aquaculture zone operators, nutraceutical procurement leads, and third-party certification laboratory directors. Bottom-up volume modeling triangulated against top-down value chain analysis anchored the market sizing framework.
Historical trendline analysis across cultivation acreage expansion, processing capacity utilization, and hydrocolloid price indices informed the projection methodology. Segmentation dimensions spanned macroalgae species, extraction method, application purity tier, and end-user procurement sophistication, with CAGRs derived from elasticity-adjusted demand curves and regulatory compliance cost trajectories. Strain optimization yield ceilings and biosecurity protocol tightening velocity served as industry-specific forecast modifiers.
The model holds under stable EU-China trade corridor access and gradual F-Gas Regulation enforcement; deviation in Atlantic wild-harvest quota compression velocity or natural gas price spike persistence would shift processor margin recovery timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Poultry Feed Market
Agriculture and Agri Products
Cattle Feed Concentrate Market
Agriculture and Agri Products
Corn Gluten Feed Concentrates Market
Agriculture and Agri Products
North America Palm Oil Market
Agriculture and Agri Products
Saudi Arabia Poultry Meat Market
Agriculture and Agri Products
Bamboos Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Egypt Compound Feed Market
Agriculture and Agri Products
Africa Olive Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Plant Breeding Market
Agriculture and Agri Products
Animal Feed and Pet Food Market
Agriculture and Agri Products
Alfalfa Hay Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
Africa Compound Feed Market