
 Plant Breeding Market | 2026-2036
Plant Breeding Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Breeding Market Intelligence
A significant divergence in genomic research and development investment is bifurcating the competitive landscape. Large-scale entities like Bayer CropScience leverage vast germplasm libraries and global distribution networks for major row crops such as corn and soy. In contrast, specialized firms such as Rijk Zwaan differentiate by focusing on high-value vegetable seeds for greenhouse and hydroponic systems. Corteva Agriscience sustains its market position through a combination of proprietary seed genetics and integrated crop protection solutions.
Plant breeding involves the science of altering plant traits to produce desired characteristics for agricultural or horticultural use. This process systematically employs techniques like marker-assisted selection to identify genes linked to drought tolerance, pest resistance, or enhanced nutritional value. While cereal crops constitute the largest volume segment, horticultural crops represent a higher-margin area due to consumer preferences for novel produce. Hybrid seeds continue to dominate commercial sales, offering significant yield advantages and trait uniformity over open-pollinated varieties.
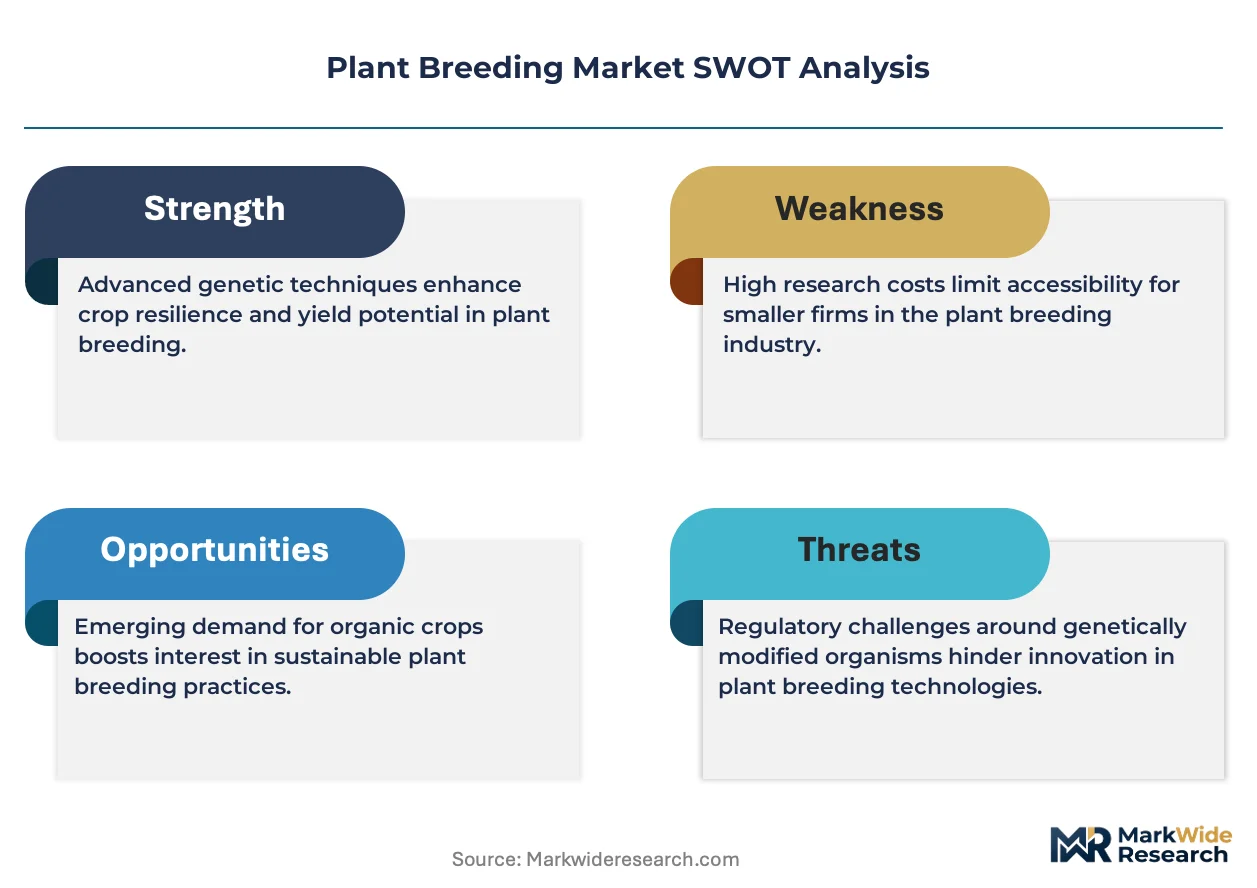
Regulatory frameworks governing genetically modified organisms create divergent market access conditions across key geographies. The USDA and FDA in the United States have established distinct pathways for gene-edited crops, while the European Food Safety Authority (EFSA) maintains a more stringent evaluation process. Stakeholder success will depend on navigating these fragmented regulatory approvals and aligning breeding programs with regional consumer acceptance and labeling requirements.
Market Dynamics
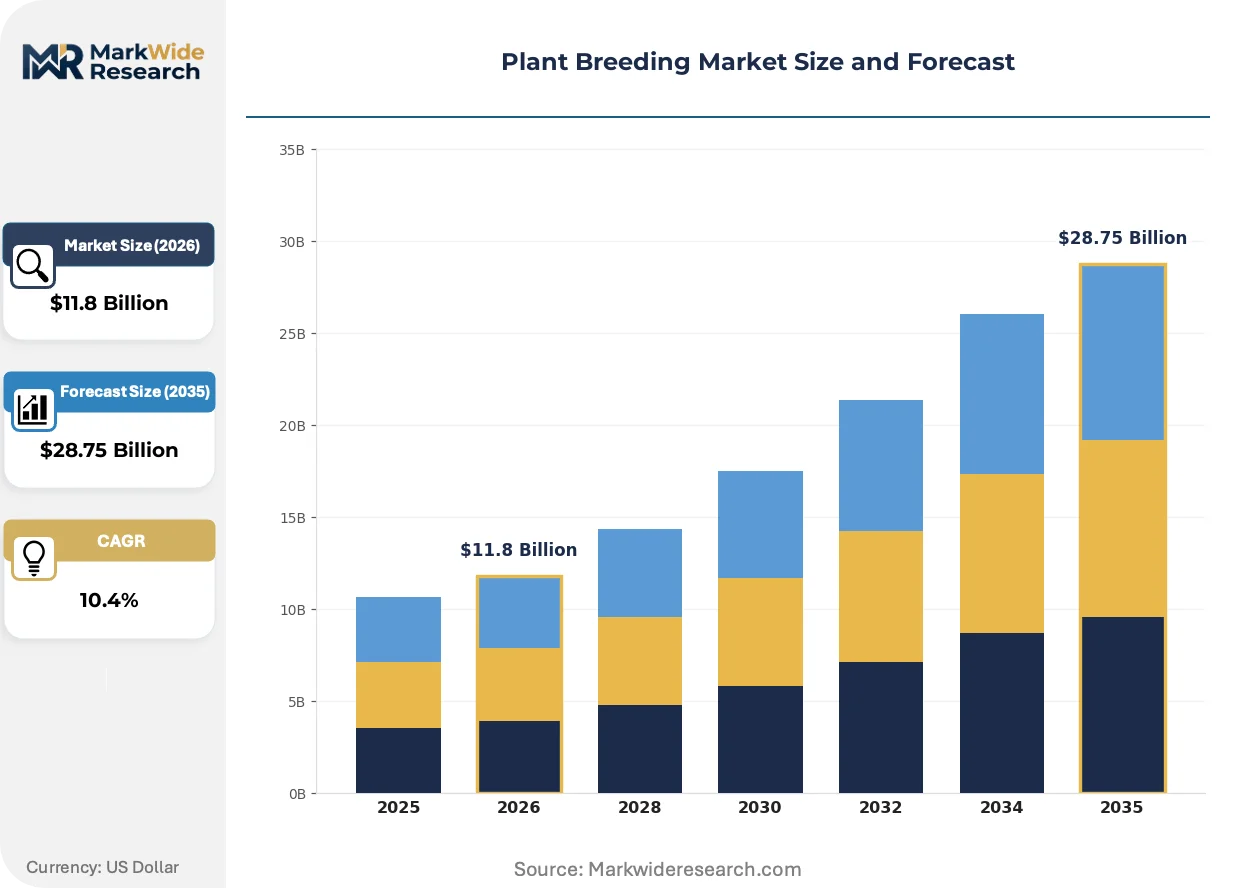
The central tension in plant breeding is the gap between rapid genomic innovation like CRISPR-Cas9 and fragmented regulatory frameworks. This divergence in policy across key agricultural economies like the United States and Europe shapes market access and investment strategy.
Growth Catalysts
- CRISPR-Cas9 Adoption:The widespread integration of gene editing tools accelerates the development of climate-resilient traits, such as drought tolerance in cereal crops, significantly shortening timelines compared to conventional methods.
- Controlled Environment Agriculture:Demand from vertical farms and greenhouses for specialized vegetable varieties with traits suited for hydroponic systems is creating high-value niches, particularly in the Netherlands and the United States.
- Bioeconomy Initiatives:Government policies promoting food security and sustainable agriculture, including elements of the EU Green Deal, provide incentives for research into advanced breeding techniques for reduced chemical inputs.
Market Restraints
- Asymmetrical Regulatory Hurdles:The stringent, process-based evaluation for new genomic techniques by the European Food Safety Authority (EFSA) creates significant market access friction compared to the product-based approach of the USDA.
- High R&D Investment:Substantial capital for genomic research, germplasm libraries, and multi-year field trials creates high barriers to entry, limiting participation to well-funded entities.
- Intellectual Property Thickets:The complex and often restrictive licensing landscape for foundational gene editing patents and genetic markers can impede research and increase the risk of costly litigation for innovators.
Strategic Opportunities
- Emerging Asian Markets:Countries like Vietnam and Indonesia present opportunities for introducing improved rice, corn, and vegetable varieties to boost domestic food production and meet agricultural export goals.
- Orphan and Specialty Crops:Breeding for niche crops like quinoa or amaranth offers high-margin potential away from saturated row crop markets, catering to evolving consumer dietary trends.
- AI-Powered Phenotyping:Integrating artificial intelligence with drone and sensor-based imaging to automate the analysis of plant traits in field trials offers a significant leap in efficiency and data accuracy.
Industry Challenges
- Bioinformatics Skill Gap:A shortage of data scientists and computational biologists able to manage and interpret massive genomic datasets is a primary operational bottleneck for breeding programs.
- Public Acceptance and Labeling:Navigating consumer skepticism around gene-edited foods, especially in Europe, demands significant investment in transparency and public education to achieve market acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Breeding Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $28.75 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Seeds, Open-Pollinated Seeds, Genetically Modified Seeds, Conventional Seeds, Tissue Culture Plants Breeding Technique: Marker-Assisted Selection, Genetic Engineering, Hybridization, Mutation Breeding, Genomic Selection Crop Type: Cereal Crops, Oilseeds, Horticultural Crops, Pulses, Forage Crops End User: Seed Companies, Agricultural Research Institutions, Contract Breeders, Crop Consultants |
| Companies Covered | Limagrain, Bayer CropScience, BASF SE, DLF Seeds, Enza Zaden, Syngenta AG, KWS SAAT SE, Rijk Zwaan, Corteva Agriscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Breeding Market Strategic Shifts & Innovations
The convergence of computational biology with high-throughput phenotyping is altering the speed and precision of varietal development. This integration transforms breeding from an empirical process into a more predictive science.
Predictive breeding uses genomic data and AI models to forecast crossbreed performance prior to field trials. Major seed developers are adopting this for complex traits in corn and soybeans. This data-driven approach is supplanting slower cycles of marker-assisted selection and empirical crossing.
Regulatory bodies are differentiating gene editing from genetic modification, seen in guidance from Argentina's CONABIA and Japan's MHLW. This creates a streamlined path to market for certain gene-edited crops lacking foreign DNA. R&D is consequently pivoting towards SDN-1 edits for specialty crops in these regions.
A shift toward trait-stacking contracts is emerging, where growers purchase seeds based on a guaranteed package of outcomes like pest resistance. This model replaces simple volume sales with integrated solutions bundling genetics and crop protection. This trend is most prominent in the commercial farming sectors of the United States and Brazil.
Plant Breeding Market Segmentation

The plant breeding market's segmentation reveals diverse approaches and applications driving agricultural innovation. Understanding these distinct segments is crucial for identifying areas of concentrated demand and technological advancement. This granular view highlights where investment in genetic improvement yields the most significant returns.
Product Type:
The diverse product types within plant breeding dictate distinct distribution channels, influencing market access and farmer adoption patterns across various regions.
- Hybrid Seeds:These seeds result from cross-pollinating two different parent lines, offering superior vigor, yield, and uniformity. Commercial sales dominate in corn, soybean, and vegetable sectors.
- Open-Pollinated Seeds:These varieties produce offspring true to type, allowing farmers to save and replant seeds.
- Genetically Modified Seeds:These contain DNA altered using genetic engineering, incorporating traits like herbicide tolerance or insect resistance. Adoption concentrates in the United States and Brazil.
- Conventional Seeds:Non-hybrid, non-GM seeds developed through traditional methods, serving cost-sensitive markets.
- Tissue Culture Plants:Produced via in vitro propagation, offering disease-free, uniform starts for high-value horticulture.
By volume, Hybrid Seeds lead the market. By growth pace, Genetically Modified Seeds are climbing the fastest.
Breeding Technique:
Different breeding techniques carry varying research and development costs, directly impacting final seed price and accessibility for growers across diverse agricultural landscapes.
- Marker-Assisted Selection:Uses DNA markers to identify desirable traits, accelerating selection in breeding programs.
- Genetic Engineering:Involves directly manipulating an organism's genes to introduce new traits or modify existing ones. Demand is high in countries with clear regulatory pathways, like the United States.
- Hybridization:Crossing two genetically different parent plants to combine desirable traits and achieve hybrid vigor.
- Mutation Breeding:Induces genetic variations using physical or chemical mutagens, from which desirable traits are selected.
- Genomic Selection:Predicts an individual's breeding value using genome-wide molecular markers, enabling faster, more accurate selection. Its application expands rapidly in corn and soybean.
Genetic Engineering techniques transform crop capabilities through precise trait introduction. Traditional Hybridization remains fundamental for broad-acre crop development.
Crop Type:
Crop types vary significantly in terms of cultivation volume, associated profit margins for breeders, and specific trait requirements from different agricultural regions.
- Cereal Crops:This category includes staple grains like corn, wheat, and rice, representing the largest volume segment. Breeding focuses on yield stability and disease resistance.
- Oilseeds:Crops like soybeans and canola are bred for oil content and disease resistance.
- Horticultural Crops:This segment includes fruits, vegetables, and ornamentals, characterized by high-value and diverse consumer preferences. Novel varieties for controlled environment agriculture drive R&D.
- Pulses:Legumes bred for nutritional value and drought tolerance, vital for sustainable agriculture.
- Forage Crops:Cultivated for animal feed, breeding focuses on biomass yield and nutritional quality.
Demand for Cereal Crops is driven by staple food requirements. Horticultural Crops respond to evolving consumer dietary trends and specialized production systems.
End User:
Different end-user segments require specialized product portfolios, technical support, and partnership models from plant breeders to meet their distinct operational needs.
- Seed Companies:These entities develop, produce, and market new plant varieties to farmers globally, forming the primary commercial channel. They invest heavily in R&D.
- Agricultural Research Institutions:Universities, government agencies, and non-profits conduct fundamental and applied research in plant genetics. They often develop foundational breeding lines.
- Contract Breeders:Offer specialized breeding services to clients, focusing on specific crops or traits under confidentiality.
- Crop Consultants:Advise farmers on variety selection and crop management, influencing seed purchasing decisions.
Seed Companies directly influence commercial seed supply. Agricultural Research Institutions drive foundational genetic innovation and public domain advancements.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global plant breeding markets exhibit diverse consumption patterns, with some regions prioritizing large-scale commodity crops while others focus on high-value specialty produce. The United States emphasizes yield and resilience in staple grains, contrasting with Europe's focus on horticultural innovations for controlled environments. This divergence influences R&D investment and market access strategies worldwide.
United States
Demand for advanced breeding techniques in the United States concentrates on corn, soybean, and cotton sectors. The USDA establishes distinct pathways for gene-edited crops, streamlining market entry. The Midwest agricultural belt, particularly Iowa and Illinois, drives significant investment in genomic selection for row crop varieties.
Netherlands
The Netherlands leads in demand for specialized vegetable varieties suited for hydroponic and greenhouse systems. The EU Green Deal provides incentives for advanced breeding techniques aligned with sustainable agriculture. Wageningen University & Research, a key cluster, fosters innovation in high-value horticultural crop development.
Brazil
Brazil's agricultural sector drives demand for improved soybean and corn varieties, essential for its position as a major global exporter. Regulatory frameworks for genetically modified seeds facilitate widespread adoption in commercial farming. The Mato Grosso region concentrates large-scale operations, implementing trait-stacking contracts for enhanced crop protection.
Vietnam
Emerging markets like Vietnam present opportunities for introducing improved rice and vegetable varieties to boost domestic food production. Government policies promote food security initiatives, encouraging research into climate-resilient traits. The Mekong Delta region, a critical agricultural hub, focuses on developing high-yield rice strains for export and local consumption.
Plant Breeding Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the plant breeding market. These large entities command significant germplasm libraries and extensive global distribution networks, particularly for major row crops. Strategic archetypes include diversified agricultural giants focused on broad-acre solutions and specialized horticultural innovators targeting high-value niche segments. The substantial capital required for genomic research and multi-year field trials creates high barriers to entry for new participants. Dominant competitive moves involve substantial R&D investment in genomic research and strategic partnerships for technology access and market expansion.
Within the diversified agricultural giants archetype, Bayer CropScience and Corteva Agriscience exemplify integrated crop solutions, anchoring market positions through proprietary genetics and extensive global reach. These entities often focus on major commodity crops, leveraging vast R&D budgets for trait development. In contrast, Rijk Zwaan occupies a specialized position, representing firms that differentiate by focusing on high-value vegetable seeds for controlled environment agriculture. Such specialists cater to specific consumer preferences and advanced cultivation systems.
| Leading Market Players |
|---|
| Limagrain |
| Bayer CropScience |
| BASF SE |
| DLF Seeds |
| Enza Zaden |
| Syngenta AG |
| KWS SAAT SE |
| Rijk Zwaan |
| Corteva Agriscience |
| Others |
Cost & Logistics Intelligence
Extensive capital investment in germplasm libraries and R&D operations creates significant economies of scale, shaping supply concentration and establishing high price floors for advanced breeding solutions. This structural dynamic favors large, integrated seed companies with broad market reach.
Pricing Analysis
Licensing and royalty fees for patented traits in hybrid and genetically modified seeds drive a significant portion of the lifetime value for breeders. The dominant pricing model is per-unit transactional, often bundled with value-added services like crop protection advice. Price differentiation stems from superior yield uniformity and specific climate-resilient traits. Pricing pressure arises from the high R&D investment required for novel trait development. Commercial farming operations in the United States typically exhibit lower price sensitivity for high-performance hybrid seeds compared to cost-sensitive markets for conventional seeds.
Supply Chain Analysis
Long lead times for varietal development, spanning multiple growing seasons, necessitate strategic inventory management for seed companies. Supply concentration for major row crops centers in the United States and Brazil, while specialized horticultural seed production is prominent in the Netherlands. The supply chain relies heavily on access to diverse germplasm collections and specialized genomic sequencing services. Regulatory fragmentation, particularly between the USDA and the EFSA, presents a structural supply chain risk. Distribution largely runs through direct sales channels to large agricultural enterprises and established agricultural cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plant breeding market operates with a defensive moat, primarily due to the regulatory entrenchment surrounding genetically modified and gene-edited crop approvals.
For Market Incumbents: Fortify intellectual property portfolios through aggressive patenting of novel gene-editing techniques and trait combinations. Pursue strategic acquisitions of specialized bioinformatics firms to integrate AI-powered phenotyping capabilities. This counters the threat from nimble biotech startups and enhances R&D efficiency. Invest heavily in germplasm collection and maintenance to maintain a foundational competitive advantage.
For New Entrants and Emerging Players: Differentiate on speed and precision in niche markets, such as high-value specialty crops or varieties optimized for controlled environment agriculture. Target regions with streamlined regulatory pathways for gene-edited crops, like Argentina or Japan, to accelerate market entry. A focused go-to-market angle involves offering outcome-based contracts for guaranteed trait performance, appealing to growers seeking specific solutions.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors entities with robust gene-editing platforms and extensive germplasm resources. The long-term viability of this sector is strong, driven by global food security demands and climate change adaptation. Identify acquisition targets specializing in bioinformatics, AI-driven phenotyping, or high-value horticultural breeding. The signal to watch is the broader harmonization of gene-editing regulations across major agricultural economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Genomic Research Capabilities | This initiative accelerates trait discovery, reducing development timelines for climate-resilient varieties. |
| Acquire Niche Horticultural Breeders | This broadens product portfolios, capturing high-margin segments like controlled environment agriculture. |
| Invest in AI-Powered Phenotyping Platforms | This enhances data accuracy and efficiency in field trials, optimizing varietal selection processes. |
| Develop Trait-Stacking Solutions | This provides integrated pest and disease resistance, offering comprehensive value to commercial growers. |
| Engage in Regulatory Harmonization Advocacy | This streamlines market access for novel gene-edited crops, reducing commercialization friction. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings and quantitative projections. Primary data collection involved conversations with plant breeders, seed company R&D directors, agricultural economists, and contract farmers. Secondary sources included USDA reports, EFSA guidance documents, academic journals, and company annual reports, triangulated using both bottom-up and top-down approaches.
Sensitivity analysis informs the analytical framework, which integrates historical market data with projected growth drivers across the analysis window. The quantitative model segments the market by product type, breeding technique, crop type, end-user, and regional regulatory environment. Compound Annual Growth Rates (CAGRs) derive from projected demand shifts and anticipated technological advancements, with key inputs including agricultural commodity prices and biotech R&D spending.
The analysis sits within stated boundaries; outcomes outside unforeseen regulatory shifts or major climate events would require recalibration. Forecasts reflect documented assumptions regarding technological adoption and market dynamics. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Date Palm Market
Agriculture and Agri Products
South Africa Agriculture Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Residential Organic Compost Market
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
Global Animal Feed Dietary Fibers Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Floriculture Market
Agriculture and Agri Products
Global Specialty Crop Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
United States Compound Feed Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
Global Palm Oil Market