
 Italy Alfalfa Market | 2026-2036
Italy Alfalfa Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Alfalfa Market Foresight
The EU Green Deal is recalibrating forage crop economics across Italian agriculture, tightening nitrogen-use efficiency benchmarks and elevating legume acreage requirements. Gruppo Carli leverages its vertically controlled dehydration network across northern Italy to secure consistent premium-grade supply. Caviro Forage anchors production in the Emilia-Romagna heartland with proprietary drying technology that preserves protein integrity. Agricole Forte S.a.r.l competes through specialized organic certification streams serving dairy cooperatives in the Po Valley.
Alfalfa comprises a perennial flowering legume of the Medicago sativa species, typically harvested at early bloom with crude protein ranging from 15% to 22% on a dry-matter basis and serving as the foundational protein and fiber source in ruminant nutrition systems. Dehydrated alfalfa dominates value capture through thermal processing that extends shelf life beyond twelve months while concentrating digestible nutrients for compound feed manufacturers. Alfalfa pellets represent the fastest-growing product configuration, driven by mechanized feeding systems among large-scale livestock producers seeking reduced labor and storage overhead. Animal feed applications command the deepest margin pools, with dairy farmers constituting the most quality-sensitive customer segment due to direct milk-yield correlation.
Italy's Ministry of Agricultural, Food and Forestry Policies enforces national quality standards for dehydrated forages, while the EU's Common Agricultural Policy cross-compliance rules shape planting subsidies and environmental performance thresholds for alfalfa growers. BIS equivalence protocols for non-EU imports and REACH-aligned feed additive regulations further structure competitive access for domestic versus foreign supply. Stakeholders must monitor evolving CAP conditionality requirements and water-usage restrictions in drought-prone southern regions to calibrate long-term varietal and irrigation investment decisions.
Market Dynamics
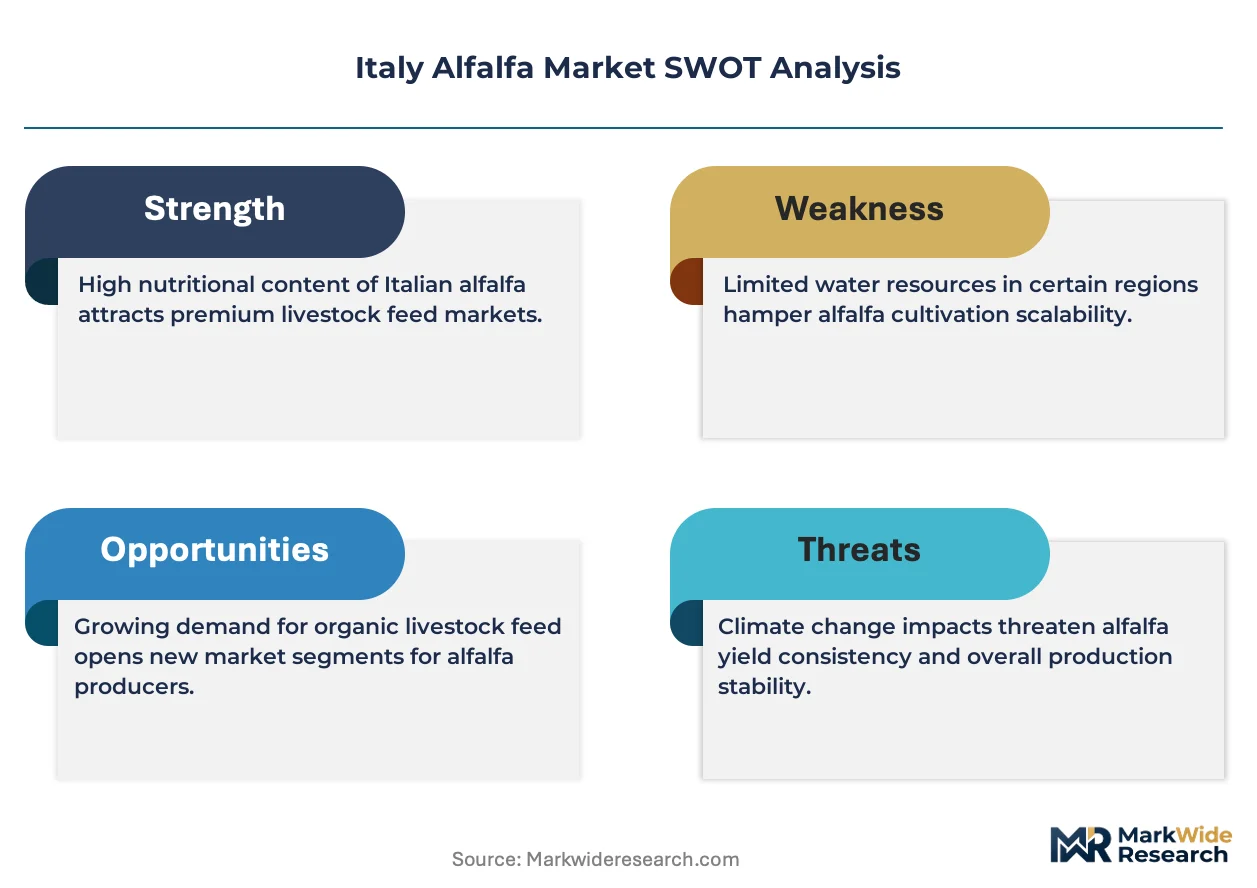
The EU Green Deal's Farm to Fork Strategy is recalibrating Italian forage economics, mandating nitrogen-fixing legume acreage expansion while tightening chemical input restrictions across the Po Valley dairy corridor.
Growth Catalysts
- EU Green Deal conditionality:The Farm to Fork Strategy mandates expanded legume cultivation in crop rotation schemes, directly elevating alfalfa acreage requirements for subsidy eligibility.
- Dairy sector protein demand:Lombardy and Emilia-Romagna dairy cooperatives are intensifying high-protein ration formulations to sustain milk yield benchmarks under tightening feed cost pressures.
- Po Valley irrigation infrastructure:Concentrated canal networks and pressurized systems enable consistent premium-grade alfalfa production with predictable protein content.
Market Restraints
- Water access volatility:Southern Italian regions face recurring drought cycles that constrain reliable alfalfa cultivation outside the irrigated northern corridor.
- Natural gas price sensitivity:Thermal dehydration operations remain exposed to energy input cost swings that compress processor margins during price spikes.
- Non-EU import equivalence:BIS protocols for North American and Middle Eastern alfalfa create administrative friction that delays competitive supply entry.
Strategic Opportunities
- Organic certification streams:CAP eco-scheme incentives reward conversion to organic forage production, opening premium pricing tiers for certified supply.
- Pellet mechanization adoption:Large-scale livestock operations are retrofitting feeding systems to handle densified alfalfa formats, reducing labor and storage overhead.
- Sicily and Apulia underpenetration:Southern regions with emerging irrigation investments represent expansion zones for drought-tolerant varietal deployment.
Industry Challenges
- Dehydration equipment capex cycles:Modern thermal processing lines require substantial capital commitment that strains mid-scale processor balance sheets.
- REACH-aligned feed additive documentation:Extended compliance timelines for novel preservation technologies delay product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Alfalfa Market |
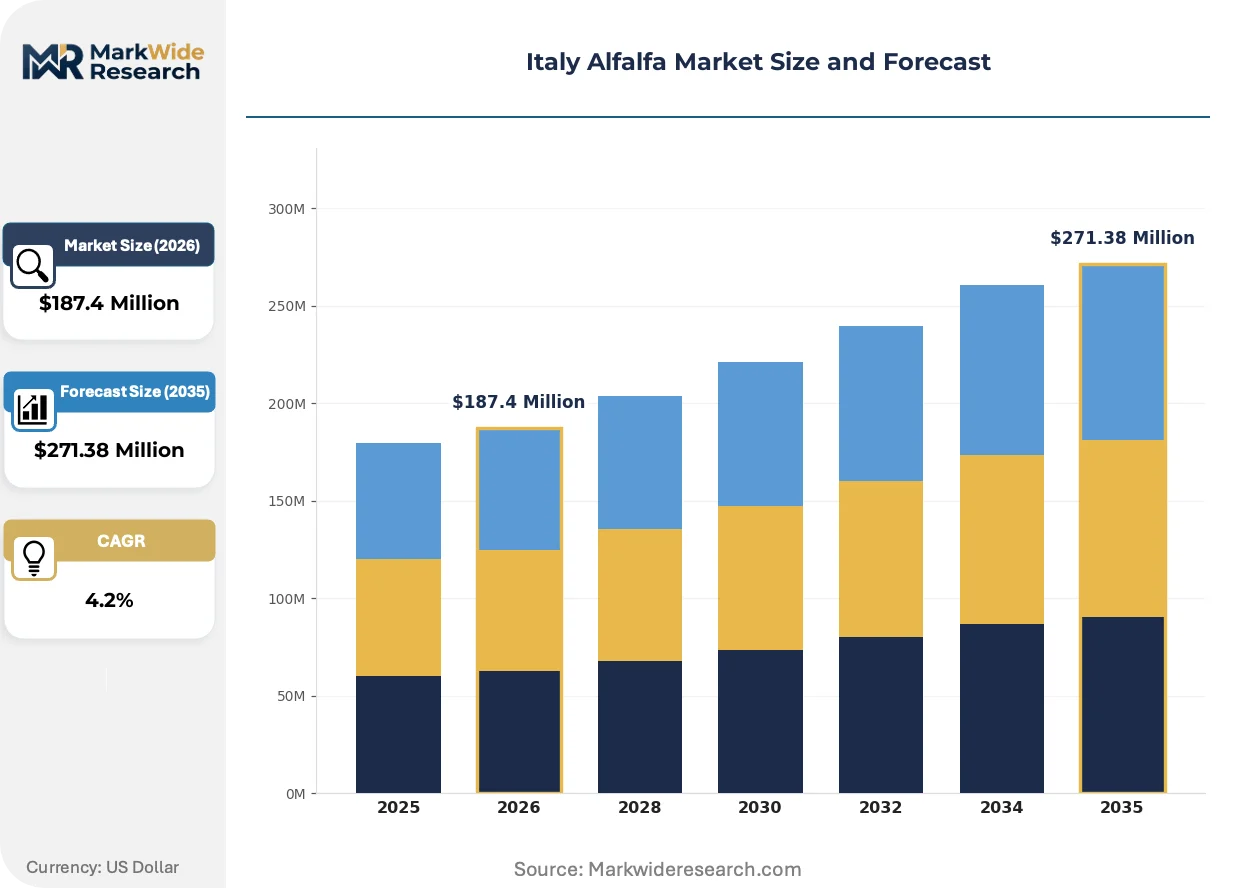
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $271.38 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dehydrated Alfalfa, Alfalfa Pellets, Alfalfa Cubes, Fresh Alfalfa Application: Animal Feed, Nutraceuticals, Horticulture, Soil Improvement Distribution Channel: Farmers' Markets, Online Retail, Agricultural Cooperatives, Wholesale Distributors Customer Type: Dairy Farmers, Livestock Producers, Organic Farmers, Commercial Growers |
| Companies Covered | Agricole Forte S.a.r.l, Caviro Forage (Caviro Group), Gruppo Carli, Italpaglia Srl, Gruppo Pagliari, Al Dahra ACX Global, Società Produzioni Erbe Disidratate, Vitagri Srl, Biselli Foraggi Group SRL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Alfalfa Market Shifts & Advancements
Italian alfalfa processing is undergoing mechanization and sustainability recalibration, with dehydration technology and regulatory compliance frameworks converging to reshape competitive positioning across the northern supply base.
Precision-controlled thermal dehydration systems are rewriting protein preservation economics in Italian forage processing. These systems modulate temperature curves to limit amino acid degradation while accelerating moisture removal. Large dairy cooperatives in Lombardy are retrofitting intake specifications to prioritize processor-deployed precision technology. The structural consequence is compressing margin capture toward operators with capital-intensive modernization capacity.
EU CAP cross-compliance rules are tightening environmental performance thresholds for nitrogen-use efficiency and crop rotation documentation. Italian growers must now maintain digital field records to verify legume acreage shares for subsidy retention. The dehydrated forage segment faces elevated audit intensity, with Emilia-Romagna processors investing in supply chain traceability systems to maintain cooperative contract eligibility.
Dairy sector buyers are consolidating procurement relationships around vertically integrated dehydration networks with certified organic streams. Traditional spot-market purchasing through agricultural brokers is contracting as large livestock operations seek volume guarantees and quality documentation. This behavioral shift concentrates contract value among processors with captive cultivation or long-term grower alliances, most visible across the Po Valley cooperative system.
Italy Alfalfa Market Segmentation
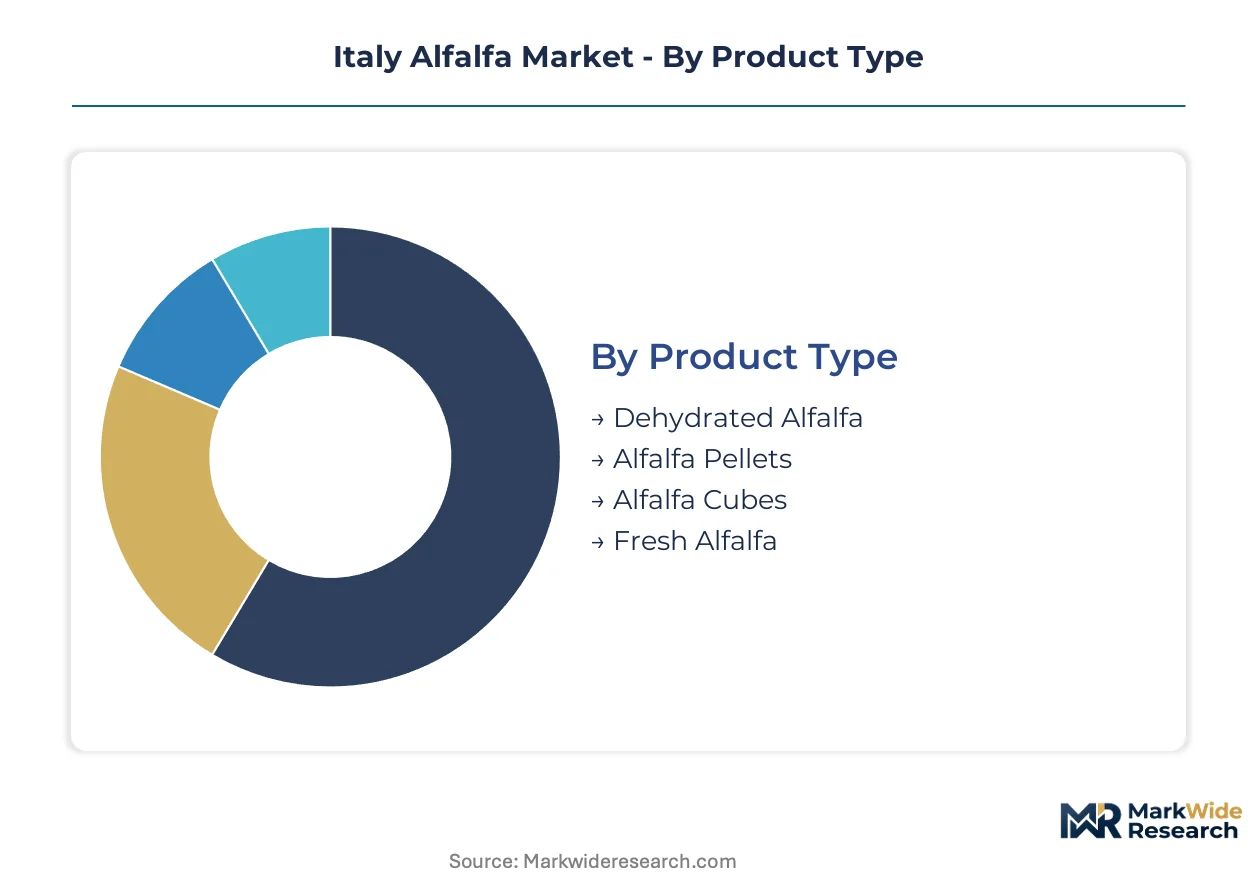
Italian alfalfa segmentation reflects divergent processing economics and buyer procurement sophistication. Product format selection directly determines shelf stability, handling costs, and protein preservation thresholds across the Po Valley dairy corridor.
Product Type:
Buyers differentiate primarily by storage duration requirements and mechanized feeding compatibility.
- Dehydrated Alfalfa:Thermal processing reduces moisture below 12% while concentrating crude protein to 18-22% dry-matter basis. Lombardy dairy cooperatives specify this grade for year-round ration formulation where consistent protein density sustains milk yield benchmarks.
- Alfalfa Pellets:Densified format reduces storage footprint by 60% versus baled hay and integrates with automated feeding systems. Large-scale livestock operations in Emilia-Romagna are retrofitting handling equipment to accommodate pellet flow characteristics, cutting labor overhead.
- Alfalfa Cubes:Compressed blocks with higher structural integrity than pellets suit outdoor storage conditions. Limited adoption concentrates among smaller operations with minimal mechanization.
- Fresh Alfalfa:Zero processing cost but 3-5 day harvest-to-feed window restricts use to on-farm cultivation or hyperlocal supply chains. Seasonal availability peaks constrain commercial scalability.
Dehydrated alfalfa leads volumes today; alfalfa pellets are gaining share fastest.
Application:
End-use economics split between commodity feed margins and premium extraction through functional ingredient positioning.
- Animal Feed:Dominant value pool serving ruminant nutrition systems with protein-fiber balance. Dairy farmers constitute the most quality-sensitive segment, with Po Valley cooperatives enforcing 18% minimum crude protein specifications for contract eligibility.
- Nutraceuticals:Chlorophyll, carotene, and saponin extraction for human dietary supplements commands 3-4x commodity pricing. Regulatory documentation burdens under EFSA novel food protocols constrain processor participation.
- Horticulture:Mulch and soil amendment applications leverage alfalfa's nitrogen-rich biomass. Organic vegetable growers in Sicily represent emerging demand nodes.
- Soil Improvement:Green manure and cover crop deployment accelerates rotation compliance under CAP eco-schemes. Agronomic value competes with direct cash crop returns.
Animal feed dominates revenue capture; nutraceuticals show the steepest expansion trajectory.
Distribution Channel:
Channel selection tracks buyer scale and quality documentation requirements.
- Agricultural Cooperatives:Vertically controlled procurement networks dominate volume flows across Lombardy and Emilia-Romagna. Members access pre-negotiated pricing and certified supply traceability.
- Wholesale Distributors:Aggregators serve mid-scale livestock producers outside cooperative catchment areas. Inventory risk concentrates with distributors during harvest-season price volatility.
- Farmers' Markets:Hyperlocal fresh alfalfa transactions serve hobby farms and small ruminant operations. Geographic fragmentation limits scalability.
- Online Retail:E-commerce penetration remains minimal for bulk forage due to freight economics. Seed and specialty supplement derivatives show modest traction.
Agricultural cooperatives anchor procurement volume; wholesale distributors are expanding fastest among non-cooperative buyers.
Customer Type:
Procurement sophistication separates price-takers from specification-enforcers.
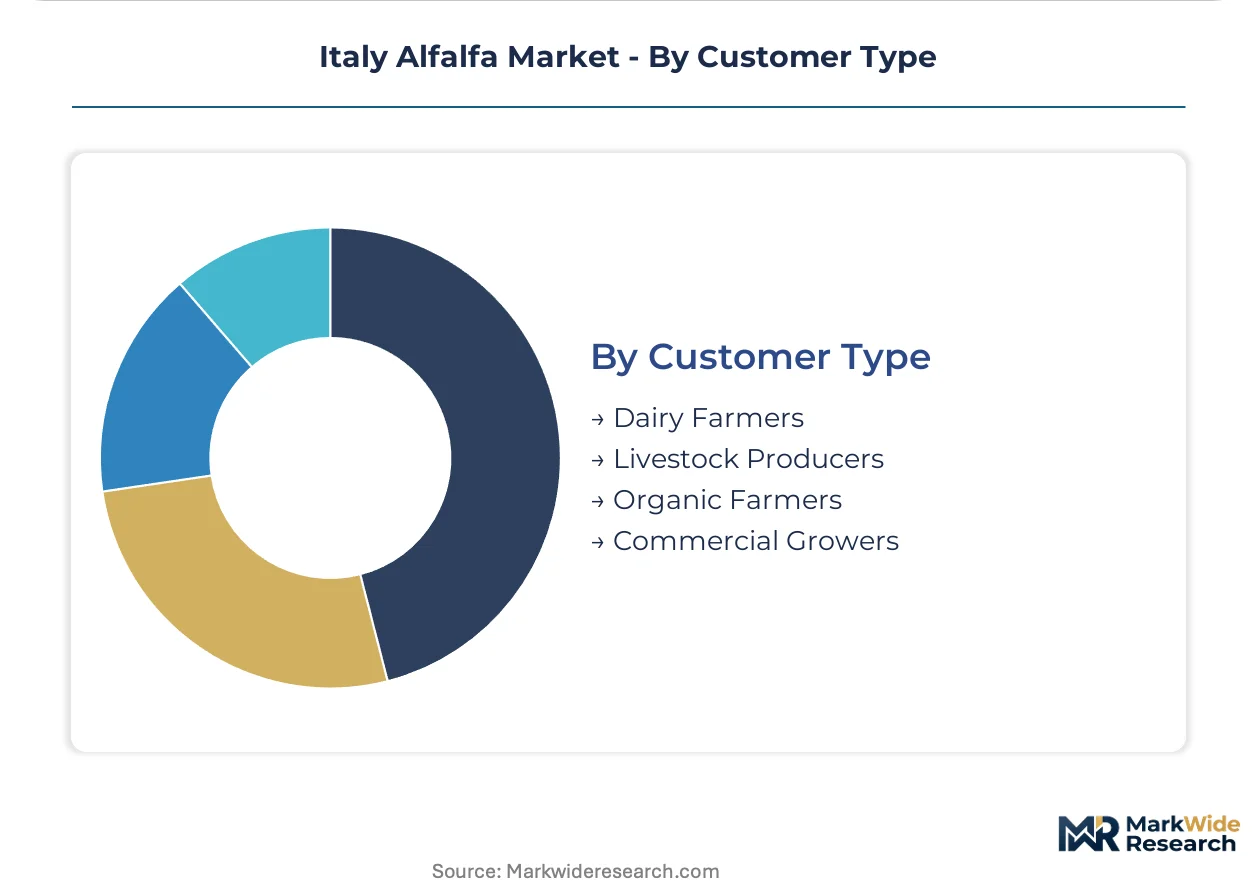
- Dairy Farmers:Most demanding segment with protein-content penalties and premiums written into supply contracts. Large Po Valley operations conduct pre-season processor audits of dehydration equipment.
- Livestock Producers:Beef and sheep operations prioritize cost efficiency over protein precision. Spot-market purchasing flexibility accommodates cash-flow timing.
- Organic Farmers:Certification-compliant supply commands 15-25% premiums. CAP eco-scheme conversion incentives are expanding this customer pool.
- Commercial Growers:Horticulture and seed multiplication operations purchase for on-farm use or resale. Volume concentration remains thin relative to livestock segments.
Dairy farmers drive premium-grade demand; organic farmers are expanding most quickly under CAP incentive structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled agronomists and dehydration technicians concentrate in the Po Valley corridor, anchoring Italy's premium-grade alfalfa production capacity and sustaining the country's competitive position in European forage markets.
Lombardy
Dairy cooperatives in the Milan-Brescia axis drive demand for 18-22% crude protein dehydrated alfalfa to sustain milk yield benchmarks. EU CAP cross-compliance rules mandate digital field records verifying legume acreage shares for subsidy retention. Gruppo Carli leverages its vertically controlled dehydration network across the region to secure consistent premium-grade supply for large-scale livestock operations.
Emilia-Romagna
Modena and Bologna processors anchor production with proprietary drying technology that preserves protein integrity for compound feed manufacturers. The EU Green Deal's Farm to Fork Strategy tightens nitrogen-use efficiency benchmarks, elevating legume requirements in crop rotation schemes. Caviro Forage maintains cooperative contract eligibility through supply chain traceability investments that satisfy audit intensity under evolving conditionality rules.
Piedmont
Turin-area livestock producers intensify high-protein ration formulations under tightening feed cost pressures, pulling dehydrated product from regional dehydration facilities. Italy's Ministry of Agricultural, Food and Forestry Policies enforces national quality standards that shape processor compliance investments. Concentrated canal networks and pressurized irrigation systems enable consistent premium-grade production with predictable protein content across the Alessandria-Asti corridor.
Veneto
Verona and Padua dairy operations retrofit feeding systems to accommodate densified alfalfa pellet formats, cutting labor overhead and storage footprint. REACH-aligned feed additive regulations structure competitive access for domestic versus foreign supply. Mid-scale processors face capital commitment strains from modern thermal processing line requirements, compressing margin capture toward operators with modernization capacity.
Sicily
Organic vegetable growers in the Catania-Palermo corridor represent emerging demand nodes for mulch and soil amendment applications leveraging alfalfa's nitrogen-rich biomass. Water access volatility from recurring drought cycles constrains reliable cultivation outside irrigated pockets. CAP eco-scheme conversion incentives reward transition to organic forage production, opening premium pricing tiers for certified supply from emerging southern irrigation investments.
Italy Alfalfa Market Competitive Landscape
The competitive structure tilts toward vertically integrated dehydration networks with captive cultivation or long-term grower alliances. Mid-scale processors without capital-intensive modernization capacity face margin compression as large dairy cooperatives consolidate procurement relationships around certified organic streams. Three archetypes dominate: cooperative-aligned processors with traceability systems, independent dehydration specialists serving spot markets, and import-dependent distributors navigating BIS equivalence protocols. Competitive moves center on backward integration into cultivation assets and technology licensing for precision-controlled thermal systems.
Within the cooperative-aligned tier, Gruppo Carli and Caviro Forage exemplify operators with vertically controlled supply networks across northern Italy. Agricole Forte S.a.r.l occupies a position among specialized organic certification streams serving dairy cooperatives in the Po Valley. These three entities represent the structural shift toward procurement consolidation around volume guarantees and quality documentation, displacing traditional spot-market purchasing through agricultural brokers. Their positioning reflects the broader industry trajectory where contract value concentrates among processors with certified organic capabilities and cooperative contract eligibility.
| Leading Market Players |
|---|
| Agricole Forte S.a.r.l |
| Caviro Forage (Caviro Group) |
| Gruppo Carli |
| Italpaglia Srl |
| Gruppo Pagliari |
| Al Dahra ACX Global |
| Società Produzioni Erbe Disidratate |
| Vitagri Srl |
| Biselli Foraggi Group SRL |
| Others |
Supply & Pricing Matrix
Skilled dehydration technicians and agronomists concentrate in the Po Valley corridor, and their scarcity outside this region widens pricing-tier spreads between premium-grade dehydrated product and standard hay alternatives. Labor-cost differentials between northern Italy's specialized workforce and southern regions' general agricultural labor pool feed directly into protein-content premiums commanded by Lombardy processors.
Pricing Analysis
Processing-plus-logistics bundling versus unbundled commodity hay sales splits the market into two pricing architectures. Three-tier pricing structure across premium dehydrated, certified organic, and standard hay levels tracks protein-content verification and CAP eco-scheme compliance documentation. Cost compression in standard-grade baled hay is intensifying because natural gas price spikes erode processor margins, while dairy cooperatives remain least price-sensitive due to milk-yield correlation with ration quality.
Supply Chain Analysis
Single-source vulnerability sits with natural gas suppliers feeding thermal dehydration operations across Emilia-Romagna and Lombardy. Cultivation concentrates in Italy's Po Valley corridor, with secondary sourcing from France and Spain under EU trade protocols. Supply chains draw from alfalfa seed stock, irrigation infrastructure, and fossil fuel energy inputs. Tariff exposure through BIS equivalence protocols for North American imports structures competitive access. Distribution runs through agricultural cooperatives with vertically controlled procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through precision dehydration technology adoption that cuts energy input costs while preserving protein premiums. Organic certification conversion under CAP eco-schemes opens additional pricing tiers for compliant supply.
For Market Incumbents: Acquire precision-controlled thermal dehydration assets to defend against margin compression from energy price volatility. Secure long-term grower alliances in the Po Valley to lock in premium-grade supply before cooperative procurement consolidation accelerates. Backward integration into certified organic cultivation streams captures CAP incentive flows. For New Entrants and Emerging Players: Launch via cooperative subcontracting arrangements serving dairy procurement networks in Sicily and Apulia where irrigation investments are expanding cultivable acreage. Target organic certification gaps in southern regions where CAP conversion incentives are expanding the certified supply pool. White-space exists in drought-tolerant varietal development for water-constrained cultivation zones. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale dehydration specialists without cooperative contract eligibility but possessing modernization-ready equipment bases. Long-term viability favors operators with captive cultivation or traceability systems that satisfy tightening EU CAP cross-compliance audit intensity. Watch for inflection when EU Green Deal nitrogen-fixing mandates tighten crop rotation requirements beyond current compliance thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Dehydration Technology Deployment | Energy-efficient thermal systems preserve protein integrity while cutting natural gas exposure for Lombardy processors. |
| Organic Certification Conversion Program | CAP eco-scheme incentives reward transition to certified forage production with premium pricing tiers. |
| Cooperative Procurement Consolidation | Large dairy operations concentrate contract value around processors with volume guarantees and traceability documentation. |
| Drought-Tolerant Varietal Development | Sicily and Apulia expansion zones require germplasm adapted to water access volatility outside irrigated northern corridors. |
| Supply Chain Traceability Investment | Digital field record systems satisfy EU CAP cross-compliance audit intensity for subsidy retention eligibility. |
Research Methodology
Coverage spans Lombardy, Emilia-Romagna, Piedmont, Veneto, and Sicily, with primary inputs from each region's dehydration facility operators and cooperative procurement managers. The approach combines interviews with dairy nutritionists, alfalfa growers, dehydration technicians, and compound feed manufacturers alongside secondary validation through Italy's Ministry of Agricultural, Food and Forestry Policies quality standards documentation, EU CAP implementation reports, and customs trade data. Bottom-up cultivation acreage estimates triangulate against top-down feed industry consumption surveys.
Granularity-level modeling captures product type splits across dehydrated, pelleted, cubed, and fresh formats; application segmentation between animal feed, nutraceuticals, horticulture, and soil improvement; and distribution channel flows through cooperatives, wholesale distributors, and direct farm sales. CAGRs derive from protein-demand elasticity models tied to dairy sector milk-yield benchmarks and CAP subsidy conditionality evolution across the projection horizon. Forecast inputs incorporate irrigation infrastructure development timelines and natural gas price scenario bands.
Several conditions sit outside the modeled scope, including extreme drought frequency beyond historical patterns, abrupt EU Green Deal nitrogen-use efficiency mandate acceleration, and geopolitical disruption to North American alfalfa import equivalence protocols. Forecasts reflect documented assumptions about cooperative procurement consolidation velocity and dehydration technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Asia Pacific Poultry Feed Market
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
Italy Animal Protein Market
Agriculture and Agri Products
Feed Protein Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
South America Animal Protein Market
Agriculture and Agri Products
Live Goods Market
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Organic Cassava Flour Market
Agriculture and Agri Products
Global Guayusa Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market