
 Bamboos Market | 2026-2036
Bamboos Market Size, Share, and Industry Trends Forecast 2026-2036
Bamboos Market Analysis
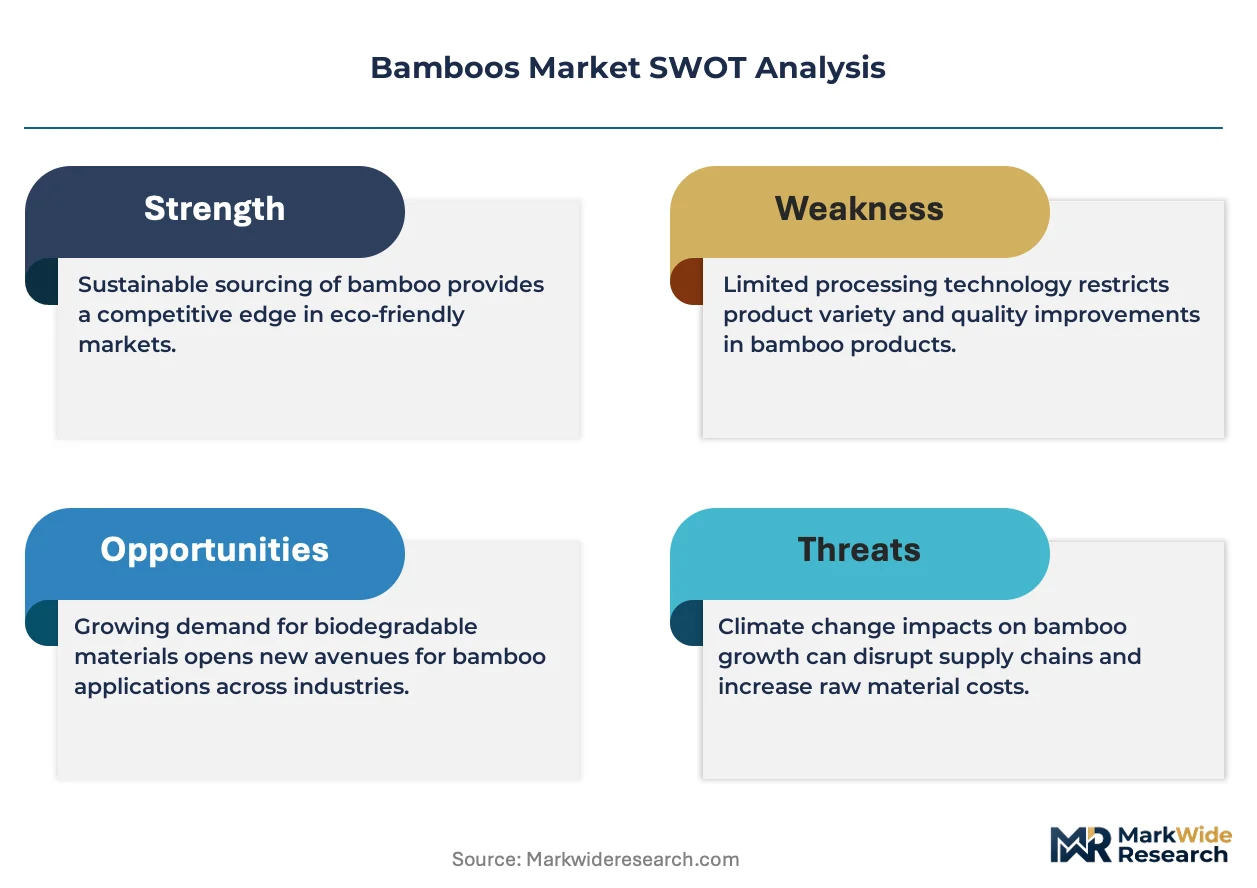
Forest Stewardship Council (FSC) certification for bamboo plantations is bifurcating supplier access in the European and North American trade corridors. MOSO International B.V. leverages its Dutch distribution hub to dominate engineered bamboo product flows into Germany and France. Dasso Industrial Group Co., Ltd. anchors its position through captive plantation assets in China's Zhejiang province. Smith & Fong Co. Inc. differentiates via proprietary strand-woven bamboo manufacturing technology that extends product density specifications beyond conventional plywood alternatives.
Bamboos comprise fast-growing perennial grasses from the Poaceae family, reaching structural maturity within three to five years with tensile strength comparable to steel by weight ratio, serving primarily as sustainable timber substitutes in load-bearing and decorative applications. Bamboo plywood and bamboo fiber command the widest industrial uptake, with plywood margins concentrating in construction-grade laminated formats while fiber applications in textiles show the steepest trajectory shift as apparel brands decouple from cotton-polyester blends. Bamboo charcoal retains a narrower but defensible niche in filtration and activated carbon markets where natural provenance commands wholesale premiums.
China's SAMR enforces GB/T standards for structural bamboo composites that determine export eligibility, while the EU Green Deal's embodied carbon tracking requirements for construction materials are reshaping import documentation burdens. The US EPA's formaldehyde emission regulations under TSCA Title VI directly govern bamboo panel products sold through American retail channels. Stakeholders must monitor evolving biogenic carbon accounting methodologies that will determine whether bamboo qualifies for green procurement tenders in public infrastructure programs.
Market Dynamics
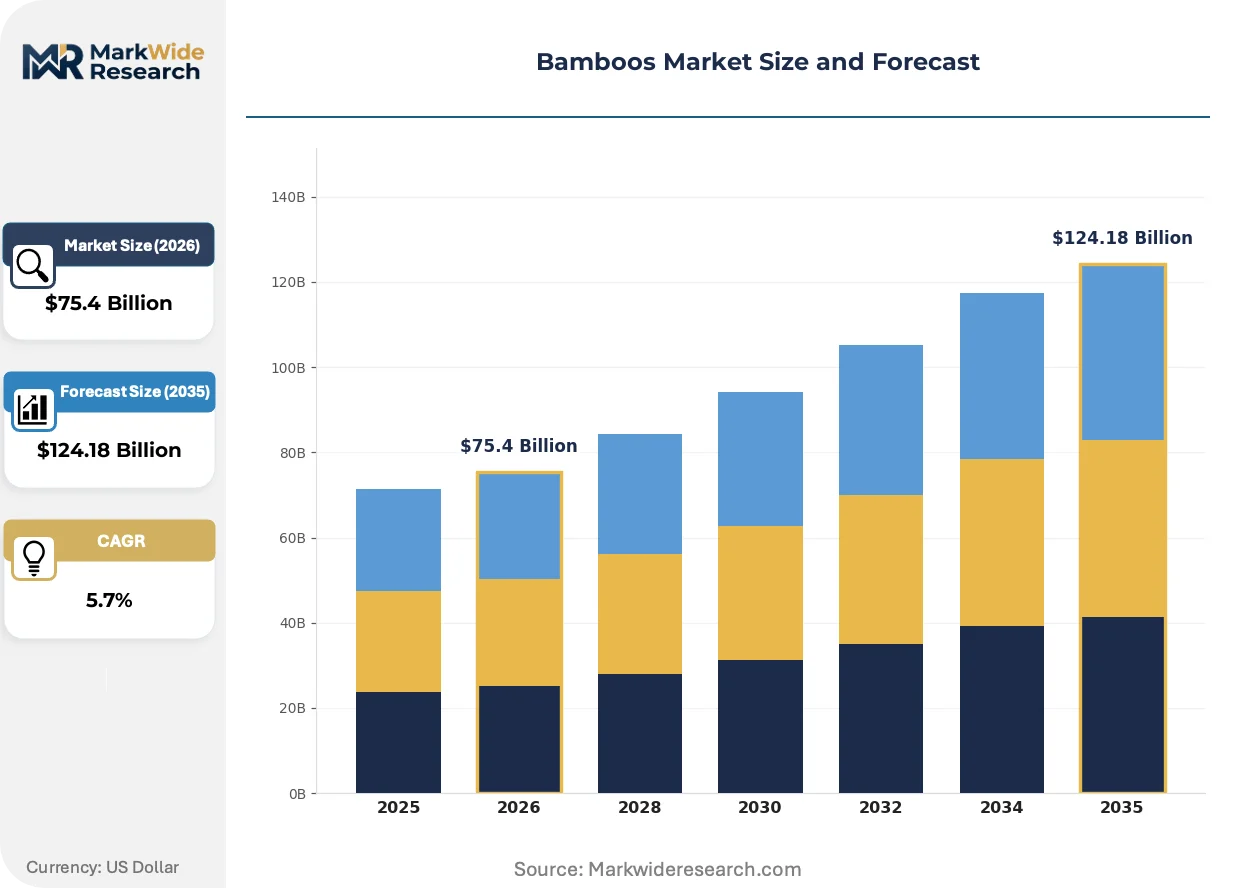
Engineered bamboo manufacturing is fragmenting as strand-woven density technologies compress traditional plywood margins while EU Green Deal carbon accounting rules rewrite import eligibility criteria for construction-grade panels.
Growth Catalysts
- EU Green Deal embodied carbon tracking:Construction material procurement rules in Germany and France now favor biogenic carbon-negative alternatives, pulling bamboo plywood into public infrastructure tenders.
- Textile fiber decoupling from cotton-polyester:Apparel brands in the Netherlands and Denmark are substituting bamboo viscose for conventional blends, creating parallel demand streams beyond construction.
- Mekong Delta supply concentration:Vietnam's raw bamboo cluster consolidation is shortening export processing lead times for European distributors.
Market Restraints
- Formaldehyde emission compliance costs:US EPA TSCA Title VI testing requirements for bamboo panels add certification overhead that disadvantages smaller Chinese exporters.
- Captive plantation dependence:Zhejiang province suppliers control premium moso bamboo genetics, creating germplasm access barriers for new market entrants.
- Steel-frame substitution resilience:Commercial developers in high-seismic zones retain structural steel specifications despite bamboo's tensile strength parity.
Strategic Opportunities
- Activated carbon filtration niche:Bamboo charcoal commands wholesale premiums in German water treatment applications where natural provenance displaces coconut-derived alternatives.
- FSC certification arbitrage:Plantation operators in Laos and Cambodia can capture European price premiums by securing chain-of-custody credentials that Chinese state forests lack.
- Cross-laminated timber hybridization:Austrian and Italian engineering firms are testing bamboo-CLT composite beams for mid-rise residential frames.
Industry Challenges
- Biogenic carbon methodology disputes:ISO 14067 lifecycle assessment protocols for perennial grasses remain unsettled, delaying green procurement tender eligibility.
- Strand-woven equipment capex intensity:Density compression machinery requires capital deployment that exceeds mid-tier plywood converter balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bamboos Market |
| Market Size in 2026 | $75.4 Billion |
| Market Size in 2035 | $124.18 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bamboo Charcoal, Bamboo Fiber, Bamboo Plywood, Bamboo Shoots Application: Construction, Furniture, Textiles, Food Industry End User: Retailers, Manufacturers, Exporters, Wholesalers Grade: Natural, Treated, Laminated, Composite |
| Companies Covered | MOSO International B.V., Bamboo Australia Pty. Ltd., Bamboo Village Company Limited, Shanghai Tenbro Bamboo Textile Co., Ltd., Dasso Industrial Group Co., Ltd., Smith & Fong Co. Inc., Anji Tianzhen Bamboo Flooring Co. Ltd., EcoPlanet Bamboo, Vietnam Bamboo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bamboos Market Emerging Trajectories
Strand-woven density engineering is compressing conventional laminated plywood economics while regulatory carbon accounting and procurement model evolution reshape competitive access across European and North American trade corridors.
Strand-woven bamboo manufacturing is fragmenting product density specifications beyond traditional plywood alternatives. Commercial developers in France and Germany are specifying 1,150 kg/m³ density panels for load-bearing applications. This density tier is compressing commodity plywood margins while creating premium pricing bands for certified plantation sources.
China's SAMR GB/T structural composite standards are tightening material specifications for export eligibility. The updated testing protocols disqualify lower-density laminated products from European construction material tenders. Vietnamese processors are responding by upgrading Mekong Delta facilities to meet the revised density and adhesive emission benchmarks.
Certification-driven specification is displacing grade-based procurement in Dutch and Danish public infrastructure tenders. Municipal buyers now mandate FSC chain-of-custody documentation alongside mechanical performance data. This behavioral shift is compressing spot-market purchasing for undifferentiated bamboo panels while extending contract durations for certified suppliers.
Bamboos Market Segmentation
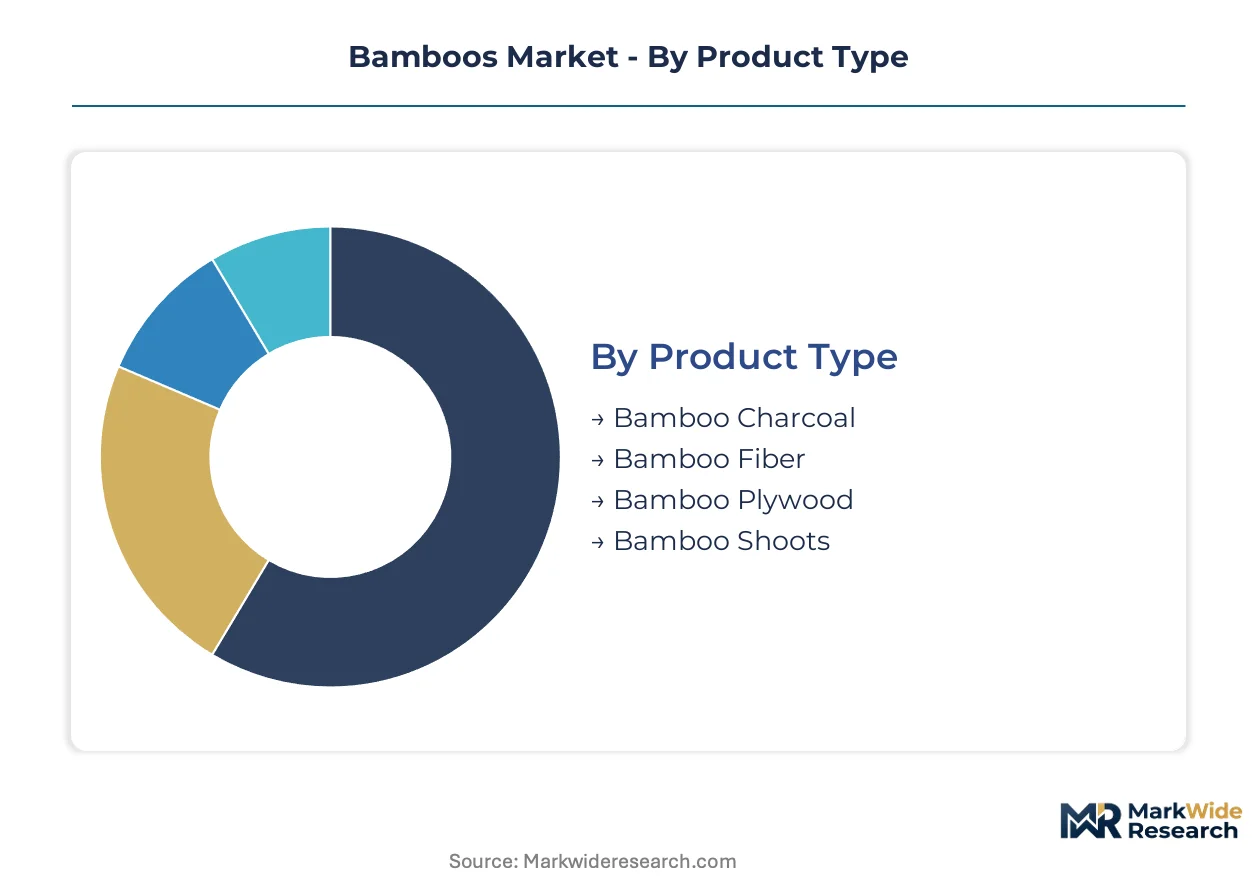
Product specifications, certification tiers, and channel structures fragment the bamboos market into distinct commercial battlegrounds. Each segmentation dimension carries different margin profiles, regulatory burdens, and geographic concentration patterns that determine competitive positioning.
Product Type:
Channel mix varies sharply across product categories: bamboo plywood and bamboo fiber flow through construction distributors and textile converters respectively, while bamboo charcoal and shoots occupy specialized wholesale channels with narrower buyer bases.
- Bamboo Plywood:Laminated structural panels manufactured from moso bamboo strips bonded under heat and pressure, achieving densities between 600-1,150 kg/m³ depending on processing intensity. Commercial developers in Germany and France specify high-density variants for load-bearing applications under EU Green Deal procurement rules. Construction-grade plywood dominates installed base. Bamboo fiber is where expansion concentrates.
- Bamboo Fiber:Viscose and lyocell derivatives extracted through chemical or mechanical processing of bamboo pulp, spun into yarns for apparel and technical textiles. Dutch and Danish apparel brands are substituting bamboo viscose for cotton-polyester blends, creating demand concentration in Northern European textile hubs.
- Bamboo Charcoal:Pyrolyzed bamboo biomass used in filtration, activated carbon, and agricultural applications, commanding wholesale premiums in German water treatment markets.
- Bamboo Shoots:Edible culm sprouts processed for canned, fresh, and fermented food applications, primarily consumed in East and Southeast Asian markets with limited Western penetration.
Bamboo plywood dominates installed base. Bamboo fiber is where expansion concentrates.
Application:
Cost tier stratification separates construction and furniture applications as premium-margin segments from textiles and food processing as volume-driven categories with thinner returns.
- Construction:Load-bearing panels, flooring systems, and facade cladding specified for mid-rise residential and commercial structures. Austrian and Italian engineering firms are testing bamboo-CLT composite beams, extending structural applications beyond conventional plywood formats.
- Furniture:Interior fittings, cabinetry, and decorative surfaces targeting hospitality and residential markets. MOSO International B.V. channels engineered bamboo products through Dutch distribution hubs into German and French furniture manufacturers.
- Textiles:Apparel, home furnishings, and technical fabrics utilizing bamboo-derived fibers. Apparel brands in the Netherlands and Denmark are decoupling from cotton-polyester blends, pulling bamboo viscose into mainstream textile supply chains.
- Food Industry:Processed shoots for canned goods, fresh retail, and fermented products, concentrated in Asian consumption markets with limited export premium capture.
Construction commands premium pricing tiers. Textiles represent the steepest volume trajectory shift.
End User:
Customer type determines contract structure: manufacturers and exporters operate on long-term supply agreements with certification requirements, while retailers and wholesalers transact on spot markets with shorter cycles.
- Manufacturers:Industrial processors converting raw bamboo into engineered products, textiles, or food derivatives. Zhejiang province suppliers control captive plantation assets, creating germplasm access barriers for new market entrants.
- Exporters:Trade intermediaries consolidating Mekong Delta raw material flows for European and North American destinations. Vietnamese processors are upgrading facilities to meet revised GB/T density and adhesive emission benchmarks.
- Retailers:Consumer-facing channels for finished bamboo goods including home improvement stores and specialty outlets.
- Wholesalers:Bulk distributors serving secondary manufacturers and regional construction markets.
Manufacturers dominate value capture. Exporters are where supply chain consolidation concentrates.
Grade:
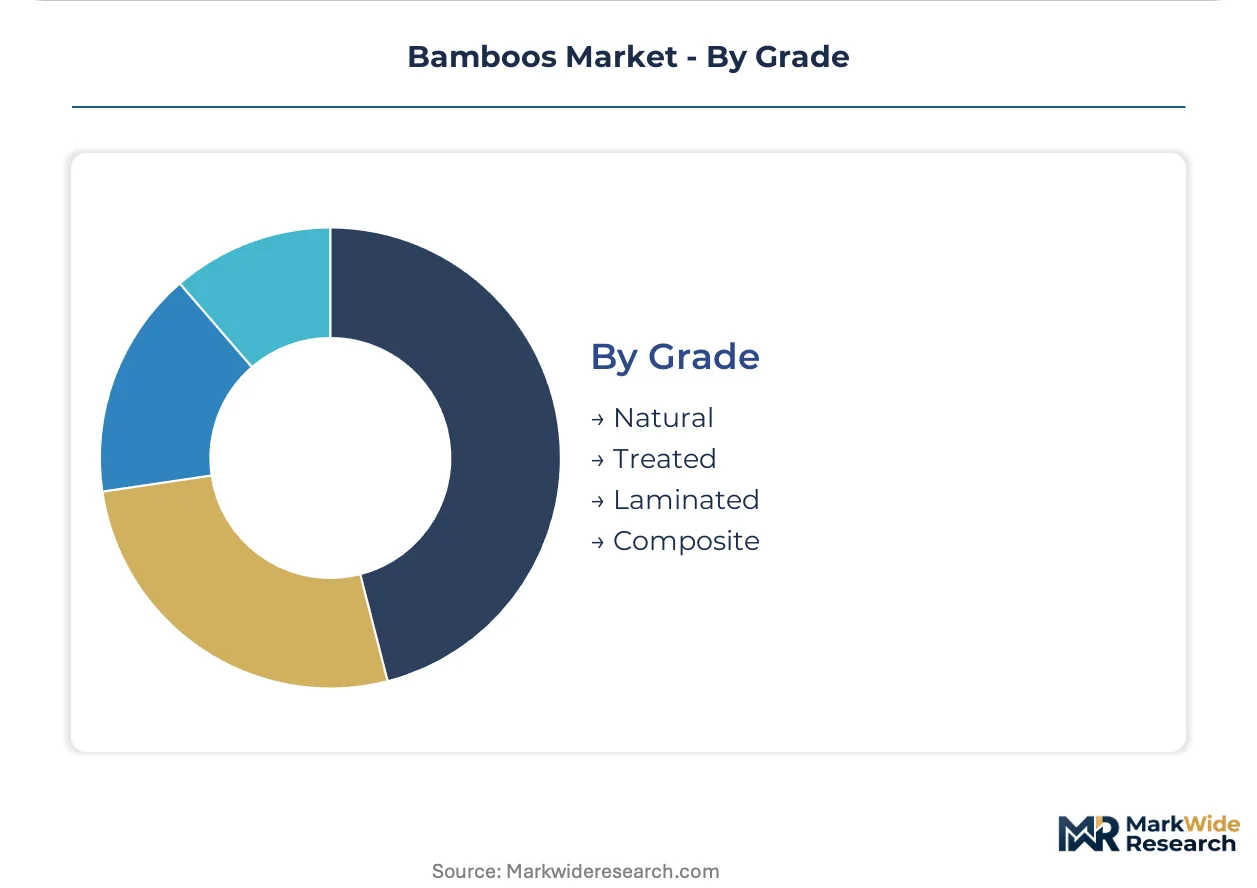
Volume distribution skews toward treated and laminated grades as industrial applications displace raw natural bamboo in commercial specifications.
- Laminated:Cross-layered bamboo strips bonded into structural panels, the standard format for construction-grade applications with established testing protocols under China's SAMR GB/T standards.
- Composite:Strand-woven density-engineered products achieving 1,150 kg/m³ specifications, compressing conventional plywood margins while creating premium pricing bands for certified plantation sources.
- Treated:Chemically or thermally modified bamboo for durability and pest resistance, widely specified in outdoor and high-humidity applications.
- Natural:Unprocessed or minimally processed culm sections, retaining niche demand in artisanal and decorative applications with limited industrial scale.
Laminated grade dominates installed base. Composite grade is where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public infrastructure procurement offices in Germany and France command premium pricing for certified bamboo plywood, while Dutch and Danish textile converters drive parallel demand for bamboo viscose fiber. Commercial developers in these markets specify biogenic carbon-negative materials under EU Green Deal construction rules.
China
Zhejiang province suppliers control captive moso bamboo plantations, creating germplasm access barriers for new market entrants. The State Administration for Market Regulation enforces GB/T structural composite standards that determine export eligibility to European construction tenders. Anji County in northern Zhejiang anchors engineered bamboo manufacturing clusters serving German and French distributors.
Germany
Municipal procurement offices in Bavaria and North Rhine-Westphalia mandate FSC chain-of-custody documentation for bamboo panels in public infrastructure. The EU Green Deal's embodied carbon tracking requirements favor biogenic carbon-negative construction materials. Cologne and Düsseldorf distribution hubs channel certified plywood into mid-rise residential developments.
Vietnam
Mekong Delta processors concentrate raw bamboo supply chains for European export, shortening lead times for Dutch distributors. Upgraded facilities in An Giang and Dong Thap provinces meet revised GB/T density and adhesive emission benchmarks. Vietnamese exporters capture contract durations from German municipal buyers seeking certified plantation sources.
Netherlands
Apparel brands in Amsterdam and Rotterdam decouple from cotton-polyester blends, pulling bamboo viscose into mainstream textile supply chains. MOSO International B.V. leverages its Dutch distribution hub to dominate engineered bamboo product flows into Germany and France. Rotterdam port infrastructure supports consolidated import processing for construction-grade panels.
United States
Commercial developers in California and Pacific Northwest states specify bamboo panels for hospitality and residential interiors despite steel-frame retention in high-seismic zones. The EPA's TSCA Title VI formaldehyde emission regulations govern bamboo panel products sold through American retail channels. West Coast distributors absorb certification overhead that disadvantages smaller Chinese exporters.
Bamboos Market Vendor Landscape
Player mix skews toward integrated plantation operators and specialized engineered product manufacturers. The vendor base separates into three tiers: captive plantation holders controlling premium germplasm, density technology specialists commanding premium pricing bands, and commodity converters facing margin compression from strand-woven competition. Competitive moves concentrate on FSC certification acquisition and Mekong Delta facility upgrades to meet EU import eligibility.
Among plantation-integrated operators, Dasso Industrial Group Co., Ltd. and MOSO International B.V. exemplify the captive supply archetype, while Smith & Fong Co. Inc. occupies a position within the technology-differentiated tier. These three entities represent distinct competitive vectors: Zhejiang-based plantation control, Dutch distribution hub leverage, and proprietary manufacturing process positioning respectively.
| Leading Market Players |
|---|
| MOSO International B.V. |
| Bamboo Australia Pty. Ltd. |
| Bamboo Village Company Limited |
| Shanghai Tenbro Bamboo Textile Co., Ltd. |
| Dasso Industrial Group Co., Ltd. |
| Smith & Fong Co. Inc. |
| Anji Tianzhen Bamboo Flooring Co. Ltd. |
| EcoPlanet Bamboo |
| Vietnam Bamboo Corporation |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day export processing lead times from Mekong Delta facilities to Rotterdam distribution hubs concentrate pricing power with integrated plantation operators who control both germplasm access and density-certification compliance. This lead-time band tightens when EU Green Deal carbon-accounting documentation requirements extend customs clearance protocols, forcing smaller converters to absorb margin compression or exit certified-panel segments entirely.
Pricing Analysis
Cost-plus contracts with adhesive-resin indexation dominate construction-grade plywood procurement between Vietnamese processors and German municipal buyers. Price differentiation hinges on FSC chain-of-custody certification and GB/T density-tier compliance, with certified composite panels commanding substantial premiums over commodity laminated grades. Cost compression in standard-density plywood is intensifying as strand-woven machinery upgrades in Zhejiang province expand high-density supply. Retail channel buyers exhibit highest price sensitivity, while public infrastructure procurement offices prioritize certification tier over unit cost.
Supply Chain Analysis
Strategic stockpiling of moso bamboo culm inventories characterizes Zhejiang province plantation operators, whereas Mekong Delta processors run lean just-in-time raw material cycles tethered to harvest seasons. Supply concentration centers on China, Vietnam, and Laos as primary raw bamboo sources. The chain rests on phenol-formaldehyde adhesive resins, strand-woven compression equipment, and FSC certification audit services. Single-source vulnerability pervades premium germplasm access. Distribution runs through Dutch hub-and-spoke networks serving German and French construction distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal procurement rule fragmentation creates niche entry points for certified plantation operators and density-technology specialists outside established Zhejiang supply clusters. Divergent national implementation timelines for biogenic carbon accounting generate arbitrage windows across member-state tender markets.
For Market Incumbents: Compound FSC certification coverage across captive plantation assets to defend margin position against emerging Lao and Cambodian entrants pursuing chain-of-custody arbitrage. Extend backward integration into phenol-formaldehyde adhesive blending to neutralize resin cost volatility. Prioritize Mekong Delta facility upgrades to capture contract durations from Dutch distributors consolidating European import flows. For New Entrants and Emerging Players: Anchor in Laos and Cambodia plantation development to exploit certification premiums that Chinese state forests cannot access. Target German municipal infrastructure tenders where FSC documentation now supersedes grade-based procurement. Pursue go-to-market partnerships with Rotterdam port consolidators to bypass established Zhejiang distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from European construction-material conglomerates divesting non-core bamboo panel divisions amid portfolio rebalancing toward engineered timber. Five-to-ten-year viability favors operators with integrated plantation-to-panel control and GB/T export compliance infrastructure. Watch for ISO 14067 methodology settlement as inflection signal triggering green procurement tender eligibility acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Certification Acquisition | Chain-of-custody credentials unlock German and French public infrastructure tender access. |
| Strand-Woven Equipment Deployment | Density compression machinery captures premium pricing bands above commodity plywood tiers. |
| Mekong Delta Facility Upgrade | GB/T compliance investments shorten export lead times for Rotterdam distribution hubs. |
| Backward Integration into Adhesive Resins | In-house phenol-formaldehyde blending neutralizes input cost volatility from petrochemical suppliers. |
| Bamboo-CLT Composite Development | Austrian and Italian engineering partnerships extend structural applications into mid-rise residential frames. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plantation managers, engineered product manufacturing executives, Dutch distribution hub operators, German municipal procurement officers, and textile converter sourcing leads. Secondary validation drew from China's SAMR GB/T standard filings, EU Green Deal procurement documentation, FSC chain-of-custody registries, and Vietnamese customs export records. Bottom-up volume modeling triangulated against top-down construction material spend analysis.
Across the analysis window, projections incorporate product type segmentation by density grade and certification tier, application segmentation across construction and textile end-uses, and geographic segmentation by plantation source and distribution hub concentration. CAGRs were derived from weighted average growth across these dimensions. Forecast inputs include EU member-state green procurement adoption curves and GB/T standard revision implementation timelines.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal enforcement and stable GB/T export eligibility criteria; material deviation would warrant model refresh. Revision becomes warranted when biogenic carbon accounting methodology disputes cross resolution thresholds or when Mekong Delta supply concentration triggers trade policy intervention.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
France Alfalfa Hay Market
Agriculture and Agri Products
Australia Animal Protein Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
Ghana Agriculture Market
Agriculture and Agri Products
North America Hemp Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
Poultry Processing Product Market
Agriculture and Agri Products
Cameroon Agriculture Market