
 North America Palm Oil Market | 2026-2036
North America Palm Oil Market Size, Share, and Industry Trends Forecast 2026-2036
North America Palm Oil Market Intelligence
Southeast Asian processing expansion is rewriting supply reliability equations for North American buyers. Cargill, Incorporated leverages its integrated supply chain to secure consistent crude oil flows from Malaysian and Indonesian origins. Bunge Limited anchors its North American distribution through Gulf Coast port infrastructure and interior river terminals. Wilmar International Limited competes on fractionation capabilities, supplying tailored olein and stearin blends to U.S. food manufacturers.
North America palm oil comprises the edible vegetable oil extracted from the mesocarp of Elaeis guineensis fruit, containing roughly 50% saturated fatty acids by weight, primarily palmitic and oleic acids, with a melting point range of 35–40°C that suits baking and frying applications. The oil serves as a functional lipid in processed foods, cosmetics, and increasingly as a feedstock for renewable diesel production. Refined oil dominates volume flows into food manufacturing, where stability and neutral flavor command premium positioning, while fractionated oil captures margin pools in personal care formulations requiring specific melting profiles. Crude oil retains cost-sensitive industrial lubricant buyers who perform in-house refining, and palm kernel oil diverges toward oleochemical applications with distinct lauric acid content.
The U.S. FDA maintains strict standards for edible oil labeling and trans fat disclosure, while EPA renewable fuel standards shape biofuel producer demand for certified sustainable palm oil feedstocks. Health Canada enforces maximum contaminant limits under its Food and Drug Regulations, affecting import acceptance criteria at Vancouver and Montreal entry points. Stakeholders must monitor evolving state-level clean fuel standards in California and Oregon, which increasingly tie carbon intensity scores to feedstock origin verification.
Market Dynamics
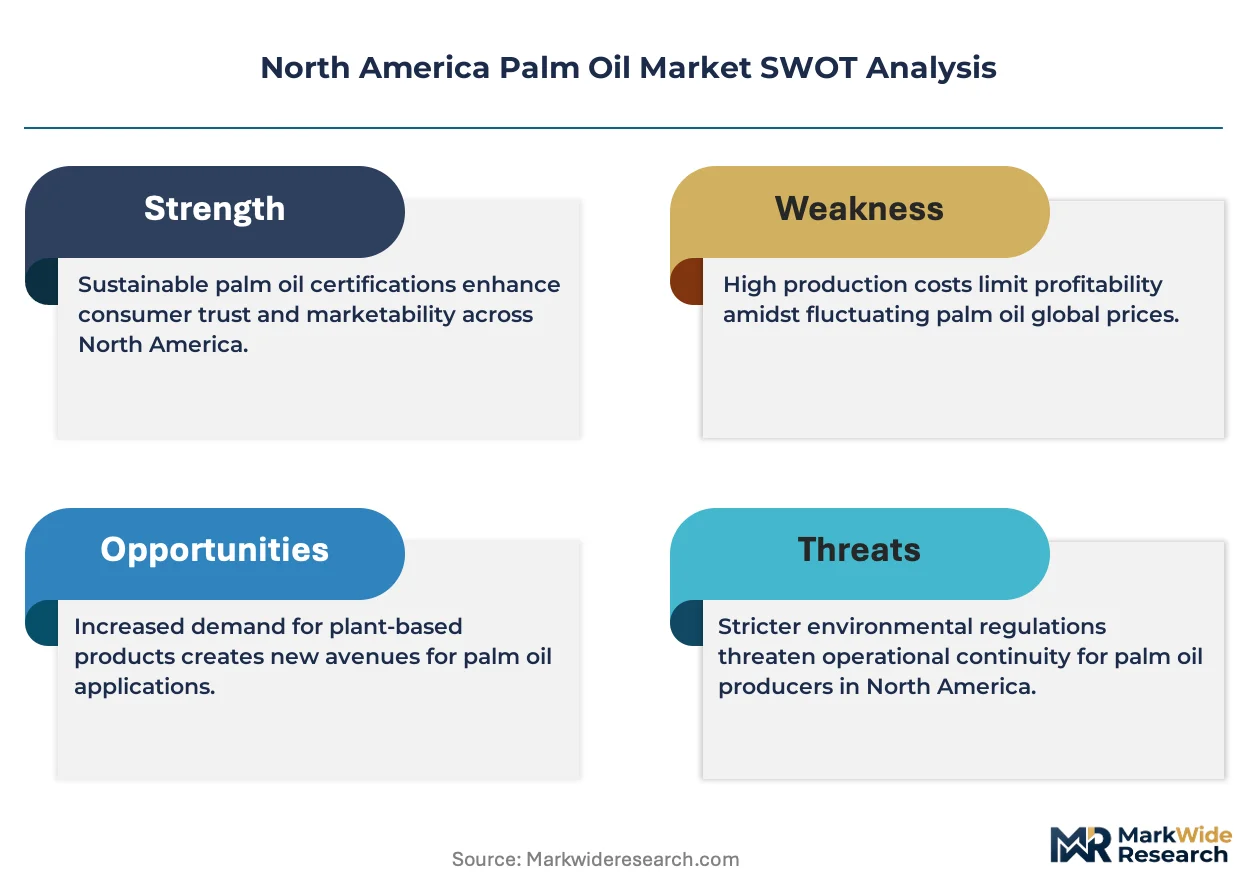
The U.S. EPA's renewable fuel standards are redirecting palm oil flows from food manufacturing toward biofuel feedstock markets, compressing edible oil availability and triggering procurement competition between refiners and food processors.
Growth Catalysts
- California LCFS carbon intensity scoring:Low-carbon fuel producers in the state now source certified sustainable palm oil to meet declining carbon intensity benchmarks, opening a dedicated demand channel separate from food applications.
- Fractionation technology advancement:Malaysian processing upgrades enable precise olein-stearin separation, allowing U.S. food manufacturers to specify exact melting profiles for bakery and confectionery formulations.
- Midwest food processing cluster density:Illinois and Ohio host concentrated meatpacking and snack production facilities that consume bulk refined palm oil for frying stability and extended shelf-life requirements.
Market Restraints
- Indonesia-Malaysia supply concentration:Over 85% of crude palm oil originates from Southeast Asian estates, exposing North American buyers to shipping disruptions and currency volatility in the ringgit and rupiah.
- U.S. FDA tropical oil labeling mandates:Disclosure requirements for saturated fat content force reformulation investments by food brands seeking to avoid negative consumer perception on packaging.
- Soybean oil substitution economics:Domestic soybean crush capacity expansion in Iowa and Minnesota offers U.S. food manufacturers a locally sourced alternative with comparable frying performance and lower transport costs.
Strategic Opportunities
- Oregon clean fuel program expansion:The state's carbon intensity reduction schedule creates incremental demand for certified palm oil feedstocks among Pacific Northwest renewable diesel producers.
- Personal care oleochemical pivot:Fractionated stearin streams supply surfactant manufacturers in New Jersey and Texas seeking palm-derived alternatives to petrochemical feedstocks for shampoo and detergent formulations.
- Blockchain-enabled origin verification:Supply chain transparency platforms allow U.S. buyers to document deforestation-free sourcing, satisfying ESG procurement criteria for multinational food brands.
Industry Challenges
- RSPO certification timeline compression:Food manufacturers face 18-24 month lead times to secure mass-balance certified supply, delaying product reformulation launches and retail placement commitments.
- Refinery retrofit capex requirements:Midwest processors must invest in hydrogenation unit modifications to handle higher free fatty acid crude streams without degrading refined oil color and stability specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Palm Oil Market |
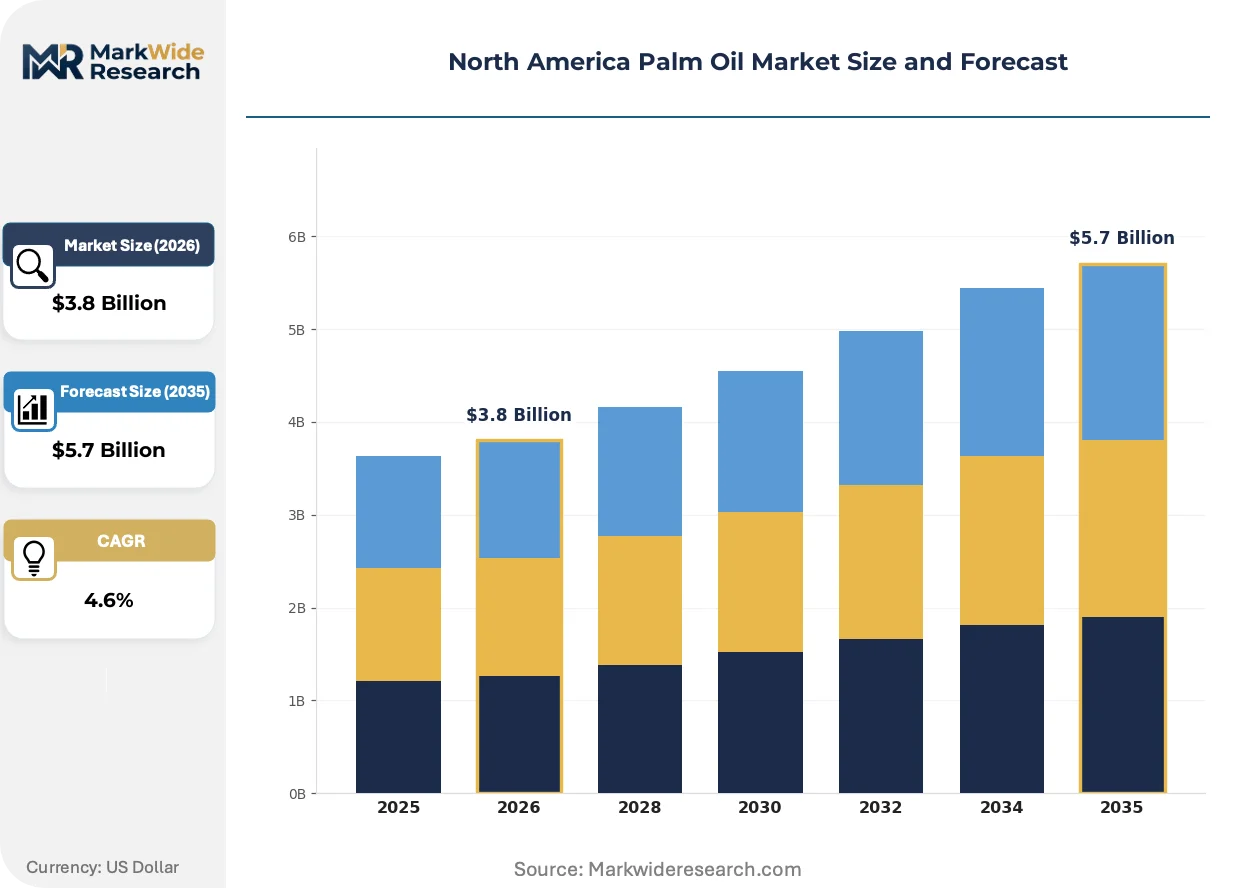
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Crude Oil, Fractionated Oil, Palm Kernel Oil Application: Food Products, Personal Care, Biofuels, Industrial Lubricants End User: Food Manufacturers, Cosmetic Companies, Biofuel Producers, Chemical Industries Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Olam Group, IOI Group, Cargill, Incorporated, Sime Darby Plantation Berhad, Musim Mas Group, Bunge Limited, Archer Daniels Midland, Golden Agri-Resources Ltd, Wilmar International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Palm Oil Market Strategic Shifts & Innovations
Processing technology convergence and regulatory carbon accounting are restructuring how palm oil enters North American value chains, with implications for supplier qualification, contract structures, and end-use allocation.
Enzymatic interesterification is collapsing the cost gap between palm oil and alternative structuring fats in bakery applications. U.S. cookie and cracker manufacturers in Chicago and Cincinnati now adopt enzymatically modified blends to achieve specific crystallization behavior without full hydrogenation. This technology is collapsing the premium previously commanded by palm stearin in laminated dough systems.
Canada's Clean Fuel Regulations enforce progressively stricter carbon intensity thresholds for liquid transportation fuels. Refiners in Edmonton and Sarnia now prioritize feedstocks with documented lifecycle emissions below 50 grams CO2 equivalent per megajoule. British Columbia importers respond by screening Malaysian suppliers with ISCC-certified mills and methane capture systems at extraction facilities.
Buyers in the U.S. snack food sector now consolidate procurement through direct mill relationships rather than merchant trading houses. Large-scale processors in Ohio and Pennsylvania negotiate annual volume contracts with named Malaysian estates, bypassing traditional commodity brokers. This disintermediation concentrates price risk directly on food manufacturers while securing traceability documentation required by retail customers.
North America Palm Oil Market Segmentation
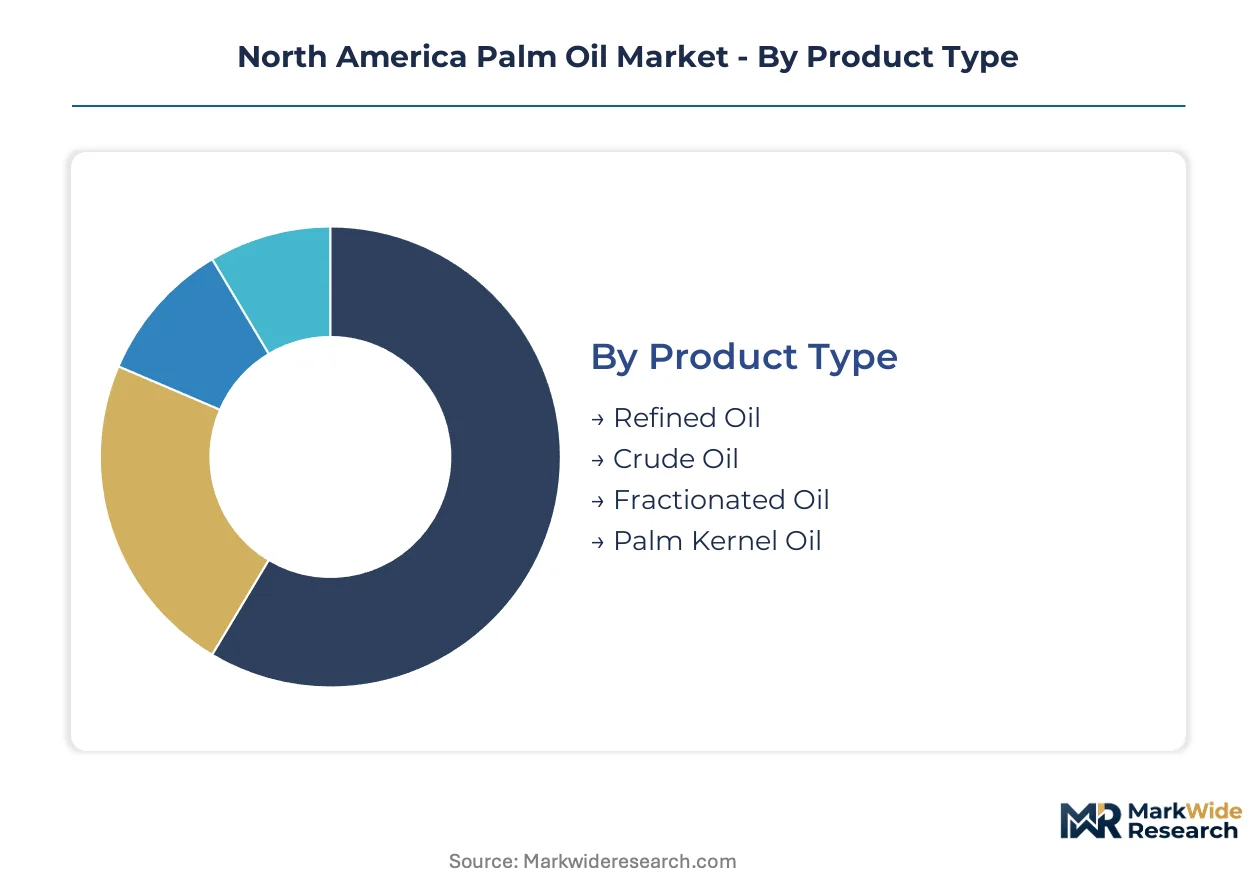
Segmentation in North American palm oil markets reveals how product specifications, application requirements, and procurement channels create distinct margin pools. Each category reflects divergent technical standards, regulatory exposure, and buyer concentration patterns that reshape competitive positioning.
Product Type:
After-sales technical support intensity varies sharply across product grades, with refined and fractionated oils demanding formulation assistance while crude buyers self-serve.
- Refined Oil:Neutral-flavored, bleached, and deodorized to <0.1% free fatty acid content for frying stability. Midwest snack manufacturers in Ohio and Illinois specify this grade for extended shelf-life requirements in packaged foods. FDA labeling compliance drives premium positioning over crude alternatives.
- Crude Oil:Unprocessed extraction containing 3-5% free fatty acids and carotenoid pigments. Cost-sensitive industrial lubricant blenders in Texas perform in-house refining to capture margin. U.S. Gulf Coast terminals handle bulk receipts for captive processing.
- Fractionated Oil:Thermally separated into olein and stearin fractions with defined melting curves. Personal care formulators specify narrow iodine value ranges.
- Palm Kernel Oil:Endosperm-derived lauric acid source diverging toward oleochemical surfactant production. New Jersey detergent manufacturers source for shampoo base stocks.
By volume, refined oil leads. By growth pace, fractionated oil is expanding most quickly.
Application:
Application segments stratify by carbon intensity accounting rules, with biofuel and food pathways facing divergent EPA and FDA compliance burdens.
- Food Products:Bakery, confectionery, and frying applications consuming 50% saturated fat content for crystallization control. Chicago cookie manufacturers adopt enzymatic interesterification to reduce trans fat labeling exposure. FDA tropical oil disclosure mandates force reformulation investments.
- Personal Care:Surfactant and emollient formulations requiring specific olein-stearin melting profiles. Texas and New Jersey oleochemical plants fractionate for shampoo and detergent base stocks. RSPO certification timelines compress supplier qualification windows.
- Biofuels:Renewable diesel feedstock competing for certified sustainable supply under California LCFS carbon intensity scoring. Oregon clean fuel program expansion redirects Pacific Northwest flows.
- Industrial Lubricants:Metalworking and hydraulic fluid applications tolerating higher free fatty acid crude streams. Captive refining at Midwest processors avoids refined oil premiums.
Food products dominates volume flows. Biofuels climbs the fastest as EPA renewable fuel standards redirect supply.
End User:
End user categories concentrate procurement power differently, with biofuel producers consolidating through direct mill relationships while cosmetic buyers fragment across specialty distributors.
- Food Manufacturers:Meatpacking and snack production clusters in Illinois and Ohio negotiate annual volume contracts with named Malaysian estates. Disintermediation concentrates price risk directly on processors while securing traceability documentation.
- Cosmetic Companies:Formulators in New Jersey specify narrow melting point ranges for lotion and cream stability. Blockchain-enabled origin verification satisfies ESG procurement criteria.
- Biofuel Producers:Edmonton and Sarnia refiners screen ISCC-certified mills with methane capture systems under Canada's Clean Fuel Regulations.
- Chemical Industries:Surfactant and lubricant additive manufacturers tolerating variable crude quality. Gulf Coast river terminals anchor distribution.
Food manufacturers command volume leadership. Biofuel producers gain share fastest as renewable diesel capacity expands.
Distribution Channel:
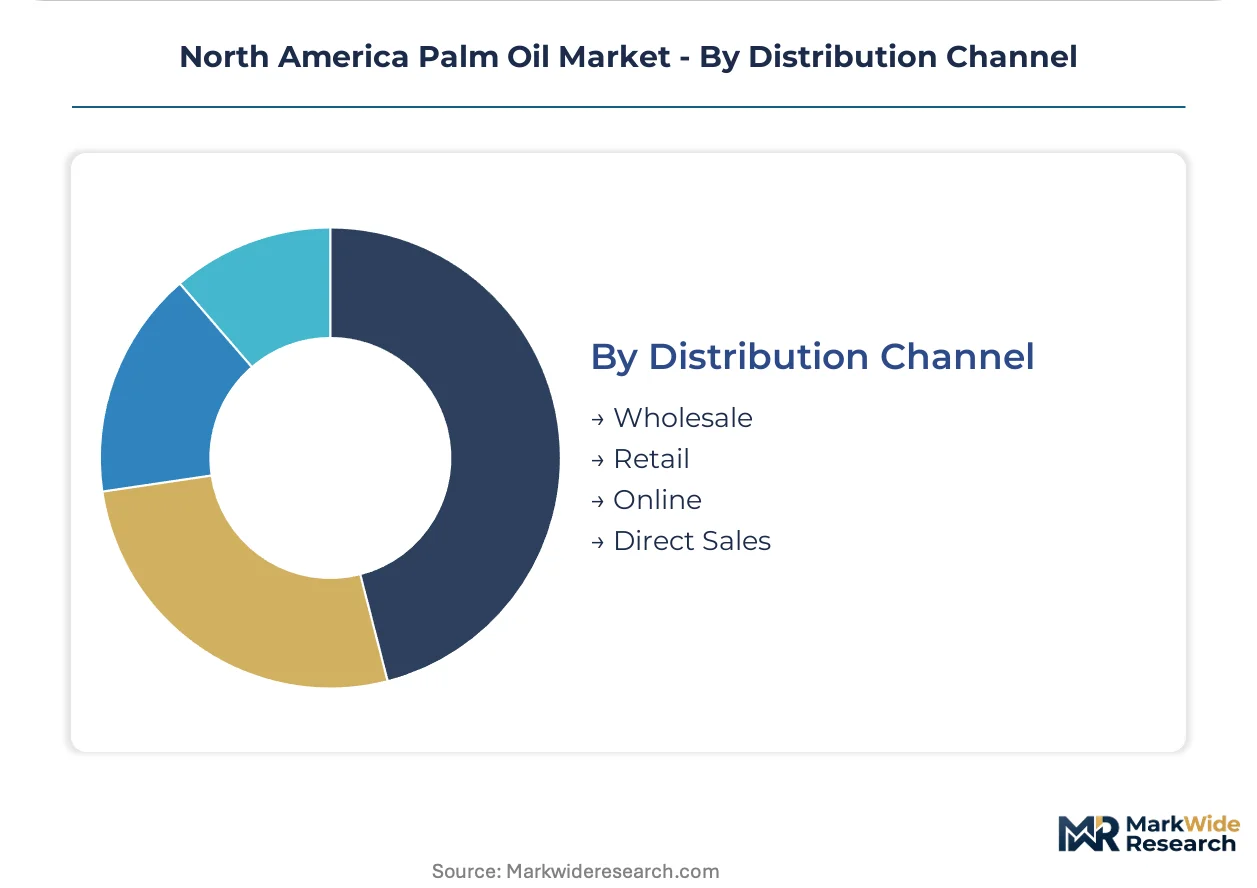
Channel structure reflects buyer scale and documentation requirements, with direct sales capturing traceability-sensitive volume while wholesale handles commodity flows.
- Wholesale:Merchant trading houses aggregate smaller food processor demand at Gulf Coast and Vancouver entry points. Currency volatility in ringgit and rupiah exposures concentrate here.
- Retail:Packaged oil for foodservice and small commercial fryer operations. California and Oregon clean fuel retail networks emerging.
- Online:Specialty oleochemical and cosmetic ingredient platforms serving New Jersey and Texas formulators. Documentation and certification transparency features command premium positioning.
- Direct Sales:Large-scale processors bypass brokers for named estate contracts with mass-balance RSPO certification. Pennsylvania and Ohio buyers consolidate procurement here.
Wholesale channels handle greatest volume. Direct sales expands most rapidly as traceability requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over 85% of crude palm oil originates from Southeast Asian estates, exposing North American buyers to shipping disruptions and currency volatility in the ringgit and rupiah. This supply concentration shapes procurement strategies across the continent.
United States
Midwest food processing clusters in Illinois and Ohio drive bulk refined oil consumption for meatpacking and snack production facilities. The EPA's renewable fuel standards redirect palm oil flows from food manufacturing toward biofuel feedstock markets, compressing edible oil availability. Chicago cookie manufacturers adopt enzymatic interesterification to reduce trans fat labeling exposure under FDA tropical oil disclosure mandates.
Canada
Edmonton and Sarnia refiners screen ISCC-certified mills with methane capture systems under Canada's Clean Fuel Regulations. British Columbia importers respond by prioritizing Malaysian suppliers with documented lifecycle emissions below 50 grams CO2 equivalent per megajoule. Vancouver entry points enforce Health Canada maximum contaminant limits affecting import acceptance criteria.
Mexico
Industrial lubricant blenders in Tamaulipas and Veracruz perform captive refining of cost-sensitive crude streams to avoid refined oil premiums. The country's national food safety regulator enforces edible oil labeling standards aligned with NAFTA-era technical barriers. Gulf Coast port infrastructure anchors distribution networks serving northern industrial corridors.
North America Palm Oil Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream. The North American palm oil market consolidates around integrated agribusiness conglomerates with captive Southeast Asian sourcing networks and interior river terminal distribution. Three archetypes dominate: integrated supply chain operators with plantation-to-port control, fractionation specialists delivering tailored olein-stearin blends, and merchant trading houses aggregating smaller processor demand. Capacity expansion at Gulf Coast entry terminals and direct mill relationship formation represent the dominant competitive moves.
Among integrated supply chain operators, Cargill, Incorporated and Bunge Limited exemplify the platform archetype through their control over Malaysian and Indonesian crude flows and North American interior distribution infrastructure. Wilmar International Limited occupies a position within the fractionation specialist tier, competing on separation capabilities for personal care and food formulation applications. These three entities anchor the competitive structure through their combined dominance of import channels, refining capacity, and customer-facing technical service.
| Leading Market Players |
|---|
| Olam Group |
| IOI Group |
| Cargill, Incorporated |
| Sime Darby Plantation Berhad |
| Musim Mas Group |
| Bunge Limited |
| Archer Daniels Midland |
| Golden Agri-Resources Ltd |
| Wilmar International Limited |
| Others |
Cost & Logistics Intelligence
Southeast Asian processing clusters in Port Klang and Belawan determine downstream pricing power for North American buyers through their control over fractionation capacity and certified sustainable output. The ringgit-rupiah exchange corridor transmits currency volatility directly into landed cost calculations at Gulf Coast terminals, while RSPO certification scarcity creates tiered access to premium food and biofuel channels.
Pricing Analysis
The U.S. FDA's tropical oil labeling mandates dictate the pricing tier structure across refined, fractionated, and crude grades. Three-tier pricing separates mass-balance certified sustainable from conventional from uncertified streams, with California LCFS carbon intensity scoring adding a fourth biofuel-specific premium band. Price differentiation centers on ISCC and RSPO certification levels rather than intrinsic quality, though Midwest food processors show highest sensitivity to transport cost differentials while personal care formulators absorb certification premiums for traceability documentation. Cost compression in standard refined grades is intensifying because soybean oil substitution economics in Iowa and Minnesota crush facilities cap palm oil ceiling prices.
Supply Chain Analysis
Indonesia and Malaysia's export licensing regimes for crude palm oil restrict flows during periodic levy adjustments and domestic obligation enforcement, creating supply uncertainty for North American refiners. Over 85 percent of global output originates from these two countries, with raw material dependencies on fertilizer inputs from China and shipping capacity through the Strait of Malacca. Single-source vulnerability concentrates at Malaysian port terminals handling bulk cargoes for Cargill and Bunge distribution networks. Distribution runs through integrated agribusiness operators controlling plantation-to-port infrastructure rather than merchant trading houses, though smaller processors still rely on wholesale aggregators at Vancouver and Gulf Coast entry points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Soybean oil substitution economics in the U.S. Midwest present a persistent displacement threat that palm oil incumbents must navigate through certification differentiation and biofuel feedstock positioning.
For Market Incumbents: Entrench through backward integration into Malaysian and Indonesian milling assets to secure mass-balance certified supply ahead of 18-24 month RSPO qualification timelines. Prioritize hydrogenation unit retrofits at Ohio and Illinois refineries to handle higher free fatty acid crude streams without degrading color specifications, defending food manufacturing share against enzymatic interesterification alternatives. For New Entrants and Emerging Players: Pursue blockchain-enabled origin verification platforms serving ESG-conscious cosmetic brands in New Jersey and Texas, where documentation premiums exceed commodity trading margins. Target Pacific Northwest biofuel producers under Oregon's clean fuel program expansion, offering ISCC-certified supply with methane capture documentation that Edmonton and Sarnia refiners now screen for under Canada's Clean Fuel Regulations. For Investors and Strategic Acquirers: Long-term, this sits as a certification-arbitrage play because regulatory carbon intensity scoring across California LCFS, Oregon clean fuel standards, and Canadian federal rules creates persistent premia for documented sustainable supply. Acquisition candidates include fractionation specialists with olein-stearin separation capabilities and direct mill relationships bypassing commodity brokers. The signal to watch is compression in RSPO mass-balance premium spreads, indicating certification commoditization or supply saturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Southeast Asian Milling | Cargill and Bunge secure captive crude flows ahead of Indonesian export levy volatility. |
| Hydrogenation Unit Retrofit Investment | Midwest processors adapt to higher free fatty acid streams without refined oil quality degradation. |
| Blockchain Origin Verification Platform | New Jersey cosmetic formulators document deforestation-free sourcing for ESG procurement criteria. |
| ISCC Certification Acquisition | Edmonton refiners meet Canada's Clean Fuel Regulations carbon intensity thresholds below 50 grams CO2 equivalent per megajoule. |
| Direct Mill Relationship Formation | Ohio snack manufacturers bypass commodity brokers to secure traceability documentation for retail customers. |
Research Approach
Operator-level perspectives from procurement directors at Midwest food processors, biofuel refinery supply managers in Edmonton and Sarnia, cosmetic formulators in New Jersey, and oleochemical plant engineers in Texas anchored the qualitative base. These primary interviews combined with secondary validation from U.S. EPA renewable fuel standard filings, FDA food additive petitions, Health Canada import inspection records, and Malaysian Palm Oil Board export statistics. Bottom-up volume estimates from individual facility consumption rates triangulated against top-down trade flow analysis through Vancouver and Gulf Coast customs data.
Scenario-bracketing around regulatory implementation timelines and substitution elasticity parameters structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, application pathway, end-user procurement scale, and distribution channel structure, with regional regulatory clusters capturing California LCFS, Oregon clean fuel program, and Canadian federal carbon intensity rules. CAGRs derived from fitted growth curves applied to base-year volume estimates, with biofuel feedstock demand elasticity and food manufacturing reformulation lag curves as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in ringgit-rupiah exchange rates, Southeast Asian palm oil levy policies, or U.S. soybean crush margins would shift the trajectory. Forecasts reflect documented assumptions about certification adoption rates, regulatory enforcement stringency, and processing technology diffusion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
Indonesia Animal Feed Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Algeria Agriculture Market
Agriculture and Agri Products
Plant Antifreeze Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Australia Compound Feed Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
South America Cashew Market
Agriculture and Agri Products
Primary Feed Materials Market