
 Europe LNG Bunkering Market | 2026-2036
Europe LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
Europe LNG Bunkering Market Insights
Modular bunkering service packages combining truck-to-ship flexibility with terminal anchorage options is realigning how ferry operators and offshore support vessel fleets procure marine LNG. Shell PLC leverages its integrated supply chain from liquefaction through port delivery to sustain competitive positioning across Northwest European ports. TotalEnergies SE anchors its presence through dedicated bunker vessels and storage partnerships in the ARA region. Gasum Oy competes by extending its Nordic terminal network into Baltic Sea ferry routes, while Titan LNG BV specializes in small-scale ship-to-ship transfers for short-sea shipping segments.
Europe LNG bunkering denotes the commercial supply of liquefied natural gas as marine fuel to vessels at ports or offshore locations, requiring cryogenic storage at minus 162 degrees Celsius and specialized transfer systems to prevent boil-off gas losses. The process serves shipping operators seeking compliance with sulfur emission limits while maintaining energy density comparable to conventional heavy fuel oils. Truck-to-ship delivery currently dominates volume in ports lacking dedicated jetty infrastructure, though terminal bunkering captures margin pools where storage facilities anchor multi-vessel refueling schedules. Container ships and tankers represent the fastest-growing vessel categories as deep-sea operators retrofit dual-fuel engine configurations, while ferry operators sustain steady offtake on fixed Baltic and North Sea routes.
The European Maritime Safety Agency coordinates port state control enforcement of the EU Alternative Fuels Infrastructure Regulation, which mandates LNG refueling points at core network ports. The EU Green Deal's FuelEU Maritime initiative progressively tightens greenhouse gas intensity limits on vessel energy use, directly shaping investment timelines for bunker operators and shipping lines. Classification societies including DNV and Bureau Veritas now certify bunkering procedures under ISO 20519 standards, creating compliance thresholds for market access. Stakeholders must monitor how the EU Emissions Trading System expansion to maritime transport reshapes fuel cost structures and bunkering location economics across competing European hub ports.
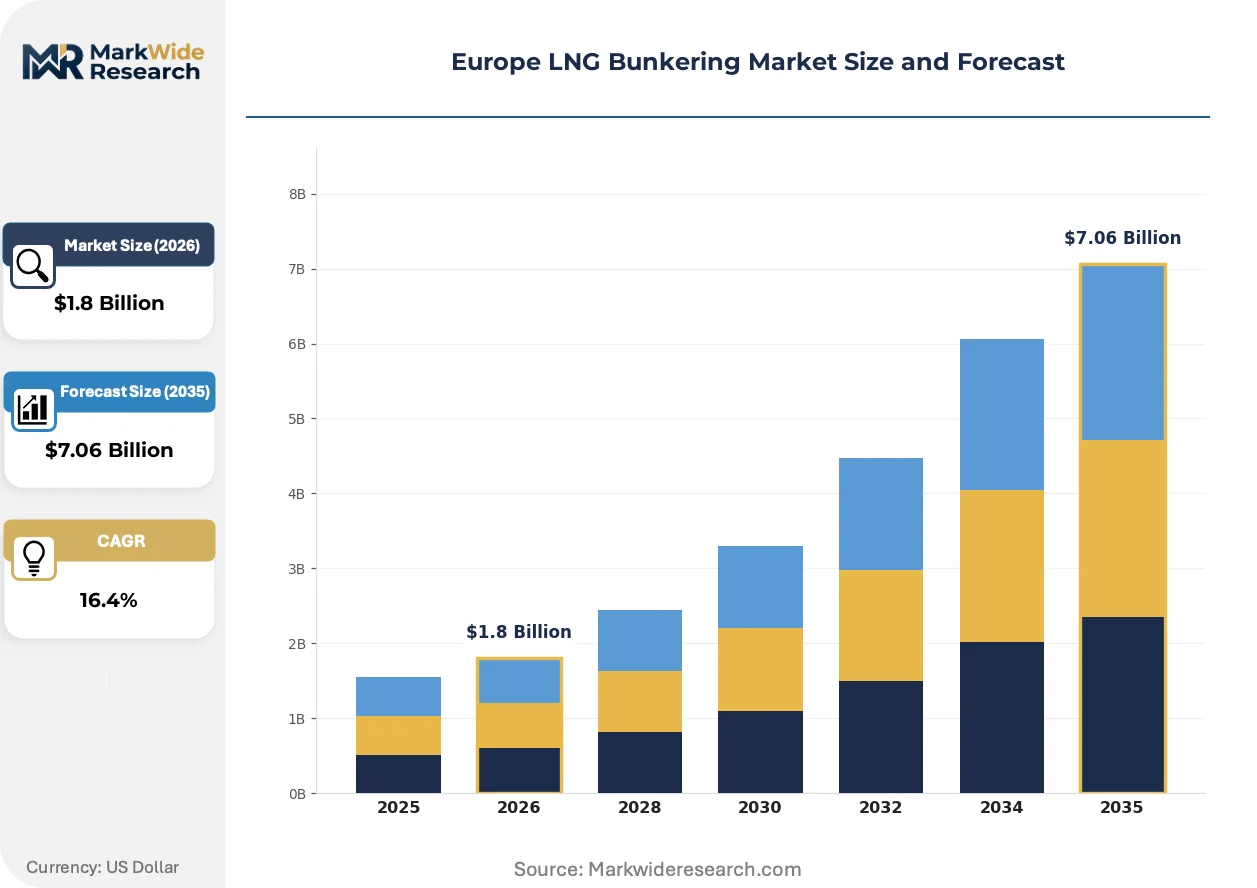
Market Dynamics
The EU Green Deal's FuelEU Maritime initiative is compressing investment timelines across Northwest European ports, forcing terminal operators to accelerate cryogenic infrastructure buildouts before 2030 compliance deadlines bite. This regulatory pressure is redistributing competitive advantage toward integrated supply chains that control liquefaction through bunkering.
Growth Catalysts
- FuelEU Maritime Intensity Limits:The regulation mandates progressive greenhouse gas reductions on vessel energy use, compelling container lines to retrofit dual-fuel engines and secure long-term LNG offtake contracts at ARA ports.
- Truck-to-Ship Delivery Networks:Modular refueling systems are expanding service coverage to secondary ports lacking dedicated jetties, capturing ferry operators and offshore support vessels on fixed Baltic routes.
- Netherlands-Germany-Belgium Hub Concentration:Terminal capacity and vessel availability in this corridor now outpaces Mediterranean supply points, drawing deep-sea operator demand northward.
Market Restraints
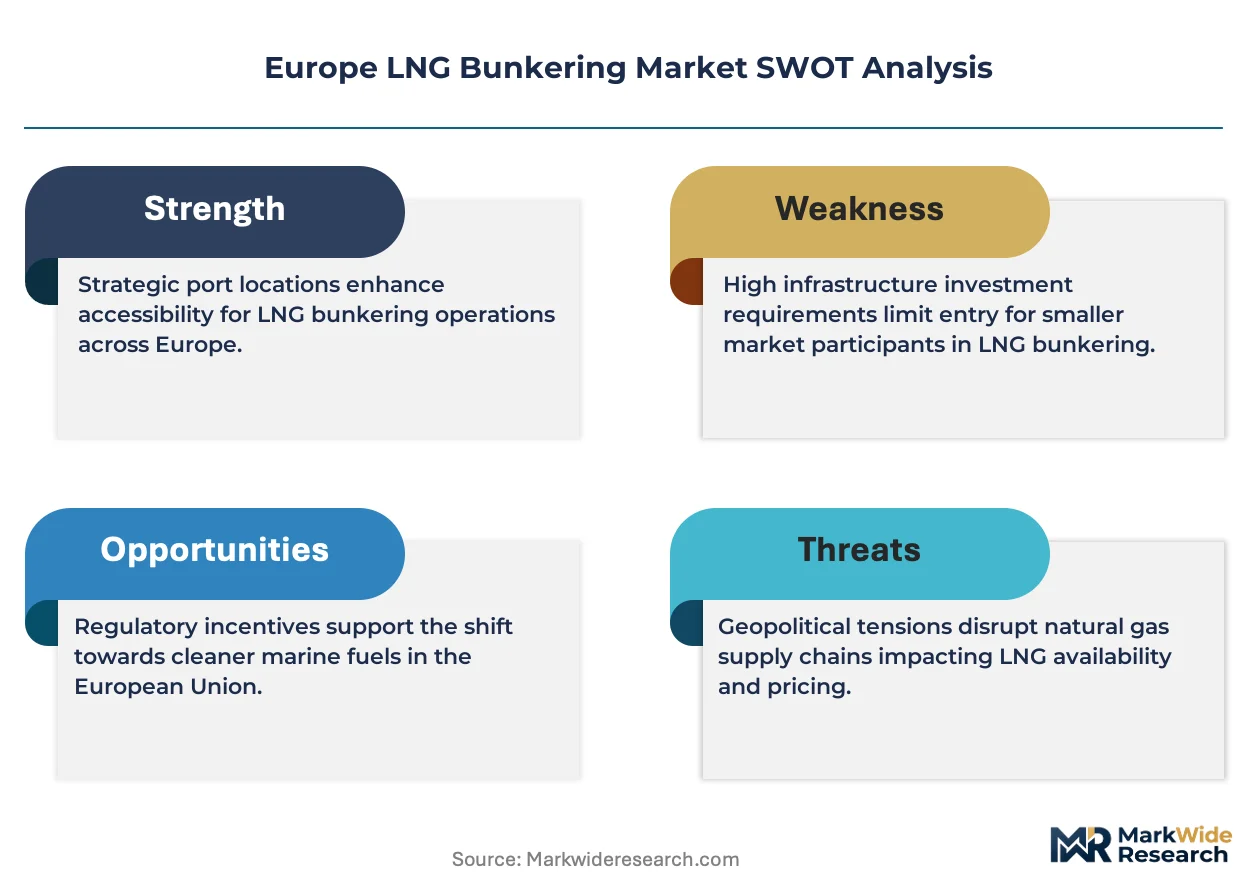
- Cryogenic Storage Capex Burden:Minus 162 degrees Celsius containment systems require specialized alloys and vacuum insulation, elevating upfront infrastructure costs beyond smaller port authority budgets.
- Baltic Sea Supply Concentration:Gasum Oy's Nordic terminal network controls critical ferry route access, creating dependency risks for operators without alternative bunkering points.
- Electrofuel Substitution Timeline:Green hydrogen-derived synthetic methane promises zero-carbon compliance under EU taxonomy, threatening LNG's transitional fuel positioning post-2035.
Strategic Opportunities
- Portuguese Atlantic Corridor:Sines and Lisbon ports lack dedicated LNG bunkering infrastructure despite growing transatlantic container traffic, presenting first-mover terminal investment potential.
- ISO 20519 Certification Services:Classification societies are expanding bunkering procedure audit capacity, creating adjacent revenue streams for compliance consultancies and training providers.
- Small-Scale Ship-to-Ship Transfers:Short-sea shipping segments in the North Sea require flexible refueling formats that bypass fixed terminal schedules, rewarding specialized bunker vessel operators.
Industry Challenges
- Cryogenic Engineer Scarcity:Specialized expertise in boil-off gas management and transfer system safety remains concentrated among Nordic maritime training institutes, constraining operational scaling.
- EU ETS Integration Complexity:Maritime transport's inclusion in the Emissions Trading System requires real-time carbon accounting across fragmented bunkering transactions, taxing legacy IT infrastructure at port authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe LNG Bunkering Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ship-to-Ship, Truck-to-Ship, Terminal Bunkering, Offshore Bunkering End User: Shipping Lines, Ferry Operators, Offshore Support Vessels, Cargo Vessels Infrastructure Type: Bunkering Terminals, Storage Facilities, Refueling Vessels, Distribution Networks Vessel Type: Bulk Carriers, Container Ships, Tankers, Fishing Vessels |
| Companies Covered | Shell PLC, TotalEnergies SE, Gasum Oy, Nauticor GmbH & Co. KG, Titan LNG BV, Gazpromneft Marine Bunker LLC, Polskie LNG S.A., ENGIE SA, Skangas AS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe LNG Bunkering Market Trends and Innovations
Technology convergence between modular refueling systems and digital port management platforms is compressing vessel turnaround times while expanding serviceable vessel categories beyond deep-sea container ships.
Bunkering infrastructure is modularizing around containerized cryogenic storage units that plug into existing port utility grids. Ferry operators on fixed Baltic routes are adopting these systems fastest, eliminating dependency on permanent jetty construction. The technology is modularizing supply chain economics by enabling smaller ports to capture bunker revenue without decade-long infrastructure commitments.
The EU Alternative Fuels Infrastructure Regulation mandates LNG refueling points at core network ports under European Maritime Safety Agency enforcement timelines. Port state control inspections now verify ISO 20519 compliance during routine vessel calls, elevating documentation burdens for non-integrated operators. Container shipping lines are responding by consolidating procurement contracts with suppliers offering certified end-to-end custody transfer.
Charter party clauses increasingly specify bunker fuel carbon intensity ceilings rather than simple sulfur compliance. Shipowners are renegotiating vessel employment contracts to pass FuelEU Maritime liability to cargo interests, redistributing compliance risk across the maritime value chain. This contractual evolution is most visible in Rotterdam-Hamburg corridor trades where major container lines anchor long-term tonnage deployment.
Europe LNG Bunkering Market Segmentation
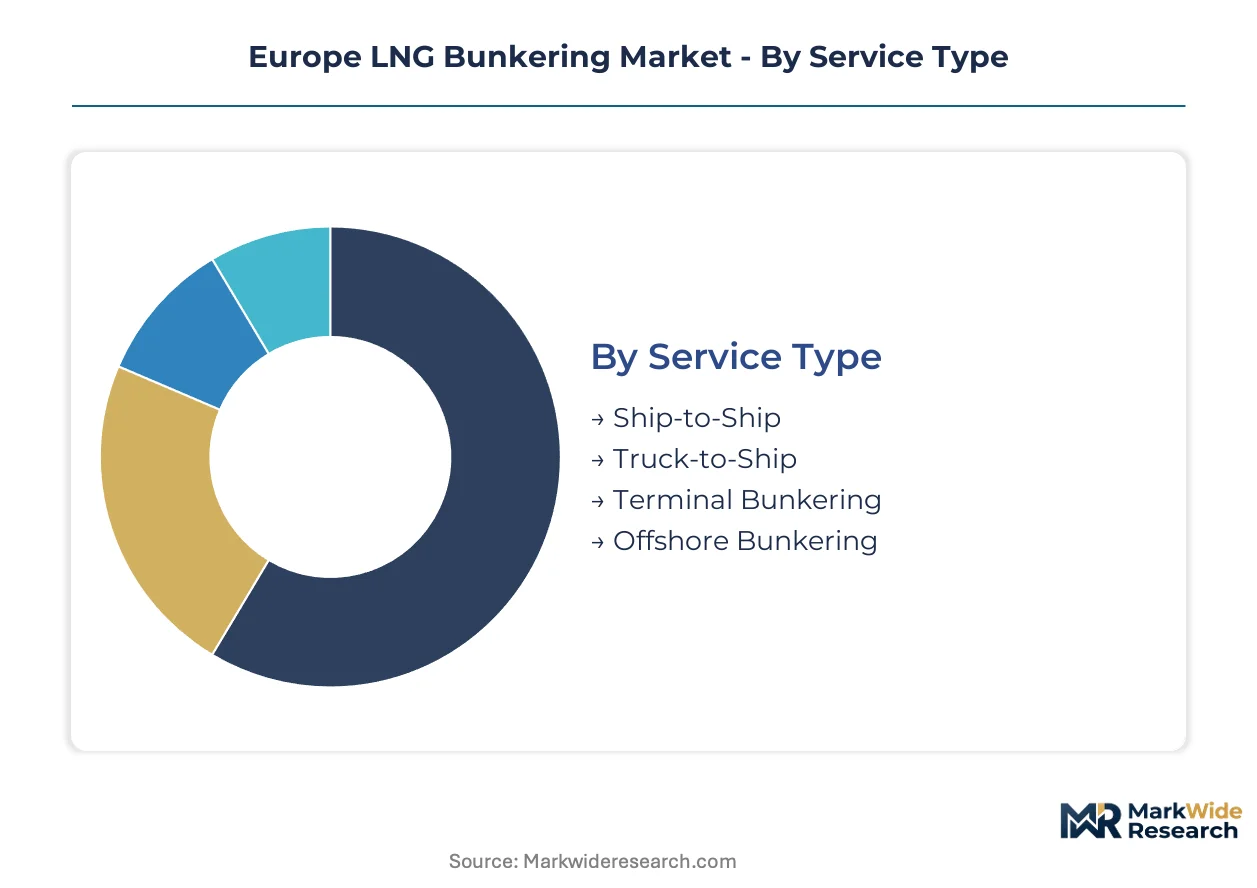
Segmentation in Europe LNG bunkering reveals how service modalities, vessel categories, and infrastructure configurations determine margin capture and regulatory compliance pathways across Northwest European ports.
Service Type:
Volume-driven terminal operations command premium pricing at ARA hub ports, while flexible truck-to-ship delivery captures secondary port revenue without permanent infrastructure commitment.
- Ship-to-Ship:Specialized bunker vessels transfer LNG directly between floating units, enabling simultaneous cargo operations and refueling. Demand concentrates on Rotterdam and Hamburg corridors where deep-sea container lines minimize port turnaround time.
- Truck-to-Ship:Cryogenic road tankers deliver modular refueling capacity to ports lacking dedicated jetties. Ferry operators on fixed Baltic routes leverage this format to bypass infrastructure bottlenecks at smaller harbors.
- Terminal Bunkering:Fixed jetty infrastructure anchors multi-vessel refueling schedules at high-throughput ports.
- Offshore Bunkering:Floating transfer systems serve vessels at anchorage outside port limits.
Today's leader: Terminal Bunkering. Tomorrow's challenger: Truck-to-Ship.
End User:
Procurement patterns diverge between scheduled ferry operators seeking contract stability and tramp shipping lines requiring spot-market flexibility.
- Shipping Lines:Deep-sea container and tanker operators negotiate multi-year offtake agreements tied to FuelEU Maritime compliance trajectories. Procurement concentrates at ARA terminals where integrated suppliers offer certified custody transfer.
- Ferry Operators:Fixed-route Baltic and North Sea services demand predictable bunkering windows aligned with strict departure schedules. Gasum Oy's Nordic terminal network captures this segment through dedicated supply contracts.
- Offshore Support Vessels:Oil and gas platform service fleets require flexible refueling at remote supply bases.
- Cargo Vessels:General freight operators represent fragmented demand across smaller port networks.
Shipping Lines anchor current revenue; Ferry Operators are gaining share fastest as route electrification delays sustain LNG demand.
Infrastructure Type:
Capital intensity separates integrated terminal operators from modular service providers competing on deployment speed.
- Bunkering Terminals:Fixed jetty and loading arm systems handle the highest throughput volumes at Rotterdam, Antwerp, and Hamburg. EU Alternative Fuels Infrastructure Regulation mandates expansion at core network ports.
- Storage Facilities:Cryogenic tanks at minus 162 degrees Celsius anchor supply security for multi-vessel scheduling.
- Refueling Vessels:Purpose-built bunker ships extend service range beyond fixed infrastructure.
- Distribution Networks:Road and short-sea logistics connect liquefaction plants to consumption points.
Bunkering Terminals dominate capital deployment; Storage Facilities face tightest capacity constraints.
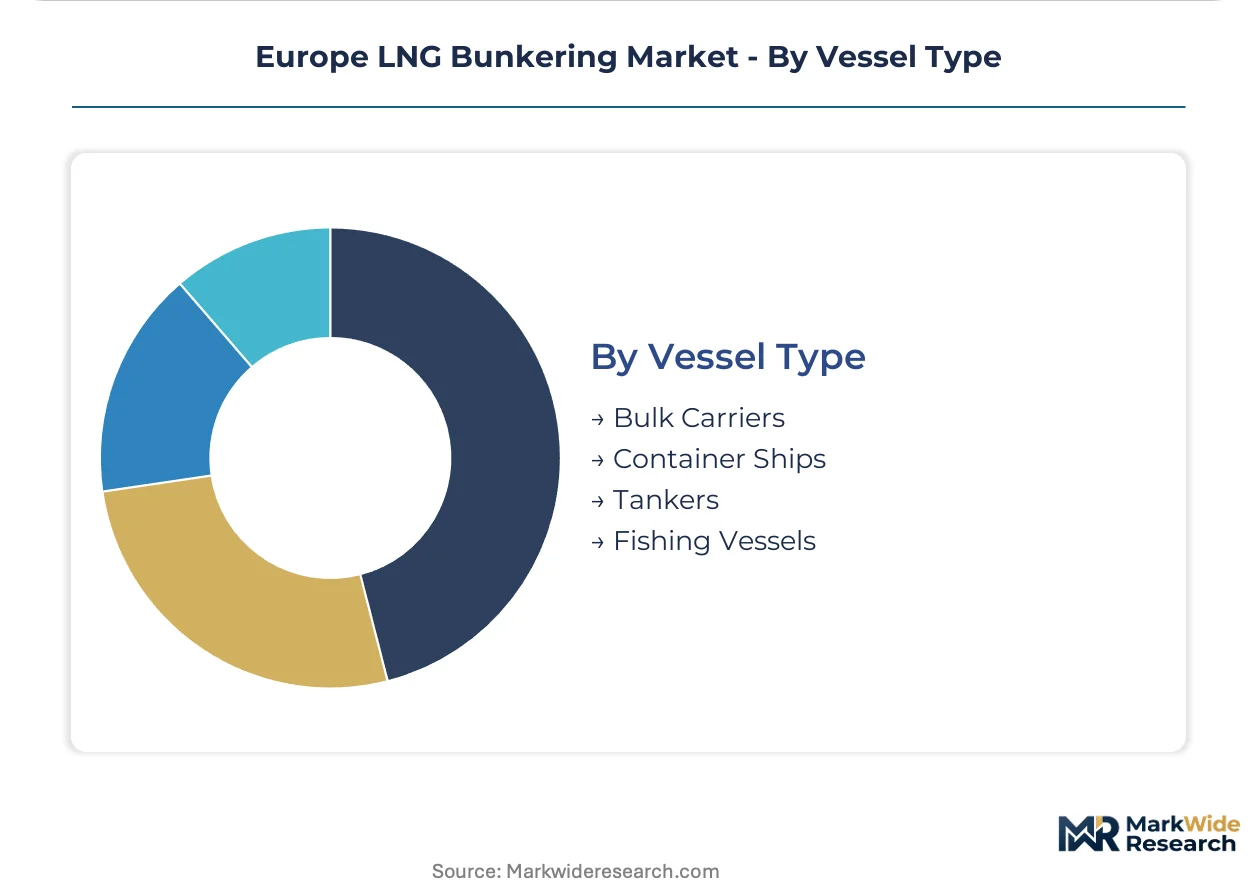
Vessel Type:
Engine retrofit economics and route predictability determine which vessel categories drive bunker demand growth.
- Container Ships:Dual-fuel engine retrofits accelerate across deep-sea fleets as FuelEU Maritime intensity limits tighten. Maersk and MSC anchor demand at Rotterdam-Hamburg corridors with long-term tonnage deployment.
- Tankers:Crude and product carriers adopt LNG propulsion for compliance with sulfur emission limits in emission control areas. Demand clusters at ARA terminals serving transatlantic routes.
- Bulk Carriers:Dry cargo vessels represent emerging retrofit candidates as charter party clauses shift compliance liability.
- Fishing Vessels:Smaller craft face infrastructure access barriers at most dedicated LNG terminals.
Container Ships lead orderbook conversion; Tankers show steepest expansion trajectory as product trade routes decarbonize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam pioneered commercial LNG bunkering in Europe during the early 2010s, establishing the technical protocols and safety frameworks that later spread to Hamburg and Antwerp. The ARA corridor remains the continent's primary demand concentration, though regulatory pressure under the EU Green Deal is forcing capacity buildouts across secondary ports.
Netherlands
Rotterdam's port authority mandates shore power and LNG bunkering compatibility for all new terminal concessions under its Clean Shipping Vision 2030. The EU Alternative Fuels Infrastructure Regulation requires LNG refueling points at core network ports, accelerating jetty construction at Maasvlakte. The Amsterdam-Rotterdam-Antwerp cluster now handles the majority of Northwest European container ship refueling.
Germany
Hamburg's container terminals anchor demand from deep-sea lines retrofitting dual-fuel engines to meet FuelEU Maritime intensity limits. The country's national maritime regulator enforces ISO 20519 bunkering certification through port state control inspections. The Elbe River corridor connects Hamburg to Bremen, creating a contiguous bunkering zone for Baltic and North Sea routes.
Belgium
Antwerp's chemical industry cluster generates captive demand for LNG-powered tankers serving downstream petrochemical complexes. The Flemish government subsidizes cryogenic infrastructure through its Port of the Future program. The Waasland industrial zone hosts dedicated storage facilities that supply both maritime and inland waterway bunkering.
France
Marseille-Fos port complex is expanding LNG bunkering capacity to capture Mediterranean container traffic bypassing the Suez Canal. The French maritime authority implements EU Green Deal port infrastructure requirements through regional prefecture oversight. The Calais-Dunkirk corridor serves short-sea ferries on fixed Channel routes with truck-to-ship delivery systems.
Spain
Barcelona and Valencia ports are retrofitting existing LNG import terminals for marine bunkering to compete with ARA hub pricing. The Spanish ports authority coordinates with the EU Green Deal timeline for alternative fuel infrastructure deployment. The Strait of Gibraltar anchorage zone presents offshore bunkering potential for transatlantic vessels.
Europe LNG Bunkering Market Competitive Landscape
The competitive structure tilts toward integrated energy majors with captive liquefaction and shipping assets. Three distinct archetypes populate the supplier base: global oil majors leveraging existing natural gas portfolios, regional gas utilities extending terminal networks, and specialized bunkering operators focused on small-scale ship-to-ship transfers. Capacity expansion and strategic port partnerships constitute the dominant competitive moves, with operators racing to secure jetty access before 2030 compliance deadlines.
Within the integrated energy major tier, Shell PLC and TotalEnergies SE exemplify archetypes combining upstream liquefaction with downstream port delivery infrastructure. Gasum Oy anchors the regional utility segment through its Nordic terminal network, while Titan LNG BV occupies a position among specialized operators targeting short-sea shipping flexibility. These three patterns—integrated majors, utility extenders, and niche specialists—capture the competitive geometry of European LNG bunkering.
| Leading Market Players |
|---|
| Shell PLC |
| TotalEnergies SE |
| Gasum Oy |
| Nauticor GmbH & Co. KG |
| Titan LNG BV |
| Gazpromneft Marine Bunker LLC |
| Polskie LNG S.A. |
| ENGIE SA |
| Skangas AS |
| Others |
Pricing and Supply Chain Analysis
Henry Hub natural gas futures and Northwest European LNG spot indices cascade through liquefaction, shipping, and terminal storage costs into three-tier pricing structures across premium, standard, and economy levels for marine fuel buyers. Rotterdam terminal operators capture margin pools through integrated custody transfer, while truck-to-ship providers compete on deployment speed without permanent infrastructure commitment.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between integrated suppliers and container shipping lines, with price differentiation hinging on ISO 20519 certification tier and volume scale commitments. Cost compression in spot-market truck-to-ship delivery is intensifying because modular providers bypass jetty queuing premiums. Ferry operators on fixed Baltic routes exhibit highest price sensitivity due to thin margins on scheduled services, while deep-sea container lines show lowest sensitivity given FuelEU Maritime compliance liability transfer to cargo interests.
Supply Chain Analysis
EU Green Deal domestic-content mandates for cryogenic equipment and port infrastructure are reshaping sourcing toward European fabricators of vacuum-insulated storage tanks and loading arm systems. Supply concentration centers on Norway, Qatar, and the United States for liquefaction feedstock, while the value chain draws from South Korea and Japan for specialized LNG carrier construction. Single-source vulnerability runs through Gasum Oy's Nordic terminal network controlling critical Baltic ferry route access. Distribution runs through ARA hub terminals anchoring multi-vessel schedules, with truck-to-ship networks extending reach to secondary ports lacking dedicated jetties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe LNG bunkering functions as a geographic-arbitrage play where Portuguese Atlantic corridor ports offer first-mover terminal investment potential at lower land and regulatory compliance costs than saturated ARA hubs.
For Market Incumbents: Cement jetty access at core network ports before 2030 EU Alternative Fuels Infrastructure Regulation deadlines harden competitive moats. Expand cryogenic storage capacity at Rotterdam and Hamburg to capture container line dual-fuel retrofits. Vertical integration into small-scale ship-to-ship vessel fleets defends against modular truck-to-ship entrants eroding spot-market share.
For New Entrants and Emerging Players: Digital port management platform partnerships offer a channel to bypass legacy terminal scheduling systems and embed into vessel turnaround optimization. Target Sines and Lisbon for greenfield terminal development where transatlantic container traffic growth outpaces infrastructure investment. White-space exists in ISO 20519 certification services and cryogenic engineer training programs constrained by Nordic maritime institute capacity limits.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized bunkering operators controlling small-scale ship-to-ship transfer capabilities in North Sea short-sea shipping segments. Long-term viability over a multi-year horizon favors acquisition targets with captive liquefaction supply agreements and ARA jetty access rights. The signal to watch is FuelEU Maritime intensity limit enforcement tightening and EU ETS carbon price trajectories reshaping fuel cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Capacity Buildout | ARA port authorities accelerate jetty construction to meet EU Alternative Fuels Infrastructure Regulation mandates. |
| Backward Integration into Liquefaction | Shell and TotalEnergies secure captive supply from Norwegian and Qatari production facilities. |
| Small-Scale Vessel Fleet Expansion | Titan LNG extends ship-to-ship service range beyond fixed infrastructure constraints in North Sea routes. |
| ISO 20519 Certification Investment | Classification societies expand audit capacity to capture compliance service revenue from fragmented operators. |
| Digital Platform Integration | Port management software vendors embed bunkering scheduling into vessel turnaround optimization workflows. |
Research Methodology
Coverage spans Northwest Europe, Mediterranean Europe, and Atlantic Europe, with primary inputs from each region combining structured interviews with terminal operators, shipping line procurement directors, port authority infrastructure planners, and classification society surveyors with secondary validation. Secondary sources include EU Green Deal regulatory filings, European Maritime Safety Agency port state control records, ISO 20519 certification databases, and customs trade data for cryogenic equipment imports. Bottom-up vessel demand modeling and top-down fuel consumption projections triangulate volume estimates.
Granularity-level framing applies country-level modeling for Netherlands, Germany, Belgium, France, and Spain, with service-type segmentation at terminal bunkering versus truck-to-ship versus ship-to-ship resolution. End-user categories distinguish shipping lines, ferry operators, and offshore support vessels. CAGRs derive from fitted growth curves across the projection horizon, with bunker vessel deployment schedules and dual-fuel engine retrofit orderbooks as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for green hydrogen-derived synthetic methane would alter the outlook for LNG's transitional fuel positioning post-2035. Forecasts reflect assumptions around FuelEU Maritime enforcement intensity and EU ETS carbon price trajectories, with electrofuel substitution timelines and cryogenic engineer availability as specific risk factors that could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Subsea Equipment Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
Asia Pacific Offshore Seismic Services Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
Europe Jackup Rig Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Downstream Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
Kuwait Oil and Gas Downstream Market