
 Boat and Ship MRO Market | 2026-2036
Boat and Ship MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Boat and Ship MRO Market Outlook
Commercial fleet operators are rotating MRO spending toward predictive and condition-based maintenance programs, reducing reliance on traditional time-based dry-docking cycles. Keppel Offshore & Marine Ltd dominates Singapore's deepwater repair berths with specialized LNG carrier retrofit capabilities. Huntington Ingalls Industries Inc. anchors US Navy vessel lifecycle support through integrated public-private maintenance contracts. BAE Systems PLC competes across UK and Australian naval MRO through sovereign sustainment partnerships with defense ministries.
Boat and Ship MRO encompasses the inspection, repair, overhaul, and replacement of hull structures, propulsion machinery, auxiliary systems, and mission-critical electronics to restore operational classification society compliance and extend vessel service life. Hull thickness gauging, crack propagation analysis, and cathodic protection renewal represent core technical procedures governed by Lloyd's Register and DNV classification rules. Engine Maintenance and Propulsion Overhaul services command the largest revenue pools given the capital intensity of crankshaft machining and turbocharger refurbishment. Predictive Analytics and IoT Solutions within the Technology dimension are expanding fastest as fleet managers deploy vibration sensors and fuel consumption algorithms to compress unplanned downtime.
The International Maritime Organization enforces MRO demand through mandatory Energy Efficiency Existing Ship Index retrofits and ballast water management system installations. Classification societies including Lloyd's Register, DNV, and ABS audit repair quality and certify structural integrity after major hull renewals. The US Coast Guard and EPA jointly regulate commercial vessel emissions testing and hazardous waste disposal from shipyard sandblasting operations. Stakeholders must monitor regulatory phase-in timelines for greenhouse gas intensity indicators while calibrating repair capacity investments against fleet age profiles and emerging alternative fuel conversion requirements.
Market Dynamics
Commercial fleet operators are compressing dry-docking intervals to satisfy IMO sulfur caps and ballast water mandates while predictive maintenance platforms displace reactive repair schedules. This regulatory-technology tension is redistributing MRO spending toward condition-based monitoring and specialized retrofit yards.
Growth Catalysts
- IMO Ballast Water Management Convention:Mandated treatment system installations force vessel owners into scheduled yard visits, creating predictable maintenance windows for hull and machinery overhaul.
- Dual-fuel engine retrofits:LNG and methanol-ready propulsion conversions concentrate demand at yards with cryogenic piping certification and crankshaft machining capacity.
- Singapore's Jurong Port cluster:Deepwater berths and integrated logistics infrastructure anchor Southeast Asian repair gravity, drawing tonnage from Indonesian and Vietnamese flag fleets.
Market Restraints
- Specialized steel plate supply:EH36 and DH36 marine-grade steel production concentrates in Chinese and South Korean mills, exposing yards to alloy price volatility and delivery delays.
- Crankshaft machining capacity scarcity:Only a dozen facilities worldwide possess in-situ grinding equipment for two-stroke marine engines, creating repair bottlenecks for ultra-large container vessels.
- REACH compliance friction:European yards face restricted coating chemistries and sandblasting waste disposal protocols that extend surface preparation timelines.
Strategic Opportunities
- Indian Subcontinent repair expansion:Alang-Sosiya and Pipavav offer labor cost arbitrage for mid-life vessel refits, though classification society presence remains thinner than Singapore.
- IoT-vibration sensor convergence:Wireless accelerometers paired with cloud-based spectral analysis enable remote machinery diagnostics, reducing unplanned dry-docking triggers.
- EU Green Deal vessel retrofit incentives:Carbon intensity reduction subsidies accelerate wind-assist propulsion and air lubrication system installations at Iberian and Baltic yards.
Industry Challenges
- Welder certification pipelines:Classification societies including Lloyd's Register and DNV enforce strict multi-pass welding qualifications that outpace vocational training output in mature maritime economies.
- Legacy SCADA integration:Predictive maintenance platforms must interface with 1990s-era engine control systems lacking standardized data protocols, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat and Ship MRO Market |
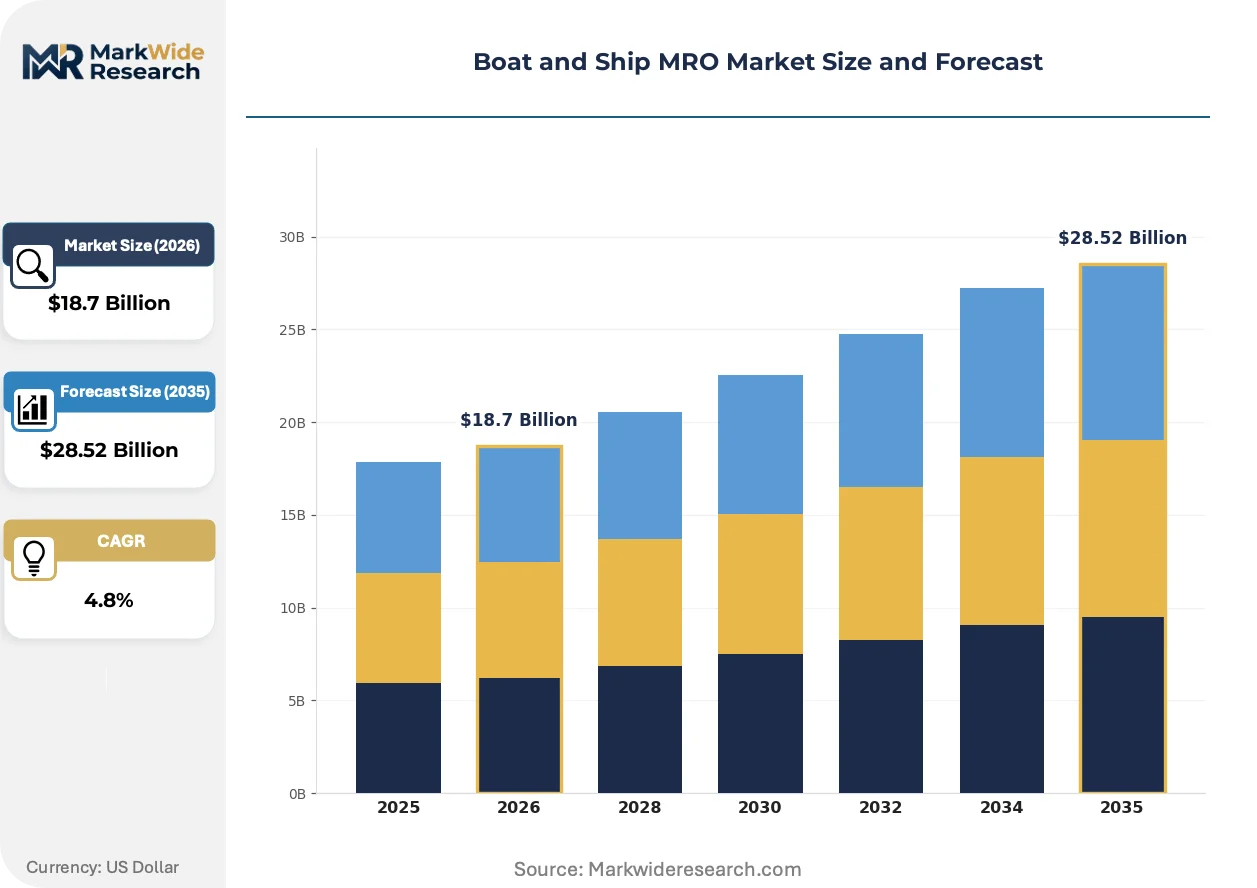
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engine Maintenance, Hull Repair, Electrical Servicing, Propulsion Overhaul Product Type: Fuel Systems, Navigation Equipment, Safety Gear, Interior Fixtures End User: Commercial Fleets, Leisure Vessels, Fishing Boats, Research Vessels Technology: Automated Monitoring, 3D Printing, Predictive Analytics, IoT Solutions |
| Companies Covered | Fincantieri S.p.A., Keppel Offshore & Marine Ltd, Huntington Ingalls Industries Inc., Seatrium Limited, Sembcorp Marine Ltd, BAE Systems PLC, Mitsubishi Heavy Industries Limited, Hyundai Heavy Industries Co., Damen Shipyards Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat and Ship MRO Market Strategic Shifts
Digital inspection tools and alternative fuel readiness are restructuring yard capabilities and fleet operator procurement criteria. Three developments dominate this transformation.
Wireless hull thickness sensors are miniaturizing. These magnetostrictive probes transmit ultrasonic pulse-echo data through Bluetooth mesh networks, eliminating manual gauging labor. Container lines including Maersk and MSC are piloting permanent sensor arrays on tanker fleets. This hardware footprint reduction is miniaturizing inspection access requirements, allowing autonomous underwater vehicles to complete Class surveys without dry-docking.
EPA marine diesel engine emission standards are tightening test protocols for Category 3 engines above 30 liters per cylinder. Commercial operators must demonstrate NOx compliance through onboard monitoring systems rather than periodic certification snapshots. US-flag Jones Act vessels face the most stringent enforcement, driving engine control module upgrades at Gulf Coast repair facilities.
Charterers now bundle MRO clauses into voyage contracts, transferring maintenance liability from owners to cargo interests. This risk reallocation concentrates repair decisions with commodity traders and oil majors rather than traditional ship managers. The Baltic Dry Index correlation with maintenance spending has weakened as a result, particularly in Capesize bulk carrier operations.
Boat and Ship MRO Market Segmentation
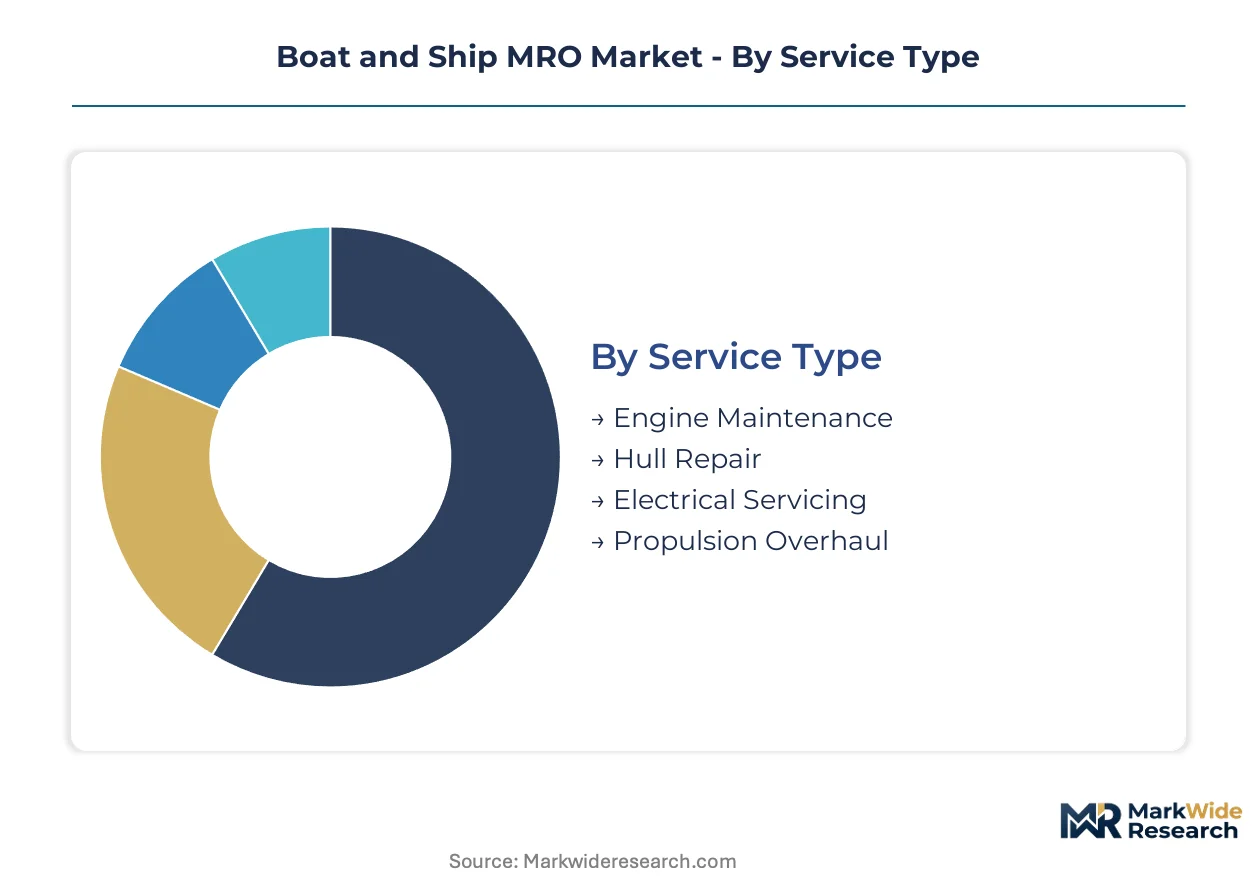
Segmentation in boat and ship MRO reveals how regulatory mandates and technology substitution reshape procurement priorities across service lines. Fleet operators allocate budgets differently when choosing between traditional dry-docking cycles and sensor-enabled predictive interventions.
Service Type:
Substitute pressure from condition-based monitoring platforms concentrates heaviest on scheduled maintenance categories that follow rigid calendar intervals.
- Engine Maintenance:Crankshaft machining, turbocharger refurbishment, and fuel injection system calibration restore propulsion reliability for two-stroke marine diesels. Demand clusters at Singapore's Jurong Port and Rotterdam's repair clusters where classification society surveyors maintain permanent presence.
- Propulsion Overhaul:Complete drivetrain teardowns including gearbox rebuilds and shaft alignment correction address torsional vibration failures. LNG carrier operators at Qatar's Ras Laffan complex drive specialized demand for cryogenic propulsion system expertise.
- Hull Repair:Steel plate renewal, crack welding, and cathodic protection replacement restore structural classification compliance.
- Electrical Servicing:Switchgear overhaul, generator rewinding, and automation system debugging sustain auxiliary power reliability.
Engine Maintenance anchors the volume base while Predictive Analytics substitution gains share at the steepest rate across this category.
Product Type:
Cost tier stratification separates capital-intensive navigation electronics from consumable safety equipment with divergent replacement cycles.
- Navigation Equipment:ECDIS upgrades, radar replacement, and GNSS receiver installations ensure SOLAS compliance for commercial certification. Deep-sea container lines at Hamburg and Busan prioritize multi-frequency receiver redundancy for polar route operations.
- Fuel Systems:Low-sulfur fuel piping, double-wall containment, and methanol-ready injection hardware address IMO sulfur cap retrofit mandates.
- Safety Gear:Liferaft servicing, fire suppression cylinder hydrotesting, and EPIRB battery replacement follow mandatory inspection calendars.
- Interior Fixtures:Galley equipment, HVAC components, and accommodation outfitting serve passenger vessel refurbishment cycles.
Navigation Equipment commands premium pricing tiers while Fuel Systems expands most quickly under emissions regulation pressure.
End User:
Customer type fragmentation creates distinct procurement patterns between asset-heavy commercial operators and discretionary leisure owners.
- Commercial Fleets:Container lines, tanker operators, and bulk carriers execute planned maintenance programs synchronized with charter schedules. Singapore's Keppel and Seatrium facilities capture concentrated demand from Asia-Pacific flag registries.
- Leisure Vessels:Yacht owners and marina-based operators follow seasonal maintenance windows with lower utilization intensity.
- Fishing Boats:Small-scale operators and industrial trawlers prioritize engine reliability over hull cosmetics given catch economics.
- Research Vessels:Academic and government science fleets require specialized winch, laboratory, and dynamic positioning system support.
Commercial Fleets generate absolute revenue scale while Research Vessels climb the fastest on specialized equipment upgrade cycles.
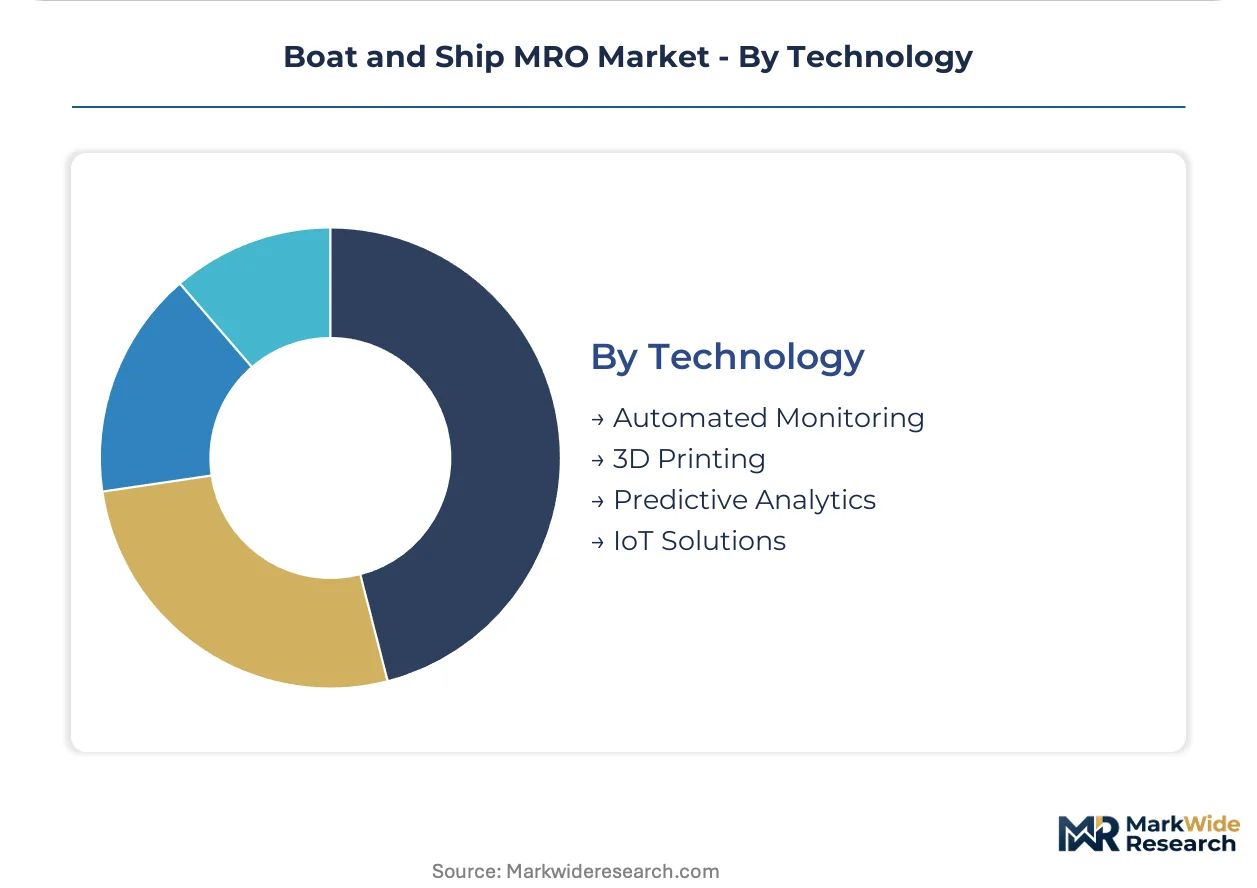
Technology:
Supply concentration in sensor hardware and cloud analytics platforms determines which yards can offer integrated predictive service bundles.
- IoT Solutions:Wireless vibration sensors, fuel consumption monitors, and hull stress telemetry transmit operational data through satellite links. Maersk and MSC pilot permanent sensor arrays on tanker fleets to compress unplanned dry-docking triggers.
- Predictive Analytics:Machine learning algorithms process spectral vibration data to forecast bearing failures and cylinder liner degradation.
- Automated Monitoring:Continuous engine parameter logging replaces periodic manual gauge readings for early fault detection.
- 3D Printing:On-demand spare part fabrication for obsolete pump housings and valve bodies reduces procurement lead times.
IoT Solutions anchors installed base expansion while Predictive Analytics shows the steepest adoption trajectory among technology-enabled operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Singapore's deepwater repair berths and integrated logistics infrastructure anchor Southeast Asian MRO gravity, drawing tonnage from across the Asia-Pacific maritime corridor.
Singapore
Jurong Port's specialized LNG carrier retrofit capabilities and permanent classification society surveyor presence concentrate demand from Asia-Pacific flag registries. The Maritime and Port Authority of Singapore enforces stringent environmental compliance standards for yard operations. Keppel Offshore & Marine and Seatrium facilities dominate deepwater repair capacity, executing crankshaft machining and cryogenic piping certifications for dual-fuel conversions.
United States
Jones Act vessel operators drive concentrated demand for engine control module upgrades and EPA Category 3 compliance testing at Gulf Coast facilities. The US Coast Guard and EPA jointly regulate commercial vessel emissions testing and hazardous waste disposal from shipyard sandblasting. Huntington Ingalls Industries anchors US Navy vessel lifecycle support through integrated public-private maintenance contracts across Virginia and Mississippi yards.
United Kingdom
Naval sustainment partnerships with the Ministry of Defence create sovereign MRO demand for complex warship refit programs. BAE Systems PLC competes across UK and Australian naval MRO through long-term government contracts. Portsmouth and Devonport dockyards maintain specialized nuclear submarine refueling capabilities alongside conventional surface vessel overhaul capacity.
South Korea
Hyundai Heavy Industries and Mitsubishi Heavy Industries drive demand for ultra-large container vessel engine overhauls and crankshaft machining. The Korean Register of Shipping audits repair quality and certifies structural integrity after major hull renewals. Busan and Ulsan clusters concentrate two-stroke marine diesel expertise, though in-situ grinding equipment scarcity creates repair bottlenecks for the largest vessel classes.
Germany
REACH compliance friction and restricted coating chemistries extend surface preparation timelines at European yards serving North Sea and Baltic fleets. The EU Green Deal vessel retrofit incentives accelerate wind-assist propulsion and air lubrication system installations at Hamburg and Bremen facilities. Lloyd's Register and DNV maintain permanent surveyor presence, enforcing strict multi-pass welding qualifications that outpace vocational training output.
Boat and Ship MRO Market Competitive Environment
Listed leaders compete with private specialists across sovereign defense contracts and commercial fleet maintenance, creating a tiered structure where scale-driven conglomerates share space with national champions. The vendor base segments into three archetypes: integrated defense contractors with government annuity streams, Asian shipbuilding conglomerates leveraging manufacturing depth, and European naval specialists with proprietary vessel-class expertise. Competitive moves concentrate on M&A-driven capability stacking and geographic expansion into Southeast Asian repair clusters.
Within the defense-contractor archetype, BAE Systems PLC and Huntington Ingalls Industries Inc. exemplify sovereign sustainment positioning through long-term government relationships. Keppel Offshore & Marine Ltd and Seatrium Limited occupy the commercial yard tier, anchoring Singapore's regional repair gravity with deepwater berth infrastructure. Hyundai Heavy Industries Co. represents the Asian conglomerate model, integrating newbuild capacity with lifecycle MRO services.
| Leading Market Players |
|---|
| Fincantieri S.p.A. |
| Keppel Offshore & Marine Ltd |
| Huntington Ingalls Industries Inc. |
| Seatrium Limited |
| Sembcorp Marine Ltd |
| BAE Systems PLC |
| Mitsubishi Heavy Industries Limited |
| Hyundai Heavy Industries Co. |
| Damen Shipyards Group |
| Others |
Value Chain & Pricing Dynamics
Crankshaft machining capacity utilization above eighty percent at Jurong Port and Busan clusters compresses yard pricing power while elevating price floors for ultra-large container vessel overhauls. Singapore's Keppel and Seatrium facilities leverage deepwater berth scarcity to maintain premium positioning for LNG carrier retrofits, whereas Indian Subcontinent yards compete on labor arbitrage for mid-life refits.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and volume scale. Premium tiers capture IMO-compliant ballast water retrofits and dual-fuel conversions at Singapore and South Korean yards with Lloyd's Register and DNV permanent surveyor presence. Standard tiers cover scheduled engine maintenance at mid-size facilities in Hamburg and Dubai. Economy tiers serve steel plate renewal and basic hull repair at Alang-Sosiya breakers. Cost compression in standard tiers is intensifying because Chinese mill supply volatility for EH36 and DH36 marine-grade steel feeds through to repair quotations. Container lines exhibit lowest price sensitivity given charterer-bundled MRO clauses, while fishing boat operators resist premium positioning.
Supply Chain Analysis
China and South Korea anchor EH36 and DH36 marine-grade steel production, with Japanese mills supplying specialized alloy grades for cryogenic piping. European yards draw from Nordic stainless steel producers for chemical tanker retrofit applications. The supply chain rests on crankshaft forging capacity concentrated at Hokkaido and Korean mill complexes, creating single-source vulnerability for two-stroke marine engine in-situ grinding equipment. Distribution runs through classification society-certified yard networks with permanent surveyor logistics, rather than spot-market procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Charterer consolidation into commodity trader and oil major hands shifts procurement leverage away from traditional ship managers, compressing incumbent margins while fragmenting repair demand across voyage-contract windows.
For Market Incumbents: Shield specialized cryogenic piping and dual-fuel retrofit capabilities through exclusive Korean Register of Shipping certification partnerships that emerging yards cannot replicate. Deepen in-house production of predictive analytics middleware to capture IoT-vibration sensor convergence demand from Maersk and MSC pilot programs. Capacity addition at Jurong Port deepwater berths reinforces Singapore's regional repair gravity against Indian Subcontinent labor cost competition. For New Entrants and Emerging Players: Predictive analytics platform gaps among legacy yards with 1990s-era SCADA infrastructure present immediate white-space opportunity. Wireless hull thickness sensor deployment for autonomous underwater vehicle Class surveys remains under-penetrated at European and North American facilities. Target Iberian and Baltic yards seeking EU Green Deal vessel retrofit incentive compliance for wind-assist propulsion installations. Go-to-market through Lloyd's Register and DNV certification pre-approval accelerates contract capture. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among predictive maintenance platform operators with multi-year fleet monitoring contracts. Long-term viability centers on yards integrating IoT Solutions with permanent classification society surveyor presence. Acquisition focus should target Southeast Asian repair clusters with cryogenic piping certification and crankshaft machining capacity. Watch for IMO greenhouse gas intensity indicator phase-in timelines as inflection signal for dual-fuel conversion demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Piping Certification Investment | Lloyd's Register and DNV dual-fuel retrofit approvals unlock LNG carrier maintenance contracts at Qatar's Ras Laffan complex. |
| Predictive Analytics Platform Integration | Wireless vibration sensor convergence with cloud-based spectral analysis compresses unplanned dry-docking triggers for container lines. |
| Backward Integration into Steel Plate Supply | Captive EH36 and DH36 marine-grade alloy sourcing insulates European yards from Chinese mill price volatility and delivery delays. |
| Geographic Expansion into Indian Subcontinent | Alang-Sosiya and Pipavav labor cost arbitrage captures mid-life vessel refit demand from Indonesian and Vietnamese flag fleets. |
| EU Green Deal Compliance Partnership | Wind-assist propulsion and air lubrication system installations at Hamburg facilities access carbon intensity reduction subsidies. |
Study Parameters
Cross-validation between Lloyd's Register and DNV classification society repair audit databases and shipyard production records anchors the qualitative findings in this study. Primary interviews with fleet operations directors, shipyard production managers, classification society surveyors, and marine equipment procurement officers combined with secondary validation from IMO regulatory filings, Korean Register of Shipping certification logs, and SEC filings from listed repair conglomerates. Bottom-up vessel-by-vessel dry-docking schedule analysis triangulates against top-down regional capacity utilization estimates.
Sensitivity analysis across regulatory phase-in timelines, steel price volatility scenarios, and alternative fuel adoption curves shapes the analytical framework. Segmentation dimensions modeled include service type, product tier, end-user category, and technology adoption intensity alongside vessel age profile and flag registry clusters. CAGRs derive from repair event frequency projections tied to IMO mandate compliance deadlines and fleet age distribution shifts. Industry-specific forecast inputs incorporate crankshaft machining capacity constraints and welder certification pipeline bottlenecks.
Forecasts assume regulatory continuity in IMO sulfur cap enforcement and ballast water management convention implementation; material policy shifts would require re-modeling. Specific risk factors include REACH compliance friction extending European yard surface preparation timelines and single-source vulnerability in two-stroke marine engine grinding equipment. Recalibration cycles align with material shifts in greenhouse gas intensity indicator phase-in schedules and charterer MRO clause bundling patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Boat Davits Market
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Global Hybrid and Full Electric Marine Propulsion Market
Marine Vehicles
Airboats Market
Marine Vehicles
Trawler Boat Market
Marine Vehicles
Marine Seats Market
Marine Vehicles
Marine Trailers Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
Yacht Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Europe Inland Waterways Vessel Market
Marine Vehicles
Air-Cushion Vehicle Market
Marine Vehicles
Sea-Based Vehicle Carrier Market