
 Marine Trailers Market | 2026-2036
Marine Trailers Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Trailers Market Analytics
Recreational boating fleets is consolidating as the dominant end-use vertical, while commercial fishing and government patrol segments hold steady. EZ Loader leverages its coastal distribution network to dominate saltwater-adjacent markets. Karavan Trailers anchors its position through cold-weather engineering for freshwater lake systems. HOSTAR Marine Transport Systems, Inc. specializes in heavy-lift configurations for commercial yards.
Marine trailers are load-bearing chassis assemblies engineered to transport watercraft between land and water, typically constructed from welded aluminum extrusions or hot-dip galvanized steel with sealed bearing hubs and adjustable bunk systems rated for specific hull weights. Their primary function is to enable safe trailering, launch retrieval, and dry-dock storage across recreational, commercial, and institutional fleets. Tandem axle configurations command the largest volume share due to balanced load distribution across mid-range boats. Aluminum material grades are capturing preference in saltwater regions where oxidation resistance extends service intervals. Heavy-duty trailer types concentrate margin pools in the commercial operator segment where payload ratings and regulatory compliance justify premium positioning.
The National Highway Traffic Safety Administration governs brake and lighting standards for road-legal marine trailers in the United States, while the European Committee for Standardization enforces CE marking and corrosion testing protocols for cross-border sales within the EU. These frameworks elevate engineering costs for multi-market suppliers but create barriers against low-specification imports. Stakeholders must monitor evolving axle-weight regulations and electric vehicle tow-rating harmonization as fleet electrification extends to tow vehicles.
Market Dynamics
Corrosion-resistant aluminum framing is displacing galvanized steel in saltwater-adjacent markets, forcing manufacturers to reconfigure welding processes and supplier relationships while recalibrating pricing architectures around material-grade premiums.
Growth Catalysts
- Recreational Fleet Expansion:Coastal U.S. states and Mediterranean marinas are registering record watercraft densities, pulling tandem-axle configurations into sustained replacement cycles.
- REACH Compliance Migration:European Committee for Standardization corrosion-testing protocols are elevating specification floors for cross-border sales, filtering low-grade imports from Eastern European supply channels.
- Electric Tow Vehicle Harmonization:NHTSA axle-weight recalibrations are accommodating heavier EV drivetrains, extending trailer brake-system upgrade demand across North American dealerships.
Market Restraints
- Aluminum Price Volatility:LME-grade aluminum input costs swing trailer manufacturing economics, compressing margin buffers for mid-tier producers dependent on spot-market purchasing.
- Galvanized Steel Oxidation Limits:Hot-dip coating degradation in saltwater environments shortens service intervals, creating warranty exposure and reputation risk for legacy product lines.
- Regional Production Concentration:Welded chassis fabrication clusters in the U.S. Upper Midwest and Nordic regions, exposing supply chains to winter logistics disruptions and labor tightness.
Strategic Opportunities
- Nordic Freshwater Systems:Sweden and Finland maintain underpenetrated commercial fishing fleets requiring cold-weather bunk engineering and sealed-bearing hub specifications distinct from temperate designs.
- EU Green Deal Procurement:Public marina infrastructure tenders are embedding lifecycle carbon metrics, advantaging aluminum recyclability credentials in institutional bidding.
- Digital Configuration Platforms:Direct-to-operator sizing tools are compressing dealer inventory requirements, enabling build-to-order workflows for specialized hull geometries.
Industry Challenges
- Certification Timeline Compression:Multi-market suppliers face staggered NHTSA brake-testing and CE marking corrosion protocols, elongating product launch windows.
- Welding Automation Skill Gaps:Aluminum TIG proficiency shortages in manufacturing hubs constrain throughput scaling for premium-grade chassis production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Trailers Market |
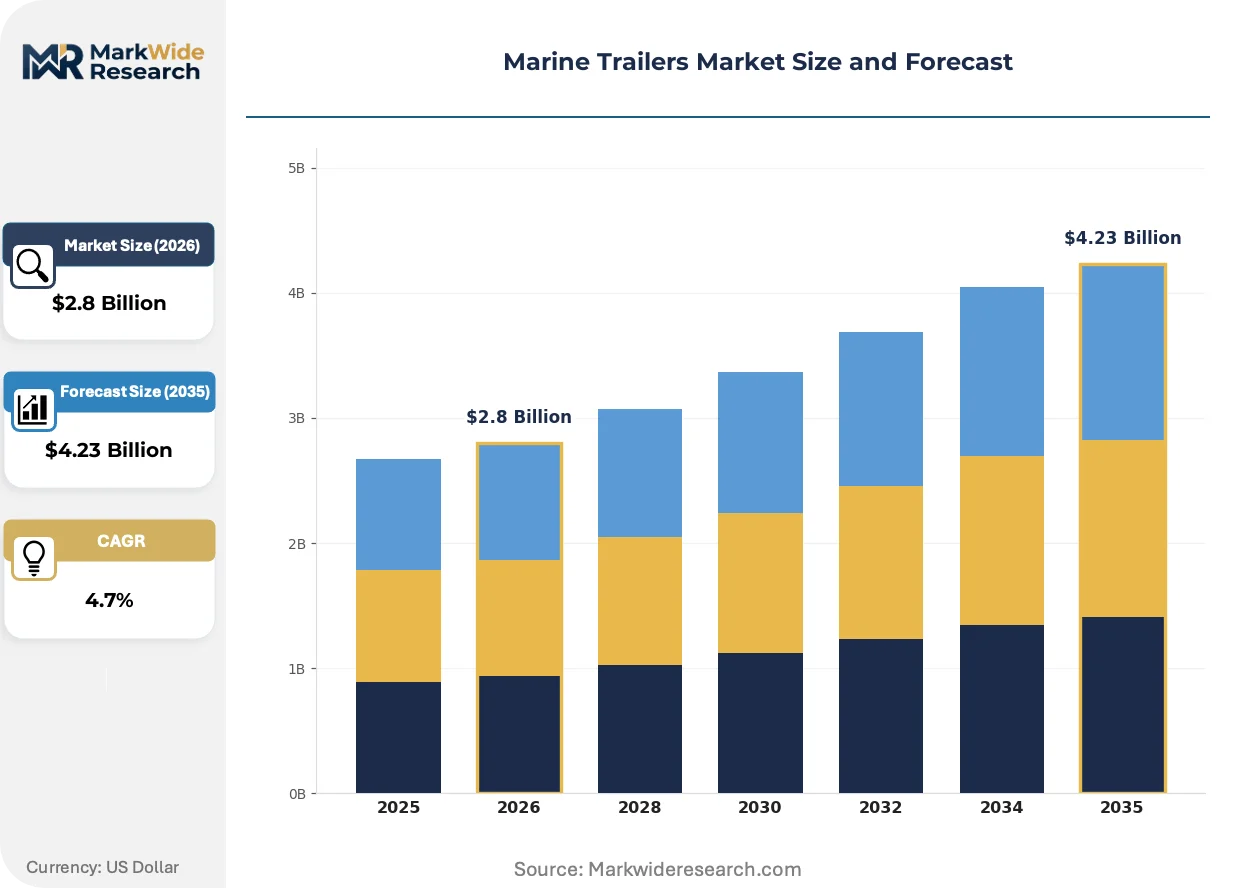
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trailer Type: Single Axle, Tandem Axle, Tri-Axle, Heavy-Duty Material: Aluminum, Steel, Polymer, Composite Use Case: Boat Transport, Jet Ski Transport, Launching, Storage End User: Recreational Users, Commercial Operators, Rental Services, Government Agencies |
| Companies Covered | EZ Loader, Karavan Trailers, Kropf Industrial Inc., Malibu Boats LLC, Magic Tilt Trailers, HOSTAR Marine Transport Systems, Inc., Load Rite Trailers Inc., Venture Trailers, TRIGANO Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Trailers Market Evolving Landscape
Connected chassis monitoring and predictive maintenance modules are penetrating commercial operator fleets, while regulatory pressure on material traceability accelerates supply-chain digitization across manufacturing tiers.
Automated bunk-positioning systems using laser-guided hull profiling are automating launch-retrieval workflows for high-frequency commercial yards. Harbor service operators in Florida and California are piloting these configurations to reduce dockside labor. The technology is automating trailer-to-vessel alignment precision previously dependent on manual winch adjustment.
NHTSA lighting-standard updates are mandating sealed LED assemblies with integrated fault diagnostics, eliminating incandescent bulb maintenance for road-legal configurations. Trailer OEMs serving the U.S. market are redesigning wiring harness architectures to accommodate these sealed modules. Saltwater-adjacent fleets face the steepest compliance retrofit obligations.
Buyer concentration among multi-vessel fleet operators is compressing procurement cycles and unbundling after-sales service from hardware transactions. Large marina management groups in Texas and the Carolinas are negotiating direct manufacturer relationships, bypassing traditional dealer networks. This channel migration concentrates volume with vertically integrated suppliers capable of captive maintenance provisioning.
Marine Trailers Market Segmentation
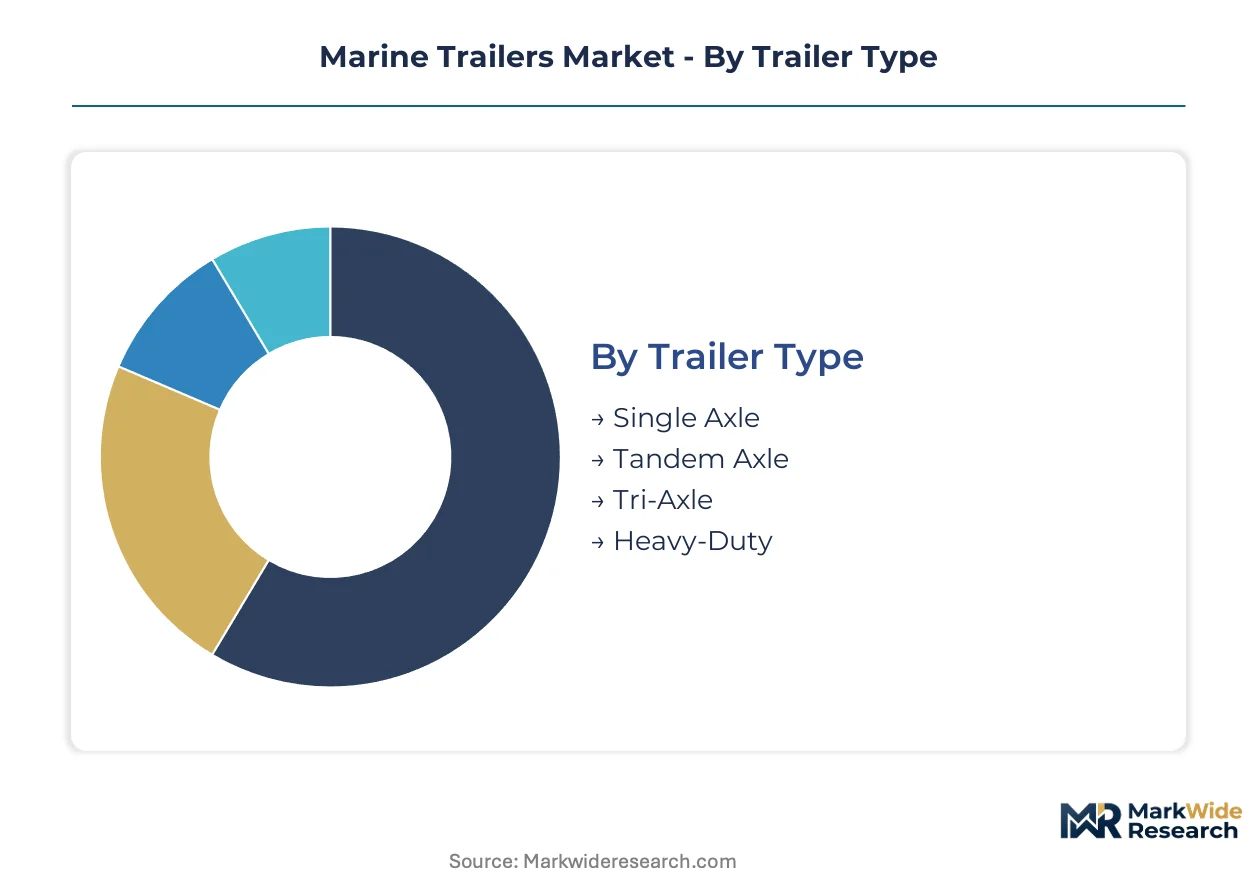
Marine trailer specifications diverge sharply between standardized mass-market configurations and engineered-to-order systems for specialized hull geometries. Segmentation discipline separates volume-driven replacement cycles from margin-rich custom fabrication, directing capital allocation across welding automation and dealer network strategies.
Trailer Type:
Customization intensity rises with axle count, creating a spectrum from commodity single-axle units to fully engineered heavy-duty platforms requiring structural certification.
- Tandem Axle:Dual-axle configurations distribute hull weight across four contact points, accommodating mid-range recreational craft between 2,000 and 5,000 pounds. Demand concentrates in Florida, Texas, and California coastal counties where boat density drives replacement turnover.
- Heavy-Duty:Reinforced chassis assemblies with triple or quad axle arrangements handle commercial fishing vessels and patrol craft exceeding 8,000 pounds. Nordic commercial yards in Norway and Sweden specify these for ice-strengthened hulls requiring launch retrieval in sub-zero conditions.
- Single Axle:Compact welded frames rated for personal watercraft and small fishing boats under 2,000 pounds.
- Tri-Axle:Three-axle spreads for large recreational cruisers and light commercial applications demanding enhanced stability.
Leading the category by volume: Tandem Axle. Expanding most quickly: Heavy-Duty.
Material:
Cost tiers separate commodity steel from aerospace-grade aluminum extrusions, with polymer and composite alternatives occupying emerging niches.
- Aluminum:6061-T6 and 5083-H321 alloy extrusions deliver saltwater corrosion resistance without galvanic degradation. Mediterranean marinas from Barcelona to Athens specify aluminum framing to extend service intervals in high-salinity environments.
- Steel:Hot-dip galvanized mild steel dominates freshwater lake systems where oxidation exposure remains minimal. Upper Midwest fabricators in Wisconsin and Michigan maintain cost advantages through proximity to steel coil suppliers.
- Polymer:Rotomolded polyethylene bunk systems and fender assemblies reduce maintenance in rental fleet applications.
- Composite:Glass-reinforced thermoplastic structural members target weight-sensitive electric tow vehicle pairings.
Dominating unit economics: Steel. Gaining share fastest: Aluminum.
Use Case:
Application specificity ranges from universal transport platforms to dedicated launch-assist systems requiring hydraulic integration.
- Boat Transport:Highway-legal configurations with NHTSA-compliant brake and lighting systems enable long-distance hull relocation. Interstate corridors connecting Great Lakes manufacturing to Gulf Coast marinas generate sustained demand for road-rated chassis.
- Launching:Submersible or roller-equipped trailers facilitate water entry without trailer immersion, critical for high-frequency commercial yards. Harbor service operators in San Diego and Charleston deploy these for daily launch-retrieval cycles.
- Jet Ski Transport:Lightweight single-axle frames sized for personal watercraft under 1,000 pounds.
- Storage:Fixed-position rack systems for dry-stack marina facilities, prioritizing vertical density over mobility.
Highest shipment frequency: Boat Transport. Steepest expansion trajectory: Launching.
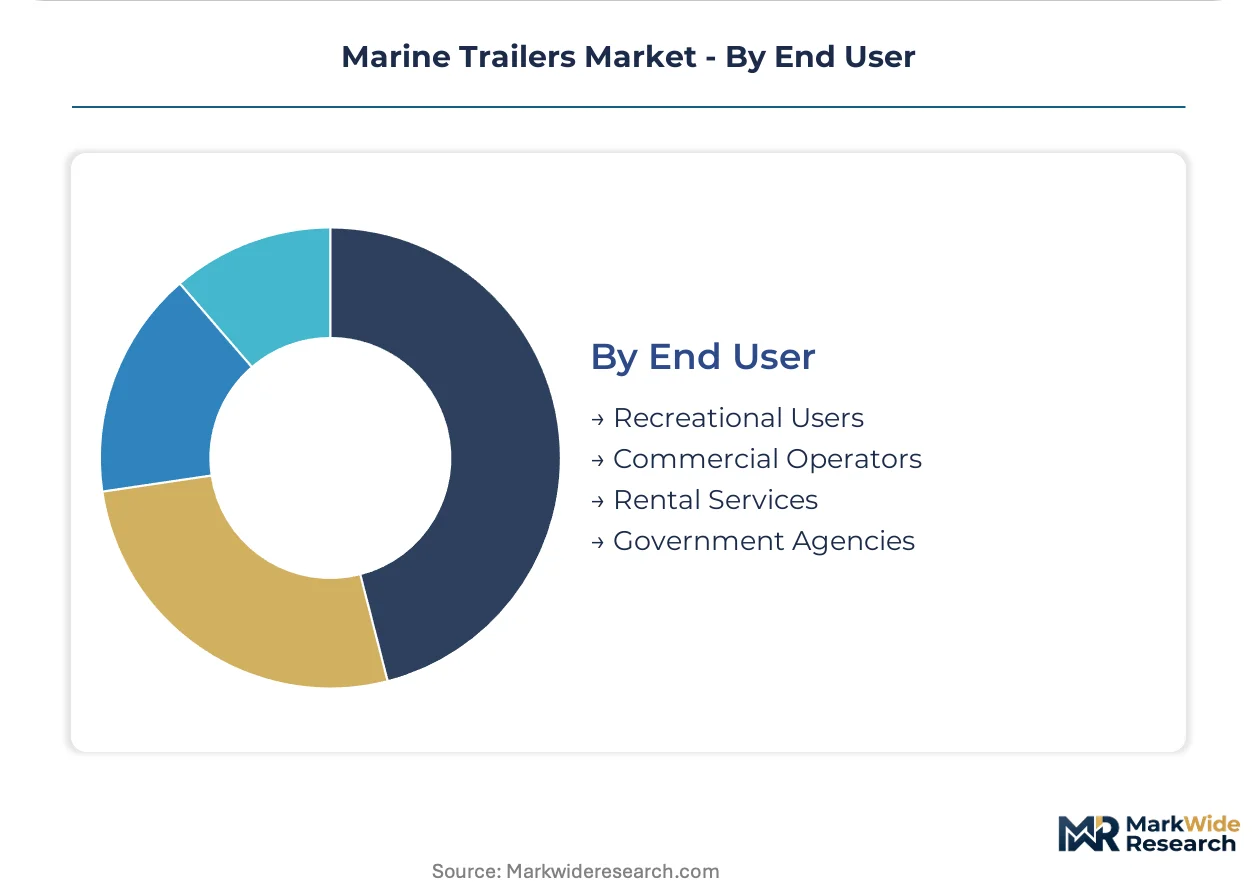
End User:
Customer type determines procurement channel, with recreational buyers transacting through dealer networks and commercial operators negotiating direct manufacturer relationships.
- Recreational Users:Individual boat owners purchasing through marine dealerships or direct-to-consumer platforms. Coastal U.S. states from Virginia to Georgia exhibit dense recreational ownership driving seasonal replacement peaks.
- Commercial Operators:Fishing fleets, harbor services, and charter businesses requiring fleet-scale procurement with captive maintenance provisions. Multi-vessel operators in the Pacific Northwest negotiate volume contracts bypassing traditional distribution.
- Rental Services:Seasonal fleet operators prioritizing standardized configurations for rapid turnaround and minimal training.
- Government Agencies:Patrol and rescue craft specifications governed by public procurement rules with lifecycle cost evaluation.
Capturing largest volume share: Recreational Users. Procurement is shifting most rapidly toward direct engagement: Commercial Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal enterprise zones in Florida and Texas concentrate recreational boat manufacturing, pulling trailer fabrication into adjacent industrial corridors. NHTSA brake-testing facilities in Ohio and Michigan anchor certification infrastructure for North American suppliers. Mediterranean port authorities in Spain and Italy are expanding marina capacity under EU Green Deal procurement frameworks.
United States
Florida's Space Coast and Texas Gulf Coast register the densest recreational boat ownership globally, driving tandem-axle replacement cycles. NHTSA lighting-standard updates mandate sealed LED assemblies with integrated fault diagnostics. Trailer OEM clusters in Wisconsin and Michigan leverage proximity to steel coil suppliers for cost-competitive freshwater lake configurations.
Sweden
Nordic freshwater systems sustain underpenetrated commercial fishing fleets requiring cold-weather bunk engineering distinct from temperate designs. EU corrosion-testing protocols under CE marking elevate specification floors for cross-border sales. Industrial fabricators in Gothenburg and Stockholm specialize in ice-strengthened hull launch-retrieval systems for sub-zero conditions.
Italy
Mediterranean marinas from Genoa to Naples exhibit record watercraft densities, pulling aluminum-framed trailer demand for saltwater corrosion resistance. EU Green Deal procurement embeds lifecycle carbon metrics in public marina infrastructure tenders. Manufacturing clusters in Lombardy and Veneto supply CE-marked configurations across Southern European coastal zones.
Germany
Baltic Sea recreational fleets and inland waterway commercial operators generate dual-channel demand for highway-legal and launch-assist configurations. REACH compliance migration filters low-grade imports from Eastern European supply channels. Fabrication hubs in North Rhine-Westphalia and Bavaria serve as distribution gateways for Central European marina networks.
Canada
Great Lakes recreational boating and Pacific Northwest commercial fishing sustain seasonal replacement peaks for galvanized steel and aluminum configurations. Transport Canada harmonizes brake and lighting standards with NHTSA frameworks for cross-border fleet compatibility. Ontario and Quebec manufacturing bases supply freshwater-optimized chassis for Prairie Provinces and Atlantic Canada lake systems.
Marine Trailers Market Competitive Landscape
Top-tier vendors anchor premium aluminum and heavy-duty segments, while mid-tier fabricators compete on galvanized steel volume for freshwater markets. The vendor base stratifies across coastal distribution networks, cold-weather engineering specialists, and commercial yard heavy-lift providers. Three archetypes dominate: saltwater-corrosion specialists, freshwater-cost optimizers, and commercial-operator direct-contractors. Competitive moves concentrate on welding automation investments and direct-to-fleet procurement channel development.
Within the coastal-distribution archetype, EZ Loader occupies a position exemplifying saltwater-adjacent market penetration through regional dealer networks. Karavan Trailers represents cold-weather engineering specialization for freshwater lake systems in northern climates. HOSTAR Marine Transport Systems, Inc. anchors the heavy-lift configuration tier for commercial yard operators requiring structural certification for specialized hull geometries.
| Leading Market Players |
|---|
| EZ Loader |
| Karavan Trailers |
| Kropf Industrial Inc. |
| Malibu Boats LLC |
| Magic Tilt Trailers |
| HOSTAR Marine Transport Systems, Inc. |
| Load Rite Trailers Inc. |
| Venture Trailers |
| TRIGANO Group |
| Others |
Value Network & Pricing Analysis
Fleet operator procurement consolidation across Texas and Carolina marina management groups is forcing manufacturers toward direct-contract pricing models and captive maintenance bundling, compressing dealer margins while elevating volume-tier discounts for vertically integrated suppliers.
Pricing Analysis
Short lead-time premiums command fifteen to twenty percent markups over standard build cycles in the marine trailer sector, with spot inventory from Upper Midwest fabricators trading at discounts during winter production slowdowns. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade aluminum configurations from hot-dip galvanized steel and bare mild steel alternatives. Cost compression in mid-tier galvanized segments is intensifying because LME aluminum volatility transfers margin pressure downstream. Commercial operators exhibit lowest price sensitivity due to lifecycle cost evaluation frameworks, while individual recreational buyers in coastal Florida counties drive hardest bargain hunting.
Supply Chain Analysis
Single-source vulnerability sits with Nordic cold-weather hub suppliers in Gothenburg and Stockholm, where ice-strengthened hull launch-retrieval system fabrication concentrates. Raw material flows draw from LME-grade aluminum smelters, hot-dip galvanizing facilities in Michigan and Wisconsin, and sealed-bearing hub manufacturers in Germany. Tariff exposure on Chinese aluminum extrusions threatens margin stability for saltwater-corrosion specialists. Distribution runs through coastal dealer networks in Florida and Texas, direct fleet contracts with Pacific Northwest commercial operators, and marina management group procurement portals bypassing traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine trailer sector sits in a material-transition phase, with aluminum TIG welding proficiency displacing legacy galvanized steel fabrication across saltwater-adjacent markets.
For Market Incumbents: Cement coastal distribution control through exclusive dealer network investments in Florida and Texas, while accelerating aluminum welding automation to offset skilled labor scarcity threatening throughput scaling. Defend against direct-to-fleet channel migration by embedding predictive maintenance modules and captive service provisioning in commercial operator contracts. For New Entrants and Emerging Players: The price-point gap between premium aluminum heavy-duty configurations and economy galvanized steel creates entry space for composite-reinforced mid-tier alternatives targeting electric tow vehicle harmonization requirements. Target Nordic freshwater systems with cold-weather bunk engineering distinct from temperate designs, leveraging digital configuration platforms for build-to-order workflows that compress dealer inventory requirements. For Investors and Strategic Acquirers: Re-rating potential sits with welding-automation-capable mid-tier fabricators given NHTSA brake-system upgrade demand across North American dealerships. Five-to-ten year viability favors suppliers with backward integration into aluminum extrusion and captive galvanizing capacity. Monitor EU Green Deal procurement embedding lifecycle carbon metrics as inflection signal for aluminum recyclability credential premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Welding Automation Investment | Aluminum TIG proficiency shortages constrain premium-grade chassis throughput scaling for saltwater markets. |
| Direct Fleet Contracting | Marina management groups in Texas and Carolinas bypass dealer networks, concentrating volume with integrated suppliers. |
| Backward Integration into Extrusion | Captive 6061-T6 and 5083-H321 alloy supply hedges LME volatility exposure for corrosion-resistant framing. |
| Predictive Maintenance Module Development | Connected chassis monitoring penetrates commercial fleets, unbundling after-sales service from hardware transactions. |
| CE Marking Certification Acceleration | REACH compliance migration filters low-grade imports, elevating specification floors for cross-border European sales. |
Research Methodology
Trade association filings, customs records, and SEC 10-K disclosures formed the secondary backbone, supplemented by primary interviews with marine trailer OEM procurement directors, marina management group fleet operators, NHTSA brake-testing facility engineers, and aluminum extrusion plant managers. Bottom-up unit shipment tallies across tandem-axle, heavy-duty, and single-axle configurations were triangulated against top-down recreational boat registration data and commercial fishing fleet capacity surveys.
Historical trendline analysis across boat transport, launching, and storage use cases established baseline growth patterns, with segmentation modeling across trailer type, material grade, and end-user archetype driving volume projections over the analysis window. CAGRs were derived from replacement cycle frequencies in Florida coastal counties, Mediterranean marina capacity expansion permits, and Nordic commercial fishing fleet modernization timelines. Electric vehicle tow-rating harmonization and EU corrosion-testing protocol evolution served as structural demand modifiers.
Inputs from harbor service operator maintenance logs and marina infrastructure tender databases were available through the study window; gaps in real-time aluminum spot pricing granularity and welding labor availability forecasts introduce uncertainty bands around margin compression scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Air-Cushion Vehicle Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Yacht Market
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Global Luxury Boat Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Boat Davits Market
Marine Vehicles
Outboard Boats Market
Marine Vehicles
Marine Electric Vehicle Market
Marine Vehicles
Trawler Boat Market