
 Global Catamaran Market | 2026-2036
Global Catamaran Market Size, Share, and Industry Trends Forecast 2026-2036
Global Catamaran Market Analysis
Market Context
CE certification under the EU Recreational Craft Directive is unwinding the competitive landscape for builders exporting into European waters. Lagoon Catamarans leverages its production scale in Bordeaux to dominate the sailing multihull segment. Fountaine Pajot sustains its position through vertical integration into composite manufacturing at its La Rochelle facility. Sunreef Yachts differentiates via its specialization in fully custom electric-hybrid superyacht catamarans from its Gdansk yard.
Technical Definition and Segment Structure
A catamaran is a twin-hulled marine vessel constructed from fiberglass-reinforced polymer, carbon fiber, or aluminum, with hull slenderness ratios typically below 8:1 and bridge deck clearance optimized to reduce wave slap; its primary purpose spans leisure cruising, commercial passenger transport, and blue-water research operations. Sailing catamarans anchor the volume base across private owner and charter service end users, while power catamarans represent the fastest-growing product type as commercial operators replace monohull ferries for inter-island routes. Luxury catamarans concentrate margin pools in the extra-large size band, where bespoke interior fit-out and hybrid propulsion command substantial price premiums over standard production models.
Regulatory Environment and Outlook
FDA marine sanitation device standards, EPA Clean Air Act Tier 3/4 emissions rules for diesel propulsion, and ISO 12217 stability and buoyancy standards collectively shape hull design, engine selection, and market access for builders targeting US and international buyers. The EU Green Deal's push for maritime decarbonization is forcing power catamaran developers to accelerate battery-electric and hydrogen fuel cell integration. Stakeholders must monitor how emerging flag-state rules on carbon intensity indicators redirect charter fleet procurement toward lower-emission hull configurations.
Market Dynamics
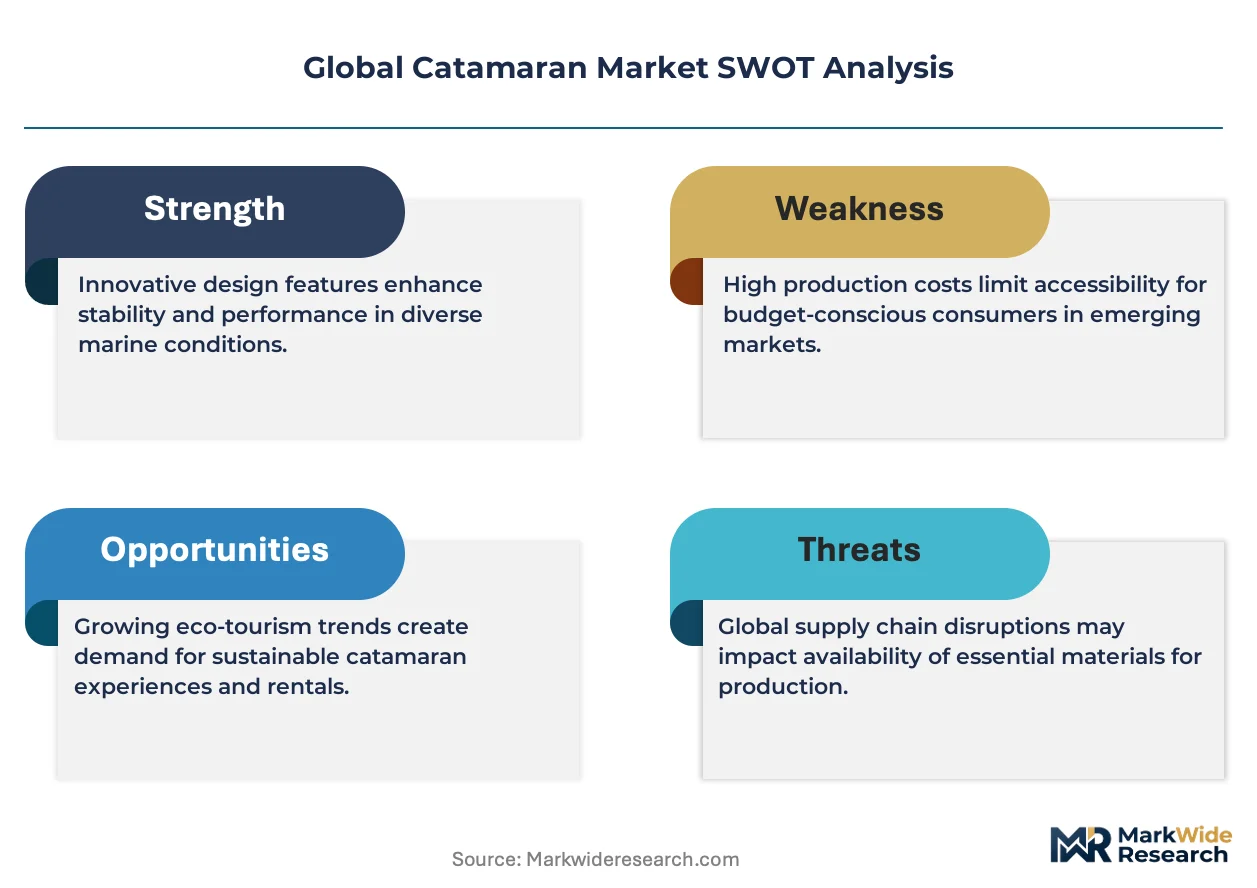
EU maritime decarbonization mandates are compressing the development timeline for zero-emission propulsion systems, forcing builders to retool production lines ahead of regulatory deadlines.
Growth Catalysts
- Coastal tourism concentration:Charter operators in Greece and Croatia are expanding fleet capacity to capture rebounding Mediterranean leisure travel demand.
- F-Gas Regulation compliance:The EU's tightening refrigerant standards for marine HVAC systems are accelerating replacement cycles in existing commercial fleets.
- Battery-electric propulsion:Falling lithium-ion pack costs are enabling viable electric-hybrid configurations for short-haul passenger ferry routes.
Market Restraints
- Carbon fiber supply concentration:Japanese and US aerospace-grade fiber producers control pricing for high-performance composite hull construction.
- Skilled laminator scarcity:The pool of certified composite technicians in Western European shipyards is shrinking faster than training programs can replenish.
- ISO 12217 certification timelines:Stability testing protocols for novel multihull configurations extend time-to-market by 8-14 months.
Strategic Opportunities
- Research vessel conversion:Oceanographic institutes are retrofitting aging monohull fleets with catamaran hulls for improved station-keeping stability.
- Inter-island ferry electrification:Caribbean and Southeast Asian governments are tendering battery-electric routes to replace diesel monohulls.
- CE marking automation:Digital compliance platforms are streamlining EU Recreational Craft Directive documentation for smaller builders.
Industry Challenges
- Naval architect pipeline:University programs specializing in multihull hydrodynamics graduate fewer than 40 qualified designers annually across France, UK, and Australia combined.
- Propulsion system integration:Matching electric motor torque curves with sailing rig aerodynamics requires cross-disciplinary engineering teams that most yards lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Catamaran Market |
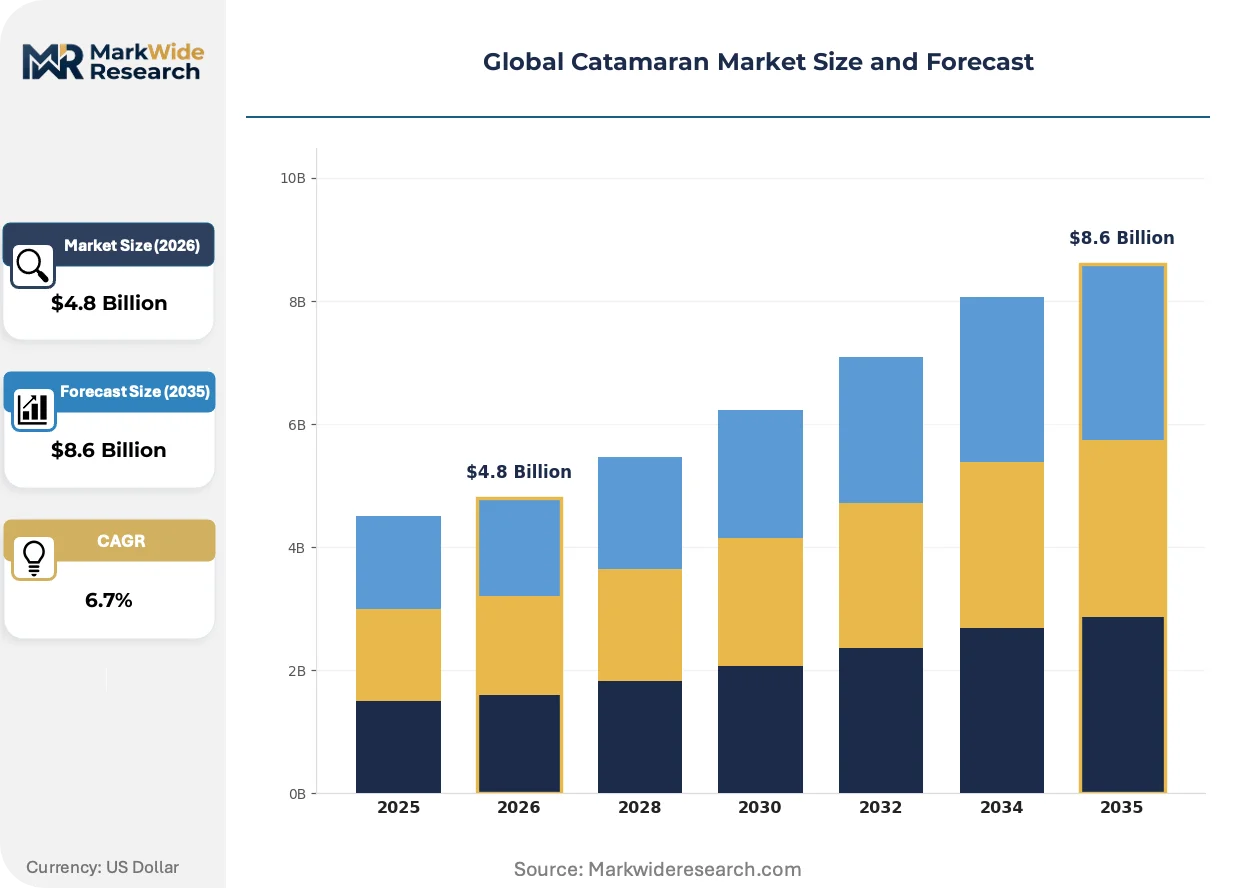
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sailing Catamarans, Power Catamarans, Commercial Catamarans, Luxury Catamarans End User: Private Owners, Charter Services, Commercial Operators, Research Institutions Application: Recreational, Transportation, Tourism, Research Size: Small, Medium, Large, Extra Large |
| Companies Covered | Lagoon Catamarans, Fountaine Pajot, Leopard Catamarans, Sunreef Yachts, Beneteau Group, Seawind, Robertson & Caine, Outremer Yachting, Catana Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Catamaran Market Emerging Trajectories
Propulsion architecture is splitting into parallel development tracks as commercial operators demand emission compliance while private owners prioritize range autonomy.
Hybrid diesel-electric drivetrains are bifurcating the power catamaran segment. Commercial ferry operators in Norway and Denmark are adopting serial-hybrid configurations with shore-charging infrastructure. Private owners in the Mediterranean resist the range penalty, sustaining demand for conventional diesel. This split is forcing builders to maintain dual engineering teams and parallel supply chains.
The EU Green Deal's carbon intensity indicators are rewriting charter fleet procurement criteria. Operators now face documented penalties for high-emission hulls under emerging flag-state rules. Greek and Croatian charter companies are responding by specifying hybrid-electric newbuilds with shore-power capability in port.
Direct-to-owner digital sales channels are displacing traditional broker networks for semi-custom builds. Lagoon Catamarans and Fountaine Pajot have both launched configuration platforms allowing buyers to specify interiors without showroom visits. This shift is most advanced in the Australian and US markets where buyer familiarity with production brands reduces the broker's information role.
Global Catamaran Market Segmentation
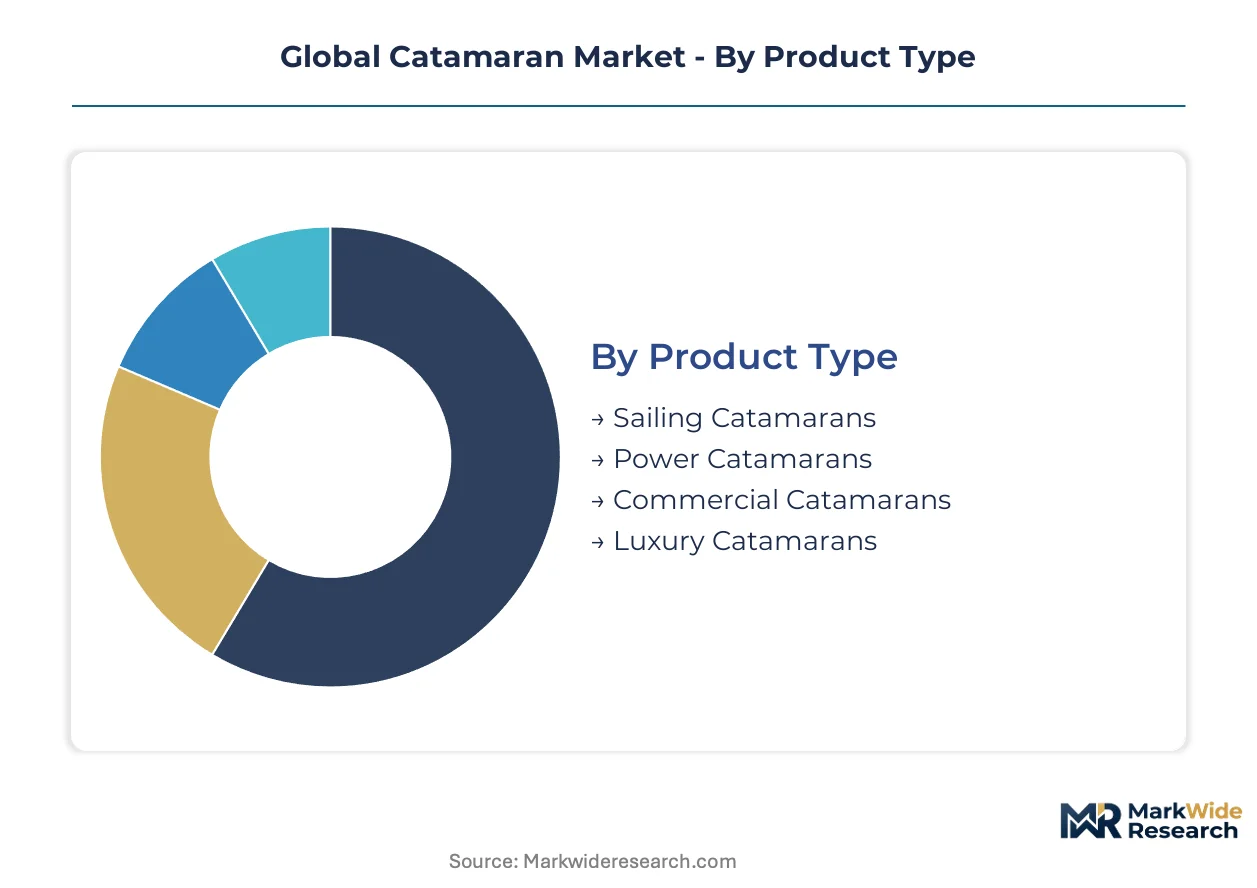
Catamaran market segmentation reveals how hull architecture, ownership models, and operational missions fragment both production economics and aftermarket service requirements. Builders must align composite layup schedules, propulsion system sourcing, and certification pathways against distinct margin profiles across each dimension.
Product Type:
Margin pools concentrate in hybrid-electric configurations where bespoke engineering commands substantial premiums over standardized production hulls.
- Sailing Catamarans:Twin-hulled vessels driven by aerodynamic sail plans and daggerboard hydrodynamics, constructed predominantly from fiberglass-reinforced polymer with carbon fiber reinforcement in high-load zones. Demand clusters in Mediterranean charter fleets operating from Greek island bases, where shallow draft enables access to restricted anchorages that monohulls cannot reach.
- Power Catamarans:Motor-driven twin-hull designs optimized for fuel efficiency through reduced wetted surface area, with bridge deck clearance engineered to minimize wave slap at cruising speeds. Norwegian and Danish ferry operators are specifying serial-hybrid configurations with shore-charging infrastructure for inter-island routes.
- Commercial Catamarans:High-density passenger vessels built to SOLAS stability standards with aluminum or steel hulls for durability under intensive duty cycles. Caribbean governments are tendering battery-electric replacements for aging diesel monohull fleets.
- Luxury Catamarans:Fully custom superyacht builds exceeding 24 meters LOA with hybrid propulsion, integrated smart-home systems, and interior fit-out by named design studios. Sunreef Yachts dominates this tier from its Gdansk facility.
The dominant share belongs to Sailing Catamarans, while Power Catamarans is closing the gap fastest.
End User:
Procurement patterns diverge sharply between emotionally driven private purchases and total-cost-of-ownership calculations governing fleet operators.
- Private Owners:Individual buyers prioritizing liveaboard comfort, blue-water range autonomy, and resale value retention; purchasing decisions hinge on broker relationships and sea trial experiences. Australian and US buyers increasingly configure interiors through direct-to-manufacturer digital platforms.
- Charter Services:Fleet operators in Greece and Croatia expanding vessel counts to capture rebounding Mediterranean leisure travel demand, with EU Green Deal carbon intensity indicators now embedded in procurement scoring.
- Commercial Operators:Scheduled passenger ferry companies and water taxi services governed by public tender requirements, flag-state safety mandates, and lifecycle cost modeling over 15-20 year horizons.
- Research Institutions:Oceanographic institutes retrofitting aging monohull fleets with catamaran hulls for improved station-keeping stability during instrument deployment operations.
Charter Services commands the largest order book volume, though Research Institutions is expanding most quickly through government-funded vessel replacement programs.
Application:
Operational intensity and regulatory exposure vary dramatically across mission profiles, dictating hull material selection and maintenance scheduling.
- Recreational:Leisure cruising and day-sailing activities under private or bareboat charter use, subject to CE marking under the EU Recreational Craft Directive for European waters.
- Transportation:Scheduled passenger and vehicle ferry services on inter-island routes, governed by SOLAS stability requirements and flag-state carbon intensity regulations.
- Tourism:Day-trip excursion vessels and liveaboard dive platforms operating from coastal Mediterranean and Southeast Asian hubs, with F-Gas Regulation compliance driving HVAC replacement cycles.
- Research:Oceanographic survey platforms requiring precise station-keeping and instrument payload capacity, with hull designs optimized for minimal acoustic signature.
Tourism generates the highest unit volumes, yet Transportation is climbing the fastest as electrification tenders proliferate across island jurisdictions.
Size:
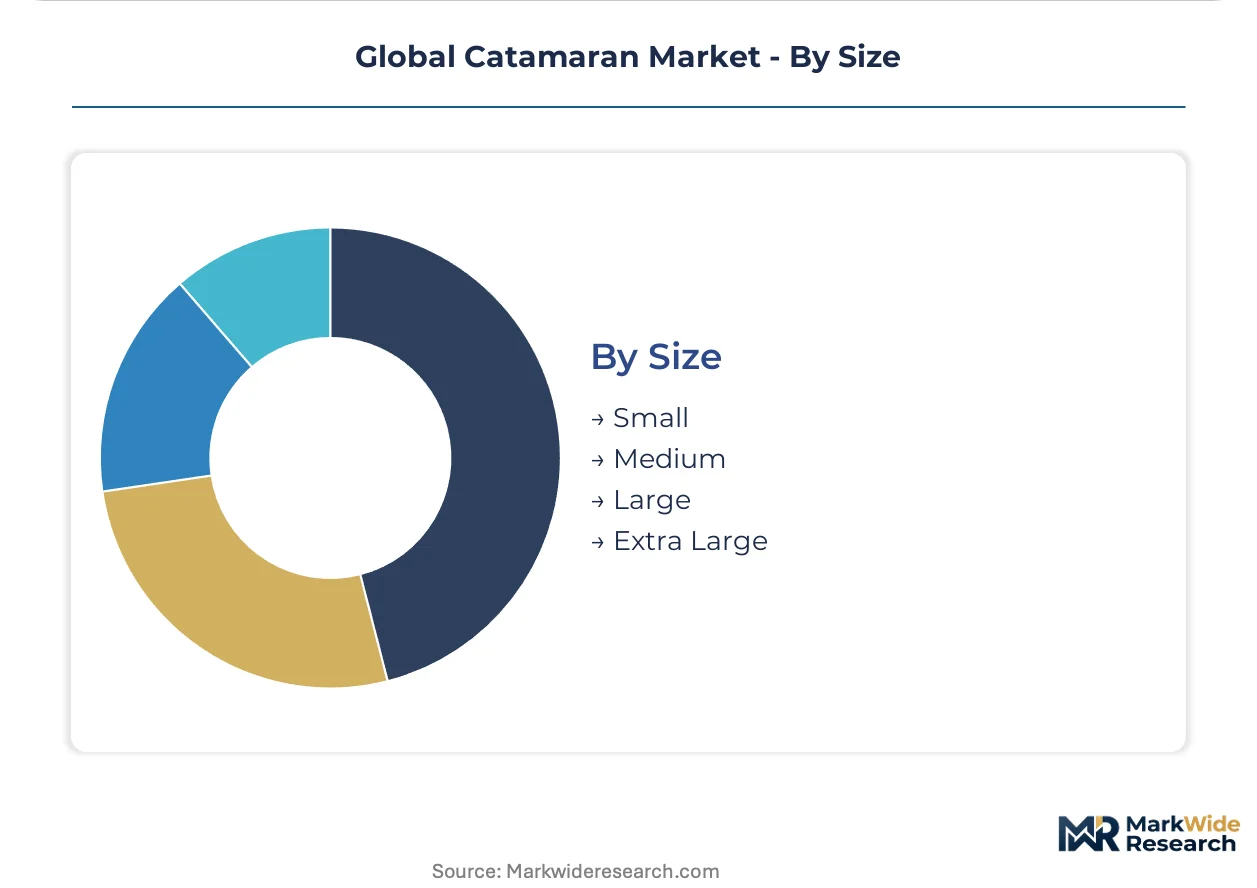
Production economics invert across size bands, with small hulls rewarding manufacturing scale and extra-large builds capturing value through engineering customization.
- Small:Vessels under 12 meters LOA, predominantly fiberglass production builds from standardized molds with limited interior configuration options.
- Medium:12-18 meter range balancing liveaboard accommodation with marina accessibility, representing the volume core for European charter fleet operators.
- Large:18-24 meter segment where semi-custom interior fit-out and hybrid propulsion options become technically and economically viable.
- Extra Large:Exceeding 24 meters LOA with fully bespoke engineering, classification society oversight, and multi-year build timelines; ISO 12217 stability testing protocols extend time-to-market by 8-14 months for novel configurations.
Medium sizes anchor production throughput, though Extra Large is gaining share fastest through superyacht commissioning activity in Mediterranean and Middle Eastern markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU maritime decarbonization mandates are redirecting fleet procurement across coastal jurisdictions, with national governments layering subsidy programs atop flag-state carbon intensity rules to accelerate hull replacement cycles.
France
Charter operators in Marseille and Nice are expanding sailing catamaran fleets to capture rebounding Mediterranean leisure travel. The EU F-Gas Regulation tightens refrigerant standards for marine HVAC systems, accelerating replacement demand. Bordeaux hosts Lagoon Catamarans' production facility, which leverages manufacturing scale to dominate the sailing multihull segment.
Croatia
Greek island charter routes are driving fleet expansion among Croatian operators seeking to capture spillover demand from Adriatic cruising corridors. CE marking under the EU Recreational Craft Directive governs hull certification for European waters. Split and Dubrovnik anchor the regional charter hub, with operators specifying hybrid-electric newbuilds to meet emerging carbon intensity scoring.
United States
EPA Clean Air Act Tier 3/4 emissions rules are reshaping diesel propulsion selection for power catamarans operating coastal routes. Florida bareboat charter fleets are digitizing procurement through direct-to-manufacturer configuration platforms. Fort Lauderdale concentrates brokerage and refit activity for Caribbean-bound vessels.
Australia
Private owners in Sydney and Brisbane are adopting digital sales channels to configure semi-custom interiors without showroom visits. ISO 12217 stability testing protocols extend time-to-market for novel multihull configurations. The Gold Coast hosts Seawind's production operations, supplying hulls to Pacific charter markets.
Poland
Gdansk has emerged as a superyacht catamaran construction center, with builders specializing in fully custom electric-hybrid configurations exceeding 24 meters LOA. The EU Green Deal's carbon intensity indicators are embedding in procurement criteria for Mediterranean charter fleets. Polish yards are capturing premium margin pools through bespoke engineering and extended build timelines.
Global Catamaran Market Vendor Landscape
Listed leaders compete with private specialists across production scale and customization depth. The vendor base splits between volume manufacturers of standardized fiberglass hulls and boutique yards executing multi-year bespoke builds. Three archetypes dominate: scale-driven production houses, semi-custom configurators, and fully custom superyacht specialists. Competitive moves center on dual supply chain maintenance for hybrid and conventional propulsion, plus CE marking automation to compress documentation timelines.
Within the production-scale tier, Lagoon Catamarans and Fountaine Pajot occupy positions representing European manufacturing concentration, with the former anchoring Bordeaux operations and the latter maintaining La Rochelle facilities. Sunreef Yachts exemplifies the superyacht specialist archetype through its Gdansk-based focus on extra-large electric-hybrid configurations. These three entities collectively illustrate how geographic clustering around specific hull size bands and propulsion architectures fragments competitive positioning across the value chain.
| Leading Market Players |
|---|
| Lagoon Catamarans |
| Fountaine Pajot |
| Leopard Catamarans |
| Sunreef Yachts |
| Beneteau Group |
| Seawind |
| Robertson & Caine |
| Outremer Yachting |
| Catana Group |
| Others |
Supply Flow & Price Mechanics
CE marking under the EU Recreational Craft Directive gates both supplier qualification and price differentiation simultaneously, with uncertified builders locked out of European waters while ISO 12217 compliance commands substantial premiums for novel multihull configurations. This regulatory architecture compresses margins for non-compliant producers while concentrating pricing power among yards with established certification pathways.
Pricing Analysis
Certification level creates the primary spread between economy production builds and premium semi-custom configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by hull material grade, with carbon fiber reinforcement commanding substantial markups over fiberglass-reinforced polymer. Cost compression in the economy tier is intensifying because charter operators are consolidating procurement around medium-size production hulls. Fleet buyers exhibit highest price sensitivity, while private superyacht commissioners demonstrate minimal elasticity for bespoke electric-hybrid engineering.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes elevates inbound logistics costs for Japanese carbon fiber and US aerospace-grade resin shipments. Manufacturing concentrates in France, Poland, and Australia, with composite hull production drawing from Taiwanese pre-preg suppliers and German engineering software providers. Single-source vulnerability runs through Japanese carbon fiber producers controlling high-performance fiber pricing. Distribution runs through direct-to-manufacturer digital platforms displacing traditional broker networks in Australian and US markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent catamaran builders face substitution pressure from electric-hydrofoil vessels capturing short-haul ferry tenders, requiring defensive repositioning around range autonomy and certification depth.
For Market Incumbents: Consolidate production scale around Bordeaux and La Rochelle facilities to defend against emerging Polish superyacht specialists. Backward integration into captive composite manufacturing reduces exposure to Japanese carbon fiber pricing volatility. CE marking automation investments compress documentation timelines against smaller configurators. For New Entrants and Emerging Players: After-sales service gaps in Caribbean charter hubs present white-space opportunities where incumbent yards under-serve maintenance-intensive commercial fleets. Battery-electric retrofit expertise for aging diesel monohulls offers the most penetrable entry vector. Target government tender processes for inter-island ferry electrification with shore-charging integration capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified marine conglomerates with under-optimized catamaran divisions lacking hybrid-electric engineering depth. Long-term viability hinges on exposure to Mediterranean charter fleet renewal cycles and EU Green Deal carbon intensity enforcement. Monitor Norwegian and Danish ferry operator tender announcements as inflection indicators for serial-hybrid adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Integration | Battery-electric and serial-hybrid configurations satisfy EU Green Deal carbon intensity indicators for charter fleet procurement. |
| CE Marking Automation | Digital compliance platforms compress EU Recreational Craft Directive documentation timelines for semi-custom builders. |
| Direct-to-Consumer Digital Sales | Configuration platforms displace traditional broker networks in Australian and US private owner markets. |
| Composite Manufacturing Scale-Up | Captive carbon fiber layup capacity reduces dependency on Japanese aerospace-grade fiber suppliers. |
| Research Vessel Conversion Programs | Oceanographic institute retrofit tenders offer stable demand outside leisure market cyclicality. |
Methodological Framework
Initial hypotheses were tested against primary input from naval architects, charter fleet operators, composite manufacturing engineers, and marine classification surveyors and refined through secondary validation against EU F-Gas Regulation filings, ISO 12217 stability test reports, and customs data on carbon fiber imports. Bottom-up vessel production counts triangulated against top-down Mediterranean charter fleet capacity estimates.
Variance decomposition across the projection horizon isolates volume drivers by hull architecture, propulsion type, and size band. Segmentation dimensions modeled include product type, end user archetype, operational application, and length overall category. CAGRs were derived from installed base replacement cycles and emerging tender pipelines for electrified ferry routes. Forecast inputs incorporate lithium-ion pack cost trajectories and skilled laminator supply constraints in Western European shipyards.
Forecasts assume regulatory continuity in EU maritime decarbonization mandates and EPA Clean Air Act Tier 3/4 enforcement; material policy shifts would require re-modeling. Battery chemistry safety standards and flag-state carbon intensity rule evolution represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Airboats Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Boat and Ship MRO Market
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Marine Reciprocating Engine Market
Marine Vehicles
Water Taxi Market
Marine Vehicles
Asean Boat Davits Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Yacht Market
Marine Vehicles
Outboard Engines Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Marine Boat Passenger Seat Market
Marine Vehicles
Small Boats Market
Marine Vehicles
Hydrogen-Powered Yacht Market
Marine Vehicles
India Aluminium Fishing Boat Market