
 Aluminium Fishing Boat Market | 2026-2036
Aluminium Fishing Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Fishing Boat Market Analysis
Market Context
Marine dealership networks is narrowing as direct-to-consumer digital platforms and manufacturer-owned showrooms capture larger transaction volumes. Lowe leverages its captive retail footprint through Bass Pro Shops to control pricing and inventory allocation across freshwater markets. Alumacraft sustains dominance in the Upper Midwest through specialized welding facilities that produce custom hull configurations for regional tournament circuits. Tracker anchors the entry-level segment with vertically integrated manufacturing that compresses delivery timelines for mass-market jon boat buyers.
Technical Definition and Segment Structure
An aluminium fishing boat denotes a welded or riveted marine vessel constructed primarily from marine-grade aluminium alloys, typically 5052-H32 or 5083-H321, designed for angling operations in freshwater and coastal environments with draft requirements under 24 inches. The hull form prioritizes structural longevity, corrosion resistance, and payload capacity for gear and catch storage across varied water conditions. Center console configurations command premium positioning due to offshore versatility and deck space optimization for serious anglers. Jon boats occupy the highest volume tier, with standardized production runs serving price-sensitive recreational and utility buyers across inland waterways. Advanced materials technology represents the fastest-evolving segment, as alloy-lithium composites and friction-stir welding reduce hull weight while maintaining impact resistance for shallow-draft applications.
Regulatory Frame and Outlook
EPA marine engine emissions standards under the Clean Air Act compel hull manufacturers to optimize weight-to-power ratios, directly influencing aluminium gauge selection and hull design parameters for outboard compatibility. US Coast Guard flotation and stability regulations, alongside ABYC standards for electrical systems, establish baseline compliance costs that favor established builders with dedicated testing protocols over emerging entrants. Stakeholders must monitor evolving state-level aquatic invasive species transport rules, as mandatory hull inspection and drainage requirements in jurisdictions like Minnesota and Wisconsin reshape seasonal usage patterns and aftermarket service demand.
Market Dynamics
EPA marine engine emissions standards under the Clean Air Act are forcing hull manufacturers to redesign gauge specifications and weight-to-power ratios, compressing design cycles and favoring builders with captive testing infrastructure.
Growth Catalysts
- Friction-stir welding adoption:Advanced joining techniques reduce hull weight while maintaining structural integrity for shallow-draft tournament applications.
- Minnesota aquatic invasive species rules:Mandatory hull inspection and drainage protocols create recurring aftermarket service revenue streams for certified dealers.
- Great Lakes tournament circuits:Competitive angling formats demand premium center console configurations with specialized livewell and rod storage systems.
Market Restraints
- 5052-H32 aluminium sheet volatility:Primary metal input costs fluctuate with LME pricing, compressing margin predictability for standardized jon boat production runs.
- Marine-grade alloy supply concentration:Domestic smelter capacity constraints in the United States limit sourcing flexibility for 5083-H321 hull plate specifications.
- Outboard power density limits:Current four-stroke emissions compliance caps maximum thrust-to-weight ratios for lightweight aluminium hull applications.
Strategic Opportunities
- Alloy-lithium composite penetration:Next-generation material systems enable 15-20% weight reduction for competitive freshwater tournament segments.
- Direct-to-consumer digital platforms:Manufacturer-owned showrooms and online configurators bypass traditional dealership networks in price-sensitive inland markets.
- ABYC electrical standard integration:Certified pre-wiring packages for trolling motor and sonar systems command premium positioning in serious angler segments.
Industry Challenges
- Friction-stir welding technician scarcity:Specialized aluminum joining expertise concentrates at regional fabrication clusters, limiting production scaling.
- US Coast Guard flotation certification timelines:Stability testing protocols extend new hull introduction cycles by 4-6 months for custom configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Fishing Boat Market |
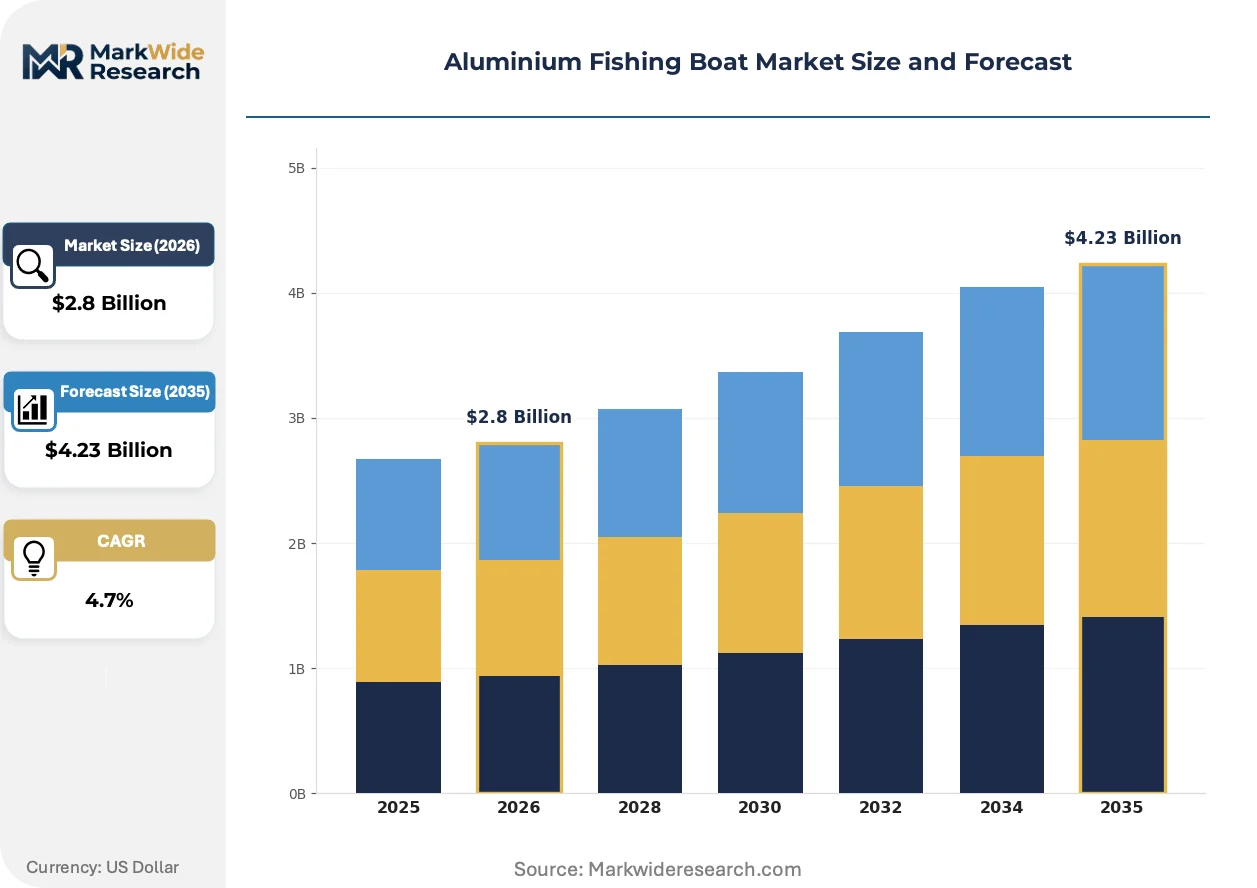
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bay Boat, Center Console, Jon Boat, Skiff End User: Commercial Fisheries, Recreational Anglers, Rental Services, Government Agencies Size: Small Boats, Medium Boats, Large Boats, Super Large Boats Technology: Traditional Build, Advanced Materials, Lightweight Design, Eco-Friendly Coatings |
| Companies Covered | Lowe, Bluecoastlines, Alumacraft, Crestliner, Vexus Boats, Tracker, Princecraft, Starcraft Marine, Xpress Boats, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Fishing Boat Market Emerging Trajectories
Digital retail infrastructure and advanced materials science are compressing traditional supply chain hierarchies while regulatory pressure on marine propulsion accelerates hull lightweighting investments across the freshwater boatbuilding sector.
Friction-stir welding is collapsing the weight-performance tradeoff that historically separated premium welded hulls from mass-market riveted alternatives. Tournament anglers in the Upper Midwest are specifying friction-stir hulls for competitive durability, and this adoption is collapsing the price premium between custom and production boat categories.
EPA Clean Air Act marine engine standards are tightening displacement-to-weight ratios for outboard compatibility. Hull designers must optimize aluminium gauge selection and structural geometry, and center console builders in the Great Lakes region are responding with integrated transom reinforcement systems.
Serious anglers are unbundling after-sales service from initial hull purchase, demanding modular electronics packages and transferable maintenance contracts. Traditional marine dealerships in freshwater markets are losing attachment revenue to manufacturer-direct subscription programs, with this pattern most visible in the United States Great Lakes tournament fishing corridor.
Aluminium Fishing Boat Market Segmentation
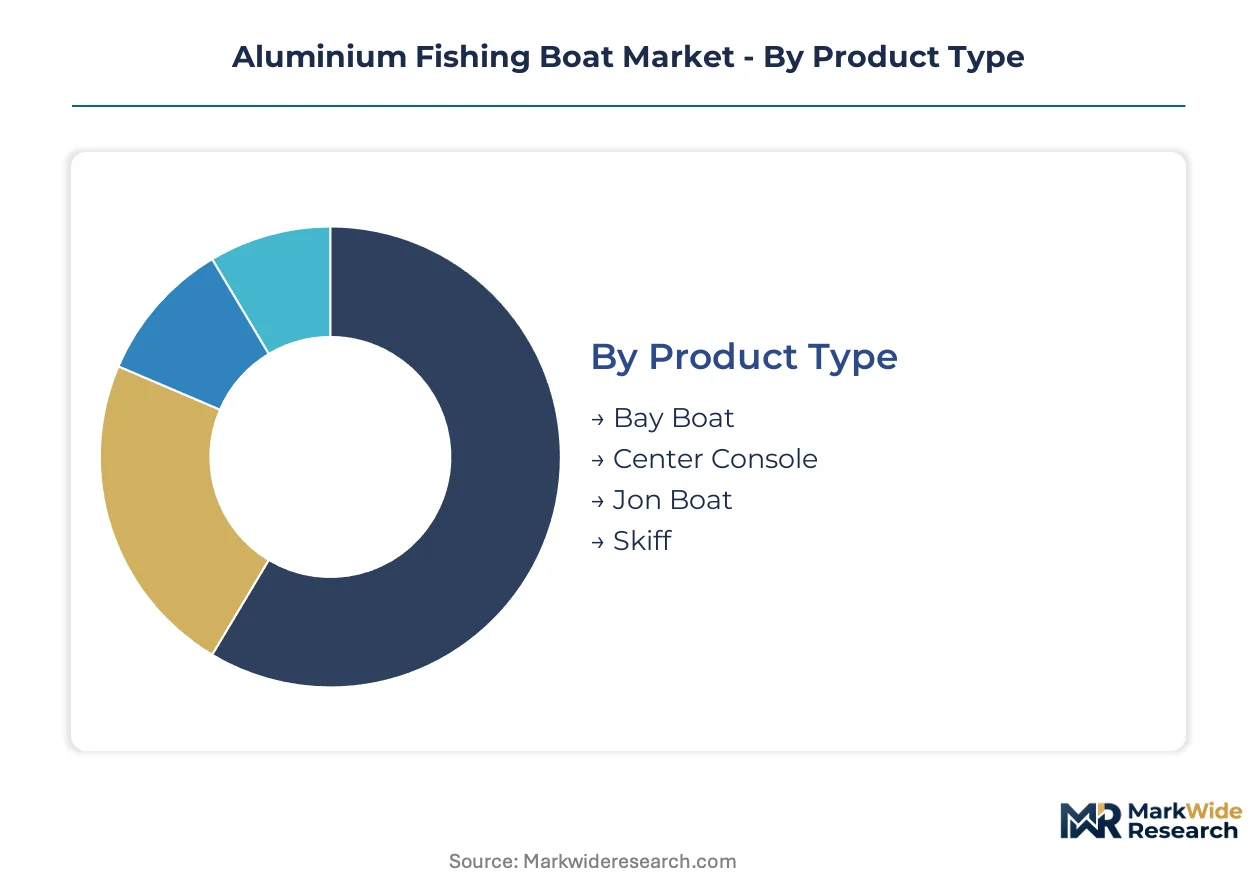
Aluminium fishing boat purchasing patterns diverge sharply across hull configuration, operator type, and construction technology. Tournament anglers prioritize specialized livewell systems and rod storage geometry, while rental fleets optimize for damage tolerance and rapid turnaround maintenance.
Product Type:
Cost tier stratification separates premium welded configurations from mass-market riveted alternatives, with hull form dictating both manufacturing complexity and end-use versatility.
- Center Console:Offshore-capable hulls with 360-degree fishability and integrated transom reinforcement systems for high-thrust outboard compatibility. Demand concentrates in the United States Great Lakes tournament corridor, where competitive formats mandate premium livewell circulation and dedicated electronics mounting.
- Jon Boat:Flat-bottom utility platforms with standardized production runs serving price-sensitive freshwater anglers and utility operators across inland waterways. Entry-level positioning attracts mass-market buyers seeking basic transportation to fishing locations without specialized tournament features.
- Bay Boat:Modified-V hulls optimized for shallow-draft coastal and estuarine environments with moderate chop protection.
- Skiff:Lightweight poling platforms designed for technical sight-fishing in extremely shallow water with minimal draft and wind signature.
Center Console commands the established base. The steepest expansion runs through Jon Boat.
End User:
Application intensity varies dramatically across operator categories, from seasonal recreational use to continuous commercial deployment demanding corrosion-resistant alloy specifications.
- Recreational Anglers:Individual owners and family operators pursuing weekend fishing across freshwater lakes and coastal estuaries. Tournament participation in Minnesota and Wisconsin drives specification for friction-stir welded hulls with integrated drainage systems compliant with aquatic invasive species protocols.
- Commercial Fisheries:Professional harvesters requiring maximum payload capacity for catch storage and gear transport under continuous operational stress.
- Rental Services:Fleet operators prioritizing hull durability and simplified maintenance protocols for high-frequency customer turnover.
- Government Agencies:Conservation enforcement and waterway patrol units specifying ruggedized construction for search-and-rescue and invasive species inspection duties.
Recreational Anglers command the established base. The steepest expansion runs through Commercial Fisheries.
Size:
Volume distribution correlates directly with water body access constraints and trailer transport limitations across inland and coastal markets.
- Small Boats:Sub-16 foot hulls optimized for solo or two-person operation with car-towable weights and launch site flexibility.
- Medium Boats:16-20 foot platforms balancing fishability with family capacity, representing the volume concentration point for Great Lakes recreational purchases.
- Large Boats:20-24 foot hulls with offshore capability and overnight range for serious tournament and coastal anglers.
- Super Large Boats:24+ foot specialized platforms with twin-engine compatibility and extended-range fuel systems for competitive offshore circuits.
Medium Boats command the established base. The steepest expansion runs through Large Boats.
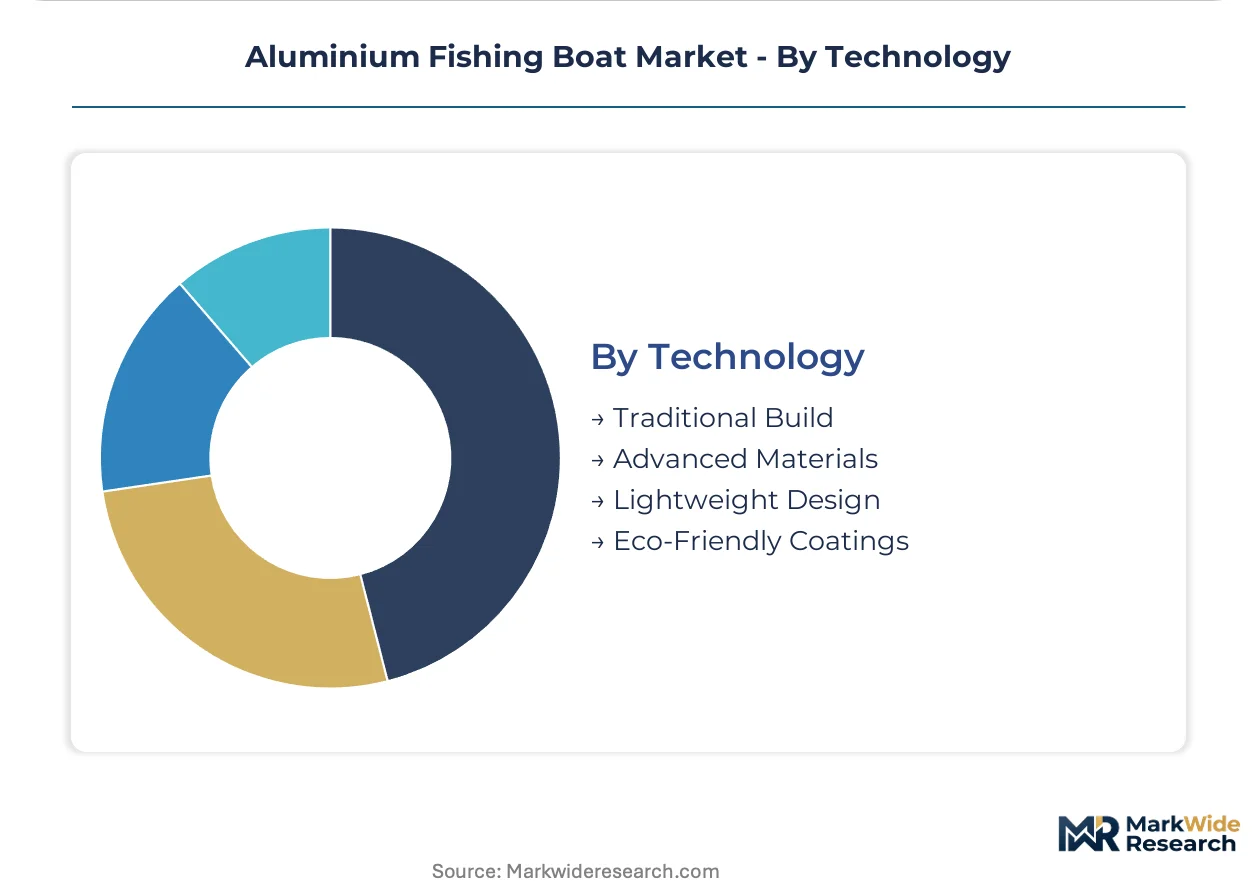
Technology:
Manufacturing sophistication determines weight-performance ratios and regulatory compliance positioning under tightening EPA marine emissions standards.
- Advanced Materials:Alloy-lithium composites and friction-stir welding techniques achieving 15-20% weight reduction while maintaining impact resistance for shallow-draft tournament applications. Adoption concentrates in competitive angling segments where hull durability under poling and beaching stress justifies premium positioning.
- Traditional Build:Riveted 5052-H32 construction with established supply chains and repair infrastructure across rural dealership networks.
- Lightweight Design:Computer-optimized structural geometry minimizing material usage without sacrificing Coast Guard flotation certification.
- Eco-Friendly Coatings:Low-VOC bottom paints and anodized finishes reducing environmental impact in sensitive freshwater ecosystems.
Traditional Build commands the established base. The steepest expansion runs through Advanced Materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA marine engine emissions standards under the Clean Air Act dominate regulatory pressure across the United States freshwater corridor. Tournament fishing circuits and fleet renewal cycles concentrate demand in specific lake systems and coastal estuaries.
United States
Great Lakes tournament circuits drive specification for premium center console configurations with integrated livewell systems. Minnesota and Wisconsin enforce mandatory hull inspection and drainage protocols under aquatic invasive species transport rules. The Upper Midwest welding cluster around St. Cloud and New York Mills supplies custom hull configurations for regional competitive angling formats.
Canada
Freshwater recreational angling across Ontario's lake systems sustains steady demand for car-towable jon boat platforms. Transport Canada vessel construction standards align with US Coast Guard flotation requirements, easing cross-border manufacturing compliance. The Kawartha Lakes and Georgian Bay regions concentrate seasonal purchasing from cottager and weekend angler segments.
Australia
Coastal estuary fishing and barramundi tournament circuits generate demand for shallow-draft skiff configurations. The Australian Maritime Safety Authority administers domestic commercial vessel standards that influence recreational build specifications. Queensland's Sunshine Coast and Sydney's Hawkesbury River estuary anchor distribution networks for corrosion-resistant alloy hulls.
Japan
Sea bass and blackfin seabass lure fishing cultures sustain specialized bay boat demand in Tokyo Bay and Ise Bay. METI oversees industrial standards for marine aluminum alloys through JIS H 4000 series specifications. The Nagoya industrial corridor hosts precision fabrication facilities serving domestic recreational vessel manufacturers.
Brazil
Pantanal wetland fishing tourism and Amazon basin peacock bass expeditions drive demand for shallow-draft utility platforms. ANVISA regulates materials contact with food catch in commercial fishing applications. The Manaus industrial free zone and São Paulo state metalworking clusters supply riveted hull components for regional boat assemblers.
Aluminium Fishing Boat Market Vendor Landscape
Mass-market manufacturers and specialized fabricators split the market along price-performance lines. The vendor base concentrates around three strategic archetypes: vertically integrated mass producers controlling entry-level volume, regional welding specialists capturing tournament-grade customization, and marine-retail-captive brands leveraging proprietary distribution. Competitive positioning hinges on backward integration into aluminum supply and captive service network density.
Among North American fabricators, Lowe, Alumacraft, and Tracker occupy positions across distinct tier structures. Lowe exemplifies retail-captive distribution architecture through specialized showroom networks. Alumacraft represents regional welding specialist concentration in Upper Midwest tournament markets. Tracker anchors mass-market positioning through streamlined production geometries for standardized jon boat configurations.
| Leading Market Players |
|---|
| Lowe |
| Bluecoastlines |
| Alumacraft |
| Crestliner |
| Vexus Boats |
| Tracker |
| Princecraft |
| Starcraft Marine |
| Xpress Boats |
| Others |
Supply Flow & Price Mechanics
The St. Cloud welding cluster in Minnesota concentrates friction-stir fabrication capacity for tournament-grade hulls, translating regional supply scarcity into pricing power for custom configurations serving competitive anglers across the Upper Midwest freshwater corridor.
Pricing Analysis
Price spreads between the Great Lakes tournament corridor and inland utility markets reflect livewell system complexity and EPA-compliant drainage integration. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and customization intensity. Cost compression in mass-market jon boat production runs through LME-linked 5052-H32 sheet volatility. Rental fleet operators exhibit highest price sensitivity, while tournament anglers absorb premium positioning for friction-stir welded durability.
Supply Chain Analysis
Contract manufacturing concentrates at regional aluminum fabrication clusters around St. Cloud, New York Mills, and the Kawartha Lakes corridor. Raw material flows draw from domestic 5083-H321 smelter capacity, Canadian alloy sheet production, and imported lithium composite feedstock. Single-source vulnerability runs through concentrated domestic smelter constraints for marine-grade plate specifications. Distribution runs through manufacturer-owned showrooms, Bass Pro Shops captive retail, and independent marine dealerships serving freshwater angling corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
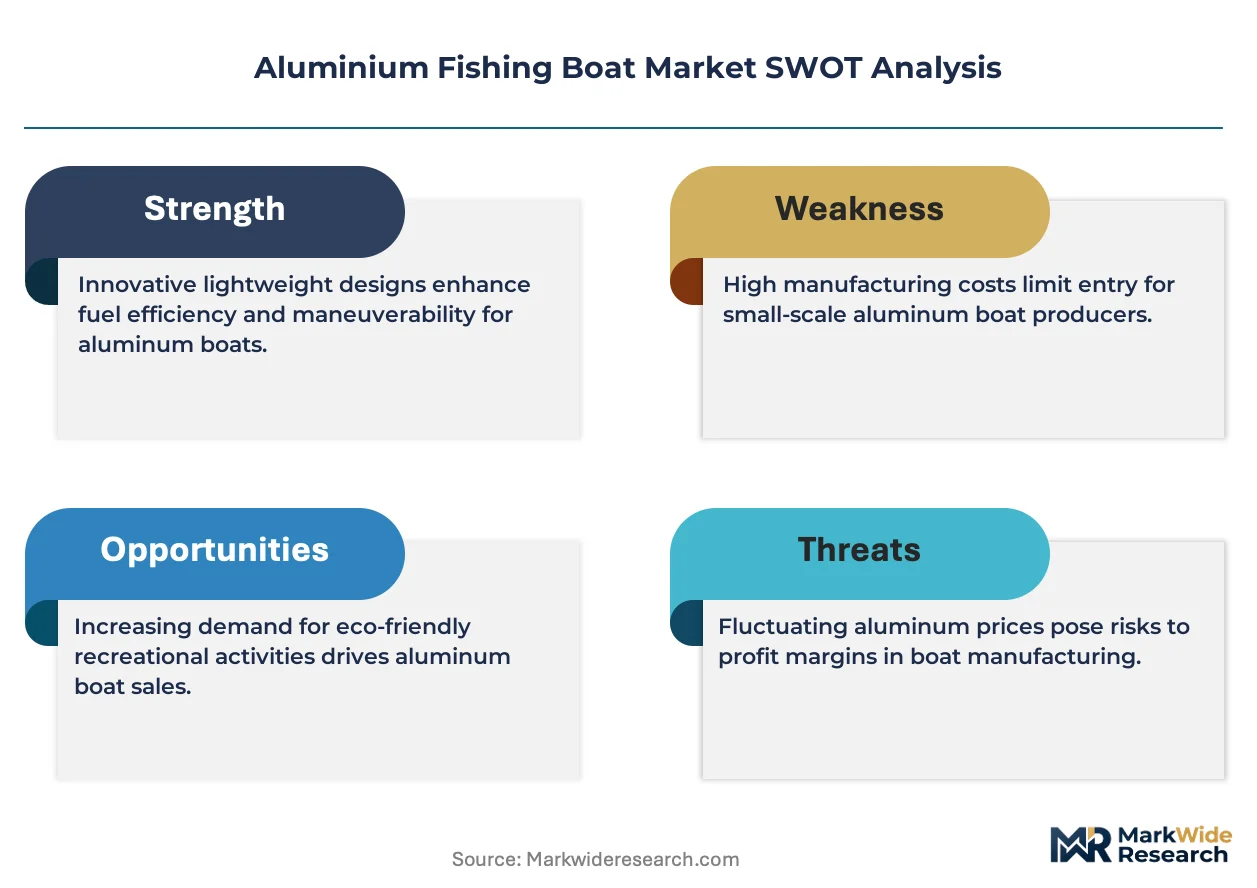
Incumbents face substitution pressure from fiberglass composite hulls penetrating shallow-draft tournament segments, requiring defensive repositioning around aluminum's repairability and weight-to-power advantages.
For Market Incumbents: Entrench regional welding specialist positioning through captive friction-stir technician training programs in the Upper Midwest. Deepen backward integration into 5083-H321 alloy supply through long-term offtake agreements with Canadian smelters. Defend against fiberglass substitution by emphasizing aluminum hull impact resistance and field-repairability for tournament anglers operating in rocky shallows. For New Entrants and Emerging Players: Pursue digital direct-to-consumer white space in price-sensitive inland jon boat markets bypassed by established dealership networks. Target government agency procurement segments specifying ruggedized construction for invasive species inspection duties. Deploy online configurators with modular electronics pre-wiring to capture serious angler demand outside traditional retail footprints. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified marine conglomerates with underoptimized aluminum fishing boat divisions lacking friction-stir capability or Great Lakes distribution density. Long-term viability hinges on material science differentiation and regulatory compliance infrastructure rather than pure scale. Monitor EPA marine engine standards tightening as the inflection signal for hull lightweighting investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Friction-Stir Welding Capacity Expansion | Captures tournament angler premium by collapsing weight-durability tradeoffs for competitive hull specifications. |
| Direct-to-Consumer Digital Platform Launch | Bypasses dealership margin capture in price-sensitive inland jon boat markets across rural freshwater corridors. |
| Alloy-Lithium Composite R&D Investment | Enables 15-20% hull weight reduction for EPA-compliant outboard compatibility in shallow-draft applications. |
| Backward Integration into Aluminum Supply | Secures 5083-H321 plate allocation amid domestic smelter capacity constraints and LME price volatility. |
| ABYC-Certified Pre-Wiring Package Development | Commands premium positioning among serious anglers demanding integrated trolling motor and sonar system compatibility. |
Methodological Framework
The analysis maps center console, jon boat, bay boat, and skiff configurations, each validated through boatyard operations managers, marine dealership principals, tournament circuit organizers, and aluminum alloy procurement leads. Primary fieldwork combined structured interviews with secondary triangulation across EPA marine engine filings, US Coast Guard flotation certification records, LME aluminum pricing data, and state-level aquatic invasive species regulatory databases. Bottom-up hull production estimates and top-down recreational expenditure patterns were reconciled across the analysis window.
Assumptions held EPA emissions standards trajectory and Great Lakes tournament participation rates fixed, while varying aluminum alloy pricing scenarios and direct-to-consumer adoption curves. Segmentation modeling incorporated hull configuration, operator type, construction technology, and regional regulatory cluster dimensions. CAGRs were derived from production volume trends and replacement cycle analysis, with inputs from friction-stir welding adoption rates and outboard power density evolution.
Macroeconomic conditions sit as an overlay; deviation in recreational discretionary spending, trailer-accessible waterway development, or aluminum tariff structures would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance timelines and materials substitution elasticity. Quarterly review of EPA rulemaking dockets, LME aluminum forward curves, and tournament circuit participation metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Liquid and Bulk Transportation Vessels Market
Marine Vehicles
Fishing Boat Market
Marine Vehicles
Marine Outboard Engine Market
Marine Vehicles
Boat Davits Market
Marine Vehicles
Marine Propulsion Systems Market
Marine Vehicles
Marine Passenger Seat Market
Marine Vehicles
Cargo Vessel Market
Marine Vehicles
Airboats Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
LNG Marine Engine Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Yacht Market
Marine Vehicles
Boat Tachometer Market
Marine Vehicles
Tugboat Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Global Outboard Motors Market