
 Boat Tachometer Market | 2026-2036
Boat Tachometer Market Size, Share, and Industry Trends Forecast 2026-2036
Boat Tachometer Market Analytics
Polymer composites are restructuring traditional metal housing economics in marine instrumentation, reducing corrosion-related replacement cycles and lowering unit production costs. Veethree Group leverages vertical integration across sensor manufacturing to sustain margin control in competitive OEM channels. Faria Beede Instruments anchors its position through brand strength in aftermarket replacement cycles across North American marinas. nKe Marine Electronics specializes in high-precision optical sensor calibration for racing yacht applications.
A boat tachometer measures rotational speed of marine propulsion engines, typically displaying revolutions per minute through inductive, optical, or Hall effect signal acquisition with IP67-rated sealing against saltwater ingress. The device serves critical functions in fuel optimization, engine protection, and propeller performance monitoring across recreational and commercial vessels. Digital tachometers lead unit volume as GPS-based sensors capture the fastest expansion among technology segments due to integrated navigation convergence. Factory installed channels dominate value capture while aftermarket replacement sustains steady recurring demand through wear-induced failure modes.
ISO 8846 ignition protection standards and NMEA 2000 digital interfacing protocols shape product certification requirements in the United States, while CE marking and REACH substance restrictions govern European market access for electronic marine components. The United States Coast Guard enforces electrical system safety regulations that directly influence tachometer housing material and ignition protection design specifications. Stakeholders must monitor evolving cybersecurity frameworks for connected smart tachometers as vessel digitization accelerates regulatory scope beyond traditional mechanical safety domains.
Market Dynamics
NMEA 2000 protocol standardization across United States and European Union commercial fleets is forcing hardware redesign cycles and consolidating supplier qualification requirements around digital interoperability.
Growth Catalysts
- Commercial Fleet Modernization:Professional mariners in Australia and Germany are replacing analog gauge clusters with networked digital instrumentation to enable centralized vessel monitoring.
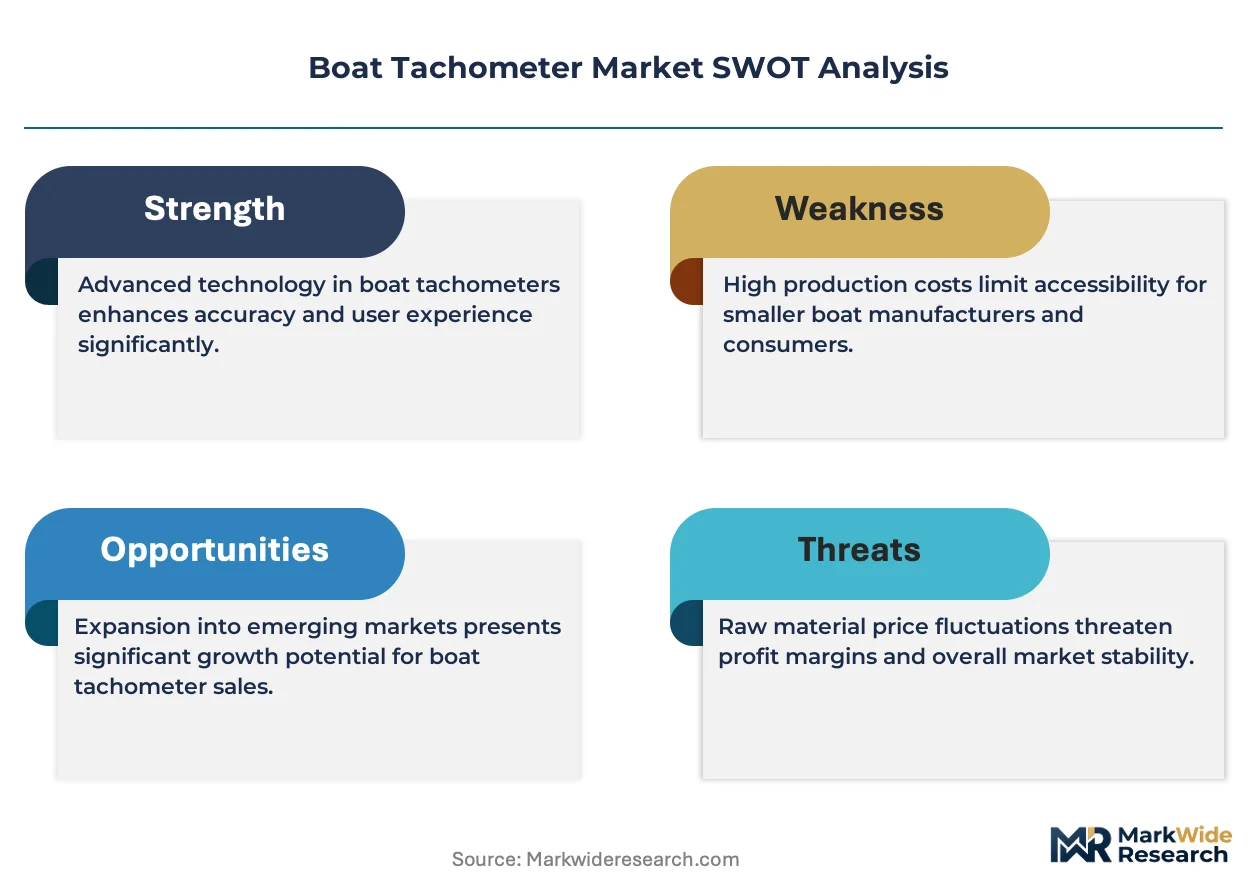
- ISO 8846 Ignition Protection Mandates:United States Coast Guard electrical safety regulations require spark-resistant housing materials, accelerating polymer composite adoption over traditional metal enclosures.
- GPS Sensor Convergence:Integrated navigation systems are capturing propulsion data through satellite-derived speed references, expanding tachometer functionality beyond standalone RPM measurement.
Market Restraints
- Copper and Rare Earth Input Volatility:Hall effect sensor production depends on neodymium and copper coil windings, exposing manufacturers to commodity price swings from Chinese processing concentration.
- REACH Substance Restrictions:European ECHA regulations limit specific polymer additives and flame retardants, forcing reformulation of housing compounds and extending certification timelines.
- Optical Sensor Substitution Risk:Laser-based crankshaft position detection in high-performance racing applications threatens inductive pickup dominance in precision segments.
Strategic Opportunities
- Aftermarket Marina Channel Expansion:Wear-induced gauge failure in aging recreational fleets across Florida and California creates replacement demand independent of new vessel sales cycles.
- Cybersecurity Framework Pre-Positioning:Connected smart tachometer architectures can align with emerging United States Coast Guard vessel digitization standards before formal mandate implementation.
- Racing Yacht Calibration Services:High-precision optical sensor tuning for competitive sailing applications commands premium pricing and generates recurring calibration revenue streams.
Industry Challenges
- Embedded Firmware Talent Scarcity:Marine electronics manufacturers compete with automotive and aerospace sectors for programmers skilled in real-time operating systems and NMEA protocol stacks.
- IP67 Validation Bottlenecks:Saltwater immersion testing facilities face capacity constraints, extending product launch timelines for sealed enclosure designs.
- Legacy Analog Integration Complexity:Retrofit installations require signal conditioning hardware to bridge mechanical pulse generators with digital display networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat Tachometer Market |
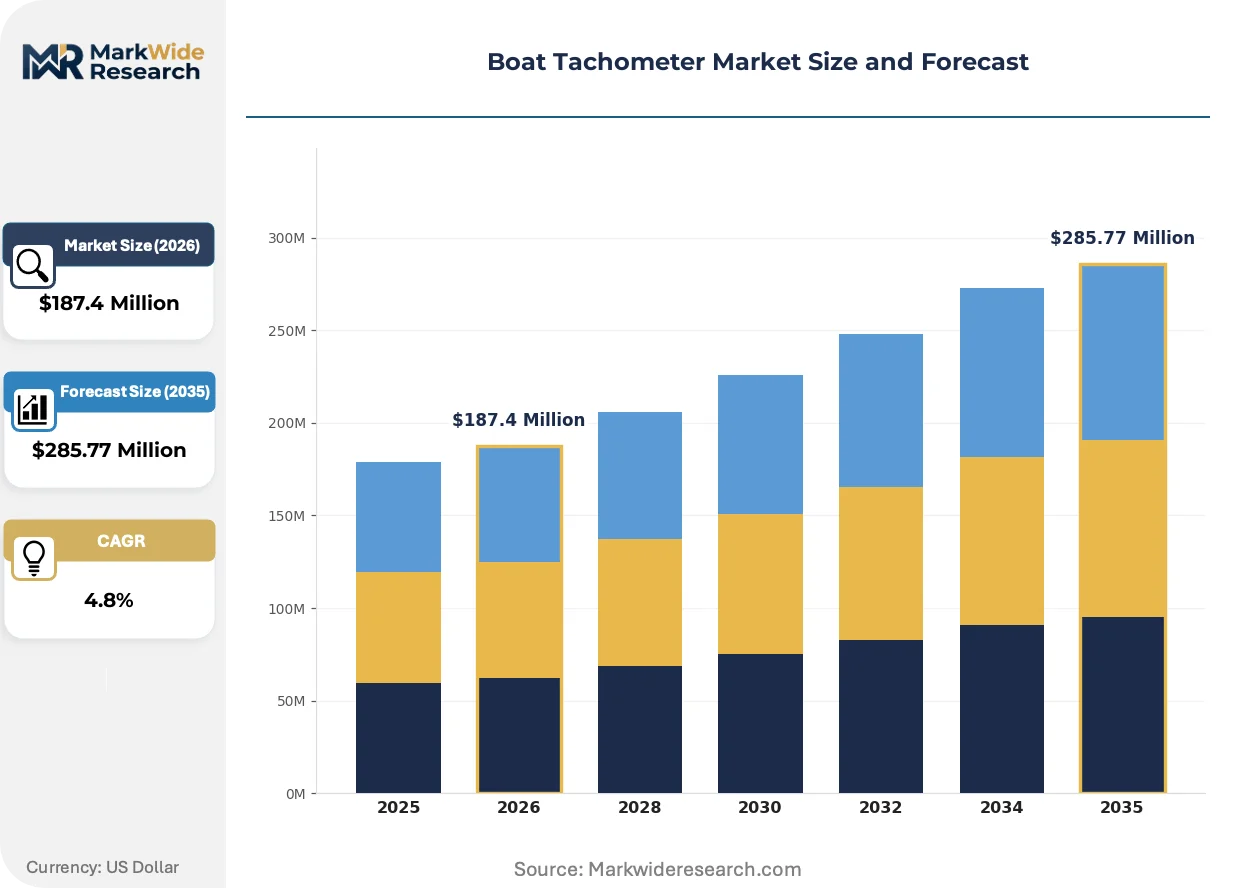
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Tachometers, Analogue Tachometers, Smart Tachometers, Wireless Tachometers End User: Recreational Boaters, Professional Mariners, Boat Manufacturers, Repair Services Installation Type: Factory Installed, Aftermarket, Custom Installation, Mobile Installation Technology: Inductive Sensors, Optical Sensors, Hall Effect Sensors, GPS-based Sensors |
| Companies Covered | Veethree Group, Faria Beede Instruments, Inc., Flir Systems Inc., Autometer Products, Nasa Marine Ltd, Gaffrig Performance Inc, Cruzpro Limited, nKe Marine Electronics, SAN GIORGIO S.E.I.N. srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat Tachometer Market Evolving Landscape
Digital instrumentation architectures are fragmenting traditional gauge ecosystems into distributed sensor networks, compressing hardware margins while expanding software and integration service value pools.
Multi-function display platforms are modularizing standalone tachometer hardware into configurable screen real estate. Commercial fishing operators in the North Sea are adopting these systems fastest, consolidating engine data with sonar and navigation feeds. This convergence is modularizing supplier relationships as vessel builders source complete bridge electronics packages rather than discrete gauges.
CE marking under EU Marine Equipment Directive is tightening electromagnetic compatibility testing requirements for electronic engine instruments. German and Dutch certification bodies are extending evaluation periods for devices with wireless connectivity features. Racing yacht manufacturers are responding by pre-certifying optical sensor modules separately from display hardware to accelerate hull integration timelines.
Marina-based service networks are capturing aftermarket replacement demand through direct vessel-owner relationships. Independent repair facilities in Sydney and Hamburg are displacing OEM parts channels by offering same-day gauge swap programs. This pattern is most visible in recreational sailing segments where seasonal commissioning schedules compress decision windows.
Boat Tachometer Market Segmentation
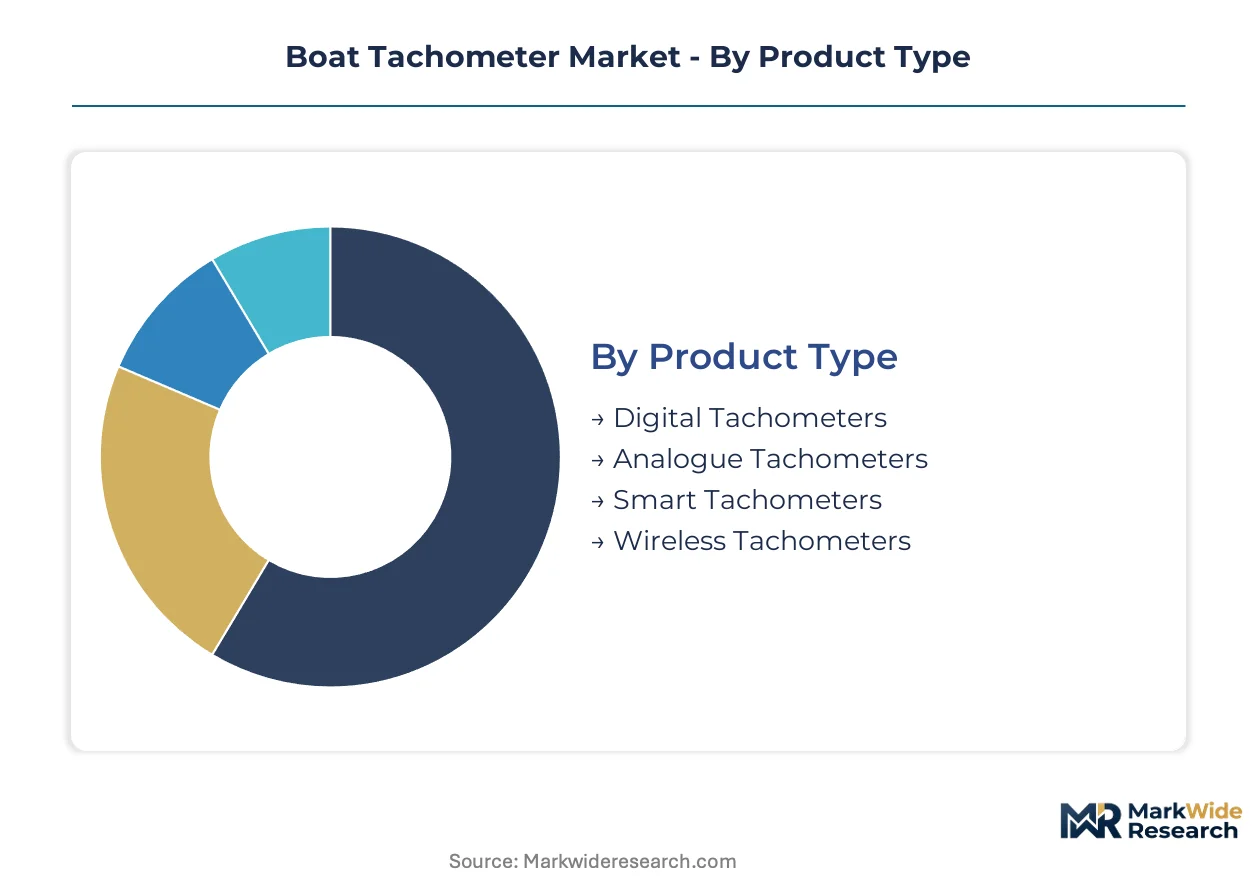
Boat tachometer purchasing patterns diverge sharply between volume-driven replacement cycles and premium integration projects. Segmentation reveals how sensor technology, installation channel, and end-user sophistication reshape supplier economics and margin structures across marine instrumentation.
Product Type:
Digital tachometers dominate unit shipments while smart variants command the steepest price premiums and fastest technology refresh cycles.
- Digital Tachometers:LCD or LED displays with NMEA 2000 digital interfacing enable network integration across multi-engine vessels. Demand concentrates in United States commercial fishing fleets where centralized bridge monitoring reduces crew workload.
- Analogue Tachometers:Mechanical needle indicators with inductive signal conditioning persist in cost-sensitive recreational segments. Aging vessel populations across Florida marinas sustain replacement demand independent of new boat sales.
- Smart Tachometers:Connected architectures with firmware-updatable features and predictive maintenance algorithms.
- Wireless Tachometers:Bluetooth or WiFi-enabled units eliminating harness runs in retrofit installations.
Today's leader: Digital Tachometers. Tomorrow's challenger: Smart Tachometers.
End User:
Professional mariners prioritize certification compliance and network interoperability while recreational buyers respond to price visibility and marina service availability.
- Professional Mariners:Commercial operators across North Sea fishing fleets and Australian offshore logistics mandate NMEA 2000 certification and IP67 sealing documentation. Regulatory enforcement by the United States Coast Guard accelerates digital gauge cluster replacement cycles.
- Recreational Boaters:Weekend sailors and coastal cruisers in California and Sydney harbor districts drive aftermarket replacement through seasonal commissioning schedules.
- Boat Manufacturers:OEM procurement teams sourcing complete instrument packages for new hull production.
- Repair Services:Independent marine technicians capturing same-day swap demand at marina service docks.
Professional Mariners set the certification standard. Repair Services capture the highest-margin replacement volume.
Installation Type:
Factory channels lock in multi-year supply agreements while aftermarket installations fragment across independent service networks with divergent technical capabilities.
- Factory Installed:OEM integration during hull assembly with calibrated sensor-to-display pairing. German and Dutch yacht builders specify electromagnetic compatibility pre-certification to accelerate production line throughput.
- Aftermarket:Replacement demand triggered by gauge failure, corrosion damage, or technology upgrades. Hamburg and Sydney service facilities displace OEM parts channels through direct vessel-owner relationships.
- Custom Installation:Specialized configurations for racing yachts and expedition vessels requiring non-standard display layouts.
- Mobile Installation:Technician-deployed services at remote moorings or seasonal haul-out locations.
Factory Installed captures the value concentration. Aftermarket sustains the revenue recurrence.
Technology:
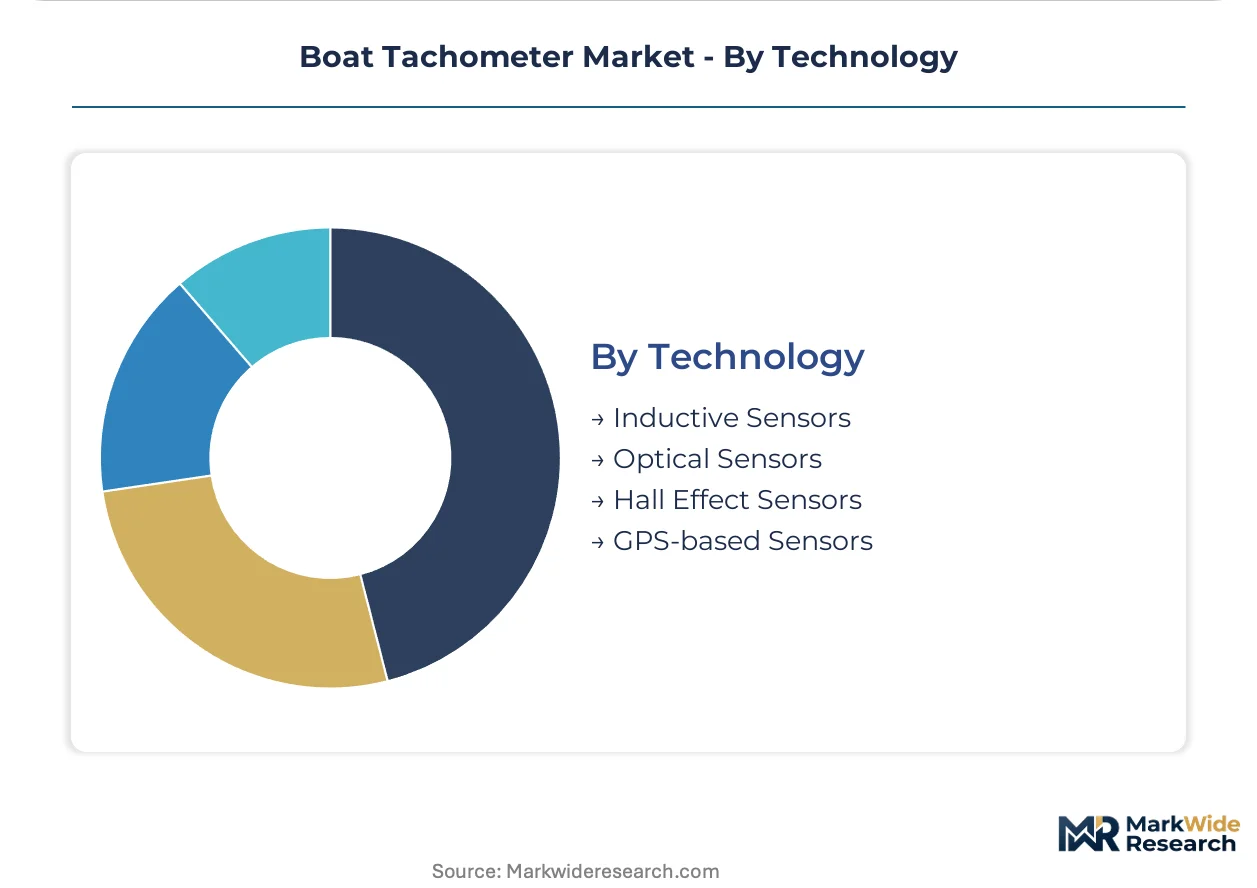
Sensor selection determines calibration precision, environmental resilience, and integration complexity with existing vessel electronics.
- GPS-based Sensors:Satellite-derived speed references eliminate mechanical pickup installation and enable over-ground speed integration with navigation systems. Australian commercial fleets adopt these fastest for fuel optimization across variable current conditions.
- Hall Effect Sensors:Magnetic field detection with solid-state reliability and no mechanical wear. Neodymium magnet supply concentration in Chinese processing creates input cost volatility for manufacturers.
- Inductive Sensors:Electromagnetic pickup coils sensing flywheel teeth or alternator pulses.
- Optical Sensors:Laser or infrared crankshaft position detection for racing applications demanding sub-RPM precision.
GPS-based Sensors are climbing the fastest. Hall Effect Sensors anchor the installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea commercial fishing corridor anchors marine instrumentation demand through fleet digitization mandates and centralized bridge monitoring requirements.
United States
Commercial fishing operators across the Pacific Northwest and Gulf Coast are replacing analog gauge clusters with NMEA 2000 networked systems. The United States Coast Guard enforces ISO 8846 ignition protection standards that accelerate polymer composite adoption over metal housings. Florida marina service networks in Tampa Bay and Fort Lauderdale capture aftermarket replacement volume through seasonal commissioning programs.
Germany
Dutch and German yacht builders specify electromagnetic compatibility pre-certification to streamline production line throughput for export hulls. CE marking under the EU Marine Equipment Directive tightens testing requirements for wireless-enabled engine instruments. Hamburg independent repair facilities displace OEM parts channels through same-day gauge swap programs at Elbe River marinas.
Australia
Offshore logistics operators mandate GPS-based sensor integration for fuel optimization across variable current conditions in the Bass Strait. The country's national maritime regulator enforces vessel monitoring system standards that drive digital instrumentation adoption. Sydney Harbor marina technicians capture high-margin replacement demand through direct vessel-owner relationships during seasonal haul-outs.
Netherlands
Commercial fishing fleets in the North Sea adopt multi-function display platforms fastest, consolidating engine data with sonar and navigation feeds. ECHA REACH substance restrictions force reformulation of housing compounds and extend certification timelines for polymer suppliers. Rotterdam and Amsterdam marine electronics distributors serve as consolidation points for Benelux aftermarket demand.
United Kingdom
Recreational sailing communities in the Solent and Firth of Clyde sustain analog gauge replacement cycles independent of new vessel sales. The Maritime and Coastguard Agency aligns with evolving cybersecurity frameworks for connected vessel systems. Southampton marine service clusters specialize in legacy analog-to-digital signal conditioning for retrofit installations.
Boat Tachometer Market Competitive Landscape
Global majors compete with regional champions across certification compliance and aftermarket service reach, producing a tiered structure where scale-driven OEM suppliers coexist with marina-focused replacement specialists. The vendor base clusters around three archetypes: vertically integrated sensor manufacturers, brand-anchored aftermarket distributors, and precision-calibration specialists for racing applications. Consolidation pressures favor acquisition of regional service networks, while technology licensing agreements accelerate NMEA 2000 protocol compliance across mid-tier players.
Among sensor-integrated manufacturers, Veethree Group and Faria Beede Instruments occupy positions reflecting distinct channel strategies—one emphasizing upstream control over component production, the other anchoring brand recognition in North American marina replacement cycles. nKe Marine Electronics exemplifies the precision-specialist archetype, sitting within the racing yacht calibration tier where optical sensor tuning commands premium positioning. These three represent the competitive vectors defining margin capture across factory-installed and aftermarket segments.
| Leading Market Players |
|---|
| Veethree Group |
| Faria Beede Instruments, Inc. |
| Flir Systems Inc. |
| Autometer Products |
| Nasa Marine Ltd |
| Gaffrig Performance Inc |
| Cruzpro Limited |
| nKe Marine Electronics |
| SAN GIORGIO S.E.I.N. srl |
| Others |
Value Network & Pricing Analysis
German and Dutch yacht builders command the dominant pricing leverage through multi-year OEM procurement contracts, compressing margins for sensor manufacturers while aftermarket marina channels sustain premium pricing through emergency replacement urgency. This buyer concentration shapes a bifurcated structure where factory-installed volumes trade at cost-plus terms and independent service networks capture value through speed-of-delivery premiums.
Pricing Analysis
Neodymium and copper coil input costs pass through variably across supplier tiers, with Hall effect sensor manufacturers absorbing volatility more than GPS-based module producers. Three-tier pricing structure across marine-grade certified, standard commercial, and economy retrofit levels separates professional fleet buyers from recreational weekend sailors. Cost compression in economy analog replacements is intensifying because Chinese polymer housing exports displace European compound suppliers. Recreational boaters in Florida marinas exhibit the highest price sensitivity, while offshore logistics operators in Australia accept premium positioning for fuel optimization integration.
Supply Chain Analysis
Refurbishment flows for IP67-sealed enclosures create secondary material recovery streams, with Hamburg and Sydney service facilities remanufacturing failed units for cost-sensitive segments. Manufacturing concentrates in China for neodymium processing, Germany for precision optical calibration, and the United States for NMEA 2000 protocol-compliant assembly. Raw material dependencies include rare earth magnet supply, marine-grade polymer compounds, and inductive coil windings. Single-source vulnerability in Chinese neodymium concentration threatens input security for Hall effect production. Distribution runs through Rotterdam consolidation hubs for European aftermarket demand and direct marina service relationships in North American coastal clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory mandate stacking, with NMEA 2000 interoperability requirements in the United States and European Union forcing replacement cycles that outpace underlying vessel demand.
For Market Incumbents: Anchor certification leadership by pre-positioning cybersecurity frameworks ahead of United States Coast Guard vessel digitization standards. Deepen backward integration into sensor manufacturing to defend margin control against polymer composite price volatility. Threat substitution from laser-based optical detection in racing segments demands accelerated R&D investment in high-precision calibration capabilities. For New Entrants and Emerging Players: Independent repair facilities in secondary Australian and United Kingdom harbors represent the most penetrable buyer archetype, with same-day swap programs displacing OEM parts channels. Target mobile installation services at remote moorings where seasonal commissioning schedules compress decision windows. Go-to-market execution should leverage direct vessel-owner relationships bypassing traditional distribution hierarchies. For Investors and Strategic Acquirers: Marine electronics platform consolidators are the most active acquirer in this space, seeking regional service network density to complement hardware portfolios. Long-term viability hinges on software and integration service value pools expanding faster than commoditized gauge hardware. Acquisition candidates with captive calibration capabilities for racing yacht applications command scarcity premiums. Monitor NMEA 2000 protocol enforcement intensity across European Union member states as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NMEA 2000 Protocol Pre-Certification | Accelerates production line throughput for German and Dutch yacht builders exporting to United States markets. |
| Marina Service Network Acquisition | Captures high-margin aftermarket replacement volume through direct vessel-owner relationships in Florida and Sydney. |
| Optical Sensor Calibration Capability Buildout | Commands premium positioning in racing yacht segments where sub-RPM precision determines competitive outcomes. |
| Cybersecurity Framework Development | Aligns connected smart tachometer architectures with emerging United States Coast Guard digitization standards. |
| Polymer Compound Formulation Investment | Addresses ECHA REACH substance restrictions forcing housing material reformulation in European market access. |
Research Methodology
Coverage spans the United States, Germany, Australia, Netherlands, and United Kingdom, with primary inputs from each market cluster combining structured interviews with marine electronics procurement directors, vessel builder platform engineers, marina service technicians, and offshore logistics fleet managers. Secondary validation draws from United States Coast Guard regulatory filings, EU Marine Equipment Directive certification databases, Australian maritime regulator vessel monitoring standards, customs trade records for marine instrumentation imports, and SEC disclosures from listed marine electronics suppliers. Bottom-up unit shipment estimates triangulate against top-down fleet modernization spending projections.
Rate-of-change decomposition separates volume effects from mix shift and pricing dynamics across the projection horizon. Segmentation dimensions include sensor technology type, installation channel, end-user sophistication tier, and vessel class. CAGRs derive from fitted growth curves calibrated to regulatory mandate implementation schedules and fleet age demographics. Industry-specific forecast inputs incorporate NMEA 2000 adoption velocity in commercial fishing fleets and GPS sensor convergence rates in integrated navigation systems.
Underlying measurement precision varies by segment; digital tachometer unit estimates carry tighter precision than smart tachometer projections where firmware update patterns remain emergent. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and rare earth supply continuity. Practitioners should monitor neodymium price volatility and United States Coast Guard cybersecurity rulemaking for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine Vehicles
Europe Inland Waterways Vessel Market
Marine Vehicles
Asean Boat Davits Market
Marine Vehicles
Marine Hybrid Propulsion Market
Marine Vehicles
Global Outboard Motors Market
Marine Vehicles
Bass Boat Market
Marine Vehicles
Trawler Boat Market
Marine Vehicles
Marine Steering Systems Market
Marine Vehicles
Small Boats Market
Marine Vehicles
Marine Methanol Engine Market
Marine Vehicles
Water Taxi Market
Marine Vehicles
Pontoon Boat Market
Marine Vehicles
Hydrogen-Powered Yacht Market
Marine Vehicles
India Aluminium Fishing Boat Market
Marine Vehicles
Global Inland Waterways Vessels Market
Marine Vehicles
Aluminium Fishing Boat Market
Marine Vehicles
LNG Marine Engine Market