
 Brazil Commercial Vehicles Lubricants Market | 2026-2036
Brazil Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Commercial Vehicles Lubricants Market Outlook
Subscription-based oil analysis and predictive maintenance programs is realigning how lubricant suppliers monetize fleet relationships in Brazil. Petrobras leverages its integrated refining and retail network to anchor volume contracts with national transport cooperatives. ExxonMobil Corporation competes through specialized heavy-duty engine oil formulations engineered for tropical operating conditions. Royal Dutch Shell Plc extends its position via digital fleet-management platforms bundled with lubricant supply agreements.
Brazil commercial vehicles lubricants are formulated hydrocarbon-based fluids with additive packages designed to reduce friction, dissipate heat, and suspend contaminants in internal combustion engines, transmissions, and hydraulic systems operating under high load and temperature stress. These products typically meet SAE viscosity grades and API service categories specified by OEMs for diesel-powered commercial equipment. Engine oil dominates volume demand across the Brazilian market, reflecting the country's substantial installed base of long-haul trucks and urban buses. Heavy-duty application specifications command premium positioning due to extended drain-interval requirements and severe-duty operating profiles in mining and agricultural logistics.
ANP, the Brazilian national petroleum regulator, enforces fuel-quality and lubricant-performance standards that directly shape product certification requirements for domestic blending and importation. CONMETRO and INMETRO administer conformity assessment procedures that determine market access for lubricant products sold through retail and wholesale channels. Fleet managers and lubricant manufacturers must monitor evolving PROCONVE emission-tier alignments and biodiesel blend-rate escalations, as these regulatory trajectories will dictate future lubricant additive chemistry and base-oil selection criteria.
Market Dynamics
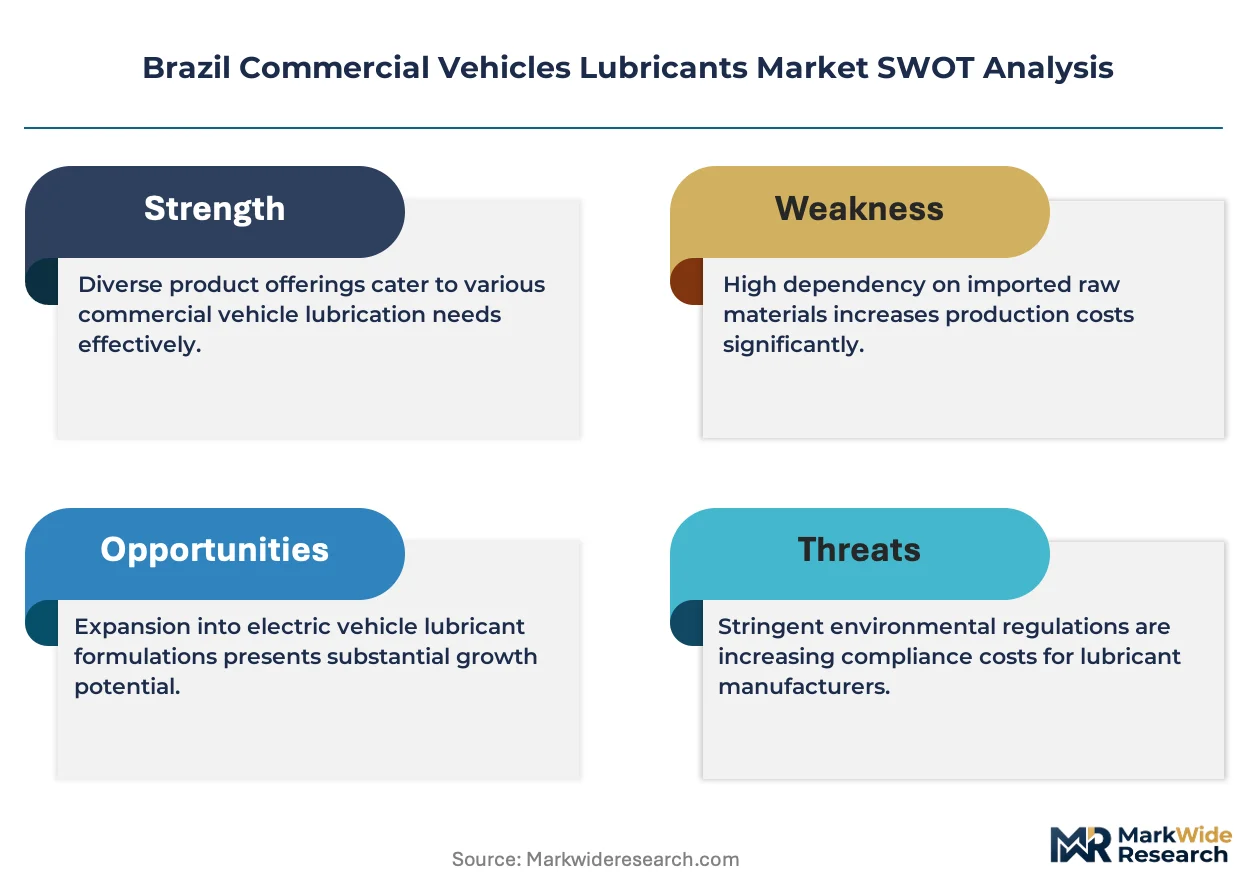
Federal biodiesel blending mandates are tightening across Brazil's agribusiness logistics corridors, forcing fleet operators to recalibrate lubricant specifications for higher corrosive fuel content and extended drain intervals.
Growth Catalysts
- PROCONVE emission-tier alignment:ANP enforcement of fuel-quality standards is compelling heavy-duty fleet operators to upgrade to premium lubricant formulations that protect aftertreatment systems.
- Agribusiness logistics expansion:Mato Grosso and Goiás grain transport corridors are generating concentrated demand for severe-duty engine oils engineered for high-load, high-temperature harvest-season operations.
- Extended drain-interval technology:Synthetic base-oil and advanced additive packages are enabling 50,000+ kilometer service intervals, reducing total cost of ownership for long-haul operators.
Market Restraints
- Group II/III base-oil import dependency:Domestic refining capacity constraints force blenders to source premium base stocks from North American and Asian suppliers, exposing margins to currency volatility and freight cost spikes.
- Counterfeit lubricant infiltration:Informal distribution channels in Brazil's northern and northeastern states undercut certified products with substandard formulations that fail API and ACEA specifications.
- Biodiesel blend-rate chemistry limitations:Rising B15 and B20 mandates accelerate oil oxidation and acid formation, compressing effective lubricant service life below OEM warranty thresholds.
Strategic Opportunities
- Minas Gerais mining logistics:Iron ore and phosphate extraction fleets in the Quadrilátero Ferrífero region represent an underpenetrated severe-duty segment requiring specialized hydraulic and transmission fluids.
- Digital fleet-management bundling:Telematics platforms that integrate oil analysis, route optimization, and predictive maintenance are creating new lubricant procurement channels outside traditional distributor networks.
- RenovaBio credit mechanism:The national biofuel decarbonization program incentivizes logistics operators to document carbon-intensity reductions, favoring suppliers with certified sustainable product lines.
Industry Challenges
- Tribology and additive chemistry specialization:Formulation engineers with expertise in biodiesel-compatible dispersant and antioxidant systems remain scarce in Brazil's domestic talent pool.
- INMETRO conformity assessment timelines:Laboratory testing and certification bottlenecks delay product launches by 8-14 months, compressing effective patent protection windows for premium formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Commercial Vehicles Lubricants Market |
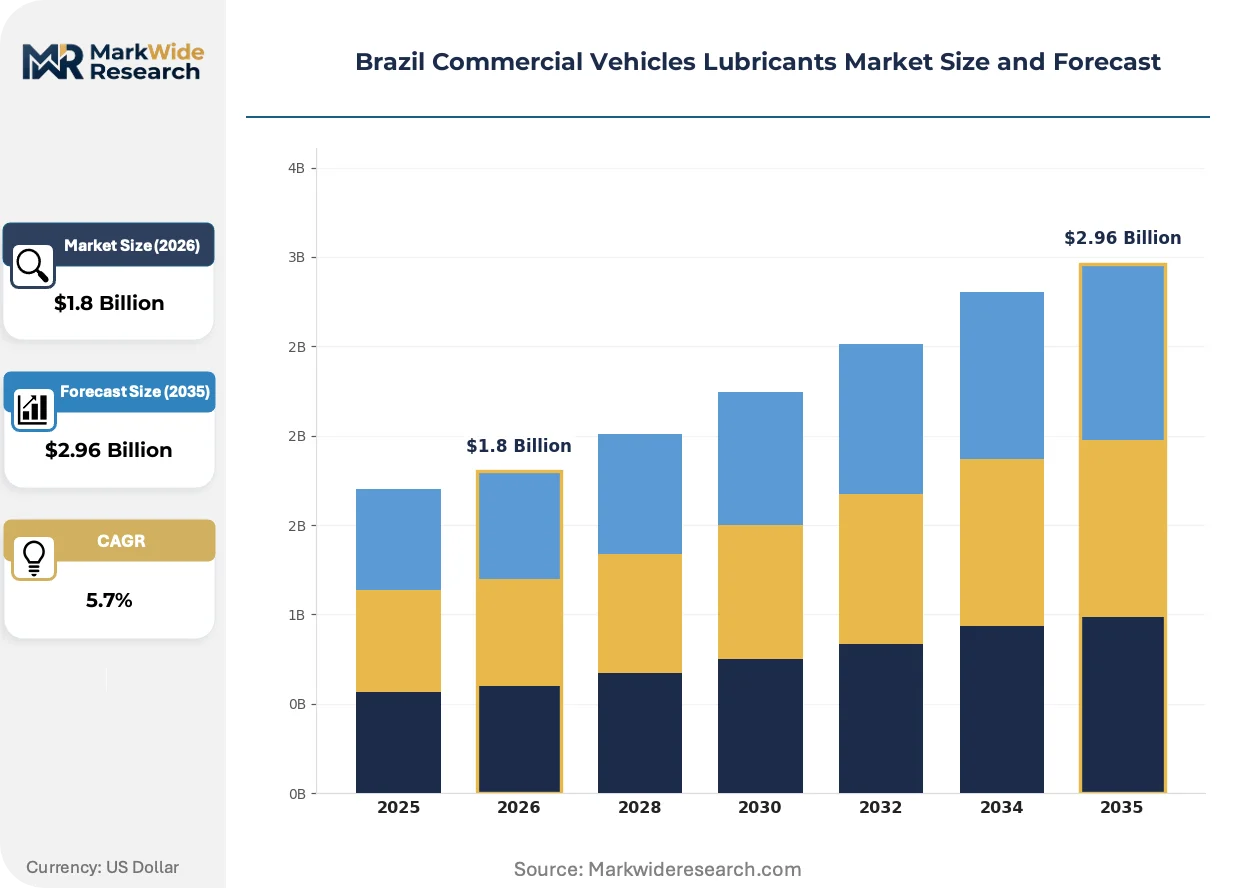
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Oil, Grease Vehicle Type: Trucks, Buses, Vans, Trailers Application: On-Road, Off-Road, Heavy-Duty, Light-Duty Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | ExxonMobil Corporation, Iconic Lubrificantes, Petrobras, Petronas Lubricants International, Royal Dutch Shell Plc, Gulf Oil International, TotalEnergies, Lucheti Lubrificantes, Marcio Benedito Vecchi EIRELI, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Commercial Vehicles Lubricants Market Strategic Shifts
Real-time oil condition monitoring and predictive analytics are displacing scheduled maintenance paradigms across Brazil's commercial vehicle fleets, rewriting procurement relationships between lubricant suppliers and transport operators.
Sensor-embedded drain plugs and on-board viscometers are automating lubricant degradation tracking in heavy-duty engines. São Paulo-based fleet operators are piloting these systems at scale. The technology is automating service interval optimization and compressing traditional oil analysis laboratory revenue streams.
ANP Resolution 858 established mandatory biodiesel blend-rate escalations through 2030, forcing lubricant formulators to recalibrate antioxidant and detergent additive packages. Blenders must now certify products against accelerated oxidation testing protocols. Heavy-duty engine oils face the most stringent reformulation timelines to maintain OEM approvals.
Fleet cooperatives in Paraná and Santa Catarina are consolidating procurement through volume-based framework agreements with integrated service providers. Traditional distributor networks are losing share to direct manufacturer relationships. This concentration is most visible in refrigerated transport segments where temperature-controlled cargo demands precise maintenance documentation.
Brazil Commercial Vehicles Lubricants Market Segmentation
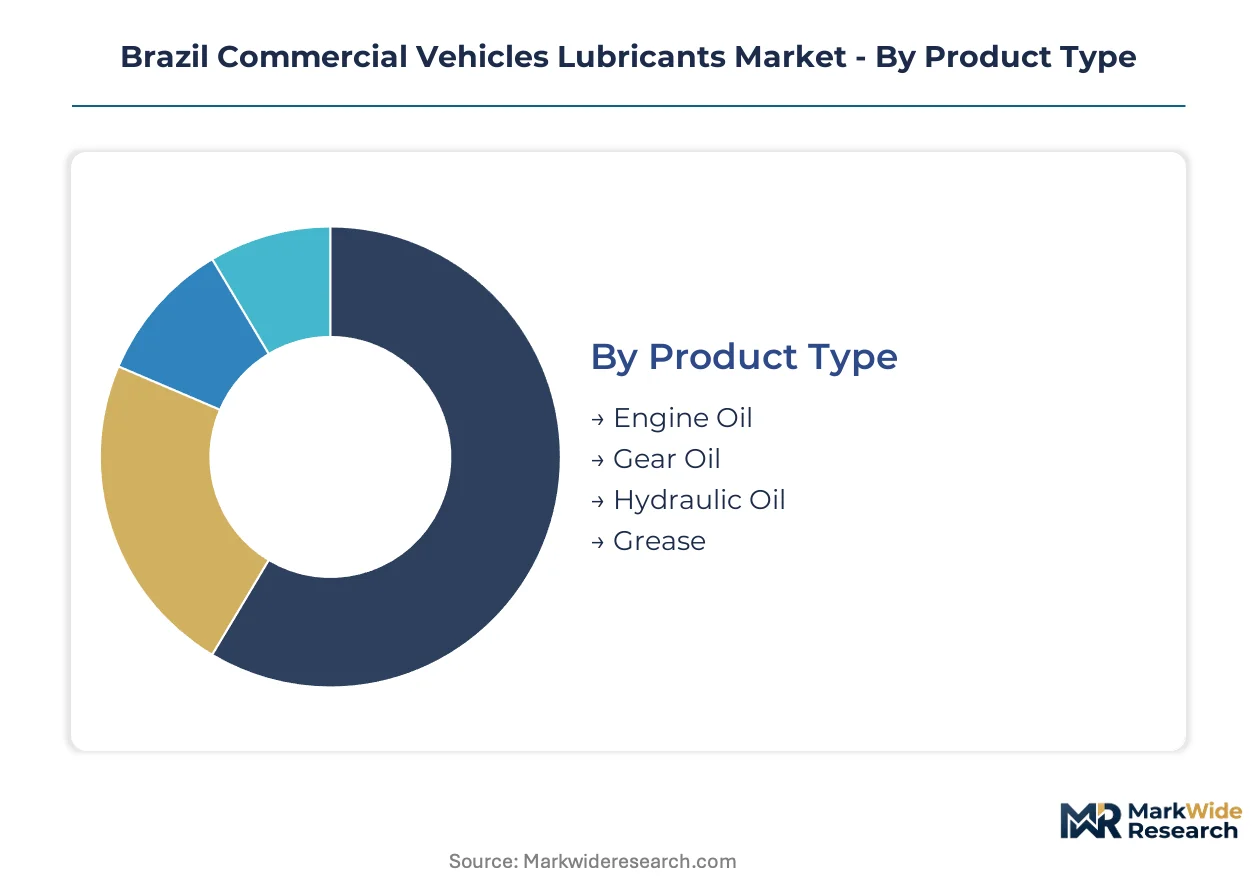
Brazil's commercial vehicle lubricant segments diverge sharply on certification intensity. ANP and INMETRO requirements stratify compliance costs across product categories, while vehicle duty cycles and distribution economics reshape where margin concentrates.
Product Type:
Engine oil carries the heaviest INMETRO conformity assessment burden, with API CK-4 and FA-4 certifications mandatory for heavy-duty diesel applications. Grease formulations face lighter documentation requirements but must still demonstrate NLGI consistency and ASTM dropping point compliance for mining equipment approvals.
- Engine Oil:Formulated with Group II/III base stocks and high-detergent additive packages meeting PROCONVE-aligned emission system protection standards. Demand concentrates in São Paulo state's long-haul trucking corridor, where fleet operators spec synthetic blends to achieve 50,000+ kilometer drain intervals under ANP biodiesel mandate pressure.
- Gear Oil:Extreme-pressure lubricants with sulfur-phosphorus additive chemistry for hypoid and spiral-bevel differentials. Mining logistics in Minas Gerais' Quadrilátero Ferrífero region drives severe-duty demand, with iron ore haulers requiring SAE 80W-140 formulations that resist high-load thermal breakdown.
- Hydraulic Oil:Anti-wear fluids with zinc-based additives for construction and agricultural machinery operating in Mato Grosso grain belts. Must demonstrate ISO 11158 viscosity stability across tropical temperature swings.
- Grease:Lithium-complex and calcium-sulfonate thickened lubricants for chassis, wheel bearings, and fifth-wheel plates. Paraná refrigerated transport fleets specify food-grade H1 variants for temperature-controlled cargo compliance documentation.
Leading the category by volume: Engine Oil. Expanding most quickly: Grease, as precision agriculture and cold-chain logistics multiply application points.
Vehicle Type:
Trucks dominate procurement scale, with national transport cooperatives negotiating framework agreements that reshape distributor economics. Buses operate under distinct municipal maintenance protocols that fragment purchasing authority across city-level fleet managers.
- Trucks:Long-haul tractors and rigid cargo vehicles account for the majority of bulk lubricant offtake. Agribusiness logistics corridors in Goiás and Mato Grosso generate concentrated seasonal demand spikes tied to soybean and corn harvest windows.
- Buses:Urban and intercity passenger fleets with standardized maintenance intervals dictated by municipal concession contracts. São Paulo's SPTrans and Rio's BRT operators mandate specific API service categories that limit blender flexibility.
- Vans:Light commercial delivery vehicles in last-mile urban distribution. Santa Catarina's e-commerce fulfillment hubs are driving synthetic oil conversion as fleet operators compress service downtime.
- Trailers:Non-powered units requiring wheel bearing, landing gear, and fifth-wheel lubrication. Often neglected in procurement frameworks, creating aftermarket service opportunities at highway corridor maintenance stops.
Trucks command the greatest volume share. Vans are gaining share fastest as urban logistics electrification delays shift investment toward efficiency optimization of existing diesel fleets.
Application:
Duty cycle severity determines base oil grade and additive treat rate, with off-road and heavy-duty applications commanding premium positioning. Light-duty specifications face downward price pressure from informal distribution channels in Brazil's northern states.
- Heavy-Duty:Sustained high-load, high-temperature operations in mining and agribusiness logistics. Requires synthetic base stocks and boosted antioxidant packages to counter accelerated oxidation from elevated B15-B20 biodiesel blends.
- On-Road:Highway trucking with predictable duty cycles and access to scheduled maintenance infrastructure. ANP fuel-quality enforcement in São Paulo and Paraná drives premium product specification.
- Off-Road:Construction, mining, and agricultural equipment with intermittent operation and contamination exposure. INMETRO certification timelines stretch longest for this segment due to specialized OEM approval requirements.
- Light-Duty:Urban delivery and passenger transport with moderate load profiles. Counterfeit infiltration is most severe here, with substandard API SJ-grade products undercutting certified formulations in informal retail channels.
Heavy-Duty generates the highest per-liter margin. Off-Road applications are climbing the fastest as iron ore and phosphate extraction expand in Minas Gerais.
Distribution Channel:
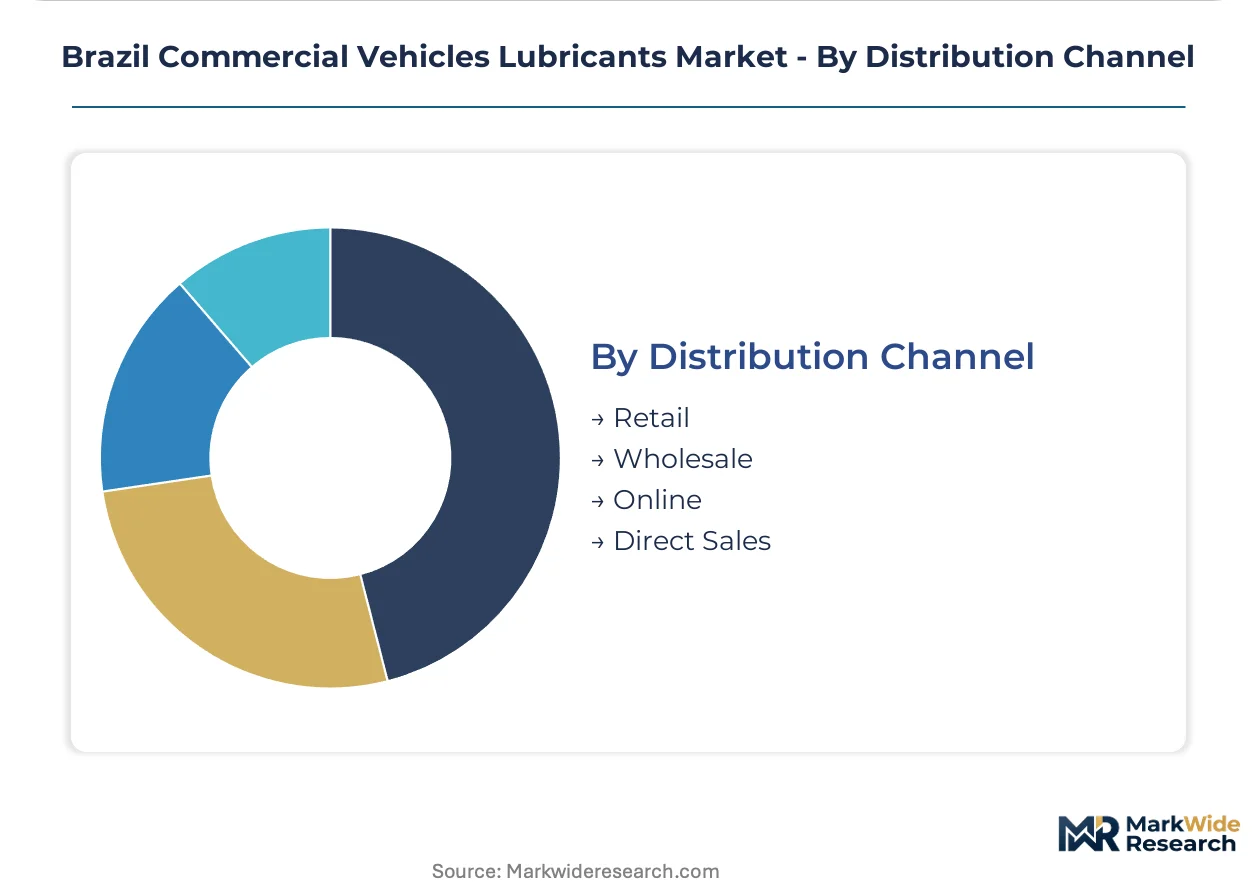
Channel selection determines customer ownership and margin capture, with direct sales and digital platforms displacing traditional distributor relationships among consolidated fleet operators.
- Wholesale:Volume supply to regional distributors and transport cooperatives. Petrobras anchors this channel through integrated refining-to-retail infrastructure, leveraging national coverage for framework contract dominance.
- Direct Sales:Manufacturer-to-fleet relationships bypassing distributor markups. Paraná and Santa Catarina refrigerated transport cooperatives are consolidating procurement through this channel, demanding bundled telematics and oil analysis services.
- Retail:Branded service stations and independent auto parts stores serving fragmented owner-operator segments. Counterfeit product infiltration concentrates in northern and northeastern retail networks.
- Online:E-commerce platforms and digital procurement portals. Emerging channel with traction among mid-size fleet managers seeking price transparency, though logistics complexity limits bulk lubricant adoption.
Wholesale retains the greatest volume flow. Direct Sales channels are expanding most quickly as fleet consolidation and digital fleet-management bundling rewrite procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's lubricant production clusters in São Paulo and Rio de Janeiro states, while consumption concentrates in agribusiness and mining corridors where fleet density outpaces local blending capacity.
São Paulo
Heavy-duty trucking fleets along the Rodoanel Mario Covas ring road and Santos port corridor generate concentrated demand for API CK-4 certified engine oils. ANP Resolution 858 enforcement tightens fuel-quality standards, compelling fleet operators to upgrade lubricant specifications. São José dos Campos anchors research partnerships between lubricant formulators and heavy-equipment OEMs testing tropical-climate additive packages.
Minas Gerais
Iron ore extraction fleets in the Quadrilátero Ferrífero region drive severe-duty hydraulic and transmission fluid demand that exceeds standard highway specifications. INMETRO conformity assessment timelines stretch longest here due to specialized mining equipment approvals. Belo Horizonte-based transport cooperatives negotiate direct procurement contracts bypassing traditional distributor networks.
Mato Grosso
Soybean and corn harvest logistics create seasonal demand spikes for high-temperature engine oils in the Sorriso-Rondonópolis grain belt. Federal biodiesel blending mandates accelerate oxidation in lubricant systems, compressing effective service intervals. Cuiabá fleet operators pilot sensor-embedded drain plugs to automate maintenance scheduling during peak harvest windows.
Paraná
Refrigerated transport fleets in the Curitiba-Londrina corridor consolidate procurement through framework agreements demanding bundled telematics and oil analysis services. PROCONVE emission-tier alignment drives premium product specification for temperature-controlled cargo compliance. Cascavel-based cooperatives are displacing traditional distributor relationships with direct manufacturer contracts.
Rio Grande do Sul
Port logistics in Porto Alegre and Rio Grande link soybean exports to maritime shipping, generating demand for marine-compatible lubricant formulations. RenovaBio credit mechanisms incentivize documentation of carbon-intensity reductions through certified sustainable product lines. Pelotas fleet operators test synthetic base-oil conversions to compress service downtime in just-in-time export chains.
Brazil Commercial Vehicles Lubricants Market Competitive Environment
Top-tier vendors anchor national framework contracts with transport cooperatives, while mid-tier blenders compete on price in fragmented retail channels. The market structure reflects a two-tier hierarchy: integrated oil majors with captive refining infrastructure versus independent blenders dependent on imported Group II/III base stocks. Three archetypes dominate: state-affiliated energy conglomerates, multinational lubricant specialists, and regional blending houses serving niche applications. Competitive moves concentrate on direct sales channel expansion and digital fleet-management bundling.
Among multinational lubricant specialists, ExxonMobil Corporation and Royal Dutch Shell Plc occupy positions exemplifying technology-driven premium positioning, while Petrobras represents the state-affiliated archetype leveraging integrated refining-to-retail infrastructure for volume contract dominance. These three companies anchor the competitive landscape through distinct channel strategies: direct fleet relationships, digital platform bundling, and national coverage through wholesale distribution networks.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Iconic Lubrificantes |
| Petrobras |
| Petronas Lubricants International |
| Royal Dutch Shell Plc |
| Gulf Oil International |
| TotalEnergies |
| Lucheti Lubrificantes |
| Marcio Benedito Vecchi EIRELI |
| Others |
Value Chain & Pricing Dynamics
RenovaBio credit mechanism compliance gates qualified supply access and premium-tier pricing power, as logistics operators document carbon-intensity reductions through certified sustainable product lines. Fleet procurement managers face tiered qualification hurdles that stratify blender participation and compress margin capture for non-compliant suppliers.
Pricing Analysis
Margin tightening in synthetic heavy-duty tiers reflects currency volatility on Group II/III base-oil imports and extended INMETRO certification timelines. Three-tier pricing structure across premium synthetic, standard mineral, and economy re-refined levels stratifies by API certification grade and drain-interval performance. Cost-down pressure on standard mineral formulations accelerates because counterfeit infiltration in northern retail channels undercuts certified products. Owner-operators in informal distribution zones exhibit highest price sensitivity; mining fleet procurement managers in Minas Gerais show lowest sensitivity due to warranty compliance requirements.
Supply Chain Analysis
Dual-sourcing mandates from national transport cooperatives force blenders to qualify backup suppliers for Group II/III base stocks. Domestic production draws from United States, South Korea, and Singapore for premium base-oil feedstocks, while additive packages rest on imports from Germany and Japan. Single-source vulnerability concentrates in specialized dispersant chemistry for biodiesel-compatible formulations. Distribution runs through Petrobras-anchored wholesale networks with direct sales channels gaining share among consolidated refrigerated transport fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Group II/III base-oil import dependency props pricing power for integrated refiners with captive supply, constraining independent blender expansion. Capacity bottlenecks at ANP-certified blending facilities reinforce incumbent positioning.
For Market Incumbents: Anticipate synthetic formulation demand acceleration by securing long-term offtake agreements with Mato Grosso grain transport cooperatives ahead of B20 mandate implementation. Backward integration into additive blending capacity in São Paulo state mitigates currency exposure on imported treat rates. Digital fleet-management bundling with Paraná refrigerated operators defends contract renewal rates against multinational specialist encroachment. For New Entrants and Emerging Players: Capture underpenetrated severe-duty mining logistics in Minas Gerais Quadrilátero Ferrífero region where specialized hydraulic fluid demand exceeds standard highway specifications. Telematics-integrated oil analysis services offer the most penetrable go-to-market angle for mid-size fleet procurement consolidation. Direct manufacturer relationships with Cascavel-based cooperatives bypass entrenched Petrobras wholesale networks. For Investors and Strategic Acquirers: INMETRO certification backlog clearance acceleration is the leading indicator that premium formulation patent protection windows will compress, favoring early-stage additive technology acquisitions. Five-to-ten year viability centers on biodiesel-compatible antioxidant intellectual property positions. Acquisition target archetype: regional blenders with qualified mining equipment approvals and established Belo Horizonte transport cooperative relationships. Monitor ANP Resolution 858 enforcement intensity as signal for synthetic conversion rate inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Blending | Captures margin currently lost to German and Japanese chemical suppliers while securing biodiesel-compatible formulation control. |
| Digital Fleet-Management Platform Launch | Renews procurement relationships with Paraná refrigerated transport cooperatives demanding bundled telematics services. |
| Mining Equipment Approval Expansion | Opens Quadrilátero Ferrífero iron ore fleet contracts requiring specialized hydraulic fluid specifications beyond highway grades. |
| RenovaBio Certification Program | Qualifies premium product lines for federal biofuel decarbonization credit mechanisms favoring documented carbon reductions. |
| Direct Sales Channel Buildout | Bypasses Petrobras-anchored wholesale networks consolidating procurement among national transport cooperatives. |
Study Parameters
Multi-period observation of PROCONVE emission-tier alignments and biodiesel blend-rate escalations anchored the trend analysis, supplemented by interviews with lubricant formulation directors, fleet procurement managers at national transport cooperatives, ANP regulatory affairs officers, and aftermarket service channel heads. Secondary validation drew from ANP Resolution 858 documentation, INMETRO conformity assessment records, SEC filings of multinational lubricant specialists, and Brazilian customs trade data on Group II/III base-oil imports. Bottom-up fleet operator demand modeling and top-down refinery capacity analysis provided triangulation checks.
Input-output matrices mapped product type, vehicle duty cycle, application severity, and distribution channel economics across the projection horizon. Segmentation dimensions modeled include base-oil grade tier, fleet size category, regional logistics corridor, and OEM approval status. CAGRs derived from elasticity-adjusted volume projections responding to biodiesel mandate schedules and synthetic conversion rate assumptions. Industry-specific forecast inputs incorporated drain-interval technology adoption curves and telematics platform penetration rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANP enforcement intensity and currency volatility on base-oil imports. Deviation in B20 mandate implementation timeline or INMETRO certification processing duration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Hydraulic Fluid Market
Lubricants
North America and Europe Forestry Lubricants Market
Lubricants
Italy Lubricants Market
Lubricants
Europe Lubricants Market
Lubricants
Bangladesh Lubricants Market
Lubricants
Mining Lubricants Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Global Independent Lubricant Manufacturers Market
Lubricants
Qatar Lubricants Market
Lubricants
Malaysia Automotive Lubricants Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
United Kingdom Automotive Lubricants Market
Lubricants
Construction Lubricants Market