
 South Korea Lubricants Market | 2026-2036
South Korea Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Lubricants Market Analytics
Product bundling of lubricants with predictive maintenance software packages is shifting procurement patterns among fleet operators and industrial buyers. SK Lubricants Co. Ltd leverages its Ulsan refining complex to sustain captive base-oil supply for synthetic formulations. ExxonMobil Corporation competes through technology leadership in low-viscosity motor oils tailored to Korean OEM specifications. Hyundai Oilbank anchors downstream distribution through integrated service station networks and direct OEM supply contracts.
Lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades and oxidation stability determining service intervals and equipment protection. South Korean production emphasizes Group III and Group III+ base stocks refined through severe hydrocracking to meet stringent OEM fill specifications. Motor oil dominates volume throughput given the density of passenger vehicles and commercial fleets operating domestically, while industrial lubricants command premium positioning around specialized hydraulic and gear applications in precision manufacturing. Synthetic oil formulations are gaining share fastest as thermal stability requirements intensify under downsized turbocharged engine architectures and extended drain intervals.
MFDS oversight of chemical substance safety and K-REACH registration requirements shape formulation disclosure and import compliance for additive packages entering South Korea. KS standards administered by KATS mandate specific performance benchmarks for automotive and industrial lubricant categories, creating technical barriers for uncertified suppliers. Stakeholders must monitor evolving OEM factory-fill specifications from Hyundai and Kia alongside tightening carbon-intensity benchmarks for refinery operations.
Market Dynamics
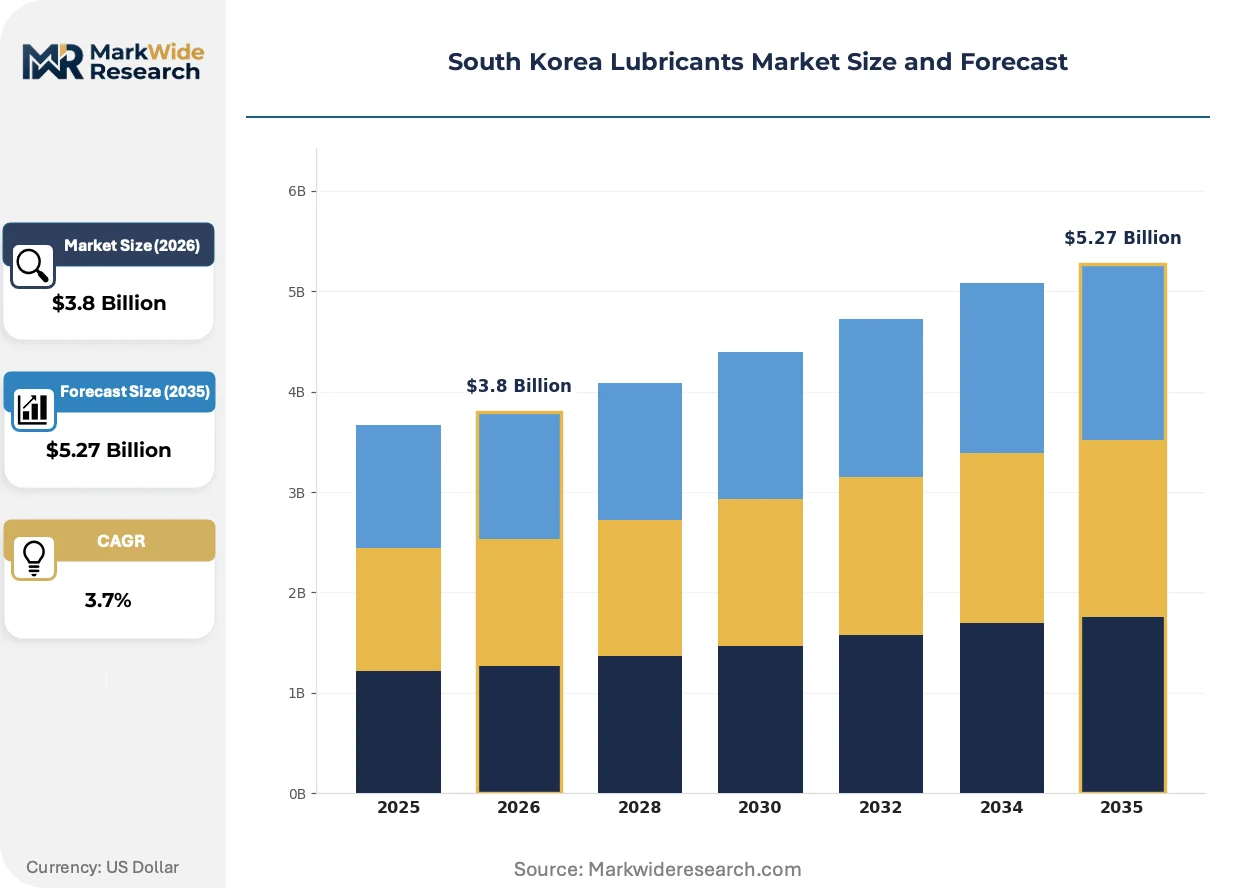
Hyundai Motor Group's hybrid fleet expansion and K-REACH chemical registration mandates are restructuring formulation requirements and procurement priorities across South Korea's lubricants value chain.
Growth Catalysts
- Hybrid powertrain proliferation:Hyundai and Kia's expanding HEV and PHEV lineages sustain demand for advanced thermal management fluids and low-viscosity motor oils optimized for stop-start cycling.
- Gyeonggi-do industrial corridor concentration:Precision manufacturing clusters around Seoul and Incheon generate sustained pull for specialized hydraulic and gear lubricants in semiconductor and automotive component production.
- K-REACH compliance tiering:The chemical registration framework's phased disclosure requirements are accelerating reformulation investments toward higher-grade synthetic base stocks.
Market Restraints
- Group III base oil import dependency:Severe hydrocracking capacity constraints leave South Korean blenders exposed to feedstock cost volatility from Middle Eastern and Singaporean suppliers.
- Synthetic formulation cost premiums:The 40-60% price differential versus mineral oils limits penetration in price-sensitive independent repair channels serving older vehicle parc.
- Extended drain interval compression:OEM-specified 15,000-30,000 kilometer service cycles are structurally reducing lubricant volume throughput per vehicle.
Strategic Opportunities
- EV-adjacent fluid diversification:Battery thermal management and e-axle greases represent white-space categories as Hyundai Ioniq and Kia EV production scales.
- Predictive maintenance bundling:Fleet operators in South Korea's dense logistics sector are piloting software-integrated lubricant procurement models tying consumption to equipment health monitoring.
- Ulsan refining complex captive supply:Integrated base oil production enables domestic formulators to bypass import bottlenecks and accelerate synthetic grade certification timelines.
Industry Challenges
- KS standard certification bottlenecks:KATS-administered automotive lubricant testing protocols create 12-18 month approval delays for new additive packages.
- Additive formulation IP fragmentation:Proprietary dispersant and anti-wear chemistries from Lubrizol, Infineum, and Afton require complex multi-party licensing for K-REACH-compliant disclosure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Lubricants Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.27 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Motor Oil, Gear Oil, Hydraulic Oil, Industrial Lubricants Application: Automotive, Industrial Machinery, Marine, Aerospace Base Oil: Mineral Oil, Synthetic Oil, Biodegradable Oil, Semi-Synthetic Oil End User: OEMs, Aftermarket Providers, Retail Consumers, Maintenance Services |
| Companies Covered | S-OIL Corporation, BP Plc (Castrol), ExxonMobil Corporation, FUCHS, Royal Dutch Shell Plc, SK Lubricants Co. Ltd, Hyundai Oilbank, TotalEnergies, GS Caltex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Lubricants Market Evolving Landscape
Formulation chemistry, regulatory compliance architecture, and procurement interfaces are converging to reshape competitive positioning in South Korea's lubricants sector.
Low-viscosity 0W-8 and 0W-16 motor oil grades are consolidating as the technical baseline for Korean OEM factory fill specifications. Hyundai and Kia engine designs prioritize fuel economy benchmarking over legacy viscosity heritage. The shift is compressing demand for 5W-30 and 10W-40 segments while elevating Group III+ and PAO base stock requirements.
MFDS chemical substance safety oversight and K-REACH registration tiering are tightening additive package disclosure thresholds. Formulators must now submit full composition data for import authorization, raising compliance costs for international suppliers. Domestic blenders with captive base oil supply and established regulatory affairs capabilities are capturing share from import-dependent competitors.
Fleet operators and industrial buyers are migrating toward consumption-based service contracts replacing transactional drum and bulk purchases. Hyundai Oilbank and SK Lubricants are deploying IoT-enabled tank monitoring systems to secure captive demand. The model is most advanced in Gyeonggi-do logistics corridors where real-time inventory visibility reduces downtime risk.
South Korea Lubricants Market Segmentation
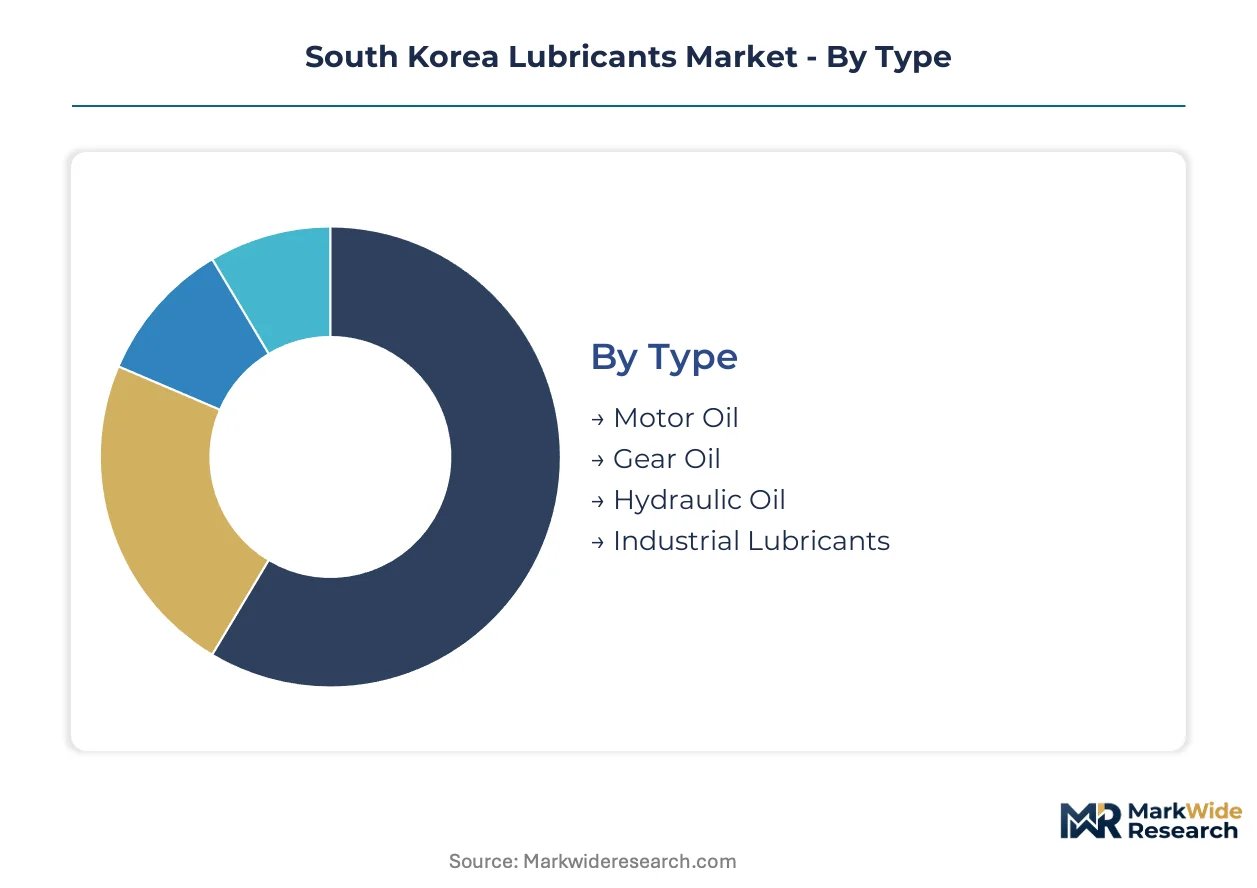
Segmentation in South Korea's lubricants market tracks how K-REACH registration tiers and KS certification requirements concentrate supply advantages among domestic blenders with captive base oil production. Each dimension reveals distinct regulatory burdens and procurement patterns across the Gyeonggi-do industrial corridor.
Type:
K-REACH chemical disclosure thresholds vary sharply by lubricant type, with automotive-facing categories subject to the most stringent MFDS substance safety reviews.
- Motor Oil:Formulated from Group III and Group III+ base stocks through severe hydrocracking, motor oil carries the heaviest KS KATS certification load for viscosity grade validation. Demand concentrates in Seoul-Incheon fleet corridors where Hyundai and Kia factory-fill specifications dictate 0W-8 and 0W-16 procurement.
- Industrial Lubricants:Precision hydraulic and gear formulations for semiconductor manufacturing command premium positioning. Gyeonggi-do production clusters generate sustained pull for specialized thermal stability chemistries under extended service interval contracts.
- Gear Oil:Heavy-duty axle and transmission lubricants serve commercial vehicle parc with moderate certification complexity.
- Hydraulic Oil:Construction and manufacturing equipment fluids face standardized KS performance benchmarks with faster approval timelines.
Motor Oil sits at the top of the volume ranking, with Industrial Lubricants climbing the fastest.
Application:
Application segmentation maps directly to end-use equipment density and OEM specification authority across South Korean manufacturing and transport infrastructure.
- Automotive:Passenger vehicle and commercial fleet lubrication dominates throughput. Hyundai Motor Group's hybrid powertrain proliferation sustains demand for low-viscosity thermal management fluids with stop-start cycling resistance.
- Industrial Machinery:Precision manufacturing equipment in Ulsan and Gyeonggi-do corridors requires specialized hydraulic and circulating oils. Semiconductor fabrication tools impose particulate cleanliness standards that filter supplier pools aggressively.
- Marine:Port operations at Busan and Incheon drive bunker and auxiliary machinery lubricant demand with IMO-aligned environmental compliance layers.
- Aerospace:Military and commercial aviation maintenance represents a narrow certification-intensive niche with extended qualification periods.
Automotive commands the largest revenue base, while Industrial Machinery expands most quickly on precision manufacturing investment.
Base Oil:
Base oil selection determines K-REACH registration depth and import authorization complexity for additive package disclosure.
- Synthetic Oil:Group III+ and PAO formulations engineered for thermal stability under downsized turbocharged architectures. SK Lubricants' Ulsan captive supply insulates domestic blenders from Middle Eastern feedstock volatility.
- Mineral Oil:Group I and II stocks refined through conventional solvent extraction face cost pressure from extended drain interval compression. Independent repair channels serving older vehicle parc sustain residual demand despite synthetic displacement.
- Semi-Synthetic Oil:Blended formulations balance performance and price positioning for mid-tier service intervals.
- Biodegradable Oil:Environmentally acceptable lubricants for sensitive marine and agricultural applications carry emerging regulatory preference signals.
Mineral Oil retains volume leadership, with Synthetic Oil gaining share fastest on OEM specification tightening.
End User:
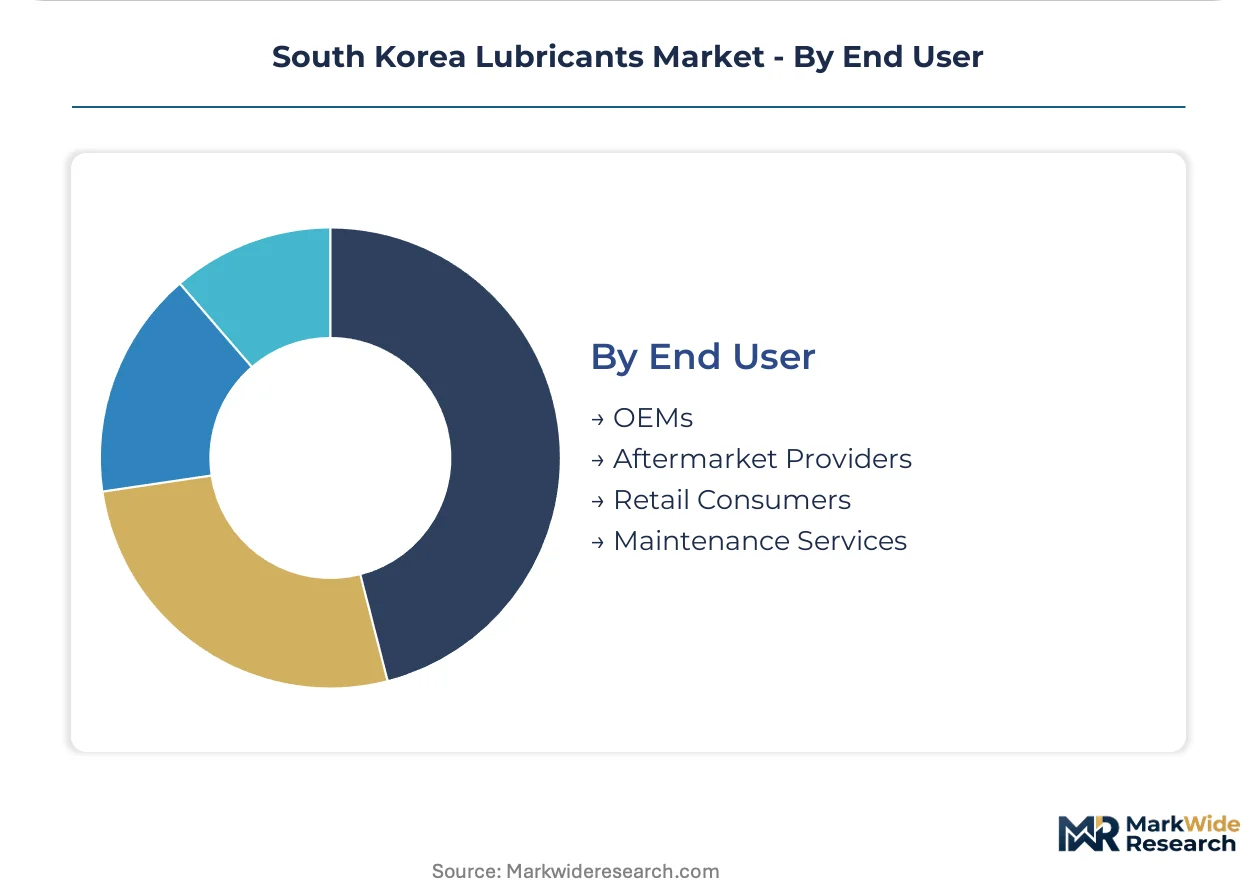
End user categories separate procurement models between specification-driven factory fill and price-sensitive aftermarket channels.
- OEMs:Hyundai and Kia factory-fill contracts impose the most demanding technical specifications and longest qualification timelines. Direct supply agreements with SK Lubricants and Hyundai Oilbank lock in volume commitments tied to production schedules.
- Aftermarket Providers:Independent distributors and service chains face 40-60% price sensitivity gaps versus synthetic premiums. Bulk procurement consolidation in Gyeonggi-do logistics corridors is shifting toward IoT-enabled consumption-based contracts.
- Retail Consumers:Individual vehicle owners purchasing through service station networks and auto parts retailers.
- Maintenance Services:Fleet operators and industrial maintenance departments with predictive maintenance software integration requirements.
OEMs anchor the highest-margin tier, with Aftermarket Providers showing the steepest procurement model transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's lubricants industry traces its modern scale to the 1970s petrochemical expansion anchored by Ulsan and Yeosu refining complexes. Domestic base oil production capacity shaped a vertically integrated supply architecture that persists today. Regional demand patterns concentrate around automotive manufacturing corridors and precision industrial clusters.
Seoul Capital Area
Hyundai and Kia headquarters in Seoul drive factory-fill specification authority for low-viscosity motor oils across the metropolitan region. MFDS chemical safety oversight and K-REACH registration requirements filter additive package imports through Incheon port facilities. Gyeonggi-do semiconductor fabrication plants in Hwaseong and Pyeongtaek sustain specialized demand for particulate-clean hydraulic fluids under extended service contracts.
Busan-Ulsan
SK Lubricants operates its severe hydrocracking base oil complex in Ulsan, supplying captive feedstock for Group III+ synthetic formulations. Hyundai Heavy Industries shipbuilding in Ulsan generates marine lubricant demand aligned with IMO environmental compliance layers. Busan container port operations drive bunker fuel and auxiliary machinery fluid throughput.
Daegu-Gyeongbuk
Textile machinery and automotive component manufacturing in Daegu sustain industrial lubricant consumption for precision gear and hydraulic systems. KATS-administered KS standards certification creates technical barriers for imported formulations in regional distribution channels. Gumi electronics industrial complex demands thermal management fluids for semiconductor packaging equipment.
Daejeon-Sejong
Government research institutes in Daejeon pilot predictive maintenance software integration with lubricant procurement systems for public fleet operators. K-REACH compliance documentation requirements concentrate regulatory affairs capabilities in Sejong administrative city. Chungnam petrochemical belt provides downstream blending capacity for domestic formulators.
Gwangju-Honam
Yeosu National Industrial Complex hosts residual Group I and II base oil refining capacity facing synthetic grade displacement pressure. Agricultural machinery and construction equipment parc in Honam region sustains mineral oil demand in price-sensitive independent service channels. Kia Motors manufacturing in Gwangju anchors OEM factory-fill contracts for hybrid powertrain fluids.
South Korea Lubricants Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the base oil grade and certification complexity spectrum. Domestic blenders with captive severe hydrocracking capacity capture margin advantages over import-dependent competitors facing Middle Eastern feedstock volatility. Three archetypes define the competitive set: integrated refining-lubricant specialists, international oil majors with technology licensing arrangements, and regional distributors serving aftermarket price sensitivity. Capacity expansion in Group III+ base stocks and strategic partnerships for additive package sourcing represent the dominant competitive moves reshaping supply positions.
Among domestic integrated specialists, SK Lubricants Co. Ltd and Hyundai Oilbank exemplify the captive supply archetype, anchoring competitive positioning through Ulsan refining complex access. ExxonMobil Corporation represents the international technology-licensing tier, competing through formulation expertise aligned with Korean OEM specifications. These three entities occupy distinct strategic positions: domestic vertical integration, foreign technology leadership, and downstream distribution density respectively.
| Leading Market Players |
|---|
| S-OIL Corporation |
| BP Plc (Castrol) |
| ExxonMobil Corporation |
| FUCHS |
| Royal Dutch Shell Plc |
| SK Lubricants Co. Ltd |
| Hyundai Oilbank |
| TotalEnergies |
| GS Caltex |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap blenders concentrated in the Gyeonggi-do corridor anchor pricing discipline through long-term service contracts tied to Hyundai and Kia factory-fill specifications, while their limited backward integration into base oil production exposes margins to Middle Eastern feedstock volatility. This ownership pattern concentrates procurement leverage among domestic formulators with captive Ulsan refining access, compressing price competition in synthetic grades while mineral oil channels face persistent cost pressure from independent repair networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM factory-fill contracts from fleet service agreements and independent aftermarket transactions. Certification grade under MFDS K-REACH tiering and volume scale through IoT-enabled consumption contracts drive price differentiation, with synthetic Group III+ formulations commanding substantial premiums over mineral alternatives. Cost compression in the economy tier is intensifying because extended drain intervals reduce per-vehicle throughput, while aftermarket providers serving older vehicle parc exhibit the highest price sensitivity versus OEM procurement teams with specification-locked contracts.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Ulsan and Yeosu refining complexes through Gyeonggi-do regional distribution centers serving Seoul-Incheon manufacturing clusters. Geographic supply concentration centers on South Korea, Singapore, and Middle Eastern producers for Group III base stocks, while additive package formulations draw from Lubrizol, Infineum, and Afton chemistries subject to K-REACH disclosure requirements. Single-source vulnerability around severe hydrocracking capacity constrains domestic blenders, with downstream distribution running through integrated service station networks and direct OEM supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's lubricants market functions as a stable compounder anchored by Hyundai Motor Group's hybrid fleet expansion and the structural durability of factory-fill specification authority. Steady demand for thermal management fluids under extended service intervals sustains predictable revenue streams across economic cycles.
For Market Incumbents: Anchor competitive position through captive base oil supply expansion at Ulsan and accelerated Group III+ certification timelines under K-REACH tiering. Defend against additive formulation IP fragmentation by securing multi-party licensing arrangements with Lubrizol and Infineum ahead of disclosure deadline compression. Prioritize backward integration into predictive maintenance software bundling to lock fleet operator demand in Gyeonggi-do logistics corridors.
For New Entrants and Emerging Players: Fleet operators with unmet predictive maintenance integration requirements represent the most penetrable entry channel for white-space positioning. Target EV-adjacent fluid categories including battery thermal management and e-axle greases as Hyundai Ioniq and Kia EV production scales. Pursue go-to-market partnerships with IoT-enabled tank monitoring providers to bypass established distribution density.
For Investors and Strategic Acquirers: Domestic refining-lubricant integrated specialists are the most active acquirer in this space, seeking additive formulation capabilities to complete vertical coverage. The five-to-ten year viability window favors targets with established K-REACH regulatory affairs infrastructure and KS certification track records. Monitor KS KATS approval timeline compression as the inflection signal for consolidation pressure among import-dependent blenders facing qualification bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive severe hydrocracking capacity at Ulsan insulates SK Lubricants from Middle Eastern feedstock volatility. |
| Predictive Maintenance Software Bundling | IoT-enabled consumption contracts with Hyundai Oilbank lock fleet demand in Gyeonggi-do logistics corridors. |
| K-REACH Compliance Certification | Accelerated additive package disclosure timelines filter uncertified international suppliers from Korean procurement. |
| EV-Adjacent Fluid Development | Battery thermal management formulations address white-space demand as Hyundai Ioniq production scales. |
| Long-Term OEM Supply Agreements | Direct factory-fill contracts with Hyundai and Kia anchor volume commitments tied to hybrid powertrain output. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant formulators, OEM procurement directors, fleet maintenance managers, and K-REACH regulatory consultants with secondary validation through Korea Petroleum Association trade data, MFDS chemical substance filings, customs import records, and Hyundai Motor Group supplier disclosures. Bottom-up volume modeling across base oil grades and top-down value reconciliation through refining margin analysis provided cross-verification.
Comparable-period anchoring tied projection assumptions to historical demand patterns observed across hybrid powertrain penetration curves and extended drain interval adoption timelines. The analytical framework segmented by lubricant type, base oil grade tier, end-use application, and procurement channel across the modeling period, with CAGRs derived from regression against vehicle parc density and industrial production indices. Forecast inputs incorporated K-REACH registration phase-in schedules and OEM factory-fill specification evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to synthetic base oil capacity expansion timelines and electric vehicle penetration rates. Outputs reflect documented assumptions around regulatory compliance costs and feedstock price trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Bulgaria Lubricants Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Gun Lubricant Market
Lubricants
Aviation Lubricants Market
Lubricants
Industrial Gear Oil Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Vietnam Lubricants Market
Lubricants
America Lubricants Market
Lubricants
Plastic Lubricants Market
Lubricants
Poland Lubricants Market
Lubricants
Global Lubricants Market
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Turkey Automotive Engine Oils Market