
 Indonesia Lubricants Market | 2026-2036
Indonesia Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Lubricants Market Outlook
The capital-intensity divergence between integrated refiners and independent blenders is collapsing as base oil supply tightens and import costs rise. PT Pertamina Lubricants leverages captive access to Group II base oil streams from domestic refining. Shell Indonesia competes through premium synthetic formulations targeting OEM fill programs. ExxonMobil Indonesia anchors its position in the mining and power generation sectors with heavy-duty diesel engine oils.
Lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with key specifications including viscosity grade, oxidation stability, and total base number for acid neutralization capacity. Engine oil dominates product type revenue due to Indonesia's large vehicle parc and stringent drain interval extensions, while synthetic base oil types are gaining fastest as OEMs specify lower-viscosity grades for fuel economy compliance. Fleet operators represent the most concentrated end-user profit pool because of their volume contracting power and technical service requirements.
BIS-equivalent SNI standards enforced by Indonesia's national standardization body mandate minimum performance benchmarks for lubricant labeling and import clearance. The Ministry of Industry's domestic content requirements shape procurement patterns for state-owned enterprises and infrastructure projects. Stakeholders must monitor how evolving emissions regulations for diesel machinery redirect formulation investment toward low-SAPS and long-drain products.
Market Dynamics
Base oil supply tightness and SNI certification mandates are compressing margins for independent blenders while rewarding integrated refiners with captive Group II streams. Fleet operators now demand technical service bundling, shifting profit pools from product sales to lifecycle contracts.
Growth Catalysts
- Mining Fleet Expansion:Heavy-duty diesel engine oil consumption is rising as copper and nickel operations in Sulawesi and Papua extend equipment uptime requirements.
- SNI Certification Mandate:Indonesia's national standardization body enforces BIS-equivalent labeling standards that filter low-grade imports and elevate reformulation toward higher-performance base stocks.
- Palm Oil Processing Intensification:Hydraulic fluid and gear oil demand tracks capacity additions in Sumatran and Kalimantan crushing facilities.
Market Restraints
- Group II Base Oil Import Dependency:Domestic refining capacity constraints force blenders to source base stocks from Singapore and South Korea, exposing margins to freight and currency volatility.
- Synthetic Lubricant Cost Premium:PAO and ester base stocks carry 40-60% higher unit costs than mineral equivalents, limiting penetration in price-sensitive independent workshop channels.
- Used Oil Collection Infrastructure Gaps:Re-refining feedstock availability remains concentrated in Java, leaving outer island markets dependent on virgin base oil supply.
Strategic Opportunities
- Eastern Indonesia Logistics Gap:Makassar and Sorong harbor zones lack lubricant blending presence, creating first-mover potential for bulk import and satellite distribution.
- Long-Drain Interval Formulations:Low-SAPS engine oils meeting Euro 5-equivalent emissions standards open technical differentiation in Jakarta's premium fleet segment.
- State-Owned Enterprise Procurement Reform:Ministry of Industry domestic content requirements redirect state mining and power generation tenders toward locally blended products.
Industry Challenges
- Formulation Chemist Shortage:Indonesian universities produce limited lubricant-specific technical talent, forcing blenders to recruit from Singapore and Malaysia.
- SNI Testing Bottleneck:Accredited laboratory capacity in Jakarta creates 8-12 week certification delays for new product registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Lubricants Market |
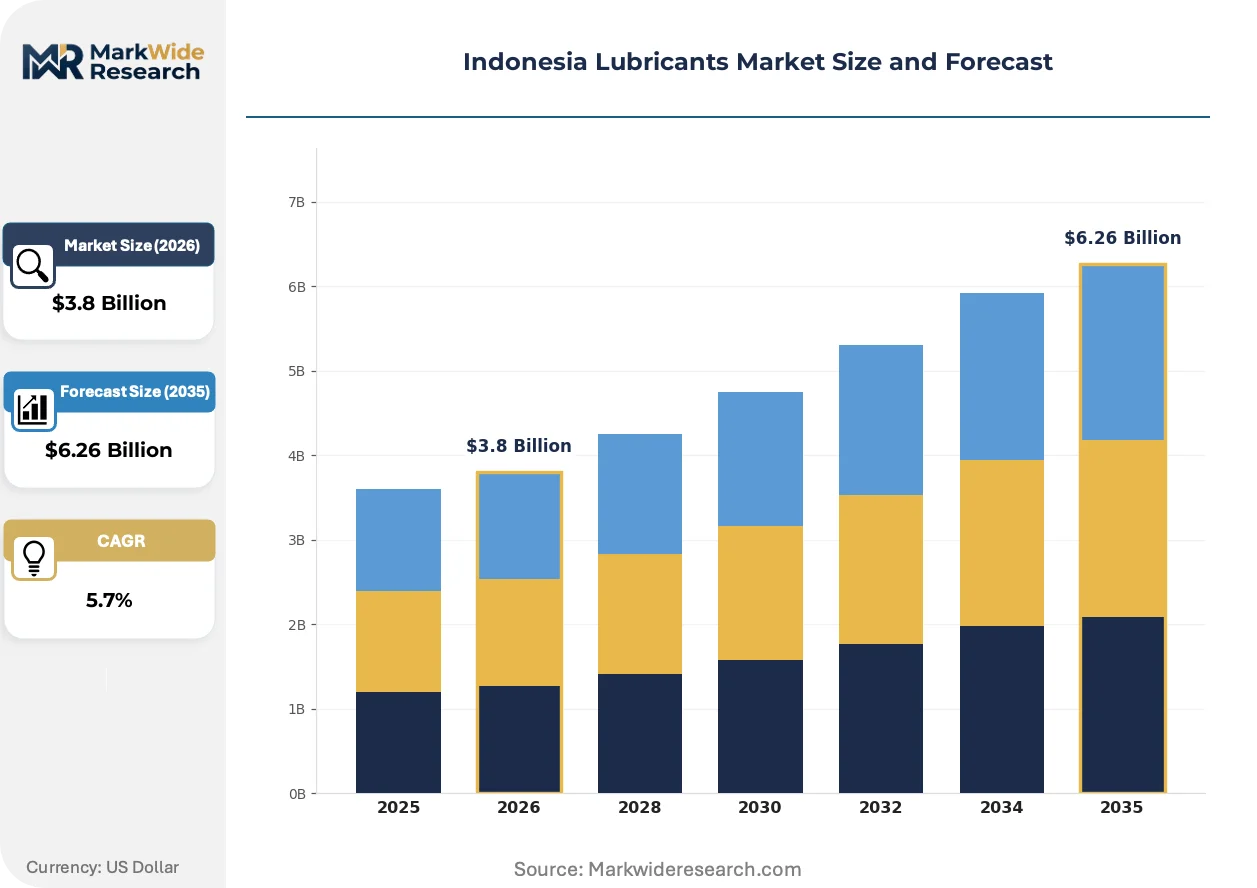
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Hydraulic Oil Application: Automotive, Industrial Machinery, Marine, Aviation End User: OEMs, Aftermarket Providers, Retail Consumers, Fleet Operators Base Oil Type: Synthetic, Mineral, Semi-Synthetic, Bio-Based |
| Companies Covered | PT Pertamina Lubricants, Shell Indonesia, ExxonMobil Indonesia, Chevron Lubricants Indonesia, TotalEnergies Lubricants Indonesia, PT Wiraswasta Gemilang Indonesia, BP PLC (Castrol), FUCHS, PETRONAS Lubricants International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Lubricants Market Strategic Shifts
Synthetic base oil technology and digital fleet monitoring are compressing traditional service intervals and rewiring distributor economics. Reformulation investments now target OEM warranty compliance rather than generic performance claims.
Group III and PAO synthetic base stocks are supplanting Group I mineral oils in heavy-duty diesel formulations. Mining contractors in Kalimantan and fleet operators in Surabaya are specifying 5W-30 and 10W-40 grades for fuel economy compliance. This shift is compressing the addressable market for conventional mineral blends while expanding technical service revenue attachments.
SNI standards enforced by Indonesia's national standardization body mandate minimum performance benchmarks for viscosity stability and oxidation resistance. The regulation blocks substandard imports from Southeast Asian trading partners. Independent blenders without captive base oil supply face reformulation costs that integrated competitors absorb through backward control.
Lifecycle contracting is displacing spot procurement in Jakarta's logistics corridor. Fleet operators now bundle lubricant supply with oil analysis and drain interval management. This shift concentrates purchasing authority among technical procurement teams and marginalizes traditional distributor relationships in Java's manufacturing zones.
Indonesia Lubricants Market Segmentation
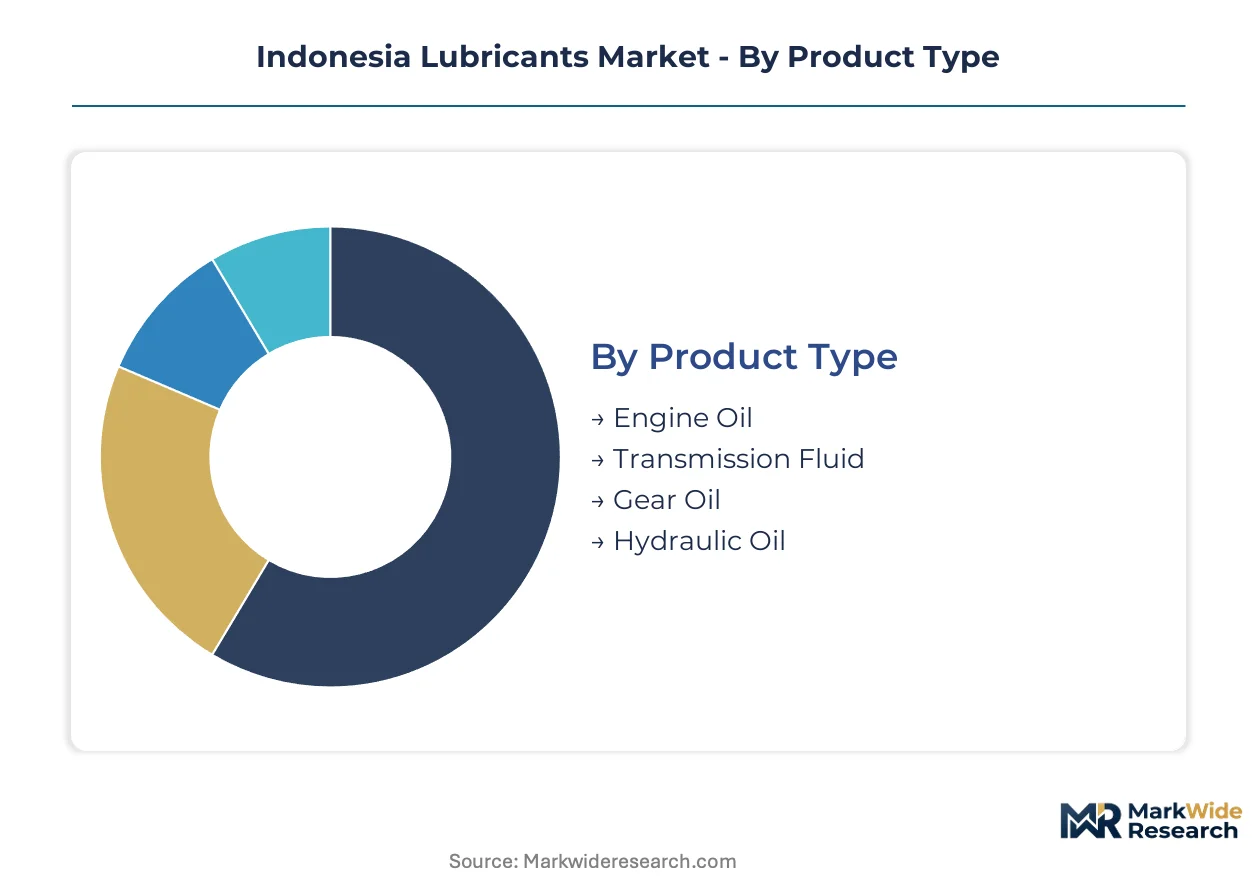
Segmentation in Indonesia's lubricants market reveals how margin pools shift between commodity volume plays and technical premium positions. Understanding these splits exposes where integrated refiners extract captive value and where independent blenders face compression.
Product Type:
Margins concentrate in formulations requiring frequent drain intervals and OEM warranty compliance, while commodity hydraulic volumes compete on logistics efficiency.
- Engine Oil:Formulated mixtures of base oils and detergent-dispersant additives meeting SAE viscosity grades and API service categories. Demand concentrates in Jakarta's logistics corridor and Surabaya's manufacturing zone as fleet operators extend drain intervals to reduce downtime. OEM fill programs and Euro 5-equivalent emissions compliance drive reformulation toward low-SAPS synthetic grades.
- Hydraulic Oil:Anti-wear fluids with zinc-based additive packages engineered for high-pressure pump circulation systems. Palm oil processing plants in Sumatra and Kalimantan account for concentrated offtake as crushing capacity expands. ISO viscosity grade standardization limits differentiation, compressing margins toward bulk supply contracts.
- Gear Oil:Extreme-pressure lubricants with sulfur-phosphorus additive chemistry for enclosed gearboxes. Mining equipment fleets in Sulawesi and Papua specify premium grades for open-pit haul trucks.
- Transmission Fluid:Friction-modified formulations for automatic and manual gearbox applications. Aftermarket channels in Java's urban centers dominate distribution.
The dominant share belongs to Engine Oil, while Hydraulic Oil is closing the gap fastest.
Application:
Application splits trace Indonesia's economic structure—mining and agriculture machinery against passenger vehicle parc expansion.
- Automotive:Passenger car and commercial vehicle lubricant demand spanning engine, transmission, and axle applications. Java's vehicle density around Jakarta, Bandung, and Surabaya generates the majority of aftermarket volume. SNI certification mandates filter low-grade imports, elevating reformulation standards for domestic blenders.
- Industrial Machinery:Factory equipment, construction machinery, and material handling systems requiring circulating oils and greases. Batam's manufacturing zone and Cikarang's industrial estates concentrate procurement authority among technical maintenance teams.
- Marine:Two-stroke and four-stroke engine oils for inter-island cargo vessels and fishing fleets. Eastern Indonesia ports face supply gaps due to blending capacity concentration in Java.
- Aviation:Turbine oils and piston engine lubricants meeting strict OEM specifications. Limited domestic production forces reliance on imported certified products.
Automotive commands the largest volume position, with Industrial Machinery expanding most quickly on infrastructure investment.
End User:
Customer type determines contract structure—lifecycle service bundling versus spot procurement through distributor networks.
- Fleet Operators:Logistics, mining, and plantation companies with centralized technical procurement and oil analysis programs. These buyers concentrate purchasing power through multi-year supply agreements covering Java's manufacturing belt. Lifecycle contracting now bundles lubricant supply with drain interval management, shifting profit pools from product margin to service attachment.
- OEMs:Vehicle and equipment manufacturers specifying factory-fill lubricants for warranty compliance. Domestic assembly plants in Bekasi and Karawang mandate SNI-certified products for local content requirements.
- Aftermarket Providers:Independent workshops and dealer networks serving retail consumers. Price sensitivity in this channel limits synthetic penetration despite technical benefits.
- Retail Consumers:Individual vehicle owners purchasing through service stations and auto parts retailers. Brand recognition and packaging visibility drive selection criteria.
Fleet Operators capture the deepest profit pool through technical service integration, while OEMs are gaining contractual leverage fastest via fill-program specifications.
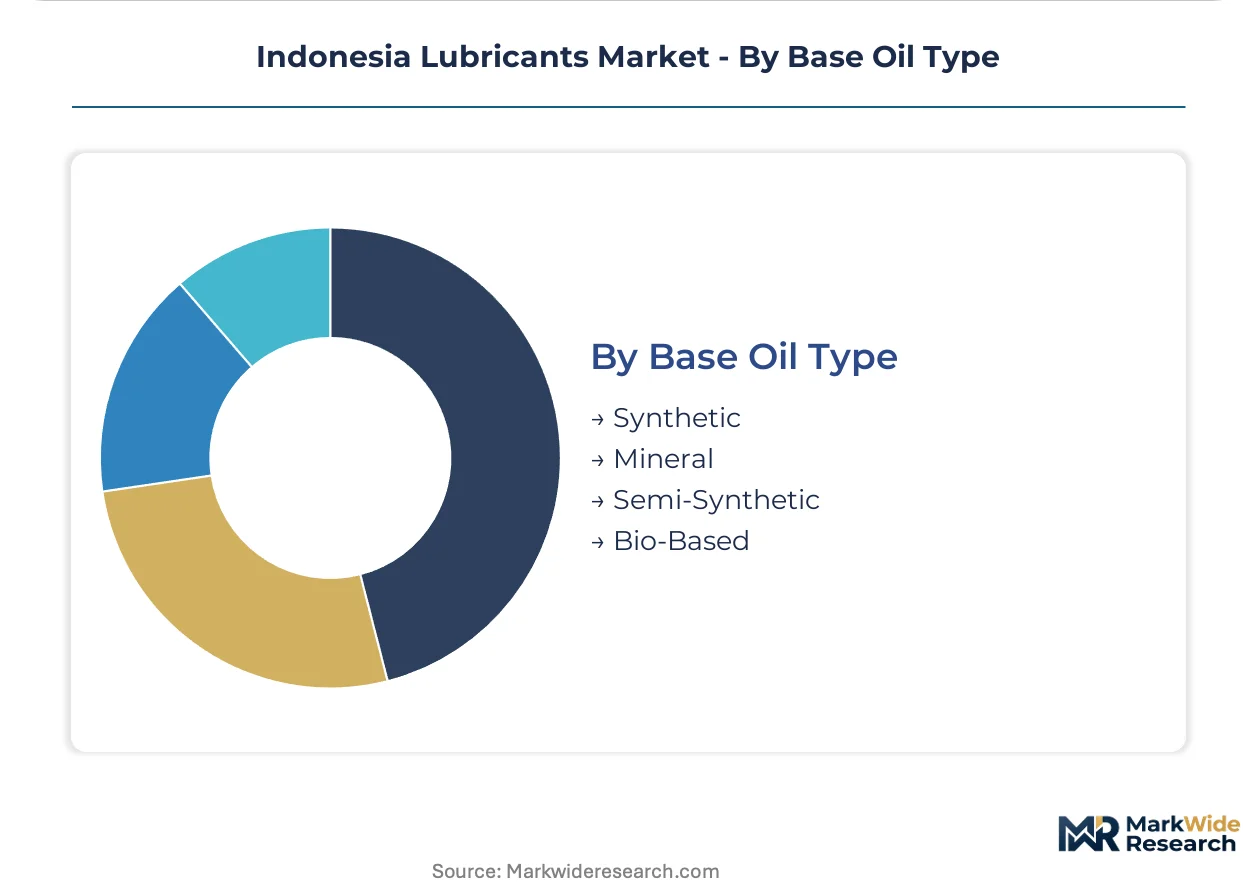
Base Oil Type:
Base oil selection separates integrated refiners with captive Group II supply from import-dependent blenders exposed to currency and freight volatility.
- Synthetic:Group III, PAO, and ester base stocks engineered for thermal stability and low-temperature fluidity. OEMs specify these grades for fuel economy compliance in Euro 5-equivalent engines. Mining contractors in Kalimantan and fleet operators in Surabaya increasingly demand 5W-30 and 10W-40 formulations despite 40-60% cost premiums over mineral equivalents.
- Mineral:Group I and Group II solvent-refined or hydrocracked base stocks derived from crude oil. PT Pertamina Lubricants leverages domestic Group II production for cost advantage in high-volume segments. Independent blenders without captive supply face margin compression from Singapore and South Korean import dependency.
- Semi-Synthetic:Blends combining mineral and synthetic base stocks for intermediate performance positioning. This category serves price-sensitive buyers seeking upgrade from conventional grades.
- Bio-Based:Vegetable oil-derived lubricants with biodegradability advantages for environmentally sensitive applications. Limited scale and feedstock availability constrain penetration in Indonesia's market.
Mineral base oils retain volume leadership, though Synthetic grades are climbing the fastest on OEM specification shifts and emissions regulation alignment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Indonesia's archipelago. Fleet operators in Java absorb premium synthetic pricing for uptime guarantees, while independent workshops in outer islands remain locked to mineral-grade spot markets. This divergence shapes distribution investment and blending capacity location.
Java
Jakarta's industrial corridor and Surabaya's manufacturing zone generate the majority of lubricant offtake. The Ministry of Industry's domestic content requirements redirect state-owned enterprise procurement toward locally blended products. Cikarang's industrial estates concentrate technical maintenance teams with centralized oil analysis programs.
Sumatra
Palm oil processing plants in Riau and North Sumatra drive hydraulic fluid and gear oil demand as crushing capacity expands. SNI certification mandates enforced by Indonesia's national standardization body filter substandard imports from regional trading partners. Medan's logistics hub serves as the primary distribution node for plantation equipment servicing.
Kalimantan
Coal and nickel mining operations in East Kalimantan specify premium heavy-duty diesel engine oils for open-pit haul truck fleets. The country's emissions regulations for diesel machinery redirect formulation investment toward low-SAPS long-drain products. Balikpapan's port infrastructure anchors bulk lubricant import and satellite blending for remote mine sites.
Sulawesi
Copper and nickel mining in Central Sulawesi extends equipment uptime requirements, expanding synthetic lubricant penetration despite cost premiums. National standardization body enforcement of BIS-equivalent SNI standards elevates reformulation toward higher-performance base stocks. Makassar's harbor zone lacks dedicated blending presence, creating logistics gaps for eastern supply routes.
Papua
Remote mining operations in Papua face the highest delivered lubricant costs due to import dependency and limited re-refining infrastructure. The Ministry of Industry's domestic content requirements shape procurement for state-backed resource projects. Sorong's emerging port zone represents potential first-mover territory for bulk import and satellite distribution.
Indonesia Lubricants Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Indonesia's lubricants market. PT Pertamina Lubricants leverages captive Group II base oil streams from domestic refining, while multinational subsidiaries compete through premium synthetic formulations and technical service bundling. Two strategic archetypes dominate: integrated refiners with backward control over base stock supply, and formulation specialists targeting OEM fill programs and lifecycle contracts. Competitive moves concentrate on SNI certification speed and eastern logistics network expansion.
Among state-linked integrated players, PT Pertamina Lubricants anchors the domestic refiner archetype with captive base oil access. Shell Indonesia and ExxonMobil Indonesia occupy positions within the multinational premium tier, representing formulation specialists that compete through OEM relationships and mining sector anchoring. These three exemplify how supply control and technical service integration separate margin leaders from price-pressured independents.
| Leading Market Players |
|---|
| PT Pertamina Lubricants |
| Shell Indonesia |
| ExxonMobil Indonesia |
| Chevron Lubricants Indonesia |
| TotalEnergies Lubricants Indonesia |
| PT Wiraswasta Gemilang Indonesia |
| BP PLC (Castrol) |
| FUCHS |
| PETRONAS Lubricants International |
| Others |
Value Chain & Pricing Dynamics
SNI certification mandates enforced by Indonesia's national standardization body gate both supply qualification and price differentiation simultaneously, filtering substandard imports while creating tiered value capture for compliant blenders. Fleet operators in Java absorb premium synthetic pricing for uptime guarantees, while independent workshops in outer islands remain locked to mineral-grade spot markets.
Pricing Analysis
Lifecycle service contracts now drive lifetime value, displacing transactional product sales as the dominant revenue model. Pricing stratifies across premium synthetic grades for OEM fill programs, standard Group II formulations for fleet operators, and economy mineral blends for independent aftermarket channels. Cost compression in the economy tier is intensifying because import-dependent blenders face currency and freight volatility without captive base oil supply. Fleet operators demonstrate the lowest price sensitivity due to downtime cost exposure, while retail consumers through independent workshops exhibit the highest.
Supply Chain Analysis
Inventory lead times for Group II base oils extend 4-6 weeks for Java-based blenders sourcing from Singapore and South Korean refiners, creating working capital intensity that favors integrated players. Supply concentrates in Singapore, South Korea, and domestic Indonesian refining capacity at Cilacap and Balikpapan. Raw material dependencies rest on Group II/III base oil streams, zinc-based anti-wear additives, and sulfur-phosphorus extreme-pressure packages. Single-source vulnerability runs through Singapore's export terminals for premium base stock grades. Distribution runs through bulk terminal imports, satellite blending facilities, and technical service teams embedded with fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's lubricants market rewards players who control scarce formulation chemistry capabilities and captive base oil supply, while punishing import-dependent blenders exposed to certification bottlenecks and currency volatility. The talent pipeline for lubricant-specific technical roles remains constrained, forcing recruitment from regional neighbors.
For Market Incumbents: Secure SNI certification speed advantages by pre-positioning product registrations ahead of regulatory tightening, while expanding captive Group II base oil capacity to absorb margin compression hitting import-dependent competitors. Defend against multinational premium positioning by embedding technical service teams within Jakarta's logistics corridor fleet accounts. For New Entrants and Emerging Players: Anchor in eastern Indonesia's logistics gaps—Makassar and Sorong harbor zones lack blending presence—by establishing bulk import terminals and satellite distribution for mining contractors in Sulawesi and Papua. Target first-mover positioning in lifecycle contracting for mid-size fleet operators seeking alternatives to incumbent technical service bundles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-optimized lubricant divisions lacking SNI certification infrastructure or eastern logistics networks. Long-term viability hinges on backward integration into base oil supply and formulation chemistry capabilities. Watch for SNI testing laboratory capacity expansion as an inflection signal for new product registration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive Group II streams at Cilacap insulate PT Pertamina Lubricants from Singapore import volatility. |
| SNI Certification Pre-Positioning | Accelerated product registration at Jakarta's accredited laboratories blocks competitor shelf-space expansion. |
| Eastern Logistics Network Buildout | Makassar bulk terminal investment captures mining contractor demand in Central Sulawesi copper operations. |
| Lifecycle Service Contracting | Drain interval management bundling shifts profit pools from product margin to technical attachment revenue. |
| Long-Drain Interval Formulation Development | Low-SAPS synthetic grades meeting Euro 5-equivalent standards open premium positioning in Jakarta's fleet segment. |
Study Parameters
Operator-level perspectives from fleet maintenance directors, mining procurement managers, palm oil processing plant engineers, lubricant blending plant managers, and aftermarket distributor owners anchored the qualitative base for this study. Primary interviews combined with secondary validation from BIS-equivalent SNI standard documentation, Ministry of Industry domestic content requirement circulars, base oil trade flow data from Indonesian customs records, and SEC filings from multinational lubricant parents. Bottom-up volume modeling across end-use segments triangulated against top-down macroeconomic indicators for the Indonesian mining, agriculture, and logistics sectors.
Sensitivity analysis tested forecast outputs against alternative scenarios for base oil import cost trajectories, SNI certification enforcement intensity, and mining fleet expansion rates. Segmentation dimensions modeled include product type, application sector, end-user contract structure, base oil technology tier, and regional demand cluster. CAGRs were derived from trend extrapolation of historical offtake patterns adjusted for structural shifts in OEM specification and emissions regulation alignment. Industry-specific inputs incorporated equipment uptime requirements for open-pit mining operations and palm oil crushing capacity utilization rates.
Material uncertainties—regulatory enforcement variability, currency volatility on base oil imports, and mining project approval timelines—sit outside the modeled envelope. Forecasts reflect assumptions about SNI laboratory capacity expansion and domestic refining utilization rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Vietnam Lubricants Market
Lubricants
Global Finished Lubricant Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
Automotive Die Casting Lubricants Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Slideway Oil Market
Lubricants
Global Lubricant Anti Wear Agents Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Construction Lubricants Market
Lubricants
North America Automotive Lubricants Market
Lubricants
Global Aerospace Lubricant Market
Lubricants
Malaysia Lubricants Market
Lubricants
Cold Rolling Oils/Lubricants Market
Lubricants
Plastic Lubricants Market