
 Japan Lubricants Market | 2026-2036
Japan Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Lubricants Market Foresight
Asset-light leasing models for bulk lubricant storage and fluid management systems is rewriting competitive entry barriers across Japan. ENEOS Corporation leverages its captive refinery network to sustain margin control in synthetic base oil supply. Idemitsu Kosan Co. Ltd anchors its position through deep channel relationships with Japanese original equipment manufacturers. Shell plc competes via technology leadership in low-viscosity formulations tailored to domestic automotive specifications.
Lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear between mechanical surfaces operating under load; Japan's domestic specifications emphasize thermal stability indices above 220°C for high-performance industrial grades. The primary purpose spans protection of precision machinery in automated manufacturing and extension of vehicle powertrain service intervals. Engine Oil occupies the largest value pool given Japan's substantial automotive production and aftermarket service infrastructure, while Synthetic technology captures expanding share as OEM drain intervals lengthen and factory energy targets tighten. Bio-based formulations remain nascent but draw regulatory tailwinds from Japan's carbon neutrality commitments for industrial supply chains.
METI enforces energy-efficiency benchmarks that directly shape lubricant viscosity grade requirements in manufacturing equipment, while JIS standards govern minimum performance specifications for products sold into domestic transportation and industrial channels. The country's national environmental regulator imposes waste oil recovery mandates that constrain distribution economics and favor suppliers with closed-loop collection infrastructure. Stakeholders must monitor how Japan's evolving carbon accounting rules for Scope 3 emissions will reshape procurement criteria among keiretsu-affiliated manufacturers.
Market Dynamics
METI's tightening energy-efficiency mandates for industrial machinery are compressing lubricant viscosity requirements while extending drain intervals, forcing reformulation cycles across Japanese manufacturing corridors.
Growth Catalysts
- Synthetic base oil transition:OEM drain interval extensions in Japanese automotive assembly are pulling demand toward Group III and PAO formulations. Precision engineering clusters in Kanto require thermal stability indices above 220°C.
- METI efficiency benchmarks:Mandatory energy-consumption targets for factory equipment are disqualifying conventional mineral grades from new machinery procurement. Industrial end-users face compliance deadlines that accelerate technology turnover.
- Tokyo-Osaka fleet modernization:Commercial vehicle operators are consolidating lubricant specifications around low-viscosity synthetics to reduce fuel consumption. Urban freight density creates concentrated demand pockets for high-performance products.
Market Restraints
- Base oil import dependency:Japan's synthetic base stock production capacity remains insufficient for domestic formulation demand, exposing blenders to freight cost volatility from Singapore and South Korean supply nodes.
- JIS certification timelines:New product approvals require extended laboratory testing cycles that delay commercialization by 18-24 months. Formulators cannot accelerate market entry despite technical readiness.
- Waste oil recovery mandates:The national environmental regulator requires closed-loop collection infrastructure that favors incumbent suppliers with established reverse logistics networks. New entrants face capital barriers to compliance.
Strategic Opportunities
- Carbon accounting integration:Japan's evolving Scope 3 emission rules for keiretsu supply chains are creating procurement criteria that favor lubricants with verified lifecycle carbon footprints. Early certifiers capture preferred supplier status.
- Bio-based formulation development:Regulatory tailwinds from national carbon neutrality commitments are opening specification windows for renewable feedstock alternatives in industrial applications. Technical performance gaps are narrowing.
- Fluid management service models:Asset-light leasing structures for bulk storage and condition monitoring systems are penetrating Osaka manufacturing zones. Equipment vendors bundle lubricant supply with predictive maintenance contracts.
Industry Challenges
- Additive chemistry expertise scarcity:Formulation chemists with deep knowledge of friction modifier synergies for Japanese OEM specifications command premium compensation. Talent pipelines from domestic universities remain thin.
- Legacy equipment compatibility:Extended machinery lifecycles in Japanese metalworking sectors create specification fragmentation. Formulators must maintain parallel product lines for incompatible seal materials and metallurgy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Lubricants Market |
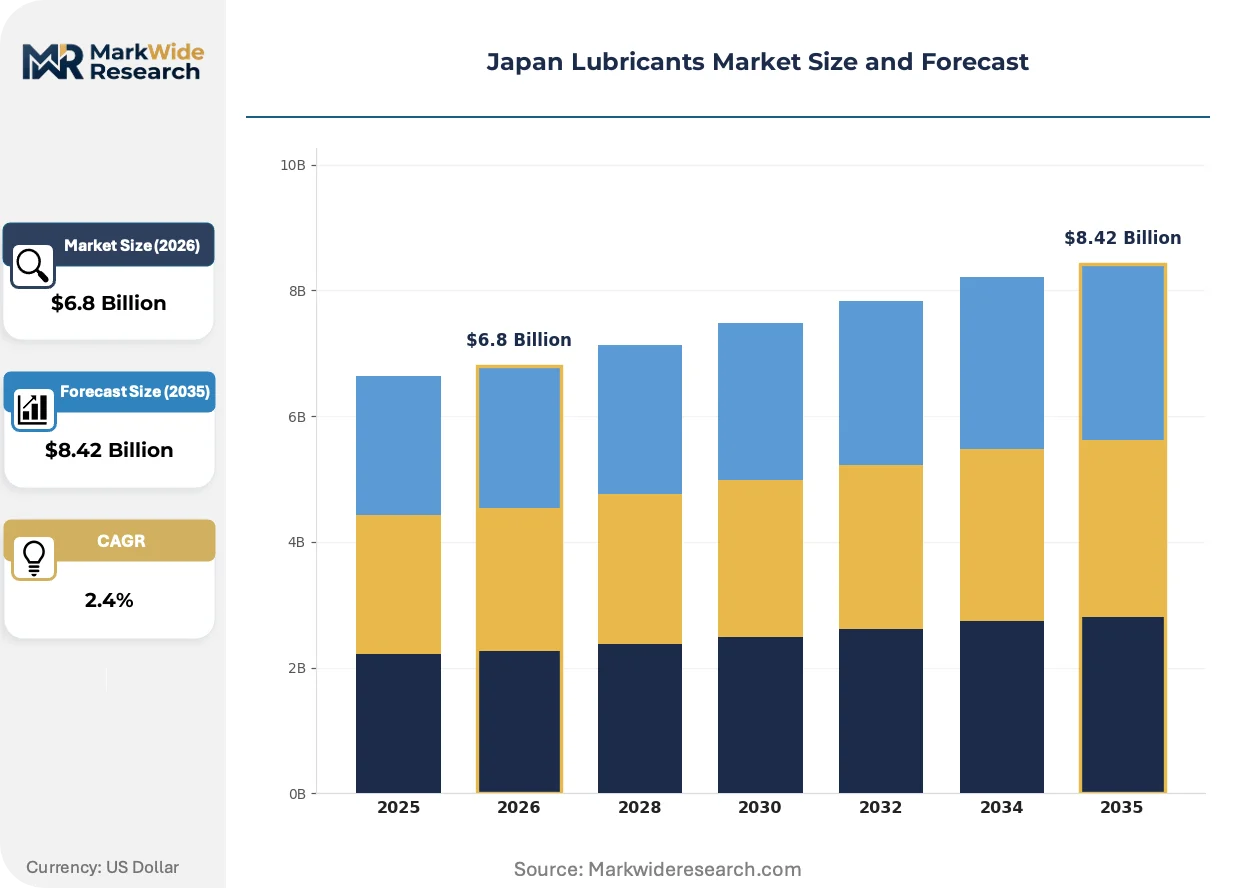
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Fluid, Grease, Transmission Fluid End User: Automotive, Industrial, Marine, Aerospace Application: Manufacturing, Transportation, Energy, Construction Technology: Mineral-based, Synthetic, Bio-based, Semi-synthetic |
| Companies Covered | ExxonMobil Corporation, FUCHS, ENEOS Corporation, Japan Sun Oil Company Ltd, TotalEnergies SE, Idemitsu Kosan Co. Ltd, Shell plc, MITASU OIL CORPORATION, Cosmo Energy Holdings Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Lubricants Market Shifts & Advancements
Reformulation priorities across Japanese lubricant channels are converging on thermal stability, extended drain intervals, and carbon footprint verification as OEM specifications and regulatory thresholds advance in lockstep.
Polyalphaolefin (PAO) synthetic base stocks are rendering obsolete conventional Group I mineral oils in high-temperature industrial gearbox applications. Japanese precision machinery manufacturers are specifying PAO for new equipment installations at accelerating rates. The technology shift is compressing margins for blenders without captive synthetic supply or long-term offtake agreements.
METI's 2023 revision to industrial energy-efficiency standards has tightened permissible viscosity grades for manufacturing equipment lubrication. Factory operators must now demonstrate measurable friction reduction to qualify for equipment subsidies. Automotive transmission plants in Aichi Prefecture are responding with accelerated trials of ultra-low-viscosity ATF formulations.
Keiretsu-affiliated manufacturers are consolidating lubricant procurement through central purchasing consortia that demand lifecycle carbon documentation. Tier-1 suppliers face Scope 3 reporting obligations that elevate preferred vendor status for certified low-carbon formulations. This concentration is most visible in Kanto automotive supply chains where Toyota and Honda tier networks dominate volume allocation.
Japan Lubricants Market Segmentation
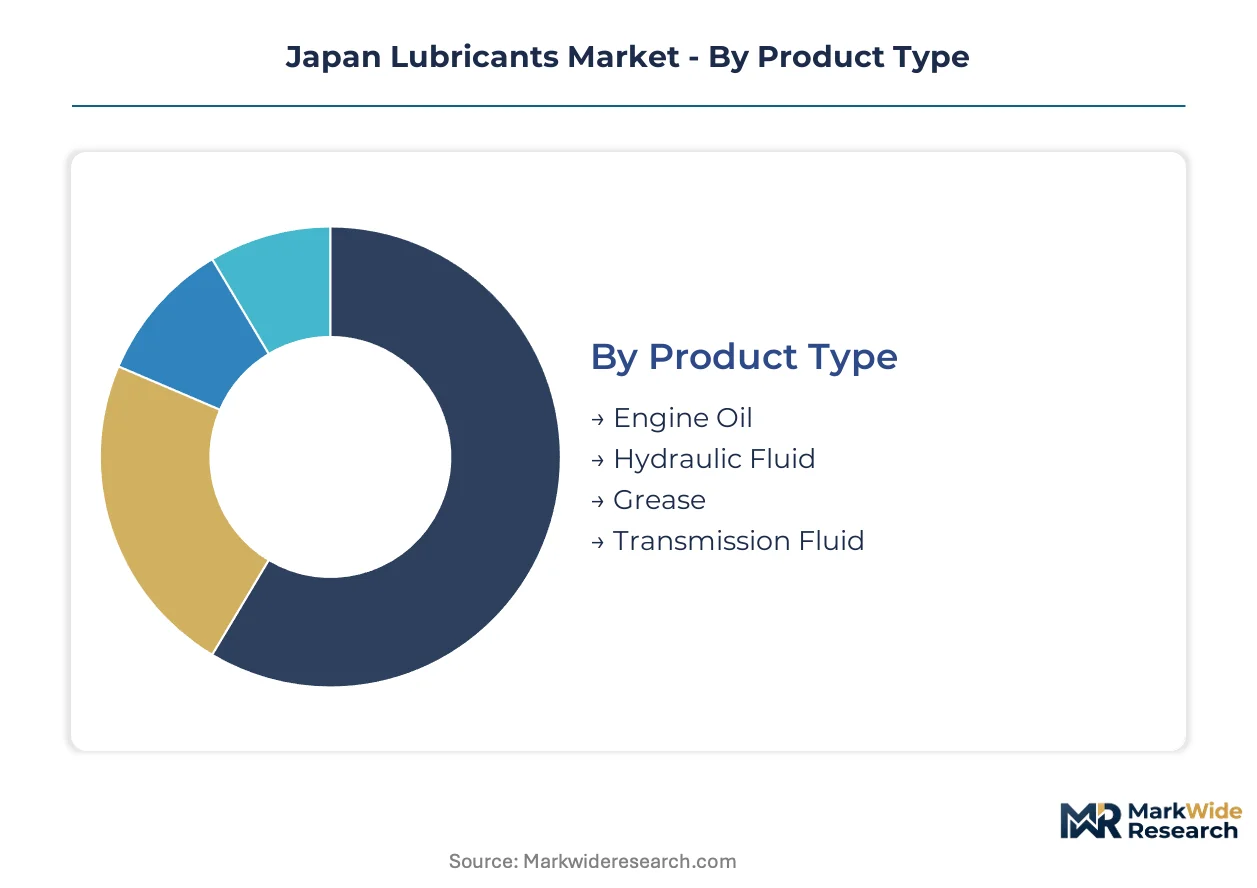
Segmentation in Japan's lubricants market reveals distinct procurement rhythms across product categories and end-use channels. Understanding these turnover patterns enables suppliers to align inventory and technical service resources with actual consumption velocity.
Product Type:
Cycle times vary dramatically by product type, with automotive fluids turning over fastest and industrial greases exhibiting the longest replacement intervals. This divergence shapes working capital requirements and technical support intensity across supplier portfolios.
- Engine Oil:Formulated from Group II/III base stocks with additive packages targeting oxidation resistance and deposit control. Automotive assembly plants in Aichi and aftermarket service networks in Tokyo-Osaka corridors drive volume concentration, with METI efficiency standards accelerating synthetic grade penetration. Engine Oil dominates installed base. Transmission Fluid is where expansion concentrates.
- Hydraulic Fluid:Precision-engineered for power transmission in factory automation systems, with viscosity indices optimized for temperature stability across Japanese manufacturing climates. Kanto precision engineering clusters specify high-performance formulations for CNC machinery and robotic systems, creating concentrated demand pockets with stringent thermal stability requirements above 220°C.
- Grease:Thickened lubricant systems for bearings and slow-moving components in heavy industrial equipment. Steel mills and shipyards in Chugoku region represent primary consumption nodes.
- Transmission Fluid:Specialized friction-modified formulations for automatic and continuously variable transmissions. Japanese OEM transmission plants are validating ultra-low-viscosity grades for next-generation fuel efficiency targets.
Engine Oil dominates installed base. Transmission Fluid is where expansion concentrates.
End User:
Cost tier stratification separates premium-specification automotive and aerospace demand from price-sensitive industrial bulk procurement. This tiering determines formulation complexity and margin structure across supplier customer portfolios.
- Automotive:OEM factory-fill specifications and dealer network aftermarket service dominate value capture. Toyota and Honda tier-1 suppliers in Kanto automotive corridors consolidate procurement through central purchasing consortia demanding lifecycle carbon documentation.
- Industrial:Factory equipment lubrication spanning metalworking, plastics processing, and automated assembly systems. METI energy-efficiency mandates are disqualifying conventional mineral grades from new machinery procurement, forcing technology turnover in Osaka manufacturing zones.
- Marine:Vessel engine and deck machinery lubrication for coastal shipping and international freight operators. Yokohama and Kobe port clusters anchor domestic demand concentration.
- Aerospace:Jet engine oils and hydraulic fluids meeting JIS and international aviation specifications. Narita and Haneda maintenance facilities represent specialized demand nodes with extreme performance requirements.
Automotive commands premium pricing tiers. Industrial generates volume scale.
Application:
Geographic concentration of end-use activity creates distinct supply chain configurations across Japan's industrial map. Application-specific formulation requirements determine technical service intensity and inventory positioning strategies.
- Manufacturing:Precision machinery lubrication in automated production environments. Aichi automotive transmission plants and Kanto electronics assembly operations specify thermal stability indices above 220°C for high-temperature gearbox applications.
- Transportation:Fleet lubrication for commercial vehicles and passenger car service intervals. Tokyo-Osaka freight corridors drive concentrated demand for low-viscosity synthetics as urban fleet operators consolidate specifications around fuel-reduction targets.
- Energy:Power generation equipment and renewable energy system lubrication. Thermal plants and offshore wind installations in Tohoku region create specialized high-load formulation requirements.
- Construction:Heavy equipment lubrication for infrastructure development projects. Tokyo metropolitan area civil engineering activity sustains seasonal demand patterns.
Manufacturing absorbs the most technical service resources. Transportation offers the steepest expansion trajectory.
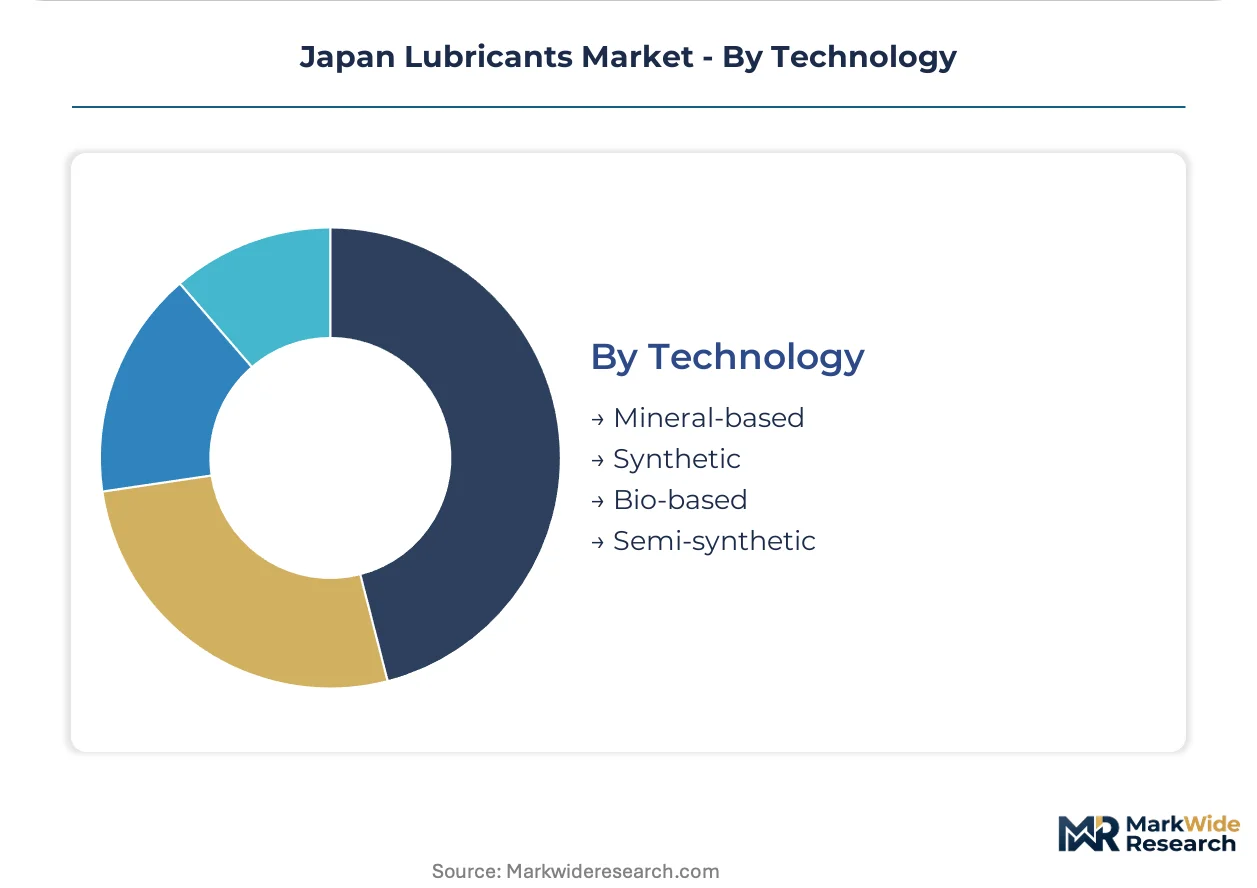
Technology:
Maturity gradients separate established mineral formulations from emerging synthetic and bio-based alternatives. This maturity spectrum determines R&D allocation and certification timeline exposure across supplier technology roadmaps.
- Mineral-based:Conventional Group I/II base stock formulations with established JIS certification pathways. Legacy equipment compatibility requirements in Japanese metalworking sectors sustain parallel product lines despite METI efficiency mandates compressing new equipment specifications.
- Synthetic:Group III and PAO base stocks engineered for extended drain intervals and thermal stability. OEM drain interval extensions in Japanese automotive assembly are pulling demand toward synthetic formulations, with precision engineering clusters in Kanto specifying PAO for new equipment installations at accelerating rates.
- Bio-based:Renewable feedstock alternatives derived from plant oils and synthetic esters. Regulatory tailwinds from Japan's carbon neutrality commitments are opening specification windows for industrial applications as technical performance gaps narrow.
- Semi-synthetic:Blended formulations combining mineral and synthetic base stocks for intermediate performance positioning. Price-sensitive industrial segments in regional manufacturing zones favor this technology for equipment upgrade transitions.
Mineral-based retains volume leadership. Synthetic technology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's lubricants trade balance tilts toward import dependency for synthetic base stocks, with domestic blending capacity concentrated in coastal industrial zones. The country's regional production clusters reflect automotive and precision manufacturing density rather than petroleum feedstock availability.
Kanto/Tokyo
Tokyo metropolitan manufacturing corridors absorb the highest per-capita lubricant consumption for precision engineering and electronics assembly. METI enforces energy-efficiency benchmarks that compress viscosity requirements for automated production equipment. Aichi automotive transmission plants and Kanto electronics clusters specify thermal stability indices above 220°C for high-temperature gearbox applications.
Kansai/Osaka
Osaka manufacturing zones generate concentrated demand for hydraulic fluids in factory automation systems and metalworking operations. The national environmental regulator imposes waste oil recovery mandates that favor suppliers with closed-loop collection infrastructure. Urban freight density across the Osaka-Kobe corridor sustains commercial fleet procurement of low-viscosity synthetics.
Chubu/Nagoya
Nagoya anchors Japan's automotive powertrain production, driving factory-fill specifications and tier-1 supplier consolidation. JIS standards govern minimum performance specifications for products sold into domestic transportation channels. Toyota and Honda tier networks dominate volume allocation through central purchasing consortia demanding lifecycle carbon documentation.
Kyushu
Kyushu hosts steel mills and shipyards that represent primary consumption nodes for industrial greases and heavy equipment lubricants. METI efficiency mandates are disqualifying conventional mineral grades from new machinery procurement in regional manufacturing zones. Legacy equipment compatibility requirements create specification fragmentation for formulators serving extended machinery lifecycles.
Tohoku
Tohoku's thermal power generation and emerging offshore wind installations create specialized high-load formulation requirements for energy sector lubrication. Bio-based formulations draw regulatory tailwinds from Japan's carbon neutrality commitments for industrial supply chains. Precision machinery lubrication demand concentrates in automated production environments with stringent thermal stability requirements.
Japan Lubricants Market Competitive Landscape
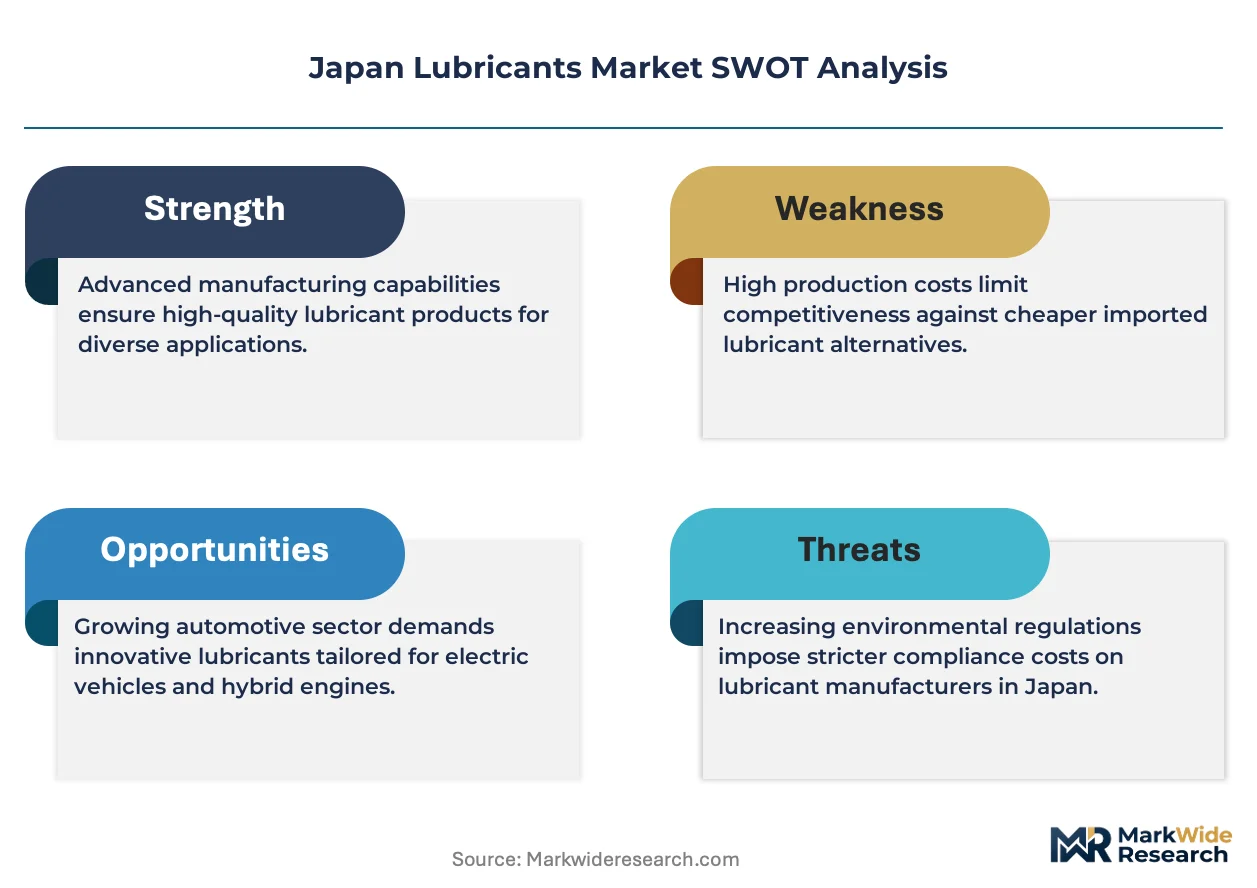
On the supply side, the industry is consolidated around integrated petroleum refiners and specialized lubricant blenders with captive distribution networks. Domestic incumbents leverage refinery integration and keiretsu channel relationships to sustain margin control. Two strategic archetypes dominate: vertically integrated energy majors with synthetic base oil production, and independent blenders competing through technical service intensity. Capacity expansion and portfolio diversification toward synthetic grades represent the primary competitive vectors.
Within the integrated refiner tier, ENEOS Corporation and Idemitsu Kosan Co. Ltd exemplify supply-side consolidation through captive base oil production and deep OEM relationships. Shell plc anchors the multinational technology-leader archetype with low-viscosity formulation capabilities. These three entities represent the competitive core around which independent blenders and import-dependent specialists position for specification windows.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| FUCHS |
| ENEOS Corporation |
| Japan Sun Oil Company Ltd |
| TotalEnergies SE |
| Idemitsu Kosan Co. Ltd |
| Shell plc |
| MITASU OIL CORPORATION |
| Cosmo Energy Holdings Co., Ltd. |
| Others |
Supply & Pricing Matrix
Kanto manufacturing corridors concentrate Japan's synthetic base oil blending capacity, with Yokohama and Chiba industrial zones anchoring domestic supply. This geographic concentration grants incumbent refiners leverage over formulation pricing, particularly for Group III and PAO grades serving precision engineering clusters with thermal stability requirements above 220°C. METI's energy-efficiency mandates compress viscosity specifications while extending drain intervals, forcing buyers to absorb premium-grade costs or risk machinery disqualification from factory equipment subsidies.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on JIS certification grade and volume scale, with keiretsu-affiliated manufacturers commanding preferential contract terms through central purchasing consortia. Cost compression in the economy tier intensifies as semi-synthetic formulations displace conventional mineral oils under METI compliance deadlines. Fleet operators in Tokyo-Osaka corridors exhibit highest price sensitivity, while aerospace maintenance facilities at Narita and Haneda accept substantial premiums for validated thermal stability indices.
Supply Chain Analysis
Blending capacity concentrates at ENEOS and Idemitsu captive facilities, with independent formulators relying on Singapore and South Korean supply nodes for synthetic base stock imports. Raw material dependencies center on Group III hydrocracked feeds, polyalphaolefin monomers, and friction modifier additive packages from specialized chemical producers. Single-source vulnerability runs through the Singapore-Japan shipping lane for high-viscosity PAO grades. Distribution runs through keiretsu-affiliated industrial distributors with embedded technical service capabilities, locking out direct supplier relationships for non-affiliated blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's lubricants market sits in a cyclical recovery phase as automotive production normalization and industrial capital expenditure rebounds drive formulation demand. METI's phased efficiency mandate implementation creates predictable replacement cycles that favor suppliers with certified synthetic portfolios.
For Market Incumbents: Pre-empt displacement by bio-based alternatives through accelerated lifecycle carbon certification for existing synthetic formulations. Secure backward integration into Group III base oil production to offset freight cost volatility from Singapore supply nodes. Deepen channel control via fluid management service contracts bundling predictive maintenance with lubricant supply in Osaka manufacturing zones.
For New Entrants and Emerging Players: Pursue specification windows in Tohoku energy sector applications where offshore wind installations lack established supplier relationships. Target bio-based industrial greases for steel mills and shipyards in Kyushu, where regulatory tailwinds from carbon neutrality commitments outpace incumbent formulation pipelines. Lead with verified Scope 3 carbon documentation to capture keiretsu procurement committee evaluations.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because additive chemistry expertise scarcity and JIS certification timeline barriers protect incumbent returns. Acquisition target archetype: independent blenders with established reverse logistics infrastructure for waste oil recovery compliance. Monitor quarterly JIS certification approval volumes as inflection indicator for new product commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Base Oil Production | Captive Group III supply shields ENEOS and Idemitsu from Singapore freight volatility. |
| Lifecycle Carbon Certification Program | Verified Scope 3 documentation captures preferred supplier status in keiretsu purchasing consortia. |
| Fluid Management Service Expansion | Asset-light leasing structures in Kanto penetrate predictive maintenance contract bundling. |
| Bio-based Formulation Development | Renewable feedstock alternatives open specification windows under carbon neutrality commitments. |
| Reverse Logistics Infrastructure Buildout | Closed-loop collection networks satisfy national environmental regulator waste oil mandates. |
Research Methodology
A standing panel of lubricant formulation chemists, METI policy officers, keiretsu procurement directors, and aftermarket service managers provided ongoing calibration across the study period. Primary interviews with Toyota and Honda tier-1 supplier technical staff, independent blender operations heads, and industrial maintenance directors in Aichi and Kanto regions were cross-validated against secondary sources including METI energy-efficiency standard filings, JIS certification databases, Japan Petrochemical Industry Association trade statistics, and customs import records for synthetic base stocks. Bottom-up consumption estimates from end-use segmentation were triangulated against top-down refinery production disclosures.
Scenario bracketing around METI mandate implementation pace and automotive production recovery trajectories shaped the analytical framework. Segmentation dimensions modeled include product type, technology tier, end-use industry, and regional manufacturing cluster density. CAGRs were derived from elasticity-adjusted consumption projections across the projection horizon, with specific inputs from OEM drain interval extension schedules and industrial machinery replacement cycles.
Macroeconomic conditions sit as an overlay; deviation in yen exchange rates, Singapore-Japan shipping costs, or automotive export demand would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and technology substitution rates. Quarterly review of JIS certification approval volumes, keiretsu procurement committee carbon documentation requirements, and synthetic base oil import customs data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Aerospace Lubricant Market
Lubricants
Iraq Lubricants Market
Lubricants
Marine Grease Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Neat Cutting Oil Market
Lubricants
Philippines Lubricants Market
Lubricants
Nigeria Lubricants Market
Lubricants
Technical Fluids Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Global Lubricants Market
Lubricants
Brazil Lubricants Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Hydro Lubricants Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Malaysia Lubricants Market
Lubricants
Global Finished Lubricant Market