
 Hydraulic Fluids and Process Oil Market | 2026-2036
Hydraulic Fluids and Process Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Fluids and Process Oil Market Outlook
The gap between premium synthetic formulations and commodity mineral oil blends is broadening as equipment OEMs tighten viscosity and thermal stability specifications. Shell plc leverages its integrated base oil supply chain to sustain cost advantages across both tiers. FUCHS Petrolub SE anchors its position through specialty lubricant expertise in high-pressure industrial hydraulics. ExxonMobil Corporation differentiates via advanced Group III+ base stock technology for extended drain intervals.
Hydraulic fluids and process oils comprise formulated lubricants engineered with base stocks—mineral, synthetic, or bio-derived—combined with additive packages delivering anti-wear, oxidation stability, and foam suppression within viscosity grades typically spanning ISO VG 32 to 100. Process oils function as extender oils, plasticizers, and carriers in rubber, polymer, and textile manufacturing. Synthetic fluids command expanding share in aerospace applications where fire resistance and thermal oxidative stability prove critical. Mineral oil-based fluids retain dominance in agricultural machinery due to cost sensitivity and established service infrastructure. The manufacturing sector end-user segment concentrates margin pools through long-term supply contracts and technical service bundling.
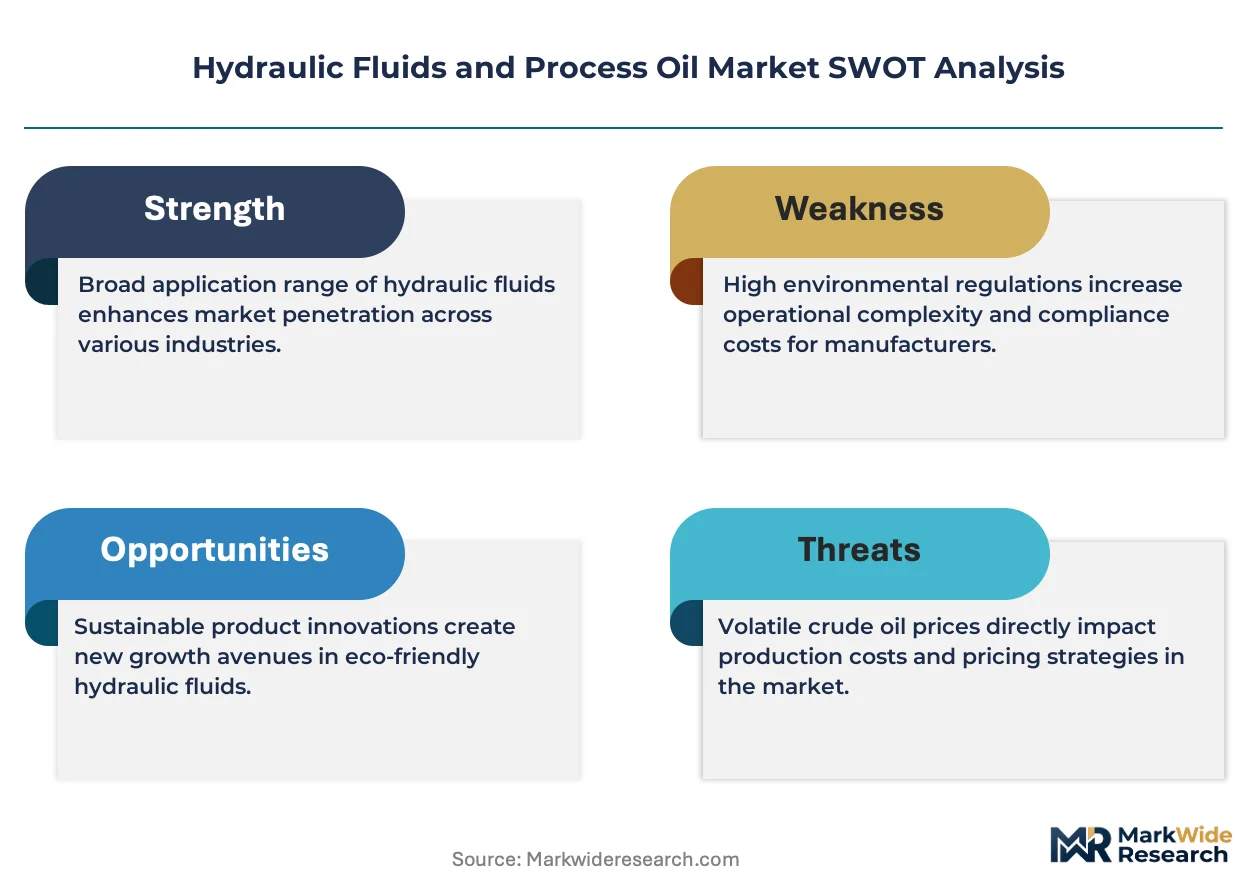
EPA regulations in the United States mandate spill prevention and countermeasure planning for hydraulic oil storage, while REACH in Europe restricts certain additive chemistries and drives substitution toward bio-based alternatives. China's MEE enforces stricter discharge standards for used oil handling, elevating demand for reclaimable synthetic formulations. Stakeholders must monitor evolving substance restrictions across multiple jurisdictions while calibrating product portfolios between performance premiums and regulatory compliance costs.
Market Dynamics
Equipment OEMs are tightening fluid specifications simultaneously with REACH-driven formulation bans, compressing margins for blenders caught between performance premiums and compliance retrofit costs.
Growth Catalysts
- Construction intensity:Infrastructure expansion across Indonesia and Vietnam is pulling ISO VG 68 and 100 grades into earthmoving equipment fleets at accelerating rates.
- REACH substitution mandates:ECHA restrictions on zinc dialkyldithiophosphate anti-wear additives are forcing rapid adoption of ashless alternatives in European industrial hydraulics.
- Synthetic ester technology:Fire-resistant formulations are penetrating underground mining and steel mill applications where mineral oil thermal failure risks dominate operational safety protocols.
Market Restraints
- Group III base oil supply concentration:Middle Eastern and Asian refinery expansions have not kept pace with synthetic fluid demand, creating input bottlenecks for premium blenders.
- Vegetable oil oxidation instability:Bio-based hydraulic fluids face technical ceiling at operating temperatures above 80°C, limiting deployment in high-load industrial presses.
- EPA spill prevention compliance:SPCC planning requirements for bulk storage impose capital burdens on agricultural distributors serving fragmented farm equipment bases.
Strategic Opportunities
- Reclaimable synthetic formulations:China's MEE discharge standards are elevating closed-loop fluid management services as a value-added revenue stream for industrial suppliers.
- Wind turbine drivetrain lubrication:Offshore installations require decade-long drain interval capabilities that mineral oils cannot satisfy, opening white space for PAO and polyol ester specialists.
- Direct-to-fleet digital channels:Construction equipment rental companies are bypassing traditional jobber networks through platform-based bulk procurement, compressing distributor margins while rewarding logistics-integrated blenders.
Industry Challenges
- Additive chemist scarcity:Formulation expertise in ashless anti-wear and biodegradable thickener systems resides with a shrinking cohort of specialists approaching retirement.
- OEM approval timeline compression:Extended drain interval certifications now require 10,000-hour field trials that delay product launches by 18-24 months against accelerating specification changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Fluids and Process Oil Market |
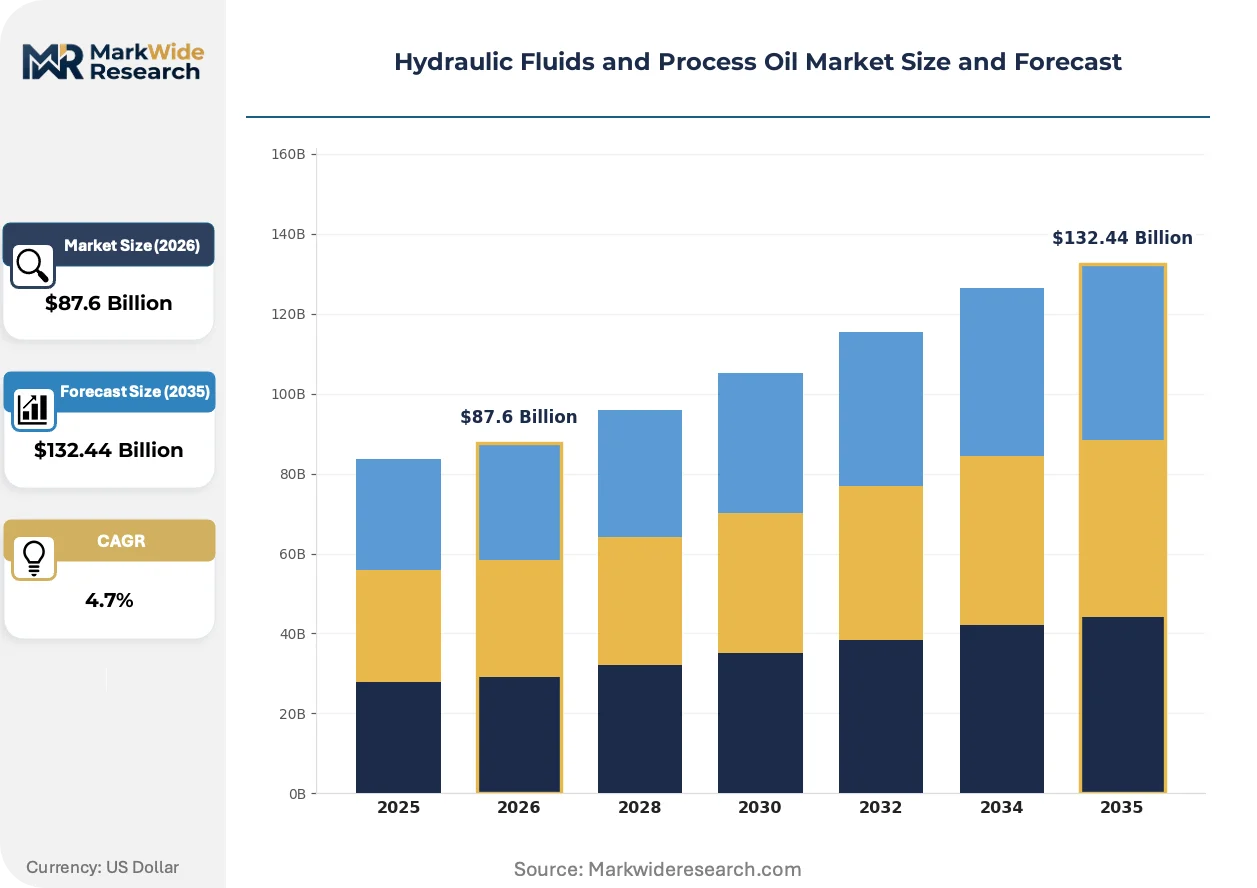
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $132.44 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Fluids, Mineral Oil-based Fluids, Water-based Fluids, Synthetic Fluids Application: Agricultural Machinery, Industrial Equipment, Automotive Systems, Aerospace Applications End User: Manufacturing Sector, Construction Industry, Transportation Services, Oil & Gas Sector Grade: High-performance Fluids, Standard Fluids, Specialty Fluids, Conventional Fluids |
| Companies Covered | BP p.l.c., FUCHS Petrolub SE, Shell plc, China Petrochemical Corporation (SINOPEC), Valvoline Inc., ExxonMobil Corporation, TotalEnergies SE, PetroChina Company Limited, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Fluids and Process Oil Market Strategic Shifts
Formulation chemistry, regulatory substance bans, and procurement digitization are converging to restructure how hydraulic fluids are specified, priced, and distributed across industrial value chains.
Polyalkylene glycol synthetic base stocks are absorbing market share in food-grade and fire-resistant applications where mineral oil thermal breakdown creates contamination risks. Food processing equipment manufacturers in Germany and the Netherlands are specifying PAG-based ISO VG 46 fluids for bakery and dairy hydraulic systems. This absorption is compressing demand for white mineral oil alternatives that require costly incidental food contact certifications.
REACH Annex XVII restrictions on medium-chain chlorinated paraffins are forcing reformulation of extreme-pressure additives in metalworking fluid extensions. Blenders serving European automotive stamping operations are substituting sulfur-phosphorus chemistries at 15-30% additive cost premiums. Metalforming shops in Poland and Czechia are absorbing these input shifts through longer fluid life claims rather than price pass-throughs.
Construction equipment end-users are consolidating procurement through integrated fleet management platforms that bundle fluid supply with telematics-based condition monitoring. Rental companies in Texas and Alberta are displacing traditional distributor relationships with direct mill contracts tied to hourly usage rates. This behavior shift is most visible in North American oilfield services, where pumper truck operators now specify fluids through platform-negotiated master service agreements rather than regional jobber selection.
Hydraulic Fluids and Process Oil Market Segmentation
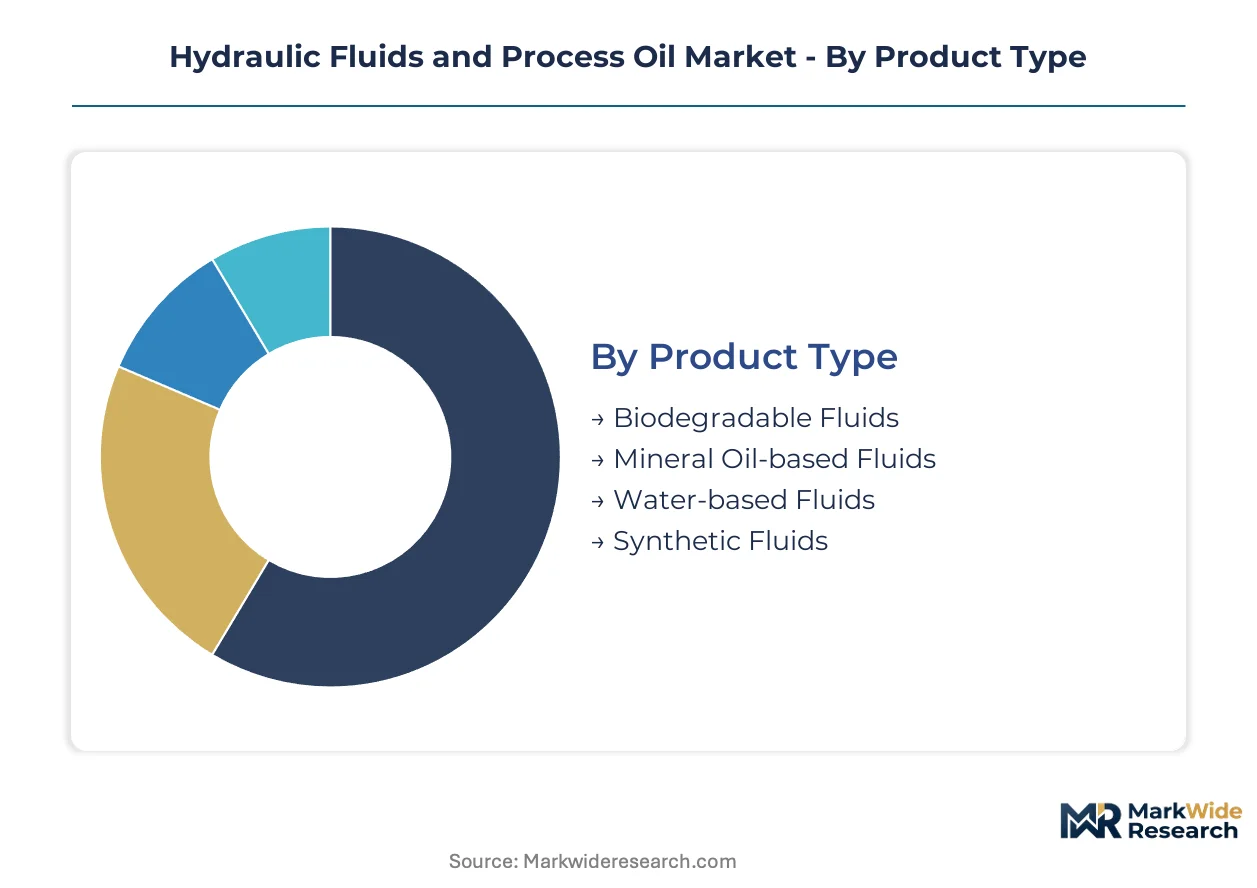
Segmentation in hydraulic fluids and process oils reveals divergent margin structures across base stock chemistry and equipment severity. Product type and application splits expose where formulation premiums command pricing power versus where mineral oil commoditization dominates procurement decisions.
Product Type:
Volume concentration sits with mineral oil formulations, while synthetic and biodegradable tiers capture expanding premium pools as equipment specifications tighten and discharge regulations multiply.
- Mineral Oil-based Fluids:Refined petroleum distillates blended with anti-wear and oxidation inhibitor packages dominate agricultural machinery fleets across India and Indonesia. Cost sensitivity in emerging market construction equipment sustains procurement volumes despite thermal stability limitations above 120°C operating temperatures.
- Synthetic Fluids:Polyalphaolefin, ester, and polyalkylene glycol base stocks deliver extended drain intervals and fire resistance for aerospace actuation systems and underground mining hydraulics. PAO formulations are penetrating wind turbine drivetrains in the North Sea and Baltic installations where decade-long service life eliminates mineral oil alternatives.
- Biodegradable Fluids:Vegetable oil and synthetic ester formulations satisfy EU ECHA mandates for environmentally acceptable lubricants in forestry, marine, and sensitive watershed construction. Oxidation instability above 80°C restricts deployment in high-load industrial presses.
- Water-based Fluids:Water-glycol and high-water-content emulsions provide fire resistance for steel mill continuous casting and die casting operations where mineral oil ignition risks trigger safety shutdowns.
Mature deployment sits with Mineral Oil-based Fluids. Newer deployment is concentrated in Biodegradable Fluids.
Application:
Equipment severity and duty cycle intensity segment demand between intermittent-use machinery and continuous-operation industrial systems.
- Industrial Equipment:High-pressure hydraulic presses, injection molding machines, and metal forming equipment in Germany and Japan specify ISO VG 46-68 synthetic formulations with ashless anti-wear additive packages. REACH-driven ZDDP substitution mandates are accelerating formulation turnover in European stamping and rolling mill operations.
- Construction Equipment:Excavators, bulldozers, and crane systems across Vietnam and Indonesia pull ISO VG 68 and 100 grades at accelerating rates as infrastructure investment intensifies. Fleet rental companies in Texas are consolidating procurement through platform-based bulk contracts tied to telematics-monitored usage rates.
- Agricultural Machinery:Tractors and harvester hydraulics retain mineral oil dominance due to established service infrastructure and cost sensitivity among fragmented farm equipment bases in the US Midwest and Punjab region.
- Automotive Systems:Power steering, brake, and suspension hydraulics specify low-viscosity Group III+ base stocks for cold-start performance in passenger vehicle assembly plants.
- Aerospace Applications:Aircraft flight control and landing gear systems mandate fire-resistant phosphate ester and polyol ester formulations certified to SAE AS1241 and MIL-PRF-5606 specifications.
Industrial Equipment absorbs the deepest formulation expertise. Construction Equipment is expanding most quickly as fleet digitization restructures procurement channels.
End User:
Contract structure and technical service intensity separate long-term supply relationships from spot procurement patterns.
- Manufacturing Sector:Automotive stamping plants and polymer processing facilities in Poland and Czechia negotiate multi-year fluid supply contracts bundling technical service, condition monitoring, and waste oil reclamation. REACH compliance retrofit costs are absorbed through extended drain interval claims rather than price pass-throughs.
- Construction Industry:Earthmoving and infrastructure equipment operators in Indonesia specify fluids through equipment OEM captive distribution or emerging direct-to-fleet digital platforms that displace traditional jobber networks.
- Oil & Gas Sector:Offshore platforms and hydraulic fracturing operations in Alberta and Texas require fire-resistant formulations for blowout preventer systems and high-pressure pumping equipment.
- Transportation Services:Rail and marine hydraulics specify biodegradable alternatives for sensitive corridor operations where spill liability exposure concentrates procurement decisions.
Long-term contract density peaks in Manufacturing Sector. Spot procurement flexibility dominates Construction Industry purchasing behavior.
Grade:
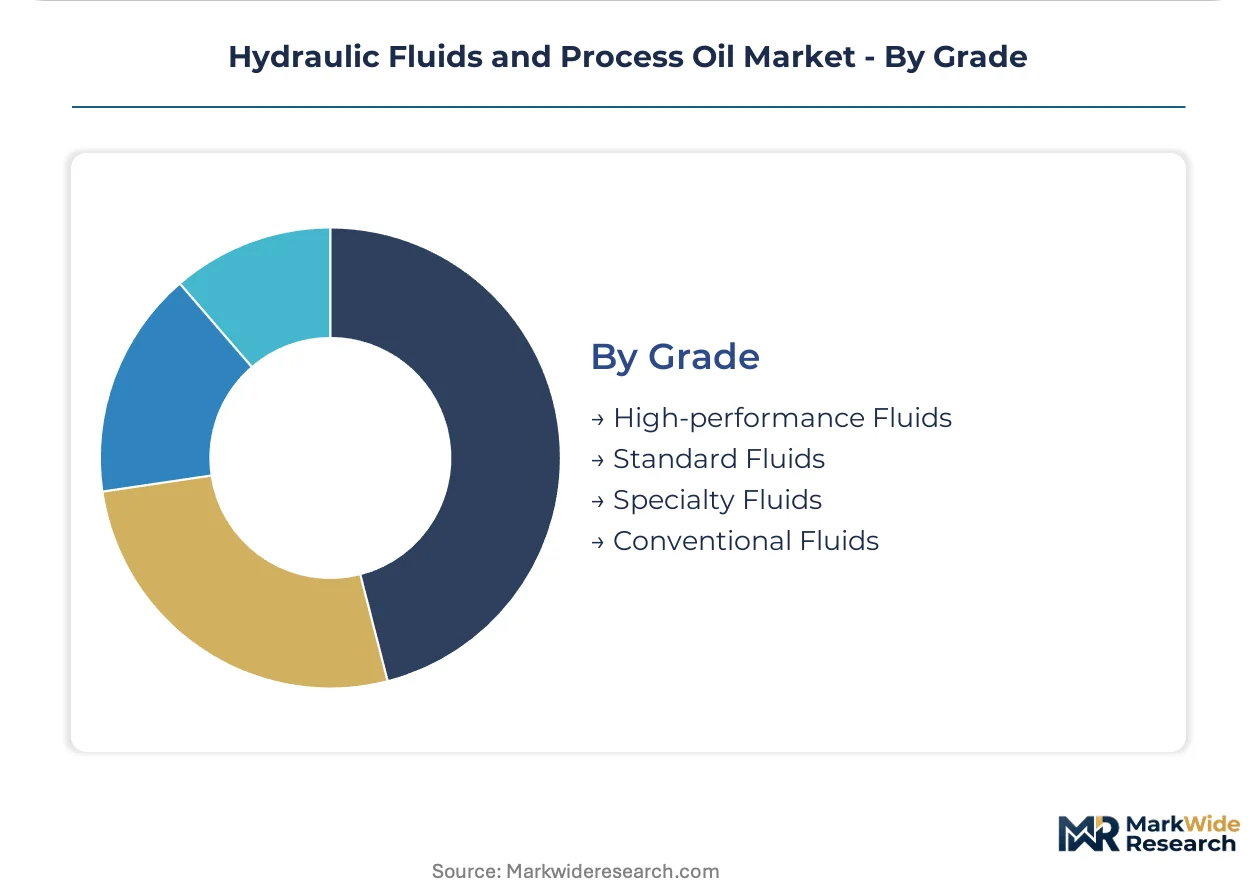
Performance certification tiers separate OEM-approved formulations from commodity blends in distributor channels.
- High-performance Fluids:Extended drain interval formulations with OEM approvals from Caterpillar, Komatsu, and Bosch Rexroth command 40-60% price premiums over standard grades. Field trial requirements spanning 10,000 operating hours create 18-24 month certification timelines that delay competitive entry.
- Specialty Fluids:Food-grade, fire-resistant, and aerospace-certified formulations serve narrow specification windows where regulatory compliance and safety certification override cost considerations. PAG-based food-grade ISO VG 46 fluids are displacing white mineral oil alternatives in German and Dutch dairy processing equipment.
- Standard Fluids:ISO VG 32-68 mineral oil blends without OEM approvals serve general industrial maintenance and aftermarket replacement demand through distributor and jobber channels.
- Conventional Fluids:Unadditized or minimally additized base stocks retain presence in legacy equipment and developing market applications where specification enforcement remains limited.
Certification concentration sits with High-performance Fluids. Specification expansion is climbing the fastest in Specialty Fluids as regulatory substance bans multiply application requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors volume consumption for hydraulic fluids across Asia, with industrial clusters in the Yangtze River Delta processing formulations for construction equipment fleets and high-pressure manufacturing systems.
China
Construction machinery manufacturers in Jiangsu and Shandong provinces drive ISO VG 68 and 100 grade consumption for excavator and crane fleets. China's MEE enforces stricter discharge standards for used oil handling, elevating demand for reclaimable synthetic formulations. The Pearl River Delta concentrates blending capacity serving export-oriented plastic processing equipment.
United States
Hydraulic fracturing operations in Texas and offshore platforms in the Gulf of Mexico require fire-resistant formulations for blowout preventer systems. EPA mandates spill prevention and countermeasure planning for bulk hydraulic oil storage, imposing capital burdens on agricultural distributors. Construction equipment rental companies in Houston consolidate procurement through platform-based bulk contracts.
Germany
Automotive stamping plants in Bavaria and Baden-Württemberg specify ISO VG 46-68 synthetic formulations with ashless anti-wear packages. REACH Annex XVII restrictions on zinc dialkyldithiophosphate additives force rapid adoption of alternative chemistries. Food processing equipment manufacturers in the Netherlands and Germany specify PAG-based fluids for bakery and dairy systems.
India
Earthmoving equipment fleets in Maharashtra and Gujarat absorb mineral oil-based ISO VG 68 grades as infrastructure investment accelerates. The Bureau of Indian Standards tightens lubricant quality specifications for imported base stocks. Punjab's agricultural machinery sector retains cost-sensitive procurement patterns through established service infrastructure.
Indonesia
Infrastructure projects across Java and Sumatra pull hydraulic fluid volumes into excavator and bulldozer fleets at accelerating rates. The country's national environmental regulator imposes spill liability frameworks for forestry and marine applications. Jakarta's construction equipment distributors face displacement from emerging direct-to-fleet digital procurement platforms.
Hydraulic Fluids and Process Oil Market Competitive Environment
Premium-margin players sit above commodity-margin players across base stock technology tiers, with integrated refiners commanding cost advantages in mineral oil formulations while specialty blenders capture synthetic premiums. The market structures around three archetypes: integrated oil majors with captive base oil supply, independent specialty lubricant formulators, and national oil companies serving domestic construction and industrial bases. Competitive moves concentrate on backward integration into additive manufacturing and geographic expansion through distribution partnerships in Southeast Asian construction markets.
Within the integrated major tier, Shell plc and ExxonMobil Corporation exemplify scale-driven positions anchored by Group III+ base stock technology and extended drain interval certifications. FUCHS Petrolub SE occupies a specialist position representing the independent formulator archetype focused on high-pressure industrial hydraulics. Among Asia-Pacific national oil companies, China Petrochemical Corporation and PetroChina Company Limited sit within the domestic supply anchor category, leveraging refinery integration to serve regional construction equipment demand.
| Leading Market Players |
|---|
| BP p.l.c. |
| FUCHS Petrolub SE |
| Shell plc |
| China Petrochemical Corporation (SINOPEC) |
| Valvoline Inc. |
| ExxonMobil Corporation |
| TotalEnergies SE |
| PetroChina Company Limited |
| Chevron Corporation |
| Others |
Value Chain & Pricing Dynamics
EU REACH Annex XVII substance restrictions gate qualified supply and premium-tier pricing access by forcing rapid ZDDP additive substitution, compressing margins for blenders lacking ashless formulation expertise while rewarding compliant specialists with OEM certification premiums. Buyers face bifurcated procurement economics: mineral oil commodity tiers compete on delivered cost, while synthetic formulations command value-based contracts tied to extended drain intervals and fire-resistance guarantees.
Pricing Analysis
Value-based contracts anchored to equipment uptime guarantees dominate premium synthetic tiers, with PAO and ester formulations priced against avoided downtime rather than per-liter benchmarks. Price differentiation separates OEM-certified high-performance grades from standard ISO VG blends through additive package sophistication and field trial documentation. Cost compression in mineral oil tiers intensifies as Middle Eastern refinery expansions lag synthetic base stock demand, squeezing blender margins. Agricultural machinery fleets in India and Indonesia exhibit highest price sensitivity, while aerospace and offshore wind turbine operators absorb premiums for fire-resistant and decade-life formulations.
Supply Chain Analysis
Direct-to-fleet digital channels handle hyperscale construction equipment demand, displacing traditional jobber networks in Texas and Alberta rental markets. Base stock supply concentrates in China, South Korea, and the United States, with Group III+ capacity expansions trailing synthetic fluid adoption curves. Formulation chemistry draws from polyalphaolefin, synthetic ester, and polyalkylene glycol feedstocks, with additive packages resting on ashless anti-wear and biodegradable thickener technologies. Single-source vulnerability in specialty additive manufacturing creates chokepoint risk as ECHA restrictions accelerate formulation turnover. Distribution runs through integrated mill contracts, OEM captive channels, and condition-monitoring bundled services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU REACH substance bans erect barrier-to-entry moats for blenders possessing ashless additive expertise and OEM certification pipelines.
For Market Incumbents: To counter additive chemist scarcity and compressed OEM approval timelines, backward integration into captive ashless additive manufacturing secures formulation autonomy. Incumbents should anchor capacity additions in Jiangsu and Shandong provinces to serve China's MEE-driven reclaimable synthetic demand while bundling closed-loop fluid management services. For New Entrants and Emerging Players: REACH-driven ZDDP substitution in Europe opens a window for ashless formulation specialists to penetrate automotive stamping and metal forming supply chains. New entrants should target Poland and Czechia manufacturing clusters through extended drain interval technical claims rather than price competition, leveraging direct digital procurement channels to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: First-mover OEM approvals for 10,000-hour field trial certifications is the leading indicator that synthetic formulation specialists will capture wind turbine and aerospace margin pools. Investors should prioritize acquisition targets with proven polyol ester expertise and existing Bosch Rexroth or Caterpillar certification pipelines, monitoring ECHA substance restriction expansion timelines as inflection signals for bio-based formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive ashless anti-wear production insulates blenders from ECHA-driven supply disruption and chemist scarcity. |
| Reclaimable Synthetic Formulation Development | Closed-loop fluid services align with China's MEE discharge standards and generate recurring revenue streams. |
| Direct-to-Fleet Digital Platform Launch | Platform-based procurement captures construction rental company volume and compresses traditional distributor margins. |
| OEM Certification Pipeline Investment | 10,000-hour field trial capabilities unlock wind turbine and aerospace premium tiers with decade-long contract visibility. |
| Regional Blending Capacity Expansion | Jiangsu and Shandong facilities position suppliers to serve China's construction machinery export clusters. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant engineers, OEM procurement teams, aftermarket service heads, and technical R&D directors. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level demand estimates. Specific sources included ECHA restriction dossiers, EPA SPCC compliance databases, China MEE discharge standards, and base stock import customs records across Asia-Pacific and European trade corridors.
Data-stream reconciliation across product type, application severity, end-user contract structure, and regional regulatory clusters produced volume and value outputs across the analysis window. CAGRs derived from equipment fleet expansion rates, formulation substitution elasticities, and OEM specification tightening trajectories. Industry-specific forecast inputs incorporated construction machinery production data from Jiangsu and Shandong provinces, wind turbine installation pipelines in the North Sea and Baltic regions, and REACH Annex XVII implementation timelines for additive chemistry bans.
The model assumes a particular technology adoption path; alternative pathways for biodegradable ester oxidation stability breakthroughs above 80°C would alter the outlook for high-load industrial press applications. Practitioners should monitor ECHA substance restriction expansion scope, China's MEE enforcement intensity, and construction equipment telematics platform consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Argentina Lubricants Market
Lubricants
Construction Lubricants Market
Lubricants
Global Lubrication Systems Market
Lubricants
Spain Automotive Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Middle East Lubricants Market
Lubricants
Philippines Lubricants Market
Lubricants
EDM Oils/Fluids Market
Lubricants
Industrial Lubricants Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
United States Automotive Lubricants Market
Lubricants
Global Compressor Oil Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
United Kingdom Automotive Lubricants Market