
 Myanmar Lubricants Market | 2026-2036
Myanmar Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Myanmar Lubricants Market Insights
Preventive maintenance contracts for heavy-duty fleets is hardening as a distinct revenue layer alongside product sales. Shell plc leverages its integrated supply chain to secure depot-level service agreements with transport operators across Myanmar's central corridor. Petronas Lubricants International anchors its position through technical support programs tied to marine and power-generation equipment. Chevron (Caltex) competes via established fuel-retail networks that double as lubricant distribution nodes.
Lubricants are formulated base oils combined with additive packages that reduce friction, dissipate heat, and prevent wear in mechanical systems; viscosity grades such as SAE 15W-40 and ISO VG 68 define performance thresholds for tropical operating conditions. Engine oils dominate product-type revenue due to Myanmar's expanding vehicle parc and commercial transport intensity. Industrial oils represent the fastest-growing end-user category as factory automation spreads in Yangon's emerging manufacturing zones. Greases command premium margins in mining and construction applications where water resistance and extreme-pressure performance justify higher formulation costs.
Myanmar's Department of Research and Innovation under the Ministry of Science and Technology administers voluntary product standards, while the Myanmar Engineering Society promotes equipment-maintenance protocols that indirectly govern lubricant selection. The absence of mandatory national lubricant specifications creates a compliance gap that international OEM warranties and import certification requirements partially fill. Stakeholders must monitor whether Myanmar adopts ASEAN-wide lubricant standards or develops enforceable domestic regulations that would reshape market access and product positioning.
Market Dynamics
Fleet modernization across Myanmar's commercial transport sector is compressing lubricant replacement cycles and elevating technical specifications for engine oils and transmission fluids.
Growth Catalysts
- Industrial Zone Expansion:Yangon's emerging manufacturing clusters are accelerating factory automation, lifting consumption of hydraulic fluids and metalworking lubricants for precision equipment.
- ASEAN Connectivity Infrastructure:The East-West Economic Corridor upgrades are expanding heavy-duty truck traffic through Myanmar's central corridor, amplifying demand for high-performance diesel engine oils.
- Marine Equipment Modernization:Port logistics expansion at Thilawa and Yangon terminals is driving cylinder oil and system oil requirements for newer-generation vessel engines.
Market Restraints
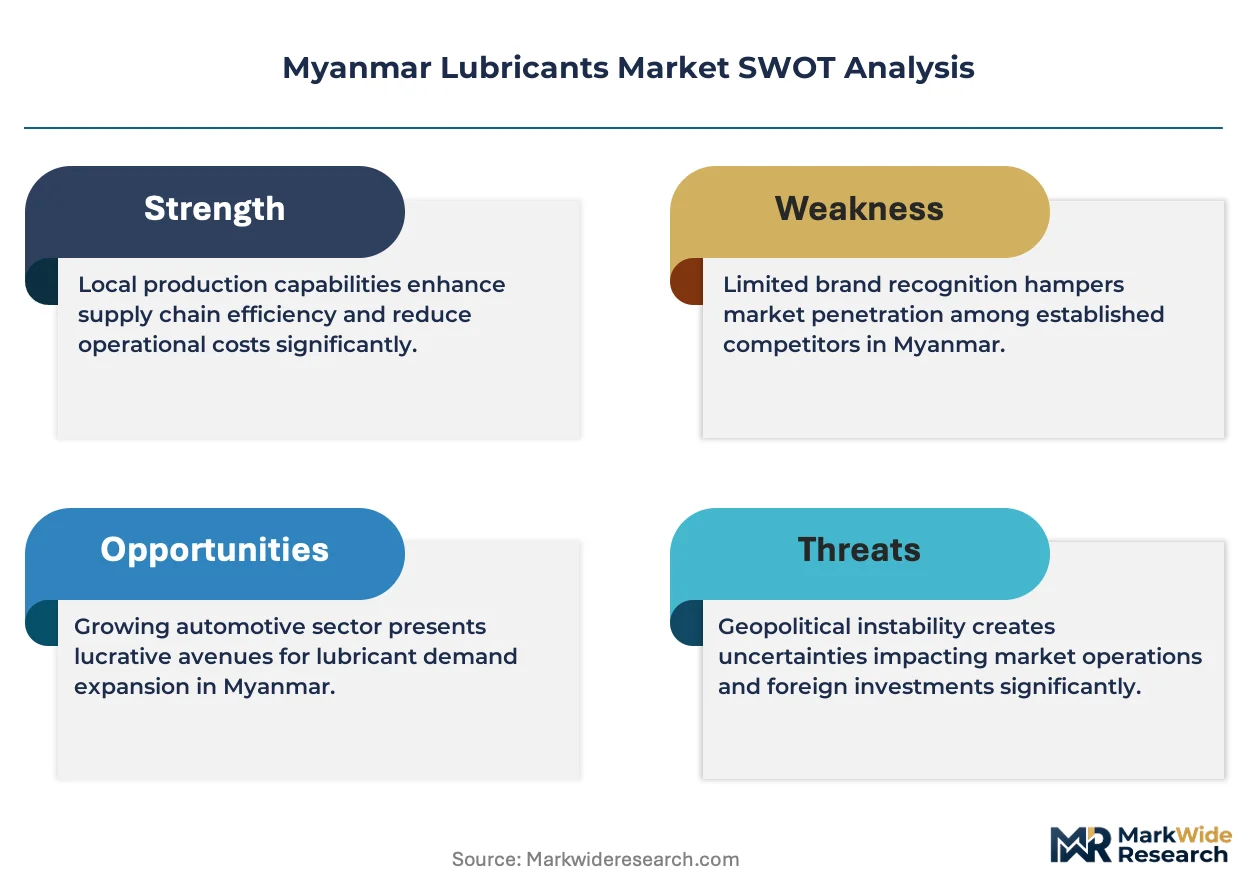
- Base Oil Import Dependency:Myanmar lacks domestic Group II/III base oil production, exposing formulators to feedstock cost volatility and currency fluctuation risks.
- Informal Blending Operations:Unregistered workshops in Mandalay and Bago regions distribute substandard lubricants that erode price discipline and technical trust.
- OEM Warranty Requirements:International equipment manufacturers impose lubricant certification standards that exceed Myanmar's voluntary national guidelines, creating compliance cost barriers for local distributors.
Strategic Opportunities
- Secondary City Penetration:Monywa and Taunggyi represent underdeveloped lubricant markets where agricultural mechanization is outpacing formal distribution network coverage.
- Preventive Maintenance Contracts:Mining operators in Kachin State are transitioning from spot purchases to integrated fluid management agreements bundling lubricants with condition monitoring.
- Renewable Energy Equipment:Wind turbine installations in Shan State and solar farm construction in Magway Region are creating demand for specialized gearbox and bearing greases.
Industry Challenges
- Technical Service Capacity:Field engineers capable of conducting oil analysis and interpreting wear metal data remain scarce outside Yangon and Mandalay.
- Regulatory Timeline Uncertainty:The absence of mandatory lubricant specifications from the Department of Research and Innovation delays investment in testing laboratory infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myanmar Lubricants Market |
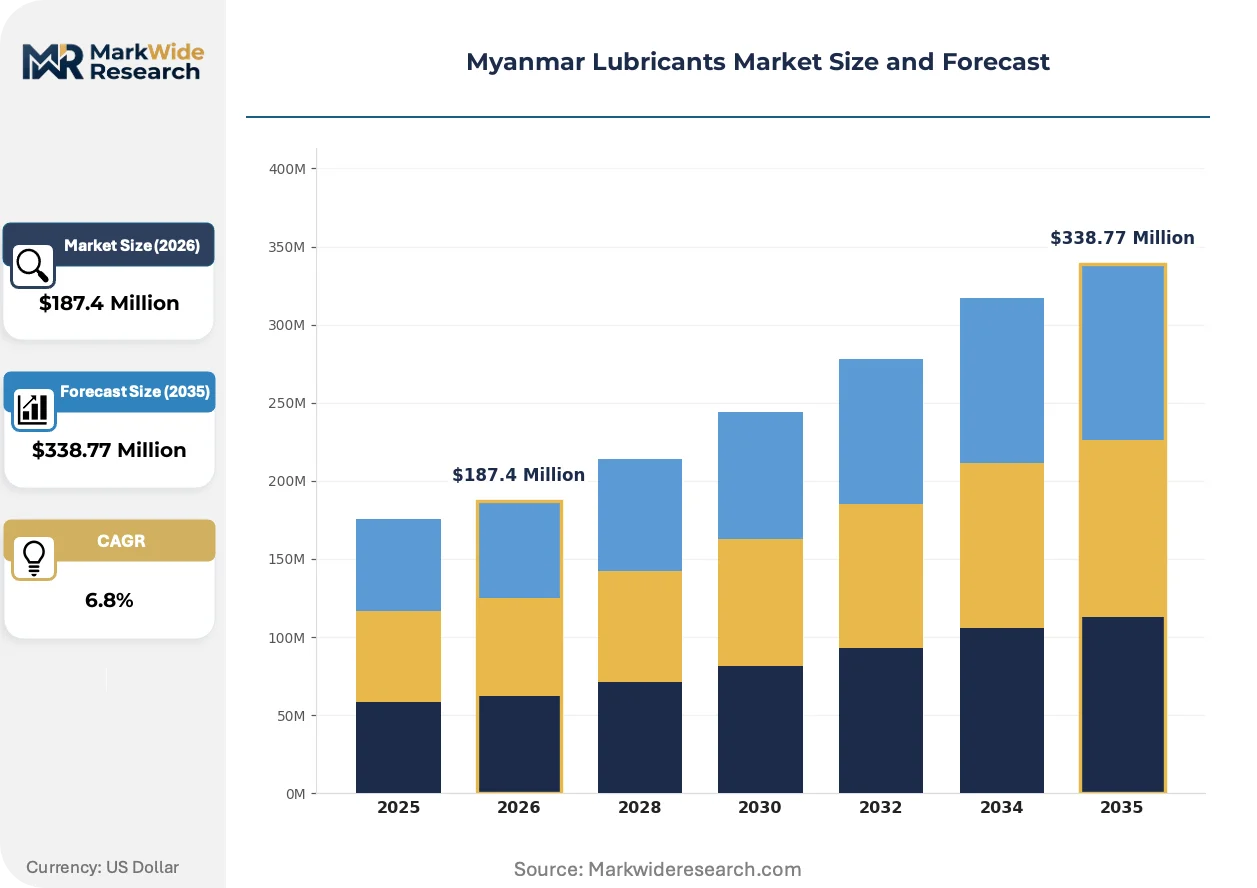
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Industrial Oils, Greases, Process Oils End User: Automotive, Manufacturing, Marine, Aviation Application: Heavy-Duty Vehicles, Machinery, Equipment, Personal Vehicles Distribution Channel: Retail Stores, Online Sales, Wholesalers, Distributors |
| Companies Covered | Exxon Mobil Corporation, Petronas Lubricants International, Shell plc, FUCHS, PTT Lubricants, BP p.l.c., PT Pertamina Lubricants, Chevron (Caltex), TotalEnergies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myanmar Lubricants Market Trends and Innovations
Reformulation priorities across Myanmar's lubricant supply base are pivoting toward extended-drain intervals and tropical climate optimization, reshaping additive package selection and viscosity grade positioning.
Synthetic and semi-synthetic lubricant formulations are rewriting performance expectations for commercial vehicle fleets operating in Myanmar's high-humidity, high-dust conditions. Transport operators plying the Yangon-Mandalay highway corridor are adopting these products at accelerating rates despite 40-60% price premiums over mineral alternatives. The technology is compressing traditional 5,000-kilometer drain intervals toward 15,000-kilometer service cycles, reducing fleet downtime and total fluid consumption.
The Myanmar Engineering Society's equipment maintenance protocols are tightening lubricant selection criteria for critical industrial machinery. These voluntary standards are pressuring formulators to submit products for third-party testing against international benchmarks such as API CK-4 and ACEA E9. Factory maintenance managers in Yangon's Thilawa Special Economic Zone are responding by requiring supplier documentation of additive chemistry and base oil group classification.
Consolidated procurement by fleet operators is displacing fragmented spot purchasing across Myanmar's road freight sector. Large logistics companies with 100-plus vehicle fleets are negotiating direct supply agreements with lubricant distributors, bypassing traditional retail channels. This pattern is most visible in Mandalay, where refrigerated transport operators serving agricultural supply chains are unbundling lubricant procurement from general maintenance contracts.
Myanmar Lubricants Market Segmentation
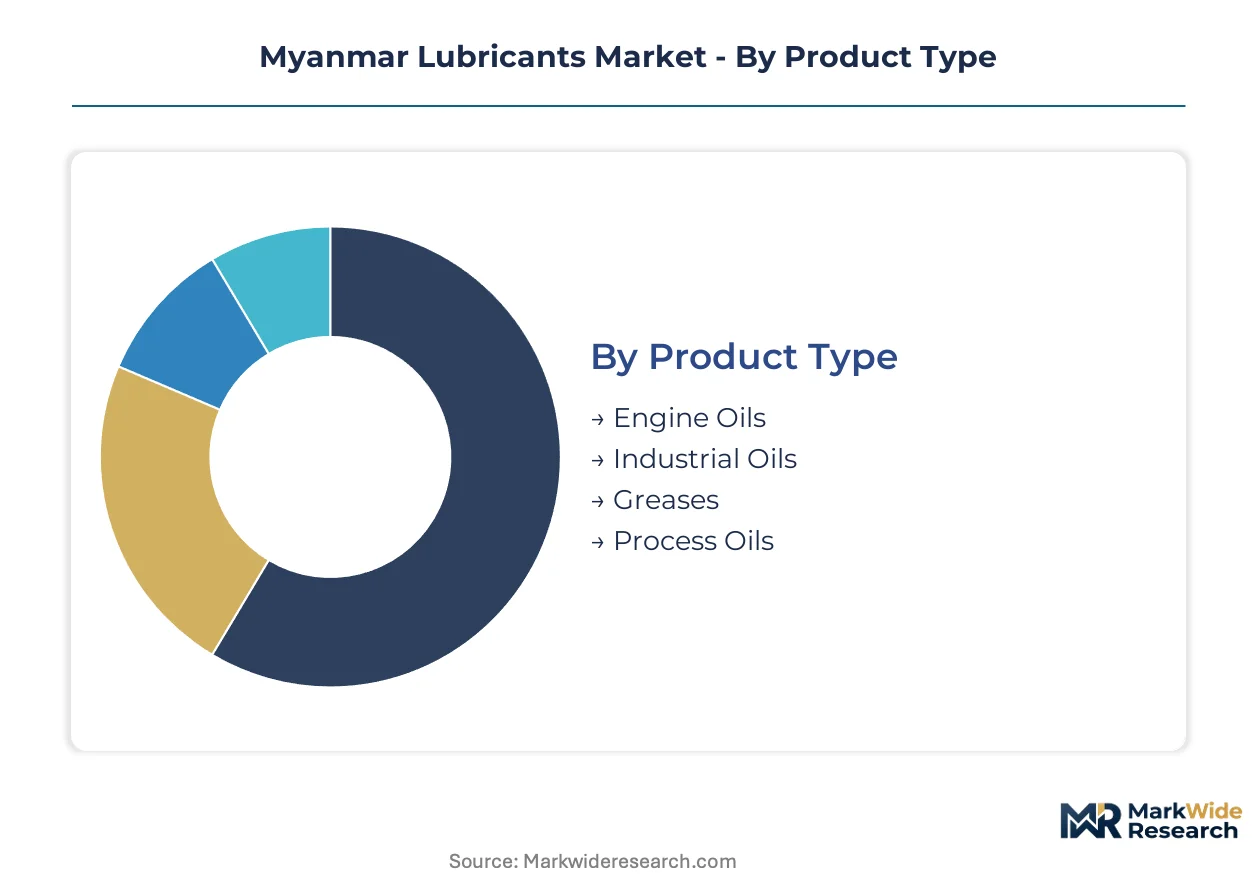
Lubricant purchasing decisions in Myanmar track equipment replacement cycles and industrial modernization timelines. Fleet operators and factory maintenance managers select products based on OEM warranty requirements and tropical operating conditions rather than price alone.
Product Type:
Upgrade cycles vary dramatically across lubricant categories, with drain interval extension driving reformulation priorities.
- Engine Oils:Formulated from Group II/III base stocks with detergent-dispersant additive packages meeting API CK-4 or ACEA E9 specifications. Demand concentrates in Yangon-Mandalay highway freight corridors where fleet operators compress 5,000-kilometer drain intervals toward 15,000-kilometer cycles using synthetic blends. Myanmar's expanding commercial vehicle parc and OEM warranty compliance requirements anchor volume placement.
- Industrial Oils:Hydraulic fluids, turbine oils, and compressor lubricants formulated for factory automation equipment. Yangon's Thilawa Special Economic Zone manufacturing clusters generate concentrated consumption as precision machinery maintenance protocols tighten lubricant selection criteria. The Myanmar Engineering Society's voluntary equipment standards are pressuring formulators toward third-party certification.
- Greases:Lithium-complex and calcium-sulfonate thickened lubricants with extreme-pressure additives for mining and construction equipment. Water resistance performance justifies premium formulation costs in Kachin State extractive operations.
- Process Oils:Refined base oil derivatives used in rubber compounding and textile manufacturing. Mandalay's emerging industrial zones drive spot demand.
Volume placements concentrate in Engine Oils; the faster expansion belongs to Industrial Oils.
End User:
Customer procurement sophistication separates spot purchasers from integrated fluid management adopters.
- Automotive:Passenger car motor oils and commercial vehicle lubricants purchased through service stations, independent workshops, and fleet direct agreements. Refrigerated transport operators in Mandalay are unbundling lubricant procurement from general maintenance contracts.
- Manufacturing:Factory maintenance managers in Yangon's emerging manufacturing zones specify hydraulic fluids and metalworking lubricants with documented additive chemistry and base oil group classification. Preventive maintenance contracts are displacing fragmented purchasing.
- Marine:Cylinder oils and system oils for vessel engines at Thilawa and Yangon port terminals. Port logistics expansion drives newer-generation engine lubricant requirements.
- Aviation:Turbine oils and hydraulic fluids for commercial and cargo aircraft. Myanmar's civil aviation regulator imposes lubricant certification standards exceeding voluntary national guidelines.
Procurement scale favors Automotive; technical service intensity distinguishes Manufacturing.
Application:
Operating environment severity dictates viscosity grade selection and additive package investment.
- Heavy-Duty Vehicles:Diesel engine oils and transmission fluids for commercial trucks plying ASEAN Connectivity corridor routes. High-humidity, high-dust conditions accelerate synthetic and semi-synthetic adoption despite 40-60% price premiums over mineral alternatives.
- Machinery:Factory automation equipment including CNC machines, injection molding systems, and conveyor drives. Equipment-maintenance protocols indirectly govern lubricant selection through warranty compliance requirements.
- Equipment:Mining excavators, construction cranes, and agricultural mechanization in Monywa and Taunggyi. Agricultural mechanization is outpacing formal distribution network coverage in secondary cities.
- Personal Vehicles:Passenger car motor oils for Myanmar's expanding private vehicle ownership. Retail channel penetration dominates purchasing patterns.
Service interval compression defines Heavy-Duty Vehicles; penetration gaps characterize Equipment.
Distribution Channel:
Channel economics reflect customer scale and technical service requirements.
- Retail Stores:Branded lubricant outlets and automotive service stations serving personal vehicle owners and small workshops. Established fuel-retail networks double as lubricant distribution nodes in urban centers.
- Online Sales:E-commerce platforms and B2B procurement portals. Digital penetration remains limited by technical service requirements for oil analysis and wear metal interpretation.
- Wholesalers:Volume distributors supplying unregistered blending workshops in Mandalay and Bago regions. Substandard product distribution erodes price discipline.
- Distributors:Authorized lubricant distributors with field engineering capacity for oil analysis and condition monitoring. Technical service capacity concentrates in Yangon and Mandalay.
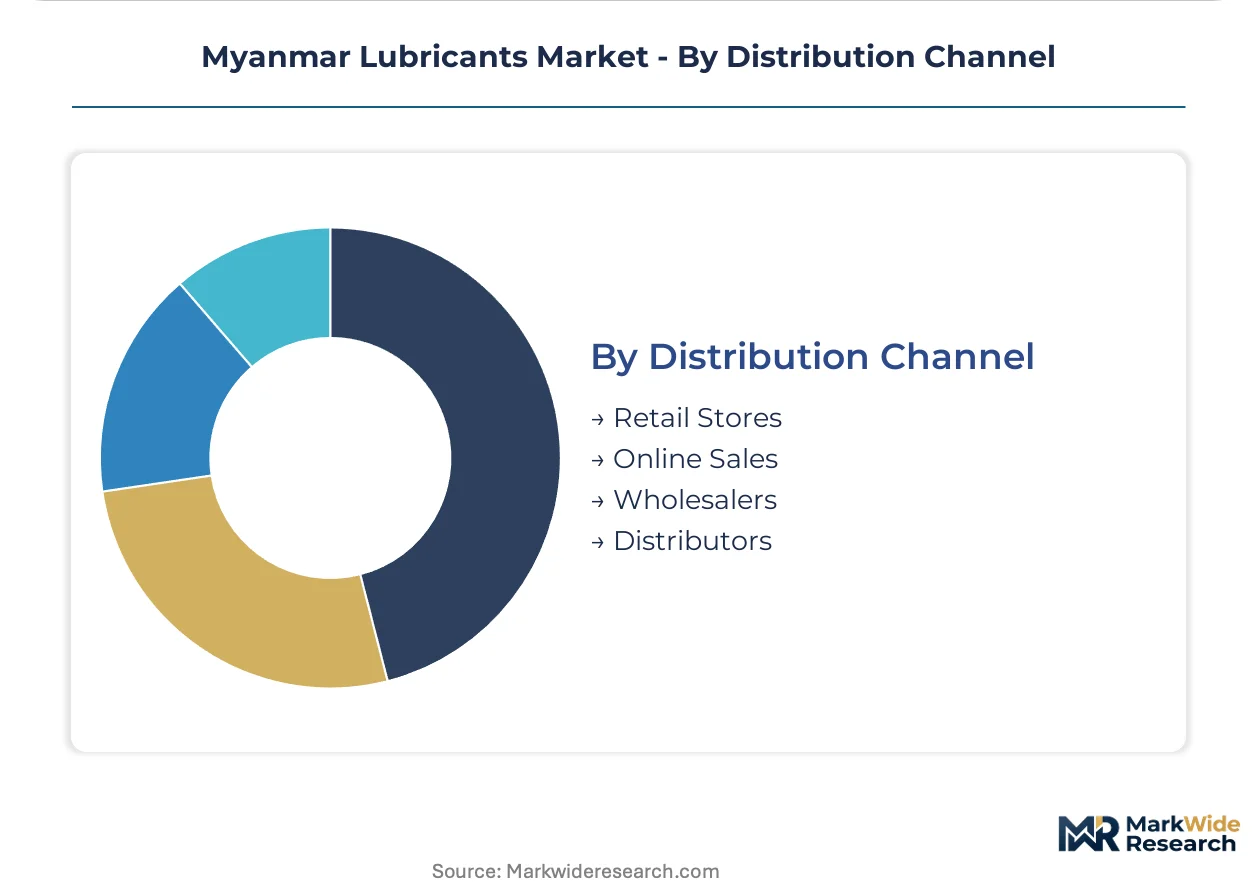
Direct agreements are displacing Retail Stores for fleet accounts; Distributors capture technical-service premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangon anchors Myanmar's lubricant consumption through its port logistics infrastructure and Thilawa Special Economic Zone manufacturing clusters. Mandalay generates secondary demand concentration via refrigerated transport corridors serving agricultural supply chains. Secondary cities including Monywa and Taunggyi present penetration gaps where mechanization outpaces formal distribution networks.
Yangon Region
Thilawa port expansion and manufacturing zone automation drive hydraulic fluid and metalworking lubricant consumption. The Ministry of Industry's standardization push pressures factory maintenance managers toward documented additive chemistry. Fleet operators along the Yangon-Mandalay highway corridor compress drain intervals through synthetic formulation adoption.
Mandalay Region
Refrigerated transport operators serving agricultural supply chains unbundle lubricant procurement from general maintenance contracts. The Myanmar Engineering Society's voluntary equipment protocols indirectly govern lubricant selection for precision machinery. Unregistered blending workshops in surrounding Bago regions distribute substandard products that erode price discipline.
Sagaing Region
Monywa's agricultural mechanization creates demand for equipment lubricants where formal distribution coverage remains underdeveloped. The Department of Research and Innovation administers voluntary product standards without mandatory enforcement. Mining operations in Kachin State transition from spot purchases to integrated fluid management agreements with condition monitoring.
Shan State
Wind turbine installations generate specialized gearbox and bearing grease requirements distinct from conventional industrial lubricants. Renewable energy project developers impose lubricant certification standards exceeding national voluntary guidelines. Solar farm construction in neighboring Magway Region amplifies cross-state equipment lubricant demand.
Tanintharyi Region
Port logistics expansion at Dawei deep-sea port drives marine cylinder oil and system oil requirements for vessel engines. ASEAN Connectivity infrastructure upgrades amplify heavy-duty truck traffic through southern corridors. Coastal humidity and salt exposure accelerate synthetic lubricant adoption despite price premiums over mineral alternatives.
Myanmar Lubricants Market Competitive Landscape
Capital-heavy producers with integrated base oil supply chains compete with asset-light formulators dependent on imported feedstocks. The market structures around three tiers: multinational majors with depot-level service networks, regional specialists leveraging geographic proximity, and informal blenders operating outside regulatory oversight. Consolidation pressure intensifies as fleet operators demand technical service capabilities beyond product supply. Dominant competitive moves include preventive maintenance contract bundling and synthetic formulation portfolio expansion.
Among integrated majors, Shell plc anchors the depot-service archetype through supply chain control, while Petronas Lubricants International exemplifies the technical-support model tied to marine and power-generation equipment. Chevron occupies the fuel-retail network position, leveraging Caltex-branded distribution nodes for lubricant placement. These three represent contrasting strategic postures rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Petronas Lubricants International |
| Shell plc |
| FUCHS |
| PTT Lubricants |
| BP p.l.c. |
| PT Pertamina Lubricants |
| Chevron (Caltex) |
| TotalEnergies |
| Others |
Pricing and Supply Chain Analysis
Fleet operators with 100-plus vehicle direct procurement agreements anchor Myanmar's lubricant pricing structure around volume-based contract tiers rather than spot-market volatility. Their consolidated purchasing power compresses distributor margins while elevating technical service bundling as the value-capture mechanism.
Pricing Analysis
Outcome-based pricing tied to equipment uptime and extended drain interval performance anchors premium synthetic formulations. Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral economy levels segments buyers by fleet sophistication and OEM warranty compliance requirements. Pricing pressure stems from unregistered blending workshops in Mandalay and Bago regions distributing substandard products that erode price discipline. Small independent workshops remain most price-sensitive, while refrigerated transport operators with cold-chain reliability requirements accept 40-60% premiums for documented additive chemistry.
Supply Chain Analysis
Freight costs from Singapore, Thailand, and South Korea dominate landed cost structures for Group II/III base oils Myanmar lacks domestic capacity to produce. Formulators draw from imported base stock feedstocks, additive packages manufactured in Singapore and Japan, and packaging materials sourced regionally. Single-source vulnerability concentrates in base oil import channels through Yangon port, exposing blenders to currency fluctuation and customs clearance delays. Distribution runs through authorized distributors with field engineering capacity, fuel-retail networks doubling as lubricant nodes, and unregistered wholesalers serving price-sensitive spot purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Myanmar's lubricant market is consolidating around technical service capabilities as fleet operators abandon fragmented retail purchasing. Substandard product competition from informal blenders is forcing margin compression that weaker formulators cannot survive.
For Market Incumbents: To counter unregistered blending workshops eroding price discipline, deepen depot-level service agreements with transport operators across the Yangon-Mandalay corridor and invest in oil analysis laboratory infrastructure outside Yangon and Mandalay. Backward integration into captive additive package sourcing from Singapore-based suppliers secures formulation cost stability against currency volatility. For New Entrants and Emerging Players: Enter via technical service partnerships with agricultural mechanization operators in Monywa and Taunggyi where formal distribution coverage lags equipment deployment. Kachin State mining operations transitioning to integrated fluid management agreements present the most penetrable segment for condition monitoring bundled offerings. Position through distributor alliances rather than greenfield infrastructure investment. For Investors and Strategic Acquirers: The window for entry favors asset-light formulators with established technical service relationships over capital-intensive base oil infrastructure plays. Acquisition targets should display existing fleet direct agreements and field engineering capacity in secondary cities. Watch for mandatory lubricant specification announcements from the Department of Research and Innovation as the inflection signal triggering laboratory infrastructure investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Maintenance Contract Expansion | Shell plc's depot-level service agreements with Yangon-Mandalay fleet operators demonstrate revenue stabilization beyond product margins. |
| Synthetic Formulation Portfolio Buildout | Extended-drain interval products meeting API CK-4 specifications capture fleet operators compressing 5,000-kilometer cycles toward 15,000 kilometers. |
| Secondary City Distribution Partnership | Agricultural mechanization in Monywa and Taunggyi outpaces formal network coverage, creating first-mover advantages for technical service entrants. |
| Oil Analysis Laboratory Infrastructure | Scarcity of field engineers capable of wear metal interpretation outside Yangon and Mandalay creates service differentiation for laboratory-capable distributors. |
| Regulatory Compliance Prepositioning | Voluntary Myanmar Engineering Society protocols tightening toward mandatory specifications favor early certification investment against compliance cost barriers. |
Research Methodology
Document review covered trade customs records, ASEAN lubricant import databases, and Myanmar Engineering Society equipment maintenance protocols, complemented by interviews with lubricant formulator technical directors, fleet maintenance managers at refrigerated transport operators, authorized distributor field engineers, and procurement leads at Thilawa Special Economic Zone manufacturing facilities. Secondary validation drew from base oil trade flow data, port logistics expansion filings, and renewable energy project equipment specifications. Bottom-up volume estimates from end-use equipment parc analysis were cross-referenced against top-down import value reconstructions.
Historical consumption patterns across engine oils, industrial oils, greases, and process oils were cross-referenced against panel input from supply chain participants. Segmentation modeling incorporated product type, end user vertical, application severity, and distribution channel structure throughout the forecast period. CAGRs were derived from equipment replacement cycle analysis and industrial automation adoption curves. Forecast inputs included commercial vehicle parc expansion rates, factory automation penetration in Yangon manufacturing zones, and port logistics modernization timelines at Thilawa and Dawei terminals.
Revisions become necessary when mandatory lubricant specifications materialize from the Department of Research and Innovation, when base oil import tariffs or currency controls shift feedstock cost structures, or when ASEAN-wide standards adoption accelerates compliance timelines. Forecasts reflect assumptions about continued fleet modernization and industrial zone expansion that external shocks to Myanmar's trade access could disrupt. Stakeholders should weight assumptions against their own operating context and supply chain exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Yarn Lubricant Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Saudi Arabia Commercial Vehicles Lubricants Market
Lubricants
Hydropower Lubricants Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Vietnam Lubricants Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Iraq Lubricants Market
Lubricants
India Commercial Vehicles Lubricants Market
Lubricants
Global Finished Lubricant Market
Lubricants
Poland Metalworking Fluids Market
Lubricants
Gun Lubricant Market
Lubricants
Germany Commercial Vehicles Lubricants Market
Lubricants
China Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market