
 Argentina Lubricants Market | 2026-2036
Argentina Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Lubricants Market Insights
Argentina's INTI lubricant quality certification is hardening requirements for oxidative stability and reduced sulfur content, forcing blenders to reformulate base stocks. YPF leverages its captive refining infrastructure to secure feedstock continuity across domestic blending plants. Shell plc anchors premium synthetic positioning through specialized distribution partnerships with Buenos Aires fleet operators. ExxonMobil Corporation competes on technical service density, deploying field engineers to Mendoza mining and Córdoba manufacturing clients.
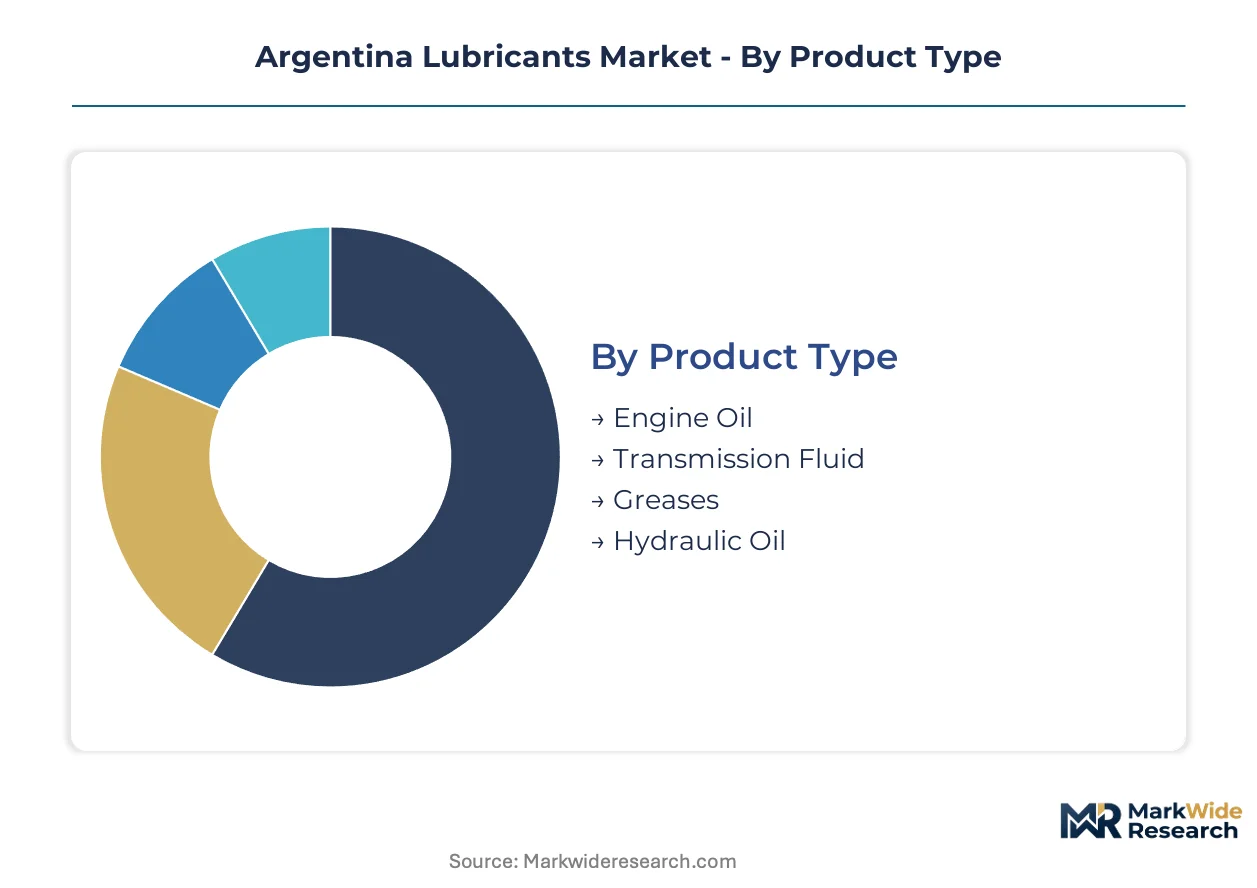
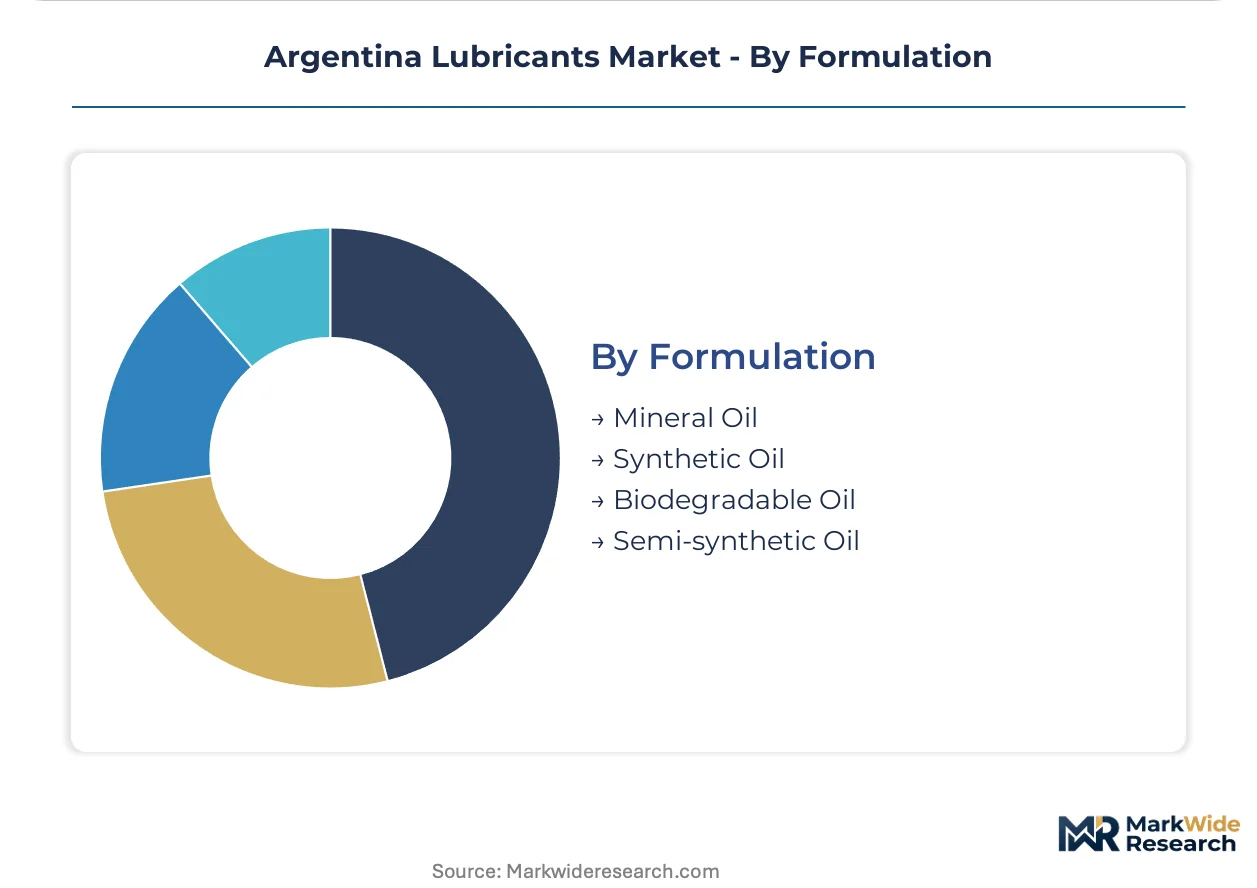
Lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with viscosity grades typically spanning ISO VG 32 through 680 for industrial applications and SAE 5W-30 through 15W-40 for automotive engines. Their primary commercial purpose is extending equipment operational life while minimizing unplanned downtime in high-load machinery. Engine oil occupies the largest revenue pool given Argentina's aging passenger vehicle parc and heavy-duty transport dependence, while biodegradable oil represents the fastest-expanding formulation segment as agricultural buyers face runoff compliance pressures in the Paraná watershed. Synthetic oil commands margin premiums in mining and power generation applications where extended drain intervals offset higher unit costs.
INTI standards align with IRAM technical norms governing lubricant labeling and performance claims, while the Secretaría de Energía monitors fuel quality rules that indirectly affect lubricant additive packages through sulfur linkage. These frameworks shape demand by restricting market access for uncertified imports and mandating environmental performance disclosures that steer procurement toward verified suppliers. Stakeholders must track enforcement intensity at provincial level, as Santa Fe and Buenos Aires provinces have advanced parallel inspection regimes that create compliance fragmentation for national distributors.
Market Dynamics
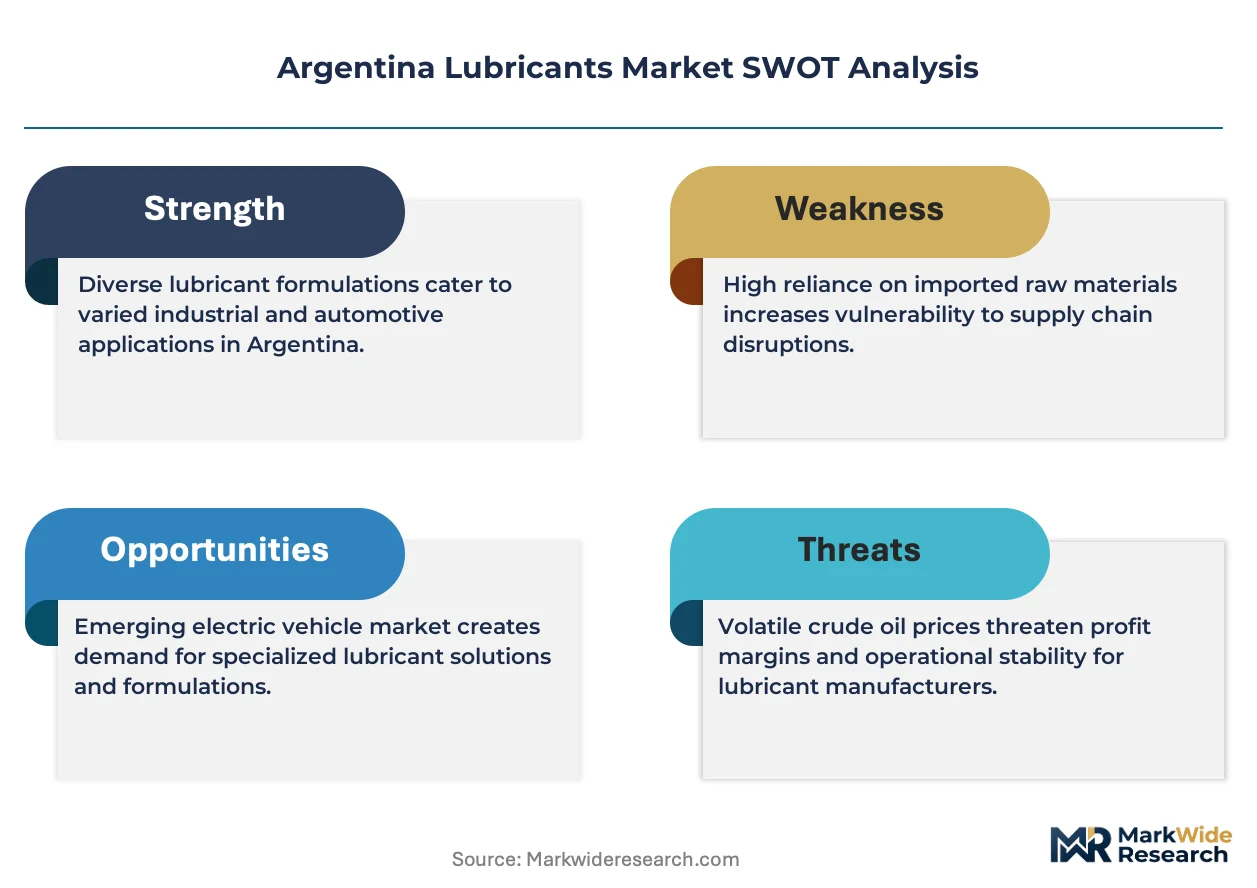
INTI certification hardening is forcing base stock reformulation across Argentina's blending sector, creating technical barriers that favor integrated refiners with captive hydrocracking capacity while squeezing independent compounders dependent on imported Group II/III feedstocks.
Growth Catalysts
- Mechanized farming density:The Pampas grain belt's fleet modernization is expanding lubricant consumption as combine harvesters and high-horsepower tractors require extended-drain formulations.
- INTI oxidative stability mandates:Argentina's tightening certification protocols are accelerating formulation upgrades that displace lower-tier mineral products from formal distribution channels.
- Paraná watershed runoff compliance:Agricultural buyers face environmental performance pressures that steer procurement toward biodegradable and bio-based lubricant categories.
Market Restraints
- Base oil import dependence:Argentina's limited domestic hydrocracking capacity forces blenders to source Group II/III feedstocks from regional traders, exposing margins to currency volatility and freight cost swings.
- Sulfur linkage constraints:Secretaría de Energía fuel quality rules indirectly restrict additive package formulations, limiting performance differentiation for mid-tier products.
- Provincial inspection fragmentation:Santa Fe and Buenos Aires provinces operate parallel enforcement regimes that create compliance cost duplication for national distributors.
Strategic Opportunities
- Mendoza mining synthetic penetration:Hard-rock extraction operations in the Andean foothills present white space for premium PAO and ester-based formulations with extended drain intervals.
- Córdoba manufacturing technical service density:Industrial clusters lack on-site lubricant engineering support, creating openings for condition-monitoring and predictive maintenance bundling.
- IRAM-INTI alignment:Convergence between national labeling norms and certification standards is streamlining market access for reformulated products that meet both frameworks.
Industry Challenges
- Formulation chemist scarcity:Argentina's technical education pipeline produces insufficient lubricant additive specialists, forcing blenders to recruit from petrochemical or coatings sectors.
- Legacy parc compatibility:Aging passenger vehicle and agricultural equipment fleets require backward-compatible formulations that complicate product line rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Lubricants Market |
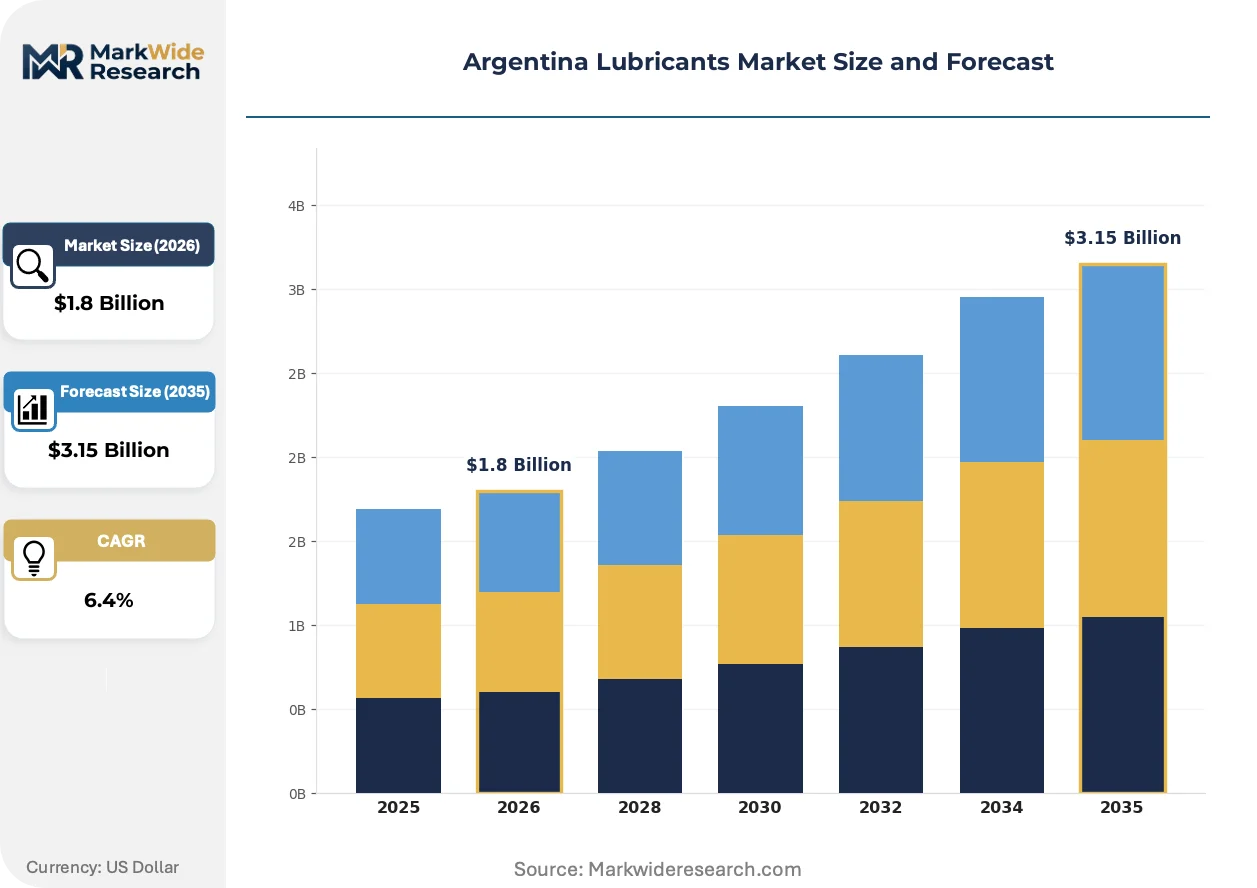
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Greases, Hydraulic Oil End User: Automotive, Industrial, Marine, Agriculture Distribution Channel: Retail, E-commerce, Direct Sales, Wholesalers Formulation: Mineral Oil, Synthetic Oil, Biodegradable Oil, Semi-synthetic Oil |
| Companies Covered | YPF, Shell plc, ExxonMobil Corporation, BP plc (Castrol), TotalEnergies, Chevron Corporation (CALTEX), AMA Oils, Brugarolas SA, Fercol, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Lubricants Market Trends and Innovations
Formulation chemistry and procurement patterns are converging to reshape Argentina's lubricant value chain, with certification-driven product tiering and service-model unbundling emerging as dominant vectors of change.
Synthetic base stocks are consolidating position in high-load industrial applications. Mining operators in Mendoza and power generation facilities are adopting Group III and PAO formulations to extend drain intervals beyond mineral oil limits. This shift is compressing the addressable market for conventional mineral products in premium segments while raising technical barriers for non-integrated blenders.
INTI certification protocols are hardening performance disclosure requirements. Argentina's national quality institute now mandates oxidative stability testing and sulfur content verification that exceeds prior IRAM labeling norms. Agricultural buyers in the Pampas region are responding by restricting procurement to certified suppliers, filtering uncertified imports from formal channels.
Fleet operators are unbundling lubricant supply from equipment maintenance contracts. Buenos Aires transport and logistics buyers are separating fluid procurement from service agreements, forcing suppliers to compete on standalone technical merit rather than bundled convenience. This pattern is most visible in heavy-duty trucking corridors where direct distributor relationships are displacing dealer-mediated supply.
Argentina Lubricants Market Segmentation
Argentina's lubricant demand fragments across equipment types, buyer sophistication, and regulatory pressure points. Each segmentation axis reveals distinct margin pools and technical barriers that reshape competitive positioning.
Product Type:
Engine Oil dominates volume flows while Greases command premium pricing in specialized applications.
- Engine Oil:Formulated from Group I through Group III base stocks with viscosity grades spanning SAE 5W-30 to 15W-40 for passenger vehicles and heavy-duty diesel fleets. Demand concentrates in Buenos Aires metropolitan corridors where aging passenger vehicle parc and long-haul transport dependence sustain high consumption intensity against tightening INTI oxidative stability mandates.
- Greases:Thickened lubricants combining base oils with metallic soaps or complex thickeners engineered for sealed-for-life bearings and extreme-pressure applications. Mining operators in Mendoza and manufacturing clusters in Córdoba drive specification-grade procurement as equipment OEMs mandate NLGI consistency grades for warranty compliance.
- Transmission Fluid:Specialized formulations with friction modifiers and shear-stable viscosity index improvers for automatic and manual gearboxes.
- Hydraulic Oil:Anti-wear and rust-inhibited fluids serving construction equipment and agricultural implements across the Pampas grain belt.
Today's leader: Engine Oil. Tomorrow's challenger: Greases.
End User:
Application-specific performance requirements split procurement patterns between fleet-scale buyers and fragmented equipment owners.
- Automotive:Passenger vehicle and commercial fleet lubricant demand spanning engine, transmission, and axle applications. Buenos Aires transport corridors and provincial urban centers concentrate volume as fleet operators unbundle supply from maintenance contracts and negotiate direct distributor relationships.
- Agriculture:Seasonal high-load applications for tractors, combines, and irrigation systems across Santa Fe, Córdoba, and Buenos Aires provinces. Pampas grain belt mechanization and Paraná watershed runoff compliance pressures steer buyers toward biodegradable formulations despite mineral oil price premiums.
- Industrial:Manufacturing plant and power generation lubrication with condition-monitoring integration potential.
- Marine:Stern tube, engine, and deck machinery fluids for riverine and coastal vessel operations.
Automotive anchors present revenue; Agriculture climbs fastest on fleet modernization and environmental compliance.
Distribution Channel:
Channel selection reflects buyer scale, technical service requirements, and inventory carrying cost tolerance.
- Direct Sales:Manufacturer-to-fleet relationships bypassing intermediaries for large-volume accounts with technical service demands. Mendoza mining operators and Buenos Aires heavy-duty trucking fleets drive this channel as they require on-site oil analysis and drain interval optimization support.
- Retail:Service station and automotive parts store networks serving fragmented passenger vehicle owners. Provincial urban centers and highway corridors sustain this channel despite e-commerce encroachment on packaged goods.
- Wholesalers:Regional distributors aggregating demand from smaller agricultural and industrial buyers.
- E-commerce:Emerging platform-based procurement for standardized packaged lubricants with transparent pricing.
Direct Sales captures margin; E-commerce gains share on procurement transparency.
Formulation:
Base stock chemistry and additive architecture determine performance tier, pricing, and regulatory compliance trajectory.
- Biodegradable Oil:Vegetable oil or synthetic ester base stocks with rapid biodegradation and low aquatic toxicity profiles formulated for environmentally sensitive applications. Agricultural buyers in the Paraná watershed face the steepest compliance pressures and are expanding procurement fastest despite 40-60% unit cost premiums over mineral equivalents.
- Synthetic Oil:Group III hydrocracked, PAO, or ester base stocks engineered for extended drain intervals and extreme temperature performance. Mining and power generation applications in Mendoza and Córdoba industrial zones adopt these formulations as equipment utilization rates justify higher upfront costs through reduced downtime.
- Mineral Oil:Conventional solvent-refined or hydrocracked base stocks serving price-sensitive legacy equipment.
- Semi-synthetic Oil:Blended formulations combining mineral and synthetic base stocks for mid-tier performance positioning.
Mineral Oil holds volume dominance. Biodegradable Oil expands most quickly on watershed compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's lubricant industry traces its modern foundation to state-led hydrocarbon development in the mid-twentieth century, when captive refining infrastructure established domestic blending capacity before multinational entrants expanded technical formulation capabilities.
Buenos Aires Province
Heavy-duty transport corridors and aging passenger vehicle density concentrate lubricant demand in the metropolitan belt. INTI certification enforcement operates at maximum intensity here, filtering uncertified products from formal channels. La Plata industrial zones host blending facilities serving fleet operators who unbundle supply from maintenance contracts.
Santa Fe Province
The Pampas grain belt's mechanized farming density drives seasonal consumption spikes for extended-drain agricultural formulations. Provincial environmental inspectors enforce parallel runoff compliance regimes that supplement federal INTI standards. Rosario agribusiness clusters source biodegradable lubricants under Paraná watershed protection mandates.
Córdoba Province
Manufacturing plant density and automotive component production sustain industrial lubricant demand across ISO VG viscosity grades. IRAM technical norms govern local labeling requirements that align with national certification frameworks. Córdoba city industrial parks lack on-site lubricant engineering support, creating technical service gaps.
Mendoza Province
Hard-rock mining operations in the Andean foothills generate specification-grade demand for synthetic formulations with extreme-pressure additives. Provincial mining secretariats mandate equipment warranty compliance that restricts procurement to certified NLGI grease suppliers. Mendoza city distributors anchor supply relationships with extraction operators.
Argentina Lubricants Market Competitive Landscape
Capital-heavy integrated refiners compete with asset-light compounders dependent on imported feedstock procurement. Market structure concentrates around three tiers: captive refiners with hydrocracking infrastructure, multinational formulators with technical service networks, and regional distributors aggregating fragmented agricultural demand. Strategic moves center on certification compliance investments and direct fleet relationship cultivation.
Within the integrated refiner archetype, YPF anchors domestic supply continuity through captive infrastructure. Shell plc and ExxonMobil Corporation exemplify multinational formulators competing on technical service density and specialized distribution partnerships. These three occupy positions across premium synthetic and mineral oil segments, with their competitive posture shaped by INTI certification alignment and provincial enforcement navigation.
| Leading Market Players |
|---|
| YPF |
| Shell plc |
| ExxonMobil Corporation |
| BP plc (Castrol) |
| TotalEnergies |
| Chevron Corporation (CALTEX) |
| AMA Oils |
| Brugarolas SA |
| Fercol |
| Others |
Pricing and Supply Chain Analysis
Captive hydrocracking infrastructure at YPF anchors both supply security and pricing power across Argentina's lubricant sector, insulating integrated refiners from the currency volatility that squeezes independent blenders dependent on imported Group II/III feedstocks. This upstream control enables premium synthetic positioning while import-dependent compounders absorb freight cost swings and peso depreciation in margin compression.
Pricing Analysis
Three-tier pricing structure across premium synthetic, certified mineral, and economy mineral levels stratifies the Argentine market. INTI certification grade and volume scale drive differentiation, with fleet operators negotiating direct contracts while fragmented agricultural buyers face distributor markups. Cost compression in the economy mineral tier is intensifying because currency depreciation inflates import feedstock costs. Agricultural cooperatives in the Pampas region exhibit highest price sensitivity, whereas Mendoza mining operators prioritize drain interval performance over unit cost.
Supply Chain Analysis
Used oil collection and re-refining flows remain underdeveloped in Argentina, limiting circular feedstock availability for base stock production. Domestic supply draws from YPF's La Plata refinery complex while imported Group II/III stocks arrive from Brazil, the United States, and regional traders. Single-source vulnerability concentrates in hydrocracking capacity, where domestic infrastructure gaps force reliance on external feedstock channels. Distribution runs through provincial distributor networks that aggregate fragmented agricultural demand and service mining clusters with technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's lubricant sector functions as a regulatory compounder where INTI certification hardening creates demand acceleration for reformulated products that displace uncertified imports from formal channels.
For Market Incumbents: Anticipate formulation chemist scarcity by recruiting from adjacent petrochemical sectors and securing backward integration into additive package sourcing. Certification investment represents the critical defensive lever against emerging regional blenders exploiting import duty arbitrage. Channel control through direct fleet relationships in Buenos Aires corridors protects margin pools from unbundling pressures. For New Entrants and Emerging Players: Begin with biodegradable lubricant white space in the Paraná watershed, where Santa Fe and Buenos Aires provincial inspectors enforce runoff compliance that outpaces national certification timelines. Technical service density gaps in Córdoba manufacturing clusters offer the most penetrable entry point. A go-to-market angle bundling condition-monitoring hardware with fluid supply addresses unmet predictive maintenance demand. For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with INTI-certified inventory positions because provincial enforcement fragmentation creates compliance cost duplication that national platforms can eliminate through scale. The five-to-ten year viability window favors acquisition targets with captive agricultural relationships in the Pampas grain belt. Monitor INTI enforcement intensity at provincial level as the inflection signal for certification-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Sourcing | Reduces exposure to sulfur linkage constraints under Secretaría de Energía fuel quality rules. |
| Biodegradable Formulation Scale-Up | Captures Paraná watershed compliance premiums as agricultural buyers face runoff mandates. |
| Technical Service Network Expansion | Addresses condition-monitoring gaps in Córdoba manufacturing and Mendoza mining clusters. |
| Direct Fleet Relationship Cultivation | Secures margin pools as Buenos Aires operators unbundle lubricant supply from maintenance contracts. |
| Provincial Certification Pre-Positioning | Navigates Santa Fe and Buenos Aires parallel inspection regimes before national harmonization. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant blenders, agricultural fleet managers, mining procurement officers, and INTI certification auditors with secondary validation from customs trade records, SEC filings of multinational suppliers, YPF operational disclosures, and IRAM technical norm documentation. Bottom-up demand modeling across equipment parc and drain interval assumptions triangulated against top-down market sizing from refinery output and import statistics.
Historical reference periods anchored the projection horizon through trend extrapolation of fleet modernization rates and regulatory enforcement intensity. Segmentation dimensions modeled include product type, end-use application, formulation chemistry, and distribution channel structure. CAGRs derived from equipment population growth, utilization rate assumptions, and premium formulation penetration curves. Forecast inputs incorporated INTI certification timeline probabilities and provincial environmental inspection staffing levels.
Several conditions sit outside the modeled scope, including abrupt currency devaluation episodes, trade policy reversals affecting Mercosur feedstock flows, and mining sector investment freezes from commodity price collapses. Forecasts reflect documented assumptions about enforcement continuity and certification alignment timelines. Practitioners should monitor provincial inspector hiring announcements and INTI laboratory capacity expansion for early signals of compliance acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Colombia Lubricants Market
Lubricants
Vietnam Automotive Engine Oils Market
Lubricants
Mexico Automotive Lubricants Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Bulgaria Lubricants Market
Lubricants
Global Compressor Oil Market
Lubricants
Mining Lubricants Market
Lubricants
Synthetic Ester Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
Solid/Dry Lubricants Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Fire Resistant Fluids Market
Lubricants
Brazil Automotive Lubricants Market
Lubricants
Norway Lubricants Market
Lubricants
Norway Commercial Vehicles Lubricants Market