
 Chile Lubricants Market | 2026-2036
Chile Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Lubricants Market Outlook
Bulk-to-tote packaging is decoupling large-volume mining contracts from traditional drum-only procurement, letting buyers mix direct tanker deliveries with smaller flexible containers. Empresas Copec leverages its national fuel-station network to embed lubricant sales within fleet-card programs. Chevron Corporation anchors premium synthetic supply through technical-service agreements with Chilean open-pit operators. Shell plc competes on marine lubricant specialization via Valparaíso port logistics.
Lubricants are formulated blends of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades typically ranging from ISO VG 32 to 680 for industrial applications. Engine oil holds the largest revenue share in Chile's automotive and mining sectors, though hydraulic fluid generates superior margins in copper extraction where fire-resistant formulations command technical premiums. Industrial applications lead volume consumption due to Chile's concentration of smelting and concentrator operations, while agriculture represents a smaller but consolidating channel as mechanized irrigation spreads in the O'Higgins and Maule regions.
Chile's Ministry of Environment administers Extended Producer Responsibility frameworks affecting lubricant packaging and waste-oil collection, while the Superintendency of the Environment monitors hydrocarbon discharge limits at mining sites. Compliance costs are redirecting procurement budgets toward certified biodegradable and re-refined product categories. Stakeholders must track how Chile's carbon-neutrality commitments reshape fuel-efficiency specifications and base-oil import sourcing from regional refiners.
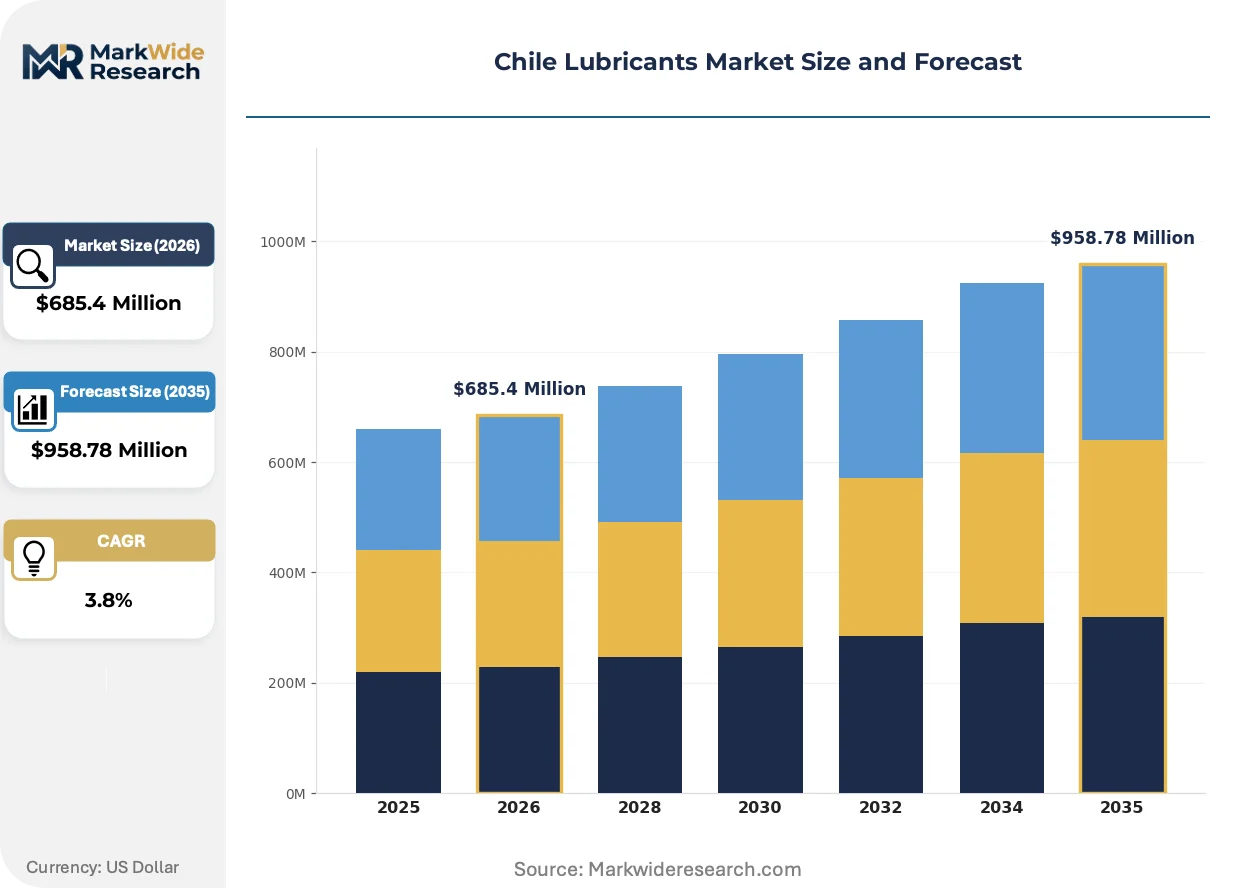
Market Dynamics
Chile's Ministry of Mining enforcement of stricter environmental discharge standards is accelerating reformulation toward biodegradable base stocks, compressing traditional mineral oil demand while elevating synthetic and re-refined product premiums across copper extraction corridors.
Growth Catalysts
- Extended Producer Responsibility frameworks:Chile's Ministry of Environment mandates lubricant packaging and waste-oil collection, redirecting procurement budgets toward certified biodegradable categories and expanding circular-economy service revenue pools.
- Copper extraction intensity:Open-pit operations in the Atacama and Antofagasta regions consume heavy-duty hydraulic fluid and engine oil at scale, with fire-resistant formulations commanding technical premiums that expand supplier margins.
- Synthetic lubricant penetration:Mining fleet operators are expanding procurement to extend equipment life cycles, reducing unplanned downtime costs and locking in multi-year technical-service agreements with formulation specialists.
Market Restraints
- Base-oil import dependency:Chile lacks domestic Group II/III refining capacity, exposing formulators to freight cost volatility and currency fluctuation risk on Atlantic-sourced feedstock.
- Re-refining infrastructure gaps:Limited collection and reprocessing capacity constrains circular-economy participation, forcing reliance on virgin base stocks despite EPR compliance requirements.
- Biodegradable formulation cost premiums:Vegetable-derived ester base stocks trade at significant markups to mineral equivalents, compressing adoption rates in price-sensitive agricultural and small-fleet segments.
Strategic Opportunities
- Bulk-to-tote packaging innovation:Flexible intermediate bulk containers enable mining buyers to mix direct tanker deliveries with smaller consumption points, decoupling large-volume contracts from drum-only procurement legacy.
- Mechanized irrigation expansion:The O'Higgins and Maule regions present consolidating agricultural channel demand as precision farming equipment spreads, creating white space for specialized hydraulic and transmission fluids.
- Carbon-neutrality procurement mandates:Chile's national decarbonization commitments reshape fuel-efficiency specifications, opening technical-consulting revenue streams around lubricant-related energy audits and carbon accounting.
Industry Challenges
- Fire-resistant hydraulic fluid certification timelines:Mining operators face extended validation periods for Factory Mutual or MSHA-approved formulations, delaying fleet-wide specification changes and locking incumbent suppliers.
- Used-oil logistics fragmentation:Sparse collection infrastructure across northern mining corridors forces operators to self-manage waste streams, elevating compliance costs and environmental liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Lubricants Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $958.78 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Fluid, Grease Application: Automotive, Industrial, Marine, Agriculture End User: OEMs, Aftermarket Providers, Repair Shops, Fleet Operators Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Petrobras, Chevron Corporation, Empresas Copec, YPF, BP PLC, Shell plc, Valvoline Inc., Repsol, TotalEnergies SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Lubricants Market Strategic Shifts
Reformulation chemistry and packaging logistics are converging to reshape competitive positioning, with biodegradable base stocks and flexible delivery systems displacing legacy mineral-oil and drum-centric supply models.
Synthetic ester and polyalphaolefin blends are integrating fire-resistance and biodegradability into single formulations, satisfying both Factory Mutual safety standards and Chile's Ministry of Environment discharge limits. Open-pit copper operators in Antofagasta are adopting these dual-certification products at accelerated pace, compressing the addressable market for conventional mineral hydraulic fluids and elevating technical-service intensity as a competitive differentiator.
Chile's Ministry of Environment Extended Producer Responsibility enforcement is tightening waste-oil collection and packaging recovery obligations, elevating operational compliance costs for formulators while creating structured revenue streams for integrated collection-and-re-refining service providers. The mining sector faces the steepest adaptation requirements, with Superintendency of the Environment monitoring driving consolidation toward suppliers with captive logistics networks.
Bulk-to-tote packaging systems are fragmenting traditional drum-only procurement, letting large mining buyers blend direct tanker deliveries with intermediate bulk container flexibility for remote consumption points. Fleet-card integration through national fuel-station networks embeds lubricant purchasing within broader energy management platforms, compressing standalone distributor margins in the northern extraction corridors where copper operations concentrate volume.
Chile Lubricants Market Segmentation
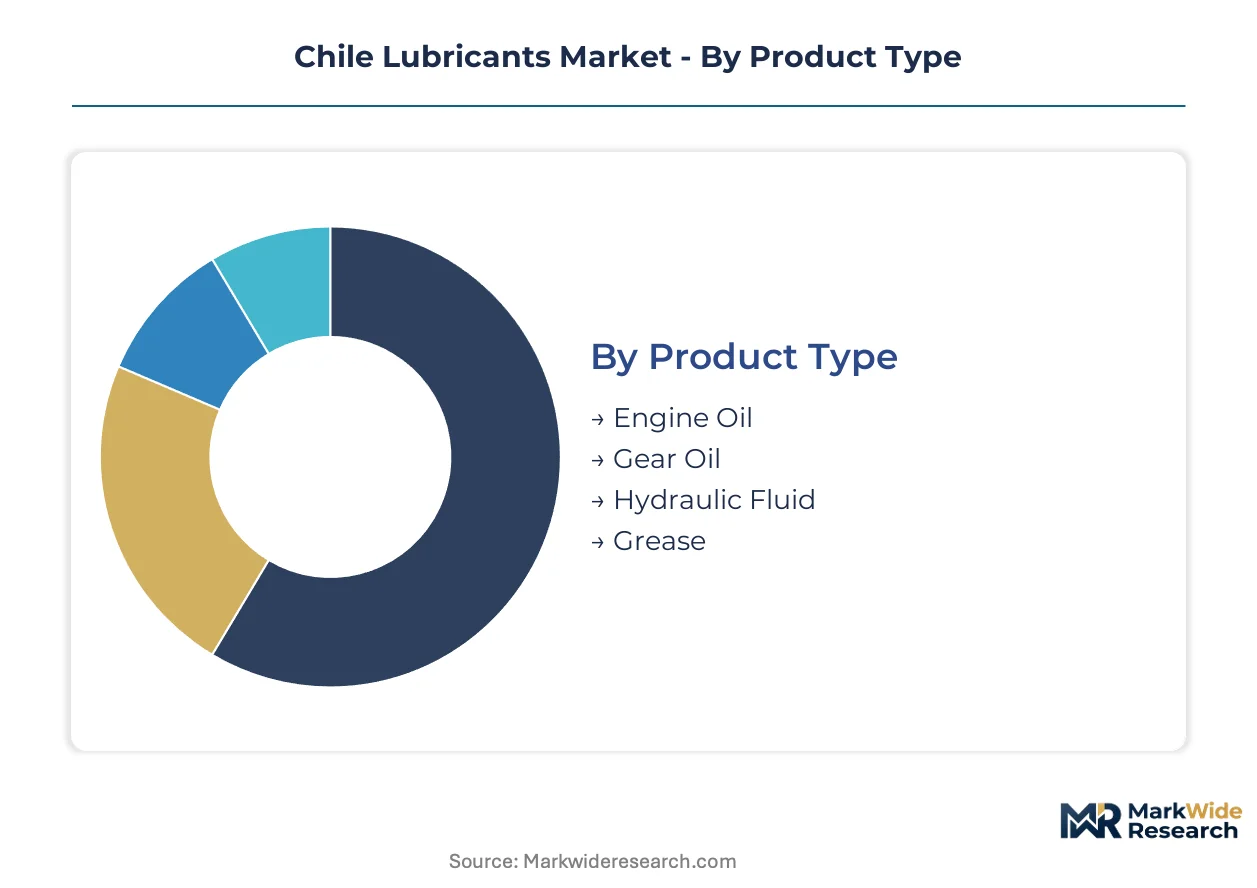
Segmentation in Chile's lubricants market reveals how copper extraction intensity and environmental compliance reshape procurement patterns across product categories and customer channels. Distinct specification requirements separate mining fleet operators from agricultural buyers, while distribution infrastructure fragments between bulk direct delivery and retail convenience.
Product Type:
Upgrade cycles in Chilean mining fleets are compressing mineral oil replacement intervals while extending synthetic formulation service life, creating divergent volume-mix dynamics across product categories.
- Engine Oil:Formulations range from mineral SAE 15W-40 for legacy fleets to full synthetic 5W-30 meeting API CK-4 and ACEA E6 specifications for Euro-VI compatible equipment. Demand concentrates in Antofagasta and Atacama mining corridors where haul truck engine hours accumulate rapidly; synthetic penetration locks in multi-year technical-service agreements with suppliers possessing on-site laboratory capabilities.
- Hydraulic Fluid:Fire-resistant HFA, HFB, and HFC formulations predominate in underground and surface mining where Factory Mutual approval is mandatory; biodegradable ester-based HFD-U grades are gaining specification in open-pit operations facing Superintendency of the Environment discharge monitoring. Copper concentrator circuits in Calama and Sierra Gorda consume ISO VG 46 and 68 grades at scale.
- Gear Oil:EP (extreme pressure) additives protect transmissions and differentials in high-load mining equipment; GL-5 specifications dominate rear axle applications.
- Grease:Lithium complex and calcium sulfonate thickeners serve bearing lubrication in crushers, conveyors, and shovels; copper mining's dust exposure demands frequent reapplication intervals.
Volume placements concentrate in Engine Oil; the faster expansion belongs to Hydraulic Fluid.
Application:
Cost tier stratification separates specification-intensive mining procurement from price-sensitive agricultural and consumer automotive segments, with margin structures inversely correlating to volume concentration.
- Industrial:Smelters, concentrators, and power generation facilities in northern Chile consume turbine oils, compressor lubricants, and heat transfer fluids; sulfuric acid plant environments demand specialized corrosion-inhibited formulations. Codelco and BHP's Escondida operations anchor regional demand with centralized procurement.
- Automotive:Passenger vehicle service fill and consumer DIY maintenance represent high-volume, low-margin throughput; Santiago metropolitan density supports quick-lube chain penetration while regional cities sustain traditional workshop networks.
- Marine:Two-stroke crosshead engine oils and trunk piston formulations serve bulk carriers and container vessels at Valparaíso, San Antonio, and Antofagasta ports; IMO 2020 sulfur regulations have shifted cylinder lubricant base number requirements.
- Agriculture:Mechanized irrigation expansion in O'Higgins and Maule valleys drives hydraulic and transmission fluid demand; tractor fleet modernization is compressing universal tractor oil specification diversity toward dedicated UTTO grades.
Industrial applications capture the dominant revenue share; Agriculture is climbing the fastest as precision farming equipment penetration accelerates.
End User:
Customer type determines contract structure, with fleet scale dictating whether procurement flows through integrated energy management platforms or fragmented spot purchasing.
- Fleet Operators:Mining and long-haul trucking fleets leverage consumption visibility through fuel-station network integration, consolidating lubricant purchasing within fleet-card programs that embed technical monitoring and scheduled delivery logistics.
- OEMs:Original equipment manufacturers specify initial fill lubricants for domestic assembly and imported machinery, with factory fill agreements locking in formulation approval cycles that delay competitive substitution.
- Aftermarket Providers:Distributors and jobbers serve fragmented workshop and retail channels, carrying inventory risk across multiple viscosity grades and specification tiers.
- Repair Shops:Independent mechanical workshops purchase in drum and pail quantities, prioritizing availability and credit terms over technical differentiation.
Procurement scale concentrates with Fleet Operators; the steepest service-intensity expansion belongs to OEMs as equipment digitization enables predictive maintenance integration.
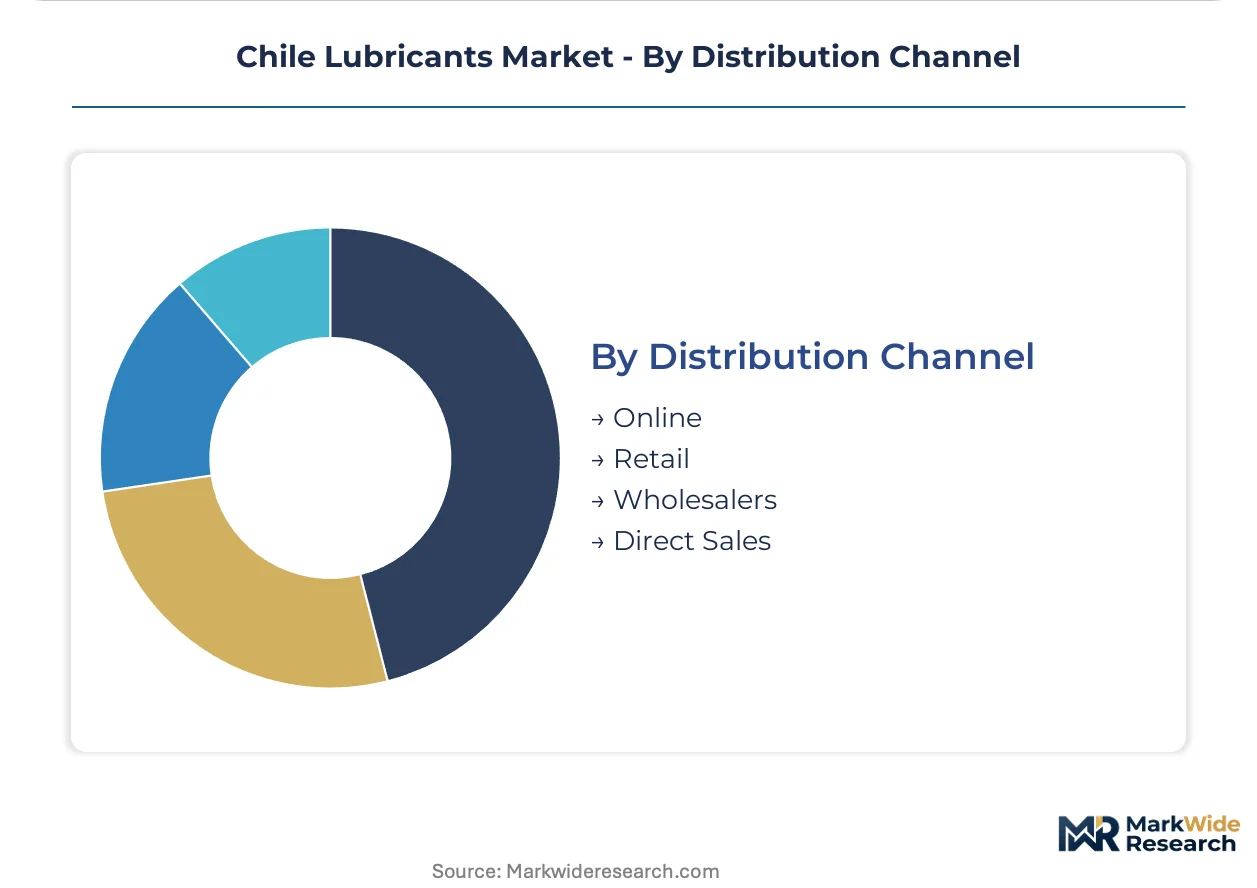
Distribution Channel:
Supply concentration in northern mining corridors forces channel architecture that reconciles bulk delivery efficiency with remote site accessibility.
- Direct Sales:Tanker and intermediate bulk container deliveries bypass distribution intermediaries for large mining and industrial accounts; Empresas Copec's national fuel network anchors this channel with embedded lubricant logistics.
- Wholesalers:Regional distributors aggregate demand from smaller industrial and agricultural buyers, managing inventory across multiple product categories and specification grades.
- Retail:Service stations and automotive parts stores serve consumer automotive and light commercial demand with packaged lubricants in bottle and pail formats.
- Online:E-commerce penetration remains limited in B2B segments; consumer automotive lubricant sales through digital channels are expanding in Santiago but face logistics cost barriers in remote regions.
Channel volume concentrates in Direct Sales; the fastest channel expansion belongs to Online as B2B platform adoption accelerates among mid-size fleet operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
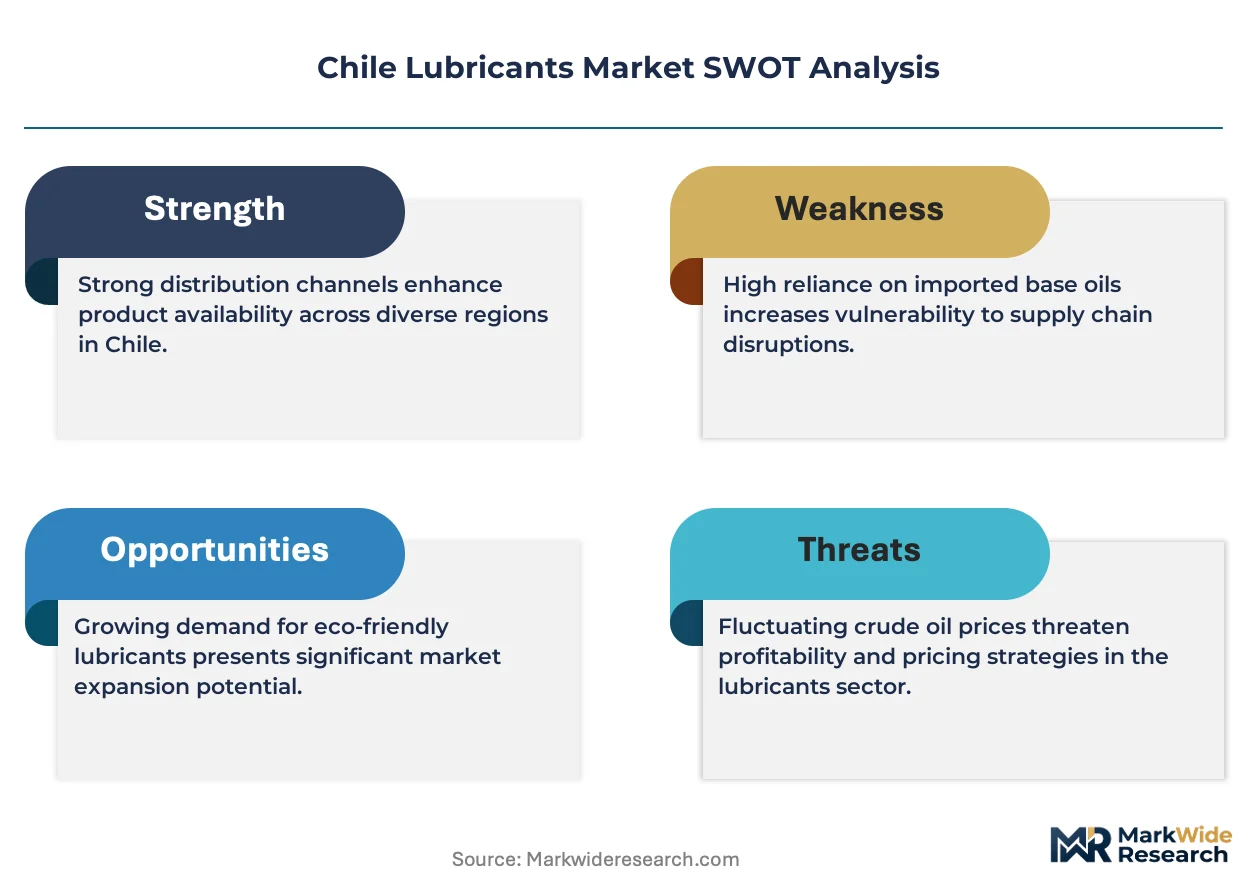
Chile produces no Group II or Group III base oils domestically, forcing complete reliance on Atlantic-sourced imports while northern mining corridors consume the bulk of national lubricant volumes. This production-consumption divide shapes procurement strategies around freight optimization and inventory positioning.
Atacama Region
Codelco's Chuquicamata and Radomiro Tomic operations anchor heavy-duty hydraulic fluid demand for open-pit copper extraction. Chile's Ministry of Environment Extended Producer Responsibility frameworks mandate waste-oil collection logistics that suppliers must embed within service contracts. Calama and Sierra Gorda concentrator circuits consume ISO VG 46 and 68 grades at industrial scale.
Antofagasta Region
Escondida and Spence mines drive fire-resistant hydraulic fluid specifications requiring Factory Mutual approval for underground and surface operations. The Superintendency of the Environment monitors hydrocarbon discharge limits, accelerating specification shifts toward biodegradable ester-based HFD-U grades. Antofagasta city clusters technical-service laboratories supporting multi-year supplier agreements.
Valparaíso Region
Marine lubricant demand concentrates at Valparaíso and San Antonio ports serving bulk carriers and container vessels. IMO 2020 sulfur regulations have shifted cylinder lubricant base number requirements for two-stroke crosshead engines. Shell plc maintains specialized supply positioning through port logistics infrastructure.
Santiago Metropolitan Region
Passenger vehicle service fill and aftermarket distribution networks concentrate in Chile's primary consumption zone. Empresas Copec leverages its national fuel-station network to embed lubricant sales within fleet-card programs. Quick-lube chains penetrate Santiago density while traditional workshop networks sustain regional city demand.
O'Higgins and Maule Regions
Mechanized irrigation expansion drives consolidating agricultural channel demand for hydraulic and transmission fluids. Tractor fleet modernization compresses universal tractor oil specification diversity toward dedicated UTTO grades. Precision farming equipment penetration creates white space for specialized fluid formulations.
Chile Lubricants Market Competitive Environment
The competitive structure tilts toward integrated energy companies with captive distribution infrastructure. National fuel networks and international oil majors divide the market between embedded fleet-card programs and premium synthetic technical-service agreements. Three archetypes dominate: integrated downstream operators leveraging retail presence, international majors competing on formulation specialization, and regional Latin American suppliers optimizing freight economics. Consolidation pressure operates through multi-year mining contracts and circular-economy service bundling rather than classical M&A.
Among international majors, Chevron Corporation and Shell plc exemplify divergent specialization strategies—one anchoring premium synthetic supply through mining technical-service agreements, the other competing on marine lubricant logistics. Empresas Copec represents the integrated downstream archetype, embedding lubricant procurement within national energy management platforms. Petrobras and YPF illustrate regional Latin American positioning shaped by geographic proximity to Atlantic refining corridors.
| Leading Market Players |
|---|
| Petrobras |
| Chevron Corporation |
| Empresas Copec |
| YPF |
| BP PLC |
| Shell plc |
| Valvoline Inc. |
| Repsol |
| TotalEnergies SE |
| Others |
Value Chain & Pricing Dynamics
Reformulation toward biodegradable ester base stocks simultaneously elevates raw material costs and compresses supplier margins across Chile's northern mining corridors, while Chile's Ministry of Environment discharge standards accelerate procurement budget reallocation toward certified premium categories.
Pricing Analysis
Cost-down pressure on mineral-based hydraulic fluids intensifies as Codelco and BHP's Escondida operations mandate fire-resistant HFD-U formulations with Factory Mutual approval and biodegradable certification. Three-tier pricing structure across premium synthetic, certified biodegradable, and conventional mineral grades separates mining fleet operators from agricultural buyers and independent repair shops. Price differentiation traces to technical-service bundling and volume scale, with the steepest buyer price sensitivity concentrated among small-fleet agricultural operators in O'Higgins and Maule regions.
Supply Chain Analysis
Group II and Group III base oil supply rests on Atlantic-sourced imports from the United States, Brazil, and regional Latin American refiners, with Chile lacking domestic hydrocracking capacity. Formulators draw from polyalphaolefin, synthetic ester, and vegetable-derived base stock feedstocks. Single-source vulnerability concentrates in northern mining corridor logistics, where sparse re-refining infrastructure forces reliance on virgin base stocks. Distribution runs through Empresas Copec's national fuel-station network and direct tanker deliveries to Antofagasta and Atacama mine sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's lubricants market operates as a vertical-integration race where captive waste-oil collection networks and re-refining capacity determine long-term contract viability against Chile's Ministry of Environment Extended Producer Responsibility mandates.
For Market Incumbents: Deepen technical-service laboratory presence in Antofagasta city clusters to lock multi-year mining contracts against emerging regional Latin American suppliers. Secure backward integration into re-refining infrastructure to deflect compliance cost pressure from Chile's Ministry of Environment waste-oil collection mandates. Expand bulk-to-tote packaging logistics to compress distributor margins in remote consumption points. For New Entrants and Emerging Players: Launch via precision farming equipment channels in O'Higgins and Maule valleys, where mechanized irrigation expansion outpaces established lubricant technical-service coverage. Target consolidating agricultural demand for dedicated UTTO grades as tractor fleet modernization compresses universal tractor oil specification diversity. Pursue carbon-accounting service bundling to differentiate against mineral-oil incumbents facing Chile's national decarbonization procurement mandates. For Investors and Strategic Acquirers: Re-rating potential sits with integrated collection-and-re-refining service providers given Chile's Ministry of Environment tightening of Extended Producer Responsibility enforcement. Long-term viability favors suppliers with captive logistics networks spanning northern mining corridors and Santiago metropolitan distribution density. Monitor Superintendency of the Environment hydrocarbon discharge monitoring intensity as the inflection signal for accelerated biodegradable formulation specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Re-refining Capacity Buildout | Captures circular-economy revenue pools under Chile's Ministry of Environment Extended Producer Responsibility frameworks. |
| Fire-resistant Formulation Certification | Locks Factory Mutual-approved supply contracts with Codelco and BHP's Escondida underground and surface operations. |
| Bulk-to-tote Packaging Innovation | Decouples large-volume mining contracts from drum-only procurement legacy across Atacama and Antofagasta corridors. |
| Carbon-accounting Service Integration | Opens technical-consulting revenue streams around lubricant-related energy audits under Chile's national decarbonization commitments. |
| Precision Farming Channel Expansion | Penetrates consolidating agricultural demand in O'Higgins and Maule valleys as mechanized irrigation spreads. |
Study Parameters
Multi-period observation of synthetic lubricant penetration rates, biodegradable formulation adoption curves, and mining fleet procurement contract structures anchored the trend analysis, supplemented by interviews with mining maintenance directors, lubricant formulator technical-service managers, Chile's Ministry of Environment compliance officers, agricultural equipment dealers, and fuel-station network procurement leads. Secondary validation drew from Chilean customs trade data, SEC filings of international oil majors, Superintendency of the Environment discharge monitoring reports, and mining sector procurement disclosures. Bottom-up volume modeling triangulated against top-down mineral extraction intensity projections.
Segment-weighting applied product type, application, end user, and distribution channel dimensions across the modeling period, with hydraulic fluid and engine oil categories receiving distinct growth trajectory treatment based on copper extraction equipment specifications. CAGRs were derived from trend extrapolation of synthetic lubricant replacement intervals versus mineral oil compression patterns, calibrated against Chile's Ministry of Mining environmental enforcement timelines and base-oil import freight cost volatility.
Currency fluctuation on Atlantic-sourced feedstock, biodegradable base stock cost premium volatility, and re-refining infrastructure buildout delays are the dominant revision risks to volume and value projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Synthetic Lubricants Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
Textile Machine Lubricants Market
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
Morocco Lubricants Market
Lubricants
Hydro Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Lubrication Equipment Market
Lubricants
Brazil Lubricants Market
Lubricants
South Korea Lubricants Market
Lubricants
Global Mineral Oil Market
Lubricants
Singapore Lubricants Market
Lubricants
Hydraulic Oil Additives Market